
 Insect Repellent Active Ingredients Market | 2026-2036
Insect Repellent Active Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Insect Repellent Active Ingredients Market Insights
Synthetic-to-biological formulation chemistry is narrowing the performance gap between conventional and plant-derived actives. BASF SE leverages its agrochemical R&D pipeline to develop next-generation picaridin variants with extended duration profiles. Sumitomo Chemical Co., Ltd anchors Asian supply chains through integrated pyrethroid and novel active ingredient production. Godrej Consumer Products Limited dominates emerging market distribution with region-specific formulations tailored to local vector species.
Insect repellent active ingredients comprise biologically active compounds—synthetic molecules such as N,N-diethyl-meta-toluamide (DEET) and picaridin, or refined natural oils—that interfere with arthropod olfactory receptors at concentrations typically ranging from 10% to 30% in finished products. These compounds serve primarily to prevent vector-borne disease transmission in human populations and protect livestock and crop assets in agricultural settings. DEET retains the largest volume position across personal care applications due to decades of established efficacy documentation, while oil of lemon eucalyptus captures the fastest expansion in premium outdoor gear and clothing treatment segments where consumers prioritize botanical positioning. Aerosol and spray formulations command the highest margin pools in developed markets, whereas lotion formats sustain deeper penetration in tropical regions with intensive agricultural worker exposure.
The EPA regulates active ingredient safety and efficacy claims through its Office of Pesticide Programs, while the EU Biocidal Products Regulation (BPR) mandates comprehensive substance authorization that filters market participants by compliance capacity. REACH chemical registration requirements further constrain raw material sourcing flexibility for European formulators. Stakeholders must monitor evolving residue tolerance standards in food-adjacent agricultural applications and vector control programs.
Market Dynamics
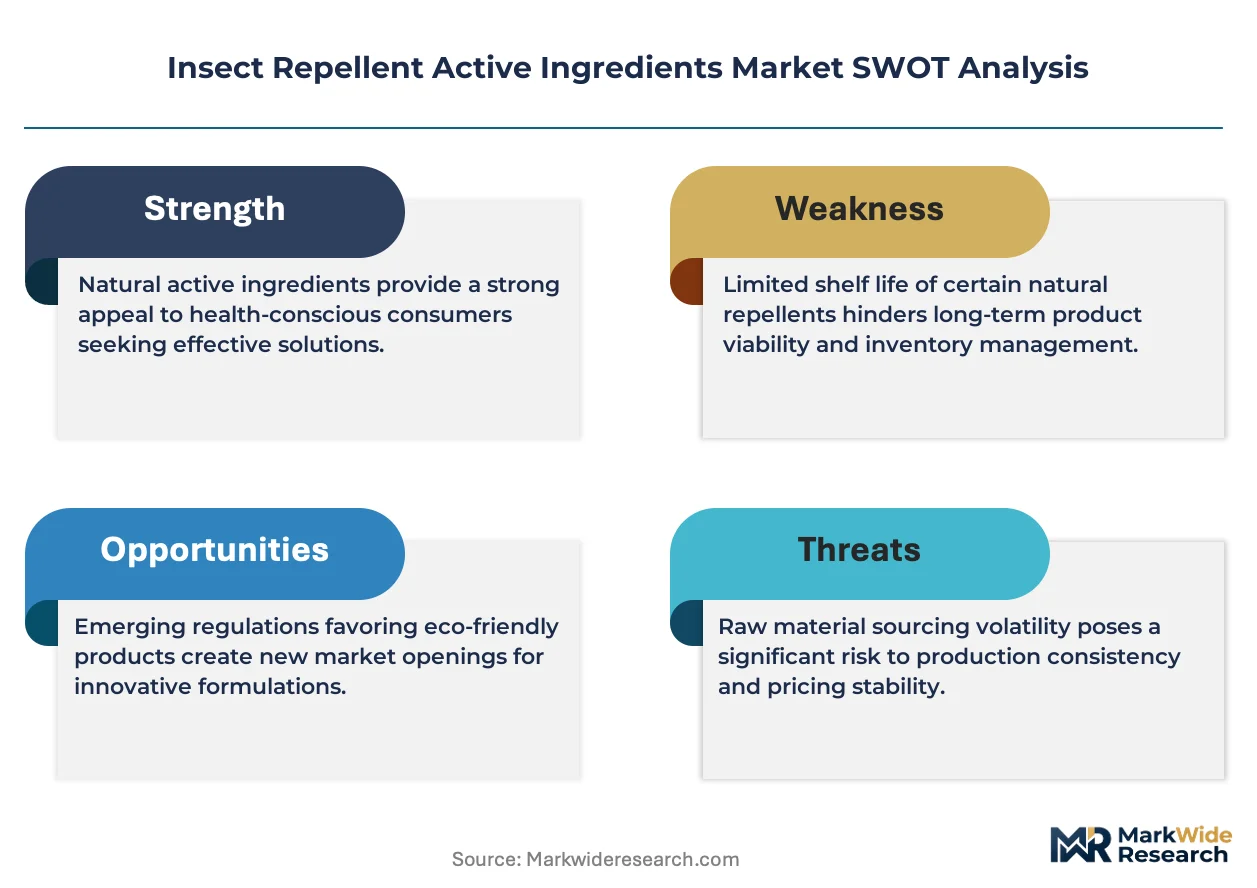
The EPA's biopesticide registration pathway is compressing approval timelines for plant-derived actives, forcing synthetic incumbent suppliers to accelerate formulation innovation cycles or cede shelf space to botanical alternatives.
Growth Catalysts
- Vector-borne disease burden:Brazil's year-round tropical climate sustains constant demand from agricultural workers and urban populations. Municipal vector control programs expand procurement of residual spraying actives.
- Adventure tourism participation:Outdoor enthusiasts now represent the fastest-expanding buyer segment in premium outdoor gear channels. Clothing treatment formulations command margin premiums over conventional skin-applied products.
- EU Biocidal Products Regulation substance authorization:The BPR's streamlined renewal process for established actives reduces regulatory uncertainty for compliant formulators. European manufacturers gain competitive clarity against non-compliant imports.
Market Restraints
- Pyrethroid supply concentration:Asian integrated chemical producers control upstream pyrethroid intermediate supply. Price volatility in key feedstocks propagates through finished active ingredient pricing.
- REACH chemical registration burden:European formulators face constrained raw material sourcing flexibility. Registration costs filter smaller participants from substance authorization processes.
- DEET efficacy perception ceiling:Decades of established documentation limits premium pricing power. Botanical alternatives capture positioning value despite performance gaps in field conditions.
Strategic Opportunities
- India agricultural worker protection:Underpenetrated rural distribution infrastructure creates whitespace for region-specific formulations. CDSCO registration pathways for public health actives remain less congested than cosmetic channels.
- Clothing treatment convergence:Microencapsulation technology married to textile finishing processes enables wash-durable repellent apparel. Outdoor gear manufacturers seek integrated supply partnerships.
- Direct-to-consumer subscription channels:Recurring replenishment models bypass traditional retail slotting constraints. Premium botanical brands build lifetime value through seasonal auto-ship programs.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in arthropod olfactory receptor interference mechanisms concentrates at legacy agrochemical laboratories. Startups compete for limited talent pools.
- Residue tolerance standard evolution:Food-adjacent agricultural applications face tightening maximum residue limits. Formulators must revalidate established application rates against emerging analytical detection thresholds.
- Supply chain reconfiguration friction:Botanical active sourcing requires traceable cultivation partnerships. Synthetic suppliers lack agricultural procurement infrastructure for plant-derived feedstock security.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insect Repellent Active Ingredients Market |
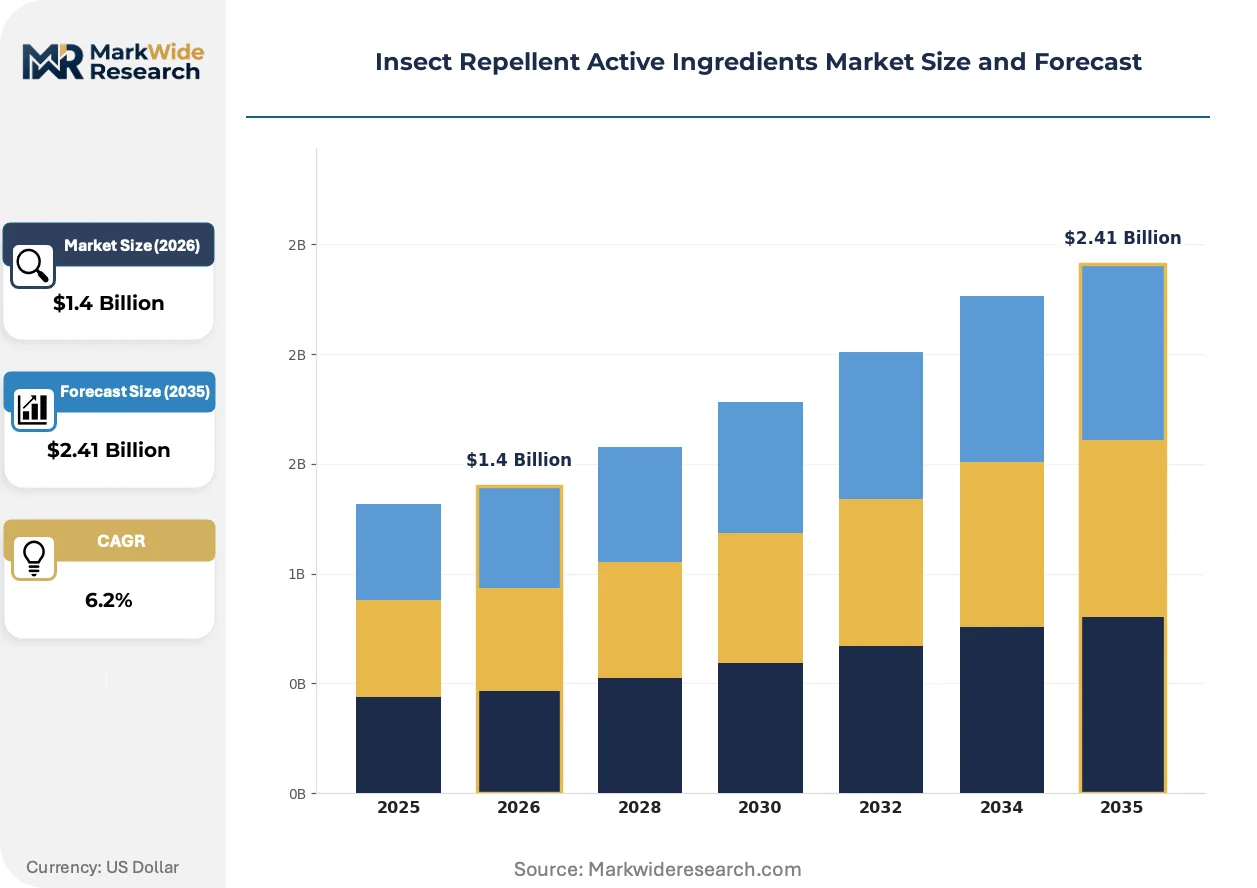
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Active Ingredient Type: DEET, Picaridin, Oil of Lemon Eucalyptus, IR3535 Formulation Type: Aerosol, Lotion, Spray, Wipes End User: Household, Outdoor Enthusiasts, Agricultural Workers, Travelers Application: Personal Care, Clothing Treatment, Outdoor Gear, Pest Control |
| Companies Covered | Spectrum Brands Inc., Reckitt Benckiser Group PLC, BASF SE, Sumitomo Chemical Co., Ltd, Henkel AG & Co. KGaA, S.C. Johnson & Son Inc., Merck KGaA, Godrej Consumer Products Limited, Dabur, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insect Repellent Active Ingredients Market Trends and Innovations
Microencapsulation and controlled-release polymer systems are collapsing the performance-duration gap that historically protected synthetic actives from botanical displacement. Formulation technology now determines competitive positioning as much as active ingredient selection.
Synthetic-to-biological formulation chemistry is collapsing the efficacy advantage DEET held over plant-derived alternatives. Microencapsulated oil of lemon eucalyptus formulations now achieve eight-hour protection profiles matching conventional synthetics. Premium outdoor gear manufacturers are collapsing their qualification timelines for botanical-treated clothing lines.
The EPA's biopesticide registration pathway is collapsing the regulatory cost barrier that favored incumbent synthetic actives. Expedited review timelines for plant-derived substances reduce time-to-market from years to months. Botanical formulators are collapsing their commercialization spend versus synthetic registration budgets.
Subscription replenishment models are collapsing the retail channel's gatekeeper role in consumer repellent access. Direct-to-consumer brands bypass pharmacy and mass merchant slotting fees. Urban outdoor enthusiasts in North American and Western European markets are collapsing their purchase cycle frequency through auto-ship programs.
Insect Repellent Active Ingredients Market Segmentation
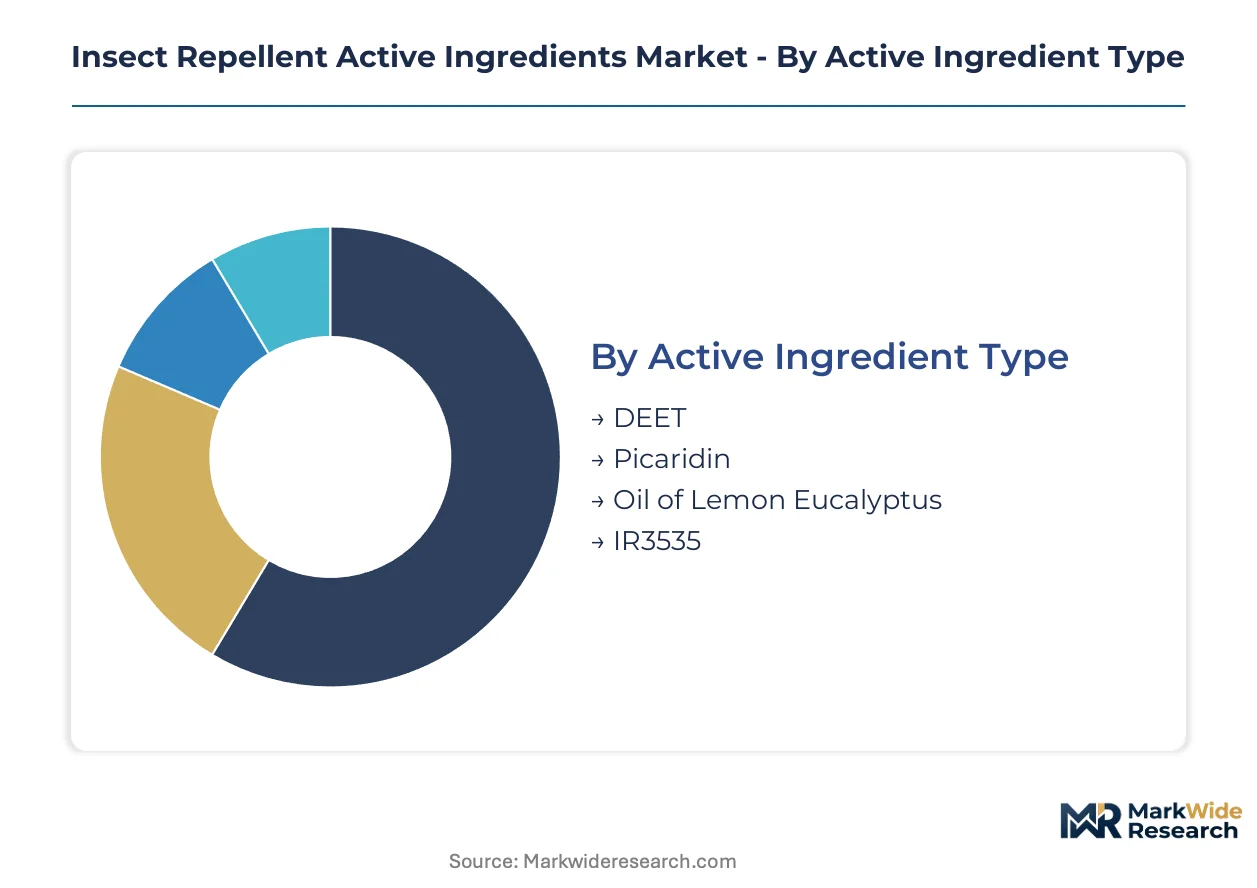
Insect repellent active ingredients segment along four critical dimensions that determine formulation chemistry, regulatory pathway, and margin architecture. Active ingredient selection dictates EPA registration requirements and performance claims. Formulation type shapes distribution channel access and geographic penetration depth.
Active Ingredient Type:
Cycle times vary dramatically across this category—synthetic actives refresh through incremental formulation improvements while botanical alternatives compress development timelines through EPA biopesticide pathways.
- DEET:N,N-diethyl-meta-toluamide remains the reference standard for arthropod olfactory receptor interference at concentrations spanning 10% to 100%. Demand concentrates in tropical regions with intensive agricultural worker exposure, particularly Brazil's year-round vector control programs, though premium positioning faces headwinds from decades of established efficacy documentation that limits pricing power.
- Picaridin:Synthetic piperidine derivative delivers comparable protection duration to DEET with improved cosmetic feel and fabric compatibility. BASF SE leverages agrochemical R&D pipelines to develop next-generation variants with extended duration profiles, capturing share in premium outdoor gear channels where consumers prioritize non-greasy application.
- Oil of Lemon Eucalyptus:Refined natural oil from Corymbia citriodora delivers botanical positioning with EPA-registered efficacy.
- IR3535:Bio-inspired amino acid derivative offers intermediate performance between synthetics and essential oils.
DEET anchors the volume base while Oil of Lemon Eucalyptus gains share at the steepest rate.
Formulation Type:
Margin tiers separate sharply across this dimension—aerosol and spray formats command premium positioning in developed markets while lotion penetration runs deepest in tropical agricultural zones.
- Aerosol:Pressurized delivery systems enable uniform skin coverage with rapid drying characteristics. North American and Western European retail channels sustain the highest margin pools through pharmacy and mass merchant distribution, though propellant regulations constrain formulation flexibility.
- Lotion:Emulsion-based systems provide extended skin residence time and precise dosage control. Brazil and India agricultural worker protection programs drive volume concentration, with CDSCO and ANVISA registration pathways favoring public health applications over cosmetic positioning.
- Spray:Pump-dispersed liquid formulations balance convenience with portability for outdoor enthusiast segments.
- Wipes:Impregnated substrate formats target travel and on-the-go applications with single-use convenience.
Lotion formats sustain the deepest geographic penetration while aerosol captures the steepest margin premiums.
End User:
Procurement patterns diverge sharply—institutional buyers run annual tenders while direct-to-consumer subscriptions collapse purchase cycle frequency.
- Household:Mass-market consumers purchasing through retail and e-commerce channels for family protection.
- Outdoor Enthusiasts:Adventure tourism participants represent the most rapidly expanding buyer segment. Clothing treatment formulations and subscription auto-ship programs concentrate demand in North American and Western European premium outdoor gear channels.
- Agricultural Workers:Occupational exposure protection drives institutional procurement through municipal vector control programs and employer-provided safety equipment. Brazil's tropical disease burden sustains year-round consumption with ANVISA-regulated application standards.
- Travelers:International visitors to endemic regions seek portable, TSA-compliant formats with compact packaging.
Agricultural Workers anchor the volume base while Outdoor Enthusiasts expand most quickly.
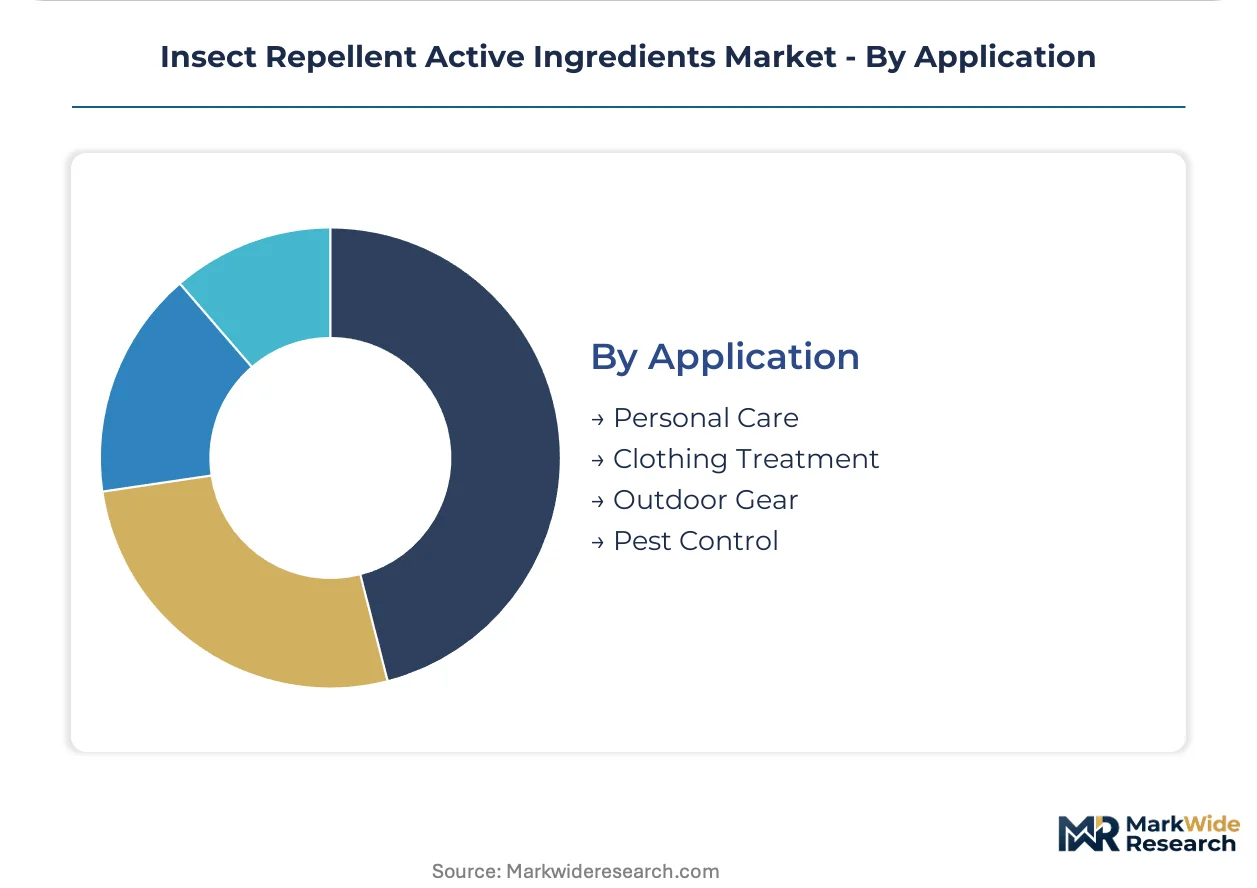
Application:
Technology convergence is blurring historical boundaries—microencapsulation now enables textile-integrated protection that rivals skin-applied performance.
- Personal Care:Skin-applied formulations dominate historical volume with established efficacy documentation. DEET and picaridin concentrations typically range 10% to 30% in consumer-facing products, with EPA and EU BPR substance authorization filtering market participants by compliance capacity.
- Clothing Treatment:Microencapsulation technology married to textile finishing processes enables wash-durable repellent apparel. Outdoor gear manufacturers seek integrated supply partnerships as eight-hour protection profiles from botanical-treated fabrics match conventional synthetic performance.
- Outdoor Gear:Tents, sleeping bags, and equipment treatments extend protection beyond skin contact.
- Pest Control:Residual spraying actives for municipal vector control programs and agricultural perimeter protection.
Personal Care anchors the volume base while Clothing Treatment climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports pyrethroid intermediates to Indian and Brazilian formulators, creating a trade-flow corridor that shapes regional supply security. Germany and Switzerland supply precision formulation technologies to North American premium brands. Southeast Asian chemical producers increasingly integrate backward into active ingredient synthesis.
United States
Adventure tourism participation and outdoor recreation spending drive premium repellent demand. EPA's biopesticide registration pathway accelerates plant-based active approvals, compressing time-to-market for botanical formulators. Research Triangle Park in North Carolina hosts vector control research clusters where public health agencies test next-generation active efficacy.
Brazil
Agricultural worker protection programs and year-round tropical disease burden sustain constant institutional procurement. ANVISA regulates application standards for occupational exposure scenarios. São Paulo state's chemical industry corridor concentrates pyrethroid formulation capacity serving Latin American vector control markets.
Germany
EU Biocidal Products Regulation substance authorization filters market participants by compliance capacity. ECHA's REACH chemical registration requirements constrain raw material sourcing flexibility for European formulators. BASF SE's Ludwigshafen headquarters anchors agrochemical R&D pipelines developing extended-duration picaridin variants.
India
Underpenetrated rural distribution infrastructure creates whitespace for region-specific formulations targeting agricultural workers. CDSCO registration pathways for public health actives remain less congested than cosmetic channels. Gujarat's chemical manufacturing belt supplies pyrethroid intermediates to domestic and export markets.
Japan
Precision formulation technologies and polymer science expertise enable microencapsulation advances for clothing treatment applications. METI supports biocidal product innovation through targeted R&D subsidies. Sumitomo Chemical Co., Ltd's integrated production facilities in Osaka anchor Asian supply chains for novel active ingredients.
Insect Repellent Active Ingredients Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered margin pools, creating a bifurcated structure where scale advantages separate from innovation premiums. The vendor base clusters around three strategic archetypes: integrated chemical conglomerates with agrochemical R&D pipelines, consumer goods multinationals with retail distribution dominance, and regional formulators with local regulatory expertise. Competitive moves concentrate on portfolio diversification into botanical actives and geographic expansion through emerging market partnerships.
Among integrated chemical producers, BASF SE and Sumitomo Chemical Co., Ltd occupy positions representing upstream control over active ingredient synthesis and formulation chemistry development. Godrej Consumer Products Limited exemplifies the emerging market distribution archetype, anchoring region-specific supply relationships that bypass traditional retail gatekeepers. These three entities collectively span the value chain from intermediate production through branded consumer access.
| Leading Market Players |
|---|
| Spectrum Brands Inc. |
| Reckitt Benckiser Group PLC |
| BASF SE |
| Sumitomo Chemical Co., Ltd |
| Henkel AG & Co. KGaA |
| S.C. Johnson & Son Inc. |
| Merck KGaA |
| Godrej Consumer Products Limited |
| Dabur |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese pyrethroid intermediate production is compressing feedstock margins and forcing integrated producers to absorb cost volatility or cede volume to Indian and Brazilian formulators with captive sourcing arrangements. This utilization dynamic propagates through finished active ingredient pricing, with synthetic suppliers defending position through extended-duration formulation premiums while botanical alternatives exploit EPA biopesticide pathway cost advantages.
Pricing Analysis
Next-generation picaridin variants command 15-25% premiums over standard DEET formulations, while microencapsulated oil of lemon eucalyptus bridges the gap between prior-generation botanicals and synthetic performance tiers. Pricing stratifies across premium, standard, and economy tiers based on duration claims and EPA registration tier, with certification level as the primary differentiation driver. Pricing pressure stems from pyrethroid feedstock volatility propagating through Asian supply chains. Agricultural worker procurement programs in Brazil and India exhibit highest price sensitivity, while North American outdoor enthusiasts accept premium positioning for clothing treatment formats.
Supply Chain Analysis
Export-control scrutiny on dual-use chemical precursors constrains pyrethroid intermediate flows from China to Indian formulators, though insect repellent actives remain below threshold classification. Supply concentrates in China for pyrethroid intermediates, India for formulation and CDSCO-registered public health products, and Germany for precision polymer encapsulation technologies. Raw material dependencies center on m-xylene for DEET synthesis, chrysanthemic acid derivatives for pyrethroids, and Corymbia citriodora plantation output for botanical extraction. Single-source vulnerability runs through Chinese intermediate supply for legacy synthetic actives. Distribution runs through institutional procurement tenders for agricultural applications and direct-to-consumer subscription channels for premium outdoor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemistry expertise in arthropod olfactory receptor interference concentrates at legacy agrochemical laboratories, creating acquisition premiums for talent-constrained entrants and forcing incumbents to build captive R&D pipelines or risk ceding botanical innovation cycles.
For Market Incumbents: Build regulatory moats through accelerated EPA biopesticide portfolio expansion ahead of synthetic incumbent response cycles. BASF SE's agrochemical R&D pipeline demonstrates how backward integration into novel active ingredient synthesis defends margin position against botanical displacement. Incumbents should anchor capacity addition in Ludwigshafen or Osaka to secure polymer encapsulation technology for clothing treatment convergence. Certification investment in EU BPR substance authorization filters smaller competitors from European procurement channels. For New Entrants and Emerging Players: Build out underpenetrated rural distribution infrastructure in India's agricultural belts where CDSCO registration pathways remain less congested than cosmetic channels. Target agricultural worker protection programs with region-specific formulations tailored to local Anopheles and Aedes vector species. Direct-to-consumer subscription models bypass retail slotting constraints and build lifetime value through seasonal auto-ship programs calibrated to monsoon and harvest cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across botanical active ingredient production as EPA biopesticide pathways compress registration timelines and commercialization spend. Long-term viability favors formulators with integrated textile finishing partnerships for clothing treatment applications. Acquisition target archetype: regional formulators with ANVISA or CDSCO regulatory expertise and established agricultural procurement relationships. Signal to watch: microencapsulation technology licensing deals between polymer specialists and outdoor gear manufacturers as inflection indicator for clothing treatment adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EPA Biopesticide Registration Acceleration | Expedited review timelines compress botanical time-to-market from years to months against synthetic benchmarks. |
| Microencapsulation Technology Licensing | Polymer science partnerships enable wash-durable apparel protection matching eight-hour synthetic performance profiles. |
| CDSCO Public Health Route Prioritization | Less congested regulatory channels in India unlock agricultural worker segments ahead of cosmetic-grade competitors. |
| Direct-to-Consumer Subscription Launch | Auto-ship programs bypass pharmacy slotting fees and capture recurring revenue from outdoor enthusiast segments. |
| Backward Integration into Plantation Sourcing | Traceable Corymbia citriodora cultivation partnerships secure feedstock for oil of lemon eucalyptus expansion. |
Research Methodology
Operator-level perspectives from formulation chemists at agrochemical laboratories, procurement leads at municipal vector control programs, brand managers at consumer goods multinationals, and regulatory affairs specialists anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from EPA Office of Pesticide Programs registration databases, EU BPR substance authorization records, CDSCO public health pesticide approvals, and customs trade flow data for pyrethroid intermediates. Bottom-up active ingredient volume estimates triangulated against top-down formulation value projections across the analysis window.
Scenario-bracketing framed demand trajectories across conservative, baseline, and expansion cases without fixed-year anchoring. Segmentation dimensions modeled include active ingredient type, formulation format, end-user procurement pattern, and application technology platform. CAGRs derived from fitted growth curves applied to base-year market sizing, with vector-borne disease burden indices and adventure tourism participation rates as industry-specific forecast inputs throughout the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion or acquisition moves by integrated chemical conglomerates would shift outcomes beyond modeled ranges. Material shifts in EPA biopesticide review timelines, pyrethroid feedstock export restrictions, or residue tolerance standard evolution would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Fluoroboric Acid Market
Chemicals
Asia-Pacific Fluorosilicic Acid Market
Chemicals
Valeryl Chloride Market
Chemicals
Naturally Derived Fatty Alcohol Market
Chemicals
3,5-Dinitroaniline Market
Chemicals
Coagulant Market
Chemicals
Hexachloroethane Market
Chemicals
Methyl P-Hydroxybenzoate Market
Chemicals
Global E Series Glycol Ether Market
Chemicals
India Metal Treatment Chemical Market
Chemicals
Africa Mining Chemicals Market
Chemicals
(S)-(+)-2-Amino-1-Propanol Market
Chemicals
Aluminium Chloride Market
Chemicals
3-Iodoaniline Market
Chemicals
Anhydrous Hydrogen Fluoride Market
Chemicals
Nonaisoprenol Market