
 Global Zinc Pyrithione Market | 2026-2036
Global Zinc Pyrithione Market Size, Share, and Industry Trends Forecast 2026-2036
Global Zinc Pyrithione Market Foresight
Modular active-ingredient sourcing is decoupling zinc pyrithione procurement from bundled antimicrobial supply contracts, letting personal care formulators mix grades across suppliers. Lonza leverages backward integration into pyrithione chemistry to sustain margin control across European cosmetic customers. Chugoku Kogyo anchors volume leadership in Asian antifouling applications through dedicated marine-coatings technical service. Kumar Organic Products Limited differentiates via specialty micronization capabilities that serve Indian and Middle Eastern personal care exporters.
Zinc pyrithione is a coordination complex of zinc with two pyrithione ligands, typically supplied as a white to off-white powder with particle sizes ranging from standard 10-20 micron to micronized sub-5 micron grades for transparent cosmetic formulations; it functions primarily as a broad-spectrum antimicrobial and antifungal agent inhibiting fungal cell division through membrane transport disruption. Micronized and coated grades capture expanding margin pools as transparent shampoo and leave-on cosmetic formulations displace opaque legacy products. Agricultural fungicide applications remain structurally mature with slower volume expansion, while powder and liquid suspension forms dominate procurement volumes across personal care and coatings end user industries.
EPA registration requirements for antimicrobial pesticides govern zinc pyrithione use in US antifouling paints and cosmetic preservatives, while ECHA biocidal product regulation under REACH drives substitution testing and dossier costs for European suppliers. China's MEE environmental compliance standards and GB specifications for cosmetic raw materials shape manufacturing investments and export qualification protocols. Stakeholders must monitor evolving classification decisions under EU CLP and state-level US regulatory reviews that could reclassify zinc pyrithione hazard profiles and trigger reformulation mandates or labeling changes.
Market Dynamics
REACH biocidal product regulation in Europe is fragmenting supplier economics, forcing reformulation investments that bifurcate the market between compliant micronized grades and legacy standard powders.
Growth Catalysts
- Southeast Asian personal care manufacturing:Contract manufacturers in Thailand and Vietnam expand antidandruff shampoo output for export to Middle Eastern and African markets, pulling zinc pyrithione demand through regional chemical distributors.
- China's GB cosmetic standards:Updated raw material specifications under SAMR oversight qualify domestic zinc pyrithione producers for international personal care supply chains, reducing import dependency.
- Marine antifouling coatings:Shipyard activity in South Korea and Japan sustains volume consumption of liquid suspension grades for copper-free hull protection systems.
Market Restraints
- Pyrithione input cost volatility:Sodium pyrithione precursor supply concentrates among Chinese specialty chemical producers, exposing formulators to freight and energy cost swings.
- Substitution threat from climbazole:European cosmetic brands accelerate climbazole testing as an alternative antifungal active, pressured by ECHA hazard classification reviews.
- Micronization capex barriers:Sub-5 micron particle production requires jet milling and surface coating equipment that locks out smaller compounders from transparent formulation markets.
Strategic Opportunities
- Indian pharmaceutical excipient applications:Regulatory filings with CDSCO for topical antifungal creams open a channel beyond shampoo and paint uses.
- US EPA FIFRA registration streamlining:Antimicrobial pesticide review efficiencies for low-risk biocides could accelerate new supplier entry into antifouling coatings.
- Leave-on cosmetic convergence:Micronized grade compatibility with transparent serums and scalp treatments creates pull from Korean and Japanese beauty brands.
Industry Challenges
- Dossier compilation timelines:ECHA biocidal product authorization requires multi-year toxicological and environmental fate studies that strain mid-tier supplier cash flows.
- Particle size standardization gaps:Absence of harmonized ISO methods for micronized grade characterization creates quality disputes between raw material suppliers and finished goods manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Zinc Pyrithione Market |
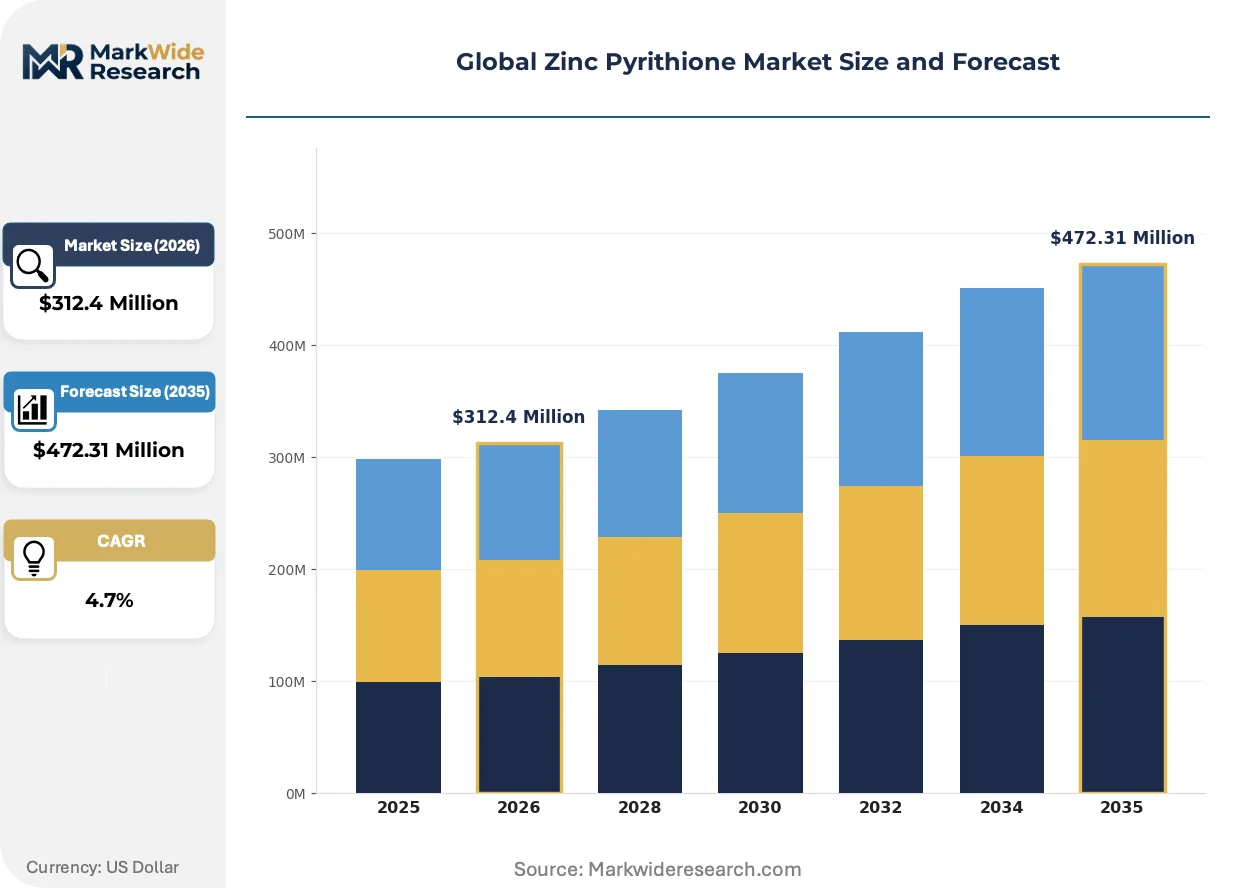
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Grade, Micronized Grade, Coated Grade, Ultra-Pure Grade Application: Antidandruff Shampoos, Antifouling Paints, Cosmetic Preparations, Agricultural Fungicides End User Industry: Personal Care Manufacturers, Paints & Coatings Producers, Crop Protection Companies, Pharmaceutical Firms Form: Powder, Granules, Liquid Suspension, Paste |
| Companies Covered | Sanitized AG, Chugoku Kogyo, Lonza, Liyuan Chem, Tinci, Regen Chem, Kolon Life Science, Zhufeng Fine Chem, Kumar Organic Products Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Zinc Pyrithione Market Shifts & Advancements
Formulation transparency requirements and regulatory hazard reclassification are compressing the viable technology set, favoring suppliers with in-house particle engineering capabilities over commodity traders.
Micronized zinc pyrithione with controlled particle distribution below 5 microns is consolidating technical differentiation in personal care procurement. Korean and Japanese cosmetic manufacturers specify these grades for transparent shampoo and scalp essence formulations. The technology is consolidating supplier margins toward particle engineering specialists and away from standard-grade traders.
REACH biocidal product regulation dossier requirements are extending compliance timelines for European market access. ECHA hazard classification reviews for respiratory sensitization are triggering reformulation mandates across leave-on cosmetic applications. German and French formulators are accelerating substitution testing while awaiting final CLP determinations.
Modular active ingredient sourcing is replacing bundled antimicrobial supply contracts in personal care procurement. Southeast Asian contract manufacturers now split zinc pyrithione, climbazole, and ketoconazole purchases across separate suppliers to optimize formulation flexibility. This pattern concentrates in Thailand and Vietnam, where export-oriented shampoo production serves Middle Eastern and African brand owners.
Global Zinc Pyrithione Market Segmentation
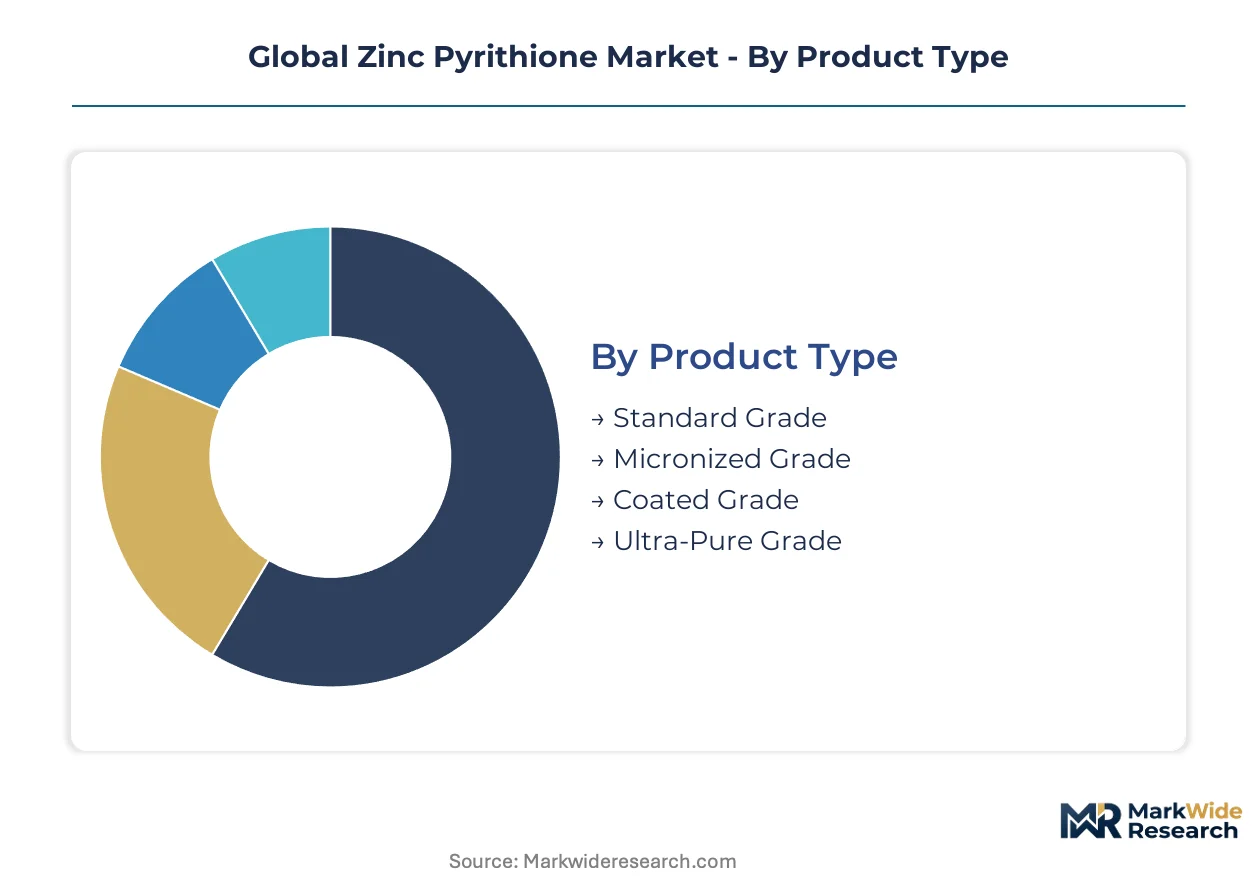
Segmentation in zinc pyrithione procurement reveals how particle engineering and regulatory compliance stratify supplier economics. Formulators select grades based on transparency requirements, biocidal authorization status, and end-use performance thresholds.
Product Type:
Integration depth varies sharply across grades, with standalone commodity powders serving legacy formulations while engineered grades embed into premium cosmetic systems requiring technical service partnerships.
- Micronized Grade:Sub-5 micron particle distribution enables transparent shampoo and scalp essence formulations. Korean and Japanese beauty brands specify this grade for leave-on cosmetic applications, though jet milling capex locks out smaller compounders from this margin pool.
- Coated Grade:Surface-modified particles improve dispersion stability in aqueous systems and reduce agglomeration during compounding. European formulators facing ECHA respiratory sensitization reviews favor coated variants for leave-on applications to mitigate exposure risk.
- Standard Grade:10-20 micron powder serves opaque antidandruff shampoos and agricultural fungicide applications where transparency is not required.
- Ultra-Pure Grade:Pharmaceutical-grade material meeting heavy metal and microbial specifications for topical drug formulations under FDA and EMA oversight.
Micronized grade leads volumes today; coated grade is gaining share fastest as regulatory pressure mounts on unmodified particles.
Application:
Cost tier stratification separates commodity biocidal uses from premium cosmetic formulations, with regulatory dossier investments creating divergent margin structures.
- Antidandruff Shampoos:Rinse-off hair care applications consume the largest zinc pyrithione volumes globally. Southeast Asian contract manufacturers in Thailand and Vietnam expand output for Middle Eastern and African export markets, pulling demand through regional distributors.
- Antifouling Paints:Marine hull coatings specify liquid suspension grades for copper-free protection systems. South Korean and Japanese shipyards sustain volume consumption despite EPA FIFRA registration burdens for new supplier entry.
- Cosmetic Preparations:Leave-on scalp treatments and transparent serums require micronized grades compatible with aesthetic performance standards.
- Agricultural Fungicides:Mature application with slower volume expansion, primarily served by standard grade powder in crop protection formulations.
Antidandruff shampoo leads volumes today; cosmetic preparations are climbing the fastest as Korean and Japanese brands expand transparent formulation portfolios.
End User Industry:
Customer type concentration shapes procurement patterns, with personal care formulators driving technical grade specifications while industrial buyers prioritize supply security.
- Personal Care Manufacturers:Cosmetic and toiletry formulators specify particle size distribution, coating chemistry, and regulatory dossier completeness. Modular sourcing now decouples zinc pyrithione from bundled antimicrobial contracts.
- Paints & Coatings Producers:Marine coatings specialists in South Korea and Japan anchor liquid suspension demand through technical service relationships with pyrithione chemistry suppliers.
- Crop Protection Companies:Agricultural fungicide producers represent mature demand with price-sensitive procurement of standard grade material.
- Pharmaceutical Firms:Topical antifungal drug developers require ultra-pure grades with CDSCO, FDA, or EMA drug master file support.
Personal care manufacturing leads volumes today; pharmaceutical applications show steepest expansion trajectory as regulatory filings for topical creams advance.
Form:
Supply concentration dictates availability, with powder and liquid suspension forms dominating procurement while paste and granule formats serve niche compounding requirements.
- Powder:Dry bulk material in standard and micronized grades serves personal care and agricultural applications. Chinese domestic suppliers anchor global powder availability.
- Liquid Suspension:Aqueous dispersions with controlled solids content simplify incorporation into antifouling paint systems and shampoo manufacturing.
- Granules:Low-dust handling format for agricultural fungicide blending operations and bulk pharmaceutical processing.
- Paste:High-solids concentrate for specialized cosmetic compounding where direct powder addition creates manufacturing challenges.
Powder leads volumes today; liquid suspension is expanding most quickly as marine coatings producers seek processing efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zinc pyrithione chemistry originated in European pharmaceutical research during the mid-twentieth century before industrial-scale production migrated to Asian manufacturing clusters. Today, supply chains concentrate in specific national hubs where regulatory frameworks and end-use manufacturing align.
China
Domestic producers under SAMR oversight supply both personal care exporters and regional antifouling paint manufacturers. GB cosmetic raw material specifications updated under national standards qualify Chinese zinc pyrithione for international supply chains, reducing import dependency. Manufacturing clusters in Jiangsu and Zhejiang provinces anchor global powder availability through integrated pyrithione chemistry operations.
United States
EPA FIFRA registration requirements govern antimicrobial pesticide applications in antifouling paints and cosmetic preservatives, creating compliance barriers for new supplier entry. Shipyard activity in Virginia and Gulf Coast states sustains consumption of liquid suspension grades for marine hull protection. Domestic formulators navigate state-level regulatory reviews alongside federal oversight.
Germany
ECHA biocidal product regulation under REACH drives substitution testing and multi-year dossier investments that strain mid-tier supplier economics. Frankfurt and Ludwigshafen chemical corridors host reformulation specialists serving European cosmetic brands. German formulators accelerate climbazole evaluation while awaiting final CLP hazard classification determinations.
Japan
METI industrial standards and PMDA pharmaceutical oversight shape manufacturing investments for cosmetic and topical drug applications. Osaka and Tokyo beauty brands specify micronized grades for transparent scalp essence formulations. Japanese marine coatings producers in Nagoya and Yokohama anchor technical service relationships with pyrithione chemistry suppliers.
India
CDSCO regulatory filings for topical antifungal creams open pharmaceutical excipient channels beyond traditional shampoo and paint uses. Mumbai and Gujarat chemical corridors host micronization specialists serving Middle Eastern and African personal care exporters. Domestic producers leverage specialty particle engineering capabilities to capture premium formulation markets.
Global Zinc Pyrithione Market Competitive Landscape
The competitive structure tilts toward chemistry-integrated specialists with backward control over pyrithione precursors. Supplier economics bifurcate between commodity-grade powder traders and engineered-grade particle specialists. Three archetypes dominate: integrated pyrithione chemistry producers, micronization technology specialists, and regional distribution-focused compounders. Capacity expansion and regulatory dossier compilation represent the dominant competitive moves as market access barriers rise.
Among chemistry-integrated producers, Lonza exemplifies the European archetype with captive pyrithione production serving cosmetic formulators. Chugoku Kogyo anchors the Asian marine coatings vector through technical service relationships with shipyard customers. Kumar Organic Products Limited occupies the specialty micronization tier, representing Indian producers targeting Middle Eastern and African export markets.
| Leading Market Players |
|---|
| Sanitized AG |
| Chugoku Kogyo |
| Lonza |
| Liyuan Chem |
| Tinci |
| Regen Chem |
| Kolon Life Science |
| Zhufeng Fine Chem |
| Kumar Organic Products Limited |
| Others |
Supply & Pricing Matrix
Specialized jet milling technicians in Jiangsu and Zhejiang provinces anchor labor-cost differentials that widen spreads between micronized premium grades and commodity standard powders. European REACH compliance investments compress margins on legacy grades while Asian manufacturing clusters exploit chemistry-integrated cost structures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies procurement by particle engineering intensity and regulatory dossier completeness. Price differentiation hinges on sub-5 micron certification and ECHA biocidal product authorization status. Cost compression in standard-grade powders is intensifying because sodium pyrithione precursor supply concentrates among Chinese specialty chemical producers. Agricultural fungicide buyers exhibit highest price sensitivity; Korean cosmetic formulators purchasing micronized grades for transparent scalp essences demonstrate lowest.
Supply Chain Analysis
Workforce availability for pyrithione chemistry and particle engineering concentrates in Chinese manufacturing clusters, with secondary technical service hubs in Japan and India. Raw material flows draw from sodium pyrithione precursor operations, zinc metal feedstock, and surface-coating chemistries. Single-source vulnerability pervades the sodium pyrithione tier where production concentrates among limited Jiangsu-based suppliers. Distribution runs through regional chemical distributors serving Southeast Asian contract manufacturers and direct technical service relationships with marine coatings specialists in South Korea and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between European regulatory compliance costs and Asian manufacturing scale, with ECHA dossier investments in Germany and France running substantially above SAMR-qualification expenditures in China.
For Market Incumbents: To counter substitution testing by European cosmetic brands evaluating climbazole alternatives, deepen captive pyrithione chemistry operations and accelerate micronization capacity additions in India to serve Middle Eastern and African export markets. Prioritize ECHA biocidal product authorization maintenance over standard-grade volume defense. For New Entrants and Emerging Players: Indian pharmaceutical excipient buyers seeking CDSCO-qualified ultra-pure grades for topical antifungal creams represent the most penetrable white-space target. Pursue regulatory filing partnerships with Mumbai-based formulators and leverage specialty particle engineering capabilities as the primary go-to-market angle. For Investors and Strategic Acquirers: Personal care chemical specialists with backward-integrated antimicrobial portfolios are the most active acquirers in this space. Long-term viability over a multi-year horizon rests on particle engineering capabilities and regulatory dossier libraries rather than commodity trading positions. Monitor ECHA CLP hazard classification determinations for respiratory sensitization as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pyrithione Chemistry | Lonza's captive precursor production insulates margin control from sodium pyrithione supply volatility. |
| Micronization Capacity Expansion | Jet milling investments in Gujarat and Jiangsu capture premium formulation demand from Korean beauty brands. |
| ECHA Biocidal Product Authorization | Dossier completion secures European market access against REACH-driven substitution threats. |
| Technical Service Partnership | Chugoku Kogyo's marine coatings relationships lock in liquid suspension volumes with Japanese shipyards. |
| Regulatory Filing for Pharmaceutical Grades | CDSCO and FDA drug master file support opens topical antifungal excipient channels beyond shampoo uses. |
Research Methodology
Coverage spans China, Germany, Japan, India, and the United States, with primary inputs from each market. Conversations with plant managers at pyrithione chemistry facilities, procurement leads at personal care contract manufacturers, distribution channel partners in Southeast Asia, and technical R&D directors at marine coatings specialists informed demand-side assessments. Secondary validation drew from SAMR GB standard publications, ECHA biocidal product registration databases, EPA FIFRA filings, and customs trade records. Bottom-up grade-volume estimates triangulated against top-down end-use consumption models.
Rate-of-change decomposition across the analysis window disaggregated expansion into particle size tier shifts, regulatory authorization status migrations, and geographic manufacturing relocation patterns. Segmentation dimensions modeled include product grade, application end-use, end user industry, and supply form. CAGRs derived from regression analysis against macro-indicators and industry-specific drivers including shipyard activity indices, personal care export volumes from Thailand and Vietnam, and ECHA regulatory timeline assumptions.
Inputs from regulatory filing databases and trade flow records were available through the study window; gaps in real-time inventory positions at Chinese precursor producers introduce uncertainty bands around near-term price trajectory assumptions. Forecasts reflect documented assumptions regarding REACH implementation timelines and SAMR enforcement intensity. Material deviation in ECHA hazard classification determinations or MEE environmental compliance actions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
1, 4 Butanediol Market
Chemicals
Pentanedione Market
Chemicals
Sodium Cyanide Market
Chemicals
Methoprene Market
Chemicals
Glyoxal Market
Chemicals
Electronic Grade Choline Hydroxide Market
Chemicals
Malonic Acid Market
Chemicals
Anticoagulant Rodenticides Market
Chemicals
Roofing Chemical Market
Chemicals
Solder Flux Market
Chemicals
Phosgene Market
Chemicals
Canada Methanol Market
Chemicals
Global Anhydrous Aluminum Chloride Market
Chemicals
Methylamines Market
Chemicals
1-Methylimidazole Market
Chemicals
Fluorene Market