
 Fine Chemicals Market | 2026-2036
Fine Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Fine Chemicals Market Analysis
Specialized process chemistry talent is bifurcating the competitive landscape, separating firms with captive PhD-level synthesis teams from commodity-dependent operators. BASF SE leverages its Ludwigshafen integrated site to sustain captive intermediate supply for pharmaceutical and agrochemical clients. Lonza Group Ltd anchors its position through biologics-focused contract development and manufacturing across Swiss and US facilities. Evonik Industries AG differentiates via high-purity silanes and specialty amines for semiconductor and medical applications.
Fine chemicals encompass high-purity, low-volume substances synthesized through multi-step reactions with stringent impurity profiles typically below 0.1 percent, serving as critical inputs for pharmaceuticals, agrochemicals, and advanced materials. Pharmaceutical intermediates command the deepest margin pools due to validation requirements and customer stickiness, while specialty chemicals for electronics is the fastest-expanding category as chip fabrication nodes advance below three nanometers. Agrochemical actives remain mature with consolidation pressure, and biotech applications in delivery mode are gaining traction as peptide and oligonucleotide therapies proliferate.
REACH in Europe, EPA toxics release protocols in the United States, and NMPA registration pathways in China collectively elevate compliance costs and screen out sub-scale producers. These frameworks push buyers toward audited suppliers with documented quality management systems, reinforcing concentration among integrated manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions and assess whether regional certification investments justify access premiums in fragmented end-use segments.
Market Dynamics
Pharmaceutical contract manufacturing is consolidating demand around audited suppliers with captive synthesis capabilities, compressing margins for non-integrated operators while rewarding firms with validated multi-step production infrastructure.
Growth Catalysts
- Biologics Pipeline Expansion:Peptide and oligonucleotide therapies are multiplying demand for high-purity intermediates with impurity profiles below 0.1 percent.
- REACH and EU Green Deal:Tightening solvent restrictions and purity benchmarks are screening out sub-scale producers across European pharmaceutical and agrochemical supply chains.
- Semiconductor Node Advancement:Chip fabrication below three nanometers is accelerating consumption of electronic-grade specialty amines and high-purity silanes.
Market Restraints
- Specialized Talent Scarcity:PhD-level process chemistry expertise concentrates in Swiss and German industrial clusters, constraining expansion elsewhere.
- Input Cost Volatility:Noble metal catalysts and rare earth precursors face supply concentration in Chinese processing facilities.
- Regulatory Divergence:Misalignment between EPA toxics protocols, REACH substance restrictions, and NMPA registration pathways multiplies compliance overhead for multi-jurisdictional suppliers.
Strategic Opportunities
- Indian API Manufacturing:PLI scheme incentives and CDSCO pathway streamlining are attracting contract development investment for export-oriented production.
- Continuous Flow Chemistry:Integration of microreactor systems with AI-driven process control is opening greenfield capacity with reduced solvent waste profiles.
- Biotech Delivery Modes:Lipid nanoparticle and polymer conjugation chemistries for mRNA and siRNA therapeutics represent underpenetrated synthesis demand.
Industry Challenges
- Validation Timeline Compression:FDA and EMA quality management system audits now require eighteen-to-twenty-four month documentation cycles before commercial supply authorization.
- Legacy Equipment Retrofit Costs:Stainless-steel batch reactors face obsolescence pressure from single-use bioreactor standards, demanding capital redeployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fine Chemicals Market |
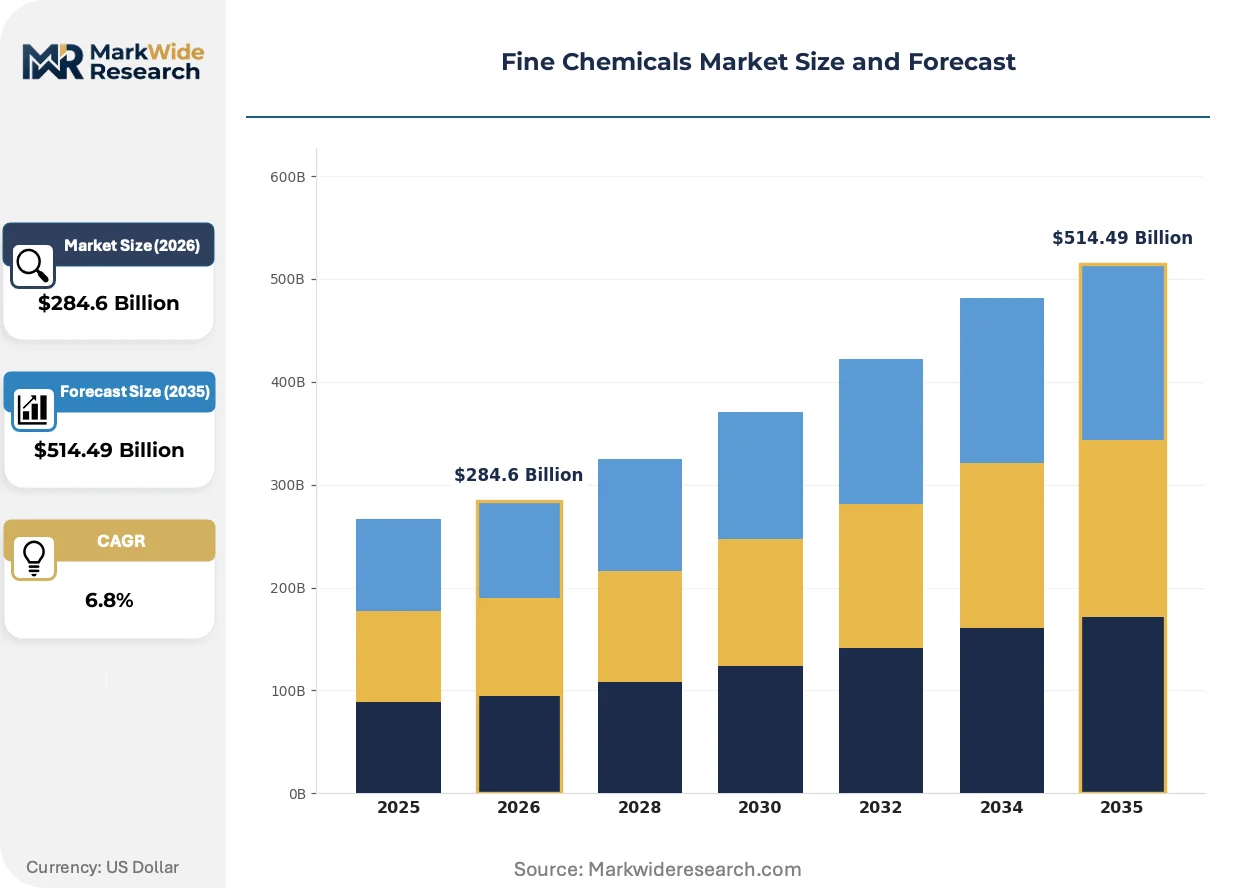
| Market Size in 2026 | $284.6 Billion |
| Market Size in 2035 | $514.49 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intermediates, Agrochemicals, Pharmaceuticals, Specialty Chemicals Application: Biotech, Electronics, Food & Beverage, Cosmetics End User: Manufacturers, Research Institutions, Laboratories, Textile Industry Delivery Mode: Bulk, Liquid, Powder, Specialty Formulations |
| Companies Covered | BASF SE, Lonza Group Ltd, Evonik Industries AG, Clariant AG, Albemarle Corporation, Lanxess AG, Nouryon, Huntsman International LLC, W.R. Grace & Co, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fine Chemicals Market Emerging Trajectories
Process intensification and regulatory digitization are restructuring how fine chemicals move from laboratory synthesis to validated commercial supply, with automation and sustainability metrics now embedded in procurement specifications.
Continuous manufacturing technology is bifurcating the competitive landscape between agile, modular production systems and legacy batch infrastructure. Pharmaceutical and agrochemical formulators are prioritizing suppliers with demonstrated flow chemistry capabilities for hazardous intermediate steps. This technology is compressing campaign changeover times from weeks to days while reducing solvent waste volumes by orders of magnitude.
REACH authorization requirements and the EU Green Deal's carbon border adjustment mechanisms are elevating lifecycle assessment documentation to a contractual prerequisite. European pharmaceutical buyers now mandate cradle-to-gate emission disclosures for solvent-intensive intermediates. Suppliers without verified environmental footprint data are losing qualified vendor status across German and French manufacturing networks.
Buyers are consolidating supplier panels around integrated manufacturers with captive analytical and regulatory affairs functions. Electronic materials purchasers in Taiwan and South Korea now require dedicated quality agreements with real-time batch release data access. This concentration pattern favors operators with Ludwigshafen-scale integrated sites over fragmented toll-manufacturing networks.
Fine Chemicals Market Segmentation
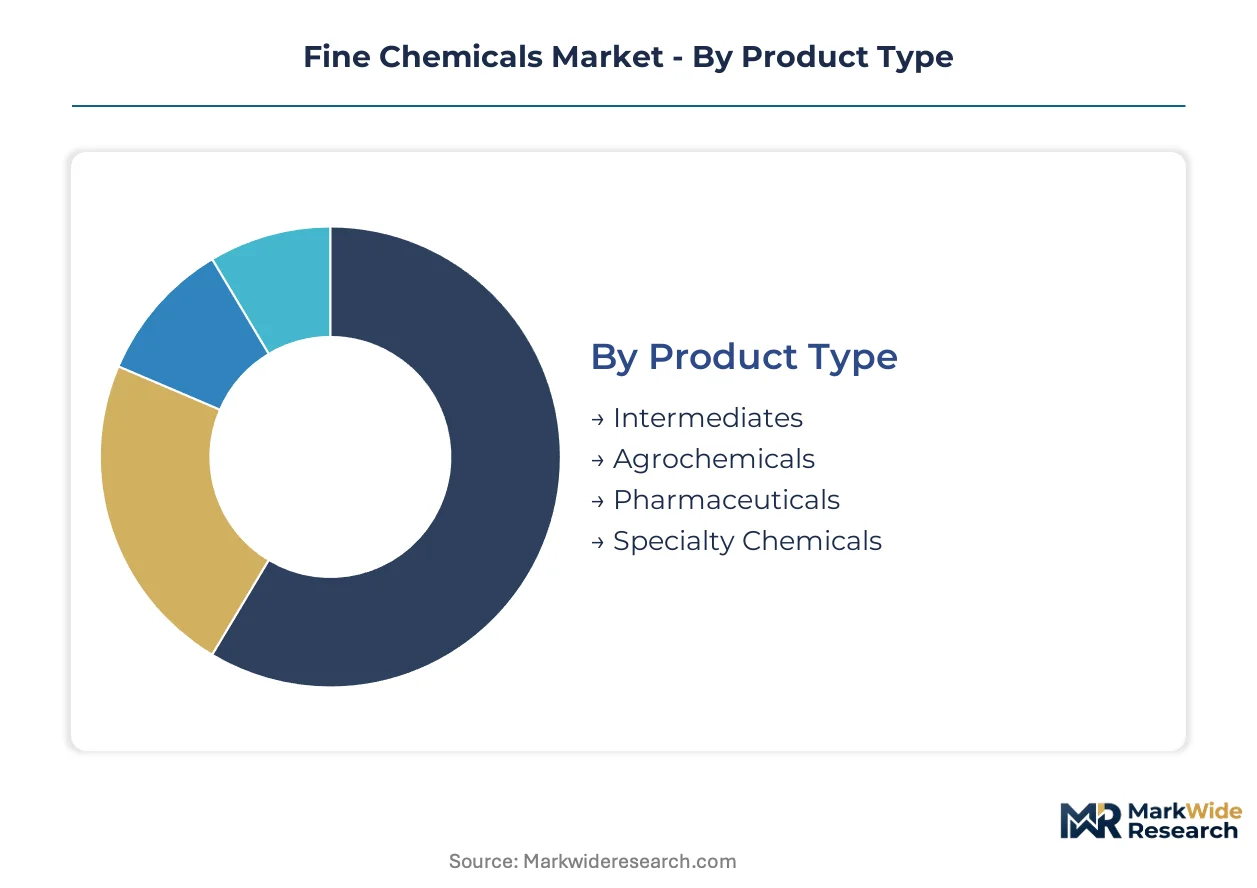
Fine chemicals segmentation reveals divergent margin structures and regulatory exposure across product categories. Pharmaceutical intermediates and electronic-grade specialties command premium pricing validated through multi-jurisdiction audits, while commodity agrochemicals face consolidation pressure.
Product Type:
Domestic production clusters in Germany, Switzerland, and China serve distinct export markets, with pharmaceutical intermediates shipping globally and agrochemical actives concentrated in regional crop protection networks.
- Intermediates:Multi-step synthetic compounds with impurity profiles below 0.1 percent serve as building blocks for downstream active pharmaceutical ingredients. Demand concentrates in Swiss and German CDMO networks serving FDA and EMA-validated supply chains, with REACH solvent restrictions elevating compliance costs for non-integrated producers.
- Specialty Chemicals:High-purity silanes, amines, and electronic-grade solvents meet semiconductor fabrication specifications at nodes below three nanometers. Taiwan and South Korean chip foundries drive fastest uptake, with NMPA-registered Chinese suppliers expanding domestic substitution programs.
- Pharmaceuticals:Finished active ingredients and registered starting materials for generic and innovator drug programs.
- Agrochemicals:Herbicide, fungicide, and insecticide actives with mature demand curves and consolidation pressure among European formulators.
Pharmaceutical intermediates hold the largest share; momentum sits with specialty chemicals for semiconductor applications.
Application:
End-use concentration shapes supply chain configuration, with biotech applications demanding validated multi-step synthesis and electronics procurement requiring real-time batch release documentation.
- Electronics:Photoresist solvents, etchant gases, and deposition precursors for advanced lithography processes. South Korean and Taiwanese manufacturers anchor demand, with EU Green Deal carbon border adjustments adding documentation overhead for imported intermediates.
- Biotech:Lipid nanoparticle chemistries, peptide synthesis reagents, and oligonucleotide building blocks for mRNA and gene therapy platforms. Swiss and Boston-area biotech clusters drive specification development, with CDSCO pathway streamlining in India attracting contract manufacturing investment.
- Cosmetics:Preservative systems, active ingredients, and formulation excipients with REACH cosmetic regulation compliance requirements.
- Food & Beverage:Flavor and fragrance molecules, preservative actives, and processing aids with FSSAI and FDA food contact approvals.
Biotech applications command the steepest expansion trajectory; electronics maintains the deepest margin pool.
End User:
Customer type determines contract structure, with multinational manufacturers demanding captive synthesis partnerships and research institutions accepting catalog-sourced materials.
- Manufacturers:Pharmaceutical, agrochemical, and electronics formulators with validated supplier qualification programs. German and French networks prioritize Ludwigshafen-scale integrated sites with cradle-to-gate emission disclosures under EU Green Deal procurement mandates.
- Research Institutions:Academic and government laboratories with small-volume, high-mix requirements and flexible specification tolerance.
- Laboratories:Contract research and analytical service providers with ISO-certified quality expectations.
- Textile Industry:Dye intermediates, finishing agents, and functional coatings with regional concentration in Chinese and Indian processing hubs.
Manufacturers dominate volume; research institutions represent the most fragmented procurement pattern.
Delivery Mode:
Physical form factors align with end-use handling requirements and regulatory documentation, with specialty formulations commanding premium positioning for hazardous or temperature-sensitive actives.
- Specialty Formulations:Pre-mixed solutions, stabilized dispersions, and controlled-release preparations for sensitive biologics and electronic materials. Swiss and US facilities lead validated formulation capabilities, with single-use bioreactor standards displacing legacy stainless-steel infrastructure.
- Bulk:Tanker and drum quantities of standard-grade solvents and reagents for high-volume manufacturing.
- Liquid:Pumpable intermediates with defined viscosity and moisture specifications for continuous flow chemistry integration.
- Powder:Crystalline actives and lyophilized materials with particle size distribution controls for solid dosage and powder coating applications.
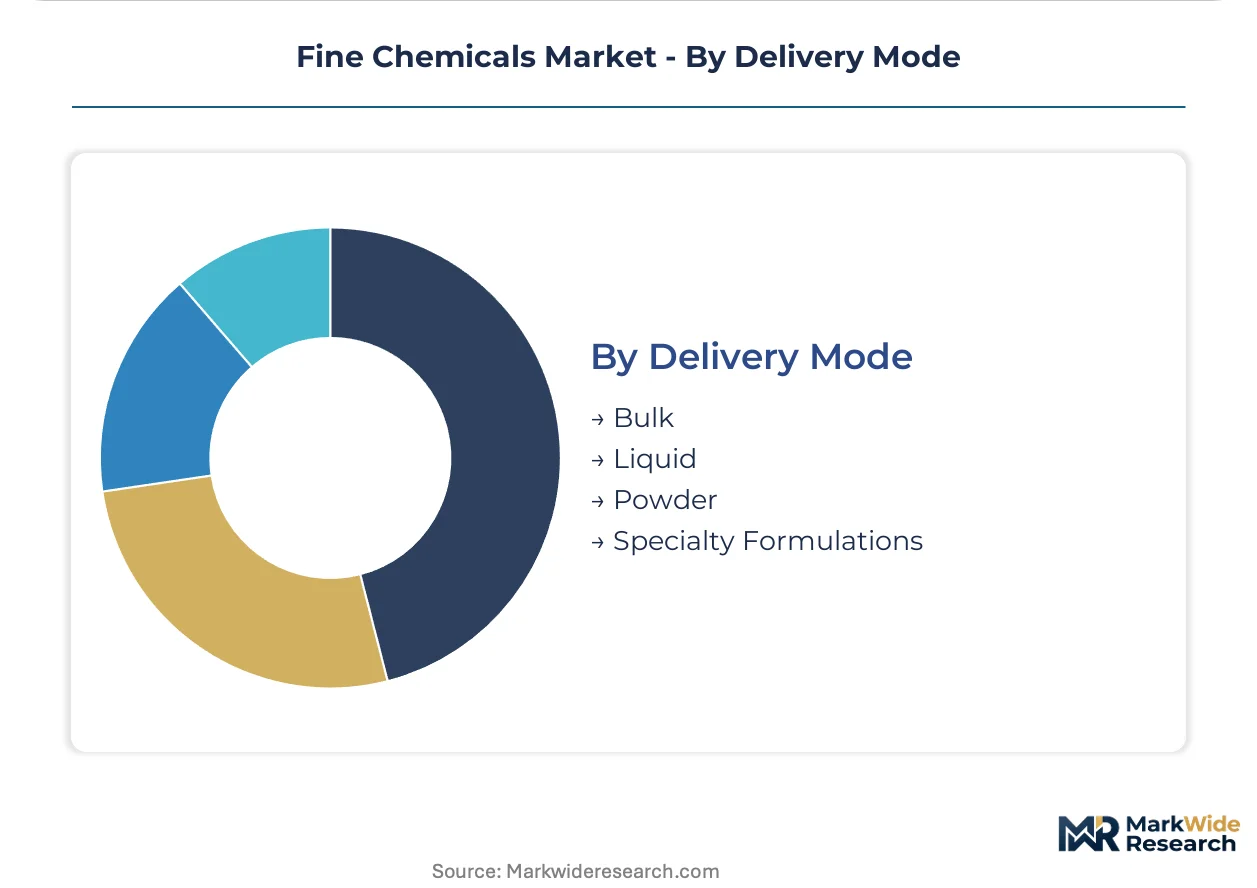
Bulk delivery holds the largest share; specialty formulations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH and the EU Green Deal are reshaping procurement specifications across German and French pharmaceutical networks, while NMPA registration pathways in China and CDSCO streamlining in India redirect contract manufacturing investment toward Asia-Pacific production clusters.
United States
Peptide and oligonucleotide therapy developers in Greater Boston and the San Francisco Bay Area are driving demand for high-purity synthesis reagents. EPA toxics release protocols now mandate documented solvent waste profiles for commercial suppliers. New Jersey and North Carolina chemical manufacturing corridors concentrate validated production infrastructure serving FDA-audited supply chains.
Germany
Ludwigshafen and Leverkusen industrial complexes anchor captive intermediate supply for pharmaceutical and agrochemical formulators. REACH authorization requirements now require cradle-to-gate emission disclosures for solvent-intensive procurement. Bavarian specialty chemical producers are retrofitting batch infrastructure to meet EU Green Deal carbon border adjustment documentation standards.
Switzerland
Basel-area biotech clusters specify lipid nanoparticle chemistries and polymer conjugation reagents for mRNA therapeutic platforms. Swissmedic validation protocols exceed EMA baseline requirements for commercial supply authorization. Visp and Monthey production sites concentrate PhD-level process chemistry expertise for multi-step synthesis campaigns.
China
Domestic API and electronic-grade chemical output is expanding across Zhejiang and Jiangsu provincial manufacturing bases. NMPA registration pathways now screen foreign suppliers while accelerating local substitution programs. Shanghai and Suzhou industrial parks concentrate semiconductor precursor production for sub-three-nanometer fabrication nodes.
India
Hyderabad and Ahmedabad API manufacturing clusters are attracting contract development investment through PLI scheme incentives. CDSCO pathway streamlining reduces registration timelines for export-oriented production. Gujarat and Telangana state industrial corridors concentrate stainless-steel batch reactor capacity serving generic drug formulators.
Fine Chemicals Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated manufacturers with captive synthesis and analytical capabilities command premium positioning in pharmaceutical and electronics supply chains. Three archetypes dominate: Ludwigshafen-scale integrated sites, Swiss-US biologics-focused CDMOs, and Asian cost-optimized API producers. Competitive moves concentrate on M&A for validated capacity and strategic partnerships for biotech delivery mode chemistries.
Among German-integrated chemical conglomerates, BASF SE and Evonik Industries AG exemplify the captive intermediate supply archetype, while Lonza Group Ltd represents the Swiss-based biologics CDMO positioning. These three entities anchor different competitive vectors within the market structure, with each occupying a distinct tier based on geographic concentration and end-use specialization.
| Leading Market Players |
|---|
| BASF SE |
| Lonza Group Ltd |
| Evonik Industries AG |
| Clariant AG |
| Albemarle Corporation |
| Lanxess AG |
| Nouryon |
| Huntsman International LLC |
| W.R. Grace & Co |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four month validation timelines for FDA and EMA quality management system audits compress working capital cycles and amplify pricing power for integrated manufacturers with captive analytical capabilities, while screening out toll-manufacturing competitors across pharmaceutical and electronics supply chains.
Pricing Analysis
Pharmaceutical intermediates in Swiss and German CDMO networks command 40-60 percent premiums over Indian API equivalents due to REACH-validated impurity profiles below 0.1 percent and documented cradle-to-gate emission disclosures. Pricing stratifies across premium electronic-grade specialties for sub-three-nanometer semiconductor nodes, standard pharmaceutical building blocks, and economy agrochemical actives facing consolidation pressure. Cost compression in commodity agrochemicals is intensifying because European formulators are consolidating supplier panels around Ludwigshafen-scale integrated sites. Research institutions exhibit the highest price sensitivity due to small-volume procurement, while Taiwanese chip foundries prioritize specification compliance over unit economics.
Supply Chain Analysis
Six-to-nine month campaign changeover times for legacy stainless-steel batch reactors extend inventory cycles and elevate working capital requirements relative to continuous flow chemistry systems with compressed solvent waste profiles. Manufacturing concentrates in Germany, Switzerland, and China, with domestic API and electronic-grade chemical output expanding across Zhejiang and Jiangsu provincial bases. Noble metal catalysts and rare earth precursors draw from Chinese processing facilities, creating single-source vulnerability for non-integrated producers. Distribution runs through validated supplier qualification programs with real-time batch release data access, favoring captive synthesis partnerships over fragmented toll-manufacturing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fine chemicals markets are recovering from cyclical trough conditions as biologics pipeline expansion for peptide and oligonucleotide therapies reactivates capacity utilization across Swiss and US CDMO networks.
For Market Incumbents: Secure captive intermediate supply positions through backward integration into high-purity silane and specialty amine production for semiconductor applications, while retrofitting legacy batch infrastructure to meet single-use bioreactor standards demanded by mRNA therapeutic developers. European REACH authorization requirements and EU Green Deal carbon border adjustments threaten non-compliant competitors, creating acquisition opportunities for validated capacity. Certification investment in NMPA-registered Chinese facilities offers geographic hedge against regulatory divergence. For New Entrants and Emerging Players: Anchor in Indian API manufacturing clusters through PLI scheme incentives and CDSCO pathway streamlining for export-oriented production, targeting generic drug formulators seeking alternatives to Chinese supply concentration. Lipid nanoparticle chemistries for biotech delivery modes represent the most penetrable white-space segment, with Swiss and Boston-area clusters driving specification development but constrained by PhD-level talent scarcity. Partner with established CDMOs for technology transfer rather than greenfield capacity builds. For Investors and Strategic Acquirers: Carve-out targets emerge from German chemical conglomerates divesting non-core agrochemical actives under EU consolidation pressure, particularly Bavarian specialty producers lacking continuous flow capabilities. Long-term viability centers on biologics-focused positioning with demonstrated multi-step synthesis expertise and validated quality management systems. Monitor FDA and EMA audit backlogs as inflection indicator for pricing power recovery in pharmaceutical intermediates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Precursors | Captive supply of electronic-grade silanes secures semiconductor foundry relationships against Chinese substitution programs. |
| Continuous Flow Chemistry Adoption | Microreactor integration with AI-driven process control reduces solvent waste and compresses campaign changeover timelines. |
| REACH-Validated Quality Certification | Cradle-to-gate emission documentation preserves qualified vendor status across German and French pharmaceutical networks. |
| Indian Manufacturing Footprint Expansion | PLI scheme incentives and CDSCO streamlining attract contract development investment for export-oriented API production. |
| Biotech Delivery Mode Partnership | Lipid nanoparticle chemistry capabilities capture synthesis demand from mRNA and siRNA therapeutic pipelines. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with plant managers at integrated chemical sites, procurement leads at pharmaceutical and electronics OEMs, distribution channel partners, and technical R&D directors; and secondary validation against customs and trade data, Cefic industry reports, SEC 10-K filings, and regulatory submission databases. Bottom-up capacity and utilization estimates were triangulated with top-down demand projections from end-use industry consumption patterns.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product grade tier, end-use industry concentration, packaging format, and regional production hub clustering. CAGRs were derived from segment-level growth rate reconciliation with macroeconomic drivers and industry-specific inputs including semiconductor node advancement schedules and biologics pipeline stage distributions.
Decision-makers should treat outputs as directional under assumptions of sustained REACH enforcement and continued biologics investment; material deviation in regulatory stringency or therapeutic platform shifts would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Integrated Chemistry Systems Market
Chemicals
HATU Market
Chemicals
Thiourea Market
Chemicals
India Ethoxylates Market
Chemicals
Global Organobromine Market
Chemicals
Negative Photoresist Chemicals Market
Chemicals
Spirodiclofen Market
Chemicals
Industrial Odor Management Market
Chemicals
Cumene Hydroperoxide Market
Chemicals
Natural Fatty Alcohols Market
Chemicals
Indonesia Nitric Acid Market
Chemicals
Nonaisoprenol Market
Chemicals
Hydrogenated Dimer Acid Market
Chemicals
P-Ethylphenol Market
Chemicals
Potassium Iodide Market
Chemicals
Coagulant Market