
 Micro Fulfillment Market | 2026-2036
Micro Fulfillment Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Fulfillment Market Foresight
Lightweight aluminum framing is repositioning capital expenditure structures for micro fulfillment infrastructure, cutting facility weight loads and accelerating vertical buildouts. AutoStore leverages dense cube-storage topology to dominate footprint-constrained urban installations. Fabric anchors its competitive stance through proprietary robotic shuttle systems designed for sub-10,000-square-foot footprints. Attabotics differentiates via three-dimensional robotic storage that collapses fulfillment aisles into single vertical columns.
Micro fulfillment denotes automated, compact warehouse systems—typically 3,000 to 10,000 square feet—deployed within or adjacent to urban demand centers, utilizing robotic goods-to-person retrieval, conveyor networks, and real-time inventory software to execute e-commerce and grocery orders within hours. Artificial Intelligence and Machine Learning segments command the deepest R&D allocation as predictive demand positioning and dynamic slotting algorithms determine labor efficiency and throughput ceilings. Robotics deployment in automated systems captures the fastest expansion trajectory, though hybrid models retaining human pickers retain margin advantages in SKUs with irregular dimensions or temperature requirements.
OSHA workplace safety standards and the EU Machinery Directive shape robotic deployment protocols, mandating collaborative robot speed limits and emergency stop architectures that influence system design costs. The EU AI Act introduces risk-classification requirements for automated decision systems in logistics, compelling vendors to document algorithmic transparency for high-throughput fulfillment operations. Stakeholders must weigh regulatory compliance spend against automation density targets when calibrating facility rollouts.
Market Dynamics
Urban labor scarcity across the United States, Germany, and China is forcing grocery retailers to compress fulfillment footprints into sub-10,000-square-foot automated facilities adjacent to demand centers. This structural pressure is reconfiguring capital deployment toward dense vertical storage and robotic goods-to-person systems.
Growth Catalysts
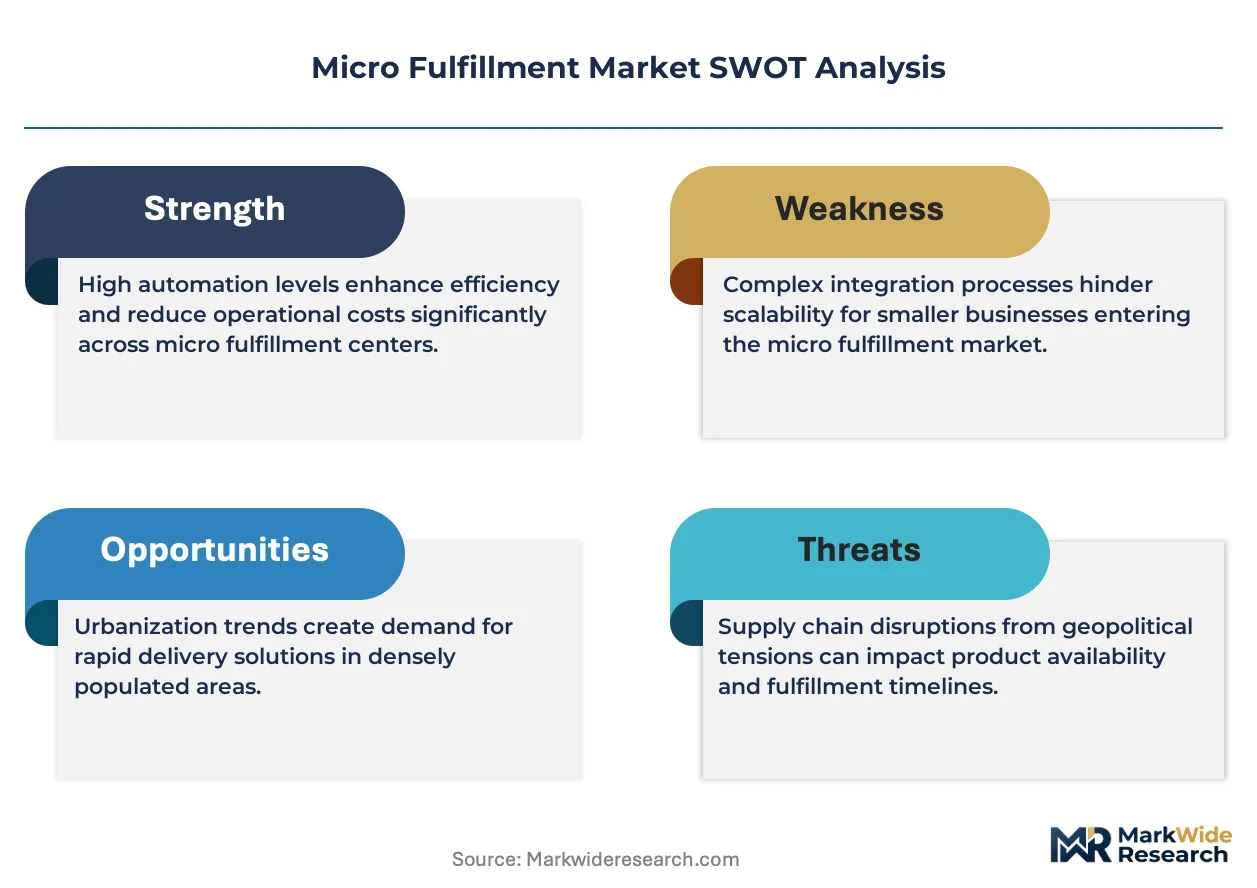
- OSHA workplace safety standards:Mandated collaborative robot speed limits and emergency stop architectures are accelerating insurance cost reductions for automated facilities in the United States.
- Grocery retail labor compression:Order cycle time requirements below two hours in dense urban zones are pulling capital into micro fulfillment installations.
- Aluminum framing substitution:Lightweight structural materials are cutting facility weight loads and enabling vertical buildouts in footprint-constrained European city centers.
Market Restraints
- EU AI Act risk classification:Automated decision systems in high-throughput logistics face mandatory algorithmic transparency documentation, inflating compliance spend.
- Autonomous mobile robotics supply concentration:Component sourcing for robotic shuttles clusters among East Asian sensor and actuator suppliers.
- Irregular SKU handling limitations:Temperature-controlled and non-standard dimension products resist full automation, requiring hybrid human-robot labor models.
Strategic Opportunities
- EU Green Deal facility incentives:Energy-efficient automated warehousing qualifies for accelerated depreciation and carbon credit offsets across German industrial zones.
- China urban density corridors:Tier-one city cluster development is creating deployment economics for sub-5,000-square-foot neighborhood fulfillment nodes.
- AI-robotics convergence:Predictive demand positioning algorithms paired with autonomous retrieval systems are opening sub-hour delivery service tiers.
Industry Challenges
- Robotics integration with legacy WMS:Real-time inventory synchronization between existing enterprise software and new automated retrieval architectures demands specialized middleware development.
- Certification timeline compression:CE marking and FDA facility registration for food-adjacent automation are extending commissioning schedules in regulated environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Fulfillment Market |
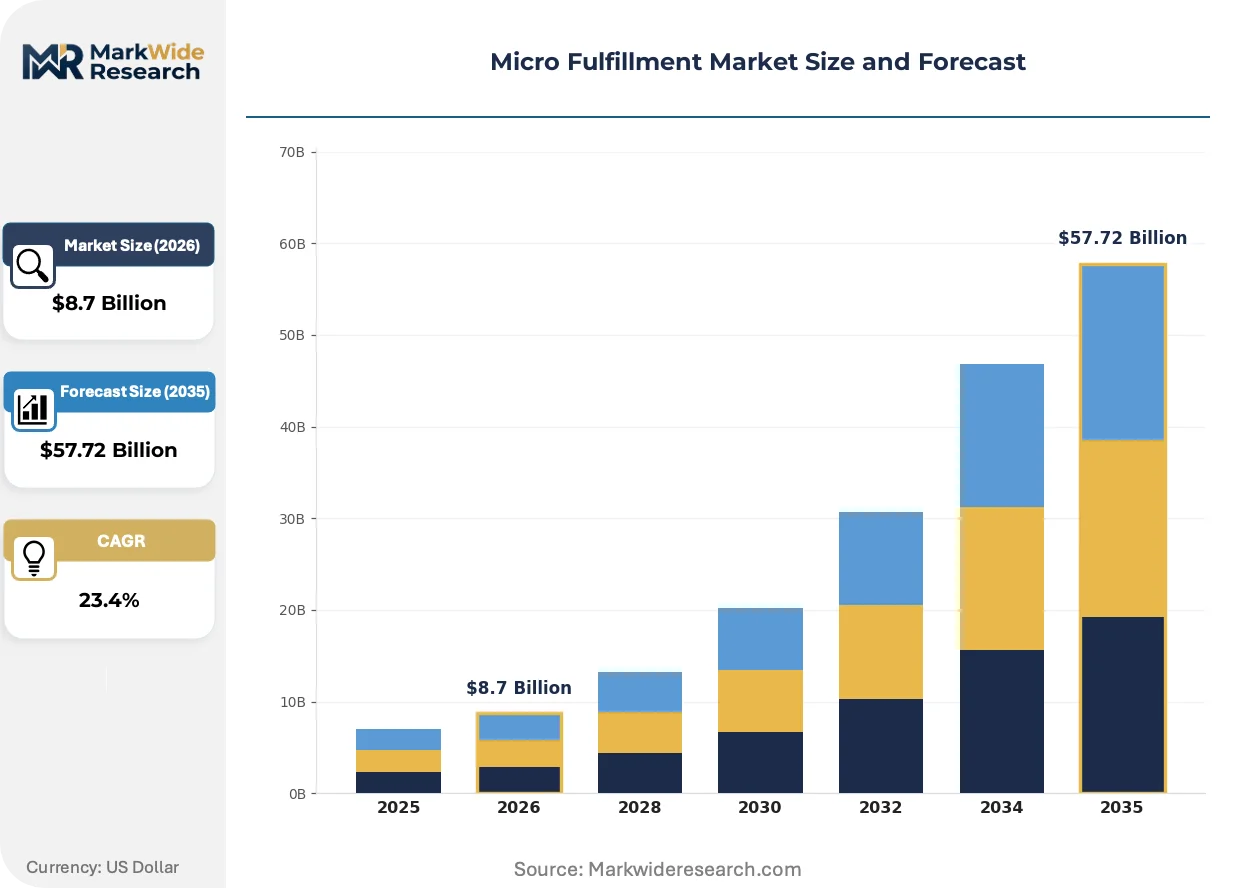
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $57.72 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Manual Solutions, Hybrid Models, Robotics End User: Grocery Retailers, E-commerce Platforms, Logistics Providers, Wholesalers Technology: Artificial Intelligence, Machine Learning, IoT, Cloud Computing Delivery Model: Same-day Delivery, Scheduled Delivery, On-demand Delivery, Subscription Services |
| Companies Covered | Deliverr, Flexe, Fabric, Thrive 3PL, Davinci Micro Fulfillment, Attabotics, ShipBob, Eco Fulfillment, AutoStore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Fulfillment Market Shifts & Advancements
Three-dimensional storage topology and AI-orchestrated inventory positioning are collapsing the physical footprint required for urban fulfillment. These innovations are restructuring how retailers balance automation density against regulatory compliance and legacy system compatibility.
Cube-based dense storage systems are overtaking traditional aisle-based warehouse layouts in urban micro fulfillment installations. Grocery retailers in the United States and Germany are deploying these configurations to maximize SKU density per square meter. This topology is overtaking conventional racking by eliminating travel time for human pickers and robotic shuttles alike.
The EU AI Act introduces risk-classification requirements for automated decision systems in logistics operations. High-throughput fulfillment vendors must now document algorithmic transparency for inventory slotting and demand prediction algorithms. European grocery chains are responding by segregating AI-driven processes into auditable modules to satisfy regulator scrutiny.
Urban consumers are compressing delivery expectation windows from same-day to sub-two-hour service tiers. This behavioral shift is disrupting centralized distribution models and pulling inventory positioning toward neighborhood-scale automated nodes. The transformation is most visible in United States coastal metros and Chinese tier-one cities where density supports micro fulfillment unit economics.
Micro Fulfillment Market Segmentation
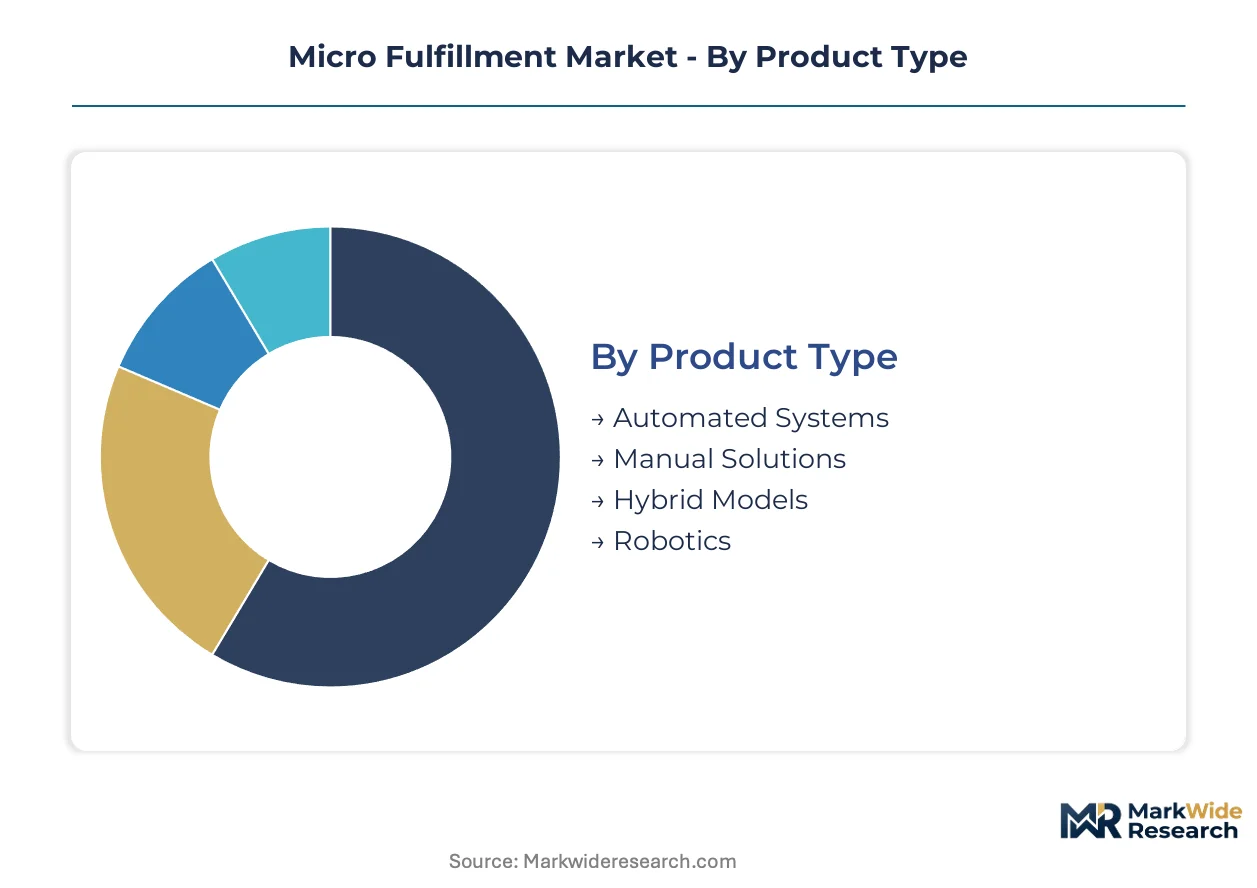
Segmentation in micro fulfillment reveals how automation intensity, end-use operational requirements, and delivery velocity expectations fragment capital deployment strategies. Distinct technology and service configurations emerge based on urban density, SKU complexity, and regulatory constraints across deployment zones.
Product Type:
Standardization dominates at the robotics and automated systems tier, while manual and hybrid solutions retain customization flexibility for irregular handling requirements.
- Automated Systems:Dense cube-storage topology with robotic goods-to-person retrieval compresses fulfillment cycles to under 30 minutes. Grocery retailers in Germany and the United States deploy these configurations where labor scarcity and OSHA collaborative robot standards permit high-density automation.
- Robotics:Autonomous mobile robots and shuttle systems navigate vertical storage columns, eliminating aisle traversal entirely. Demand concentrates in Chinese tier-one cities where urban land costs justify premium capital expenditure on three-dimensional storage infrastructure.
- Manual Solutions:Human picker workflows with basic conveyor assistance serve temperature-controlled and irregular-dimension SKUs resistant to full mechanization.
- Hybrid Models:Robotic retrieval paired with human handling for final packing accommodates produce, frozen goods, and fragile items in grocery micro fulfillment installations.
Leading the category by volume: Automated Systems. Growing fastest: Robotics.
End User:
Margin pressure and order cycle requirements divide end users between grocery operators facing sub-two-hour delivery mandates and logistics providers optimizing for multi-tenant density.
- Grocery Retailers:Fresh inventory velocity demands real-time slotting algorithms and temperature-zone robotics. United States coastal metros drive deployment as labor compression forces automation adoption in sub-10,000-square-foot urban facilities.
- E-commerce Platforms:General merchandise fulfillment prioritizes SKU breadth over temperature control, enabling denser robotic storage configurations with faster inventory turns.
- Logistics Providers:Multi-tenant micro fulfillment nodes aggregate demand across retailers, requiring flexible warehouse management system integration and modular robotics architectures.
- Wholesalers:Case-pick and pallet-pick operations in urban adjacency locations serve restaurant and small-format retail replenishment with hybrid automation approaches.
Grocery Retailers command the largest installed base. E-commerce Platforms exhibit the steepest expansion trajectory.
Technology:
Algorithmic sophistication separates high-throughput operations from basic automation, with AI and machine learning commanding disproportionate R&D allocation against infrastructure hardware.
- Artificial Intelligence:Predictive demand positioning and dynamic slotting algorithms determine labor efficiency ceilings in high-SKU-density facilities. EU AI Act documentation requirements for automated decision systems add compliance overhead to European deployments.
- Machine Learning:Demand forecasting models trained on hyperlocal consumption patterns optimize inventory pre-positioning for sub-hour delivery service tiers in Chinese and United States urban corridors.
- IoT:Sensor networks track robotic shuttle health, environmental conditions, and inventory location with sub-meter precision.
- Cloud Computing:Distributed order management and real-time inventory synchronization enable multi-node fulfillment orchestration across metropolitan networks.
Artificial Intelligence leads technology spend. Machine Learning is gaining share fastest in demand prediction applications.
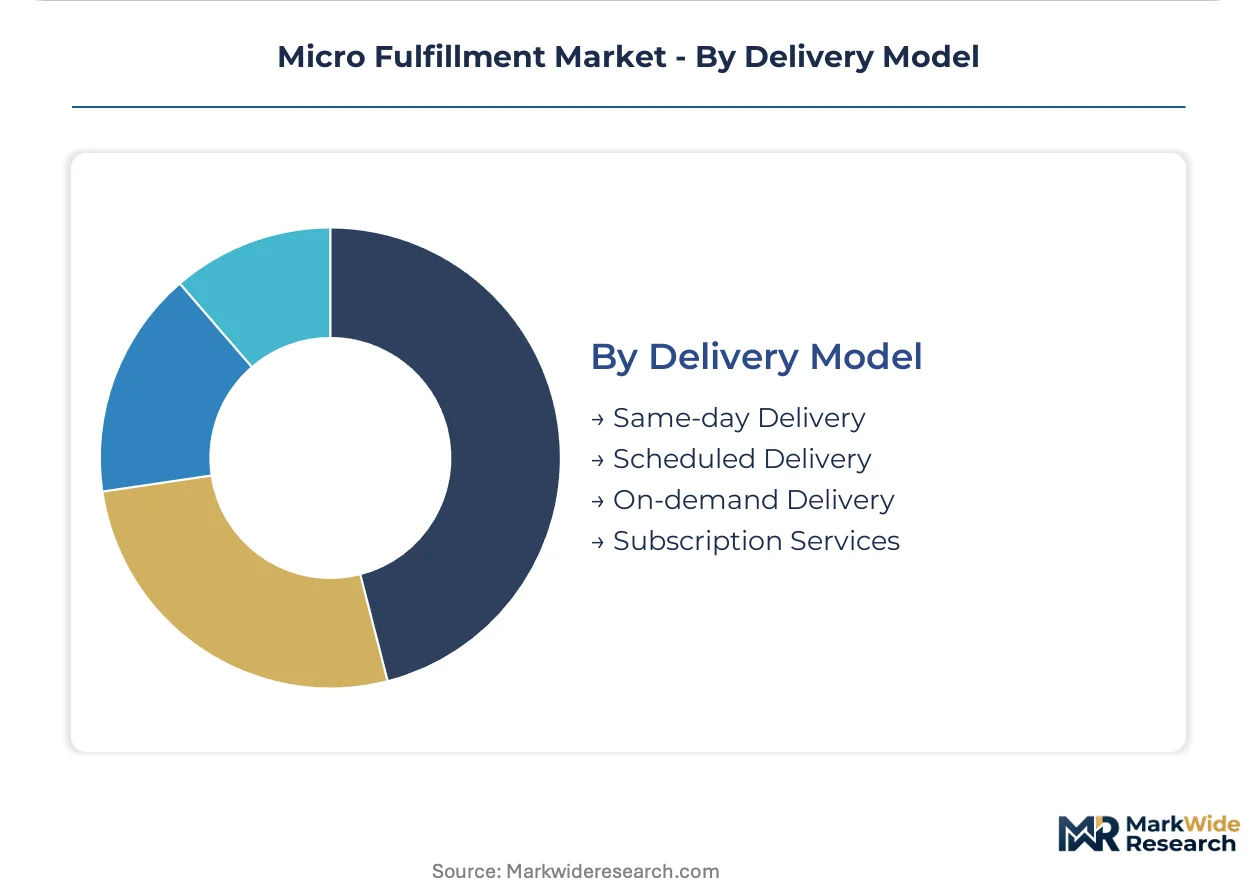
Delivery Model:
Velocity expectations stratify infrastructure investment, with on-demand and same-day configurations requiring neighborhood-scale node density against centralized distribution economics.
- Same-day Delivery:Batch-pick workflows with scheduled dispatch windows optimize robotic throughput in United States and German grocery operations where delivery density supports route consolidation.
- On-demand Delivery:Sub-two-hour service tiers demand inventory positioning within five kilometers of demand clusters, pulling capital into sub-5,000-square-foot neighborhood nodes in Chinese tier-one cities.
- Scheduled Delivery:Fixed-window fulfillment permits centralized micro fulfillment with longer lead times, reducing robotics redundancy requirements.
- Subscription Services:Predictable demand patterns enable pre-positioned inventory and optimized pick paths for recurring basket configurations in European urban markets.
Same-day Delivery holds the largest operational footprint. On-demand Delivery is climbing the fastest as consumer expectations compress across urban markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for micro fulfillment infrastructure concentrates in urban corridors where land scarcity and labor compression intersect. The United States, Germany, and China anchor deployment volumes, with facility economics driven by last-mile cost thresholds and grocery retailer automation mandates.
United States
Coastal metros including New York, Los Angeles, and Seattle drive facility deployment as grocers face sub-two-hour delivery mandates. OSHA collaborative robot standards shape system architecture, mandating speed limits and emergency stop protocols that influence vendor selection. Chicago and Dallas-Fort Worth emerge as inland hubs where hybrid automation models serve temperature-controlled grocery SKUs.
Germany
Urban labor scarcity in Berlin, Hamburg, and Munich accelerates capital inflow into dense vertical storage installations. The EU AI Act imposes algorithmic transparency requirements on automated inventory slotting systems, inflating compliance documentation spend. The Ruhr industrial corridor hosts pilot deployments leveraging EU Green Deal accelerated depreciation for energy-efficient warehousing infrastructure.
China
Tier-one city clusters in Shanghai, Beijing, and Shenzhen create deployment economics for sub-5,000-square-foot neighborhood fulfillment nodes. National dual carbon goals channel investment toward energy-efficient automated systems in urban logistics. The Yangtze River Delta region leads in three-dimensional robotic storage adoption as e-commerce platforms compress delivery windows.
United Kingdom
London and the Southeast concentrate grocery retailer automation investments amid post-Brexit labor market tightening. CE marking requirements for robotic systems extend commissioning timelines, favoring vendors with established European certification pathways. The Midlands logistics corridor sees multi-tenant micro fulfillment node development serving e-commerce aggregation demand.
Canada
Toronto and Vancouver anchor deployment as cross-border e-commerce fulfillment requirements intensify. Health Canada facility registration for food-adjacent automation shapes vendor qualification protocols in grocery applications. The Greater Toronto Area emerges as a testbed for hybrid human-robot models handling irregular-dimension fresh produce SKUs.
Micro Fulfillment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with technology-integrated solution providers commanding premium positioning against asset-light logistics platforms. The vendor base organizes around three archetypes: cube-storage topology specialists, proprietary robotic shuttle developers, and multi-tenant fulfillment operators. Consolidation pressure intensifies as grocery retailers demand turnkey integration capabilities spanning hardware, software, and last-mile orchestration. Strategic moves concentrate on vertical buildout partnerships and WMS middleware development.
Among North American automation specialists, AutoStore represents dense cube-storage topology deployment, while Attabotics exemplifies three-dimensional vertical column architectures. Fabric occupies a position within the sub-10,000-square-foot proprietary shuttle tier, serving footprint-constrained urban installations. These archetypes illustrate how vendor specialization maps to distinct facility scale and throughput requirements across grocery and e-commerce end uses.
| Leading Market Players |
|---|
| Deliverr |
| Flexe |
| Fabric |
| Thrive 3PL |
| Davinci Micro Fulfillment |
| Attabotics |
| ShipBob |
| Eco Fulfillment |
| AutoStore |
| Others |
Supply & Pricing Matrix
Aluminum framing costs cascade through micro fulfillment infrastructure tiers, with lightweight structural materials sourced from Chinese and German mills feeding into premium urban vertical buildouts while standard-grade steel alternatives anchor economy-tier suburban deployments. Labor scarcity in United States coastal metros compresses margins on manual-hybrid installations, redirecting procurement toward robotic goods-to-person systems that command higher upfront capital but defray wage inflation across the facility lifecycle.
Pricing Analysis
Volume concentration in grocery retail automation compresses margins for standardized cube-storage configurations, while project-based pricing prevails in custom three-dimensional vertical installations serving footprint-constrained European city centers. Price differentiation rests on certification tier—CE-marked robotic systems with documented EU AI Act algorithmic transparency command premiums against uncertified alternatives—and on geographic delivery cost, with German Ruhr corridor deployments benefiting from EU Green Deal accelerated depreciation offsets. Pricing pressure stems from East Asian sensor and actuator supply concentration inflating component costs for autonomous mobile robotics. E-commerce platforms exhibit highest price sensitivity due to multi-tenant throughput requirements, while grocery retailers with sub-two-hour delivery mandates absorb premiums for temperature-zone automation.
Supply Chain Analysis
Single-source vulnerability sits with East Asian suppliers of LiDAR sensors and precision actuators that feed robotic shuttle production for dense urban installations. Component sourcing clusters in China, South Korea, and Japan, with aluminum structural framing drawing from Chinese smelters and German extrusion specialists. Raw material dependencies span lithium-ion power cells, high-grade aluminum alloys, and machine-vision chipsets. Supply chain risk centers on tariff exposure affecting cross-border robotics component flows. Distribution runs through systems integrators who bundle hardware, warehouse management middleware, and commissioning services for grocery retailers and logistics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Robotic shuttle production capacity constraints in East Asian supplier networks prop pricing premiums for automated micro fulfillment systems, creating a supply-constrained market structure favoring incumbents with established component relationships.
For Market Incumbents: Lock in long-term offtake agreements with Chinese and South Korean sensor suppliers to secure actuator allocation against emerging entrant competition. Prioritize backward integration into aluminum framing production to capture margin from lightweight structural materials. Invest in EU AI Act documentation capabilities to defend certification-tier pricing premiums in European grocery retail deployments. For New Entrants and Emerging Players: EU Green Deal facility incentives in Germany open a window for energy-efficient vertical storage specialists to capture accelerated depreciation benefits. Target sub-5,000-square-foot neighborhood fulfillment nodes in Chinese tier-one cities where urban density corridors create deployment economics for compact installations. Lead with AI-orchestrated inventory positioning software as the go-to-market wedge, licensing predictive demand algorithms to established hardware vendors rather than competing on capital-intensive robotics manufacturing. For Investors and Strategic Acquirers: Grocery retailer automation mandates in United States coastal metros are the leading indicator that sub-two-hour delivery service tiers will consolidate vendor share toward turnkey integration providers. Position for a 5-to-10-year horizon where middleware developers bridging legacy WMS with robotic retrieval architectures become acquisition targets. Watch for tier-one Chinese city cluster development approvals as the signal that neighborhood-scale node economics have crossed threshold viability.| Strategic Initiative | Industry Significance |
|---|---|
| Vertical Buildout Partnership | Collaborative agreements with German aluminum suppliers secure lightweight framing allocation for dense urban installations. |
| WMS Middleware Development | Real-time inventory synchronization software bridges legacy enterprise systems with AutoStore and Attabotics retrieval architectures. |
| EU AI Act Compliance Certification | Documented algorithmic transparency for automated decision systems unlocks premium pricing in European grocery retail. |
| Robotics Component Supply Agreement | Long-term LiDAR and actuator contracts with South Korean suppliers mitigate single-source vulnerability. |
| Energy-Efficient Facility Design | EU Green Deal qualification for accelerated depreciation attracts capital into German Ruhr corridor pilot deployments. |
Research Methodology
Document review covered SEC filings from automation specialists, EU regulatory submissions for CE marking pathways, and OSHA collaborative robot safety standards, complemented by interviews with grocery retail operations executives, robotics systems integrators, warehouse management software architects, and aluminum framing procurement leads at facility developers. Secondary validation drew from customs trade data on robotics component flows, EU AI Act implementation guidance, and German industrial zone incentive disclosures. Bottom-up installation counts across United States, German, and Chinese urban corridors were triangulated against top-down capital expenditure estimates from grocery retailer automation announcements.
Segment-level outputs across the analysis window reflect modeled deployment trajectories for automated systems, robotics, hybrid models, and manual solutions, with end-use splits for grocery retailers, e-commerce platforms, logistics providers, and wholesalers. Technology segmentation incorporated AI and machine learning R&D allocation patterns, IoT sensor network density, and cloud computing orchestration penetration. CAGRs were derived from facility rollout velocity assumptions tied to urban labor compression metrics and last-mile cost thresholds.
The model assumes a particular technology adoption path; alternative pathways for autonomous mobile robotics in irregular-SKU handling would alter the outlook for hybrid human-robot labor models. Forecasts reflect assumptions about EU AI Act enforcement intensity, East Asian component supply continuity, and grocery retailer delivery window compression. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Data Center Automation Market
Automation
Workload Scheduling and Automation Market
Automation
APAC Water Automation and Instrumentation Market
Automation
Home Automation and Controls Market
Automation
Hyperautomation Market
Automation
Italy Process Orchestration Market
Automation
Home Automation System Market
Automation
Global Field Force Automation Market
Automation
Escalator Control Systems Market
Automation
Europe Laboratory Automation Market
Automation
Retail Automation Market
Automation
Lab Automation Market
Automation
Global Form Automation Software Market
Automation
Global Automated Liquid Handling System Market
Automation
Cognitive Process Automation Market
Automation
Global Smart Vending Machines Market