
 Distribution Automation Solutions Market | 2026-2036
Distribution Automation Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Distribution Automation Solutions Market Analysis
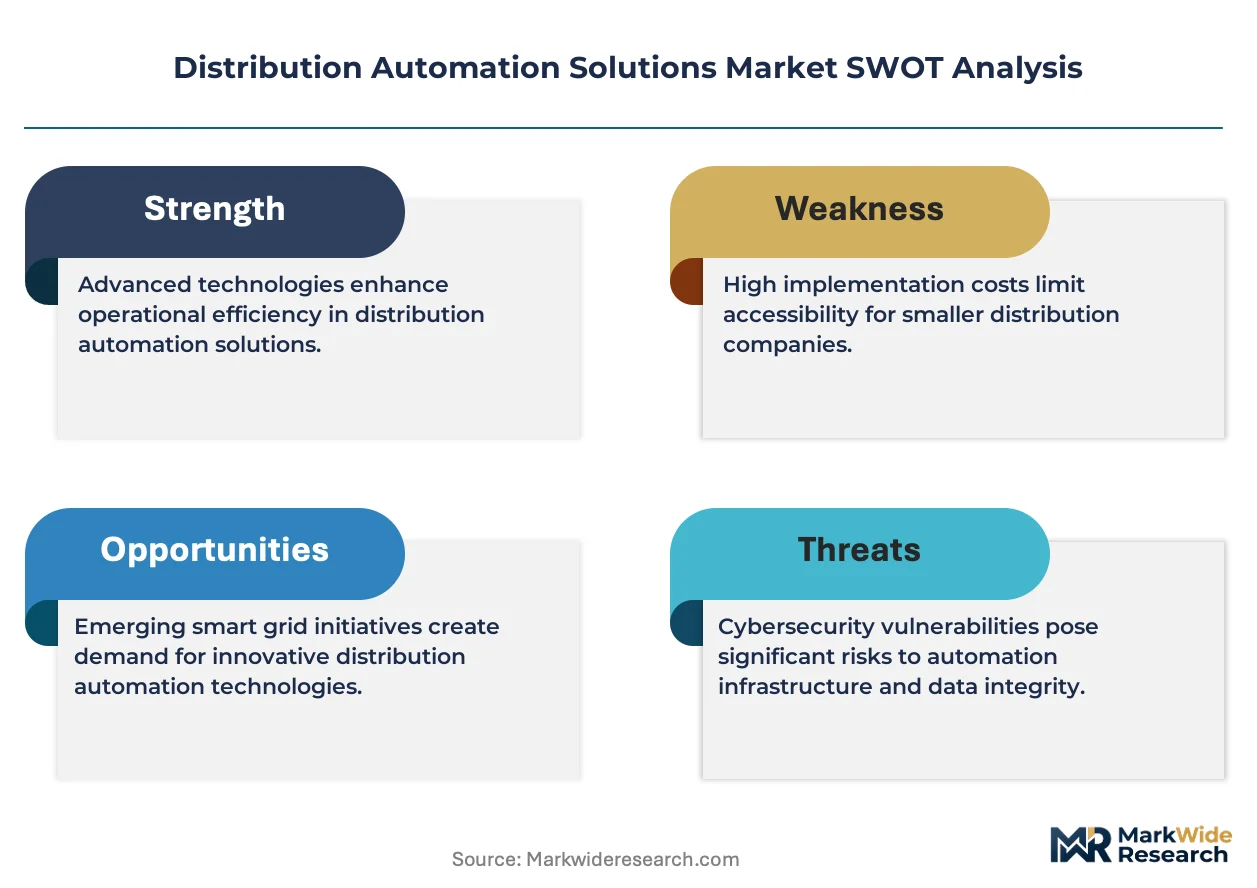
Aftermarket service revenue is reshaping margin pools across the distribution automation value chain, pulling profitability from hardware sales toward lifecycle support contracts. ABB leverages its installed base of substation automation systems to secure long-term service agreements. Schneider Electric anchors its competitiveness through integrated software-hardware portfolios spanning grid edge to control room. Siemens differentiates via deep R&D investment in digital twin platforms for distribution network simulation.
Distribution automation solutions encompass intelligent hardware, communication networks, and control software that monitor, coordinate, and optimize electric power delivery from substations to end consumers, typically operating at voltage levels between 4 kV and 34.5 kV with response times under 100 milliseconds for fault isolation. These systems enable utilities to reduce outage duration, improve voltage quality, and integrate distributed generation. SCADA and Distribution Management Systems command the largest installed base but face margin compression as platforms commoditize. Smart Grid Technology and Microgrid segments attract accelerated capital allocation where utilities prioritize resilience and renewable integration. Cybersecurity services within the service-type dimension capture expanding budgets as NERC CIP compliance requirements tighten and attack surfaces multiply across IP-enabled field devices.
FERC Order 2222 and IEEE 1547 standards in the United States, alongside EU cybersecurity directives under the NIS2 framework, are mandating interoperable, secure architectures that reshape procurement specifications and vendor qualification criteria. The EPA's power plant emissions rules indirectly amplify automation spending by accelerating distributed solar and storage interconnection complexity. Stakeholders must monitor how state-level integrated resource plans reconcile capital efficiency targets with resilience mandates, particularly where wildfire risk or extreme weather exposure drives hardening investments faster than standard depreciation cycles allow.
Market Dynamics
Self-healing grid architectures are restructuring utility procurement priorities, shifting capital allocation from passive equipment toward intelligent systems capable of autonomous fault detection and sectionalization. This architectural transition compresses response times while demanding interoperable communication protocols across heterogeneous device fleets.
Growth Catalysts
- FERC Order 2222:This mandate enables distributed energy resource aggregation in wholesale markets, compelling utilities to deploy automation platforms capable of bidirectional coordination with behind-the-meter assets.
- Rural electric cooperative infrastructure:Aging distribution networks across the United States require systematic replacement, creating concentrated demand for fault circuit indicators and automated switchgear with embedded sensing.
- NERC CIP cybersecurity frameworks:Compliance deadlines for critical infrastructure protection are accelerating procurement of IP-enabled field devices with hardened firmware and encrypted communication stacks.
Market Restraints
- Semiconductor supply concentration:Power electronics and communication chipsets depend heavily on East Asian foundry capacity, exposing project timelines to geopolitical disruption and allocation constraints.
- Copper and rare earth price volatility:Transformer cores and permanent magnet materials face commodity swings that destabilize equipment pricing and margin predictability for hardware vendors.
- Legacy SCADA protocol fragmentation:Proprietary communication standards from established vendors create technical debt that impedes seamless integration of third-party automation components.
Strategic Opportunities
- Microgrid controller convergence:Integration of distributed solar, storage, and load management within single automation platforms opens new revenue streams for vendors with software-hardware portfolios.
- EPA power plant emissions rules:Accelerated coal retirement timelines are forcing rapid interconnection of distributed generation, requiring advanced voltage regulation and power quality management systems.
- Service contract unbundling:Lifecycle support agreements covering firmware updates, cybersecurity patches, and predictive maintenance represent recurring revenue models displacing transactional equipment sales.
Industry Challenges
- Cybersecurity workforce scarcity:Utilities struggle to recruit personnel with combined expertise in operational technology protocols and enterprise security frameworks, delaying NERC CIP implementation.
- Multi-vendor integration complexity:Field deployment of automation systems requires coordination across relay manufacturers, communication providers, and control software vendors, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distribution Automation Solutions Market |
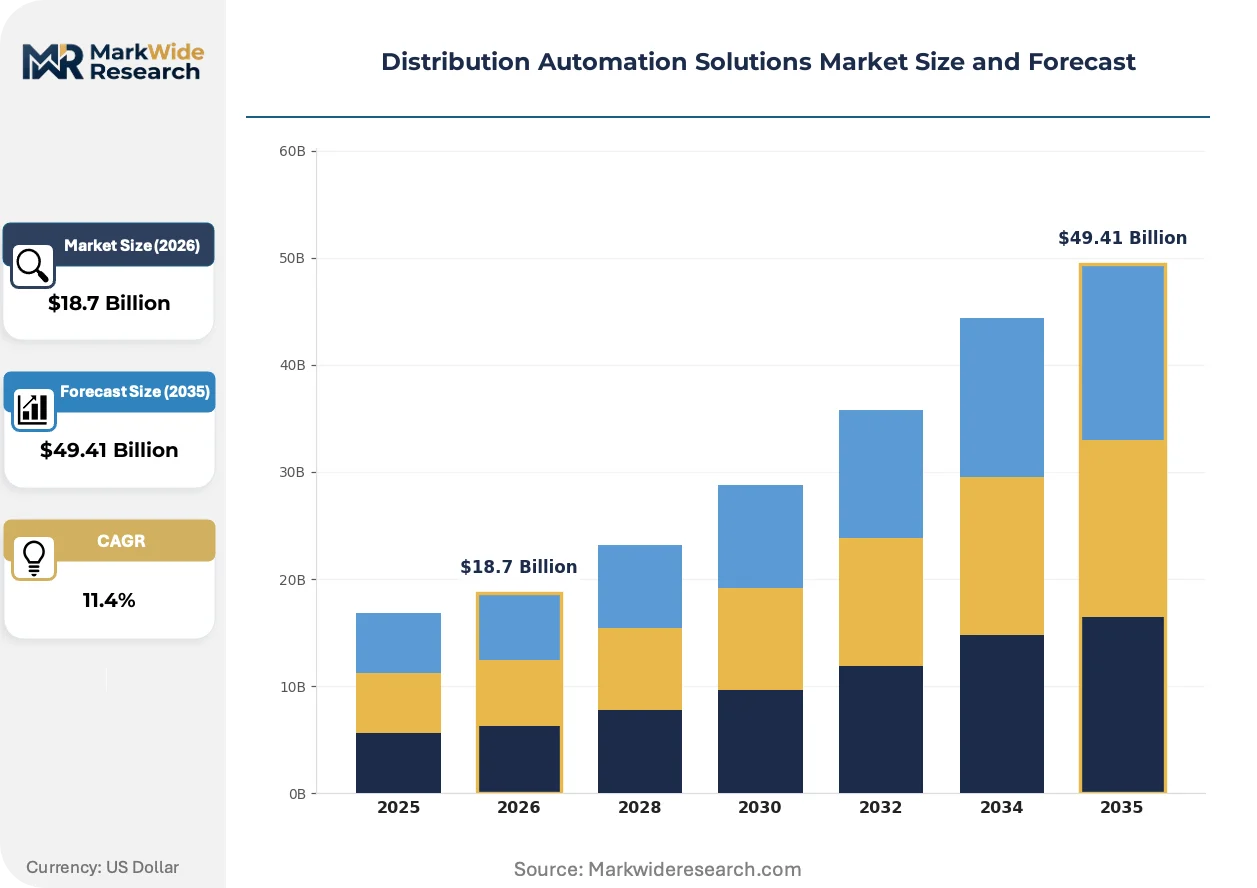
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: SCADA, Distribution Management Systems, Smart Grid Technology, Microgrid Application: Voltage Control, Load Management, Fault Detection, Energy Management End User: Utilities, Industrial, Commercial, Residential Service Type: Consulting, Integration, Maintenance, Cybersecurity |
| Companies Covered | ABB, Schneider Electric, Siemens, Eaton, GE Vernova, Itron, Schweitzer Engineering Laboratories, S&C Electric Company, Landis+Gyr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distribution Automation Solutions Market Emerging Trajectories
Digital twin technology is transforming how utilities simulate, validate, and optimize distribution network behavior before field deployment. This capability reduces commissioning risk while enabling scenario testing for extreme weather and cyberattack response.
Digital twin platforms are digitizing physical distribution assets into virtual environments where operators model load flows, fault scenarios, and protection coordination settings. Mid-sized municipal utilities in storm-prone regions are adopting these tools most aggressively. The technology is digitizing traditional engineering workflows that previously relied on static planning studies and manual field verification.
The EPA's power plant emissions regulations are indirectly mandating automation sophistication by accelerating distributed resource interconnection complexity. Utilities must now manage bidirectional power flows and voltage variability at distribution voltage levels previously designed for unidirectional delivery. Distribution automation vendors serving the United States market are prioritizing IEEE 1547-compliant inverter control interfaces and dynamic voltage regulation algorithms.
Aftermarket service unbundling is altering how utilities contract for automation system lifecycle support. Buyers are separating hardware procurement from multi-year service agreements covering cybersecurity updates, firmware patches, and predictive analytics. This pattern is most pronounced among investor-owned utilities in states with aggressive renewable portfolio standards, where operational technology uptime directly affects regulatory rate case outcomes.
Distribution Automation Solutions Market Segmentation
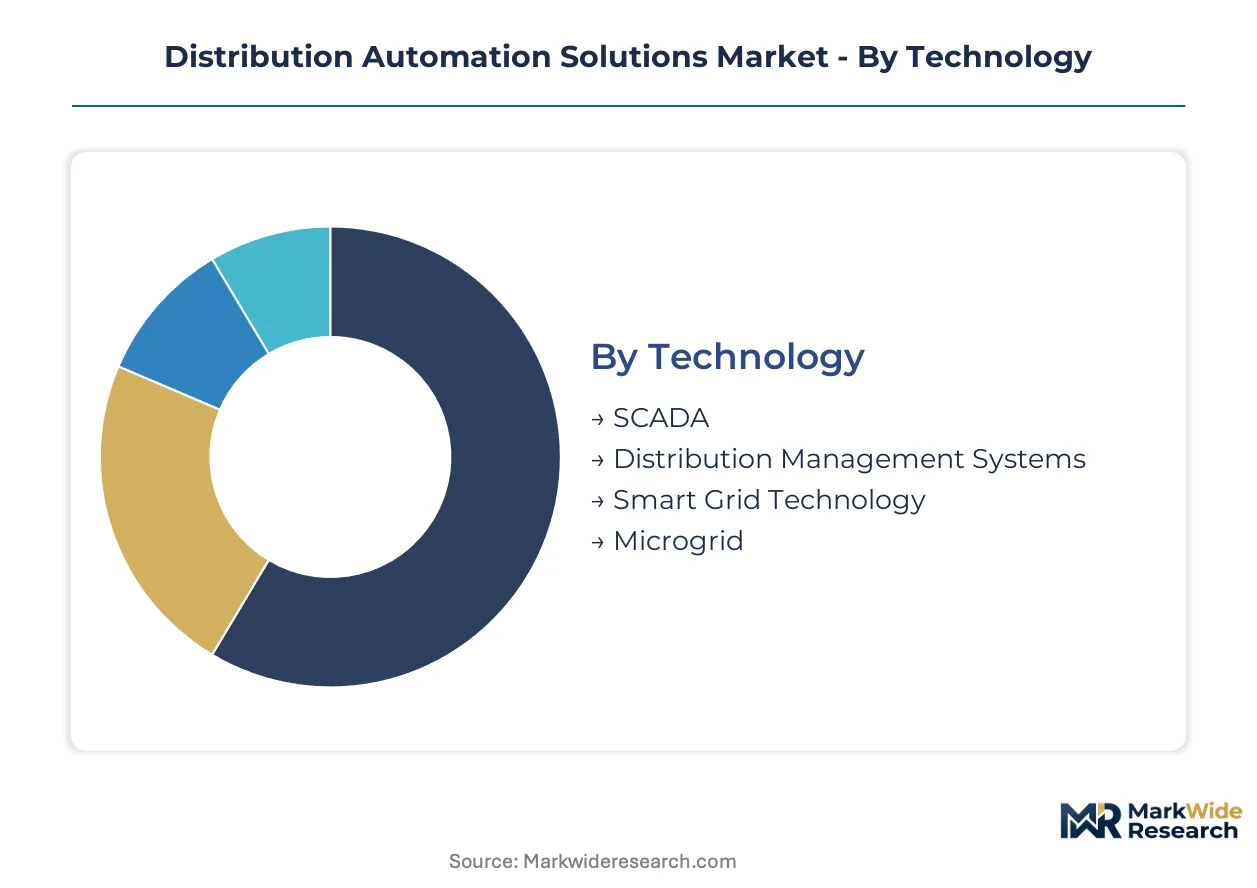
Segmentation in distribution automation reveals how procurement priorities diverge across operational contexts. Technology choices determine integration complexity, while service-type preferences expose where utilities seek external expertise versus in-house capability.
Technology:
Use-case spectrum spans legacy monitoring platforms to autonomous grid architectures, with investment intensity tracking regulatory pressure for renewable integration.
- SCADA:Supervisory control and data acquisition systems provide centralized monitoring of substations and feeder equipment through polled communication protocols. United States municipal utilities with aging RTU installations drive replacement demand as NERC CIP compliance deadlines approach.
- Distribution Management Systems:Advanced software platforms integrate real-time network modeling with outage management and voltage optimization functions. Investor-owned utilities in states with aggressive renewable portfolio standards are concentrating procurement here to manage bidirectional power flows.
- Smart Grid Technology:Sensor networks and automated switchgear enabling autonomous fault isolation and sectionalization.
- Microgrid:Island-capable control systems coordinating distributed generation, storage, and critical loads.
The dominant share belongs to SCADA, while Distribution Management Systems is closing the gap fastest.
Application:
Functional requirements map directly to grid hardening priorities, with storm resilience and renewable interconnection creating divergent capability demands.
- Fault Detection:Intelligent electronic devices and fault circuit indicators locate and isolate distribution faults within sub-cycle timeframes. Rural electric cooperatives across the United States prioritize this segment to reduce SAIDI metrics and justify rate case filings.
- Voltage Control:Capacitor bank controllers and voltage regulators maintain power quality across variable load and generation conditions. Southwestern utilities facing high solar penetration concentrate investment here to manage flicker and thermal loading.
- Load Management:Demand response interfaces and direct load control systems shaping consumption patterns.
- Energy Management:Optimization algorithms balancing generation cost, emissions, and reliability constraints.
Fault Detection commands the largest installed base, though Voltage Control is expanding most quickly under IEEE 1547 interconnection mandates.
End User:
Customer archetypes separate by procurement sophistication, capital access, and regulatory exposure.
- Utilities:Vertically integrated and distribution-only electric companies with formalized asset management frameworks. These entities dominate volume through multi-year capital programs tied to rate base recovery mechanisms.
- Industrial:Heavy manufacturing and data center operators with captive distribution infrastructure.
- Commercial:Retail, healthcare, and institutional facilities pursuing resilience through behind-the-meter automation.
- Residential:Single-home and multi-family deployments, typically via utility-managed demand response programs.
Utilities absorb the majority of vendor revenue, while Industrial end users are gaining share fastest through microgrid controller adoption.
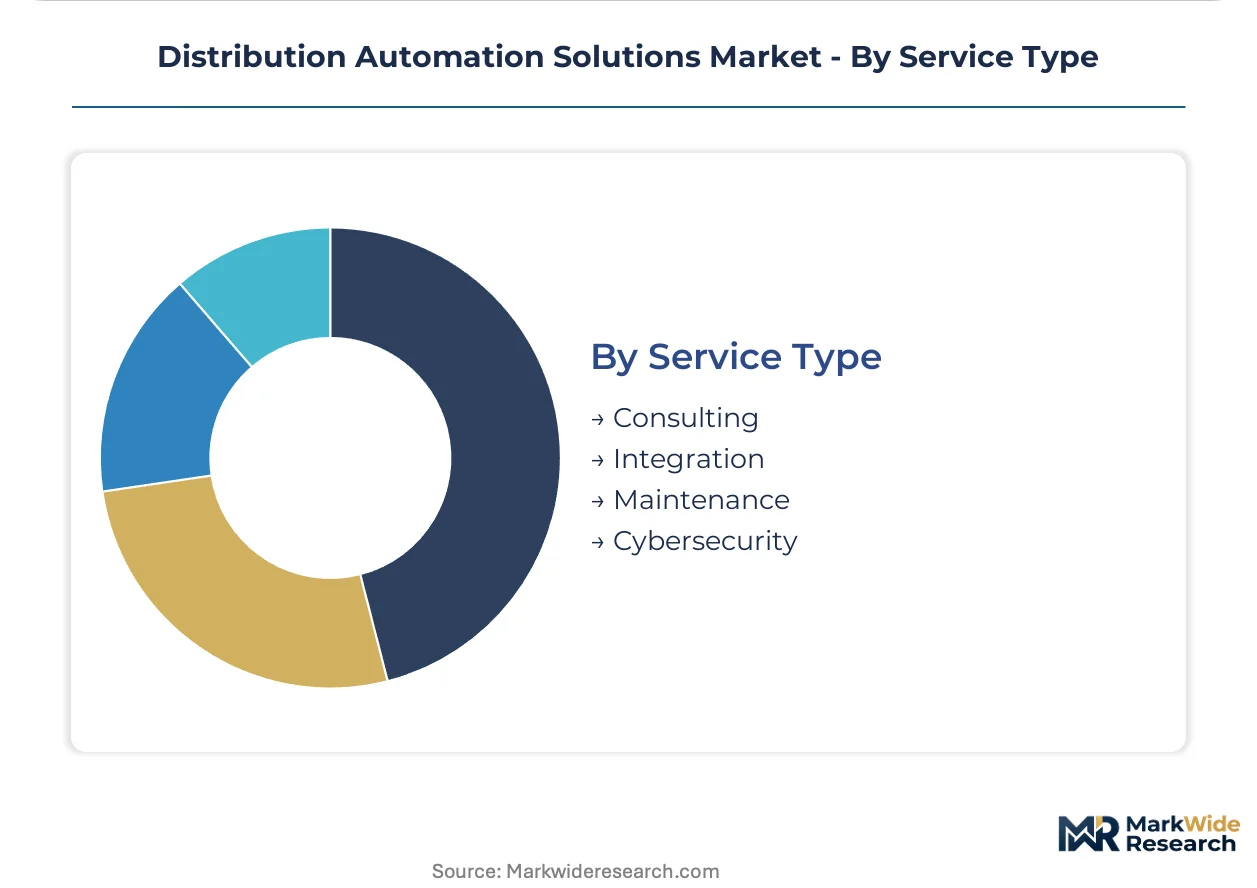
Service Type:
Procurement unbundling is shifting contract structures from equipment-centric to lifecycle-support models.
- Cybersecurity:NERC CIP compliance services, firmware hardening, and encrypted communication stack deployment. United States utilities facing enforcement deadlines are concentrating procurement here, treating security as a distinct workstream from hardware integration.
- Integration:Multi-vendor system commissioning, protocol translation, and interoperability testing.
- Maintenance:Predictive analytics, firmware updates, and field service contracts extending equipment operational life.
- Consulting:Network planning studies, protection coordination reviews, and automation roadmapping.
Integration services hold the largest contract value, while Cybersecurity is climbing the fastest as attack surface expansion outpaces utility staffing capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys distribution automation primarily for storm resilience and renewable interconnection, while Germany emphasizes industrial microgrid integration and China prioritizes urban load density management.
United States
Rural electric cooperatives and municipal utilities drive hardware replacement cycles for aging substation equipment. FERC Order 2222 mandates bidirectional coordination capabilities for distributed energy resource aggregation. Texas and California utilities concentrate procurement of automated switchgear and voltage regulators where extreme weather exposure and solar penetration peak simultaneously.
Germany
Industrial clusters and manufacturing hubs seek island-capable microgrid controllers for supply security. The EU NIS2 cybersecurity directive tightens procurement specifications for IP-enabled field devices. Bavarian and Baden-Württemberg utilities lead deployment of digital twin platforms for distribution network simulation and protection coordination studies.
China
State Grid Corporation accelerates urban distribution automation to manage explosive load growth in megacities. National dual carbon goals mandate renewable integration at distribution voltage levels. Yangtze River Delta and Pearl River Delta regions concentrate smart switchgear deployment where manufacturing density and electric vehicle charging loads converge.
Japan
Utilities prioritize earthquake-resilient automation architectures with sub-cycle fault isolation capabilities. METI's grid modernization directives emphasize interoperability standards for heterogeneous device fleets. Tokyo Electric Power and Kansai Electric concentrate investment in sensor networks and automated sectionalizers for coastal industrial corridors.
India
State electricity boards modernize rural distribution networks to reduce technical losses and improve voltage quality. The CEA's Smart Grid Roadmap mandates automation deployment for renewable integration targets. Maharashtra and Gujarat utilities lead procurement of fault circuit indicators and capacitor bank controllers where industrial load centers intersect with solar parks.
Distribution Automation Solutions Market Vendor Landscape
Capability concentration sits with integrated automation specialists; scale advantage sits with diversified industrial conglomerates. The market structures around three tiers: full-stack platform vendors, component specialists with deep installed bases, and regional system integrators. Strategic archetypes include software-hardware portfolio integrators, lifecycle service providers, and cybersecurity-hardened device manufacturers. Dominant competitive moves encompass multi-year service contract unbundling and digital twin platform development.
Within the integrated platform tier, ABB, Schneider Electric, and Siemens exemplify contrasting approaches to automation value capture. ABB anchors its position through substation automation installed base leverage for recurring service agreements. Schneider Electric occupies a position spanning grid edge hardware through control room software integration. Siemens represents deep research and development commitment to simulation and digital twin capabilities for distribution network planning.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Siemens |
| Eaton |
| GE Vernova |
| Itron |
| Schweitzer Engineering Laboratories |
| S&C Electric Company |
| Landis+Gyr |
| Others |
Supply Flow & Price Mechanics
East Asian foundry concentration for power electronics and communication chipsets funnels pricing power toward semiconductor vendors, compressing margins for automation hardware manufacturers while concentrating margin pools in firmware and cybersecurity service tiers.
Pricing Analysis
Long-term service contracts dominate procurement structures, displacing transactional equipment sales as utilities unbundle lifecycle support from hardware acquisition. Price differentiation rests on NERC CIP certification tiers and geographic deployment complexity, with rural electric cooperatives exhibiting highest price sensitivity due to rate case constraints. Pricing pressure intensifies from commodity volatility in copper and rare earth inputs, eroding hardware margin predictability. Investor-owned utilities in states with aggressive renewable mandates show lowest price sensitivity, prioritizing uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Upstream feedstock dependencies center on Taiwan and South Korea for advanced semiconductors, China for rare earth processing, and Japan for precision electronic components. Raw material exposure concentrates in copper for transformer windings, silicon carbide for power electronics, and lithium for battery-backed switchgear controllers. Single-source vulnerability in advanced node chip fabrication creates procurement risk for IP-enabled field devices. Distribution runs through authorized system integrators and direct utility procurement channels, with aftermarket parts flowing via manufacturer service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as FERC Order 2222 compliance demands splinter procurement specifications across cooperative, municipal, and investor-owned utility archetypes.
For Market Incumbents: Pre-empt margin erosion in commoditized SCADA hardware by securing exclusive multi-year cybersecurity service contracts tied to NERC CIP enforcement deadlines. Counter emerging software-native competitors through backward integration into digital twin simulation platforms. Prioritize certification investment in IEEE 1547-compliant inverter interfaces to capture distributed solar interconnection revenue pools. For New Entrants and Emerging Players: Establish a beachhead in microgrid controller convergence by targeting industrial end users in Texas and California where resilience premiums outweigh procurement sophistication gaps. Exploit cybersecurity workforce scarcity among rural electric cooperatives through managed security service offerings. Deploy channel partnerships with established relay manufacturers to bypass multi-vendor integration complexity barriers. For Investors and Strategic Acquirers: Capital is best deployed toward lifecycle service specialists with NERC CIP compliance expertise and recurring revenue visibility across depreciation-extended utility asset bases. Long-term viability favors platforms integrating grid edge hardware with control room software rather than point-solution device manufacturers. Monitor state integrated resource plan filings as inflection signals for automation spending acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Development | Siemens and ABB compete through virtual commissioning capabilities that reduce field deployment risk for storm-prone utilities. |
| Service Contract Unbundling | Schneider Electric separates hardware procurement from cybersecurity lifecycle agreements to capture recurring revenue streams. |
| Microgrid Controller Convergence | Industrial end users in California prioritize island-capable automation for supply security against wildfire-triggered outages. |
| Cybersecurity Hardening Investment | IP-enabled field device vendors embed encrypted firmware stacks to meet NERC CIP enforcement deadlines. |
| IEEE 1547 Interface Certification | Automation vendors prioritize inverter control compatibility to capture distributed solar interconnection complexity premiums. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, utility capital expenditure disclosures, and vendor contract announcements to validate market sizing and growth trajectory assumptions. Primary interviews engaged utility planning officers, distribution automation procurement leads, EPC contractors, and cybersecurity compliance specialists across cooperative, municipal, and investor-owned utility structures. Secondary sources encompassed FERC orders, state integrated resource plans, NERC CIP enforcement records, and equipment vendor SEC filings. Bottom-up triangulation across installed base estimates and replacement cycle analysis was cross-checked against top-down capital flow tracking across the analysis window.
Forecast inputs incorporate technology deployment rates by utility customer class, regulatory compliance deadline clustering, and distributed generation interconnection queue data. Segmentation modeling spanned hardware-software-service type, end user archetype, and regional regulatory framework variations. CAGRs were derived from regression analysis of historical capital expenditure patterns against forward-looking rate case filings and federal mandate implementation timelines. Scenario weighting reflected EPA power plant emissions rule acceleration effects and semiconductor supply availability assumptions.
Stress conditions across copper and rare earth price volatility, East Asian foundry allocation constraints, and NERC CIP enforcement delay scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding cooperative infrastructure replacement urgency and investor-owned utility renewable integration timelines. Cross-checking against EIA distribution automation expenditure surveys and utility rate case testimony is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Global Remote Monitoring and Control Market
Automation
North America Marketing Automation Software Market
Automation
Laboratory Automation Market
Automation
Italy Process Orchestration Market
Automation
Elevator Control Market
Automation
Window Automation Market
Automation
Retail Automation Market
Automation
Modular Laboratory Automation Market
Automation
Indonesia Automation and Control System Market
Automation
Global Door and Window Automation Market
Automation
Automation Testing Market
Automation
Europe Data Center Automation Market
Automation
US Workload Scheduling and Automation Market
Automation
Voice Picking Solutions Market
Automation
Parcel Sorting System Market
Automation
Global Warehouse Barcode System Market