
 Computer Numerical Control Market | 2026-2036
Computer Numerical Control Market Size, Share, and Industry Trends Forecast 2026-2036
Computer Numerical Control Market Analysis
The EU Green Deal is hardening carbon-accounting requirements for capital equipment procurement across European manufacturing. Siemens AG leverages its digital twin portfolio to embed energy monitoring into CNC control architectures. Fanuc Corporation anchors high-volume servo motor production for Japanese and Southeast Asian machine tool builders. DMG Mori Seiki Co., Ltd. competes on integrated automation cells that reduce per-part energy intensity in aerospace and medical device production.
Computer numerical control denotes automated machine tool operation via programmable commands encoded in G-code or M-code, typically achieving positional accuracy within micrometers for multi-axis cutting, milling, or additive processes. Its primary purpose is to manufacture precision-engineered components with repeatable tolerances across batch sizes ranging from single prototypes to mass production. CNC milling machines occupy the largest installed base among product categories, sustained by universal applicability across metals and composites. 5-axis CNC technology captures the fastest expansion trajectory as aerospace and medical device end users demand complex geometries in single setups. Hybrid CNC systems, combining subtractive and additive operations, concentrate emerging margin pools in tooling and customized production applications.
REACH and RoHS frameworks in Europe restrict hazardous substances in electronic CNC control modules, while the EU AI Act introduces conformity requirements for autonomous machining optimization algorithms. China's GB standards and MIIT efficiency mandates shape import eligibility and domestic product specifications for machine tools. Japan's METI promotes JIS-certified precision benchmarks that influence export competitiveness across Asian supply chains. Stakeholders must monitor divergent regulatory timetables for digital integration and sustainability compliance when allocating R&D and localization investments.
Market Dynamics
Energy-efficiency mandates from the EU F-Gas Regulation and China's dual carbon goals are compressing machine tool motor specifications while aerospace demand for titanium airframe components accelerates 5-axis CNC capacity expansion across precision manufacturing clusters.
Growth Catalysts
- EU Green Deal procurement rules:Carbon-accounting requirements for capital equipment are redirecting European manufacturing investment toward energy-monitoring CNC architectures.
- Titanium aerospace machining:German and Japanese manufacturers are scaling 5-axis capacity for complex airframe geometries requiring single-setup precision.
- Hybrid manufacturing convergence:Combined subtractive-additive CNC systems are capturing tooling margin pools in customized production applications.
Market Restraints
- Rare earth magnet supply concentration:Servo motor production depends on concentrated rare earth processing capabilities concentrated in limited jurisdictions.
- REACH and RoHS substance restrictions:European frameworks limit electronic control module material options, constraining design flexibility for control system manufacturers.
- Skilled G-code programming shortage:Multi-axis machining expertise scarcity limits operational scaling for advanced CNC deployments.
Strategic Opportunities
- Medical device precision clusters:Swiss and South Korean hubs present underpenetrated demand for micrometer-tolerance orthopedic implant machining.
- AI Act conformity services:EU algorithmic machining optimization mandates create compliance service revenue streams for control system integrators.
- Digital twin integration:Real-time energy monitoring embedded in CNC architectures enables predictive maintenance subscription models.
Industry Challenges
- Multi-axis programming certification timelines:JIS-certified precision benchmarks and METI training requirements extend workforce readiness cycles.
- Legacy analog control migration:Brownfield facilities face integration friction retrofitting decades-old machine tool fleets with networked sensor architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computer Numerical Control Market |
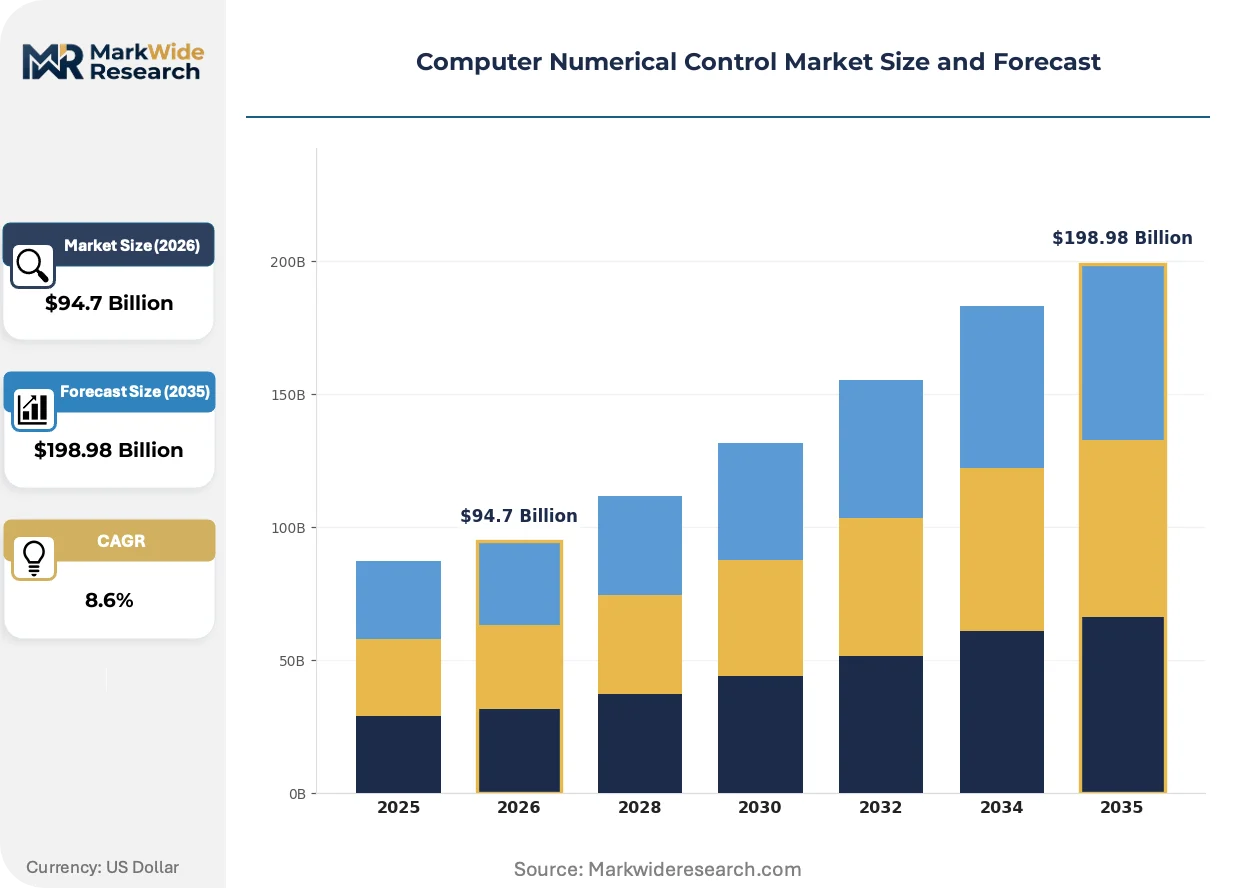
| Market Size in 2026 | $94.7 Billion |
| Market Size in 2035 | $198.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CNC Milling Machines, CNC Lathes, CNC Routers, CNC Plasma Cutters Technology: Hybrid CNC, 5-Axis CNC, 3-Axis CNC, CNC Laser End User: Aerospace, Automotive, Electronics, Medical Devices Application: Components Manufacturing, Customized Production, Prototyping, Tooling |
| Companies Covered | Siemens AG, Fanuc Corporation, DMG Mori Seiki Co., Ltd., Haas Automation, Inc., Yamazaki Mazak Corporation, Okuma Corporation, JTEKT Corporation, Hurco Companies Inc, Bosch Rexroth AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computer Numerical Control Market Emerging Trajectories
Machine tool architectures are converging around energy-transparent operation and autonomous process optimization, with regulatory pressure and buyer procurement criteria accelerating technology refresh cycles across precision manufacturing.
Adaptive process control software is automating real-time feed rate and spindle load adjustments based on tool-wear sensing and material variability detection. Aerospace tier-one suppliers in Germany and Japan are deploying these systems at scale for titanium roughing operations. The technology is automating manual operator intervention cycles, compressing per-part machining time while maintaining surface finish tolerances.
China's MIIT efficiency mandates and GB standards are tightening import eligibility thresholds for machine tool motors, forcing control system redesigns for Asian market access. Domestic Chinese builders must now certify energy consumption metrics for servo drive configurations. European and Japanese CNC suppliers are responding with localized motor sourcing and regional firmware customization.
After-sales service unbundling is fragmenting traditional maintenance contract structures as aerospace and medical device buyers demand usage-based spindle monitoring subscriptions. Independent service providers are displacing OEM captive service networks in the US Midwest precision component belt. This shift concentrates in high-mix, low-volume production environments where downtime costs exceed preventive maintenance premiums.
Computer Numerical Control Market Segmentation
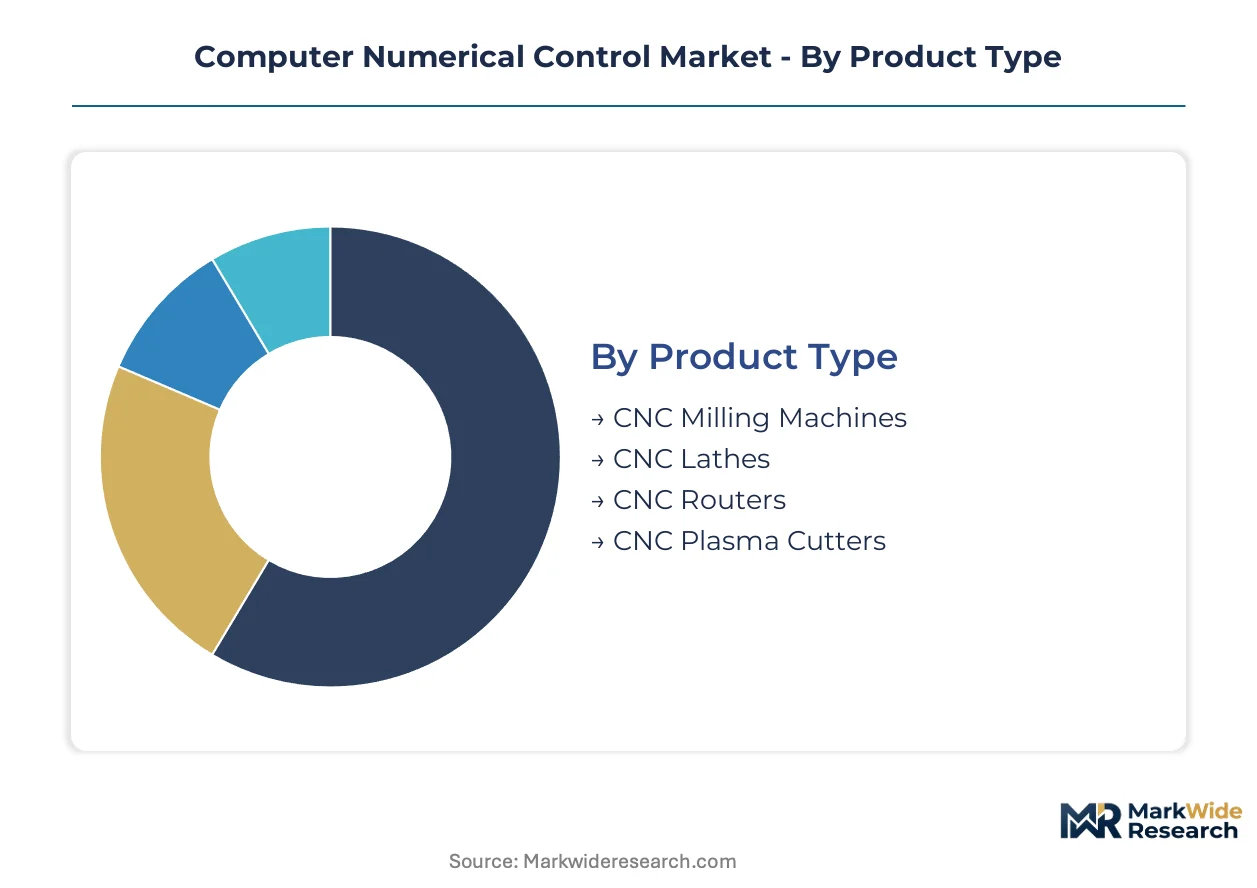
Segmentation in the CNC market tracks how technology tiers align with capital replacement cycles and end-use precision requirements. Equipment refresh timelines vary dramatically across aerospace, automotive, and medical device manufacturing clusters.
Product Type:
Upgrade cycles in machine tool fleets concentrate heaviest where multi-axis capability delivers measurable per-part energy reduction.
- CNC Milling Machines:Universal subtractive platforms handle metals and composites across batch sizes from single prototypes to mass production. Aerospace manufacturers in Germany and Japan anchor demand for 5-axis-capable milling centers that compress titanium airframe machining into single setups.
- CNC Lathes:Rotational machining systems excel at cylindrical component production with repeatability measured in micrometers. Automotive powertrain suppliers in the US Midwest drive capacity expansion for high-volume shaft and bearing production.
- CNC Routers:Gantry-based systems optimized for softer materials including wood, plastics, and foam composites.
- CNC Plasma Cutters:Thermal cutting platforms for thick metal plate processing in heavy fabrication environments.
CNC milling machines sit at the top of the volume ranking, with CNC lathes climbing the fastest on automotive electrification-driven component demand.
Technology:
Cost tier differentiation separates premium multi-axis architectures from standardized three-axis configurations serving price-sensitive production environments.
- Hybrid CNC:Converged subtractive-additive systems alternate between material removal and deposition within single part programs. Tooling and customized production applications in medical device clusters capture emerging margin pools from reduced setup changeover.
- 5-Axis CNC:Simultaneous multi-axis motion enables complex geometry machining without fixture repositioning. Swiss and South Korean precision component hubs underpenetrate this technology tier for orthopedic implant production.
- 3-Axis CNC:Entry-level and mid-market workhorse platforms dominating high-volume, lower-complexity production.
- CNC Laser:Non-contact thermal processing for thin-gauge metals and specialized material cutting applications.
5-Axis CNC commands the premium tier by installed value, while hybrid CNC gains share fastest on tooling application convergence.
End User:
Application maturity varies sharply across end-use sectors, with medical device and aerospace buyers demanding certification-grade traceability that extends replacement cycles.
- Aerospace:Titanium airframe and engine component machining requires JIS-certified precision benchmarks and METI-compliant process documentation. German and Japanese tier-one suppliers anchor capacity expansion for single-setup complex geometry production.
- Automotive:Powertrain and chassis component volumes sustain the broadest installed base of three-axis and four-axis equipment. China's MIIT efficiency mandates force motor specification redesigns for market access.
- Electronics:Miniaturization trends drive demand for micrometer-tolerance PCB and enclosure machining.
- Medical Devices:Orthopedic implant and surgical instrument production requires biocompatible material processing with full lot traceability.
Aerospace leads by capital deployed per installation, with medical devices expanding most quickly on aging demographic-driven implant demand.
Application:
Customer type segmentation separates high-mix, low-volume job shops from captive production facilities with dedicated product lines.
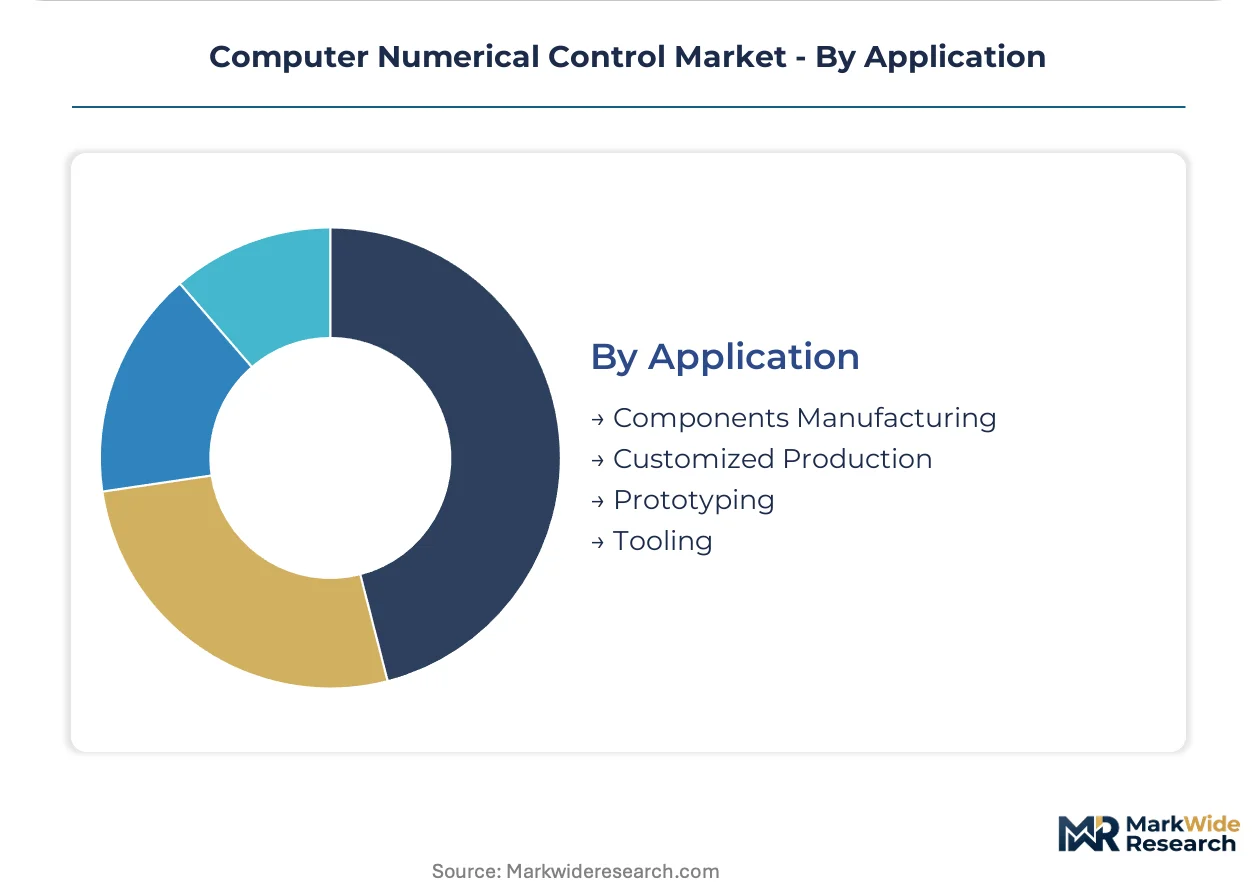
- Components Manufacturing:Repetitive production of standardized parts for downstream assembly integration. EU F-Gas Regulation energy-efficiency mandates redirect procurement toward architectures with embedded consumption monitoring.
- Tooling:Mold, die, and fixture production requiring hybrid material addition and removal capabilities. After-sales service unbundling concentrates subscription revenue in this application tier.
- Customized Production:One-off and small-batch manufacturing for specialized industrial and consumer applications.
- Prototyping:Rapid iteration environments prioritizing setup speed over per-part cost optimization.
Components manufacturing holds the largest installed base, with tooling showing the steepest expansion trajectory on hybrid system adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese machining expertise anchors global precision manufacturing capacity, with specialized workforce clusters in Stuttgart and Nagoya sustaining multi-axis programming proficiency that limits competitor replication.
Germany
Aerospace tier-one suppliers in Baden-Württemberg drive 5-axis CNC capacity expansion for titanium airframe components. The EU F-Gas Regulation compresses motor efficiency specifications for machine tool builders serving automotive powertrain manufacturers. Stuttgart's precision engineering corridor concentrates JIS-certified process documentation capabilities.
Japan
METI promotes servo motor production scaling through JIS-certified precision benchmarks that influence export competitiveness across Asian supply chains. METI training requirements extend multi-axis programming certification timelines for workforce readiness. Nagoya's Chubu region anchors high-volume servo motor output for domestic and Southeast Asian machine tool builders.
United States
Automotive electrification in the US Midwest sustains demand for high-volume shaft and bearing production on CNC lathe platforms. OSHA workplace safety standards intersect with EPA energy efficiency guidelines for manufacturing equipment procurement. Michigan and Ohio's precision component belt concentrates independent service provider displacement of OEM captive maintenance networks.
China
MIIT efficiency mandates and GB standards tighten import eligibility thresholds for machine tool motors, forcing control system redesigns for Asian market access. The country's dual carbon goals redirect domestic builder certification requirements toward energy consumption metrics. Yangtze River Delta manufacturing clusters absorb localized motor sourcing and regional firmware customization from European and Japanese CNC suppliers.
Switzerland
Micrometer-tolerance orthopedic implant machining demand concentrates in Swiss precision component hubs with underpenetrated 5-axis CNC adoption. Swissmedic medical device regulations impose biocompatible material processing standards with full lot traceability requirements. Geneva and Basel's medical technology corridor presents expansion opportunities for hybrid subtractive-additive system deployment.
Computer Numerical Control Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across tiered technology portfolios. The vendor base separates into integrated automation cell providers, control architecture specialists, and precision machine tool builders. Three strategic archetypes dominate: full-stack system integrators bundling hardware and software, component specialists supplying servo motors and drives to third-party builders, and regional machine tool manufacturers competing on localized service density. Competitive moves concentrate on capacity expansion in aerospace-adjacent geographies and strategic partnerships embedding energy monitoring into procurement specifications.
Among German-based industrial conglomerates, Siemens AG occupies a position exemplifying control architecture integration, while Bosch Rexroth AG sits within the drive systems specialist tier. Japanese manufacturers Fanuc Corporation and DMG Mori Seiki Co., Ltd. represent contrasting archetypes—Fanuc anchors high-volume servo motor production, while DMG Mori Seiki exemplifies integrated automation cell provision for aerospace and medical device end users. Haas Automation, Inc. and Yamazaki Mazak Corporation occupy positions within the regional machine tool builder category, with geographic naming indicating US and Japanese origins respectively.
| Leading Market Players |
|---|
| Siemens AG |
| Fanuc Corporation |
| DMG Mori Seiki Co., Ltd. |
| Haas Automation, Inc. |
| Yamazaki Mazak Corporation |
| Okuma Corporation |
| JTEKT Corporation |
| Hurco Companies Inc |
| Bosch Rexroth AG |
| Others |
Supply Flow & Price Mechanics
Aerospace tier-one suppliers in Germany and Japan command project-based pricing with multi-year service bundling, compressing margin capture for standard three-axis equipment while elevating premium tiers for JIS-certified 5-axis architectures. This buyer concentration forces control system vendors to unbundle after-sales subscriptions from hardware sales, fragmenting traditional captive maintenance revenue streams.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies CNC equipment procurement, with aerospace and medical device buyers absorbing premium tiers for METI-compliant process documentation while automotive powertrain manufacturers drive standard-tier volume. Price differentiation hinges on JIS certification grade and embedded energy-monitoring capability. Cost compression in economy-tier three-axis lathes is intensifying because Chinese domestic builders undercut European and Japanese entrants on MIIT efficiency-mandated motor specifications. Automotive electrification suppliers in the US Midwest exhibit highest price sensitivity; Swiss orthopedic implant manufacturers show lowest sensitivity due to micrometer-tolerance requirements.
Supply Chain Analysis
China's GB standards and MIIT local-content rules are reshaping sourcing, forcing European and Japanese CNC suppliers toward Yangtze River Delta motor partnerships and regional firmware customization. Servo motor production draws from concentrated rare earth processing in China, high-volume winding operations in Japan, and precision bearing manufacture in Germany. Single-source vulnerability in neodymium magnet supply creates tariff exposure for control system vendors serving EU aerospace customers. Distribution runs through captive OEM service networks in aerospace and independent providers in high-mix US Midwest job shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CNC market functions as a stable compounder anchored by irreplaceable precision manufacturing demand across aerospace, medical device, and automotive electrification verticals. Capital equipment replacement cycles and regulatory compliance mandates sustain recurring revenue visibility for technology leaders.
For Market Incumbents: Acquire multi-axis programming certification capabilities to extend workforce readiness moats against emerging Chinese control system vendors. Siemens AG and Fanuc Corporation should deepen backward integration into rare earth magnet supply through offtake agreements with Chinese processors, insulating servo motor production from export restriction risk. METI training requirement extensions in Japan create defensible certification timelines that limit competitor replication. For New Entrants and Emerging Players: Digital-channel aftermarket service platforms offer lowest-friction entry into US Midwest precision component clusters where independent providers already displace OEM captive networks. Target Swiss orthopedic implant machining hubs for hybrid subtractive-additive system penetration; underpenetrated 5-axis adoption in Geneva and Basel corridors presents white-space opportunity. Lead with usage-based spindle monitoring subscriptions rather than capital equipment sales to compress customer acquisition cost. For Investors and Strategic Acquirers: Industrial automation conglomerates are the most active acquirer in this space, seeking control architecture specialists to embed energy monitoring into procurement specifications. Five-to-ten year viability rests on digital twin integration density and AI Act conformity service attach rates. Monitor EU F-Gas Regulation enforcement intensity as inflection signal for motor specification redesign cycles and associated compliance service revenue expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Secures servo motor production continuity against Chinese export licensing volatility. |
| Digital Twin Platform Integration | Enables predictive maintenance subscriptions for DMG Mori Seiki aerospace customers. |
| AI Act Conformity Service Development | Captures EU algorithmic machining optimization compliance revenue for control integrators. |
| Hybrid System Capacity Expansion | Positions tooling specialists for medical device cluster convergence demand in Switzerland. |
| Regional Firmware Customization | Unlocks MIIT-compliant market access for European and Japanese CNC suppliers in China. |
Methodological Framework
Multiple input streams — plant engineer interviews at German aerospace tier-ones, procurement lead discussions at US Midwest automotive suppliers, and aftermarket service head conversations at Japanese machine tool builders — were reconciled with secondary validation from METI production statistics, EU F-Gas Regulation implementation reports, and SEC filings from listed control system vendors. Customs data on servo motor trade flows, JIS certification registries, and MIIT efficiency mandate compliance disclosures provided demand-side calibration. Bottom-up equipment installation tracking and top-down manufacturing value-added estimates were triangulated to anchor market sizing.
Historical capacity expansion patterns in Stuttgart and Nagoya were cross-referenced against panel input from aerospace program managers and medical device manufacturing directors to construct projection scenarios. Segmentation modeling spanned product type, technology tier, end-use vertical, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and energy-efficiency mandate compliance timelines. Forecast inputs incorporated titanium aerospace machining demand trajectories and hybrid system adoption curves in orthopedic implant production.
The model assumes a particular technology adoption path; alternative pathways for autonomous process control software would alter the outlook if G-code programming expertise scarcity resolves faster than METI certification timelines project. Forecasts reflect assumptions regarding EU Green Deal procurement rule enforcement consistency and China's dual carbon goal implementation pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Asia Pacific Marketing Automation Software Market
Automation
Italy Process Orchestration Market
Automation
Cognitive Process Automation Market
Automation
Process Control Systems for Steel Market
Automation
Global Remote Monitoring and Control Market
Automation
Self Bag Drop Machine Market
Automation
Database Automation Market
Automation
Global Sales Force Automation (SFA) Market
Automation
Hyperautomation Market
Automation
Workload Automation Software Market
Automation
Automated Cell Block Systems Market
Automation
Asia-Pacific Data Center Automation Market
Automation
Europe Data Center Automation Market
Automation
Distribution Automation Solutions Market
Automation
Terminal Automation Systems Market
Automation
Marketing Automation Solutions Market