
 Europe Application Modernization Services Market | 2026-2036
Europe Application Modernization Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Application Modernization Services Market Intelligence
The capability gap between hyperscale integrators and mid-tier specialists is unwinding as cloud-native skill scarcity redistributes contract value. Accenture leverages its multi-cloud platform engineering centers across France and the Netherlands to anchor complex SAP modernization programs for continental manufacturers. Capgemini sustains deep mainframe-to-Azure partnerships that dominate France's banking sector. Tata Consultancy Services competes aggressively on fixed-price transformation guarantees, pressuring margin structures for European-born rivals.
Europe Application Modernization Services encompass the architectural refactoring, re-platforming, and containerization of legacy software estates to improve scalability, interoperability, and security posture across hybrid IT environments. These services deploy microservices decomposition, API gateway orchestration, and infrastructure-as-code pipelines to replace monolithic applications with cloud-compatible workloads. Cloud-Native Development commands premium pricing as Kubernetes and serverless implementations require scarce platform engineering talent, while Legacy Modernization retains volume leadership through mainframe offload programs at German and Italian financial institutions. Hybrid Cloud deployments are expanding fastest among regulated European sectors seeking data sovereignty compliance without full public cloud exposure.
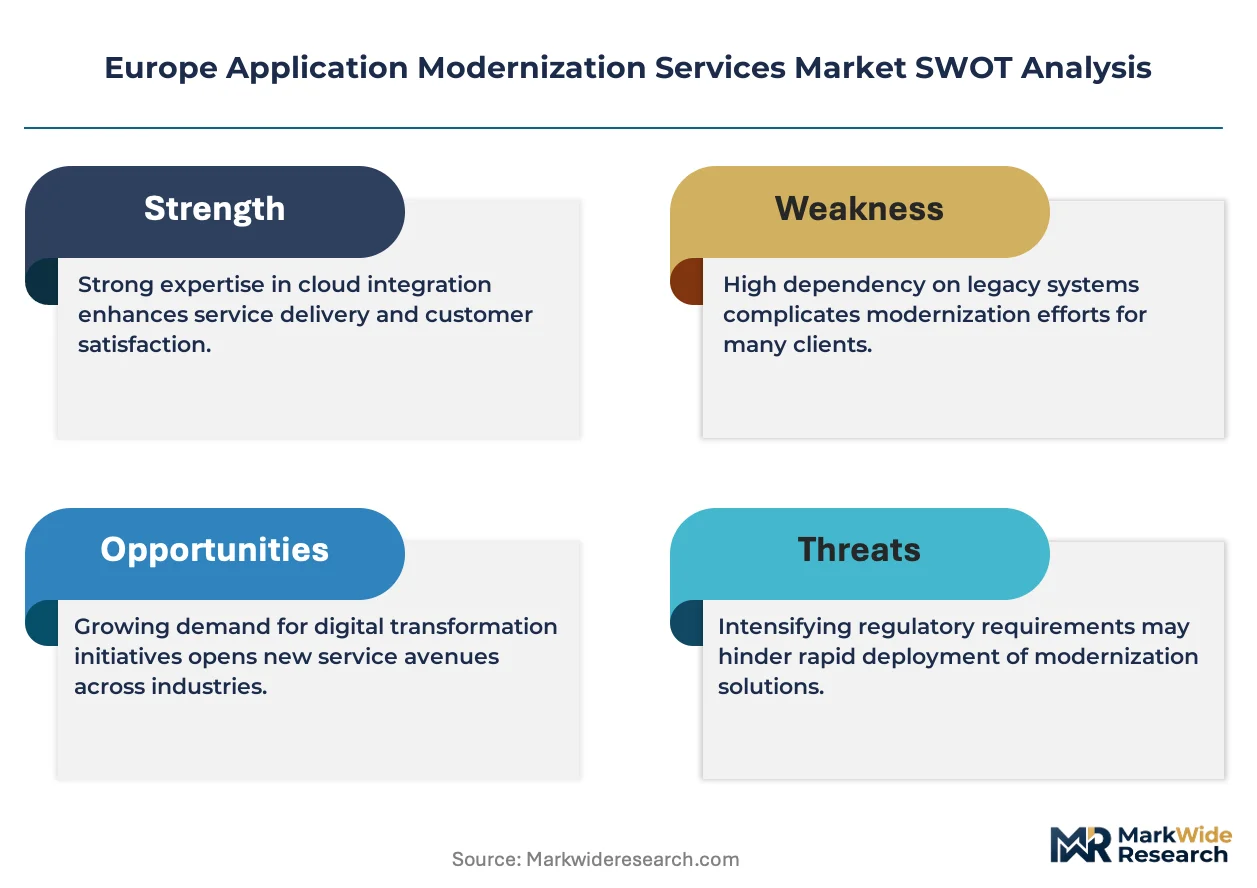
The EU AI Act and Digital Operational Resilience Act (DORA) impose algorithmic audit trails and third-party risk management mandates that directly expand modernization budgets for financial services end users. EBA guidelines on ICT risk and EMA validation requirements for cloud-hosted pharmaceutical systems further tighten infrastructure compliance standards. Stakeholders must weigh the trade-off between accelerated cloud migration timelines and the documentation burden of concurrent regulatory alignment across multiple supervisory frameworks.
Market Dynamics
The EU AI Act and DORA are compressing modernization timelines across European financial services, forcing institutions to replace opaque legacy systems with auditable cloud-native architectures before enforcement deadlines arrive.
Growth Catalysts
- Algorithmic Transparency Mandates:The EU AI Act requires explainable AI pipelines that legacy mainframes cannot support, driving re-platforming budgets at continental insurers.
- Operational Resilience Deadlines:DORA's third-party risk management rules mandate ICT infrastructure overhauls that expand contract scopes for system integrators.
- Industrial Cloud Migration:German automotive suppliers are offloading monolithic ERP estates to Kubernetes environments to enable real-time supply chain visibility.
Market Restraints
- Platform Engineering Talent Scarcity:Certified Kubernetes and Terraform specialists command compensation premiums that inflate project delivery costs.
- Data Sovereignty Requirements:GDPR localization rules prevent full public cloud migration for sensitive workloads, trapping capital in hybrid infrastructure.
- Mainframe Dependency Lock-in:COBOL codebases at Italian and Spanish banks lack documentation, extending discovery phases and freezing budget flexibility.
Strategic Opportunities
- Pharmaceutical Cloud Validation:EMA guidelines for GxP-compliant cloud hosting create specialized modernization demand at mid-cap drug manufacturers.
- Edge-Native Refactoring:Convergence of 5G private networks and container orchestration enables latency-sensitive manufacturing applications.
- Polish and Romanian Delivery Expansion:Underdeveloped nearshore talent pools offer cost arbitrage for Western European system integrators.
Industry Challenges
- Multi-Framework Compliance Burden:Concurrent EBA, EMA, and national DPA audits require parallel documentation streams that strain project management capacity.
- Legacy Integration Complexity:API gateway orchestration with 30-year-old COBOL transaction processors demands scarce mainframe-cloud bilingual engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Application Modernization Services Market |
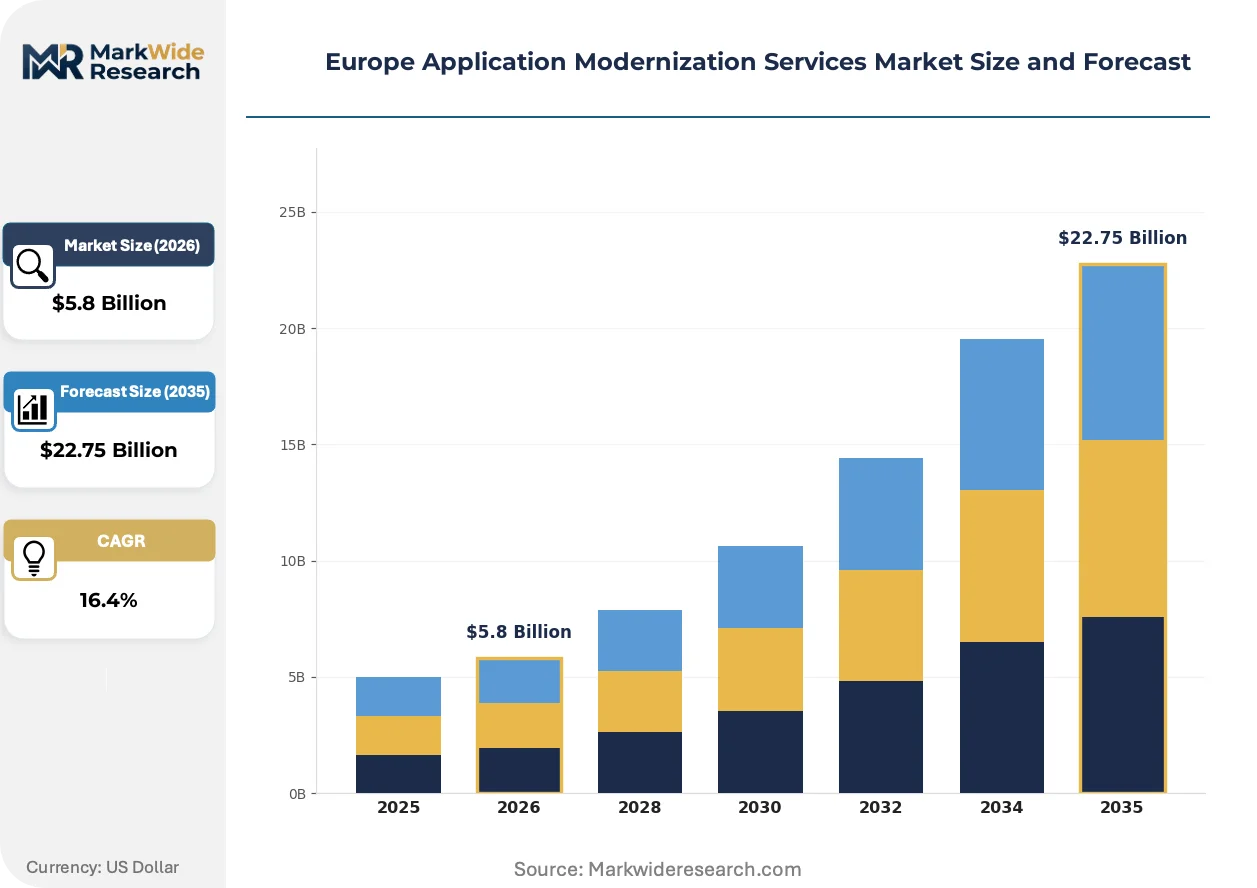
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $22.75 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Application Migration, Cloud-Native Development, API Management, Legacy Modernization Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Financial Services, Manufacturing, Retail, Healthcare Technology: Microservices, Containers, Serverless, DevOps |
| Companies Covered | Accenture, Capgemini, Atos, IBM Corporation, HCL Technologies Limited, DXC Technology Company, Tata Consultancy Services, Cognizant, Bell Integrator, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Application Modernization Services Market Strategic Shifts & Innovations
Cloud-native platform engineering is displacing lift-and-shift migration as the dominant service model, with European buyers prioritizing containerized microservices over infrastructure replication.
Serverless function architectures are miniaturizing application footprints for event-driven financial workflows. Dutch and Belgian banks are deploying AWS Lambda and Azure Functions for payment processing spikes. This compression is miniaturizing the addressable market for traditional virtual-machine-based managed services.
The EU AI Act's risk-based classification system is forcing algorithmic audit capabilities into modernization roadmaps. High-risk AI systems in credit scoring and insurance underwriting must maintain technical documentation and human oversight interfaces. German and French financial institutions are front-loading these requirements to avoid supervisory penalties.
Fixed-price transformation guarantees are displacing time-and-material contracts as the preferred commercial structure. Procurement teams at Scandinavian industrial conglomerates now demand outcome-based pricing tied to measurable cloud cost reduction. This shift is most visible in Germany's automotive supply chain, where Tier-1 suppliers negotiate gain-share arrangements for mainframe offload programs.
Europe Application Modernization Services Market Segmentation
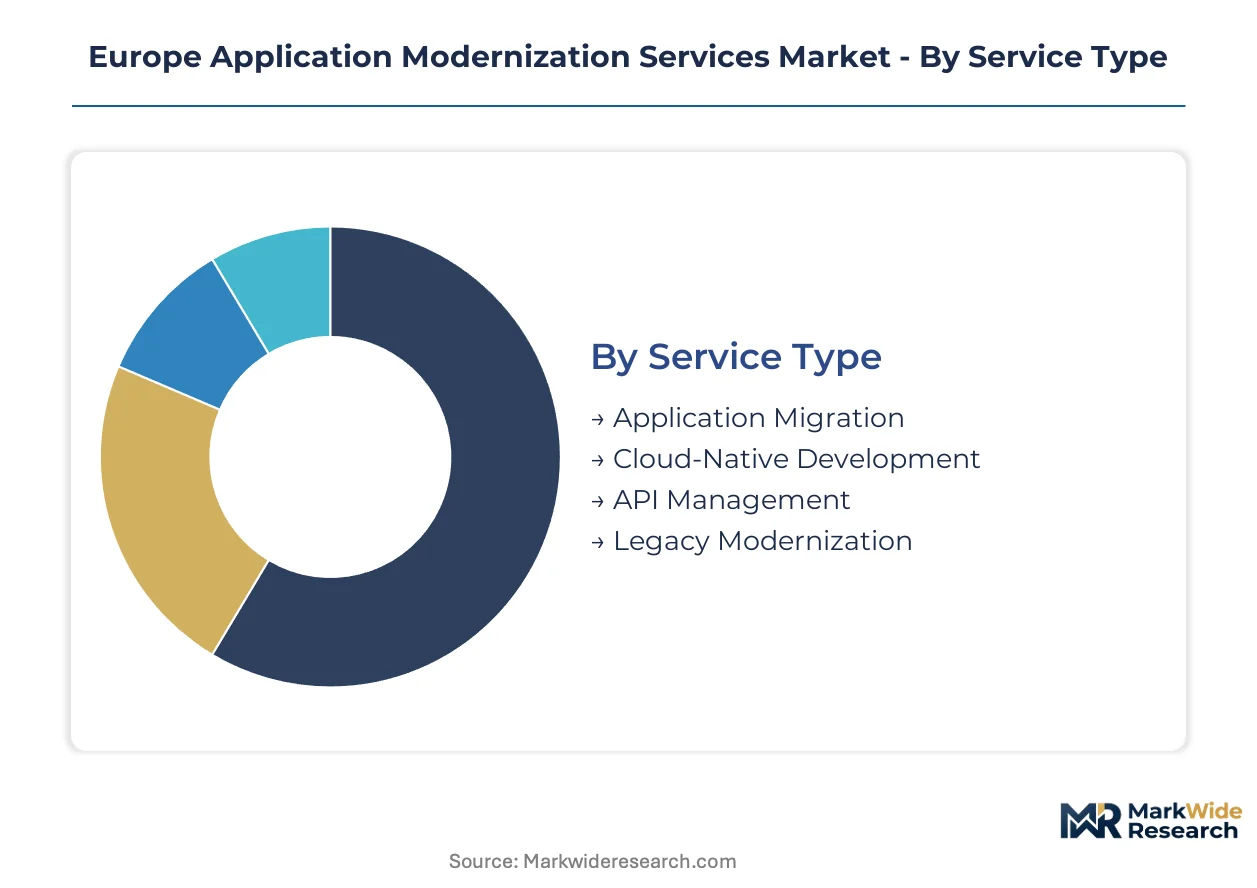
Service differentiation across the Europe Application Modernization Services Market follows distinct technical and commercial fault lines. Procurement patterns diverge sharply between regulated financial institutions seeking compliance-first architectures and industrial conglomerates prioritizing supply chain velocity.
Service Type:
Substitution pressure runs highest against traditional lift-and-shift migration as buyers demand outcome-based transformation guarantees rather than infrastructure replication.
- Cloud-Native Development:Kubernetes-native application rebuilds deploy containerized microservices with infrastructure-as-code pipelines. German automotive suppliers and Dutch banks commission these programs to achieve real-time scalability that monolithic estates cannot deliver. Talent scarcity for certified platform engineers inflates project premiums across France and the Benelux.
- Legacy Modernization:COBOL-to-cloud refactoring addresses core banking systems at Italian and Spanish institutions where documentation gaps extend discovery phases. EBA operational resilience deadlines compress implementation timelines for mainframe offload programs. These engagements retain volume leadership through multi-year transformation roadmaps.
- Application Migration:Re-hosting workloads to cloud infrastructure without architectural change serves mid-market manufacturers seeking rapid cost reduction.
- API Management:Gateway orchestration and service mesh deployment enables interoperability between modern cloud services and residual legacy systems.
Legacy Modernization anchors the volume base while Cloud-Native Development gains share at the steepest rate.
Deployment Model:
Cost tier stratification separates sovereign-cloud deployments from commodity public infrastructure, with hybrid configurations commanding intermediate pricing.
- Hybrid Cloud:Split workload architectures satisfy GDPR data localization mandates while retaining elastic compute for non-sensitive processing. French insurers and German pharmaceutical manufacturers deploy these configurations to maintain EMA and CNIL compliance without sacrificing cloud agility. Procurement teams negotiate multi-vendor contracts spanning Azure, AWS, and sovereign European cloud providers.
- Private Cloud:Dedicated infrastructure estates serve credit scoring and insurance underwriting systems classified as high-risk under the EU AI Act. German and Austrian banks invest in these deployments to maintain algorithmic audit trails that public clouds cannot guarantee. Capital intensity limits adoption to Tier-1 financial institutions.
- Public Cloud:Shared infrastructure delivers unit economics for development environments and non-production workloads at retail and logistics end users.
- On-Premises:Residual bare-metal and virtualized estates persist where latency requirements or national security classifications preclude external hosting.
Hybrid Cloud deployments expand most quickly among regulated sectors while On-Premises retention concentrates in defense and critical infrastructure.
End User:
Application maturity divides buyers between institutions replacing thirty-year-old core systems and digital-native operations seeking incremental optimization.
- Financial Services:Banks and insurers face concurrent EU AI Act and DORA compliance deadlines that mandate auditable infrastructure replacement. German and French institutions commission the largest transformation programs to meet algorithmic transparency and third-party risk management requirements. Procurement specifications now embed regulatory documentation deliverables into SOW structures.
- Manufacturing:Automotive suppliers and industrial conglomerates modernize ERP estates to enable real-time supply chain visibility and predictive maintenance. German Tier-1 suppliers negotiate gain-share contracts tied to measurable cloud cost reduction and inventory velocity improvement. Edge-native refactoring for 5G private networks represents emerging demand.
- Healthcare:Hospital systems and pharmaceutical manufacturers pursue EMA-validated cloud hosting for GxP-compliant workloads.
- Retail:Omnichannel merchants deploy serverless architectures to manage seasonal demand spikes in payment processing and inventory systems.
Financial Services commands the highest contract values per engagement while Manufacturing delivers the largest aggregate addressable expansion.
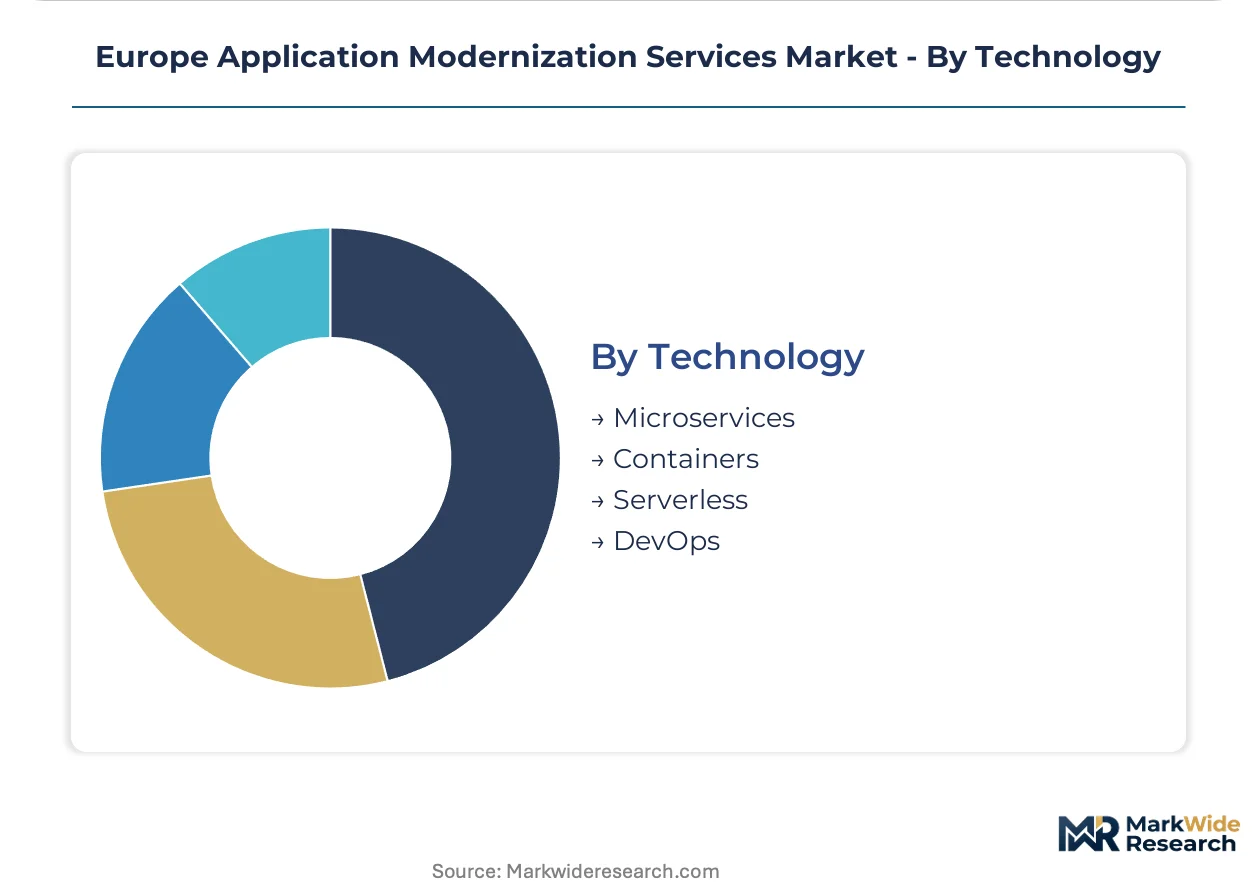
Technology:
Supply concentration for certified practitioners creates margin divergence between commoditized DevOps tooling and scarce container orchestration expertise.
- Containers:Docker and Kubernetes orchestration underpins microservices decomposition at scale, requiring platform engineering capabilities that outstrip European talent supply. Dutch cloud engineering centers and Polish delivery hubs compete for these implementation contracts. Certification premiums for CKA and CKAD credentials inflate project staffing costs.
- Microservices:Fine-grained service decomposition enables independent deployment velocity and fault isolation for complex application estates. French and German manufacturers adopt these patterns to decouple supply chain modules from monolithic ERP cores. Architectural complexity demands specialized SRE and observability tooling.
- Serverless:Function-as-a-service architectures miniaturize application footprints for event-driven financial workflows at Belgian and Dutch banks.
- DevOps:CI/CD pipeline automation and infrastructure-as-code practices underpin delivery velocity across all modernization programs.
Containers dominate current implementation spend while Serverless climbs fastest among payment processing and IoT data ingestion workloads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Europe diverge sharply between German industrial conglomerates pursuing supply chain velocity and French financial institutions prioritizing algorithmic audit compliance. The EU AI Act and DORA reshape procurement specifications differently across national markets.
Germany
Industrial automation and automotive supply chain visibility drive modernization budgets at Tier-1 suppliers. The Digital Operational Resilience Act (DORA) mandates ICT infrastructure overhauls that expand contract scopes for system integrators. Stuttgart and Munich engineering clusters anchor Kubernetes-native ERP decomposition programs for predictive maintenance workloads.
France
Banking sector algorithmic transparency requirements concentrate demand for explainable AI pipelines. CNIL guidelines on automated decision-making tighten documentation standards for credit scoring systems. Paris-based insurers and asset managers commission cloud-native rebuilds to satisfy EU AI Act high-risk system classifications.
United Kingdom
Post-Brexit regulatory divergence creates dual-compliance burden for multinational financial institutions. Financial Conduct Authority operational resilience rules parallel DORA requirements with additional stress-testing mandates. London fintech clusters drive serverless architecture adoption for payment processing spikes.
Netherlands
Logistics and maritime technology sectors prioritize real-time supply chain orchestration. GDPR data localization requirements shape hybrid cloud procurement for Rotterdam port operators. Amsterdam cloud engineering centers compete for Kubernetes implementation contracts across Benelux manufacturing networks.
Italy
Core banking system replacement dominates as COBOL documentation gaps extend discovery phases. EBA operational resilience deadlines compress timelines for mainframe offload programs at Milan and Rome financial institutions. Southern European delivery hubs emerge as cost-competitive alternatives for Western European system integrators.
Europe Application Modernization Services Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with hyperscale consultancies anchoring complex multi-year transformations while mid-tier players compete on sector-specific delivery velocity. The market structure reflects capability concentration in cloud-native platform engineering and mainframe-to-cloud bilingual expertise. Two strategic archetypes dominate: full-service integrators with multi-cloud engineering centers and fixed-price transformation specialists. Competitive moves center on geographic delivery expansion and outcome-based commercial restructuring.
Among the integrated tier, Accenture and Capgemini occupy positions as archetypal full-service providers with established European delivery footprints. Tata Consultancy Services exemplifies the fixed-price guarantee model that pressures margin structures for regional-born competitors. These three anchors represent contrasting commercial approaches to the same regulatory-driven demand pool.
| Leading Market Players |
|---|
| Accenture |
| Capgemini |
| Atos |
| IBM Corporation |
| HCL Technologies Limited |
| DXC Technology Company |
| Tata Consultancy Services |
| Cognizant |
| Bell Integrator |
| Others |
Cost & Logistics Intelligence
Fixed-price transformation guarantees displacing time-and-material contracts simultaneously concentrate contract value with integrators possessing Polish and Romanian delivery footprints while compressing margin structures for rivals lacking cost-arbitrage capabilities.
Pricing Analysis
Post-implementation support and managed service extensions drive lifetime value across multi-year modernization roadmaps. Three-tier pricing structure across premium, standard, and economy levels separates hyperscale integrators with multi-cloud platform engineering centers from mid-tier specialists competing on sector-specific velocity. Cost compression in standard-tier legacy modernization is intensifying because Tata Consultancy Services pressures European-born rivals with outcome-based guarantees. Mid-market manufacturers exhibit highest price sensitivity due to capital constraints, while German Tier-1 automotive suppliers demonstrate lowest sensitivity given gain-share contract structures tied to measurable cloud cost reduction.
Supply Chain Analysis
Container availability constraints across Rotterdam and Hamburg port complexes inflate inbound logistics costs for hardware-dependent private cloud deployments. Talent supply concentrates in Poland, Romania, and India, with platform engineering certification programs in Warsaw and Bucharest feeding Western European contract demand. Delivery draws from scarce mainframe-cloud bilingual engineers and certified Kubernetes specialists. Single-source vulnerability sits with COBOL documentation expertise concentrated among aging practitioner cohorts in Italy and Spain. Distribution runs through direct enterprise sales teams and hyperscaler marketplace partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as EU AI Act and DORA compliance deadlines splinter demand between algorithmic audit specialists and operational resilience integrators, creating distinct service niches that unified players struggle to address simultaneously.
For Market Incumbents: Consolidate around multi-cloud platform engineering centers in France and the Netherlands to anchor complex SAP modernization programs against fixed-price guarantee competitors. Acquire Polish and Romanian delivery capabilities to restore cost competitiveness against offshore challengers. Deepen mainframe-to-Azure partnerships dominating France's banking sector before DORA enforcement deadlines compress contract timelines.
For New Entrants and Emerging Players: Differentiate on pharmaceutical cloud validation expertise addressing EMA GxP-compliant hosting requirements at mid-cap drug manufacturers underserved by generalist integrators. Target edge-native refactoring for 5G private networks in German automotive supply chains. Pursue outcome-based pricing models with gain-share arrangements to bypass incumbent relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier specialists possessing deep COBOL-to-cloud refactoring capabilities but lacking Kubernetes-native platform engineering scale. Long-term viability hinges on bridging mainframe heritage talent with container orchestration delivery capacity. Watch fixed-price transformation guarantee penetration rates as inflection indicator for margin structure compression across the competitive tier.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Cloud Platform Engineering Center Expansion | Accenture anchors complex SAP modernization programs for continental manufacturers across France and Netherlands. |
| Fixed-Price Transformation Guarantee Deployment | Tata Consultancy Services pressures margin structures for European-born rivals with outcome-based contracts. |
| Nearshore Delivery Hub Establishment | Polish and Romanian talent pools offer cost arbitrage for Western European system integrators. |
| Pharmaceutical Cloud Validation Specialization | EMA guidelines for GxP-compliant hosting create specialized modernization demand at mid-cap drug manufacturers. |
| Edge-Native Refactoring Capability Buildout | Convergence of 5G private networks and container orchestration enables latency-sensitive manufacturing applications. |
Research Approach
The analysis maps cloud-native development, legacy modernization, application migration, and API management segments, each validated through CTOs, IT procurement officers, platform engineers, and integration specialists. Primary interviews with these stakeholders combine with secondary validation against hyperscaler capex disclosures, SEC filings, EU regulatory filings, and cloud engineering certification databases. Bottom-up project pipeline analysis and top-down market sizing triangulate volume estimates across service types.
Consistency checks against external benchmarks validated output plausibility across the projection horizon. The analytical framework models deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster dimensions. CAGRs derive from segment-level growth trajectory analysis incorporating EU AI Act implementation timelines, DORA enforcement deadlines, and mainframe practitioner retirement curves as industry-specific forecast inputs.
Material uncertainties — regulatory enforcement timing variations, platform engineering talent supply shocks, and hyperscaler pricing volatility — sit outside the modeled envelope. Forecasts reflect assumptions about concurrent compliance burden trajectories and cloud migration velocity. Practitioners should keep alternative scenarios live as EBA guideline interpretations and national DPA audit intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
E-Clinical Solution Software Market
Software & Services
Global Auto Dealer Software Market
Software & Services
Staffing Software Market
Software & Services
Global Automotive Software Market
Software & Services
Global Address Verification Software Market
Software & Services
Global Permit Management Software Market
Software & Services
Programming Language Market
Software & Services
Global Pharmaceutical Manufacturing Software Market
Software & Services
Global Virtual Data Room (VDR) Market
Software & Services
Software Testing Company Market
Software & Services
North America Equity Management Software Market
Software & Services
Data Preparation Tools Market
Software & Services
Online Project Management Software Market
Software & Services
Vending Software Market
Software & Services
Mobile Device Management (MDM) Market
Software & Services
Sports League Management Software Market