
 Hyperautomation Market | 2026-2036
Hyperautomation Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperautomation Market Intelligence
Enterprise-grade orchestration is reorganizing competitive dynamics in the hyperautomation space. UiPath, Inc. leverages its robotic process automation platform to anchor workflow automation across Fortune 500 accounts. Automation Anywhere, Inc. competes through cloud-native architecture that sustains deployment flexibility for hybrid environments. Microsoft Corporation extends its advantage by integrating hyperautomation capabilities deeply within its productivity and cloud ecosystems.
Hyperautomation denotes the disciplined orchestration of multiple automation technologies—robotic process automation, artificial intelligence, machine learning, and natural language processing—into unified systems that execute complex business processes with minimal human intervention. These systems typically operate through API-driven architectures that enable real-time data exchange across enterprise applications. The technology segment dominates current spending as organizations prioritize AI-enhanced automation over standalone RPA deployments. Cloud-based deployment is capturing the fastest growth trajectory as enterprises abandon capital-intensive on-premises infrastructure in favor of scalable SaaS models. Banking and insurance verticals concentrate the deepest margin pools due to compliance-intensive workflows that reward automation precision.
The EU AI Act and GDPR framework shape algorithmic transparency mandates that directly impact hyperautomation deployments in European jurisdictions. The SEC's disclosure requirements for material cybersecurity incidents in the United States are compelling publicly traded enterprises to embed automated governance controls within their automation stacks. Stakeholders must monitor evolving regulatory fragmentation between jurisdictions as a primary determinant of platform architecture decisions and market access strategies.
Market Dynamics
Enterprise orchestration platforms are consolidating control over fragmented automation toolchains, compressing vendor margins while elevating architecture decisions to C-suite priority. The EU AI Act's risk-classification framework for automated decision systems is forcing platform redesigns ahead of enforcement timelines.
Growth Catalysts
- GDPR Article 22 mandates:European enterprises must maintain human oversight of automated profiling, creating sustained demand for human-in-the-loop orchestration layers that audit AI-driven process decisions.
- Banking compliance workflows:Financial institutions in the United States face SEC disclosure requirements for material cybersecurity incidents, accelerating deployment of automated governance controls within automation stacks.
- API-first architectures:Real-time data exchange protocols enable unified systems that stitch robotic process automation with machine learning inference engines, reducing integration friction for hybrid cloud deployments.
Market Restraints
- Specialized talent scarcity:Shortage of engineers proficient in both legacy mainframe systems and modern API orchestration limits deployment velocity for large-scale automation programs.
- Algorithmic audit costs:EU AI Act conformity assessments for high-risk automated decision systems impose documentation burdens that extend implementation timelines and inflate professional services spend.
- Cloud concentration risk:Dominance of hyperscale infrastructure providers in North America creates dependency exposure for enterprises seeking multi-cloud failover capabilities.
Strategic Opportunities
- Process mining convergence:Integration of task capture analytics with automation design tools enables discovery-led deployment models that identify automation candidates without manual process mapping.
- India's digital public infrastructure:Unified Payments Interface and Aadhaar-linked service delivery create standardized data environments where hyperautomation platforms can achieve faster time-to-value for government and banking use cases.
- CSRD reporting automation:Corporate Sustainability Reporting Directive mandates in Europe are generating demand for automated data collection and validation workflows across supply chain emissions tracking.
Industry Challenges
- Legacy system entanglement:Mainframe-dependent enterprises struggle to expose stable APIs for automation platforms, forcing expensive middleware development or risky rip-and-replace decisions.
- Cross-functional coordination gaps:Automation programs require alignment between IT security, compliance legal, and business operations teams with conflicting incentive structures and budget ownership.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperautomation Market |
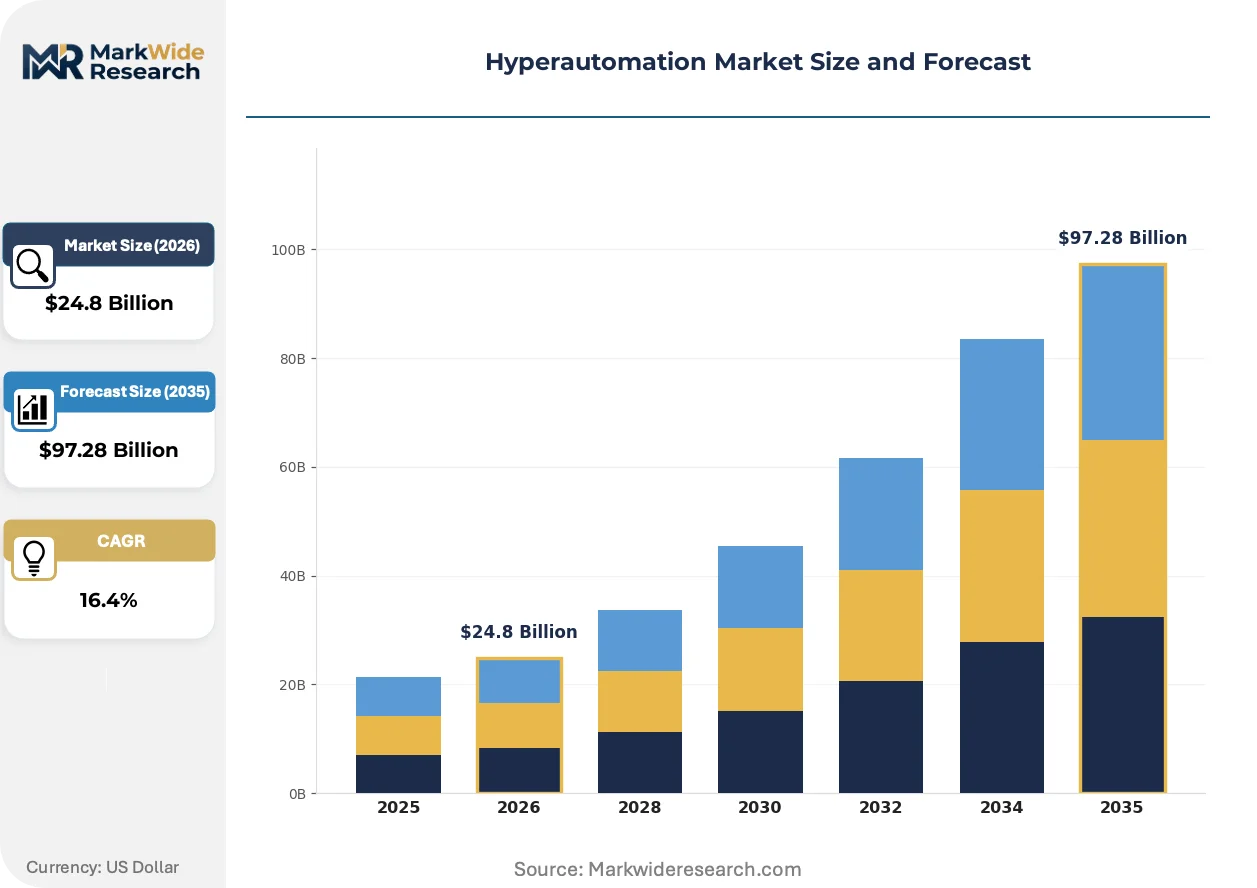
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $97.28 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Robotic Process Automation, Artificial Intelligence, Machine Learning, Natural Language Processing Deployment: Cloud-Based, On-Premises, Hybrid, Multi-Cloud Industry Vertical: Banking, Insurance, Healthcare, Telecommunications End User: Large Enterprises, SMEs, Government Agencies, Non-Profit Organizations |
| Companies Covered | UiPath, Inc., Automation Anywhere, Inc., Tata Consultancy Services Ltd., Appian Corporation, Microsoft Corporation, IBM Corporation, Honeywell International, Inc., Mitsubishi Electric Corporation, Blue Prism Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperautomation Market Strategic Shifts & Innovations
Agentic AI architectures are displacing rule-based automation sequences, enabling systems that autonomously plan multi-step workflows rather than executing pre-scripted tasks. This shift is compressing the boundary between decision support and autonomous execution.
Large language model integration is bifurcating the automation stack between deterministic RPA backends and probabilistic natural language interfaces. Insurance claims processors are deploying these hybrid systems to extract unstructured data from submission documents while maintaining auditable decision trails. The structural consequence is a compression in pure-play document capture software margins as LLM capabilities subsume specialized extraction tools.
EU AI Act enforcement preparations are mandating algorithmic impact assessments for high-risk automation deployments. European banking regulators are requiring documented human override mechanisms for credit-scoring automations. German automotive manufacturers are responding by embedding governance checkpoints within their manufacturing execution system integrations, creating procurement preference for platforms with built-in audit logging.
Consumption-based licensing models are displacing perpetual seat-based contracts in enterprise automation procurement. Managed service providers are capturing workflow orchestration contracts that bundle platform access with outcome-guaranteed operational support. This shift is most visible in United States healthcare revenue cycle management, where hospitals prefer variable-cost automation partnerships over capital-intensive platform purchases.
Hyperautomation Market Segmentation
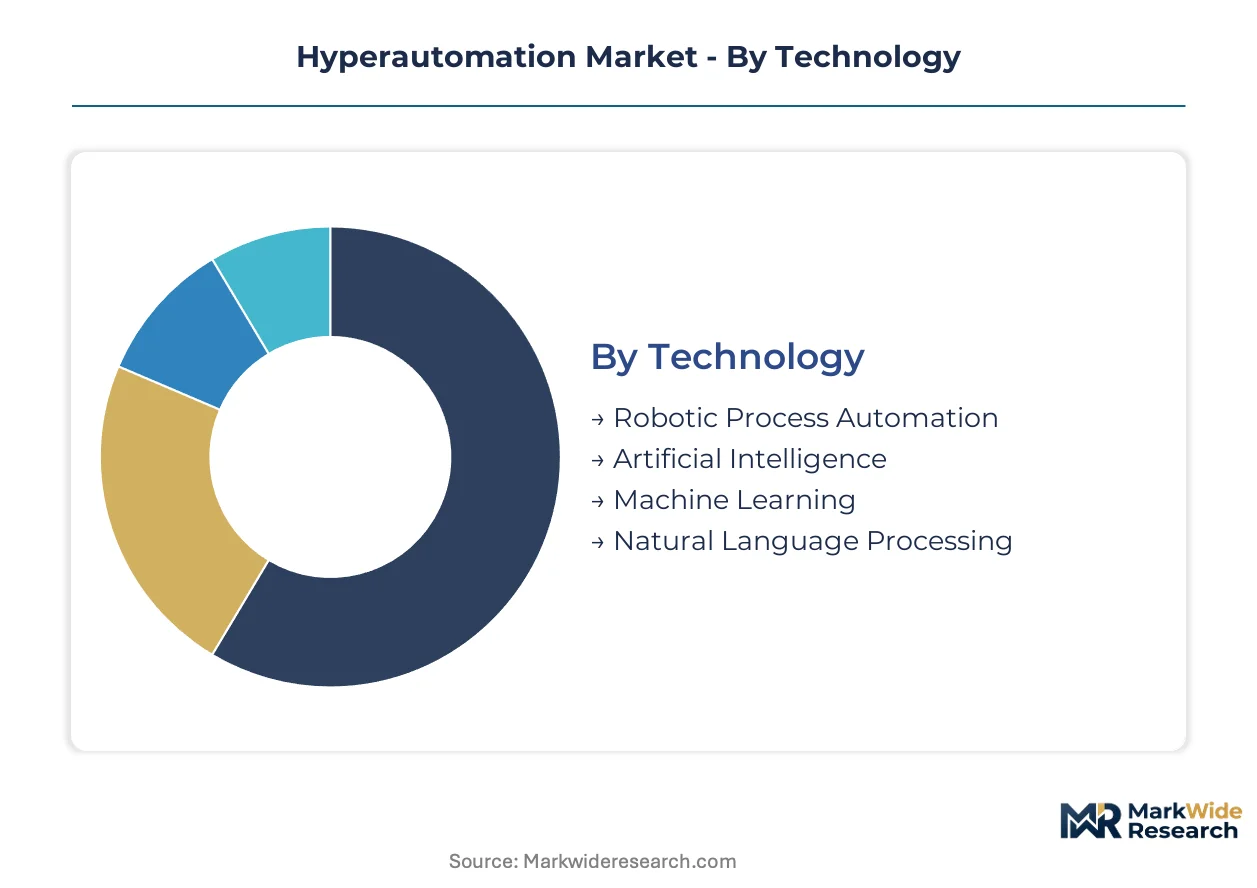
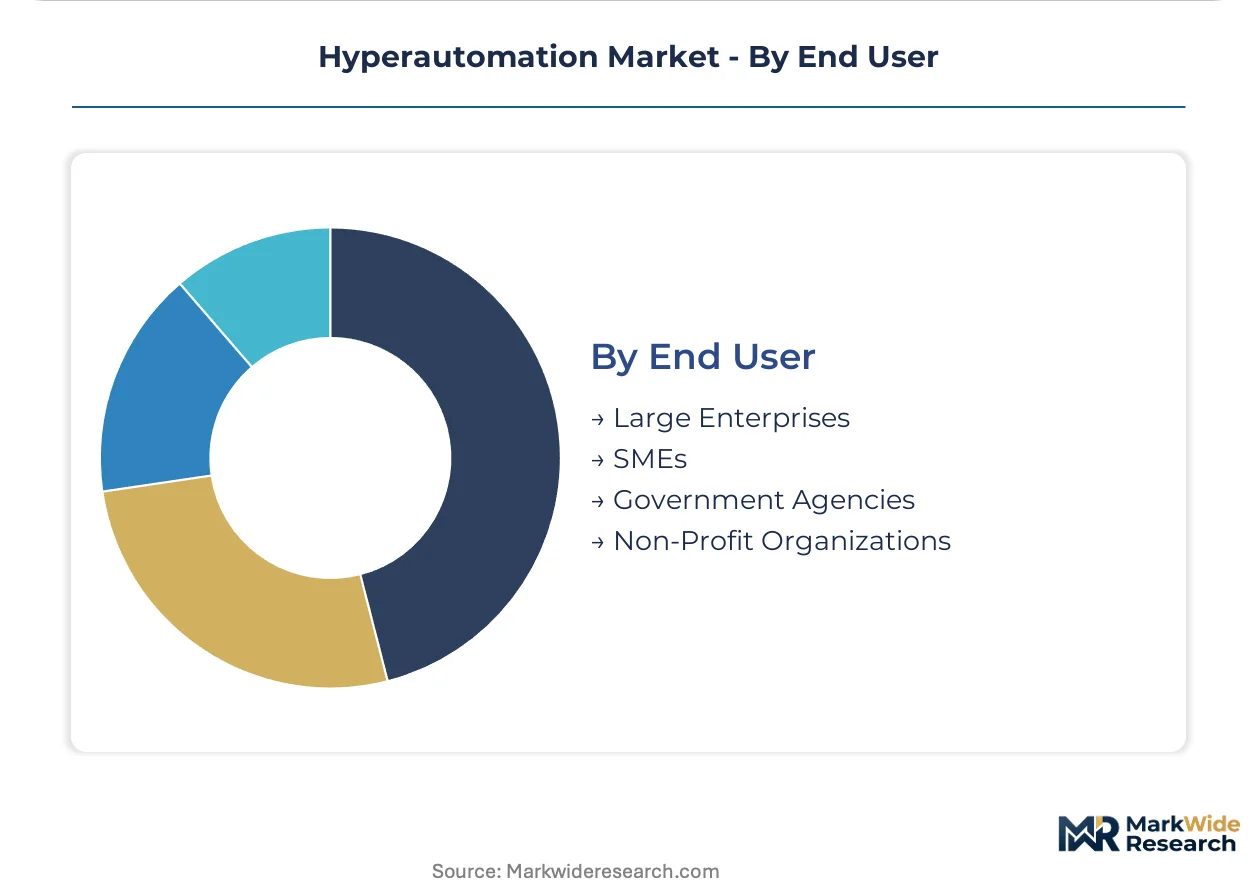
Hyperautomation deployments fragment across technology stacks, infrastructure models, and organizational contexts. Regulatory requirements from the EU AI Act, SEC disclosure mandates, and sector-specific compliance frameworks reshape how enterprises prioritize segments. Understanding these divisions reveals where procurement budgets concentrate and where platform architectures must adapt.
Technology:
GDPR Article 22 and EU AI Act risk classifications differentiate compliance burdens across automation technologies, forcing divergent governance investments.
- Robotic Process Automation:Rule-based software bots execute repetitive, structured tasks through UI interactions and API calls. Banking operations in the United States deploy RPA for Know Your Customer workflows, though legacy mainframe integration limits API-native deployments. RPA handles the majority of throughput; Artificial Intelligence is the fastest mover on share.
- Artificial Intelligence:Cognitive engines process unstructured data, make probabilistic decisions, and enable adaptive process optimization. Insurance underwriting in Germany faces heightened documentation requirements under EU AI Act high-risk system classifications, extending implementation timelines. AI capabilities are climbing the fastest as enterprises prioritize decision automation over task execution.
- Machine Learning:Statistical models trained on historical data predict outcomes and flag anomalies within operational workflows.
- Natural Language Processing:Text and speech analysis tools extract meaning from documents, emails, and conversational interfaces.
Machine Learning and NLP function as enabling layers rather than standalone procurement categories in most enterprise architectures.
Deployment:
Cost tier differentiation separates capital-intensive on-premises builds from variable-cost cloud consumption models favored by CFOs managing OpEx ratios.
- Cloud-Based:SaaS-delivered automation platforms eliminate infrastructure ownership, enabling rapid scaling and automatic feature updates. Healthcare revenue cycle management in the United States prefers consumption-based partnerships over perpetual licenses, aligning costs with transaction volumes. Cloud-Based is expanding most quickly; On-Premises retains share in defense and classified government environments.
- On-Premises:Self-managed infrastructure within enterprise data centers satisfies data residency requirements and air-gapped security mandates. German automotive manufacturers maintain on-premises manufacturing execution system integrations to satisfy industrial data sovereignty preferences.
- Hybrid:Split architectures place sensitive processing on-premises while leveraging cloud elasticity for non-critical workloads.
- Multi-Cloud:Redundancy across AWS, Azure, and GCP infrastructure mitigates vendor lock-in and satisfies geographic failover requirements.
Hybrid architectures dominate European banking due to GDPR data localization constraints; Multi-Cloud is gaining share fastest among Fortune 500 technology companies.
Industry Vertical:
Margin concentration tracks compliance intensity, with verticals facing the densest regulatory scrutiny commanding premium platform pricing.
- Banking:Transaction processing, regulatory reporting, and customer onboarding automation face SEC cybersecurity disclosure requirements and Fed stress testing mandates. United States institutions embed automated governance controls within automation stacks to satisfy material incident reporting timelines.
- Insurance:Claims processing, underwriting, and policy administration leverage document extraction and decision automation. French insurers navigate CNIL guidance on automated profiling alongside EU AI Act conformity assessments for high-risk systems.
- Healthcare:Revenue cycle management, clinical documentation, and prior authorization workflows operate under HIPAA privacy and security rules.
- Telecommunications:Network operations, customer service, and billing automation manage massive transaction volumes with lower per-transaction compliance overhead.
Banking and Insurance concentrate the deepest margin pools; Healthcare is the fastest-expanding vertical as hospital systems modernize revenue operations.
End User:
Organizational scale determines procurement complexity, with large enterprises demanding customization and SMEs prioritizing out-of-box deployment speed.
- Large Enterprises:Fortune 500 and equivalent organizations operate multi-year automation programs with dedicated Centers of Excellence. India's Unified Payments Interface creates standardized data environments where government and banking use cases achieve faster time-to-value.
- SMEs:Mid-market companies adopt templated automation solutions through managed service providers, avoiding internal platform expertise requirements. United States regional banks contract outcome-guaranteed revenue cycle partnerships rather than building internal capabilities.
- Government Agencies:Public sector procurement emphasizes vendor diversity certifications, FedRAMP authorization, and long-term maintenance guarantees.
- Non-Profit Organizations:Mission-driven entities prioritize donor-funded automation for administrative efficiency over revenue-generating process transformation.
Large Enterprises command platform roadmap influence through direct engineering collaboration; SMEs are expanding fastest as low-code tools democratize access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperautomation platform development concentrates in technology corridors where enterprise software engineering talent pools intersect with dense banking and insurance headquarters. The United States, Germany, India, Japan, and the United Kingdom anchor deployment scale and vendor R&D investment.
United States
Fortune 500 banking operations and healthcare revenue cycle managers drive platform consumption across New York, Charlotte, and San Francisco Bay Area clusters. SEC cybersecurity disclosure requirements for material incidents compel automated governance control integration within automation stacks. UiPath, Inc. and Automation Anywhere, Inc. maintain headquarters and primary engineering centers in this market.
Germany
Automotive manufacturing execution systems and industrial insurance underwriting create demand for high-assurance automation with embedded audit logging. EU AI Act high-risk system classifications and KBA technical standards mandate documented human override mechanisms for credit-scoring automations. Bavaria and Baden-Württemberg host Siemens AG and automotive supplier clusters deploying these governance-heavy implementations.
India
Unified Payments Interface standardization and Aadhaar-linked service delivery generate government and banking use cases with faster time-to-value. RBI guidelines on digital lending and SEBI compliance automation requirements shape platform procurement specifications. Bengaluru and Hyderabad technology corridors concentrate Tata Consultancy Services Ltd. delivery centers and domestic hyperautomation startups.
Japan
Metropolitan banks and precision manufacturing enterprises prioritize deterministic RPA backends over probabilistic AI interfaces for operational reliability. METI industrial data governance guidelines and JIS standards for automated systems influence platform architecture decisions. Tokyo-Osaka corridor deployments emphasize human-in-the-loop orchestration layers for compliance documentation.
United Kingdom
London financial services institutions and NHS administrative modernization programs sustain demand for cloud-native orchestration platforms. FCA operational resilience requirements and post-Brexit data localization rules shape hybrid deployment preferences. Blue Prism Ltd. originated in this market, anchoring a regional specialist ecosystem in Manchester and London technology clusters.
Hyperautomation Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where specialized RPA vendors, hyperscale cloud platforms, and systems integrators occupy distinct strategic positions. The vendor base organizes around three archetypes: pure-play automation platform developers, productivity software incumbents with embedded orchestration capabilities, and global IT services firms delivering managed automation outcomes. Consolidation pressure intensifies as enterprise procurement shifts from point solutions toward unified orchestration suites. Strategic moves center on API ecosystem expansion and consumption-based licensing model adoption.
Within the pure-play platform tier, UiPath, Inc. and Automation Anywhere, Inc. exemplify specialized vendors competing through robotic process automation depth and cloud-native architecture flexibility respectively. Microsoft Corporation represents the productivity incumbent archetype, leveraging Office 365 and Azure ecosystem integration to embed hyperautomation within existing enterprise workflows. Tata Consultancy Services Ltd. occupies the systems integrator position, bundling platform implementation with outcome-guaranteed operational support for banking and insurance clients.
| Leading Market Players |
|---|
| UiPath, Inc. |
| Automation Anywhere, Inc. |
| Tata Consultancy Services Ltd. |
| Appian Corporation |
| Microsoft Corporation |
| IBM Corporation |
| Honeywell International, Inc. |
| Mitsubishi Electric Corporation |
| Blue Prism Ltd. |
| Others |
Cost & Logistics Intelligence
Consumption-based licensing agreements lock in multi-year platform access while capping price escalation risk for enterprises navigating EU AI Act compliance costs. These contract structures bundle SaaS delivery with outcome-guaranteed operational support, aligning vendor revenue to customer transaction volumes rather than upfront seat purchases.
Pricing Analysis
EU AI Act conformity assessments dictate the pricing tier structure for high-risk automation deployments in European jurisdictions. Three-tier pricing separates enterprise-grade orchestration platforms with embedded audit logging from mid-market SaaS offerings and basic RPA toolkits lacking governance modules. Price differentiation rests on certification depth—platforms pre-validated for banking credit-scoring automations command premium positioning against uncertified alternatives. Cost compression in the mid-market tier is intensifying as hyperscale productivity suites bundle automation capabilities at marginal incremental pricing. SME buyers exhibit highest price sensitivity, preferring outcome-guaranteed managed service partnerships over capital-intensive platform licenses.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes compress margin buffers for hardware-dependent edge automation deployments. Software supply chains draw from engineering talent pools concentrated in the United States, India, and Germany, with cloud infrastructure provisioning anchored in hyperscale data center clusters across Virginia, Frankfurt, and Mumbai. Proprietary AI model training, open-source orchestration frameworks, and API middleware constitute critical input dependencies. Single-source vulnerability runs through NVIDIA GPU supply for machine learning inference workloads. Distribution runs through direct enterprise sales teams and systems integrator partnerships for complex implementations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyperautomation penetration remains in early-cycle expansion as agentic AI architectures displace rule-based sequences and unlock autonomous workflow planning previously requiring human intervention.
For Market Incumbents: Secure API ecosystem dominance by embedding governance checkpoints that satisfy EU AI Act documentation requirements ahead of enforcement timelines. Deepen vertical integration into process mining analytics to preempt displacement by standalone discovery vendors. Threat substitution from hyperscale productivity suites bundling automation at marginal cost demands roadmap differentiation through industry-specific compliance pre-certification. For New Entrants and Emerging Players: Lead with India's Unified Payments Interface and Aadhaar-linked service delivery environments where standardized data formats accelerate time-to-value for government and banking automation use cases. White-space targets include SME revenue cycle management in United States healthcare and CSRD reporting automation for European supply chain emissions tracking. Go-to-market positioning as outcome-guaranteed managed service providers bypasses internal platform expertise requirements that constrain mid-market adoption. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platforms with consumption-based licensing and embedded governance modules that generate switching costs through compliance documentation accumulation. Long-term viability across the next decade favors vendors with proven EU AI Act pre-certification and established Centers of Excellence relationships at Fortune 500 accounts. Acquisition target archetype: specialized process mining or document extraction vendors whose capabilities are being subsumed by LLM integration but retain enterprise customer density. Signal to watch: procurement shift from point solutions toward unified orchestration suites accelerating consolidation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding hyperautomation within Microsoft 365 and Azure ecosystems captures existing enterprise workflow density. |
| Acquisition of Specialist Firm | Consolidating process mining capabilities enables discovery-led deployment models that reduce manual process mapping. |
| Geographic Expansion | Establishing delivery centers in Bengaluru and Hyderabad accesses India's standardized digital public infrastructure. |
| Strategic Partnership | Aligning with Tata Consultancy Services bundles platform access with outcome-guaranteed banking implementation. |
| Product Launch | Releasing agentic AI architectures with documented human override mechanisms satisfies German KBA technical standards. |
Research Approach
Desk research of SEC 10-K filings, EU regulatory impact assessments, and hyperscaler capex disclosures preceded structured interviews with CTOs, IT procurement officers, platform engineers, and channel partners across banking, insurance, and healthcare verticals. Primary fieldwork captured deployment timeline data, compliance cost structures, and vendor selection criteria. Secondary validation drew from automation platform documentation, Gartner and Forrester vendor evaluations, and trade association surveys. Bottom-up segment sizing triangulated against top-down market expenditure estimates.
Variance decomposition across technology, deployment model, industry vertical, and end-user segments shaped the analytical framework over the projection horizon. Modeled dimensions included RPA versus AI capability mix, cloud-native versus on-premises infrastructure, compliance intensity by vertical, and organizational scale. CAGRs derived from segment-level growth rate assumptions weighted by current expenditure shares. Forecast inputs incorporated EU AI Act implementation timelines and SEC cybersecurity disclosure mandate compliance velocity.
Forecasts assume regulatory continuity in EU AI Act enforcement, SEC disclosure requirements, and GDPR Article 22 interpretation; material policy shifts would require re-modeling. Technology substitution risk from generative AI capabilities and talent scarcity constraints on deployment velocity represent primary forecast revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Home Automation System Market
Automation
Middle East and Africa Workforce Management Market
Automation
RFID Kanban Systems Market
Automation
Global Direct Mail Automation Software Market
Automation
North America Marketing Automation Software Market
Automation
Retail Automation Market
Automation
Laboratory Benchtop Automation Market
Automation
Terminal Automation Systems Market
Automation
Home Automation and Controls Market
Automation
Global Process Automation and Instrumentation Market
Automation
Database Automation Market
Automation
Smart Home Automation Market
Automation
Playout Automation Market
Automation
Automatic Message Handling System Market
Automation
Global Remote Monitoring and Control Market
Automation
Automated Cell Block Systems Market