
 Global Catalog Management Systems Market | 2026-2036
Global Catalog Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Catalog Management Systems Market Foresight
Enterprise data steward shortages are unwinding implementation timelines for complex catalog deployments. SAP SE leverages its ERP integration depth to anchor multi-domain product data hubs for industrial manufacturers. Oracle Corporation competes through database-native architectures that sustain real-time synchronization across distributed supplier networks. Akeneo SAS specializes in open-source flexibility, positioning its platform for mid-market brands seeking modular growth paths.
Catalog management systems govern the centralized creation, enrichment, and distribution of structured product data across sales channels, typically enforcing attribute consistency through configurable taxonomies and validation rules. Cloud-based deployment leads solution uptake as organizations trade capital intensity for elastic scalability and API-first integration architectures. Product Information Management captures the largest solution share by revenue, while Digital Asset Management grows fastest as video and 3D content proliferate across e-commerce storefronts. Wholesale Distribution and Manufacturing use cases dominate current installations, though Retail Chains represent the deepest expansion opportunity as unified commerce strategies demand single-source product truth.
FDA oversight of medical device labeling intersects with HIPAA data handling requirements to elevate catalog accuracy standards in healthcare-adjacent commerce. EMA's MDR traceability mandates and the EU AI Act's risk classification framework further compel European manufacturers to invest in auditable product data lineage. GDPR enforcement by national regulators across France, Germany, and Italy tightens consent-linked attribute management for customer-facing catalogs. Stakeholders must weigh interoperability investments against emerging sovereignty requirements that fragment cloud infrastructure choices.
Market Dynamics
Cloud-native architectures are compressing deployment cycles for enterprise catalog platforms while GDPR and EU AI Act compliance mandates force parallel investments in auditable data lineage infrastructure.
Growth Catalysts
- EU AI Act risk classification:European manufacturers must maintain traceable product attribute histories, forcing upgrades to governance-ready catalog systems.
- Video and 3D asset proliferation:Digital Asset Management modules capture expanding share as e-commerce storefronts demand rich media orchestration.
- India:PLI scheme incentives for electronics manufacturing are accelerating digital commerce infrastructure buildouts requiring centralized product data hubs.
Market Restraints
- Enterprise data steward scarcity:Specialized talent shortages in Germany and the United States extend implementation timelines for multi-domain deployments.
- Cloud infrastructure sovereignty requirements:Fragmented data localization rules across France, Germany, and Italy complicate single-tenant architecture decisions.
- Legacy ERP integration friction:Custom middleware requirements for SAP and Oracle environments inflate total cost of ownership for mid-market adopters.
Strategic Opportunities
- Healthcare-adjacent commerce:FDA medical device labeling intersects with HIPAA handling requirements, creating specialized accuracy standards for catalog vendors.
- Real-time supplier synchronization:API-first architectures enable distributed manufacturing networks to maintain attribute consistency across tiered supplier bases.
- EMA MDR traceability mandates:European medical device manufacturers face auditable product lineage requirements that favor investment in compliant platforms.
Industry Challenges
- Taxonomy standardization delays:Competing industry-specific classification schemes force redundant mapping exercises during cross-vertical deployments.
- Consent-linked attribute management:GDPR enforcement by CNIL and national regulators complicates customer-facing catalog personalization workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Catalog Management Systems Market |
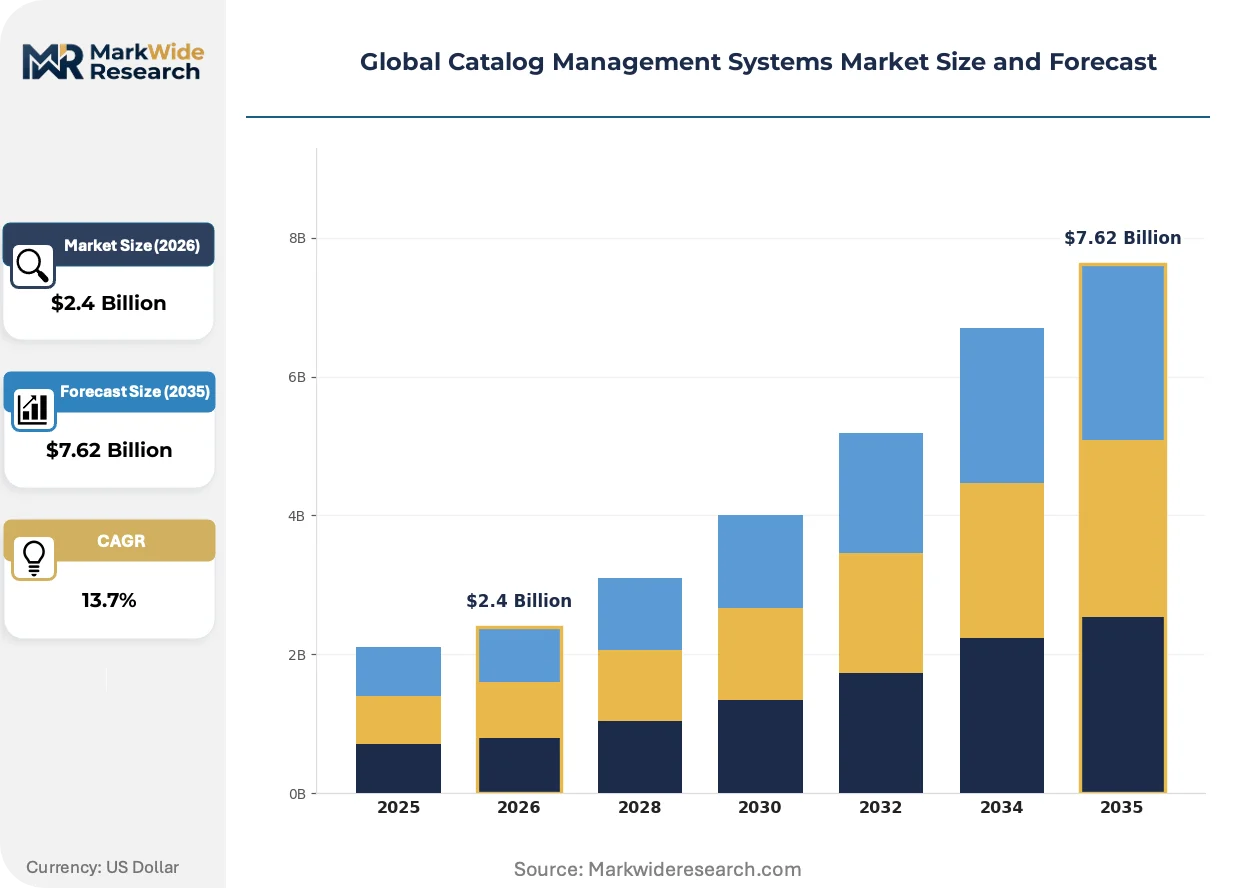
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.62 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Private Cloud, Public Cloud Solution/Offering: Product Information Management, Digital Asset Management, Data Quality Management, Syndication, Pricing Management Use Case: E-commerce, Wholesale Distribution, Manufacturing, Publishing, Telecommunications Customer Type: Retail Chains, Distributors, Manufacturers, Content Providers, Service Providers |
| Companies Covered | IBM Corporation, SAP SE, Oracle Corporation, Salsify Inc., Coupa Software Inc., ServiceNow Inc., Broadcom Inc., Fujitsu Limited, Akeneo SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Catalog Management Systems Market Shifts & Advancements
Generative AI is infiltrating attribute enrichment workflows while regulatory pressure hardens data governance requirements across transatlantic commerce corridors.
Large language models are automating product description generation and attribute extraction from unstructured supplier documents. Mid-market brands in India and Germany are piloting these tools to compress content production cycles. The technology is bifurcating vendor roadmaps between governance-first incumbents and speed-focused challengers.
EMA's MDR traceability mandates and FDA Unique Device Identification rules are converging to elevate healthcare catalog accuracy standards. Manufacturers must maintain immutable audit trails linking product attributes to regulatory submissions. European and American medical device exporters are consolidating onto platforms with pre-built compliance modules.
Unified commerce strategies are collapsing channel-specific product silos into single-source data hubs. Retail chains in the United States are retiring channel-dedicated catalogs in favor of centralized enrichment workflows. This consolidation is most visible among enterprise merchants operating physical-digital hybrid footprints.
Global Catalog Management Systems Market Segmentation
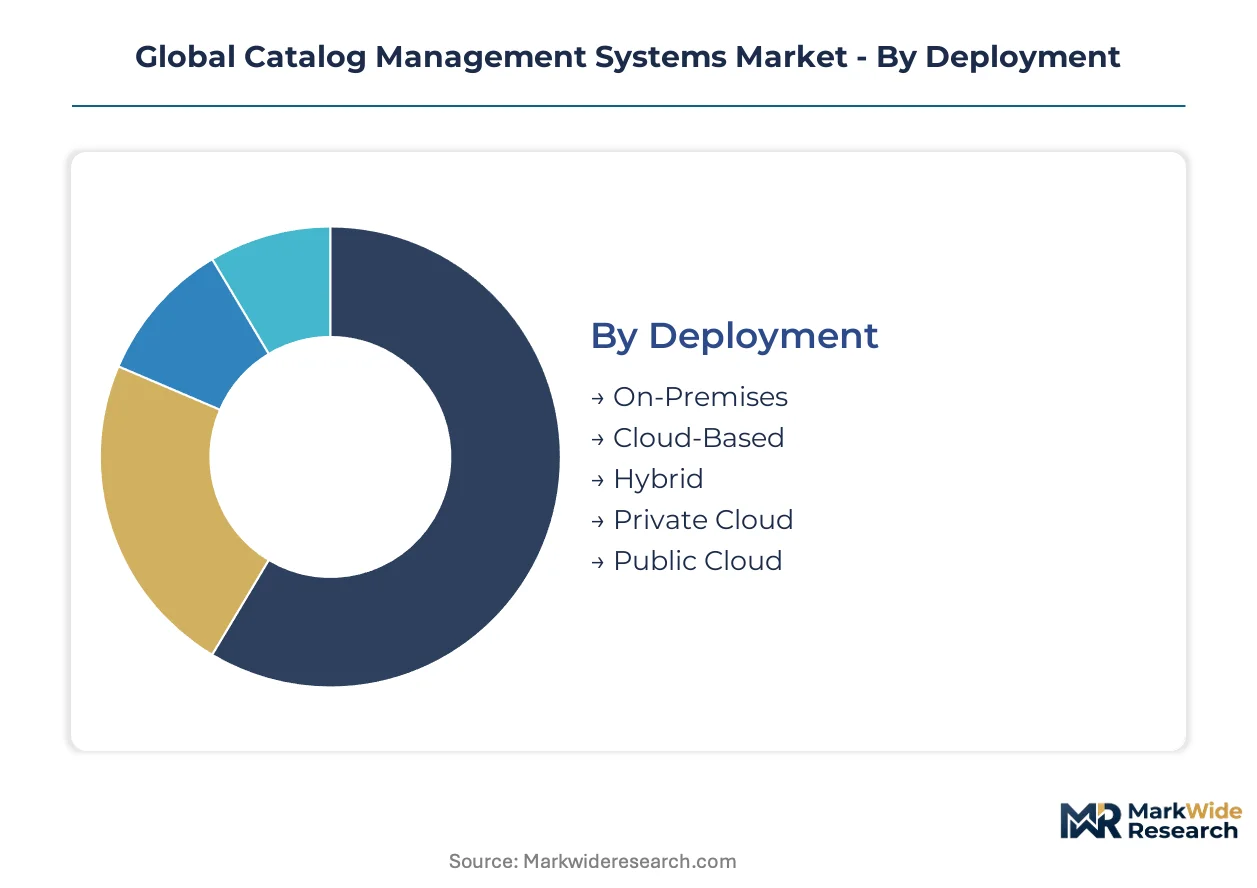
Catalog management systems fragment across deployment models, solution layers, and customer archetypes. Understanding margin concentration within each dimension reveals where vendors can defend pricing power and where commoditization pressures intensify.
Deployment:
Margin pools concentrate in cloud-native architectures that command recurring revenue premiums, while on-premises deployments face compression from infrastructure outsourcing trends.
- Cloud-Based:Multi-tenant SaaS architectures deliver elastic scalability through API-first integration frameworks. Enterprise retailers in the United States and Germany are migrating core product data hubs to these platforms to compress capital expenditure cycles.
- Hybrid:Split architectures partition sensitive master data on-premises while syndicating enriched content through cloud edge nodes. Indian electronics manufacturers under PLI scheme incentives favor this model to satisfy data localization requirements without sacrificing channel agility.
- On-Premises:Single-tenant installations persist in defense and healthcare-adjacent sectors where HIPAA and FDA audit trails mandate physical infrastructure control.
- Private Cloud:Dedicated tenant environments hosted in third-party facilities address European sovereignty concerns under GDPR and EU AI Act jurisdiction rules.
- Public Cloud:Shared infrastructure deployments serve mid-market brands seeking modular growth paths without dedicated DevOps overhead.
Cloud-Based holds installed capacity. Hybrid is rotating up the share rankings.
Solution/Offering:
Application depth varies by vertical data complexity, with healthcare and industrial manufacturing demanding specialized modules that sustain price premiums.
- Product Information Management:Centralized attribute governance platforms enforce taxonomy consistency across distributed supplier networks. Wholesale distributors in Germany deploy these systems to synchronize tiered supplier bases under EMA MDR traceability mandates.
- Digital Asset Management:Rich media orchestration engines manage video, 3D, and augmented reality content lifecycles. United States retail chains are consolidating channel-specific creative silos into unified repositories to support hybrid commerce strategies.
- Data Quality Management:Validation engines scrub inbound supplier feeds against configurable rules and reference datasets.
- Syndication:Multi-channel publishing adapters translate master data into marketplace-specific formats.
- Pricing Management:Dynamic optimization modules link product attributes to competitive positioning algorithms.
Product Information Management anchors current revenue. Digital Asset Management is gaining share fastest as rich media proliferates.
Use Case:
Volume concentration tracks digital commerce infrastructure maturity, with manufacturing and wholesale distribution representing installed base depth while telecommunications emerges as greenfield expansion terrain.
- Wholesale Distribution:Multi-tier supplier synchronization platforms maintain attribute consistency across fragmented sourcing networks. Distributors in India are building these capabilities to serve electronics manufacturing clusters under PLI scheme acceleration.
- Manufacturing:Product data hubs integrate engineering BOMs with commercial attributes for unified lifecycle management. Industrial manufacturers in Germany deploy these systems to satisfy EMA MDR and EU AI Act auditable lineage requirements.
- E-commerce:Channel-specific enrichment workflows optimize product discovery and conversion metrics.
- Publishing:Metadata management systems govern rights-cleared content distribution across subscriber platforms.
- Telecommunications:Service catalog platforms bundle network products with configurable pricing and eligibility rules.
Manufacturing holds installed capacity. Telecommunications is rotating up the share rankings.
Customer Type:
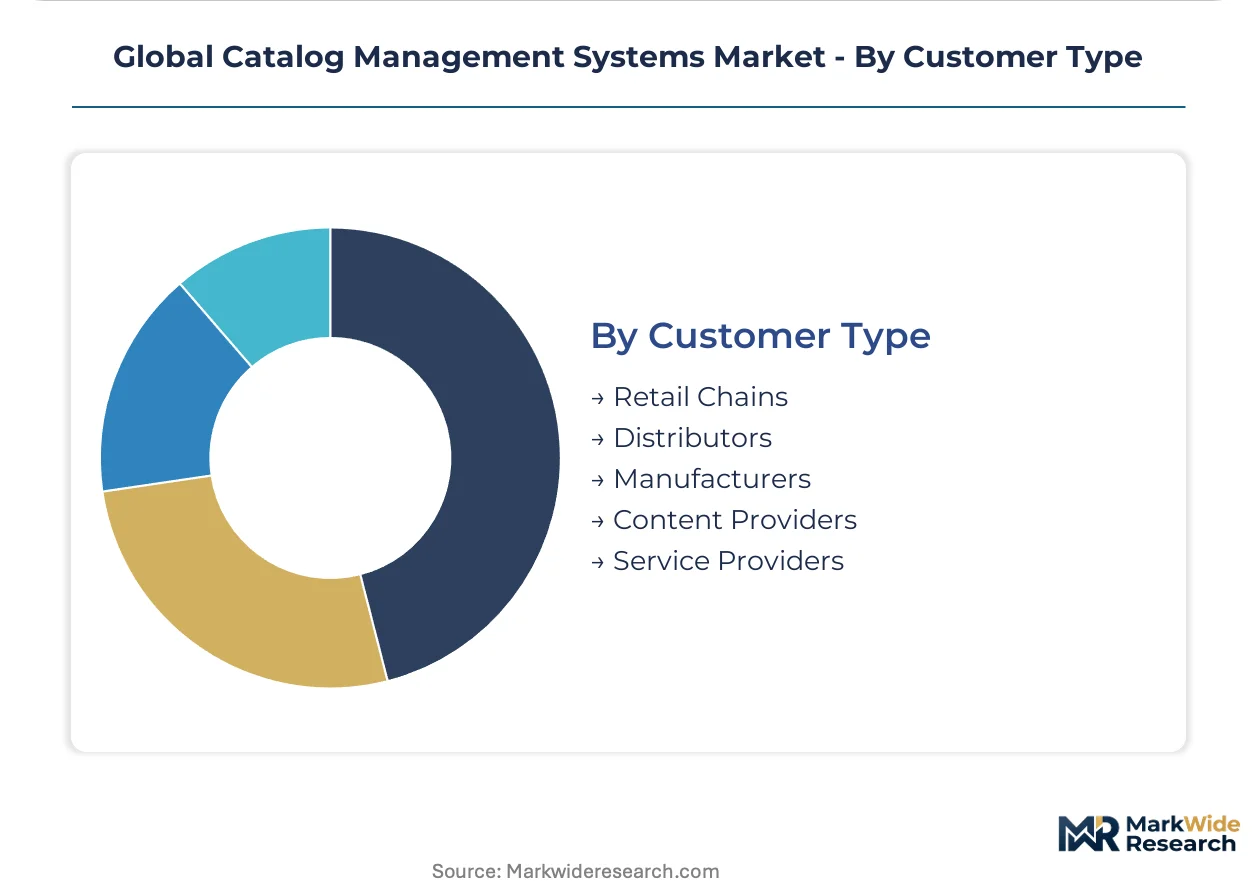
Procurement sophistication separates enterprise adopters with dedicated data governance functions from mid-market buyers seeking managed service overlays.
- Retail Chains:Unified commerce operators collapsing physical and digital product silos into single-source data hubs. United States enterprise merchants are retiring channel-dedicated catalogs in favor of centralized enrichment workflows.
- Manufacturers:Industrial producers requiring multi-domain integration between engineering, supply chain, and commercial systems. German automotive suppliers invest here to maintain CE marking documentation under REACH and RoHS substance tracking.
- Distributors:Inventory aggregators synchronizing supplier attribute feeds across downstream customer segments.
- Content Providers:Media and information services managing rights-linked metadata for subscription monetization.
- Service Providers:Telecommunications and utility operators configuring product bundles from network element catalogs.
Manufacturers hold installed capacity. Retail Chains is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States retailers prioritize unified commerce data hubs while German manufacturers invest in compliance-heavy multi-domain architectures. Indian electronics clusters under PLI incentives are building cloud-native catalog infrastructure from greenfield.
United States
Enterprise retail chains are collapsing physical-digital product silos into centralized enrichment workflows. HIPAA and FDA medical device labeling rules elevate accuracy standards for healthcare-adjacent commerce. Greater Boston and Pacific Northwest technology corridors host pilot deployments of generative AI attribute enrichment tools.
Germany
Industrial manufacturers require auditable product lineage under EMA MDR and EU AI Act risk classification frameworks. REACH and RoHS substance tracking mandates CE marking documentation integration into catalog systems. Automotive suppliers in Baden-Württemberg and Bavaria anchor multi-domain deployments linking engineering BOMs to commercial attributes.
India
Electronics manufacturing clusters under PLI scheme incentives are accelerating digital commerce infrastructure buildouts. DGFT export documentation requirements intersect with BIS standards compliance for product attribute validation. Karnataka and Tamil Nadu industrial corridors are deploying hybrid cloud architectures to satisfy data localization without sacrificing channel agility.
France
CNIL enforcement of GDPR consent-linked attribute management complicates customer-facing catalog personalization workflows. ANSM medical device traceability requirements parallel EMA MDR mandates for auditable product histories. Île-de-France retail headquarters are piloting unified commerce strategies that retire channel-specific product silos.
United Kingdom
Post-Brexit regulatory divergence is forcing dual-compliance catalog architectures for exporters serving EU and domestic markets. London-based financial services and retail headquarters are investing in API-first syndication platforms. Midlands manufacturing bases are integrating supplier attribute feeds under pressure from tiered automotive supply chain traceability demands.
Global Catalog Management Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with ERP-native vendors leveraging database depth against cloud-native challengers. SAP SE and Oracle Corporation anchor the upper tier through pre-built connector ecosystems. The specialist tier clusters around open-source flexibility and vertical-specific compliance modules. Competitive moves concentrate on API-first architecture expansion and pre-built regulatory compliance packaging.
Within the integrated tier, SAP SE and Oracle Corporation exemplify ERP-native positioning, while Akeneo SAS occupies a specialist position emphasizing modular growth paths. SAP SE leverages its German industrial manufacturing footprint to anchor multi-domain product data hubs. Oracle Corporation competes through database-native architectures sustaining real-time synchronization. Akeneo SAS represents the open-source flexibility archetype targeting mid-market brands with governance-light deployment options.
| Leading Market Players |
|---|
| IBM Corporation |
| SAP SE |
| Oracle Corporation |
| Salsify Inc. |
| Coupa Software Inc. |
| ServiceNow Inc. |
| Broadcom Inc. |
| Fujitsu Limited |
| Akeneo SAS |
| Others |
Supply & Pricing Matrix
API-first integration architectures are displacing legacy middleware stacks as the primary connectivity layer, simultaneously concentrating vendor development resources in cloud-native hubs and compressing implementation pricing for mid-market adopters seeking modular deployment paths.
Pricing Analysis
Long-term SaaS subscription contracts dominate enterprise procurement, with three-tier pricing structure across premium, standard, and economy levels differentiated by API call volume limits and governance module depth. Price differentiation hinges on vertical compliance certification—FDA-validated healthcare modules and EU AI Act-ready lineage tools command substantial premiums over baseline PIM functionality. Cost compression in standard tiers is intensifying because hyperscaler marketplace listings are commoditizing core syndication capabilities. Mid-market brands in India exhibit highest price sensitivity, while German automotive manufacturers prioritize compliance-grade investments over unit economics.
Supply Chain Analysis
Just-in-time feature delivery through continuous deployment pipelines dominates cloud-native vendor operations, though strategic stockpiling of compliance documentation and pre-validated connector libraries buffers against regulatory submission delays. Development talent concentrates in the United States, Germany, and India, with Indian engineering centers feeding from domestic electronics manufacturing demand under PLI scheme acceleration. Single-source vulnerability exists around specialized data steward expertise for multi-domain taxonomy design. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams serving vertical-specific buyer committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is expanding as unified commerce strategies splinter demand across specialized healthcare compliance, industrial multi-domain integration, and mid-market modular growth paths.
For Market Incumbents: Consolidate API-first architecture investments to preempt cloud-native challengers from capturing mid-market expansion. Acquire specialized DAM capabilities to capture video and 3D asset proliferation before vertical specialists entrench. Defensive positioning requires deepening ERP connector ecosystems around SAP and Oracle environments where switching costs remain highest. For New Entrants and Emerging Players: Anchor in Indian electronics manufacturing clusters where PLI scheme incentives are greenfield-building catalog infrastructure without legacy technical debt. Target healthcare-adjacent commerce segments where FDA and HIPAA accuracy standards create specialized barriers against generalist platforms. Go-to-market through compliance-first messaging emphasizing pre-built audit trail modules. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed vertical specialists possessing pre-validated regulatory modules but lacking horizontal scalability. Five-to-ten year viability favors platforms with durable data governance moats rather than pure syndication utilities. Watch for EU AI Act enforcement thresholds crossing into mandatory risk classification territory as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Module Pre-Validation | FDA and EMA-ready lineage tools capture healthcare manufacturer consolidation demand. |
| API-First Architecture Expansion | Real-time supplier synchronization capabilities penetrate tiered manufacturing networks in Germany. |
| Generative AI Attribute Enrichment | LLM-powered description generation compresses content production cycles for mid-market brands. |
| Hyperscaler Marketplace Listing | AWS and Azure storefront presence reduces customer acquisition friction for cloud-native buyers. |
| Vertical Talent Acquisition | Data steward hiring in Bangalore and Munich accelerates multi-domain implementation capacity. |
Research Methodology
A standing panel of chief data officers, enterprise architects, compliance officers, and integration specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC filings, hyperscaler marketplace disclosures, EU regulatory submission databases, and healthcare GPO contract repositories. Bottom-up sizing of vendor bookings and top-down triangulation against enterprise IT spending benchmarks ensured convergence.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling spanned deployment architecture, solution layer depth, vertical compliance intensity, and regional adoption pattern. CAGRs were derived from fitted growth curves incorporating PLI scheme acceleration timelines and EU AI Act implementation phases as industry-specific inputs.
Decision-makers should treat outputs as directional under sustained cloud migration and regulatory enforcement base assumptions; material deviation would warrant model refresh. Specific risk factors include data steward talent shortages prolonging implementation cycles and sovereignty requirements fragmenting cloud infrastructure choices. Revision becomes warranted when EU AI Act risk classification thresholds trigger mandatory compliance investments across manufacturer segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Configuration Management (CM) Tools Market
Software & Services
Mindfulness Meditation Application Market
Software & Services
User Retention Software Market
Software & Services
Global Club Management Software Market
Software & Services
Enterprise MLC (Emlc) Market
Software & Services
Global Advanced Planning and Scheduling (APS) Software Market
Software & Services
Account Reconciliation Software Market
Software & Services
Global Salesforce Appexchange Tools Market
Software & Services
Global Online Proofing Software Market
Software & Services
North America Servicenow Store Apps Market
Software & Services
Human Capital Management (HCM) Saas Market
Software & Services
Global AI Writing Assistant Software Market
Software & Services
Latin America ERP Software Market
Software & Services
Coaching Management Software Market
Software & Services
Desktop Hypervisor Market
Software & Services
Laser Engraving Software Market