
 Home Automation and Controls Market | 2026-2036
Home Automation and Controls Market Size, Share, and Industry Trends Forecast 2026-2036
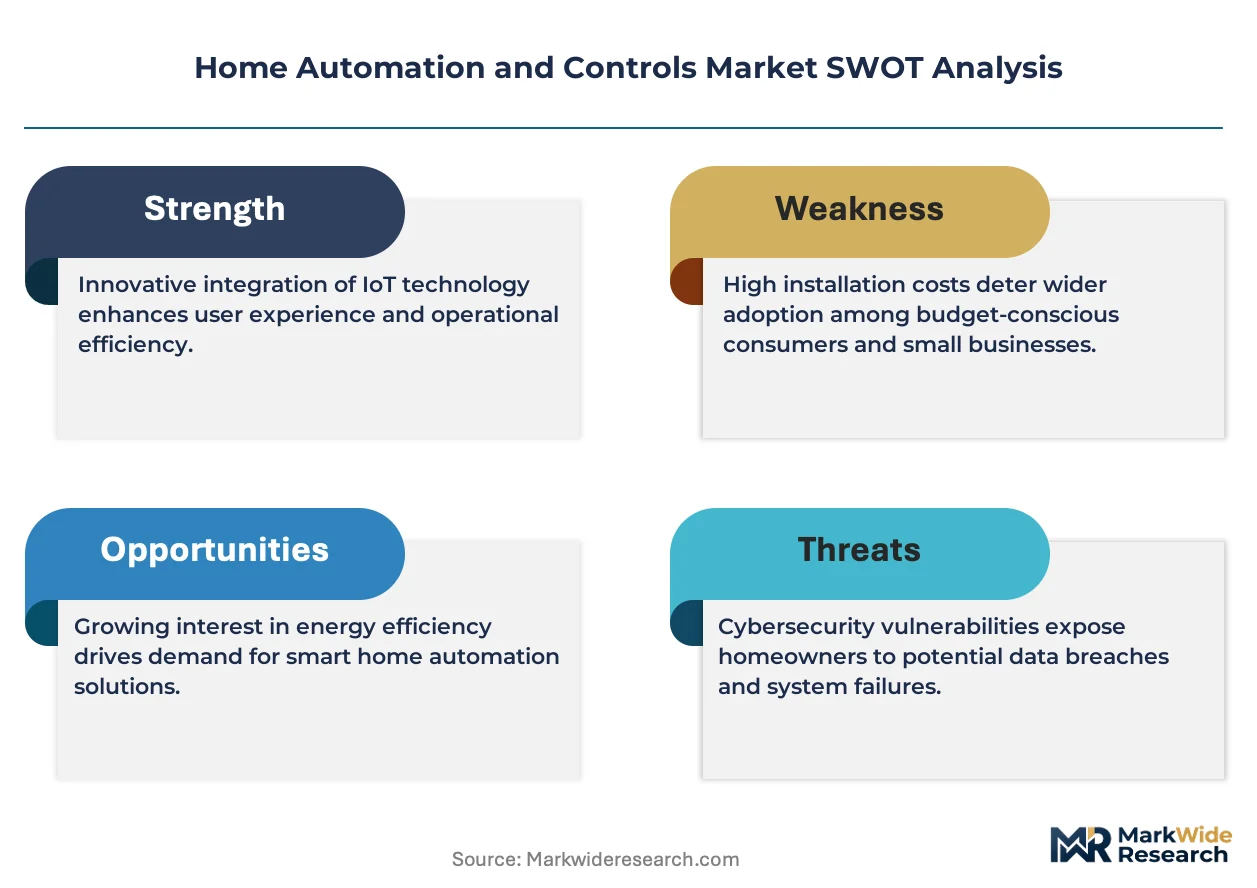
Home Automation and Controls Market Analysis
Luxury homeowners is reorganizing demand within the Home Automation and Controls Market as high-net-worth buyers prioritize integrated wellness and energy management ecosystems over standalone gadgets. Schneider Electric leverages its BMS heritage to dominate commercial-to-residential technology transfer. Samsung Electronics anchors its position through display-integrated smart home hubs that unify entertainment and environmental controls. Honeywell International competes through specialized fire-safety-to-automation convergence in premium properties.
Home automation and controls encompass networked electromechanical systems that regulate lighting, climate, security, and entertainment through centralized or distributed command architectures, typically operating via Z-Wave, Zigbee, or Wi-Fi protocols with latency thresholds below 100 milliseconds for real-time responsiveness. These systems serve residential, commercial, and industrial facilities by reducing energy consumption, enhancing occupant safety, and enabling remote facility oversight. Security Systems commands the largest installed base due to insurance-mandated monitoring requirements, while Cloud-Based technology represents the fastest-expanding architecture as edge-to-cloud orchestration reduces local hardware dependency. Smart Lighting captures concentrated margin pools in the commercial segment where daylight harvesting and circadian programming justify premium pricing.
The EU Green Deal and its building renovation wave mandate smart metering integration, while the US EPA Energy Star certification and FCC Part 15 radio frequency standards shape product compliance pathways for wireless control devices. India's BIS certification requirements for electronic control equipment create incremental market access barriers for imported automation hardware. Stakeholders must monitor how fragmented national cybersecurity standards for IoT devices reshape certification costs and regional competitive dynamics.
Market Dynamics
Residential builders are consolidating procurement around pre-integrated smart infrastructure packages, compressing vendor count per development and elevating systems integrators over component suppliers. This procurement consolidation is redistributing margin pools from hardware manufacturers toward installation and commissioning services.
Growth Catalysts
- EU Green Deal building renovation wave:Mandatory smart metering integration in multi-family housing retrofits across Germany, France, and Italy is accelerating thermostat and lighting control replacements.
- Insurance-mandated security monitoring:Underwriters in the United States and United Kingdom now require connected intrusion detection and environmental sensors for premium property coverage.
- Edge-to-cloud orchestration:Z-Wave Long Range and Thread protocol adoption is reducing gateway hardware dependency while expanding device density per installation.
Market Restraints
- Silicon supply concentration:Microcontroller and RF module production concentrates in Taiwan and South Korea, exposing automation OEMs to geopolitical logistics disruption.
- Cybersecurity certification fragmentation:Divergent national IoT security standards across the European Union, United States, and India inflate compliance testing costs and delay product launches.
- Copper and rare earth price volatility:Electromechanical relay and motor component costs fluctuate with commodity markets, compressing hardware margins.
Strategic Opportunities
- India BIS certification pathway:Domestic manufacturing incentives and import substitution policies create localized production advantages for control hardware serving South Asian markets.
- Wellness-integrated residential ecosystems:Circadian lighting and air quality management convergence addresses high-net-worth buyer priorities in luxury housing developments.
- Utility demand-response programs:Time-of-use electricity pricing mandates in California and Texas incentivize smart thermostat and load control adoption.
Industry Challenges
- Systems integration skill scarcity:Shortage of certified installers capable of commissioning multi-protocol networks across Z-Wave, Zigbee, and Thread environments.
- Legacy HVAC interoperability:Proprietary building management system protocols in commercial retrofits resist standardized API integration.
- Product liability exposure:Fire-safety system convergence with automation platforms expands manufacturer responsibility for false alarm and failure incidents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Automation and Controls Market |
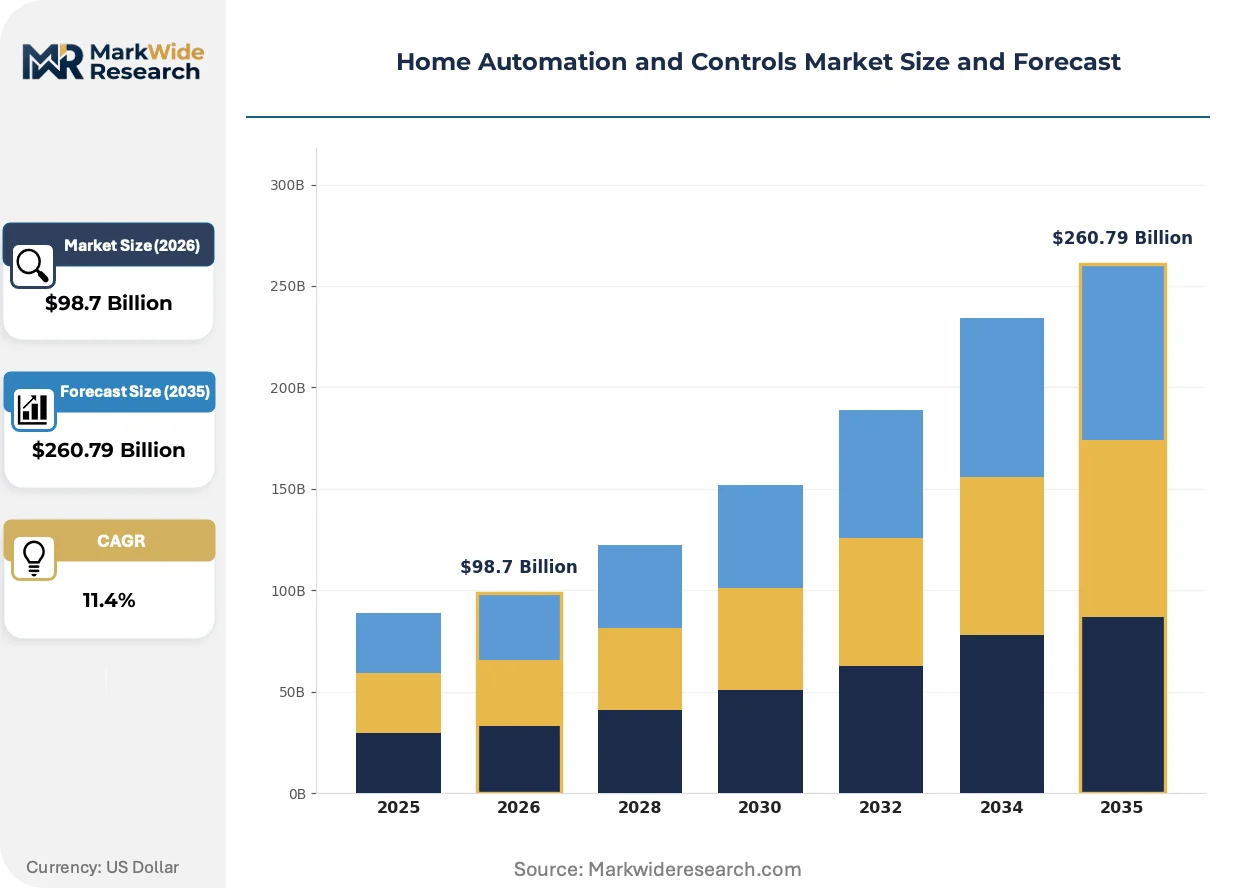
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $260.79 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, Security Systems, Thermostats, Entertainment Systems Technology: Wireless, Wired, IoT, Cloud-Based Application: Residential, Commercial, Industrial, Hospitality End User: Homeowners, Builders, Property Managers, Developers |
| Companies Covered | Siemens AG, Honeywell International, Johnson Controls International, Schneider Electric, Samsung Electronics, ABB Group, Legrand Group, Amazon, Google Nest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Automation and Controls Market Emerging Trajectories
Protocol convergence and sensor fusion are collapsing the traditional boundaries between environmental control, security, and entertainment systems. Vendors now compete on ecosystem coherence rather than standalone device performance.
Matter-over-Thread connectivity hardware is miniaturizing to single-chip implementations that embed directly into light switches and outlet receptacles. Residential builders in Scandinavia and the Netherlands are specifying these invisible control nodes in new construction at accelerating rates. Component miniaturization is eliminating visible wall-mounted control panels and shifting user interaction entirely to mobile applications and voice interfaces.
The EU AI Act's risk classification framework is imposing documentation and conformity assessment burdens on automation systems with biometric or predictive energy optimization capabilities. Manufacturers must now maintain algorithmic transparency records and human oversight protocols for smart security cameras and occupancy-predicting climate controls. German and French certification bodies are expanding testing scope to cover machine learning model drift and data governance compliance.
Subscription monetization is displacing perpetual licensing for cloud-connected automation platforms. Homeowners in the United States and Australia increasingly accept recurring fees for remote access, energy analytics, and predictive maintenance alerts. This shift compresses upfront hardware affordability while extending customer lifetime value for platform operators.
Home Automation and Controls Market Segmentation
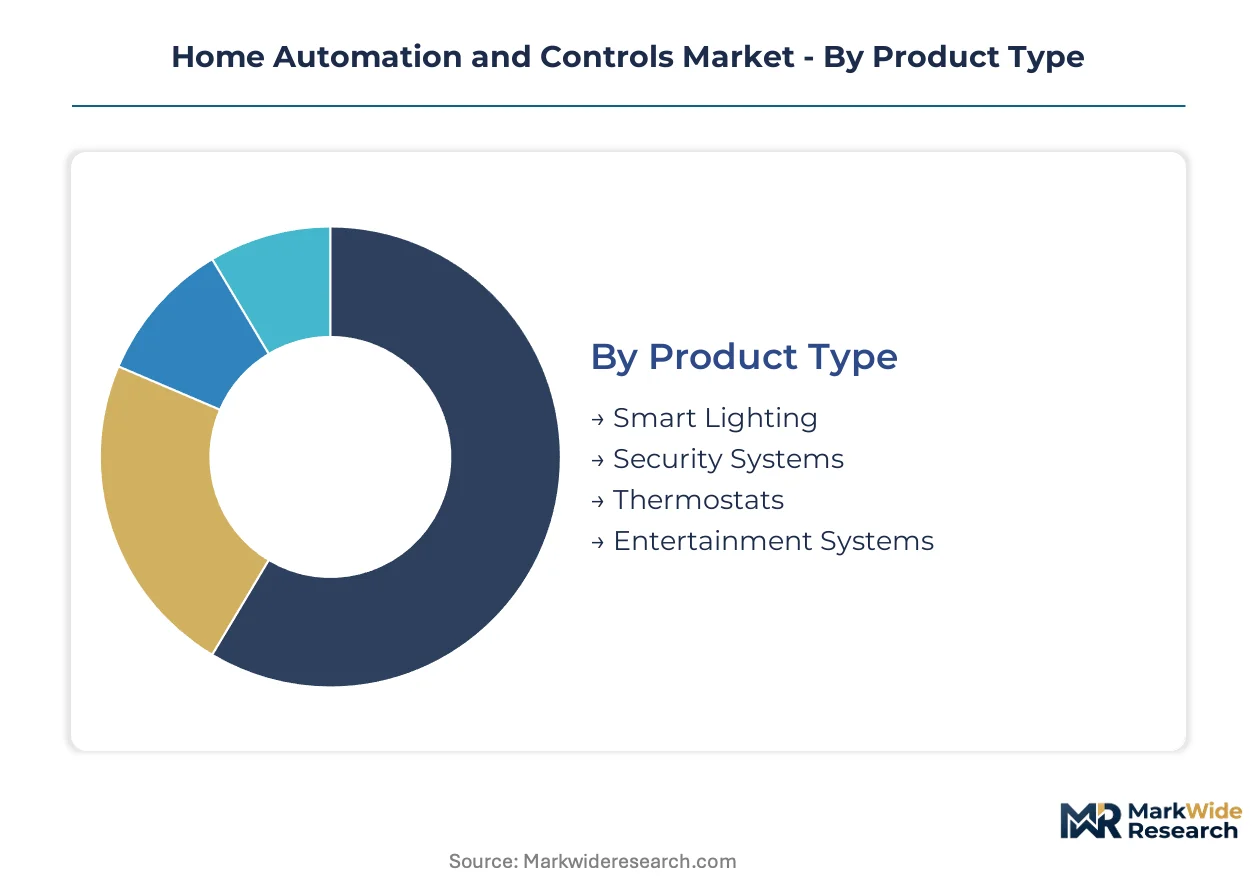
Home automation and controls segment along four intersecting dimensions that reshape procurement patterns and margin capture. Product type determines hardware-versus-service revenue splits. Technology choices dictate installation complexity and recurring revenue potential. Application and end-user categories reveal divergent price sensitivity and integration requirements across built environments.
Product Type:
Geographic demand concentration varies sharply across product categories, with security systems and thermostats driven by regulatory mandates in Europe and insurance requirements in North America, while entertainment systems follow discretionary spending patterns in high-income households.
- Smart Lighting:LED drivers with embedded Z-Wave or Thread radios enable daylight harvesting and circadian programming. Demand clusters in German and Dutch commercial retrofits where EU Green Deal efficiency mandates justify premium fixture upgrades.
- Security Systems:Networked intrusion detection, environmental sensors, and video analytics platforms operating through centralized monitoring stations. UK and US underwriters now mandate connected sensors for premium property coverage, accelerating replacement cycles in detached single-family housing.
- Thermostats:Programmable and learning climate controllers with occupancy sensing and utility API integration. California and Texas time-of-use pricing structures incentivize adoption among cost-conscious homeowners.
- Entertainment Systems:Multi-room audio, display-integrated control hubs, and unified media distribution architectures. Luxury housing developments in Scandinavia and the Netherlands specify invisible infrastructure over visible wall panels.
Security Systems commands the established base. The steepest expansion runs through Smart Lighting.
Technology:
Cost tier stratification separates enterprise-grade wired installations from mass-market wireless deployments, with cloud connectivity now table stakes for mid-tier and above.
- Wireless:Mesh networks using Z-Wave, Zigbee, or Wi-Fi protocols with sub-100 millisecond latency thresholds. Residential builders in North America and Europe consolidate procurement around pre-certified wireless packages to reduce commissioning complexity.
- Wired:Dedicated low-voltage cabling for power and data transmission, predominant in commercial new construction and luxury residential where reliability overrides installation cost. German multi-family housing renovation specifications favor wired backbones for fire safety integration.
- IoT:Sensor-equipped devices with edge processing capabilities and cloud telemetry. India's BIS certification requirements for electronic control equipment create compliance barriers for imported IoT hardware.
- Cloud-Based:Edge-to-cloud orchestration architectures reducing local gateway dependency. US and Australian homeowners increasingly accept subscription fees for remote access and predictive maintenance alerts.
Wired infrastructure retains share in commercial construction. Cloud-Based architectures gain share fastest in residential retrofits.
Application:
Volume concentration tilts toward residential, but margin pools concentrate in commercial where integration complexity and service contracts extend customer lifetime value.
- Residential:Single-family and multi-family housing with centralized or distributed control architectures. EU Green Deal renovation wave accelerates thermostat and lighting replacements across German, French, and Italian multi-family stock.
- Commercial:Office buildings, retail, and institutional facilities requiring BMS integration and energy management dashboards. Schneider Electric leverages building management heritage to transfer technology from commercial to residential segments.
- Industrial:Manufacturing and warehouse facilities with environmental monitoring and access control tied to operational technology networks. Cybersecurity certification fragmentation across EU, US, and Indian standards complicates cross-border equipment deployment.
- Hospitality:Hotels and serviced residences with guest room management systems and centralized facility oversight. High-net-worth buyer priorities for wellness-integrated ecosystems drive premium specification in luxury properties.
Residential absorbs the highest unit volumes. Commercial delivers the strongest margin expansion trajectory.
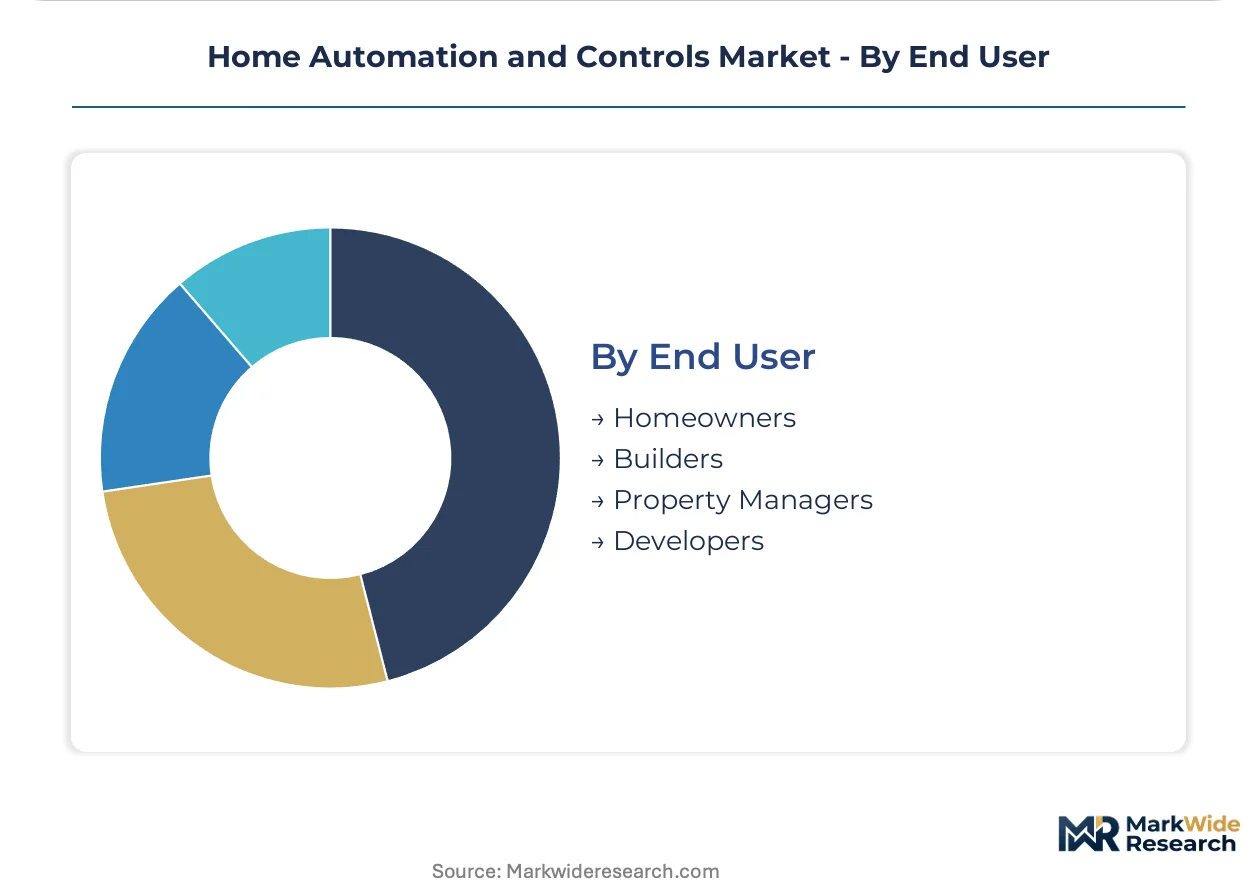
End User:
Customer type determines procurement channel and pricing power, with builders consolidating vendor counts while homeowners prioritize ecosystem coherence over component performance.
- Homeowners:Individual purchasers selecting devices through retail, direct-to-consumer, or installer channels. Voice interface and mobile application control expectations eliminate demand for visible wall-mounted panels.
- Builders:Residential construction firms specifying pre-integrated smart infrastructure packages for new developments. Procurement consolidation redistributes margin pools from hardware manufacturers toward installation and commissioning services.
- Property Managers:Multi-family and commercial portfolio operators requiring remote oversight and tenant-facing control interfaces. Utility demand-response program participation incentivizes smart thermostat deployment.
- Developers:Large-scale housing and mixed-use project sponsors negotiating volume procurement agreements. Scandinavian and Netherlands developers accelerate specification of Matter-over-Thread invisible control nodes.
Builders drive the highest aggregate contract values. Property Managers represent the fastest-expanding service revenue opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Luxury homeowners and property developers in Germany, the United States, and the Netherlands currently drive the highest contract values for integrated automation ecosystems. Builder procurement consolidation across these markets favors systems integrators capable of delivering pre-certified wireless packages.
Germany
Multi-family housing renovation and EU Green Deal efficiency mandates accelerate thermostat and lighting control replacements. The country's building codes under the national implementation of the EU Green Deal require smart metering integration in retrofitted stock. Demand clusters in North Rhine-Westphalia where housing associations specify wired backbones for fire safety integration.
United States
Insurance-mandated security monitoring and utility demand-response programs in California and Texas expand connected sensor deployment. The FCC Part 15 radio frequency standards shape wireless control device compliance pathways. Silicon Valley and Austin metro areas concentrate developer activity around Matter-over-Thread specification.
Netherlands
Residential builders specify invisible control nodes with embedded radios eliminating visible wall panels. The EU AI Act's risk classification framework imposes documentation burdens on predictive energy optimization systems. Amsterdam and Rotterdam housing developments lead specification of display-integrated smart home hubs.
India
Domestic manufacturing incentives and import substitution policies create localized production advantages for control hardware. The BIS certification requirements for electronic control equipment create compliance barriers for imported automation hardware. Demand concentrates in Maharashtra and Karnataka where property managers deploy smart thermostats for utility program participation.
United Kingdom
Underwriters now mandate connected intrusion detection for premium property coverage accelerating replacement cycles. The country's national cybersecurity standards for IoT devices reshape certification costs for imported hardware. London and Southeast England luxury developments prioritize wellness-integrated ecosystems with circadian lighting.
Home Automation and Controls Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with building management heritage alongside consumer electronics specialists and cloud platform operators. Siemens AG, Schneider Electric, and Honeywell International anchor the industrial tier with commercial-to-residential technology transfer capabilities. Samsung Electronics and Amazon occupy the consumer-facing tier with display-integrated and voice-first control architectures. Johnson Controls International and ABB Group represent the building systems integration specialists. Competitive dynamics center on ecosystem coherence through protocol convergence and subscription monetization displacing perpetual licensing.
Within the industrial conglomerate tier, Siemens AG, Schneider Electric, and Honeywell International exemplify archetypes leveraging commercial building management heritage for residential market entry. These European and US-based entities occupy positions where fire-safety-to-automation convergence and BMS technology transfer create differentiation. Samsung Electronics anchors the consumer electronics vector with smart home hub integration, while Amazon and Google Nest represent cloud-native platform operators competing on voice interface and mobile application control. The competitive landscape rewards vendors capable of collapsing boundaries between environmental control, security, and entertainment systems.
| Leading Market Players |
|---|
| Siemens AG |
| Honeywell International |
| Johnson Controls International |
| Schneider Electric |
| Samsung Electronics |
| ABB Group |
| Legrand Group |
| Amazon |
| Google Nest |
| Others |
Supply Flow & Price Mechanics
EU Green Deal certification requirements gate both supplier qualification and price differentiation simultaneously, as BSI Kitemark and CE marking tiers separate premium integrators from commodity hardware vendors while mandating traceable supply chains for smart metering components.
Pricing Analysis
Cost-plus contracts with copper and rare earth indexation dominate thermostat and lighting control procurement, linking hardware margins to London Metal Exchange pricing. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth and after-sales service bundling. Pricing pressure stems from silicon supply concentration in Taiwan and South Korea, compressing margins for gateway manufacturers. Property managers exhibit highest price sensitivity due to volume procurement mandates, while luxury developers prioritize ecosystem coherence over unit cost.
Supply Chain Analysis
Taiwan Strait transit risk underwrites microcontroller and RF module security, as 70% of Z-Wave and Zigbee silicon fabrication concentrates in Hsinchu Science Park and Seoul metropolitan area facilities. Electromechanical relays draw from Chinese and German motor component suppliers, while copper wiring feeds from Chilean and Indonesian smelters. Single-source vulnerability in 40nm process node production exposes automation OEMs to geopolitical logistics disruption. Distribution runs through systems integrators and certified installer networks rather than direct-to-builder channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home automation sits in early-cycle expansion as EU Green Deal renovation mandates penetrate multi-family housing stock, with smart metering integration still below saturation across German, French, and Italian retrofits.
For Market Incumbents: Consolidate around Matter-over-Thread protocol convergence to defend against cloud-native platform entrants, while deepening backward integration into edge processor design to offset Taiwan silicon concentration risk. Prioritize BIS certification investment for India manufacturing localization. For New Entrants and Emerging Players: Differentiate on wellness-integrated ecosystem orchestration targeting Scandinavian and Netherlands luxury developers specifying invisible control nodes. White-space opportunity concentrates in commercial-to-residential technology transfer for mid-market property managers. Go-to-market through utility demand-response program partnerships in California and Texas. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed systems integration specialists holding German multi-family housing renovation contracts. Five-to-ten year viability hinges on subscription monetization displacement of perpetual licensing. Signal to watch is Thread protocol adoption velocity in new construction specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Protocol Convergence Investment | Matter-over-Thread adoption collapses gateway hardware dependency and expands device density per installation. |
| Certification Pathway Expansion | BIS and EU AI Act compliance investments unlock India manufacturing incentives and European predictive energy optimization markets. |
| Subscription Platform Migration | Recurring revenue models displace perpetual licensing among US and Australian homeowners accepting remote access fees. |
| Wellness Ecosystem Integration | Circadian lighting and air quality convergence addresses high-net-worth buyer priorities in London and Amsterdam luxury developments. |
| Installer Network Acquisition | Systems integration skill scarcity elevates certified commissioning capabilities above component manufacturing margins. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured interviews with residential builders, property managers, systems integrators, and smart lighting procurement leads at housing associations. Secondary validation drew from FCC Part 15 filings, EU ETSI standards documentation, BIS certification registries, and utility demand-response program disclosures. Bottom-up device shipment analysis triangulated against top-down construction spending data across the analysis window.
Across the modeling period, forecasts segmented by product type, technology architecture, application vertical, and end-user procurement channel. CAGRs derived from installed base growth rates and replacement cycle compression in security and thermostat categories. Input assumptions incorporated EU Green Deal implementation timelines, Thread protocol adoption curves, and copper price volatility bands.
Material uncertainties — cybersecurity certification fragmentation, Taiwan semiconductor logistics disruption, and EU AI Act enforcement variance — sit outside the modeled envelope. Forecasts reflect stated policy implementation and technology substitution assumptions. Practitioners should keep alternative scenarios live as national IoT security standards and rare earth supply arrangements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Universal Process Control Market
Automation
Middle East and Africa Workforce Management Market
Automation
Network Automation Market
Automation
Global Process Automation and Instrumentation Market
Automation
Italy Marketing Automation Market
Automation
Lab Automation Market
Automation
Global Water Automation and Instrumentation Market
Automation
Parcel Sorting System Market
Automation
Global Database Automation Systems Market
Automation
Voice Picking Solutions Market
Automation
Task-Level Labor Planning and Workforce Orchestration for Fulfillment Market
Automation
Home Automation System Market
Automation
Global Door and Window Automation Market
Automation
Global Direct Mail Automation Software Market
Automation
North America Home Automation Systems Market
Automation
Global Field Force Automation Market