
 Automatic Message Handling System Market | 2026-2036
Automatic Message Handling System Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Message Handling System Market Outlook
Defense sector procurement is realigning toward interoperable secure messaging architectures. Frequentis leverages its established presence in air traffic management to extend into military message handling systems. Rohde & Schwarz sustains technology leadership through specialized encryption capabilities for classified communications. Thales Group anchors its competitive position with deep integration across NATO command infrastructure.
An automatic message handling system constitutes a software platform that routes, processes, and secures structured digital communications through protocol standardization engines with built-in cryptographic validation. The system serves defense, government, and critical infrastructure operators requiring assured message delivery with non-repudiation and audit trails. Cloud-based deployments are capturing accelerated investment as agencies prioritize elastic scalability over fixed on-premise capacity, while hybrid architectures retain stronghold status among organizations with strict data residency requirements. Message encryption functionality commands premium positioning as sovereign encryption mandates proliferate across European defense procurement.
EU cybersecurity certification schemes under ENISA and NATO STANAG standards shape product compliance requirements for cross-border military interoperability. Germany's BSI and France's ANSSI enforce national cryptographic profiles that vendors must satisfy for domestic defense contracts. Stakeholders must monitor evolving quantum-resistant encryption standards and their integration timelines into existing fielded systems.
Market Dynamics
Defense communications modernization across NATO member states is accelerating procurement of secure message handling infrastructure, while cloud migration mandates from the European Union's cybersecurity certification frameworks are reshaping deployment preferences toward elastic, sovereign-compliant architectures.
Growth Catalysts
- NATO STANAG Standards:Interoperability mandates for allied military communications are forcing upgrades to unified message handling protocols. Defense ministries across member states must replace legacy point-to-point systems with certified platforms.
- EU Cybersecurity Certification:ENISA frameworks for cloud and encryption services are creating compliance-driven demand cycles. Agencies require certified vendors for cross-border data sharing arrangements.
- Quantum-Resistant Cryptography:Post-quantum algorithm standardization by NIST is triggering early replacement cycles. Fielded systems require hardware and software refreshes to maintain long-term security assurance.
Market Restraints
- Specialized Hardware Costs:Tamper-resistant cryptographic modules and certified secure enclaves carry substantial procurement premiums. Budget constraints delay full-fleet modernization programs.
- Supplier Concentration:Qualified vendors for NATO-grade encryption number fewer than ten globally. Single-source dependencies create vulnerability in supply assurance for critical defense programs.
- Legacy Protocol Entrenchment:Decades-old message formats and proprietary interfaces resist standardization. Migration complexity extends deployment timelines and inflates integration costs.
Strategic Opportunities
- Hybrid Cloud Architectures:Split-processing models allowing classified data to remain on-premise while leveraging commercial cloud for unclassified traffic are opening new deployment categories. German federal data sovereignty requirements favor this approach.
- Critical Infrastructure Expansion:Energy grid operators and financial clearing systems are adopting military-grade message assurance. France's ANSSI certification pathways enable commercial sector entry.
- AI-Augmented Threat Detection:Machine learning integration with message handling platforms enables real-time anomaly identification. Convergence of encryption and behavioral analytics creates differentiated product tiers.
Industry Challenges
- Cryptographic Engineering Talent:Shortages of cleared personnel with expertise in both classical and post-quantum algorithms constrain development velocity. Security clearance timelines extend hiring cycles beyond eighteen months.
- Cross-Domain Integration:Message handling systems must interface with satellite, terrestrial radio, and IP networks simultaneously. Multi-protocol synchronization introduces latency and failure modes that degrade operational reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Message Handling System Market |
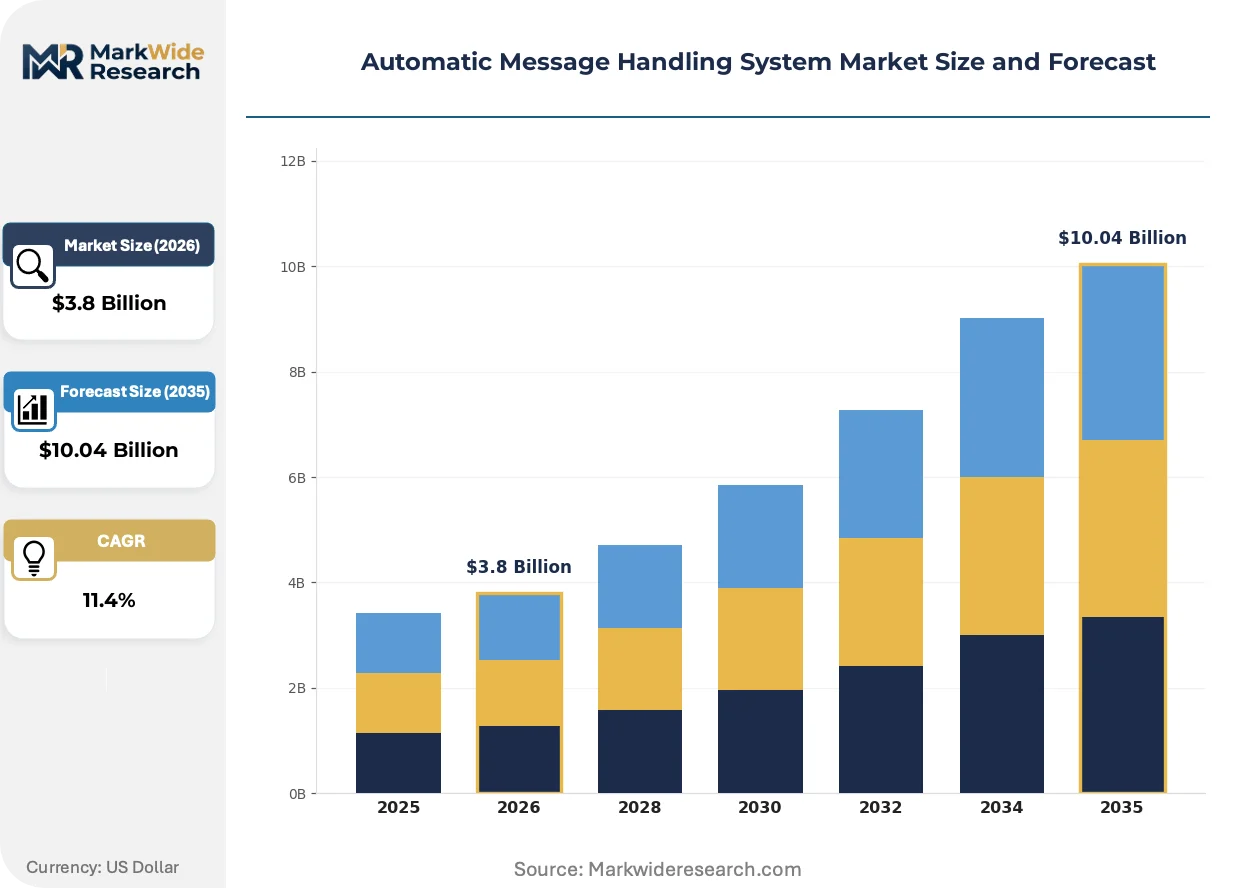
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Open Source End User: Government, Enterprises, Educational Institutions, Non-Profits Deployment Model: Public Cloud, Private Cloud, Community Cloud, Multi-Cloud Functionality: Automated Response, Message Encryption, Integration with CRM, Analytics |
| Companies Covered | Frequentis, EID, Rohde & Schwarz, ELTA-R, Skysoft Servicios SA, Indra, Nexor, Leonardo Turkey, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Message Handling System Market Strategic Shifts
Software-defined cryptographic engines are displacing hardware-dependent implementations, enabling faster algorithm updates without physical replacement. This architectural shift is compressing product lifecycles and reshaping vendor competitive advantages.
Quantum-resistant encryption is rewriting security planning horizons for defense procurement offices. NIST's finalized post-quantum standards are triggering immediate pilot programs among early-adopter agencies. The technology is compressing traditional ten-year capital planning cycles into three-year refresh windows as quantum threat timelines accelerate.
EU AI Act classification rules for high-risk autonomous systems are extending compliance obligations to message handling platforms with embedded decision-support features. Vendors must document algorithmic transparency and human oversight mechanisms. French and German defense procurement offices are requiring AI Act conformity assessments alongside existing NATO certifications.
Consolidated platform procurement is displacing best-of-breed point solutions across defense ministries. Buyers favor integrated suites combining message handling, voice, and video over standalone systems requiring custom integration. Germany's military digitalization programs exemplify this preference, bundling messaging infrastructure with broader command-and-control modernization contracts.
Automatic Message Handling System Market Segmentation
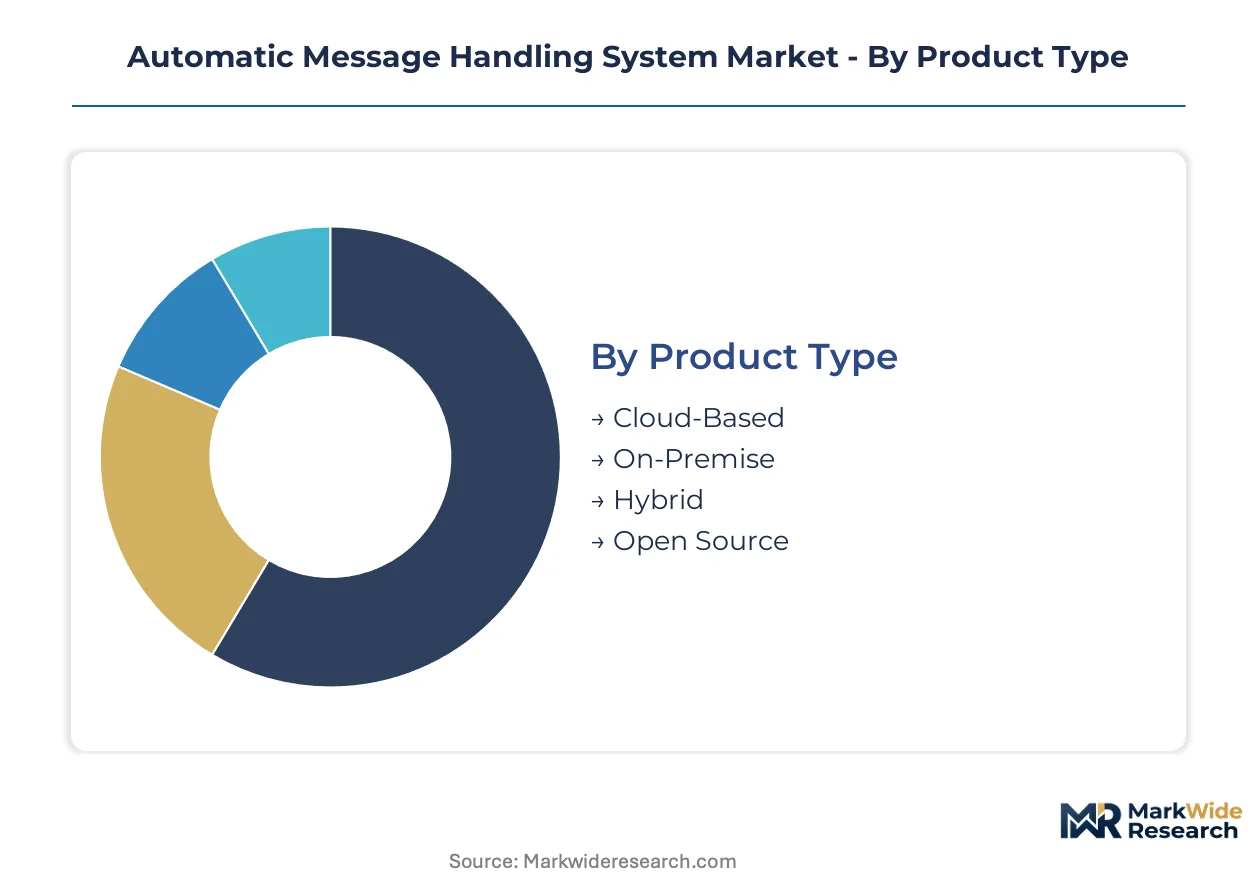
Automatic message handling systems fragment across deployment architectures, user security profiles, and functional capabilities. Each segment carries distinct certification burdens from NATO STANAG, ENISA cloud frameworks, or national cryptographic authorities. Procurement officers weight these compliance requirements against operational flexibility when selecting platform configurations.
Product Type:
ENISA cloud certification and NATO STANAG 4406 compliance create divergent approval pathways across deployment modes. German BSI and French ANSSI impose additional national cryptographic validations on certain architectures.
- Cloud-Based:Elastic infrastructure enables rapid scaling for fluctuating message volumes without capital-intensive hardware procurement. German federal agencies favor this model for unclassified traffic under strict data residency controls mandated by the country's national cybersecurity authority. Demand concentrates in defense ministries pursuing hybrid modernization strategies.
- On-Premise:Fixed-capacity installations maintain complete physical custody of cryptographic materials and message archives. NATO classified networks require air-gapped deployments with tamper-evident hardware security modules. France's defense procurement office specifies on-premise mandatory for secret-level communications.
- Hybrid:Split-processing architectures route classified traffic through sovereign infrastructure while leveraging commercial cloud for routine correspondence. German data sovereignty requirements favor this approach for federal police and border control applications.
- Open Source:Community-developed codebases require independent security audits before military adoption. Limited deployment in academic research environments and non-classified government pilot programs.
On-Premise sits at the top of the volume ranking, with Hybrid climbing the fastest.
End User:
Security clearance requirements and budget authorization levels shape procurement patterns across institutional categories. Each user type presents distinct integration complexity with existing command infrastructure.
- Government:Defense ministries and intelligence services demand NATO-interoperable protocols with quantum-resistant algorithm readiness. German military digitalization programs anchor regional demand with bundled command-and-control contracts.
- Enterprises:Critical infrastructure operators in energy and finance sectors adopt military-grade assurance for transaction clearing and grid management. French ANSSI certification pathways enable commercial sector entry.
- Educational Institutions:Research universities with defense partnerships require controlled unclassified information handling. Limited procurement volumes concentrated in technical universities with NATO collaborative agreements.
- Non-Profits:Humanitarian organizations operating in conflict zones need assured communications without classified infrastructure overhead. NGO demand remains minimal due to cost barriers.
Government captures dominant procurement volume, while Enterprises expand most quickly through critical infrastructure mandates.
Deployment Model:
Infrastructure ownership and multi-tenancy isolation determine which ENISA assurance levels apply. Sovereign cloud requirements from Germany and France restrict certain models for sensitive workloads.
- Public Cloud:Shared infrastructure delivers cost efficiency for high-volume, low-classification message streams. EU cybersecurity certification schemes limit public cloud to unclassified government communications.
- Private Cloud:Single-tenant environments satisfy data residency requirements for defense and federal police applications. German BSI Common Criteria evaluations apply to national deployments.
- Community Cloud:Restricted multi-tenant platforms serve specific NATO mission networks or EU agency consortiums. Cross-border data sharing arrangements require harmonized certification across member states.
- Multi-Cloud:Distributed architectures mitigate vendor concentration risk while complicating unified security policy enforcement. Complexity premiums constrain adoption to large defense integrators with dedicated cloud engineering teams.
Private Cloud holds the largest installed base, with Multi-Cloud gaining share fastest among alliance-scale modernization programs.
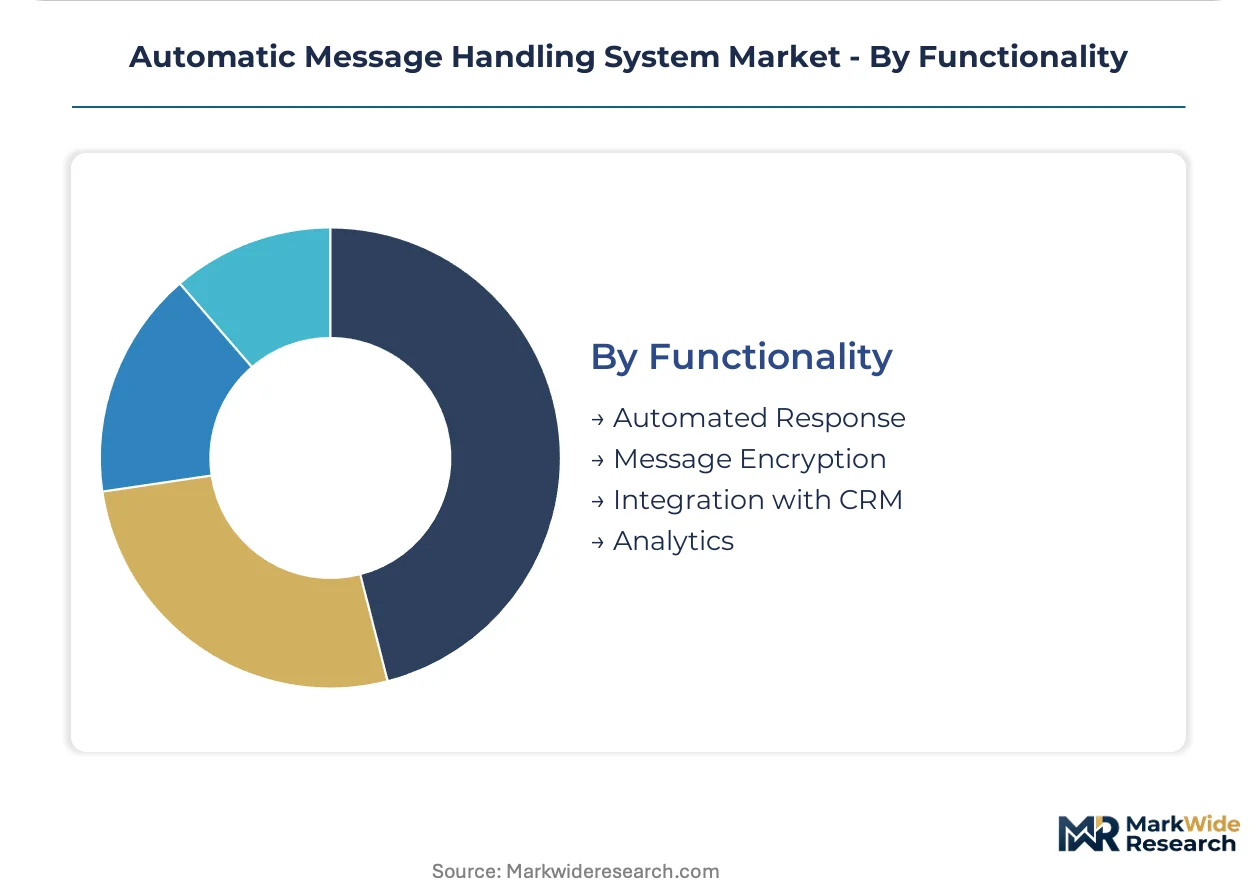
Functionality:
Feature depth directly correlates with certification scope and integration engineering requirements. Core message routing requires baseline NATO approval, while AI-augmented capabilities trigger additional EU AI Act conformity assessments.
- Automated Response:Rules-based and machine-learning systems for message triage and preliminary reply generation. EU AI Act high-risk system classifications extend compliance obligations to platforms with embedded decision-support features.
- Message Encryption:Classical and post-quantum cryptographic implementations with non-repudiation and audit trail capabilities. NIST algorithm standardization drives replacement cycles across NATO member states.
- Integration with CRM:Bi-directional data synchronization with customer relationship and case management platforms. Civilian government applications in consular services and citizen correspondence drive demand.
- Analytics:Behavioral pattern recognition and operational intelligence extraction from message metadata. Convergence with threat detection systems creates premium product tiers for signals intelligence applications.
Message Encryption commands the highest procurement priority, with Analytics showing steepest expansion trajectory as AI integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping procurement geography as defense ministries migrate toward jurisdictions with harmonized NATO certification and streamlined ENISA approval pathways. Compliance-cost differentials between national cryptographic authorities concentrate platform development in countries with established security-clearance infrastructure.
Germany
Bundeswehr digitalization programs and federal police modernization anchor regional demand for hybrid deployment architectures. BSI Common Criteria evaluations and data sovereignty mandates under the German IT Security Act shape vendor selection for classified networks. Munich and Berlin host concentrated defense integrator clusters where Thales and Rohde & Schwarz maintain established engineering presence.
France
Direction Générale de l'Armement procurement bundles message handling with broader command-and-control upgrades across naval and air force platforms. ANSSI national cryptographic profiles and EU AI Act conformity assessments for embedded decision-support features extend compliance obligations. The Paris-Saclay defense technology corridor concentrates systems integration expertise for NATO-interoperable deployments.
United Kingdom
Strategic Command's integrated operating concept drives replacement of legacy point-to-point military messaging with unified secure platforms. National Cyber Security Centre guidance on quantum-resistant algorithm migration accelerates refresh cycles for fielded systems. Bristol and London house specialized cryptographic engineering clusters serving UK and allied NATO requirements.
United States
Department of Defense zero-trust architecture mandates and NSA Commercial Solutions for Classified program reshape procurement toward certified commercial platforms. NIST post-quantum cryptography standardization triggers early replacement of hardware-dependent encryption modules. Northern Virginia and Maryland corridors concentrate cleared defense contractors with active NATO supply relationships.
Italy
Aeronautica Militare and Marina Militare modernization programs generate demand for interoperable message handling within southern NATO flank operations. National military certification authority requirements align with STANAG 4406 protocols for allied exercise participation. Rome and Turin defense electronics clusters support integration with Leonardo's broader command infrastructure portfolio.
Automatic Message Handling System Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with defense-prime integrators commanding classified procurement while niche cryptographic vendors capture subsystem contracts. The vendor base concentrates among fewer than ten NATO-qualified encryption suppliers, creating tiered access based on security clearance depth and national certification breadth. Two strategic archetypes dominate: full-platform integrators bundling message handling with broader command infrastructure, and encryption specialists supplying cryptographic engines to multiple prime contractors. M&A activity targets quantum-resistant algorithm capabilities, while strategic partnerships bridge gaps between cloud infrastructure providers and sovereign-compliant deployment expertise.
Among European defense electronics conglomerates, Thales Group and Leonardo occupy positions exemplifying full-platform integration archetypes, with geographic naming conventions indicating French and Italian origins respectively. Rohde & Schwarz represents the specialized encryption tier, its compound surname structure suggesting German corporate heritage and family-controlled governance. These three entities anchor competitive positioning across NATO procurement corridors where national industrial preferences intersect with interoperability mandates.
| Leading Market Players |
|---|
| Frequentis |
| EID |
| Rohde & Schwarz |
| ELTA-R |
| Skysoft Servicios SA |
| Indra |
| Nexor |
| Leonardo Turkey |
| Thales Group |
| Others |
Value Chain & Pricing Dynamics
NATO STANAG 4406 compliance mandates and quantum-resistant cryptography refresh cycles are forcing defense procurement offices toward certified platform bundles, compressing vendor margins and concentrating supply relationships among cleared integrators with established cryptographic module sourcing.
Pricing Analysis
Distributor margins for NATO-qualified message handling platforms typically range from 12% to 18% depending on classification tier and integration complexity. Three-tier pricing structure across strategic, operational, and tactical levels reflects certification depth rather than feature differentiation alone. Cost compression in tactical-grade deployments is intensifying because German BSI and French ANSSI are harmonizing evaluation standards, reducing vendor differentiation leverage. Government defense ministries exhibit lowest price sensitivity due to sovereign encryption mandates, while critical infrastructure operators in energy and finance sectors demonstrate highest sensitivity as they benchmark against commercial-grade alternatives.
Supply Chain Analysis
Tamper-resistant hardware security module supply rests on specialized semiconductor fabrication concentrated in Germany, the United States, and Taiwan. Field-programmable gate arrays for cryptographic acceleration, secure enclave processors, and radiation-hardened memory components constitute critical input dependencies. Single-source vulnerability pervades qualified foundry capacity for Common Criteria EAL4+ certified silicon. Distribution runs through defense prime integrators with active NATO supply agreements, bypassing commercial IT channels entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
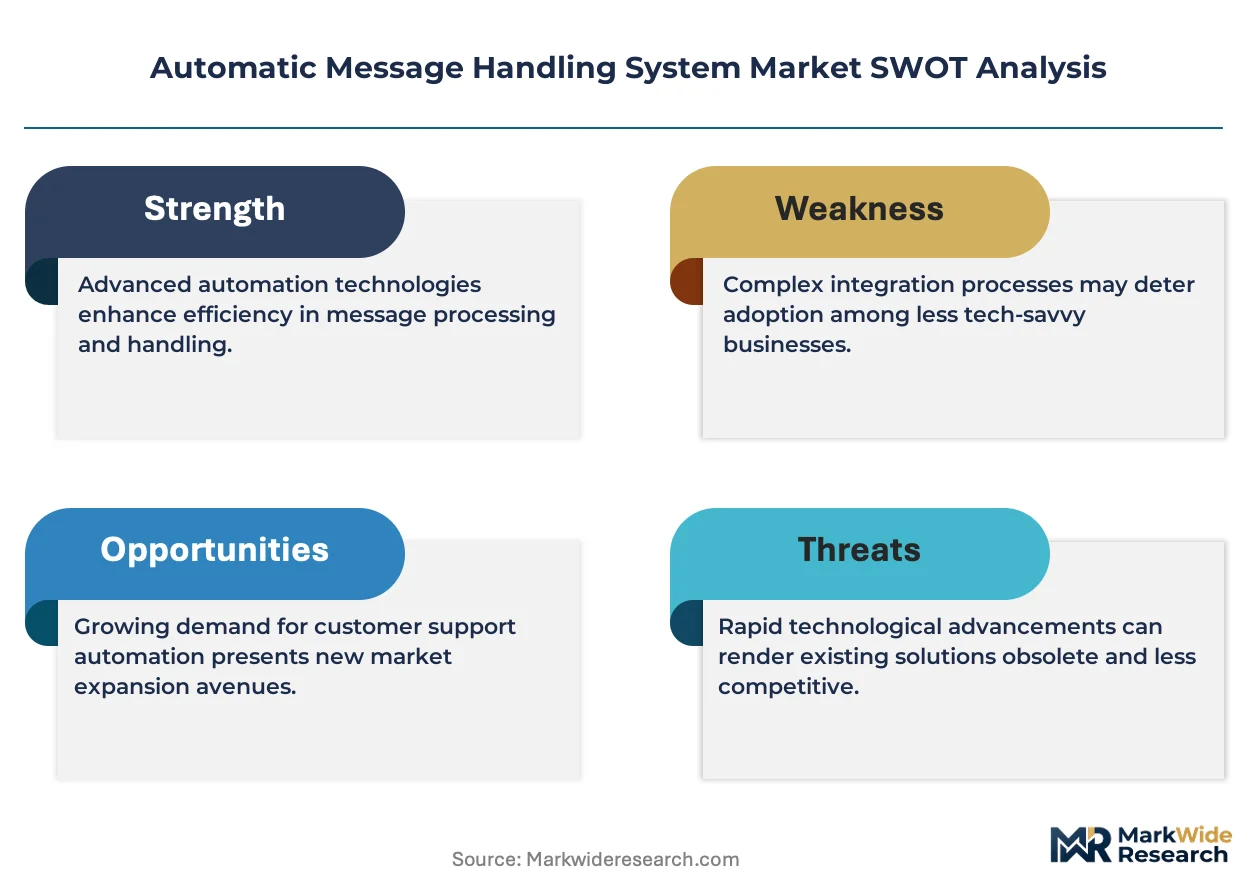
This market operates as a regulatory compounder where EU AI Act classification rules for high-risk autonomous systems are extending compliance obligations to message handling platforms with embedded decision-support features, creating sustained demand for certified vendors.
For Market Incumbents: Anchor competitive position through backward integration into post-quantum cryptographic algorithm development, securing NIST-standardized implementations before field refresh cycles accelerate. Acquire specialized talent pools in cleared cryptographic engineering to offset eighteen-month security clearance hiring timelines that constrain development velocity. Counter emerging cloud-native entrants by bundling message handling with broader command-and-control infrastructure contracts.
For New Entrants and Emerging Players: Begin with critical infrastructure applications in energy grid and financial clearing sectors where French ANSSI certification pathways enable commercial sector entry without NATO security clearance barriers. Target hybrid cloud deployment architectures for German federal police and border control applications, where data sovereignty requirements favor split-processing models. Pursue strategic partnerships with established defense primes to access NATO STANAG certification pathways.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized encryption subsystem vendors possessing quantum-resistant algorithm portfolios and active NIST pilot program participation. Long-term viability hinges on sustained defense modernization budgets across NATO member states and successful navigation of EU AI Act conformity assessment requirements. Monitor NIST post-quantum standardization finalization as the critical inflection signal triggering accelerated replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptography Integration | NIST algorithm standardization drives hardware and software refresh cycles across NATO member states. |
| Hybrid Cloud Architecture Development | German BSI data sovereignty requirements favor split-processing models for federal applications. |
| AI-Augmented Threat Detection Platform | EU AI Act conformity assessments extend compliance obligations to decision-support features. |
| Critical Infrastructure Market Entry | French ANSSI certification pathways enable commercial sector adoption without classified clearance. |
| Strategic Partnership with Cloud Providers | Sovereign-compliant deployment expertise bridges gaps between commercial infrastructure and defense requirements. |
Study Parameters
Bottom-up defense procurement modeling reconciled against top-down vendor capacity tracking forms the analytical core. Primary interviews with defense ministry procurement officers, NATO standardization committee members, cryptographic engineering directors, and critical infrastructure CISOs combined with secondary validation from ENISA certification databases, NATO STANAG publication records, NIST cryptographic standardization documents, and national defense budget appropriations. Triangulation between demand-side program timelines and supply-side engineering capacity ensures forecast robustness.
Input-output matrices map message volume projections across deployment architecture, user security profile, and functional capability dimensions throughout the forecast period. Modeled segmentation spans cloud-based, on-premise, hybrid, and open source deployment modes; government, enterprise, educational, and non-profit end users; public, private, community, and multi-cloud infrastructure ownership; and automated response, encryption, CRM integration, and analytics functionality tiers. CAGRs derive from procurement cycle analysis and technology refresh timelines, incorporating quantum-resistant algorithm migration schedules and EU AI Act implementation phases as industry-specific demand drivers.
Several conditions sit outside the modeled scope, including classified program budgets, undisclosed national cryptographic requirements, and geopolitical disruptions to NATO interoperability agreements. Forecasts reflect documented procurement assumptions and technology adoption curves. Supply concentration among fewer than ten qualified encryption vendors, extended security clearance timelines, and evolving post-quantum standardization timelines warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Global Field Force Automation Market
Automation
CNC Controller Market
Automation
Global Warehouse Barcode System Market
Automation
Database Automation Market
Automation
Network Automation Market
Automation
Global Zig-Bee Automation Market
Automation
North America Home Automation Systems Market
Automation
Process Automation Market
Automation
Micro Fulfillment Market
Automation
Workflow Automation Market
Automation
Global Direct Mail Automation Software Market
Automation
Helpdesk Automation Market
Automation
Distributed Control System Market
Automation
Distribution Automation Solutions Market
Automation
Global Warehouse Execution System Market
Automation
Italy Marketing Automation Software Market