
 AR Automation Market | 2026-2036
AR Automation Market Size, Share, and Industry Trends Forecast 2026-2036
AR Automation Market Insights
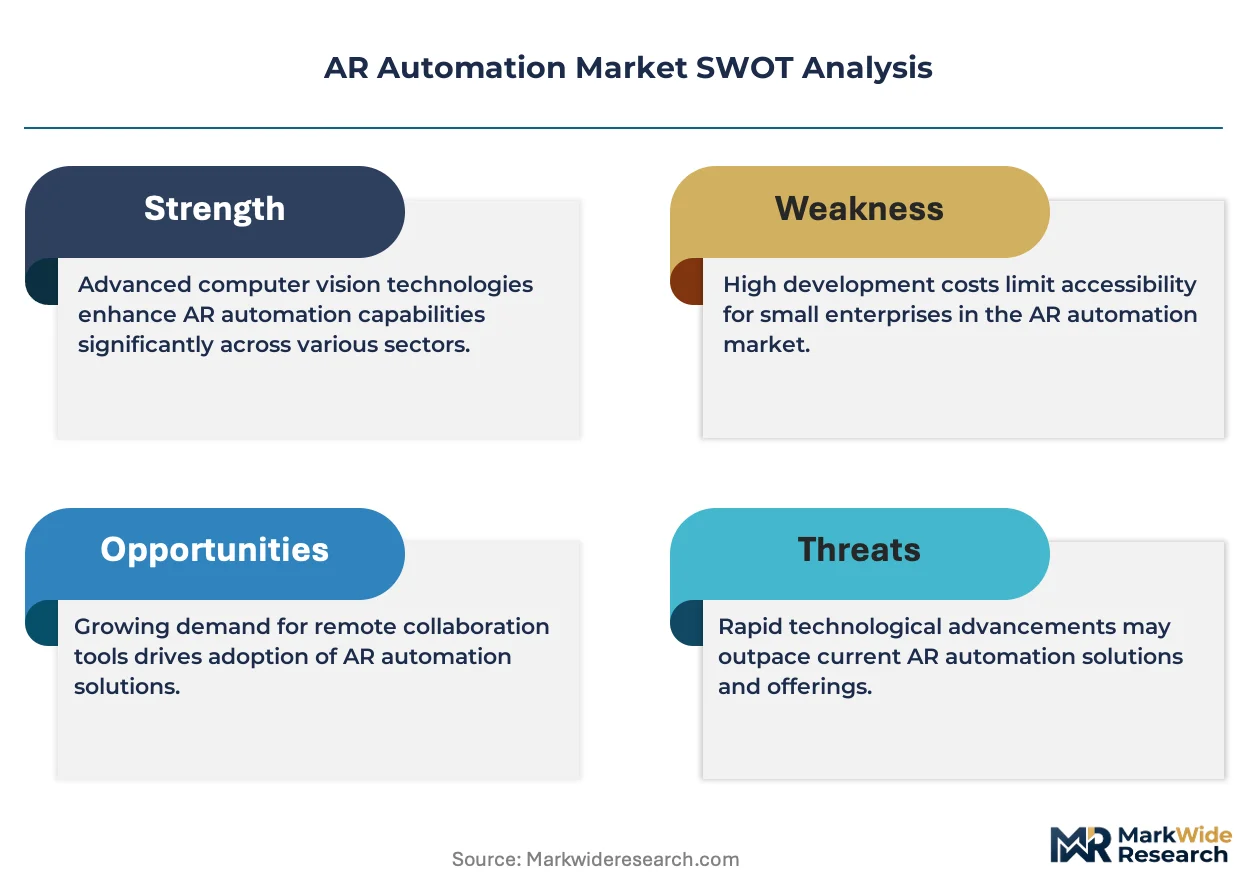
The AR automation space is consolidating around two distinct value tiers: premium platforms with native ERP integration and commodity tools offering basic invoice matching. Versapay leverages deep NetSuite and SAP connectors to anchor enterprise accounts requiring multi-entity cash application. HighRadius competes on AI-driven deduction coding that reduces manual reconciliation hours in high-volume B2B environments. Tesorio differentiates through real-time cash flow forecasting modules that extend beyond traditional dunning automation into treasury planning workflows.
AR automation encompasses software systems that digitize and orchestrate the entire order-to-cash cycle, from credit decisioning through payment collection and cash application, typically operating via API connections into ERP ledgers and bank payment rails. Computer vision technology now enables automatic extraction of remittance data from scanned checks and email attachments, while cloud-based deployment architectures allow mid-market firms to access enterprise-grade functionality without dedicated infrastructure teams. The technology dimension shows marker-based AR stagnating as projection-based interfaces gain traction in warehouse and factory floor settings where hands-free operation proves critical. Manufacturing application segments command the deepest implementation budgets due to complex multi-site reconciliation requirements across global supply chains.
ISO standards for financial data interoperability shape how AR automation platforms structure API exchanges between banks and corporate treasuries, while the EU AI Act imposes transparency requirements on machine learning models used for credit scoring and payment risk prediction in European deployments. The US Federal Reserve's instant payment infrastructure modernization creates both opportunity and compliance burden for platforms handling real-time remittance matching. Stakeholders must monitor whether regulatory fragmentation between GDPR-mandated data residency in Europe and sector-specific US banking rules will force architectural divergence in platform roadmaps.
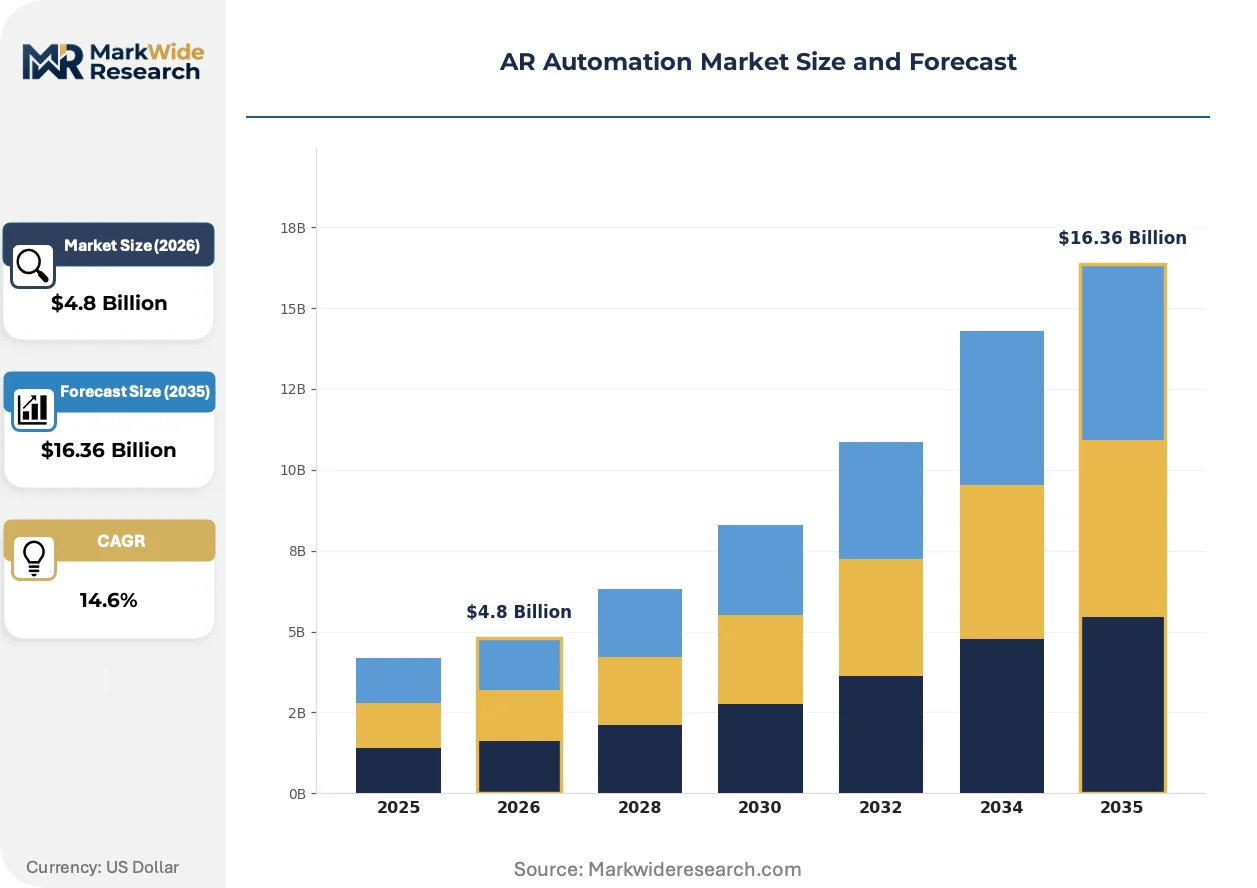
Market Dynamics
Cloud deployment architectures now dominate procurement discussions among Fortune 500 finance departments, compressing sales cycles for on-premise legacy systems while accelerating API-first platform adoption.
Growth Catalysts
- ISO 20022 financial messaging standards:The global standard for electronic data interchange between banks and corporate treasuries mandates structured remittance data formats, forcing ERP vendors to upgrade connector capabilities and creating upgrade revenue for AR automation platforms.
- Healthcare provider consolidation:Hospital networks in the United States are centralizing revenue cycle operations across acquired facilities, generating demand for multi-entity cash application systems that reconcile payments across disparate legacy billing systems.
- Projection-based AR interfaces:Spatial computing hardware is displacing marker-based systems in warehouse and factory floor settings where hands-free operation proves critical for assembly accuracy.
Market Restraints
- Data residency requirements:GDPR-mandated data localization in European deployments forces platform vendors to maintain separate regional cloud instances, increasing operational complexity and compliance overhead.
- Legacy ERP lock-in:Decades-old on-premise accounting systems in mid-market manufacturing lack modern API layers, requiring expensive custom integration work that extends implementation timelines.
- Substitution by built-in modules:NetSuite, SAP, and Oracle are expanding native AR functionality in their core ERP offerings, compressing addressable market for standalone automation vendors serving existing customer bases.
Strategic Opportunities
- Real-time payment infrastructure:The US Federal Reserve's instant payment modernization creates demand for remittance matching engines capable of sub-second reconciliation, opening treasury workflow extensions beyond traditional dunning automation.
- AI-driven deduction coding:Machine learning models for automated dispute classification remain underdeployed in European markets due to EU AI Act transparency requirements, creating first-mover advantage for compliant platforms.
- Mid-market manufacturing:German and Japanese factory floors are deploying AR-guided assembly systems to reduce rework rates, creating adjacent demand for integrated accounts receivable workflows tied to production milestone billing.
Industry Challenges
- ERP integration complexity:Multi-entity cash application across disparate accounting systems requires specialized technical expertise that remains scarce in implementation partner networks.
- Machine learning explainability:Credit scoring and payment risk prediction models face heightened scrutiny under EU AI Act documentation requirements, extending compliance timelines for European deployments.
- Banking API fragmentation:Real-time payment rails lack standardized data formats across jurisdictions, forcing platforms to maintain multiple connector variants and increasing engineering maintenance burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AR Automation Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Manufacturing, Retail, Healthcare, Education Technology: Computer Vision, Gesture Recognition, Projection-Based, Marker-Based End User: Consumer Electronics, Automotive, Aerospace, Healthcare Providers Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Versapay, Tesorio, Serrala, BlackLine, Esker, HighRadius, YayPay, Oracle Corporation, Billtrust, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AR Automation Market Trends and Innovations
Computer vision technology now enables automatic extraction of remittance data from scanned checks and email attachments, while cloud-based deployment architectures allow mid-market firms to access enterprise-grade functionality without dedicated infrastructure teams.
Projection-based AR interfaces are expanding into warehouse and factory floor environments where hands-free operation proves critical for assembly accuracy. Automotive OEMs in Germany and Japan are deploying these systems to guide complex multi-step assembly sequences, reducing rework rates while generating structured data streams that feed directly into milestone-based billing workflows. The technology is compressing implementation timelines for integrated order-to-cash systems that tie production completion to automated invoice generation.
The EU AI Act imposes transparency requirements on machine learning models used for credit scoring and payment risk prediction in European deployments. Platforms must now document algorithmic decision pathways and maintain human oversight mechanisms, increasing compliance engineering overhead but creating competitive differentiation for vendors with robust governance frameworks. Healthcare providers and financial institutions in France and Germany are prioritizing compliant platforms in procurement evaluations, shifting competitive emphasis from raw predictive accuracy to auditability.
Buyer concentration among Fortune 500 finance departments is consolidating vendor relationships around platforms with deep ERP connectors. Procurement teams are unbundling point solutions in favor of integrated order-to-cash suites that span credit decisioning through cash application, compressing addressable market for standalone dunning or collections modules. This pattern is most visible in United States healthcare networks and automotive supplier ecosystems where treasury centralization mandates are accelerating platform consolidation decisions.
AR Automation Market Segmentation
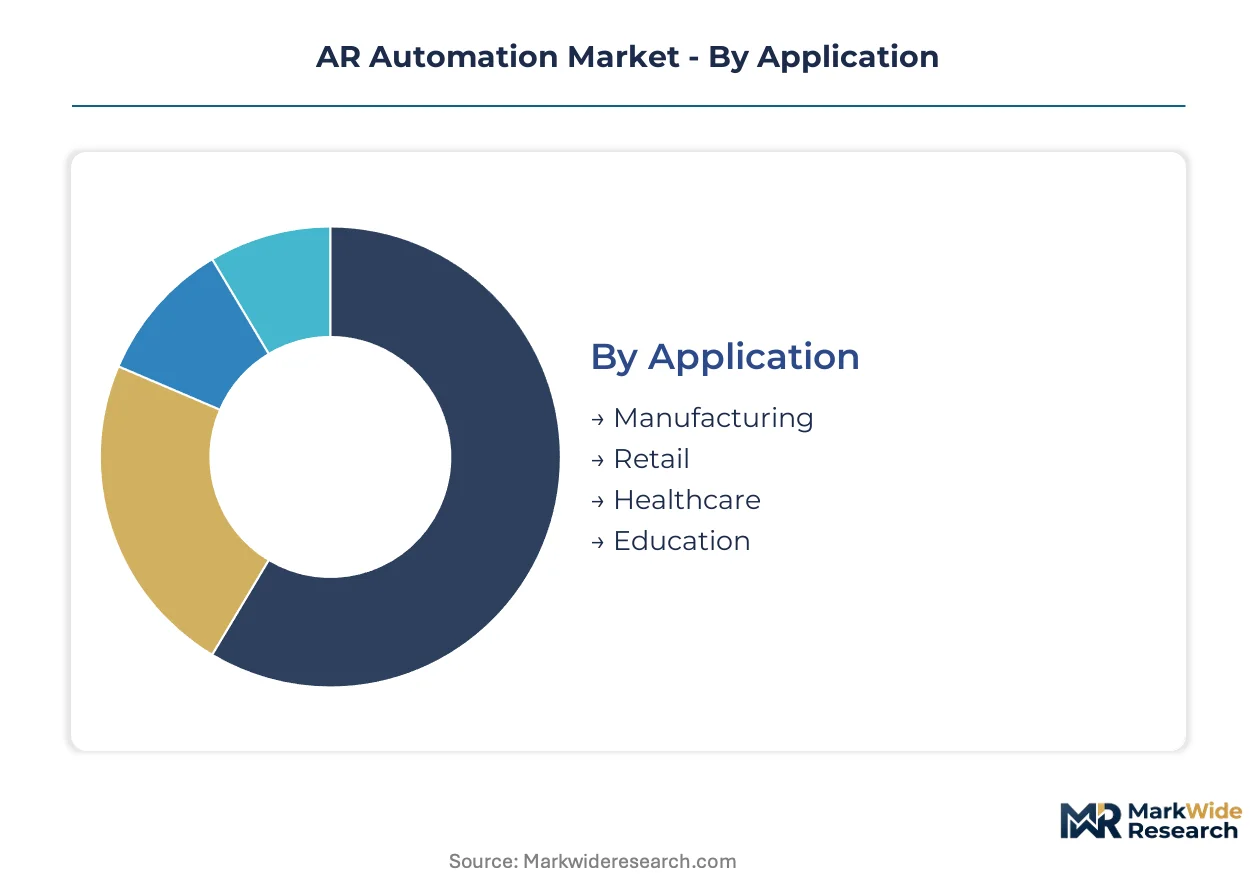
AR automation deployments fragment across multiple technical and operational dimensions, each carrying distinct integration requirements and procurement decision frameworks. Understanding these segment boundaries clarifies where platform vendors must architect specialized capabilities versus generalized functionality.
Application:
Upgrade cycles in this category track manufacturing capital expenditure patterns and healthcare revenue cycle modernization mandates, with replacement timelines compressing as cloud-native architectures displace legacy on-premise installations.
- Manufacturing:Assembly floor systems overlay digital work instructions onto physical components, guiding technicians through complex multi-step sequences. German and Japanese automotive suppliers dominate procurement volumes, driven by zero-defect quality mandates and milestone-based billing integration with production systems.
- Healthcare:Surgical navigation and patient education applications require FDA-compliant visualization pipelines with sub-millimeter spatial accuracy. United States hospital networks are consolidating vendor relationships around platforms that integrate with Epic and Cerner revenue cycle modules.
- Retail:Virtual try-on and inventory management interfaces deploy through consumer mobile devices, reducing hardware capital requirements.
- Education:Training simulations for technical skills development operate on lower-specification hardware, prioritizing content libraries over spatial precision.
Volume placements concentrate in Manufacturing; the faster expansion belongs to Healthcare.
Technology:
Cost tier differentiation in this category separates enterprise-grade spatial computing from commodity mobile AR, with procurement committees weighing hardware lifecycle costs against software licensing models.
- Computer Vision:Remittance data extraction from scanned documents and payment images leverages optical character recognition pipelines trained on financial document corpora. Cloud deployment architectures enable mid-market firms to access enterprise-grade extraction accuracy without dedicated machine learning infrastructure.
- Projection-Based:Spatial computing hardware casts contextual information directly onto work surfaces, eliminating wearable device requirements. Warehouse and factory floor environments in Japan and Germany favor this modality for hands-free operation compliance with safety regulations.
- Gesture Recognition:Touchless interface controls reduce contamination risks in sterile healthcare environments.
- Marker-Based:QR code and fiducial trigger systems persist in cost-constrained educational deployments despite limited tracking stability.
Procurement volume clusters around Computer Vision; Projection-Based systems are climbing the fastest as manufacturing safety standards tighten.
End User:
Customer type maturity in this category spans from consumer-facing volume applications to aerospace qualification requirements measured in certification years rather than implementation months.
- Automotive:OEM assembly lines and supplier quality stations deploy AR-guided inspection protocols with direct ERP integration for defect tracking. German manufacturers including Volkswagen and BMW facilities mandate ISO 26262-compliant visualization systems for safety-critical component verification.
- Healthcare Providers:Surgical planning and revenue cycle operations converge on platforms requiring both HIPAA data handling and FDA 510(k) clearance for diagnostic visualization. United States health systems prioritize vendors with established Epic integration credentials.
- Consumer Electronics:Device manufacturers apply AR to assembly verification and packaging quality control.
- Aerospace:Boeing and Airbus supplier networks impose AS9100 quality system requirements on AR documentation tools, extending vendor qualification timelines.
Revenue concentration sits with Automotive; Healthcare Providers show the steepest expansion trajectory as revenue cycle centralization accelerates.
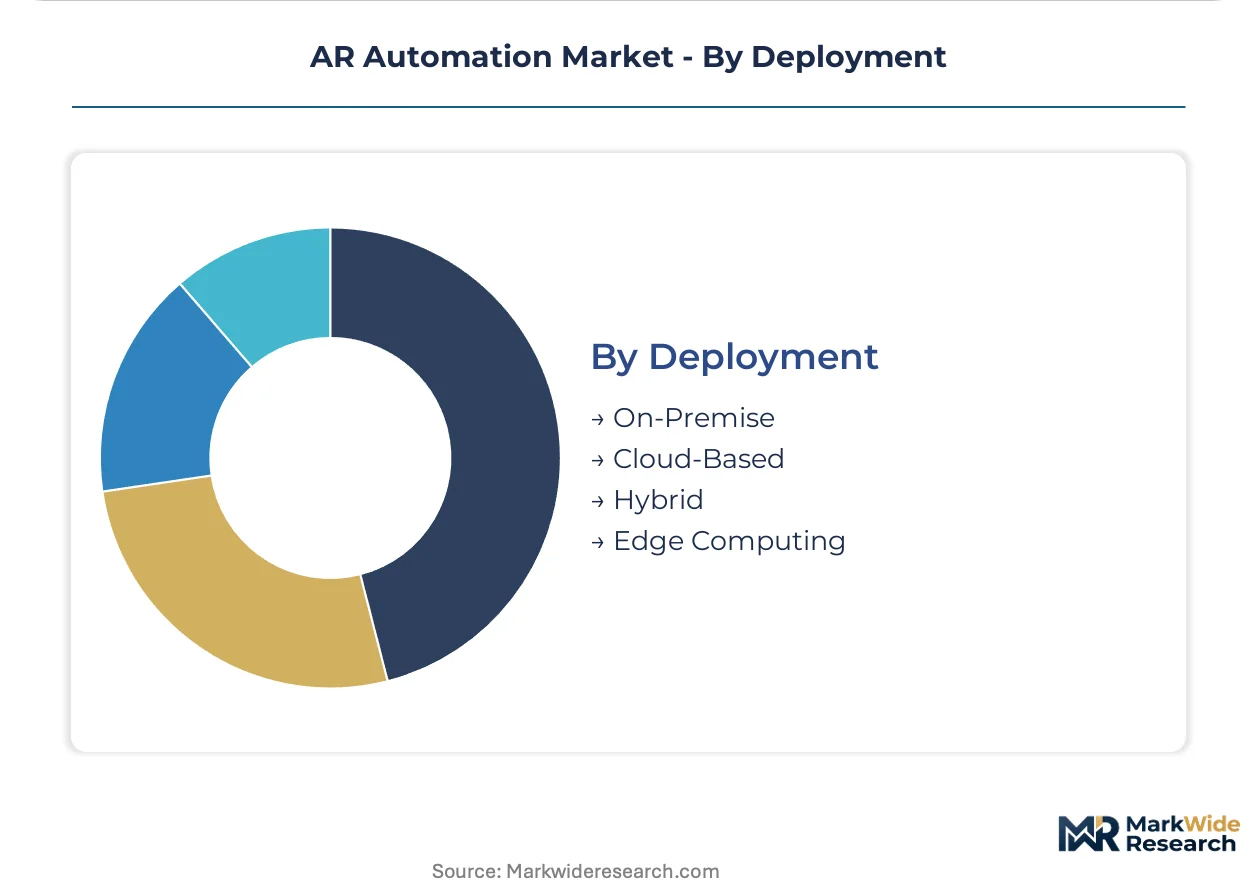
Deployment:
Supply concentration in cloud infrastructure shapes procurement patterns, with hyperscaler availability zones determining data residency compliance capabilities for multi-national deployments.
- Cloud-Based:API-first platforms operating across AWS, Azure, and GCP regions enable Fortune 500 finance departments to consolidate vendor relationships without infrastructure capital expenditure. GDPR-mandated European data residency requires deliberate region selection for EU AI Act compliance.
- Hybrid:Sensitive payment data remains on-premise while analytics workloads burst to cloud resources, addressing banking regulator concerns in United States and European jurisdictions simultaneously.
- On-Premise:Defense and classified manufacturing programs mandate air-gapped installations with no external connectivity.
- Edge Computing:Sub-50 millisecond latency requirements for real-time assembly guidance drive localized processing in high-throughput production environments.
Platform selections cluster in Cloud-Based architectures; Hybrid deployments are gaining share fastest as regulatory fragmentation between jurisdictions intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors the highest concentration of AR automation platform development, with venture-backed fintechs clustering near enterprise software talent pools. Cloud-native deployment architectures spread from this hub into Fortune 500 finance departments across three continents.
United States
Healthcare provider consolidation drives multi-entity cash application demand across hospital networks. HIPAA compliance requirements shape procurement evaluations for platforms handling patient billing data. Epic Systems' dominance in Chicago and Verona, Wisconsin creates tight integration requirements for AR vendors serving Midwest health systems.
Germany
Automotive OEMs mandate ISO 26262-compliant visualization systems for assembly floor AR deployments. The EU AI Act imposes documentation burdens on machine learning models used for credit scoring in European deployments. Volkswagen and BMW facilities in Bavaria and Baden-Württemberg pilot milestone-based billing tied to production completion.
Japan
Zero-defect quality mandates in automotive supplier networks accelerate AR-guided inspection protocol adoption. METI industrial digitization programs subsidize factory floor automation investments. Toyota supplier parks in Aichi Prefecture and Nissan operations in Kanagawa integrate production milestone billing with automated invoice generation.
United Kingdom
Open Banking standards force API-first platform architectures for real-time payment reconciliation. FCA conduct rules extend to automated credit decisioning workflows in financial services deployments. London fintech clusters in Shoreditch and Canary Wharf drive demand for treasury workflow extensions beyond traditional dunning automation.
India
RBI's account aggregator framework enables consent-based financial data sharing for automated remittance matching. PLI scheme incentives for electronics manufacturing create adjacent demand for production-integrated billing systems. Bangalore and Hyderabad SaaS development centers export API-first AR platforms to mid-market firms globally.
AR Automation Market Competitive Landscape
Premium-margin players sit above commodity-margin players across ERP integration depth and AI model sophistication. The vendor base stratifies between cloud-native specialists with native SAP and NetSuite connectors versus legacy on-premise incumbents defending installed bases. Three archetypes dominate: API-first fintechs, ERP-embedded modules, and vertical specialists in healthcare or manufacturing. Consolidation pressure intensifies through strategic partnerships between banks and platform vendors, plus geographic expansion by North American vendors into European compliance-heavy deployments.
Within the API-first tier, Versapay and HighRadius exemplify divergent specialization strategies—one anchoring enterprise multi-entity cash application, the other competing on AI-driven deduction coding. Tesorio occupies a position at the forecasting-extension frontier, representing the treasury-planning archetype that stretches beyond traditional dunning automation. These three firms collectively illustrate how competitive positioning now hinges on workflow breadth rather than point-solution depth.
| Leading Market Players |
|---|
| Versapay |
| Tesorio |
| Serrala |
| BlackLine |
| Esker |
| HighRadius |
| YayPay |
| Oracle Corporation |
| Billtrust |
| Others |
Pricing and Supply Chain Analysis
Fortune 500 finance departments concentrate procurement authority for AR automation platforms, compressing vendor margins through consolidated contract negotiations while favoring subscription-based SaaS tiers over perpetual licensing. This buyer concentration forces platforms to anchor pricing around realized cash flow improvements rather than feature checklists.
Pricing Analysis
Value-based pricing tied to days-sales-outstanding reduction anchors enterprise contracts, with platforms charging percentage-of-recovery fees for AI-driven deduction coding modules. Three-tier pricing structure across premium, standard, and economy levels separates deep ERP-integrated suites from API-light mid-market tools. Cost compression in the standard tier intensifies because NetSuite and SAP are expanding native AR functionality without third-party licensing. Mid-market manufacturing firms show highest price sensitivity due to legacy ERP lock-in costs, while healthcare networks prioritize HIPAA-compliant platforms with less negotiation leverage.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and India anchor cloud infrastructure provisioning for AR automation platforms, with AWS and Azure availability zones determining data residency compliance capabilities. Software development draws from Bangalore and Hyderabad talent pools, while customer success operations rest on specialized implementation partner networks concentrated in North America and Western Europe. Single-source vulnerability in ERP connector development creates supply chain risk, as scarce SAP and NetSuite certification expertise limits platform scaling velocity. Distribution runs through direct enterprise sales teams supplemented by systems integrator channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in ISO 20022-compliant engineering talent prop pricing power for platforms with certified bank connector development teams, insulating premium tiers from commodity pressure.
For Market Incumbents: Anticipate substitution pressure from ERP-embedded modules by deepening native SAP and NetSuite connector roadmaps ahead of core platform upgrades. Vertical integration into specialized implementation partner networks defends margin position against API-first challengers lacking deployment expertise. For New Entrants and Emerging Players: Systems integrator partnerships offer the fastest path to credibility in European deployments burdened by EU AI Act compliance documentation. White-space concentrates in mid-market manufacturing verticals across Germany and Japan, where milestone-based billing integration with production systems remains underpenetrated. A compliance-first positioning targeting healthcare provider revenue cycle centralization bypasses crowded dunning automation segments. For Investors and Strategic Acquirers: The window for entry favors platforms with established ERP connector IP and documented EU AI Act governance frameworks. Long-term viability hinges on treasury workflow extension capabilities beyond traditional cash application. Watch for Federal Reserve instant payment infrastructure completion as inflection signal for real-time remittance matching engine demand.| Strategic Initiative | Industry Significance |
|---|---|
| ERP Connector Certification Investment | SAP and NetSuite native integration credentials unlock Fortune 500 procurement committees. |
| EU AI Act Compliance Documentation | Algorithmic transparency frameworks differentiate platforms in French and German healthcare evaluations. |
| Treasury Workflow Extension | Cash flow forecasting modules capture budget authority from CFO offices beyond AR operations. |
| Manufacturing Floor Integration | Production milestone billing ties invoice automation to German and Japanese automotive quality systems. |
| Real-Time Payment Engine Development | Sub-second remittance matching aligns with Federal Reserve instant payment infrastructure modernization. |
Research Methodology
Independent corroboration across primary interviews with AR operations directors, ERP implementation specialists, and treasury technology officers, combined with secondary validation through SEC 10-K filings, hyperscaler capex disclosures, and ISO 20022 migration documentation, underwrites the qualitative findings. Bottom-up triangulation across vendor-reported deployment metrics and top-down reconciliation against ERP vendor ecosystem disclosures ensures segmentation integrity.
Rate-of-change decomposition across the analysis window separates volume expansion from pricing trajectory, with CAGRs derived from modeled adoption curves across deployment model, organization size, and vertical integration complexity dimensions. Forecast inputs incorporate Federal Reserve payment infrastructure timelines and EU AI Act implementation phases without specific date anchoring.
Several conditions sit outside the modeled scope, including macroeconomic credit cycle shifts affecting B2B payment behavior and unforeseen ERP vendor acquisition of standalone automation platforms. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Global Automated Liquid Handlers Market
Automation
Database Automation Market
Automation
Global Cloud Automation Market
Automation
Workload Scheduling and Automation Market
Automation
Smart Home Automation Market
Automation
Global Direct Mail Automation Software Market
Automation
Industrial Vending Machines Market
Automation
Global Sales Force Automation (SFA) Market
Automation
IoT Home Automation Market
Automation
Global Remote Monitoring and Control Market
Automation
Data Center Automation Market
Automation
Cognitive Process Automation Market
Automation
Global Zig-Bee Automation Market
Automation
Global Warehouse Barcode System Market
Automation
Network Automation Market
Automation
Elevator Control Market