
 Network Attached Storage (NAS) Market | 2026-2036
Network Attached Storage (NAS) Market Size, Share, and Industry Trends Forecast 2026-2036
Network Attached Storage (NAS) Market Analysis
GDPR enforcement is shifting the cost-of-entry calculus for NAS vendors serving European enterprises. Dell Technologies Inc. leverages its integrated server-storage portfolio to anchor large enterprise contracts across regulated industries. NetApp Inc. competes through cloud-connected fabric architectures that bridge on-premises NAS with hyperscaler environments. Synology Inc. differentiates via software-defined storage stacks targeting small businesses and home users with enterprise-grade features.
Network Attached Storage denotes dedicated file-level data storage servers connected to computer networks, typically operating over TCP/IP via NFS, SMB/CIFS, or AFP protocols with drive configurations spanning HDD, SSD, and hybrid tiers. Rack-mounted systems dominate enterprise data centers where density and thermal management drive procurement decisions, while standalone units sustain growth among home users and remote offices prioritizing plug-and-play deployment. Fibre Channel connectivity occupies premium virtualization workloads demanding sub-millisecond latency, whereas Ethernet-based NAS extends across mainstream backup and file sharing applications where cost-per-terabyte governs selection.
The EU AI Act, GDPR, and ISO 27001 standards collectively reshape NAS demand by mandating audit trails, encryption-at-rest, and geographic data containment that legacy direct-attached storage cannot satisfy. The US SEC and HIPAA frameworks impose parallel accountability on financial services and healthcare NAS deployments, elevating certified hardware procurement. Stakeholders must weigh sovereign cloud integration against on-premises retention as regulatory fragmentation intensifies across jurisdictions.
Market Dynamics
Enterprise data gravity is shifting toward edge-computing nodes, forcing NAS architectures to disaggregate storage intelligence from physical hardware and distribute file services across hybrid infrastructure stacks.
Growth Catalysts
- GDPR Article 44:Cross-border data transfer restrictions compel European enterprises to maintain on-premises NAS estates for primary storage, insulating local vendors from cloud substitution.
- Healthcare imaging archives:PACS and DICOM workloads in diagnostic centers generate petabyte-scale unstructured data that object storage cannot access with sufficient latency for radiologist workflows.
- AI training pipelines:GPU clusters in Germany, the United States, and Japan require high-throughput NFSv4.1 access to training datasets, resurrecting NAS as the preferred interface over parallel file systems for mid-scale deployments.
Market Restraints
- NAND flash supply concentration:Korean and Taiwanese foundries control high-density SSD wafer output, exposing NAS vendors to input cost volatility when memory cycles tighten.
- Hyperscaler object storage substitution:Amazon S3, Azure Blob, and Google Cloud Storage compete for secondary and archival tiers with price points that on-premises NAS cannot match at equivalent durability.
- F-Gas Regulation phase-down:EU restrictions on fluorinated refrigerants complicate thermal management for high-density rackmount NAS systems in continental data centers.
Strategic Opportunities
- India's data localization mandate:RBI and MEITY directives on financial and government data residency create whitespace for domestic NAS assembly and sovereign cloud partnerships.
- Computational storage convergence:Integration of FPGA-based compression and erasure coding into drive controllers reduces CPU overhead for video surveillance and genomics workloads.
- Utility tariff arbitrage:Nordic countries with surplus renewable generation attract hyperscale-adjacent NAS colocation for AI training datasets requiring 24/7 availability.
Industry Challenges
- Zero-trust architecture integration:NIST 800-207 mandates for continuous verification strain legacy NAS authentication stacks that rely on Kerberos and LDAP without hardware-backed attestation.
- Interoperability certification timelines:VMware vSphere, Kubernetes CSI, and Red Hat OpenShift compatibility testing extends product release cycles by 6-9 months for enterprise-qualified SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Attached Storage (NAS) Market |
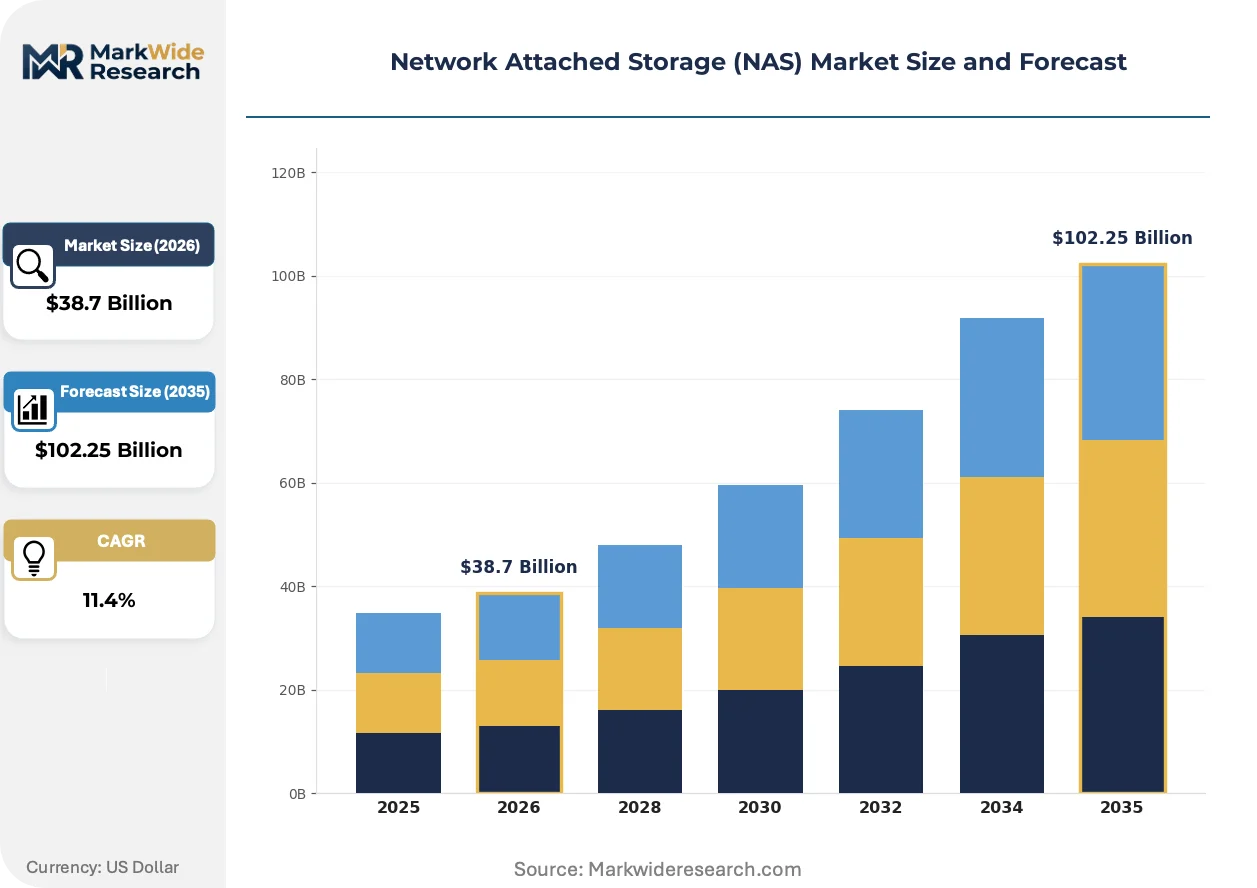
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Rack-mounted, Blade, Hybrid Application: Media Streaming, Data Backup, File Sharing, Virtualization End User: Small Businesses, Large Enterprises, Home Users, IT Service Providers Connectivity: Wi-Fi, Ethernet, Fibre Channel, Thunderbolt |
| Companies Covered | Dell Technologies Inc., NetApp Inc., Synology Inc., Western Digital Corp., QNAP Systems Inc., Hewlett Packard Enterprise Co., Seagate Technology Holdings PLC, Hitachi Vantara LLC, Netgear Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Attached Storage (NAS) Market Emerging Trajectories
Software-defined storage controllers are decoupling file system logic from proprietary hardware, enabling NAS functionality to deploy as containerized microservices across commodity compute.
NVMe-oF fabrics is overtaking traditional NFS and SMB for latency-sensitive workloads in financial trading and real-time analytics. Hedge funds and quantitative research departments in London and New York deploy NVMe/TCP and NVMe/RoCE NAS front-ends to feed tick databases. The shift compresses storage network latency from hundreds of microseconds to tens, collapsing the performance gap between file and block access.
The EU AI Act's risk-based classification system mandates audit logging and model lineage tracking for high-risk AI systems. Storage vendors must embed immutable WORM capabilities and cryptographic timestamping into NAS software stacks to satisfy conformity assessments. German automotive and French healthcare AI developers now specify NAS platforms with built-in compliance instrumentation during procurement.
Consumption-based financing is displacing capital expenditure models for mid-market NAS procurement. Dell Technologies and NetApp extend hardware-as-a-service contracts with embedded cloud tiering and predictive support. Japanese manufacturing SMEs and US regional hospital systems favor opex-aligned contracts that bundle capacity scaling with operational management.
Network Attached Storage (NAS) Market Segmentation
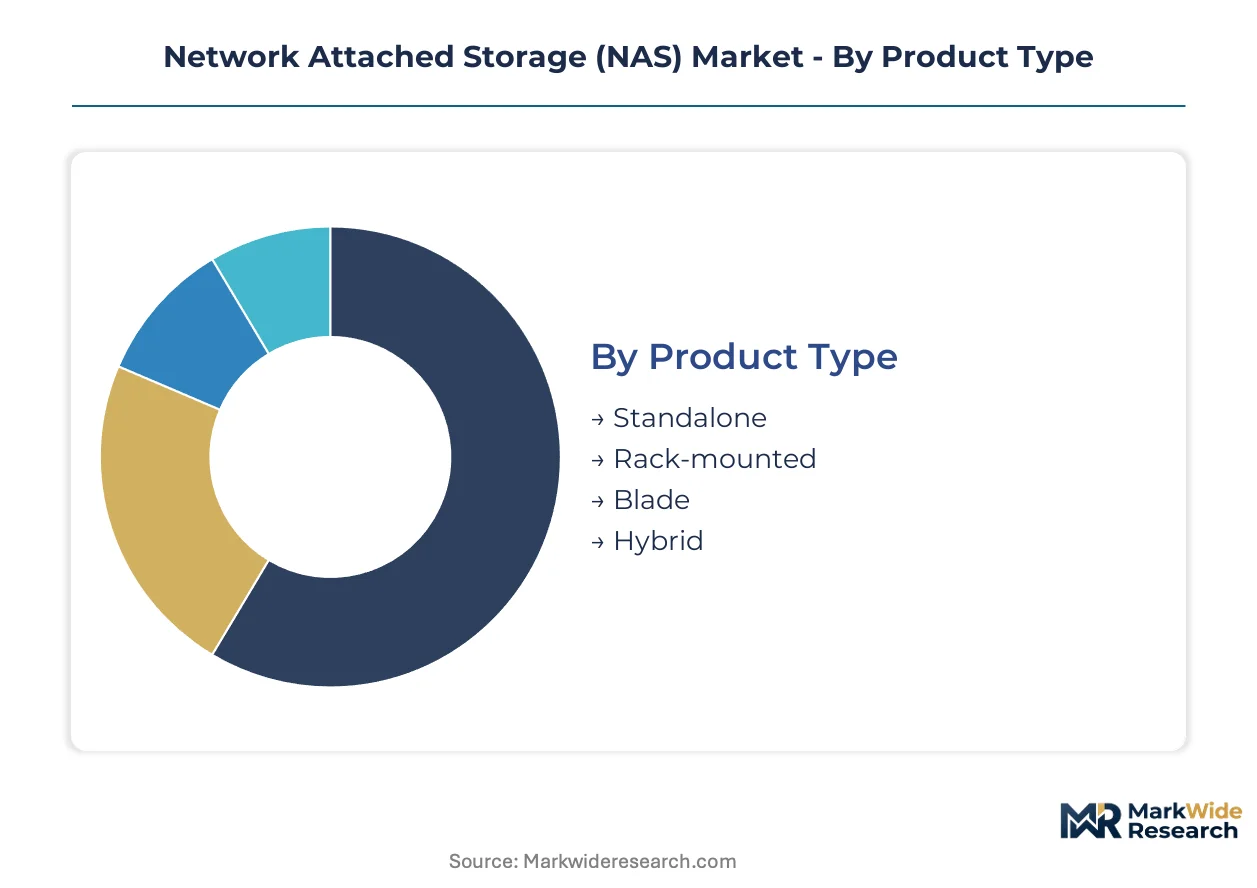
Network Attached Storage procurement decisions hinge on balancing capital expenditure against performance requirements and regulatory constraints. Segment boundaries increasingly blur as software-defined architectures allow hardware form factors to serve multiple workload types.
Product Type:
Rack-mounted systems demand the highest upfront capital commitment due to data center real estate, cooling infrastructure, and enterprise-grade redundancy requirements.
- Rack-mounted:High-density enclosures designed for 19-inch data center racks with redundant power supplies and hot-swappable drive bays. German automotive manufacturers and Japanese financial institutions deploy these for PACS imaging and AI training clusters where thermal management and serviceability dominate TCO calculations.
- Standalone:Desktop or tower units prioritizing acoustic dampening and plug-and-play deployment over density. Home users in the United States and small diagnostic clinics across France favor these for media archives and compliance-light backup workloads where facility constraints preclude rack infrastructure.
- Blade:Modular storage blades integrating into converged infrastructure chassis alongside compute and networking resources. Enterprises running VMware vSphere clusters in London and Singapore data centers specify blade NAS for footprint consolidation.
- Hybrid:Systems combining on-premises controllers with cloud tiering gateways. Healthcare networks in California and Texas adopt these for HIPAA-compliant primary storage with archival overflow to sovereign cloud instances.
Rack-mounted configurations absorb the bulk of installed capacity; hybrid architectures are expanding most quickly.
Application:
Workload characteristics determine whether throughput, latency, or capacity efficiency governs hardware selection.
- Data Backup:Sequential write-optimized repositories targeting recovery point objectives with deduplication and compression. German Mittelstand manufacturers and US regional hospital systems drive demand for immutable backup targets satisfying GDPR Article 32 and HIPAA security rule requirements.
- Virtualization:Low-latency storage for VMware, Hyper-V, and KVM hypervisor environments requiring VMFS or NFS datastores. Quantitative trading firms in New York and London specify sub-millisecond response times for tick database hosting.
- Media Streaming:Sequential read-optimized systems serving video content to distributed clients. Production houses in Los Angeles and Mumbai deploy these for 4K/8K editorial workflows where bandwidth consistency outweighs random IOPS.
- File Sharing:General-purpose collaboration storage with access control and versioning. Legal and architectural partnerships across Sydney and Toronto prioritize these for client document exchange with audit logging.
Data Backup claims the largest installed base; Virtualization is climbing the fastest as containerization and VDI refresh cycles accelerate.
End User:
Procurement authority and technical sophistication create distinct buying patterns across organizational scale.
- Large Enterprises:Centralized IT procurement with formal RFP processes, compliance certification requirements, and multi-year support contracts. Fortune 500 manufacturers in Illinois and pharmaceutical conglomerates in Basel specify ISO 27001 and SOC 2 Type II attested platforms.
- Small Businesses:Owner-operated technology decisions prioritizing total cost of ownership and minimal administrative overhead. Independent dental practices in Florida and retail chains in Ontario favor subscription-bundled appliances with remote monitoring.
- Home Users:Enthusiast and prosumer segments seeking media centralization and personal cloud alternatives. Creative professionals in Brooklyn and Berlin drive demand for 10GbE-equipped units with Plex and Docker support.
- IT Service Providers:Managed service operators delivering multi-tenant storage-as-a-service. Colocation facilities in Amsterdam and Sydney aggregate these for SME clients requiring geographic redundancy without capital deployment.
Large Enterprises dominate absolute spending; IT Service Providers are gaining share fastest as consumption-based models displace direct ownership.
Connectivity:
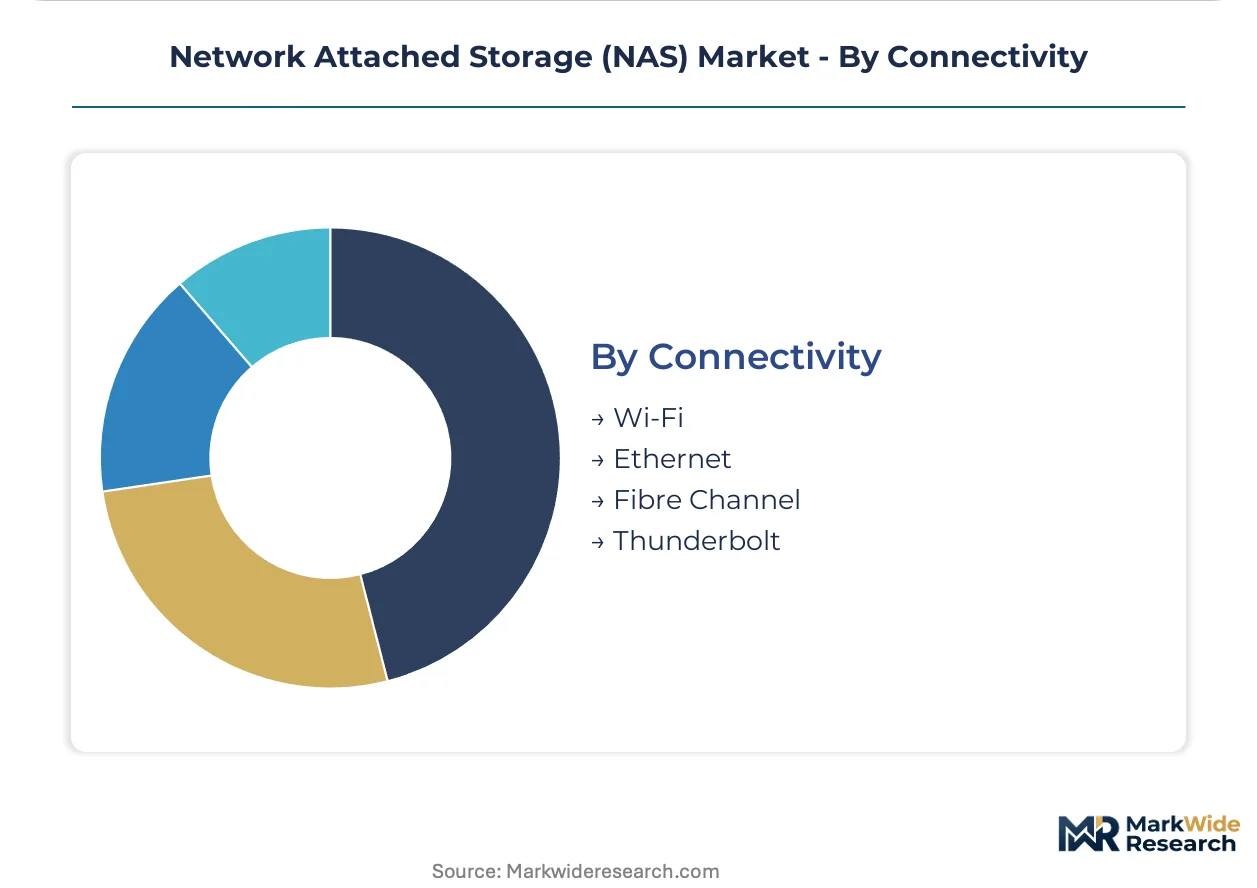
Protocol selection directly constrains achievable latency and infrastructure compatibility.
- Ethernet:Ubiquitous TCP/IP transport supporting NFS, SMB, and iSCSI with switch infrastructure leverage. Corporate campuses in Texas and Bavaria standardize on 25GbE and 100GbE for mainstream file services and backup targets.
- Fibre Channel:Lossless, low-latency SAN protocol for mission-critical databases and ERP systems. SAP HANA deployments at BASF and Siemens in Germany mandate FC connectivity for storage area network integration.
- Wi-Fi:Wireless access for mobile and edge deployment scenarios with tolerance for variable throughput. Construction site offices and temporary medical clinics in rural India utilize these where cabling is impractical.
- Thunderbolt:Direct-attached protocol bridging to NAS controllers for high-bandwidth workstation integration. Video editing suites at Netflix and BBC post-production facilities in London deploy Thunderbolt 3/4 for DAS-NAS hybrid workflows.
Ethernet underpins the majority of active connections; Fibre Channel maintains premium positioning in latency-sensitive verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center investment zones in Singapore, Frankfurt, and North Virginia concentrate hyperscale-adjacent NAS deployments where tax incentives and renewable energy access reduce operational expenditure for AI training infrastructure.
United States
Healthcare networks in Texas and California drive petabyte-scale PACS imaging archives requiring HIPAA-compliant retention. SEC disclosure rules mandate immutable audit trails for financial services NAS estates. Northern Virginia data centers host GPU clusters for AI training pipelines demanding NVMe-oF connectivity.
Germany
Automotive manufacturers in Stuttgart and Munich deploy NAS for autonomous vehicle training datasets subject to GDPR Article 44 localization. The EU AI Act risk classification system mandates cryptographic timestamping for high-risk AI storage. Bavarian diagnostic centers specify ISO 27001-certified systems for DICOM workloads.
Japan
Precision manufacturing SMEs in Osaka and Nagoya favor consumption-based NAS contracts bundling predictive support. METI data sovereignty guidelines reinforce on-premises retention for sensitive industrial designs. Tokyo financial institutions specify sub-millisecond Fibre Channel connectivity for quantitative trading databases.
India
RBI data localization directives compel domestic banks to maintain primary storage within national boundaries. The PLI scheme for electronics manufacturing incentivizes local NAS assembly partnerships. Bengaluru and Hyderabad cloud operators provision sovereign infrastructure for government and fintech workloads.
United Kingdom
Post-production facilities in London deploy Thunderbolt-bridged NAS for 4K editorial workflows. FCA operational resilience rules mandate geographic redundancy for trading system backups. Manchester and Edinburgh colocation providers aggregate multi-tenant storage-as-a-service for regional SMEs.
Network Attached Storage (NAS) Market Vendor Landscape
United States vendors anchor the enterprise tier through integrated server-storage portfolios; Taiwan specialists hold the prosumer segment with software-defined stacks. Market structure concentrates around three strategic archetypes: converged infrastructure providers, cloud-connected fabric architects, and subscription-bundled appliance specialists. Dominant competitive moves include consumption-based financing displacement and sovereign cloud partnership formation.
Within the integrated infrastructure tier, Dell Technologies Inc. and Hewlett Packard Enterprise Co. exemplify scale-driven positioning through comprehensive hardware portfolios. NetApp Inc. occupies a distinct position bridging on-premises controllers with hyperscaler tiering. Synology Inc. and QNAP Systems Inc. represent the software-defined specialist archetype targeting deployment simplicity. These named entities collectively illustrate how competitive differentiation fragments across enterprise contract complexity, hybrid cloud integration depth, and administrative accessibility.
| Leading Market Players |
|---|
| Dell Technologies Inc. |
| NetApp Inc. |
| Synology Inc. |
| Western Digital Corp. |
| QNAP Systems Inc. |
| Hewlett Packard Enterprise Co. |
| Seagate Technology Holdings PLC |
| Hitachi Vantara LLC |
| Netgear Inc. |
| Others |
Supply Flow & Price Mechanics
GDPR Article 44 data localization mandates are forcing European enterprises to absorb premium pricing for certified on-premises NAS systems, compelling vendors to reconfigure supply chains toward regional assembly hubs and sovereign cloud partnerships rather than centralized manufacturing.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to enterprise-qualified SKUs with VMware vSphere and Kubernetes CSI certifications, while spot inventory of uncertified units trades at discounts through distribution channels. Three-tier pricing structure across premium, standard, and economy levels separates ISO 27001-certified rackmount systems from standalone units and refurbished hardware. Cost compression in the mid-market tier is intensifying because Taiwanese and Korean foundry concentration for high-density SSDs exposes vendors to NAND flash cycle volatility. Small businesses exhibit highest price sensitivity, prioritizing total cost of ownership, while large enterprises accept premium positioning for compliance-bundled contracts.
Supply Chain Analysis
Reverse logistics flows for rackmount NAS systems concentrate refurbishment and drive replacement operations in Singapore, Shenzhen, and Amsterdam to satisfy EU WEEE directive requirements and minimize downtime for enterprise service contracts. Component sourcing draws from Taiwanese ODMs for controller boards, Korean fabs for NAND flash, and Chinese assembly for power supply units. Single-source vulnerability in high-density SSD wafer output from Samsung and SK Hynix creates procurement risk during memory supply tightening. Distribution runs through value-added distributors in Frankfurt and North Virginia for enterprise accounts, with direct-to-consumer e-commerce serving prosumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NAND flash foundry capacity constraints in Korea and Taiwan are propping hardware pricing, creating a supply-constrained market where procurement flexibility and certification speed determine competitive position.
For Market Incumbents: Anticipate hyperscaler object storage substitution by embedding immutable WORM capabilities and cryptographic timestamping directly into NAS software stacks to satisfy EU AI Act conformity assessments. Deepen backward integration into FPGA-based computational storage controllers to reduce CPU overhead for genomics and video surveillance workloads, defending margin position against white-box competitors. For New Entrants and Emerging Players: RBI data localization directives in India open a window for domestic NAS assembly partnerships with Bengaluru and Hyderabad cloud operators serving government and fintech workloads. Target India's whitespace for sovereign infrastructure procurement, leveraging PLI scheme incentives for electronics manufacturing to establish cost-competitive regional production. For Investors and Strategic Acquirers: The window for entry favors software-defined storage specialists with containerized microservice architectures that decouple file system logic from proprietary hardware. Monitor hyperscaler capex disclosures for AI training infrastructure as the inflection signal indicating sustained demand for high-throughput NVMe-oF connectivity.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership Formation | GDPR Article 44 compliance enables European market access for certified vendors. |
| Computational Storage Convergence | FPGA-based compression reduces CPU overhead for genomics and surveillance workloads. |
| Consumption-Based Financing Displacement | Hardware-as-a-service contracts align Japanese SME procurement with opex preferences. |
| NVMe-oF Fabric Integration | Sub-millisecond latency satisfies quantitative trading database requirements in London. |
| Zero-Trust Architecture Certification | NIST 800-207 compliance opens federal and financial services procurement channels. |
Methodological Framework
Document review covered SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory guidance, complemented by interviews with data center infrastructure directors, storage procurement managers at Fortune 500 manufacturers, IT service provider operators, and biomedical engineers managing PACS imaging archives. Secondary validation drew from VMware compatibility certification databases, ISO 27001 registry listings, and NAND flash supply chain trade data. Bottom-up unit economics triangulated against top-down market sizing across product type, connectivity protocol, and end-user scale dimensions.
Cross-referencing historical shipment patterns against panel input from German automotive manufacturers and Japanese financial institutions anchored volume projections across the analysis window. Segmentation modeling incorporated rackmount versus standalone form factors, Ethernet versus Fibre Channel connectivity, and healthcare imaging versus AI training application splits. CAGRs derived from elasticity-adjusted demand curves reflecting GDPR enforcement intensity and hyperscaler tiering adoption rates.
Caveats apply where NAND flash supply disruptions, EU F-Gas Regulation phase-down impacts on thermal management, or accelerated hyperscaler object storage substitution could materially shift the outlook. Practitioners should monitor RBI and MEITY data localization directive implementation timelines for early signals of geographic demand redistribution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Storage and Backup Software Market
Storage Solutions
Global Storage As a Service Market
Storage Solutions
Disk Based Data Fabric Market
Storage Solutions
Hard Disk Market
Storage Solutions
Vietnam Data Center Storage Market
Storage Solutions
Spain Data Center Storage Market
Storage Solutions
Singapore Data Center Storage Market
Storage Solutions
Cloud Object Storage Solutions Market
Storage Solutions
Saudi Arabia Data Center Storage Market
Storage Solutions
Global Virtual Data Storage Market
Storage Solutions
Indonesia Data Center Storage Market
Storage Solutions
Philippines Data Center Storage Market
Storage Solutions
Mexico Data Center Storage Market
Storage Solutions
Consumer Network Attached Storage Market
Storage Solutions
Automated Storage and Retrieval System (AS & RS) Market
Storage Solutions
Global Ethernet Storage Fabric Market