
 Courier Express and Parcel (CEP) Market | 2026-2036
Courier Express and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
Courier Express and Parcel (CEP) Market Insights
Modular service bundling is shifting buyer choice in the CEP sector, as shippers now expect integrated first-mile, line-haul, and returns management rather than standalone point-to-point delivery. Deutsche Post DHL Group leverages its integrated network to anchor premium cross-border express volumes. FedEx Corporation competes through specialized healthcare cold-chain logistics. Amazon Logistics dominates domestic fulfillment through captive warehouse-to-door infrastructure.
Courier Express and Parcel services encompass time-definite transportation of documents and packages up to thirty kilograms, utilizing integrated sorting hubs, track-and-trace systems, and multi-modal capacity to guarantee delivery windows for commercial and residential recipients. Same-day delivery and next-day delivery command the highest margin pools as e-commerce platforms absorb premium pricing for speed-critical shipments. Standard delivery occupies the volume base across retail and manufacturing end users, while drone delivery remains nascent outside regulatory test corridors.
EPA emissions standards in the United States, the EU Green Deal's F-Gas Regulation for transport refrigeration, and FAA drone integration rules collectively shape fleet composition, last-mile automation timelines, and cross-border operational compliance. China's MIIT and SAMR enforce data-localization and vehicle-electrification mandates that determine platform architecture for operators serving the domestic market. Stakeholders must monitor regulatory divergence between aviation authorities and environmental agencies to anticipate which delivery modes gain operational clearance.
Market Dynamics
Modular service bundling is compressing buyer decision cycles across the CEP sector, as e-commerce platforms now mandate integrated first-mile, line-haul, and returns management from single-source providers rather than assembling fragmented carrier networks.
Growth Catalysts
- EU Green Deal fleet mandates:The F-Gas Regulation and CO2 standards for transport refrigeration are accelerating electric vehicle procurement across member states, creating captive demand for zero-emission last-mile infrastructure.
- China's tier-one city density:Same-day delivery baselines in Beijing, Shanghai, and Shenzhen clusters are pulling investment into hyperlocal sorting hubs and micro-fulfillment nodes.
- Healthcare cold-chain protocols:Temperature-sensitive biologics and vaccines require specialized express lanes with validated thermal packaging, expanding premium service tiers.
Market Restraints
- Aviation fuel cost volatility:Jet fuel represents the largest variable cost input for cross-border express operators, with price spikes directly compressing margin on time-definite international shipments.
- Pilot certification bottlenecks:FAA and EASA drone operator licensing timelines extend deployment schedules for beyond-visual-line-of-sight delivery corridors.
- Sorting hub concentration:Automated parcel handling capacity concentrates in Germany, Netherlands, and Kentucky, creating single-point vulnerability for transatlantic volume flows.
Strategic Opportunities
- India's e-commerce penetration gaps:Tier-two and tier-three cities remain underserved by integrated express networks, offering first-mover advantage for domestic operators building captive last-mile infrastructure.
- Battery-swapping standardization:Convergence of modular battery platforms with electric two-wheeler fleets enables rapid turnaround for urban delivery without charging downtime.
- CSRD supply-chain disclosure:The EU Corporate Sustainability Reporting Directive creates service demand for emissions-verified logistics as enterprises seek Scope 3 reduction partners.
Industry Challenges
- Sorting automation capex intensity:Robotic parcel handling systems require capital deployment exceeding legacy manual hub investments by multiples, straining mid-tier operator balance sheets.
- Legacy WMS integration friction:Warehouse management systems at established retailers resist API-based connectivity with carrier platforms, delaying real-time inventory visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Courier Express and Parcel (CEP) Market |
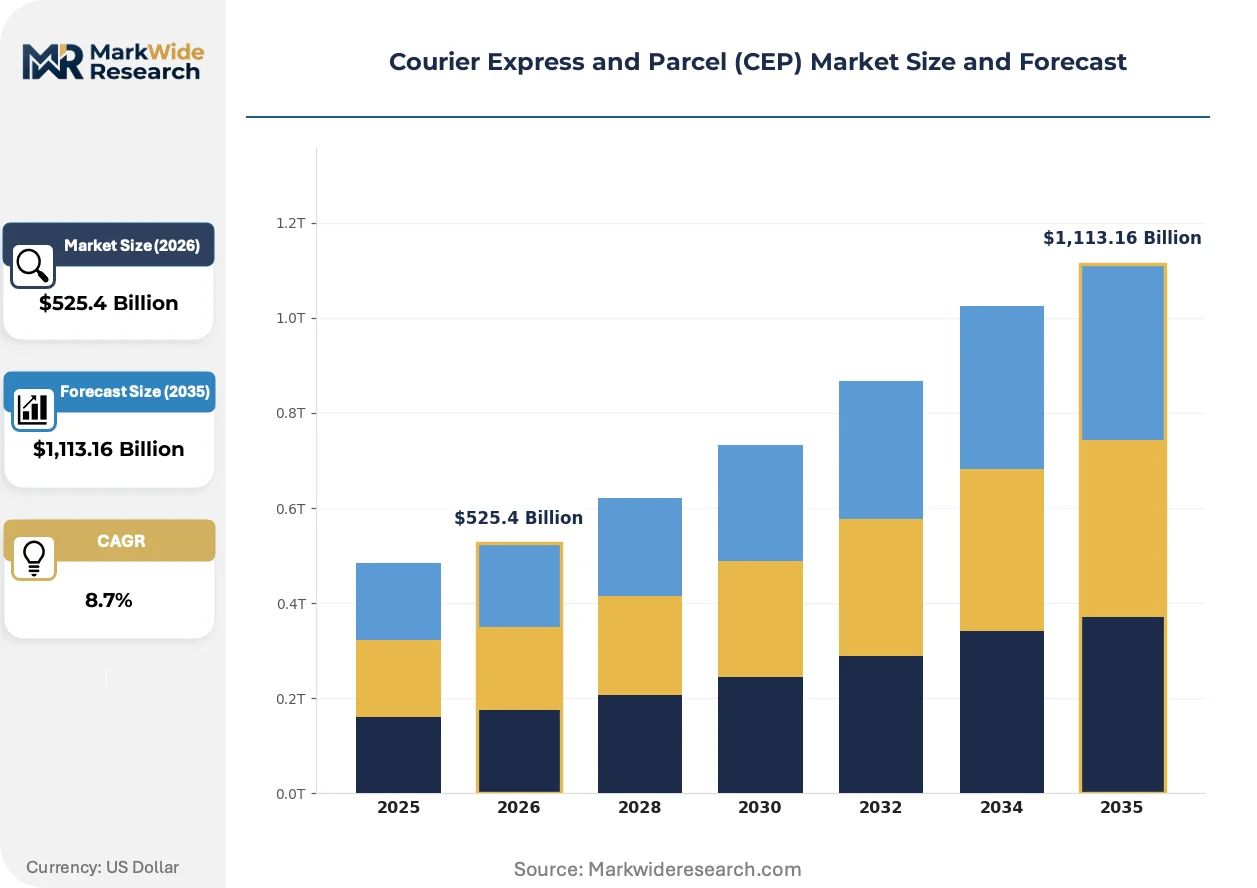
| Market Size in 2026 | $525.4 Billion |
| Market Size in 2035 | $1,113.16 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Next-Day Delivery, Standard Delivery, Expedited Delivery End User: E-commerce, Retail, Healthcare, Manufacturing Delivery Mode: Ground, Air, Sea, Drone Package Type: Parcel, Document, Freight, Envelope |
| Companies Covered | Deutsche Post DHL Group, Yamato Holdings Co., Ltd., United Parcel Service (UPS), Amazon Logistics, United States Postal Service (USPS), FedEx Corporation, SF Express, Aramex, DHL Express, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Courier Express and Parcel (CEP) Market Trends and Innovations
Autonomous ground and aerial systems are advancing from pilot programs toward operational scale, while regulatory frameworks simultaneously harden emissions accountability and data sovereignty requirements.
Autonomous delivery robots are expanding into sidewalk and campus environments across dense urban districts. Grocery and quick-commerce platforms in California and Texas are deploying these units for sub-five-pound payloads on fixed routes. The technology is expanding into regulated operational corridors as municipal permitting frameworks mature and liability protocols standardize.
The EU Green Deal's F-Gas Regulation is phasing out hydrofluorocarbon refrigerants in transport vehicles. Cold-chain operators must retrofit or replace refrigerated van fleets with alternative cooling systems before mandated deadlines. Express healthcare logistics serving temperature-sensitive biologics face the steepest compliance timelines and equipment conversion costs.
Merchant procurement of bundled first-mile and returns services is displacing standalone delivery contracts. E-commerce platforms in China's Yangtze River Delta now require reverse logistics integration as a table-stake qualification. This pattern is most visible among fashion and electronics verticals where return rates exceed thirty percent of forward volume.
Courier Express and Parcel (CEP) Market Segmentation
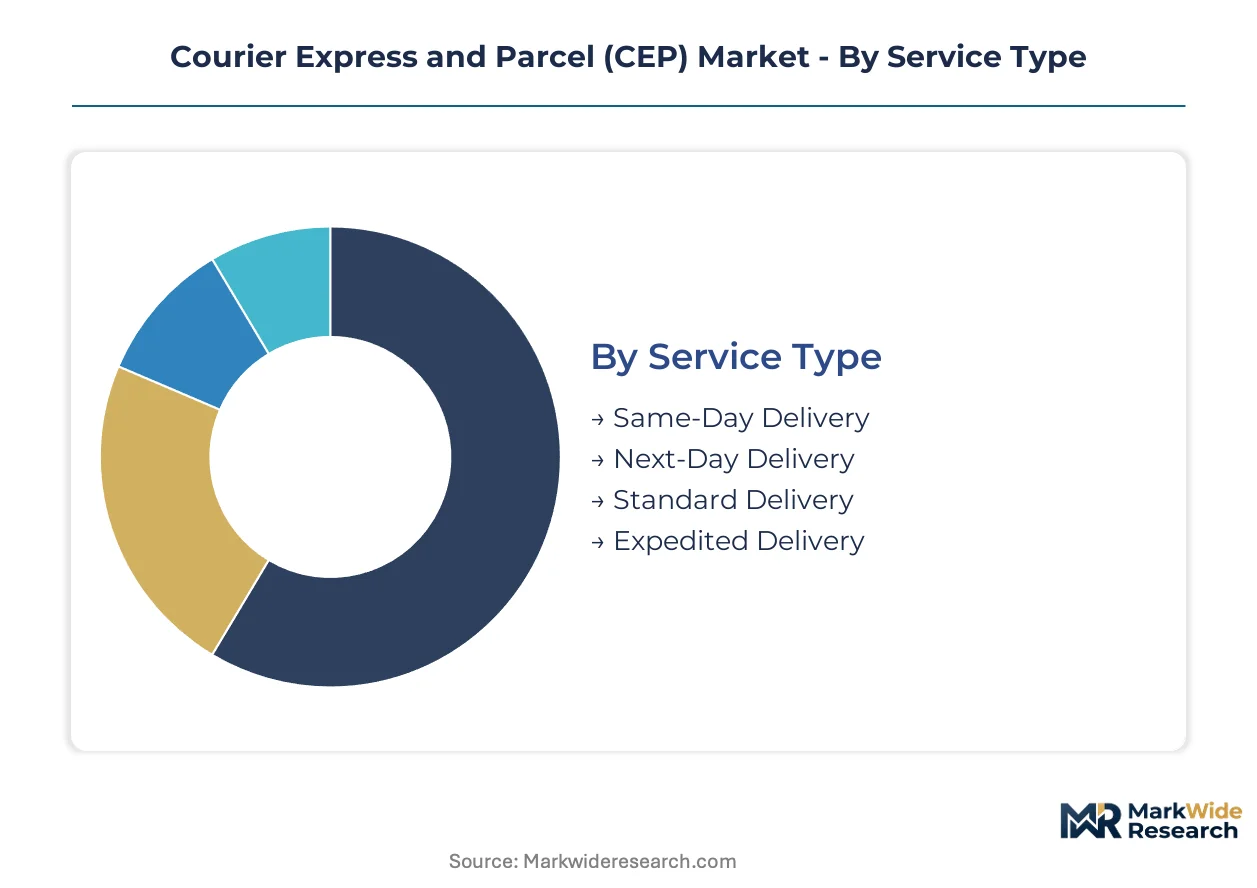
CEP operators configure service portfolios around velocity tiers and payload specifications. Each segmentation dimension carries distinct margin profiles and capital requirements. Procurement patterns diverge sharply across end-use verticals.
Service Type:
Customization intensity peaks at premium velocity tiers while standardization dominates volume segments. Same-day and next-day services require dedicated sortation infrastructure and dynamic routing algorithms.
- Same-Day Delivery:Hyperlocal hub networks and real-time dispatch systems compress fulfillment windows to under eight hours. Demand concentrates in China's Yangtze River Delta and California's Bay Area where e-commerce platforms absorb premium surcharges for speed-critical shipments.
- Next-Day Delivery:Overnight line-haul operations between regional sortation hubs guarantee morning delivery windows through integrated air-ground networks. Retail replenishment and healthcare specimen transport drive procurement in Germany and the United Kingdom.
- Standard Delivery:Two-to-five-day ground networks optimize cost per unit for non-urgent retail and manufacturing flows.
- Expedited Delivery:Time-definite international express lanes with customs pre-clearance serve cross-border e-commerce and urgent industrial parts.
Most installed capacity flows through Standard Delivery. Expansion is steepest in Same-Day Delivery.
End User:
Vertical-specific compliance requirements fragment service specifications across customer categories. Healthcare and manufacturing impose validation protocols that consumer-facing segments rarely require.
- E-commerce:Returns integration and flexible delivery windows dominate procurement criteria. Fashion and electronics verticals in India's tier-two cities are pulling investment into reverse logistics infrastructure as penetration gaps close.
- Healthcare:Temperature-controlled express lanes with chain-of-custody documentation serve biologics, vaccines, and diagnostic specimens. FDA and EMA validation requirements for cold-chain protocols create steep entry barriers.
- Retail:Store replenishment and direct-to-consumer fulfillment demand hybrid first-mile capabilities.
- Manufacturing:Just-in-time production lines require time-definite delivery of production-critical components.
Revenue concentration sits with E-commerce. Healthcare is climbing the fastest on margin contribution.
Delivery Mode:
Modal choice trades speed against emissions compliance and infrastructure access. Regulatory divergence between aviation and environmental agencies shapes deployment timelines.
- Ground:Electric van and two-wheeler fleets dominate urban last-mile under EU Green Deal fleet mandates. Battery-swapping standardization is emerging as a critical enabler for high-turnover urban operations.
- Air:Express freighter networks and belly-hold capacity guarantee intercontinental time-definite service. Jet fuel cost volatility directly compresses margin on cross-border premium shipments.
- Sea:Maritime parcel consolidation serves cost-sensitive non-urgent international flows.
- Drone:Beyond-visual-line-of-sight corridors remain restricted to FAA and EASA test zones outside limited operational deployments.
Ground infrastructure carries the highest installed base. Drone deployment is gaining share fastest where regulatory corridors open.
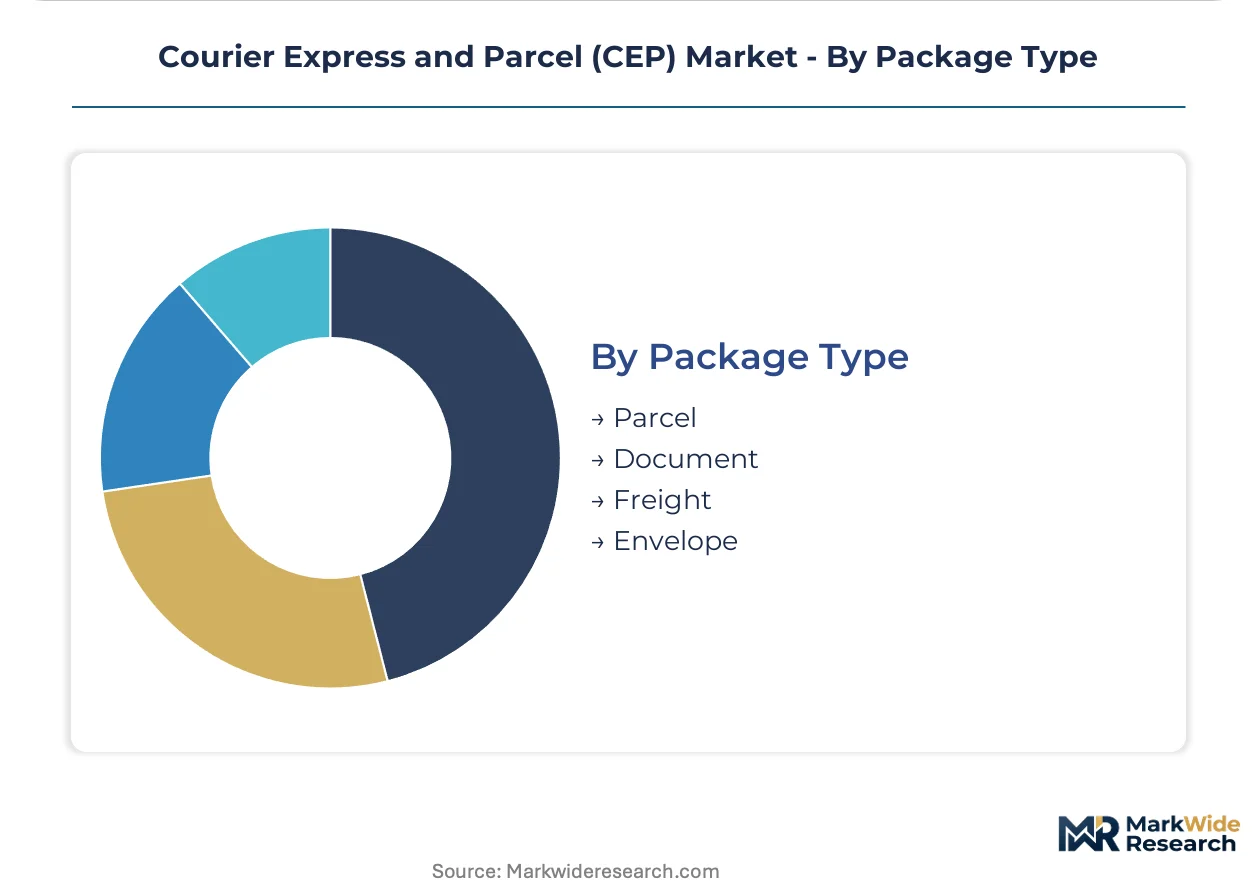
Package Type:
Physical form factor determines sortation automation compatibility and vehicle payload optimization. Document and envelope volumes are collapsing while parcel complexity increases.
- Parcel:Dimensional weight pricing and automated sortation handling define operational economics for e-commerce fulfillment. Robotic parcel handling systems in Germany and the Netherlands set throughput benchmarks.
- Document:Digital substitution has collapsed legacy express document volumes to niche legal and financial instrument flows.
- Freight:Palletized shipments between thirty and seventy kilograms blur into less-than-truckload territory.
- Envelope:Ultra-lightweight urgent correspondence retains premium pricing in select B2B corridors.
Parcel sortation absorbs the most capital deployment. Freight is expanding most quickly as e-commerce order sizes increase.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The courier express and parcel industry traces its modern lineage to the United States, where Federal Express pioneered overnight air-ground integration in the 1970s. German and Japanese operators subsequently developed dense ground networks that set efficiency benchmarks for regional parcel consolidation. Today, operational patterns diverge sharply across regulatory environments and urban density gradients.
United States
E-commerce volume concentration in California and Texas metropolitan corridors drives demand for same-day fulfillment infrastructure. FAA drone integration rules and EPA emissions standards for commercial fleets shape capital deployment timelines for last-mile automation. The Kentucky-Ohio sorting hub cluster processes transcontinental express volumes through automated handling systems.
Germany
Industrial manufacturing corridors in North Rhine-Westphalia and Bavaria generate time-definite component delivery requirements for automotive and machinery supply chains. The EU Green Deal's F-Gas Regulation and CO2 fleet mandates accelerate electric van procurement across Deutsche Post DHL's domestic network. The Leipzig-Halle air hub anchors European cross-border express flows.
China
Same-day delivery baselines in the Yangtze River Delta and Pearl River Delta city clusters pull investment into hyperlocal micro-fulfillment nodes. MIIT and SAMR enforce data-localization and vehicle-electrification mandates that determine platform architecture for domestic operators. Shenzhen and Shanghai sortation facilities set throughput benchmarks for robotic parcel handling.
Japan
Aging demographics and shrinking rural populations compress delivery density in peripheral prefectures while Tokyo-Osaka corridors maintain premium express volumes. METI standards for autonomous delivery systems guide pilot program expansion in dense urban districts. Yamato Holdings operates from the Kanto logistics cluster with integrated temperature-controlled capabilities.
India
Tier-two and tier-three city penetration gaps in Maharashtra and Karnataka create first-mover opportunities for domestic operators building captive last-mile infrastructure. BIS certification requirements for logistics equipment and DGFT trade facilitation protocols influence cross-border service configuration. Mumbai and Bengaluru e-commerce corridors absorb rising investment in reverse logistics integration.
Courier Express and Parcel (CEP) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service velocity tiers, with integrated network operators commanding pricing power in time-definite express segments. The vendor base stratifies into three functional layers: global integrators with owned air fleets, regional specialists with dense ground networks, and captive platforms with warehouse-to-door infrastructure. Consolidation pressure concentrates among mid-tier operators lacking scale for automated hub investment. Dominant competitive moves include fleet electrification partnerships and strategic acquisitions of last-mile technology providers.
Among integrated express specialists, Deutsche Post DHL Group and FedEx Corporation occupy positions at the premium-service tier, while Amazon Logistics exemplifies the captive infrastructure archetype. Deutsche Post DHL Group represents the global integrator model with cross-border network density. FedEx Corporation anchors healthcare cold-chain positioning through specialized temperature-controlled capabilities. Amazon Logistics demonstrates warehouse-to-door control through captive fulfillment infrastructure.
| Leading Market Players |
|---|
| Deutsche Post DHL Group |
| Yamato Holdings Co., Ltd. |
| United Parcel Service (UPS) |
| Amazon Logistics |
| United States Postal Service (USPS) |
| FedEx Corporation |
| SF Express |
| Aramex |
| DHL Express |
| Others |
Pricing and Supply Chain Analysis
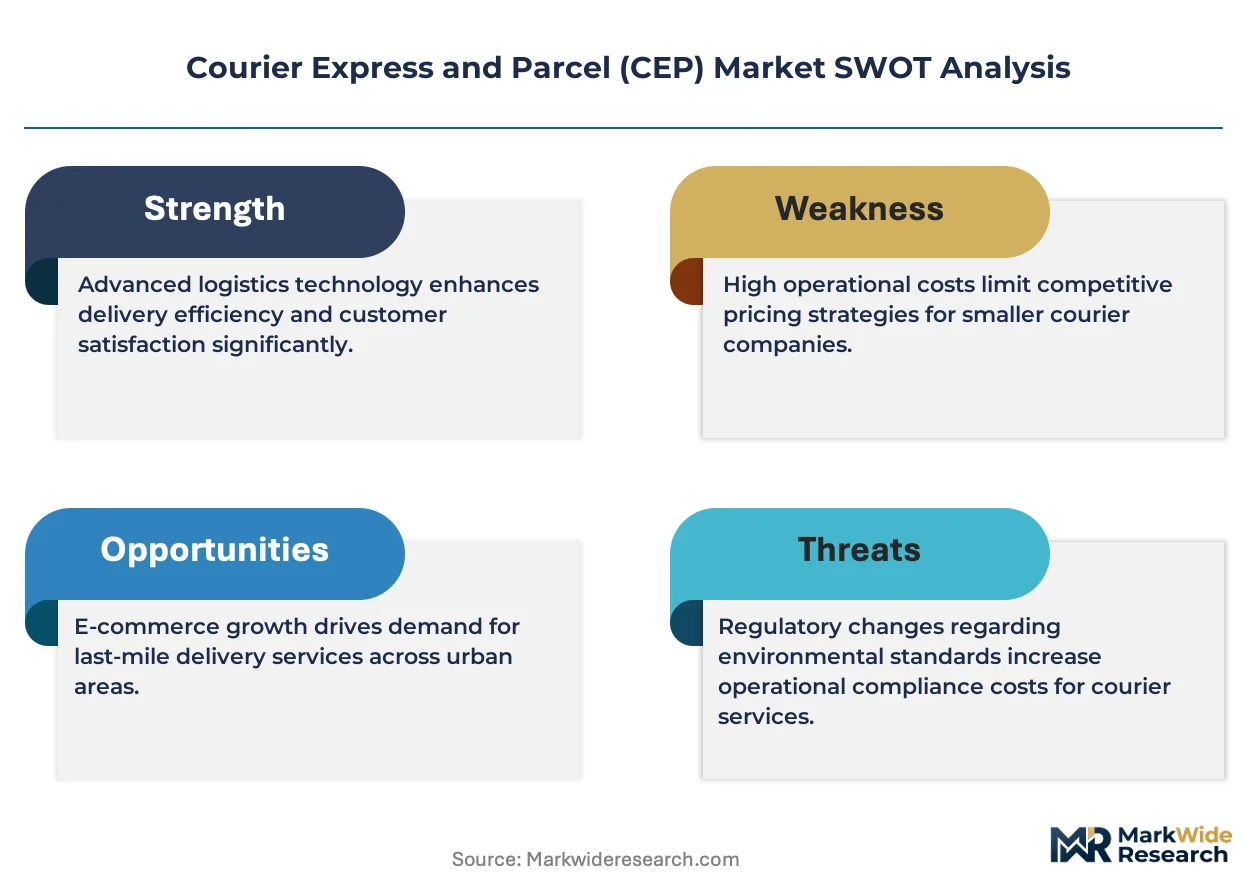
Jet fuel volatility cascades through cross-border express pricing tiers, with carriers passing cost spikes to time-definite international shipments while absorbing margin compression in contracted retail volumes. Electric van procurement under EU Green Deal mandates anchors premium last-mile rates in Germany and the Netherlands, where fleet conversion costs concentrate.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates same-day delivery surcharges from deferred ground rates. Price differentiation rests on velocity guarantees and emissions-verified service tiers, with healthcare cold-chain protocols commanding the widest spreads. Cost compression in standard delivery is intensifying because e-commerce platforms consolidate volume through captive warehouse networks. Small and mid-sized retailers exhibit highest price sensitivity, while pharmaceutical shippers absorb premium surcharges for validated thermal packaging.
Supply Chain Analysis
Dual-sourcing requirements from major e-commerce platforms mandate multi-carrier qualification across first-mile, line-haul, and returns legs. Automated sorting capacity concentrates in Germany, the Netherlands, and Kentucky, with robotic parcel handling systems drawing from German engineering and Chinese manufacturing inputs. Single-point vulnerability at transatlantic hub clusters poses structural risk to cross-border volume flows. Distribution runs through integrated air-ground networks for premium tiers and dedicated ground fleets for standard delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Courier Express and Parcel sector presents a late-cycle quality story as e-commerce merchants shift procurement criteria toward bundled first-mile and returns integration with emissions-verified service tiers.
For Market Incumbents: Anticipate margin pressure from Amazon Logistics' captive warehouse-to-door infrastructure by accelerating fleet electrification partnerships in EU member states and securing long-term renewable fuel offtakes for express freighter networks. Reinforce hub automation investments in Germany and Kentucky to defend throughput advantages against mid-tier operators lacking capital for robotic parcel handling systems. For New Entrants and Emerging Players: The premium-economy price-point gap in India's tier-two and tier-three cities offers white-space entry through battery-swapping electric two-wheeler fleets and localized micro-fulfillment nodes. Target Maharashtra and Karnataka e-commerce corridors with reverse logistics integration as the primary go-to-market angle, leveraging BIS certification requirements as a qualification barrier against unqualified competitors. For Investors and Strategic Acquirers: Roll-up economics work for regional ground specialists with dense last-mile networks because automated hub concentration has stranded mid-tier operators lacking scale for capital-intensive sortation investments. Long-term viability favors acquisition targets with established electric fleet deployment and API-native warehouse management connectivity. Watch FAA beyond-visual-line-of-sight drone corridor approvals as the signal indicating regulatory inflection for autonomous delivery scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | EU Green Deal CO2 mandates accelerate zero-emission van procurement across member state operations. |
| Automated Hub Investment | German and Dutch robotic parcel handling systems set throughput benchmarks for transatlantic volume flows. |
| Reverse Logistics Integration | China's Yangtze River Delta e-commerce platforms mandate returns management as table-stake qualification. |
| Battery-Swapping Standardization | Modular electric two-wheeler platforms enable rapid urban turnaround without charging downtime penalties. |
| Cold-Chain Certification Pathway | FDA and EMA validation requirements create steep entry barriers for healthcare express service tiers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with logistics procurement directors, fleet operations managers, e-commerce platform supply chain leads, and regulatory affairs specialists at express carriers with secondary validation from EU transport emissions databases, FAA drone integration filings, customs trade flow records, and SEC 10-K disclosures from listed operators. Bottom-up volume modeling and top-down macroeconomic anchoring provided cross-check triangulation.
Comparable historical periods anchored the projection horizon to observed demand elasticity during prior fuel price cycles and regulatory phase-in timelines. Segmentation dimensions modeled include service velocity tier, end-use vertical, delivery mode, and geographic regulatory cluster, with CAGRs derived from elasticity-adjusted volume trajectories and pricing power assessments. Forecast inputs incorporated jet fuel cost assumptions, electric vehicle adoption curves, and e-commerce penetration rates across tiered city classifications.
Caveats apply where aviation fuel cost spikes, drone regulatory delays, or sorting hub capacity constraints could materially shift the outlook. Deviation in EU Green Deal enforcement timelines or FAA beyond-visual-line-of-sight approval schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Global Ecommerce Platform Market
E-Commerce Solutions
North America Automotive E-Commerce Market
E-Commerce Solutions
Sweden E-Commerce Market
E-Commerce Solutions
E-Commerce Fulfillment Services Market
E-Commerce Solutions
Italy E-Commerce Market
E-Commerce Solutions
Online Apparel Retailing Market
E-Commerce Solutions
Iceland E-Commerce Market
E-Commerce Solutions
China E-Commerce Market
E-Commerce Solutions
Japan Cross Border E Commerce Market
E-Commerce Solutions
Slovak Republic E-Commerce Market
E-Commerce Solutions
Switzerland E-Commerce Market
E-Commerce Solutions
Multi-Channel E-Commerce Software Market
E-Commerce Solutions
UAE Q-Commerce Industry Market
E-Commerce Solutions
E-Commerce Technology Market
E-Commerce Solutions
Serbia E-Commerce Market
E-Commerce Solutions
Nigeria Alcohol E-Commerce Market