
 Wide Area Network Optimization Market | 2026-2036
Wide Area Network Optimization Market Size, Share, and Industry Trends Forecast 2026-2036
Wide Area Network Optimization Market Intelligence
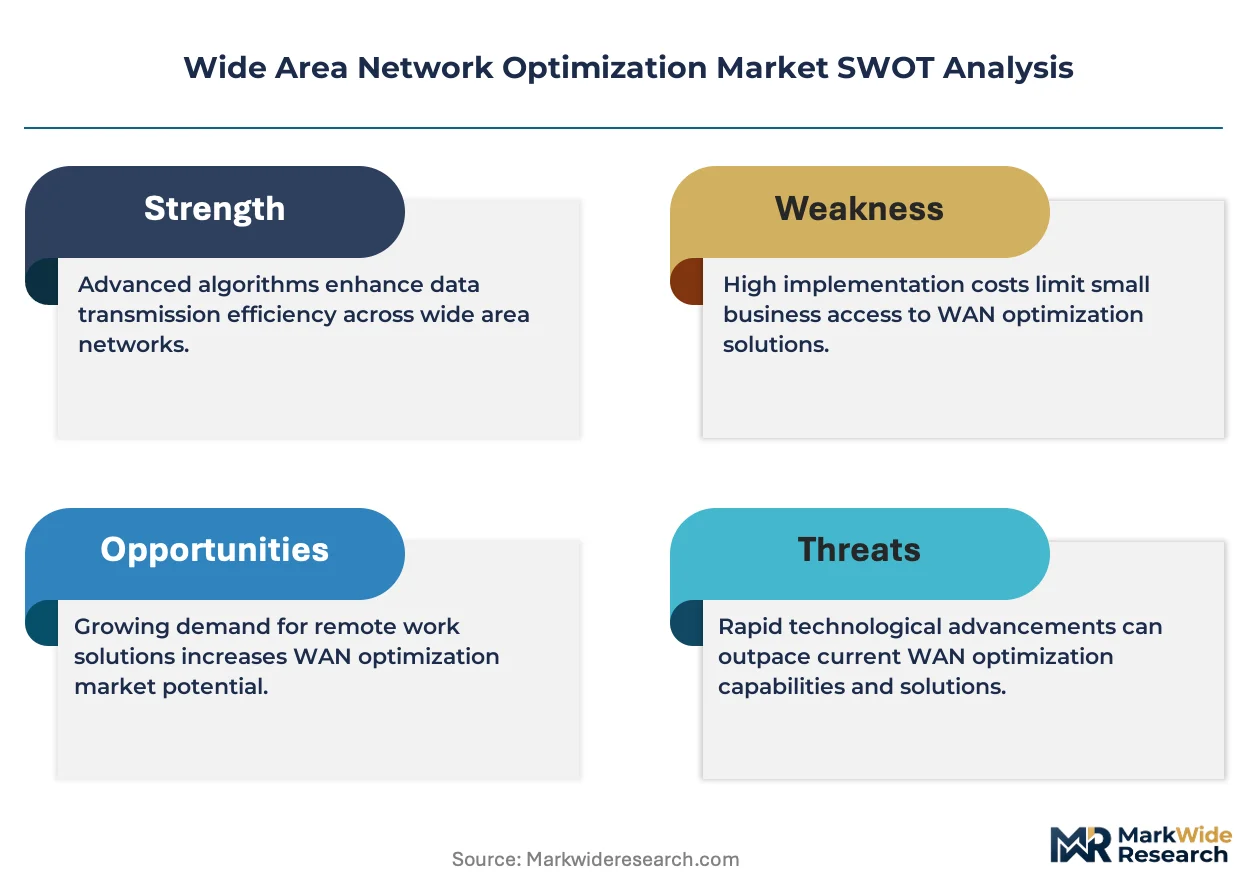
Project finance and equipment-leasing structures for WAN optimization infrastructure is narrowing the competitive field to vendors with strong balance sheets and flexible delivery models. Cisco Systems leverages its global channel network to sustain enterprise deployments across hybrid cloud environments. Riverbed Technology specializes in application-aware acceleration for remote workforce connectivity. Aryaka Networks competes through its managed SD-WAN service model that reduces capital requirements for mid-market buyers.
Wide Area Network Optimization encompasses hardware appliances, software controllers, and cloud-delivered services that compress traffic, deduplicate data streams, and route packets across geographically distributed links using path-selection algorithms and quality-of-service policies. The technology serves commercial and industrial users by ensuring predictable application performance across branch-to-datacenter and branch-to-cloud connectivity. Cloud-based deployment models are capturing the fastest growth as enterprises retire capex-heavy appliance estates, while on-premise installations retain margin pools in regulated sectors with data residency requirements. SD-WAN application segments are displacing traditional MPLS backbones, and software solutions within the technology dimension are expanding faster than purpose-built hardware as virtualization matures.
The Federal Communications Commission shapes US market access through net-neutrality and broadband infrastructure rules that affect last-mile optimization strategies, while the EU AI Act and GDPR impose algorithmic transparency and data-localization constraints on traffic-inspection features. Enterprises must evaluate how NIS2 Directive cybersecurity mandates across Europe will alter vendor qualification criteria and procurement specifications. Stakeholders should monitor whether emerging quantum-resistant encryption standards will trigger refresh cycles in existing WAN optimization estates.
Market Dynamics
Cloud-native SD-WAN architectures are compressing deployment cycles and forcing incumbent appliance vendors to restructure delivery models around subscription economics.
Growth Catalysts
- EU AI Act compliance mandates:Network traffic inspection tools must demonstrate algorithmic transparency, driving replacement of opaque legacy optimization engines in European financial services corridors.
- Industrial automation clusters in Germany:Smart manufacturing deployments require sub-10 millisecond latency guarantees that conventional MPLS backbones cannot provision.
- Remote workforce permanence:Distributed application access patterns have normalized branch-to-cloud traffic flows that exceed traditional hub-and-spoke optimization design limits.
Market Restraints
- Semiconductor supply concentration:Purpose-built packet-processing silicon depends on Taiwan-based foundry capacity with 26-week lead times extending hardware refresh cycles.
- GDPR data-localization friction:Traffic deduplication engines that inspect payload content face jurisdictional constraints on cross-border data stream analysis.
- Open-source routing stack substitution:DPDK and VPP software libraries enable in-house development of basic acceleration functions, eroding mid-market appliance attach rates.
Strategic Opportunities
- NIS2 Directive cybersecurity procurement:European critical infrastructure operators must requalify vendors against mandatory incident-response and encryption standards by late 2024.
- Edge computing convergence:WAN optimization controllers collocated with 5G multi-access edge computing nodes enable localized application acceleration for autonomous vehicle telemetry.
- Managed service channel expansion:Mid-market enterprises lacking internal network engineering capacity represent an addressable segment for fully outsourced SD-WAN operations.
Industry Challenges
- Multi-vendor orchestration complexity:Heterogeneous estates mixing Cisco, VMware, and cloud-native controllers require custom API integration that extends deployment timelines.
- Quantum-resistant certificate migration:NIST post-quantum cryptographic standards will force wholesale replacement of RSA-based tunnel encryption without backward compatibility paths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wide Area Network Optimization Market |
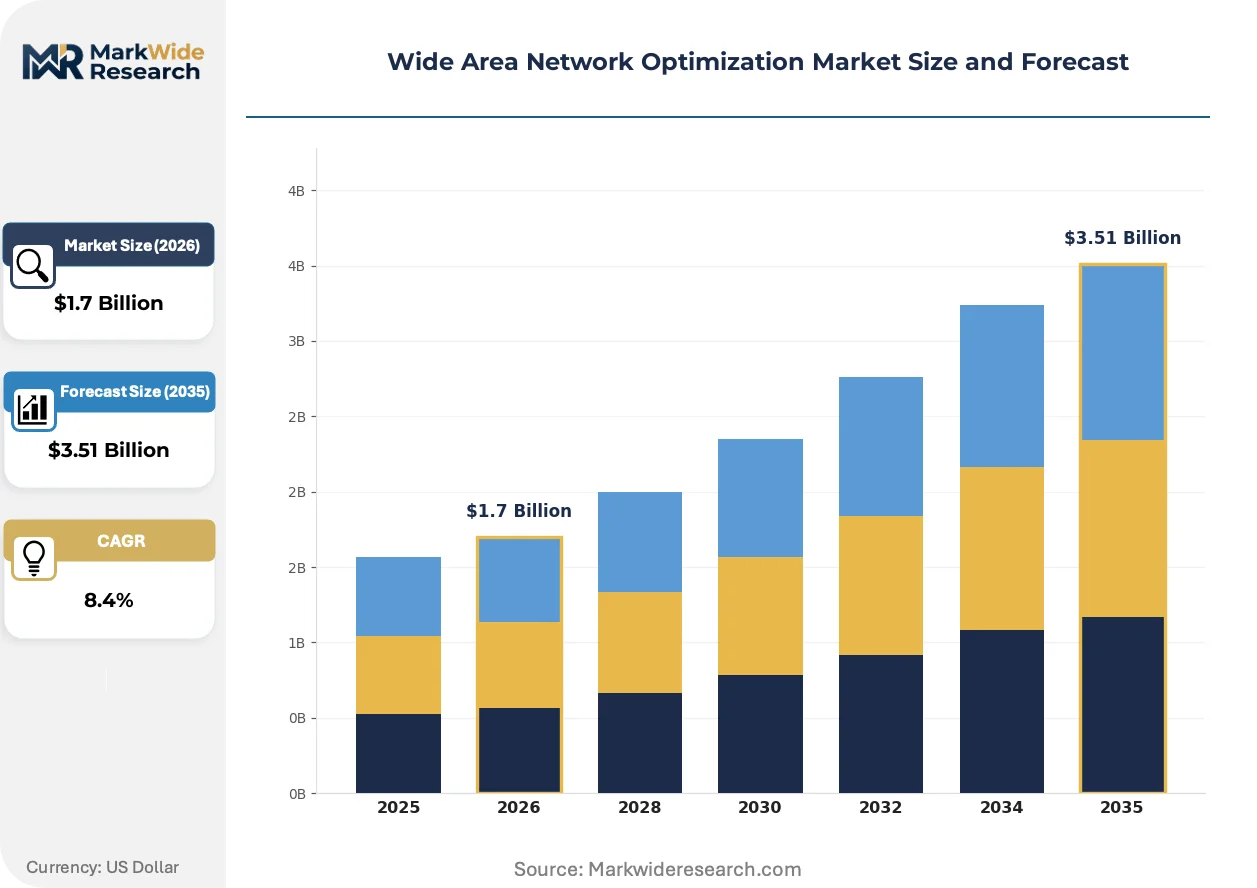
| Market Size in 2026 | $1.7 Billion |
| Market Size in 2035 | $3.51 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
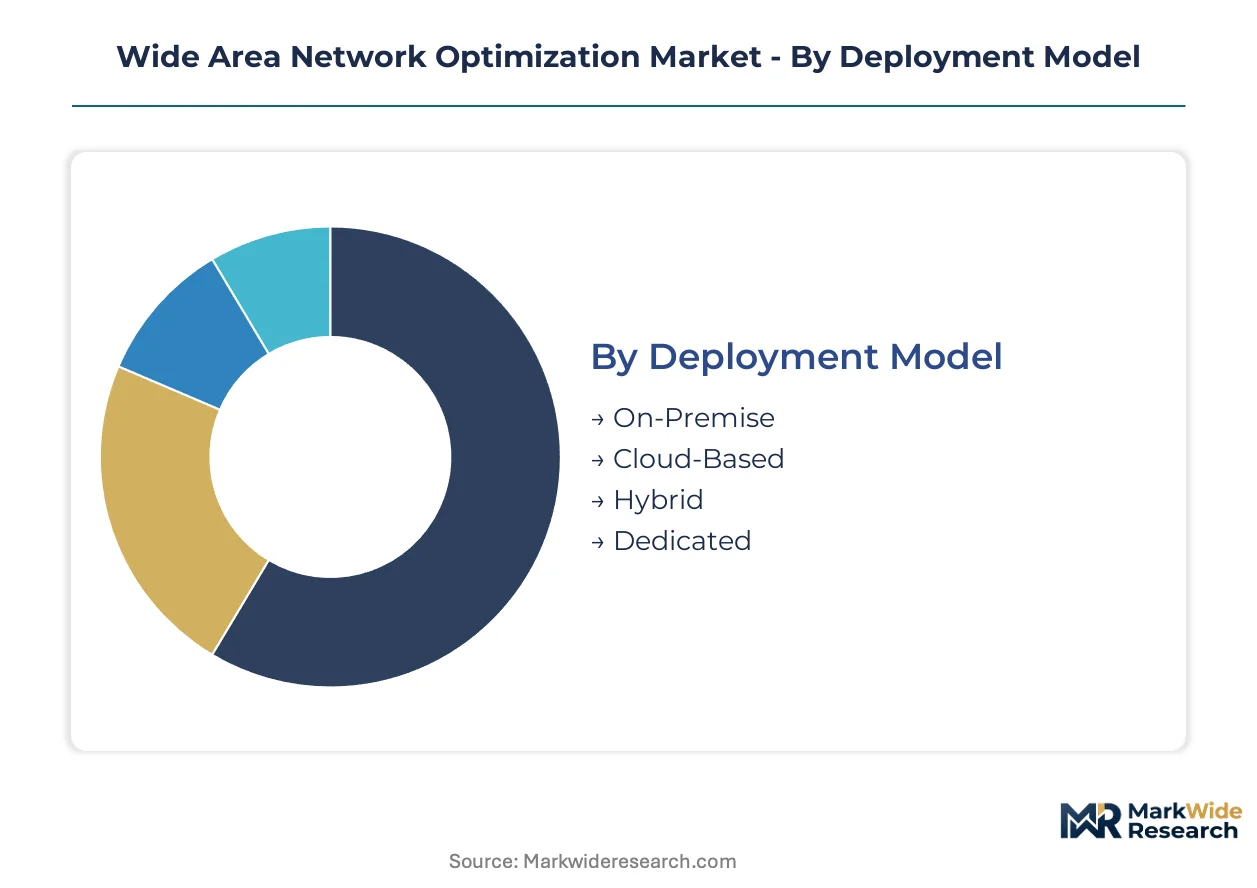
| Segmentation | Deployment Model: On-Premise, Cloud-Based, Hybrid, Dedicated Application: Enterprise Connectivity, Remote Access, Branch Networking, SD-WAN End User: SMEs, Large Enterprises, Telecommunication Companies, Managed Service Providers Technology: WAN Optimization Appliances, Software Solutions, Network Management Tools, Virtual WANs |
| Companies Covered | Cisco Systems, Riverbed Technology, Citrix Systems, Fortinet, VMware, Hewlett Packard Enterprise, Broadcom, Aryaka Networks, FatPipe Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wide Area Network Optimization Market Strategic Shifts & Innovations
Traffic management intelligence is relocating from dedicated hardware to distributed software layers, compressing vendor margins while expanding addressable use cases beyond traditional enterprise boundaries.
Application-aware path selection is migrating from static policy engines to machine-learning models that predict link degradation before congestion manifests. Financial trading firms in Frankfurt and Singapore deploy these predictive controllers to maintain order-entry latency below exchange-mandated thresholds. The shift is compressing differentiation around proprietary hardware acceleration toward data science and telemetry integration capabilities.
The EU AI Act imposes documentation requirements on algorithmic traffic-routing decisions that affect quality-of-service outcomes. Vendors must maintain audit trails for path-selection logic that prioritizes specific application flows. European managed service providers are responding by separating control-plane AI functions into sovereign cloud instances with localized model training.
Enterprise sourcing patterns now favor consumption-based licensing that scales with measured application throughput rather than provisioned link capacity. Channel partners in the United States are replacing perpetual-license resale with recurring revenue managed service arrangements. This reconfiguration is most visible among healthcare systems consolidating dozens of acquired hospital networks onto unified cloud-delivered WAN fabrics.
Wide Area Network Optimization Market Segmentation
Segmentation in the WAN optimization market reflects divergent procurement economics and operational constraints across deployment architectures, application workloads, and buyer sophistication tiers. Understanding these divisions reveals where vendor margins concentrate and where growth trajectories diverge.
Deployment Model:
Cost tier differentiation separates capex-intensive perpetual ownership from opex-scalable consumption models, with procurement patterns varying sharply by buyer balance sheet capacity and compliance exposure.
- On-Premise:Physical appliances deployed within customer data centers deliver deterministic performance through dedicated packet-processing hardware. Financial services firms in Frankfurt and Singapore maintain these estates to satisfy data residency mandates and sub-millisecond latency requirements for trading infrastructure.
- Cloud-Based:Controller software delivered as a service eliminates hardware refresh cycles and shifts optimization intelligence to distributed points of presence. Healthcare systems across the United States are consolidating acquired hospital networks onto unified cloud-delivered fabrics to reduce network engineering headcount.
- Hybrid:Split deployments retain on-premise appliances for latency-sensitive traffic while routing burst workloads through cloud gateways. Manufacturing clusters in Germany deploy this architecture to balance deterministic shop-floor connectivity with flexible cloud ERP access.
- Dedicated:Single-tenant managed infrastructure provisioned for regulated industries with strict isolation requirements. Managed service providers in London and Zurich market these deployments to private banking clients facing EU AI Act audit obligations.
On-Premise commands the established base. The steepest expansion runs through Cloud-Based.
Application:
Volume concentration tracks the migration from traditional hub-and-spoke architectures toward distributed cloud access patterns that exceed legacy optimization design limits.
- Enterprise Connectivity:Campus-to-datacenter and campus-to-campus optimization for headquarters, regional offices, and recovery sites. Large manufacturing conglomerates in Japan maintain these deployments to synchronize ERP systems across domestic production facilities.
- Remote Access:Acceleration of application delivery to distributed workforces through client software or virtual desktop infrastructure. The permanence of hybrid work arrangements in North American professional services has normalized branch-to-cloud traffic flows that strain conventional MPLS backbones.
- Branch Networking:Lightweight optimization at retail locations, bank branches, and field offices with limited local IT support. Quick-service restaurant chains in the United Kingdom deploy these solutions to centralize point-of-sale transaction processing.
- SD-WAN:Software-defined overlay networks that displace MPLS with intelligent path selection across broadband, LTE, and satellite links. Telecommunication companies in India are bundling managed SD-WAN services to capture enterprise customers seeking alternatives to expensive international private leased circuits.
Enterprise Connectivity retains the revenue base. SD-WAN is climbing the fastest as MPLS displacement accelerates.
End User:
Customer type determines whether procurement flows through direct vendor relationships, carrier intermediaries, or outsourced managed service arrangements.
- SMEs:Mid-market enterprises with limited network engineering capacity that favor fully managed service delivery over in-house appliance management. Regional healthcare clinics in Australia are adopting this procurement model to avoid capital expenditure on dedicated infrastructure.
- Large Enterprises:Multinational organizations with internal network operations centers that negotiate direct vendor relationships and customize optimization policies. Automotive manufacturers with production facilities spanning Germany, Mexico, and China maintain these capabilities.
- Telecommunication Companies:Carriers that integrate WAN optimization into managed network service portfolios sold to enterprise customers. Incumbent operators in France and Spain are repositioning legacy MPLS offerings as SD-WAN bundles to defend enterprise relationships.
- Managed Service Providers:Third-party outsourcers that assume full operational responsibility for customer WAN infrastructure under multi-year contracts. Specialist providers in Singapore and Dubai are expanding regional footprints to serve financial services clients establishing trading operations in Asian and Middle Eastern corridors.
Large Enterprises command the established base. Managed Service Providers are gaining share fastest as mid-market outsourcing demand intensifies.
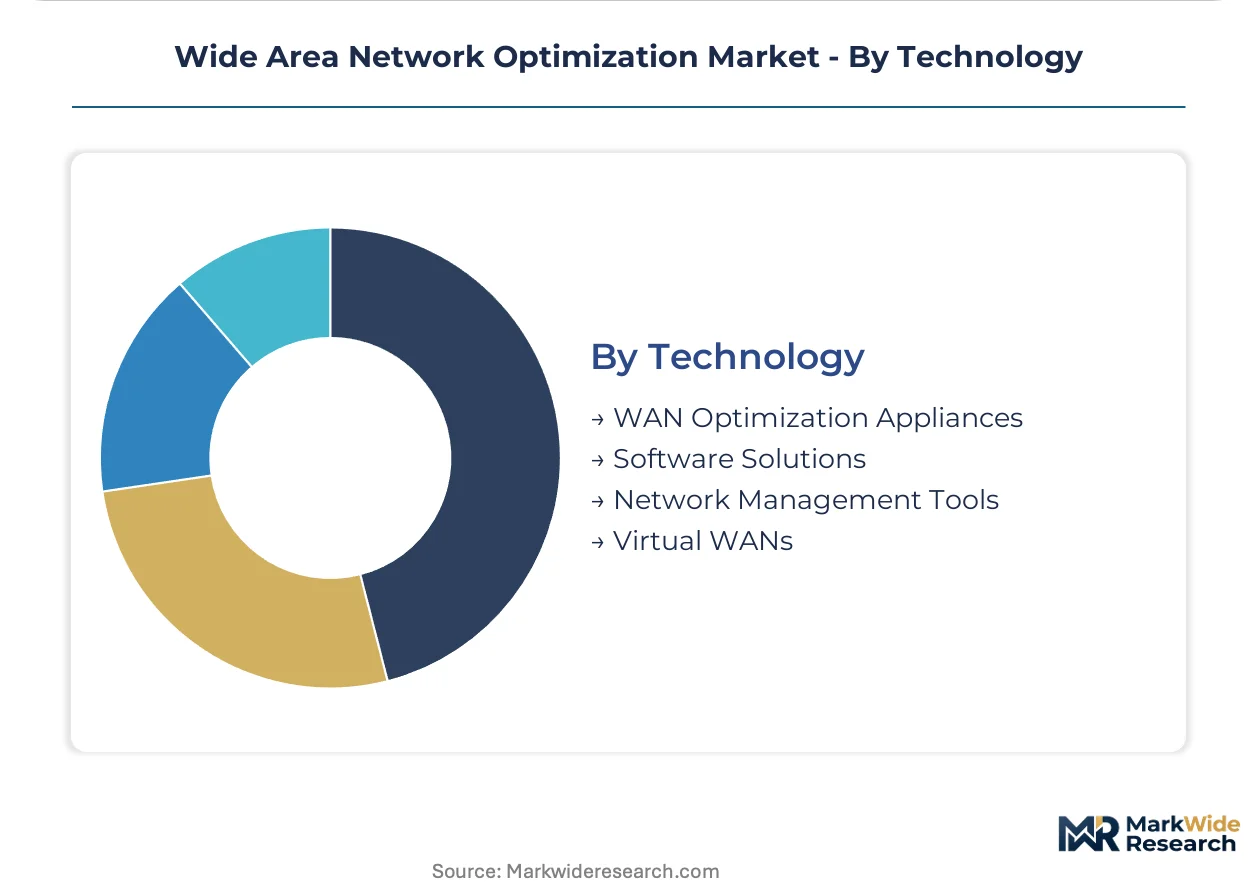
Technology:
Maturity curves separate purpose-built hardware from virtualized and cloud-native implementations, with margin pools shifting toward software layers as packet processing commoditizes.
- WAN Optimization Appliances:Purpose-built hardware devices with dedicated silicon for compression, deduplication, and protocol acceleration. Regulated sectors with data residency requirements in Switzerland and Saudi Arabia retain these deployments despite cloud migration trends elsewhere.
- Software Solutions:Virtualized controllers running on standard x86 servers or hyperconverged infrastructure within customer premises. Enterprise data centers in the Netherlands are standardizing on these implementations to collapse network function silos onto unified compute platforms.
- Network Management Tools:Orchestration and monitoring platforms that provide visibility across heterogeneous optimization estates without performing inline traffic manipulation. IT organizations managing Cisco, VMware, and cloud-native controller mixtures in the United States deploy these tools to reduce multi-vendor integration complexity.
- Virtual WANs:Cloud-native overlay networks that abstract physical connectivity into software-defined paths without dedicated customer premises equipment. Development teams in Bangalore and São Paulo are adopting these architectures to accelerate access to cloud-hosted development environments.
WAN Optimization Appliances command the established base. Software Solutions are expanding most quickly as virtualization matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act and NIS2 Directive are redirecting procurement specifications across European data corridors, while industrial automation clusters in Germany and financial trading hubs in Singapore generate concentrated demand for sub-10 millisecond latency guarantees.
United States
Healthcare systems consolidating acquired hospital networks onto unified cloud-delivered WAN fabrics represent a primary demand source. The FCC shapes market access through net-neutrality and broadband infrastructure rules affecting last-mile optimization strategies. Greater Boston and the Pacific Northwest host development teams adopting cloud-native overlay architectures for cloud-hosted development environments.
Germany
Smart manufacturing deployments in industrial automation clusters require deterministic connectivity that conventional MPLS backbones cannot provision. The EU AI Act imposes algorithmic transparency mandates on network traffic inspection tools, forcing replacement of opaque legacy optimization engines. Manufacturing clusters in Bavaria and Baden-Württemberg deploy hybrid architectures balancing deterministic shop-floor connectivity with flexible cloud ERP access.
Singapore
Financial trading firms deploying predictive controllers to maintain order-entry latency below exchange-mandated thresholds drive specialized demand. The Monetary Authority of Singapore's cybersecurity guidelines influence vendor qualification criteria for financial services infrastructure. Specialist managed service providers are expanding regional footprints to serve financial services clients establishing trading operations in Asian corridors.
United Kingdom
Quick-service restaurant chains and retail banking networks require lightweight optimization at locations with limited local IT support. GDPR data-localization constraints affect traffic deduplication engines that inspect payload content across jurisdictions. London-based managed service providers market dedicated single-tenant infrastructure to private banking clients facing EU AI Act audit obligations.
India
Telecommunication companies bundle managed SD-WAN services to capture enterprise customers seeking alternatives to expensive international private leased circuits. TRAI regulations shape competitive dynamics in enterprise connectivity markets. Development teams in Bangalore adopt cloud-native overlay architectures to accelerate access to cloud-hosted development environments.
Wide Area Network Optimization Market Key Industry Players
On the supply side, the industry is consolidating around vendors with strong balance sheets and flexible delivery models capable of sustaining project finance and equipment-leasing structures. The competitive field narrows to three strategic archetypes: global networking incumbents with channel scale, specialists in application-aware acceleration, and managed service providers reducing capital requirements for mid-market buyers. Dominant competitive moves include restructuring delivery models around subscription economics and expanding managed service channel partnerships to capture outsourcing demand.
Within the global networking tier, Cisco Systems and VMware occupy positions anchored by enterprise channel scale and hybrid cloud integration capabilities. Riverbed Technology exemplifies the application-aware specialization archetype, while Aryaka Networks represents the managed service model reducing capital requirements for mid-market buyers. These three companies collectively illustrate how vendor positioning stratifies across hardware-centric, software-defined, and fully outsourced delivery vectors.
| Leading Market Players |
|---|
| Cisco Systems |
| Riverbed Technology |
| Citrix Systems |
| Fortinet |
| VMware |
| Hewlett Packard Enterprise |
| Broadcom |
| Aryaka Networks |
| FatPipe Networks |
| Others |
Cost & Logistics Intelligence
Undercapacity at Taiwan-based foundry facilities is compressing hardware refresh cycles and elevating pricing power for vendors with secured wafer allocations, while subscription economics in cloud-native delivery models are displacing perpetual-license revenue streams.
Pricing Analysis
Deployment architecture creates the primary spread between on-premise perpetual licenses and cloud-based consumption tiers. Pricing stratifies across dedicated appliance ownership, virtualized software subscriptions, and fully managed service bundles, with customization levels for EU AI Act compliance commanding material premiums. Cost compression in mid-market hardware tiers is intensifying because open-source DPDK libraries enable in-house acceleration development. Telecommunication companies exhibit the highest price sensitivity due to thin margin pressure on bundled SD-WAN services, while private banking clients in Zurich and London demonstrate lowest sensitivity given regulatory audit requirements.
Supply Chain Analysis
Taiwan Semiconductor Manufacturing Company and United Microelectronics Corporation hold dominant capacity for purpose-built packet-processing silicon. Hardware assembly concentrates in Taiwan, China, and Mexico, with software development distributed across engineering clusters in Bangalore, São Paulo, and Greater Boston. Raw material dependencies center on advanced node wafers, high-speed memory modules, and specialized networking ASICs. Single-source vulnerability in Taiwan-based foundry capacity presents structural concentration risk. Distribution runs through direct vendor relationships for large enterprises, carrier intermediaries for telecommunication companies, and specialist managed service providers for mid-market outsourcing demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wide Area Network Optimization sits in early-cycle expansion as cloud-native SD-WAN architectures displace legacy MPLS backbones and normalize branch-to-cloud traffic patterns that exceed traditional hub-and-spoke design limits.
For Market Incumbents: Pre-empt margin erosion from open-source routing stack substitution by deepening software-defined control plane capabilities and securing NIS2 Directive certification ahead of European critical infrastructure requalification deadlines. Accelerate managed service channel partnerships to capture mid-market outsourcing demand before specialist providers consolidate regional footprints.
For New Entrants and Emerging Players: Pursue white-space opportunities in sovereign cloud instances for EU AI Act compliance, where algorithmic transparency mandates require localized model training separated from global control planes. Target regional healthcare clinics in Australia and quick-service restaurant chains in the United Kingdom with fully outsourced SD-WAN operations that eliminate capital expenditure burdens.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native delivery models as virtualization collapses dedicated hardware requirements. Long-term viability favors vendors with recurring revenue composition exceeding perpetual-license legacy exposure. Acquisition target archetype: managed service providers with established NIS2 Directive compliance frameworks and existing relationships with European critical infrastructure operators. Monitor semiconductor supply allocation announcements from Taiwan-based foundries as inflection indicator for hardware-dependent vendor margin pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Subscription economics displace perpetual licenses across healthcare systems consolidating acquired hospital networks. |
| EU AI Act Compliance Certification | Algorithmic transparency mandates force replacement of opaque legacy optimization engines in Frankfurt trading corridors. |
| Managed Service Channel Expansion | Fully outsourced SD-WAN operations capture mid-market enterprises lacking internal network engineering capacity. |
| Edge Computing Node Collocation | Controllers at 5G multi-access edge computing sites enable localized acceleration for autonomous vehicle telemetry. |
| Quantum-Resistant Encryption Migration | NIST post-quantum cryptographic standards trigger wholesale refresh of RSA-based tunnel encryption estates. |
Research Approach
Findings reconcile primary fieldwork against secondary review of vendor SEC filings, hyperscaler capex disclosures, and TRAI regulatory notices. Primary interviews engaged network operations directors at automotive manufacturers, procurement leads at telecommunication companies, and channel partners distributing Cisco and VMware portfolios. Secondary validation drew from FCC broadband infrastructure reports, EU AI Act implementation guidance, and customs data tracking networking equipment imports. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Forecast inputs include deployment model adoption curves, application workload migration patterns, and end-user procurement channel shifts. Segmentation dimensions span deployment architecture, application type, buyer sophistication tier, and technology maturity curve. CAGRs derive from logistic diffusion modeling of SD-WAN displacement against MPLS backbones, calibrated against semiconductor supply constraints and regulatory compliance timeline acceleration.
Sensitivities concentrate around Taiwan foundry capacity allocation shifts, EU AI Act enforcement variance across member states, and quantum-resistant encryption standard finalization. Forecasts reflect documented assumptions on cloud migration velocity and managed service penetration rates. Quarterly review of NIS2 Directive vendor requalification progress and hyperscaler edge computing capex announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Broadband Network Gateway Market
Data Center and Networking
Mobile Data Offload Market
Data Center and Networking
Cluster Computing Market
Data Center and Networking
Datacenter Network Consulting and Integration Service Market
Data Center and Networking
Vietnam Data Center Server Market
Data Center and Networking
Mexico Data Center Networking Market
Data Center and Networking
Global Database Management System (DBMS) Market
Data Center and Networking
Global Internet Protocol Television (IPTV) CDN Market
Data Center and Networking
Austria Data Center Networking Market
Data Center and Networking
Virtual Data Optimizer Market
Data Center and Networking
GPU Database Market
Data Center and Networking
Graph Database Market
Data Center and Networking
Communications Service Provider (CSP) Network Market
Data Center and Networking
Brazil Optical Transceiver Market
Data Center and Networking
China Data Center Networking Market
Data Center and Networking
Software Defined Video Networking Market