
 Portable Fire Extinguisher Market | 2026-2036
Portable Fire Extinguisher Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Fire Extinguisher Market Intelligence
Data center construction is restructuring demand patterns across the portable fire extinguisher landscape. Amerex Corporation leverages its clean-agent specialization to capture premium contracts in hyperscale server farms. Kidde sustains broad retail penetration through big-box distribution networks. Yamato Protec Corporation anchors its position in East Asian manufacturing corridors with localized production lines.
A portable fire extinguisher is a handheld, pressurized vessel containing an extinguishing agent—typically dry chemical powder, carbon dioxide, aqueous film-forming foam, or water—designed for immediate deployment on incipient-stage fires in commercial, industrial, or vehicular settings. Dry chemical units occupy the largest volume share due to their versatility across Class A, B, and C fire scenarios, though CO2 systems command higher margins in electronics-sensitive environments. The commercial application segment leads absolute demand as office complexes and retail chains execute mandatory retrofit programs. Wall-mounted installations dominate new construction specifications, while portable configurations drive replacement demand in existing building stock.
NFPA 10 standards in the United States, EN 3 certification requirements in Europe, and BIS IS 15683 specifications in India collectively dictate cylinder pressure ratings, agent discharge durations, and labeling protocols that manufacturers must satisfy for market access. OSHA workplace safety inspections and local fire marshal audits create recurring compliance-driven replacement cycles that insulate baseline demand from economic volatility. Stakeholders must monitor evolving lithium-ion battery fire suppression protocols, as emerging hazard classifications threaten to obsolete conventional agent formulations and recertify entire product lines.
Market Dynamics
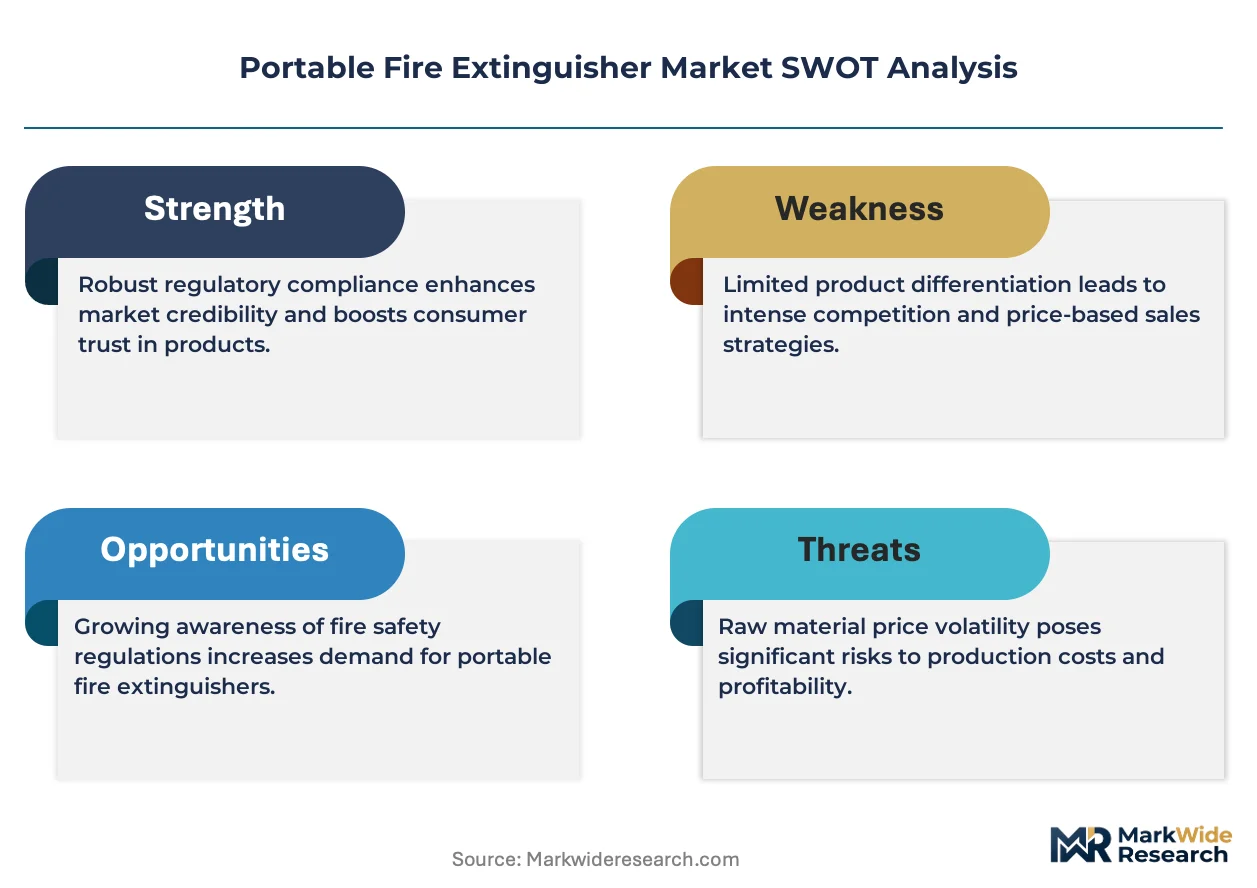
NFPA 10 recertification deadlines are compressing replacement cycles across commercial building stock, forcing facility managers into accelerated procurement schedules regardless of budget cycles.
Growth Catalysts
- OSHA workplace safety inspections:Multi-state enforcement sweeps in warehousing and logistics corridors trigger fleet-scale extinguisher purchases ahead of audit windows.
- Lithium-ion battery hazard protocols:Emerging fire classifications for EV charging stations and data center UPS systems expand addressable demand beyond conventional agent formulations.
- Dry chemical versatility:Single-unit coverage of Class A, B, and C scenarios reduces inventory complexity for property managers overseeing mixed-use facilities.
Market Restraints
- Steel cylinder input volatility:Raw material cost swings compress margin predictability for manufacturers without backward integration into metal forming.
- Clean-agent supply concentration:Halon alternative feedstock production clusters in select chemical corridors, exposing buyers to single-source risk during force majeure events.
- Agent disposal regulations:EPA hazardous waste protocols extend total cost of ownership and complicate end-of-life logistics for dry chemical units.
Strategic Opportunities
- India BIS IS 15683 compliance mandates:Certification requirements for imported units create localized assembly opportunities for domestic manufacturers.
- Hyperscale data center construction:Clean-agent specialization commands premium positioning in server farm specifications where residue damage exceeds fire loss.
- Direct-to-facility digital channels:E-procurement platforms bypass traditional distributor markups for institutional buyers with standardized specifications.
Industry Challenges
- Pressure vessel certification timelines:DOT/UN transport approval delays extend new product introduction cycles by 8-14 months.
- Agent formulation IP fragmentation:Proprietary blends across regional competitors complicate cross-border licensing and technical standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Fire Extinguisher Market |
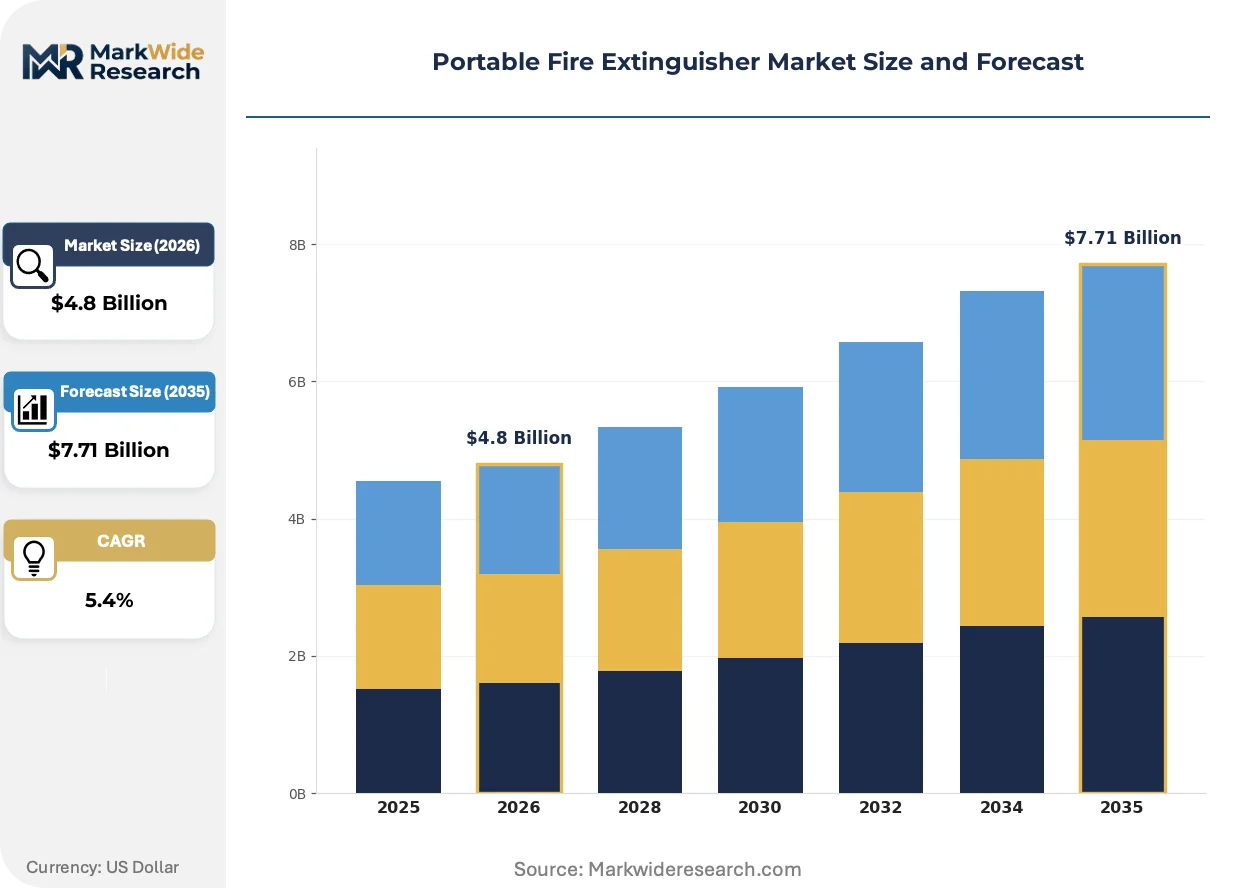
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Water, Foam, Dry Chemical, CO2 Application: Commercial, Residential, Industrial, Automotive Size: 2kg, 4kg, 6kg, 9kg Installation: Wall-Mounted, Portable, Vehicle-Mounted, Standalone |
| Companies Covered | Buckeye Fire Equipment, First Alert, Amerex Corporation, Hochiki Corporation, Strike First Corporation, Kidde, Minimax GmbH & Company KG, Yamato Protec Corporation, Ansul, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Fire Extinguisher Market Strategic Shifts & Innovations
Agent chemistry and deployment mechanisms are diverging sharply between legacy commercial applications and emerging electronics-protected environments.
Clean-agent halocarbon alternatives are overtaking CO2 in hyperscale data center specifications due to zero-residue discharge and reduced thermal shock to server components. Amazon Web Services and Microsoft Azure facilities specify these systems in procurement templates that cascade to mechanical contractors. The technology is overtaking conventional CO2 margins by compressing price competition into commodity dry chemical segments.
REACH restrictions on fluorinated compounds are forcing European manufacturers to reformulate foam concentrates and clean agents ahead of 2025 substance evaluation deadlines. Industrial laundries and aviation hangars face accelerated transition timelines as ECHA adds legacy fire suppression chemicals to candidate lists. German chemical producers are responding with aqueous film-forming foam alternatives that trade-off performance for regulatory compliance.
Facility managers now bundle extinguisher replacement with integrated fire suppression system audits, collapsing separate vendor relationships into single-source service contracts. This consolidation displaces independent inspection firms and commoditized product distributors in favor of full-service fire protection integrators. The pattern is most visible in United States multi-site retail chains where procurement centralization mandates vendor reduction programs.
Portable Fire Extinguisher Market Segmentation
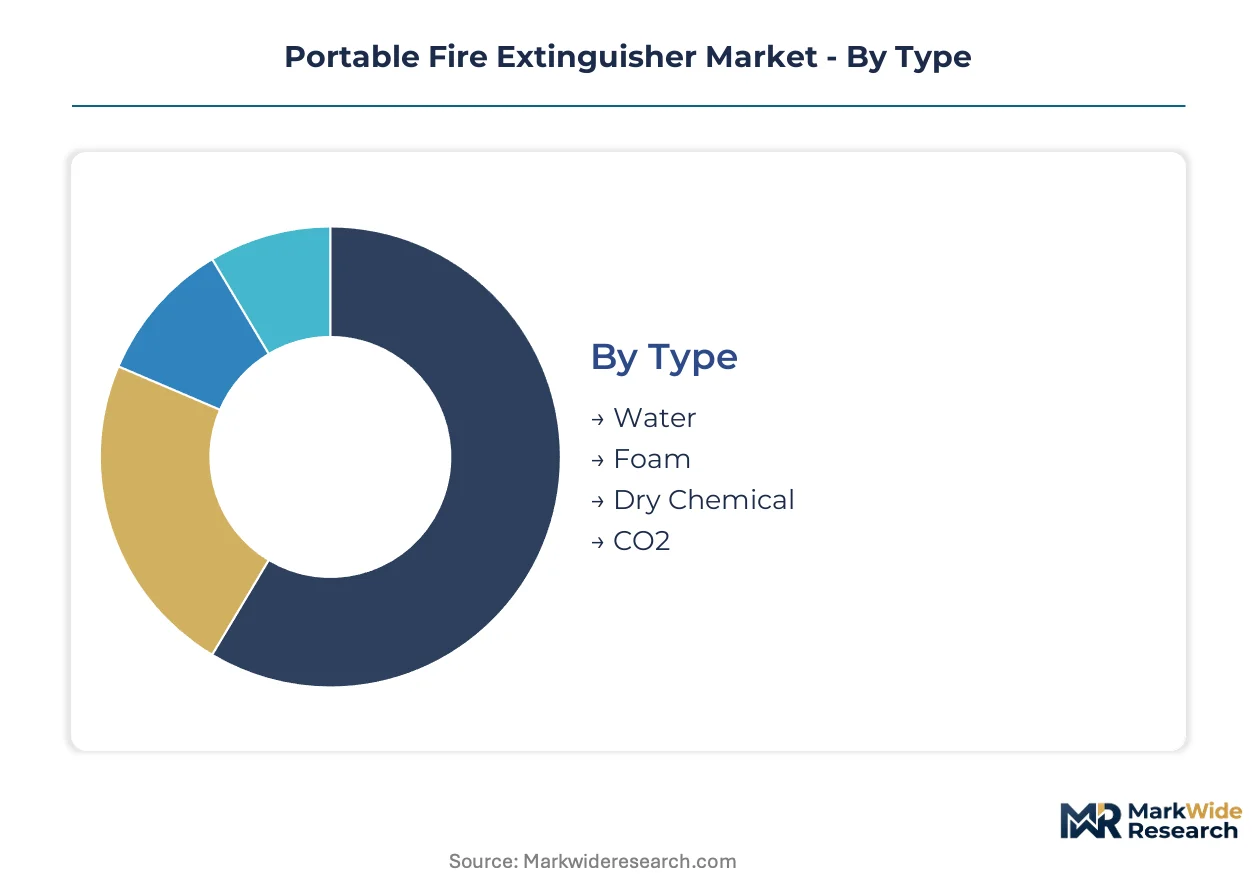
Portable fire extinguisher procurement varies sharply across deployment contexts, with facility managers balancing agent versatility against residue sensitivity and space constraints. Segmentation reveals how compliance mandates and hazard profiles reshape specification patterns across building types and mobility requirements.
Type:
Dry chemical units function as standalone suppression assets requiring no integration with building systems, while clean-agent alternatives embed into data center infrastructure as specialized protection layers.
- Dry Chemical:Monoammonium phosphate or sodium bicarbonate formulations deliver Class A, B, and C coverage from single cylinders. Warehousing operators across the United States favor these units for OSHA compliance sweeps due to broad hazard compatibility and lower per-unit cost.
- CO2:Carbon dioxide systems discharge without residue, protecting electronics in server farms and laboratories where conductive or corrosive agents would inflict secondary damage. Hyperscale data center contractors specify these for UPS battery rooms and switchgear enclosures.
- Foam:Aqueous film-forming concentrates smother flammable liquid fires through vapor suppression; aviation hangars and fuel storage depots deploy these for Class B hazard density.
- Water:Pressurized water extinguishers target Class A combustibles in schools, hospitals, and office buildings with minimal environmental impact and straightforward refill logistics.
Dry chemical leads volumes today; CO2 is gaining share fastest in electronics-protected environments.
Application:
Cost tier stratification separates high-frequency replacement cycles in commercial portfolios from capital-intensive industrial installations with extended service intervals.
- Commercial:Office complexes, retail chains, and hospitality properties drive replacement demand through NFPA 10 recertification deadlines. Facility management firms bundle extinguisher swaps with annual inspection contracts to compress vendor relationships.
- Industrial:Manufacturing plants and process facilities specify heavy-duty steel cylinders with extended discharge durations. Chemical corridor operators in Germany and the United States face REACH and EPA agent disposal protocols that elevate total ownership cost.
- Automotive:Vehicle-mounted units require DOT/UN pressure vessel certification for transport safety; fleet operators standardize on compact 2kg and 4kg formats for cabin and engine bay accessibility.
- Residential:Single-family and multi-unit housing stock shows penetration gaps where code enforcement lags commercial mandates; smart home integration is emerging as a specification differentiator in premium construction.
Commercial applications dominate absolute demand; industrial specifications command the steepest margin premiums.
Size:
Volume concentration clusters in mid-weight formats that balance suppression capacity against manual handling limits for diverse operator populations.
- 4kg:The standard specification for general commercial occupancy, delivering sufficient agent volume for initial attack on incipient fires without exceeding ergonomic limits for untrained personnel. Retail chains and office buildings specify this format across property portfolios.
- 6kg:Industrial facilities and high-hazard occupancies select this tier for extended discharge duration; logistics warehouses with elevated racking systems require the additional reach and volume.
- 2kg:Compact cylinders suit vehicle compartments, aircraft cabins, and confined mechanical spaces where stowage dimensions constrain selection.
- 9kg:Heavy-duty format reserved for specialized industrial and marine applications with severe hazard density; operators require formal training for safe deployment.
4kg specifications anchor procurement volumes today; 6kg formats are expanding most quickly in logistics and manufacturing corridors.
Installation:
Customer type separation distinguishes new construction specifications favoring fixed mounting from replacement demand in existing stock prioritizing mobility.
- Wall-Mounted:Fixed brackets position units at code-mandated intervals along egress paths; architects specify these in construction documents to satisfy fire marshal pre-occupancy inspections. Installation density per square foot varies by occupancy classification under NFPA 10.
- Portable:Freestanding configurations dominate retrofit procurement and replacement cycles, allowing facility managers to reposition assets without structural modification. Multi-site operators favor these for standardization across aging building stock.
- Vehicle-Mounted:Specialized brackets secure cylinders in commercial fleets, public transit, and emergency response vehicles; vibration resistance and rapid-release mechanisms differentiate specifications from static installations.
- Standalone:Cabinet-enclosed or wheeled units protect outdoor events, temporary structures, and construction sites lacking permanent suppression infrastructure; rental and event services represent a fragmented demand channel.
Wall-mounted systems lead new construction specifications; portable configurations drive replacement revenue in existing commercial stock.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as producers seek lower compliance costs outside mature markets. Steel cylinder fabrication and agent formulation capacity migrates toward jurisdictions with streamlined pressure-vessel certification timelines.
United States
NFPA 10 recertification deadlines compress replacement cycles across commercial building stock. OSHA multi-state enforcement sweeps in warehousing corridors trigger fleet-scale purchases ahead of audit windows. Data center construction in Northern Virginia and Dallas-Fort Worth drives clean-agent specification premiums.
Germany
REACH substance evaluation deadlines force reformulation of foam concentrates and clean agents ahead of 2025. Industrial laundries and aviation hangars face accelerated transition timelines as ECHA adds legacy chemicals to candidate lists. Chemical producers in the Rhine-Ruhr region respond with aqueous film-forming foam alternatives.
China
GB standards for pressure vessels and dual carbon goals reshape domestic manufacturing compliance costs. Steel cylinder production concentrates in Shandong and Jiangsu provinces where foundry capacity supports vertical integration. Local fabricators supply Southeast Asian markets with cost-competitive dry chemical units.
India
BIS IS 15683 certification requirements for imported units create localized assembly opportunities for domestic manufacturers. Commercial real estate expansion in Mumbai and Bangalore drives 4kg specification volumes through mandatory retrofit programs. Logistics warehousing growth along the Delhi-Mumbai Industrial Corridor accelerates procurement timelines.
Japan
METI industrial safety protocols and JIS standards maintain stringent cylinder pressure rating requirements. Manufacturing corridor operators in the Chubu region specify extended-discharge 6kg formats for high-hazard process facilities. Local producers anchor supply relationships across East Asian electronics manufacturing clusters.
Portable Fire Extinguisher Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with full-service integrators capturing bundled inspection-and-replacement contracts in multi-site retail chains. The vendor base organizes around three strategic archetypes: clean-agent specialists commanding data center premiums, dry chemical volume producers serving OSHA compliance cycles, and regional fabricators leveraging localized certification advantages. Consolidation pressures intensify as procurement centralization mandates vendor reduction programs. Geographic expansion and backward integration into steel cylinder production represent the dominant competitive moves.
Among North American specialists, Amerex Corporation and Kidde occupy positions across distinct market tiers. Amerex exemplifies the clean-agent specialization archetype serving electronics-protected environments, while Kidde represents broad retail penetration through big-box distribution networks. Yamato Protec Corporation anchors the East Asian manufacturing corridor tier with localized production lines. Hochiki Corporation and Minimax GmbH & Company KG sit within the integrated fire protection systems tier serving European industrial specifications.
| Leading Market Players |
|---|
| Buckeye Fire Equipment |
| First Alert |
| Amerex Corporation |
| Hochiki Corporation |
| Strike First Corporation |
| Kidde |
| Minimax GmbH & Company KG |
| Yamato Protec Corporation |
| Ansul |
| Others |
Cost & Logistics Intelligence
Pressure vessel welders concentrated in Shandong and Jiangsu provinces anchor steel cylinder fabrication costs, compressing labor-cost differentials between premium clean-agent units and economy dry chemical formats across export markets.
Pricing Analysis
Distributor markups of 18-25 percentage points separate factory gate from end-user pricing across institutional procurement channels. Three-tier pricing structure across premium clean-agent, standard dry chemical, and economy water-mist levels stratifies by certification grade and after-sales inspection bundling. Cost compression in commodity dry chemical segments is intensifying because REACH and EPA agent disposal protocols elevate total ownership cost. Facility management firms with centralized procurement show lowest price sensitivity; independent distributors serving fragmented retail channels exhibit highest.
Supply Chain Analysis
Dual-sourcing requirements for DOT/UN pressure vessel certification compel buyers to qualify fabricators across China, India, and Germany. Steel coil feedstock draws from integrated mills in Hebei province and specialty alloy suppliers in North Rhine-Westphalia. Single-source vulnerability concentrates in halocarbon clean-agent feedstock corridors. Distribution runs through fire protection integrators consolidating inspection-and-replacement contracts in multi-site retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as data center construction shifts procurement specifications toward zero-residue clean-agent systems commanding premium positioning.
For Market Incumbents: Acquire steel cylinder fabrication capacity to secure backward control over pressure vessel input costs. Defensive consolidation around NFPA 10 inspection bundling protects against distributor disintermediation. Threat from lithium-ion battery fire classifications demands R&D investment in specialized agent formulations. Certification investment in BIS IS 15683 compliance opens India assembly opportunities. For New Entrants and Emerging Players: The 40-60 percent price-point gap between premium clean-agent and economy dry chemical tiers creates entry space for mid-market hybrid formulations. White-space targets include EV charging station protection and residential smart-home integration. Most penetrable segment: logistics warehousing corridors along the Delhi-Mumbai Industrial Corridor. Go-to-market angle: direct e-procurement platforms bypassing traditional distributor markups. For Investors and Strategic Acquirers: Full-service fire protection integrators are the most active acquirer in this space, consolidating fragmented inspection firms. Five-to-ten year viability hinges on clean-agent specialization and data center contract capture. Acquisition target archetype: regional fabricators with captive steel forming and localized certification advantages. Signal to watch: lithium-ion battery fire classification adoption by NFPA and BIS as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Cylinder Fabrication | Captive supply of pressure vessels insulates margin from raw material volatility in Shandong corridor. |
| Clean-Agent Specialization Investment | Zero-residue formulations command premium positioning in hyperscale data center specifications. |
| Direct E-Procurement Platform Launch | Bypasses distributor markups for institutional buyers with standardized NFPA 10 specifications. |
| Localized Assembly for BIS IS 15683 Compliance | Domestic India manufacturing satisfies certification requirements blocking imported unit access. |
| Integrated Inspection-and-Replacement Service Bundling | Consolidates vendor relationships for multi-site retail chains executing NFPA 10 recertification cycles. |
Research Approach
Bottom-up commercial and industrial facility modeling reconciled against top-down steel cylinder production tracking forms the analytical core of this study. Primary interviews with fire protection integrators, facility management procurement leads, pressure vessel fabricators, and OSHA compliance officers combined with secondary validation from NFPA technical standards, BIS certification registries, ECHA substance evaluation databases, and customs trade data. Triangulation across demand-side replacement cycle analysis and supply-side capacity mapping ensures cross-verified outputs.
Input-output matrices connect agent formulation chemistry, cylinder pressure ratings, and installation format specifications to end-use demand across the projection horizon. Segmentation dimensions modeled include extinguisher type, application context, size format, and installation method, with regional regulatory cluster as an additional cross-cutting variable. CAGRs derive from fitted trend analysis of replacement cycle compression and new construction specification patterns. Industry-specific forecast inputs incorporate OSHA enforcement sweep frequency and data center construction pipeline tracking.
Caveats apply where lithium-ion battery fire classification adoption or REACH substance evaluation acceleration could materially shift the outlook. Forecasts reflect documented assumptions regarding NFPA 10 recertification timeline adherence and steel input cost stability. Deviation in clean-agent feedstock supply concentration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Global Fire Suppression System Market
Fire Safety & Protection
Automatic Fire Suppression System (AFSS) Market
Fire Safety & Protection
Fire Fighting Foam Market
Fire Safety & Protection
Global Portable Foam Fire Extinguisher Market
Fire Safety & Protection
Fire Rated Cables Market
Fire Safety & Protection
China Thermal Protector Market
Fire Safety & Protection
US Fire Safety Equipment Market
Fire Safety & Protection
Fire Pump Market
Fire Safety & Protection
US Fire Alarm and Detection Market
Fire Safety & Protection
Fire Resistant Glass Market
Fire Safety & Protection
UAE Firefighting Foam Market
Fire Safety & Protection
Smart Smoke Detector Market
Fire Safety & Protection
Civil Combustible Gas Alarm Market
Fire Safety & Protection
Automatic Fire Ball Extinguisher Market
Fire Safety & Protection
Laser Smoke Detector Market
Fire Safety & Protection
Flame Barrier Market