
 Outdoor Safety Lock Market | 2026-2036
Outdoor Safety Lock Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Safety Lock Market Analysis
China's manufacturing corridor is reshaping component economics for outdoor safety lock producers. ASSA ABLOY leverages its integrated foundry network across Asia to sustain cost leadership in brass and steel deadbolt production. Allegion anchors North American distribution through locksmith and hardware cooperative channels. Dormakaba competes on commercial-grade smart lock platforms with embedded Bluetooth modules.
An outdoor safety lock is a mechanical or electromechanical fastening device engineered for exterior deployment, typically featuring weather-resistant housings rated to IP54 or higher and corrosion-treated shackles or bolts to withstand temperature cycling and moisture exposure; its primary purpose is to secure gates, sheds, storage units, and perimeter access points against unauthorized entry. Smart locks and biometric-enabled systems represent the fastest-expanding technology tier, with Bluetooth and fingerprint modules capturing margin pools from traditional keyed segments. Steel and brass materials still dominate volume, though polymer housings gain share in marine and coastal recreational applications where salt corrosion accelerates metal fatigue.
FCC certification governs wireless transmission protocols for smart locks sold in the United States, while the EU AI Act and GDPR impose algorithmic transparency and data handling requirements on biometric outdoor locks distributed in Europe. OSHA lockout/tagout standards indirectly stimulate industrial padlock replacement cycles by mandating dedicated safety isolation hardware. Stakeholders must weigh certification lead times against regional product rollout schedules when allocating R&D budgets.
Market Dynamics
Smart lock penetration is compressing replacement cycles for mechanical outdoor hardware as property managers prioritize tenant convenience over capital longevity, forcing incumbents to reengineer supply chains around Bluetooth module sourcing and firmware update infrastructure.
Growth Catalysts
- Sun Belt Rental Concentration:Property managers in Phoenix, Houston, and Tampa are mandating keyless entry to reduce turnover costs. This operational preference is pulling smart deadbolt volumes upward in multi-family housing clusters.
- OSHA Lockout/Tagout Mandates:Industrial facilities must maintain dedicated safety isolation hardware under federal workplace standards. This sustains replacement demand for color-coded, non-interchangeable padlock systems across manufacturing plants.
- FCC Certification Pathway:Streamlined wireless device approval for sub-gigahertz protocols is reducing time-to-market for smart lock entrants. Domestic manufacturers leverage this to compete with imported electromechanical units.
Market Restraints
- Brass Input Volatility:Foundry-grade copper-zinc alloy pricing swings directly compress margin on premium deadbolt production. Producers lack hedging instruments for this specific metallurgical input.
- Foundry Concentration in Zhejiang:Die-cast housing and precision machining capacity clusters in a single Chinese province. Geopolitical friction or energy rationing there propagates immediately through component lead times.
- Biometric Algorithm Limitations:Fingerprint sensors degrade accuracy below freezing, constraining deployment in northern climates without supplemental heating elements that inflate unit cost.
Strategic Opportunities
- Marine Recreation Expansion:Salt-corrosion-resistant polymer housings address unmet demand among coastal boat storage and dock access applications. This segment currently relies on repainted metal units with shortened service life.
- GDPR-Compliant Biometric Design:Edge-processing architectures that store templates locally rather than cloud-syncing satisfy EU data sovereignty requirements. First movers capture specification roles in German and Dutch municipal procurement.
- Hardware Cooperative Bypass:Direct-to-installer e-commerce platforms disintermediate traditional locksmith distribution. This channel innovation reaches independent security contractors previously captured by Allegion's cooperative network.
Industry Challenges
- Firmware Engineering Talent Scarcity:Electromechanical manufacturers lack embedded systems expertise for secure over-the-air update pipelines. Recruitment competition with consumer electronics firms inflates compensation costs.
- ANSI/BHMA Certification Timelines:Grade 1 deadbolt testing protocols require 12-16 weeks of sequential mechanical cycling and environmental exposure. This gates product launches against seasonal construction windows.
- Legacy Mechanical Interoperability:Retrofit smart locks must interface with non-standard strike plates and door prep dimensions common in pre-1990 residential stock. Integration complexity drives support call volume and return rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Safety Lock Market |
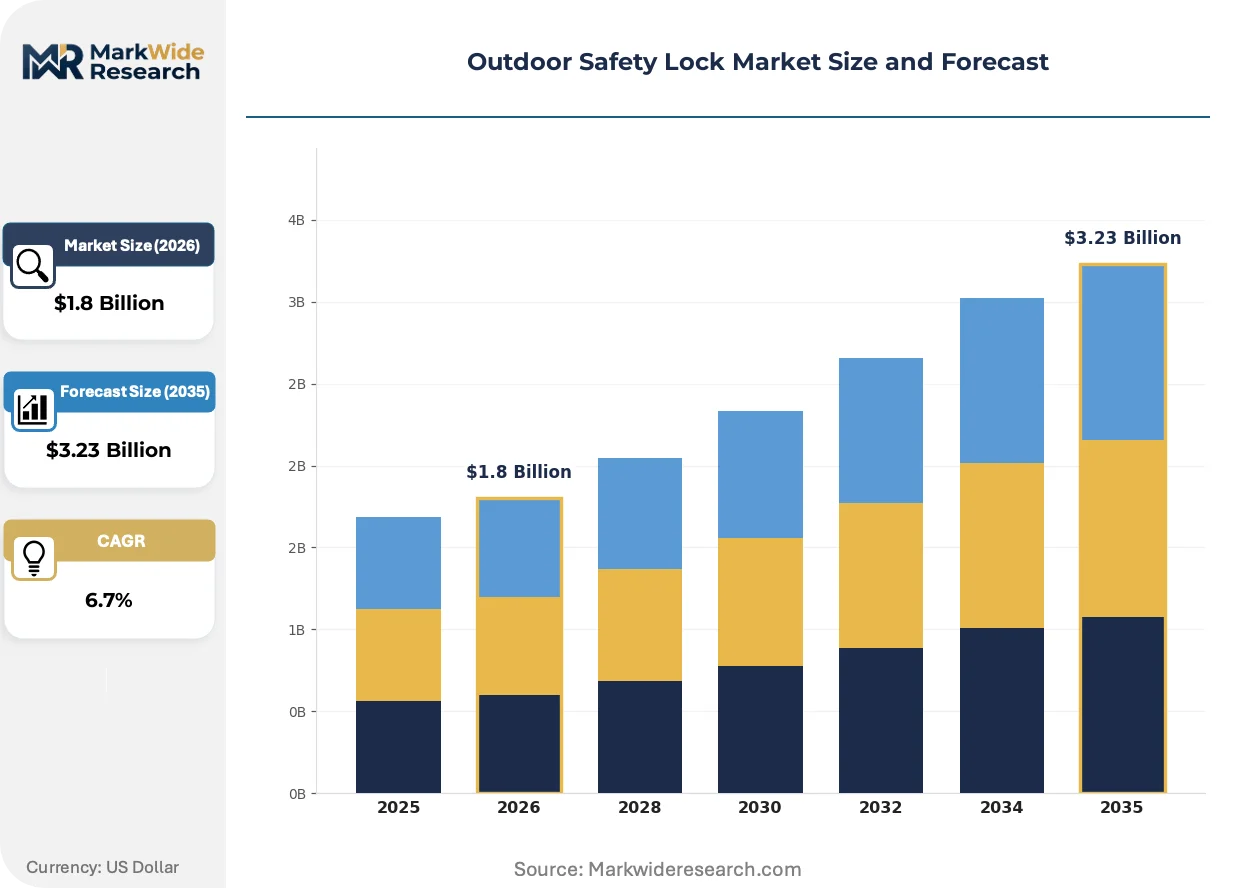
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Padlocks, Deadbolts, Digital Locks, Smart Locks Material: Steel, Brass, Aluminum, Polymer Application: Residential, Commercial, Industrial, Recreational Technology: Keyed, Keyless, Bluetooth, Biometric |
| Companies Covered | ASSA ABLOY, Allegion, August Home, Schlage, Yale Home, Kwikset, Dormakaba, Level Home, Ultraloq, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Safety Lock Market Emerging Trajectories
Electromechanical convergence is redefining product architecture as mechanical durability requirements collide with consumer electronics refresh cycles, forcing suppliers to reconcile IP54 ingress protection with annual firmware feature updates.
Biometric authentication modules are hybridizing mechanical deadbolt platforms with capacitive fingerprint sensors and liveness detection algorithms. Multi-family property operators in Texas and Florida are specifying these units for Class A apartment repositioning projects. The technology is hybridizing supplier R&D budgets away from pure mechanical engineering toward embedded software and machine-learning model training.
The EU AI Act imposes algorithmic transparency requirements on biometric outdoor locks sold in Europe. Manufacturers must document training data provenance and decision logic for fingerprint matching systems. Commercial-grade smart lock platforms with embedded Bluetooth modules face the strictest documentation burdens, prompting some suppliers to delay EU market entry or strip biometric features for that geography.
Tenant self-service provisioning is displacing traditional key handoff workflows in professionally managed rental housing. Property technology platforms now integrate lock APIs into mobile tenant applications, eliminating locksmith dispatch for turnover rekeying. This behavioral shift concentrates most visibly in Arizona and Nevada metropolitan markets where institutional multifamily ownership dominates housing stock.
Outdoor Safety Lock Market Segmentation
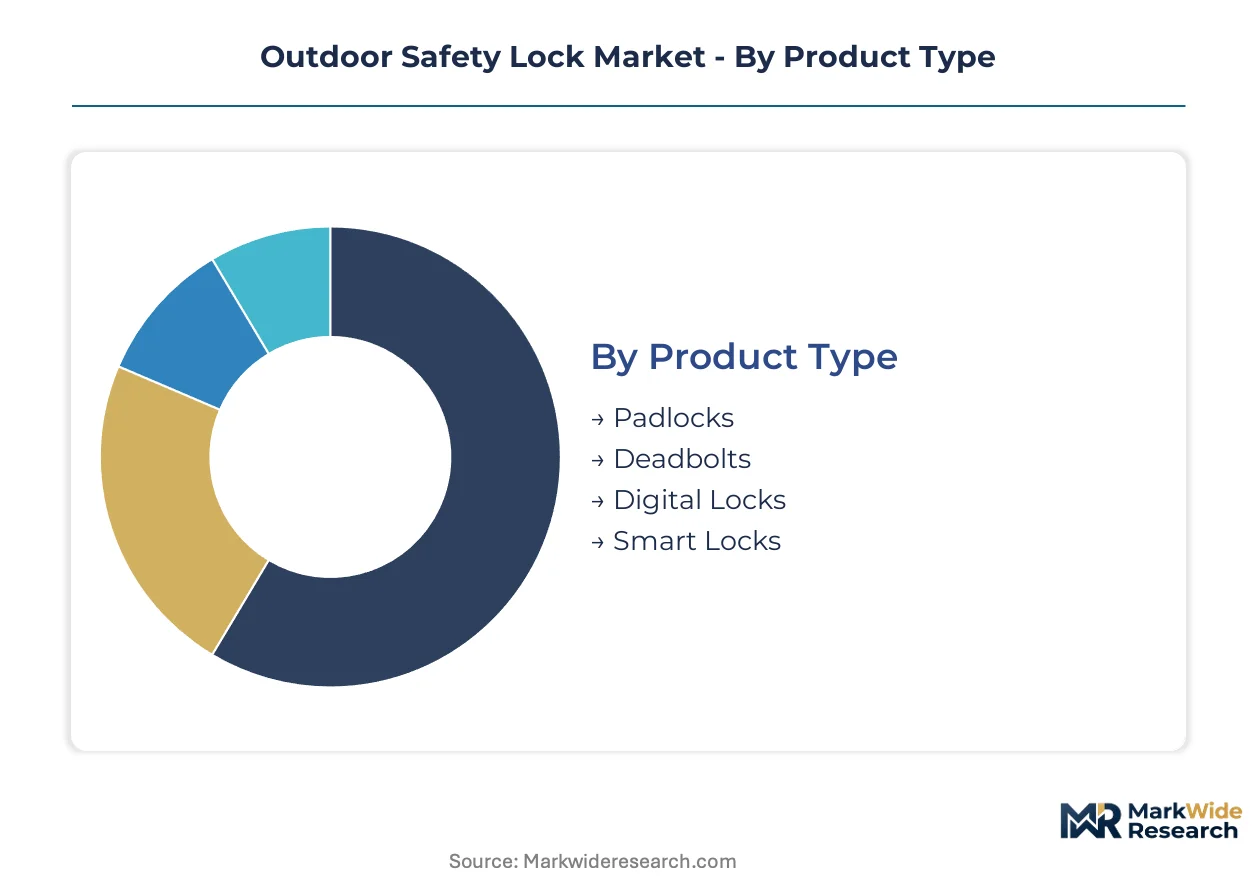
Outdoor safety lock segmentation reveals divergent engineering priorities across mechanical durability and digital convenience. Product architecture, material selection, and authentication technology each create distinct margin profiles and certification pathways for suppliers.
Product Type:
Mature mechanical formats coexist with emerging electromechanical platforms, each serving different replacement cycle expectations and installation labor requirements.
- Padlocks:Portable shackle-and-body designs in hardened steel or brass housings rated for outdoor exposure. Industrial lockout/tagout programs under OSHA mandates sustain replacement demand across manufacturing facilities in the United States.
- Deadbolts:ANSI/BHMA Grade 1 single-cylinder and double-cylinder configurations with 1-inch minimum bolt throw. Sun Belt property managers in Phoenix and Tampa specify these for multifamily perimeter security where tenant turnover drives hardware refresh cycles.
- Digital Locks:Keypad-entry electromechanical units with programmable PIN codes and audit trail logging. These address commercial storage facilities requiring temporary access delegation without physical key distribution.
- Smart Locks:Bluetooth and WiFi-enabled platforms with mobile app provisioning and over-the-air firmware updates. Salt-corrosion-resistant polymer variants are expanding into marine dock access applications previously served by repainted metal hardware.
Deadbolts handle the majority of throughput; smart locks are expanding most quickly on share.
Material:
Cost tier stratification separates premium metallurgical specifications from commodity alternatives, with coastal environments forcing material substitution beyond pure price considerations.
- Steel:Case-hardened boron alloy and stainless variants dominate industrial padlock production. Foundry-grade input volatility in copper-zinc markets pushes some specification engineers toward steel alternatives for budget-conscious commercial projects.
- Brass:Copper-zinc alloys with corrosion-resistant plating for decorative deadbolt applications. ASSA ABLOY's integrated Asian foundry network sustains cost leadership in this premium segment despite raw material price swings.
- Aluminum:Die-cast housings offering weight reduction for portable lock applications. Recreational vehicle and marine storage operators specify these for gate hardware where manual handling frequency matters.
- Polymer:Glass-filled nylon and ABS housings with UV stabilizers for salt-air environments. German and Dutch municipal procurement programs are testing these for coastal infrastructure where metal fatigue accelerates replacement cycles.
Steel commands the highest volume position; polymer is climbing the fastest as coastal specifications harden against corrosion.
Application:
Customer type determines certification burden and channel access, with industrial buyers prioritizing compliance documentation over convenience features.
- Residential:Single-family and multifamily exterior door and gate hardware. Tenant self-service provisioning through property technology platforms is displacing traditional locksmith dispatch in Arizona and Nevada metropolitan markets.
- Commercial:Retail back-of-house, office perimeter, and storage facility access control. GDPR-compliant biometric designs with edge-processing architectures are capturing specification roles in German municipal procurement.
- Industrial:Manufacturing plant lockout/tagout isolation hardware and perimeter security. OSHA mandates for dedicated safety padlock systems sustain replacement demand regardless of broader construction cycles.
- Recreational:Boat storage, campground, and park facility access hardware. Salt-corrosion-resistant polymer housings address unmet demand in dock access applications where repainted metal units fail prematurely.
Residential generates the largest revenue base; recreational is gaining share fastest as marine infrastructure investment expands.
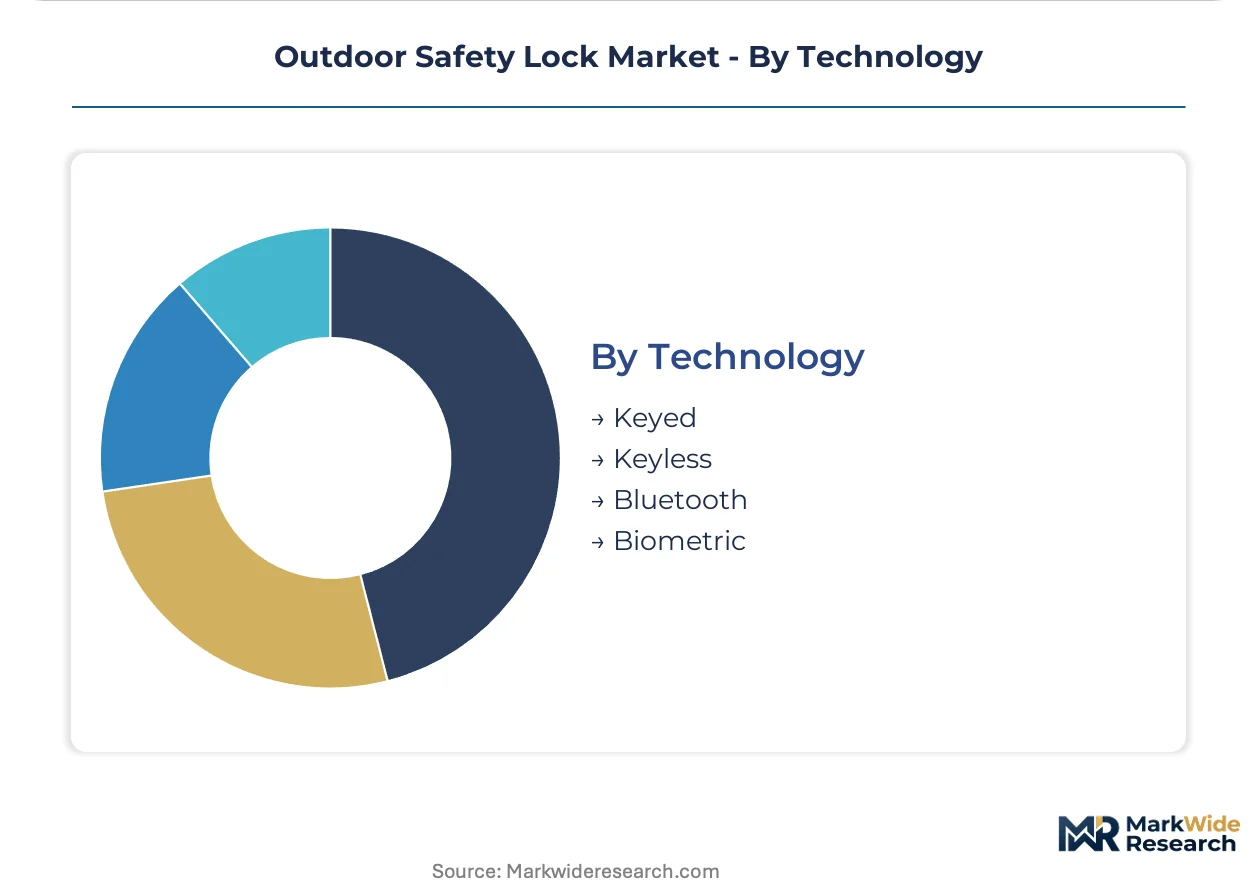
Technology:
Authentication modality defines the supplier's required capabilities, separating mechanical engineering heritage from embedded systems and machine-learning competencies.
- Keyed:Traditional pin-tumbler and wafer mechanisms with physical key control. Legacy mechanical interoperability challenges with pre-1990 door prep dimensions drive support complexity for retrofit applications.
- Keyless:Push-button mechanical combination locks without electronic components. These serve remote utility infrastructure where battery maintenance is impractical and wireless connectivity is unavailable.
- Bluetooth:Low-energy wireless modules enabling smartphone proximity unlocking and temporary credential issuance. FCC streamlined certification for sub-gigahertz protocols is reducing time-to-market for domestic electromechanical entrants.
- Biometric:Capacitive fingerprint sensors with liveness detection algorithms and local template storage. EU AI Act documentation burdens for algorithmic transparency are prompting some suppliers to strip biometric features for European distribution.
Keyed technology retains the installed base; biometric is on the steepest expansion trajectory despite regulatory friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA lockout/tagout mandates anchor the United States as the dominant geography, with FCC certification pathways accelerating domestic smart lock deployment. Sun Belt metropolitan rental markets concentrate demand for keyless entry hardware.
United States
Phoenix, Houston, and Tampa property managers mandate keyless entry to reduce turnover costs. FCC streamlined certification for sub-gigahertz protocols reduces time-to-market for domestic electromechanical entrants. Arizona and Nevada metropolitan markets concentrate institutional multifamily ownership driving tenant self-service provisioning adoption.
Germany
Municipal procurement programs test salt-corrosion-resistant polymer housings for coastal infrastructure applications. EU AI Act imposes algorithmic transparency requirements on biometric outdoor locks, prompting edge-processing architectures. Bavarian industrial clusters drive demand for OSHA-compliant lockout systems in manufacturing facilities.
China
Zhejiang province concentrates die-cast housing and precision machining capacity for global component supply. GB standards govern mechanical durability ratings for export-oriented production. Yangtze River Delta manufacturing corridors reshape brass and steel deadbolt economics through integrated foundry networks.
Netherlands
GDPR-compliant biometric designs with local template storage capture specification roles in municipal procurement. Dutch coastal infrastructure programs test polymer alternatives to metal hardware for salt-air environments. Randstad logistics hubs drive demand for commercial storage facility access control systems.
Japan
METI standards govern wireless transmission protocols for smart lock platforms in residential applications. Kanto region metropolitan rental markets adopt Bluetooth-enabled entry systems for aging housing stock retrofit. Osaka industrial corridors sustain replacement demand for color-coded safety isolation hardware under workplace standards.
Outdoor Safety Lock Market Vendor Landscape
Integrated conglomerates and specialized electromechanical platforms split the market between capital-intensive foundry operations and firmware-driven convenience features. Three archetypes dominate: Asian-integrated manufacturers with captive metallurgical supply, North American distribution-heavy incumbents anchored through locksmith cooperatives, and software-native entrants competing on over-the-air update infrastructure. Competitive moves concentrate on backward integration into component foundries and direct-to-installer channel bypass strategies.
Within the integrated manufacturing tier, ASSA ABLOY exemplifies the Asian foundry network model, while Allegion occupies a position representing North American cooperative channel dominance. Dormakaba sits within the commercial-grade smart lock specialization archetype. These three anchors illustrate how heritage mechanical engineering competencies collide with embedded systems requirements across the competitive spectrum.
| Leading Market Players |
|---|
| ASSA ABLOY |
| Allegion |
| August Home |
| Schlage |
| Yale Home |
| Kwikset |
| Dormakaba |
| Level Home |
| Ultraloq |
| Others |
Supply Flow & Price Mechanics
Zhejiang province's die-cast housing and precision machining capacity concentration grants component suppliers substantial leverage over finished lock pricing. Brass input volatility from copper-zinc alloy markets compresses margins on premium deadbolt production, while polymer alternatives gain traction in coastal specifications where salt corrosion accelerates metal fatigue replacement cycles.
Pricing Analysis
Price spreads between Asian-manufactured and North American-assembled units reach three-to-one ratios across comparable ANSI/BHMA Grade 1 specifications. Pricing stratifies across premium brass deadbolts, standard steel padlocks, and economy polymer variants, with certification tier and foundry integration as primary differentiation drivers. Cost compression in the brass tier intensifies because raw material hedging instruments remain unavailable for this specific metallurgical input. Industrial lockout/tagout buyers exhibit lowest price sensitivity due to OSHA compliance mandates, while residential property managers in Sun Belt markets prioritize convenience features over per-unit cost.
Supply Chain Analysis
Contract manufacturing concentrates among Yangtze River Delta foundries and Zhejiang precision machining clusters, with ASSA ABLOY's integrated Asian network and Allegion's cooperative-sourced components representing dominant capacity holders. Supply chains draw from Chinese brass and steel foundries, Taiwanese Bluetooth module fabricators, and German biometric sensor specialists. Single-source vulnerability in Zhejiang die-casting propagates immediately through component lead times during energy rationing or geopolitical friction. Distribution runs through locksmith cooperatives, hardware wholesaler networks, and emerging direct-to-installer e-commerce platforms serving independent security contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as tenant self-service provisioning displaces traditional key handoff workflows across professionally managed rental housing. Electromechanical convergence splits supplier capabilities between mechanical durability heritage and embedded systems competencies.
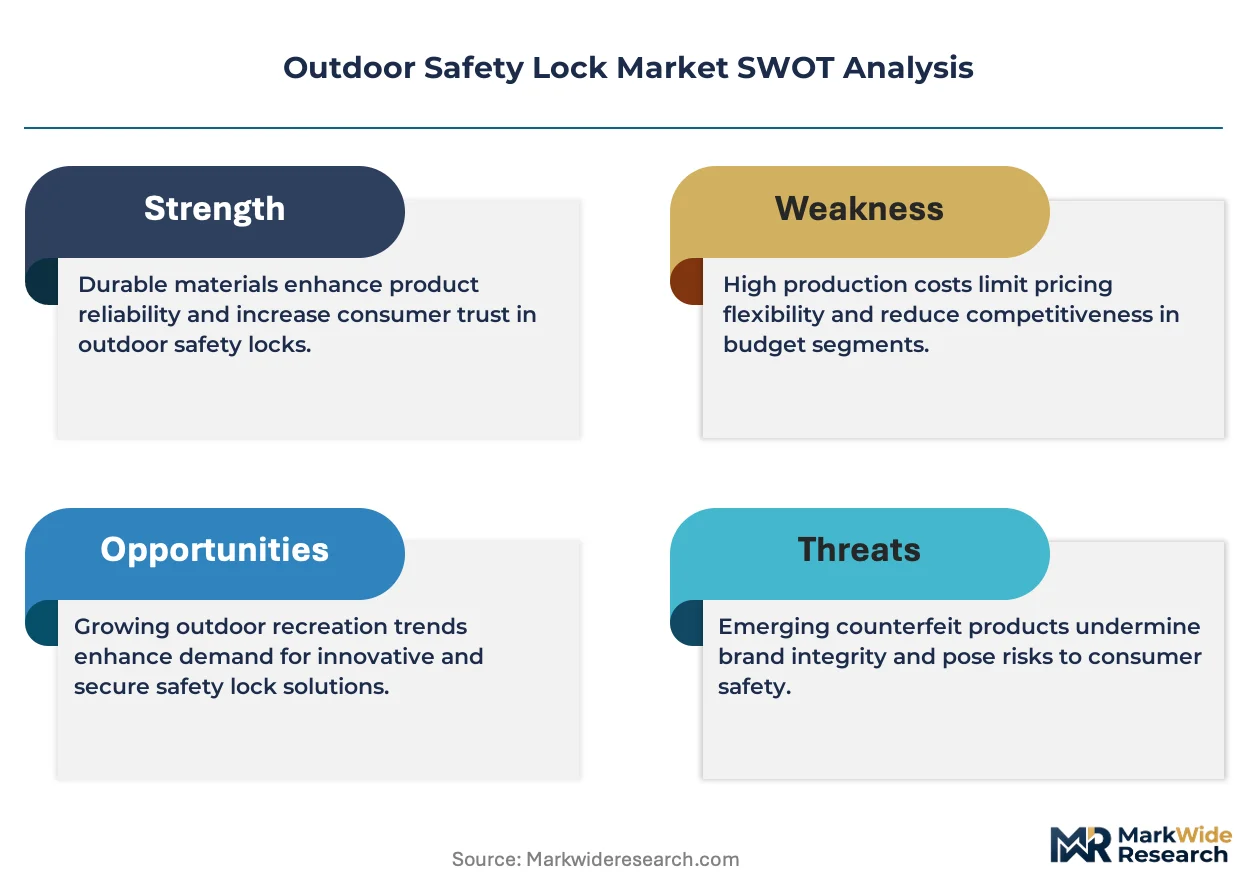
For Market Incumbents: Pre-empt firmware-native entrants by acquiring edge-processing biometric capabilities before EU AI Act documentation burdens harden specification advantages. Anchor backward integration into Zhejiang foundry partnerships to secure brass housing supply against input volatility. Reinforce ANSI/BHMA certification pipelines to gate seasonal construction windows against software-first competitors lacking mechanical cycling expertise. For New Entrants and Emerging Players: Build out salt-corrosion-resistant polymer platforms for marine dock access applications where incumbent metal offerings fail prematurely. Target recreational boat storage operators in Florida and German coastal municipalities testing polymer alternatives to metal hardware. Pursue direct-to-installer e-commerce channels to bypass Allegion's cooperative network capture of independent security contractors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electromechanical platforms with captive firmware update infrastructure over pure mechanical engineering heritage. Long-term viability rests on suppliers reconciling IP54 ingress protection with annual feature refresh expectations. Acquisition candidates with edge-processing biometric architectures and GDPR-compliant local template storage warrant priority attention. Monitor FCC certification queue lengths as inflection signal for domestic electromechanical entrant momentum against import competition.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Operations | Captive brass and steel supply insulates margin from copper-zinc alloy price swings in Zhejiang. |
| Edge-Processing Biometric Platform Launch | Local template storage satisfies GDPR and EU AI Act requirements for German municipal procurement. |
| Direct-to-Installer E-Commerce Channel | Bypasses Allegion's cooperative network to reach independent security contractors in Sun Belt markets. |
| Polymer Housing Certification Investment | Marine-grade UV-stabilized nylon addresses salt-corrosion failures in Florida dock access applications. |
| Firmware Update Infrastructure Buildout | Over-the-air capability aligns product refresh cycles with property technology platform integration demands. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, incorporating property technology platform executives, multifamily asset managers, locksmith cooperative distributors, industrial safety officers, and electromechanical engineering leads. Secondary validation drew from FCC equipment authorization databases, ANSI/BHMA certification registries, OSHA lockout/tagout compliance filings, and customs trade data on brass and steel component flows. Bottom-up unit shipment estimates triangulated against top-down construction spending allocations across residential, commercial, and industrial application segments.
Calibration against historical replacement cycle data and tenant turnover correlation studies anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, material specification, authentication technology, and regional regulatory cluster. CAGRs were derived from fitted growth curves against smart lock penetration assumptions and mechanical hardware displacement rates. Industry-specific inputs incorporated Bluetooth module cost decline trajectories and biometric sensor accuracy degradation curves in sub-freezing climates.
Stress conditions across brass input volatility, Zhejiang energy rationing scenarios, and EU AI Act enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding smart lock adoption elasticity and property manager convenience preference shifts. Cross-checking against multifamily housing permit data and industrial capital expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Steel Smart Locker Market
Safety Equipment and Personal Protective Equipment (PPE)
Cut Resistant Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Pest Control Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Seat Belt Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
In Room Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Snowmobile Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Public Address and Voice Alarm Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Explosion-Proof Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Intrinsically Safe Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Self-Contained Breathing Apparatus Market
Safety Equipment and Personal Protective Equipment (PPE)
Functional Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
Cargo Security Seals Market