
 UAE Firefighting Foam Market | 2026-2036
UAE Firefighting Foam Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Firefighting Foam Market Analytics
Buyer concentration among UAE municipal fire departments and aviation authorities is realigning procurement toward consolidated long-term supply agreements. NAFFCO leverages its domestic manufacturing footprint to anchor government contracts across emirates. FIREX competes through specialized marine foam certifications for Port Khalifa operations. Johnson Controls extends its building-systems integration expertise into automated foam suppression for data centers and logistics warehouses.
Firefighting foam comprises surfactant-based formulations designed to suppress flammable liquid fires by forming a stable blanket that excludes oxygen and cools fuel surfaces; modern concentrates typically achieve expansion ratios from 1:1 to 1000:1 depending on application requirements. AFFF formulations dominate current stockpiles across UAE industrial zones, though fluorine-free alternatives are displacing legacy products amid environmental scrutiny. The Aviation end-user segment sustains premium pricing due to ICAO-mandated performance thresholds, while Concentrates in bulk form capture the largest volume share through refinery and tank farm deployments.
The UAE Civil Defence mandates product approval under its fire safety certification framework, while the Emirates Authority for Standardization and Metrology enforces quality benchmarks for foam concentrates sold domestically. MOHAP oversight of environmental health standards is tightening restrictions on PFAS-containing formulations in coastal protection zones. Stakeholders must monitor regulatory alignment between federal emirate-level specifications and evolving Gulf Standardization Organization protocols to anticipate compliance-driven product transitions.
Market Dynamics
The UAE Civil Defence's tightened environmental compatibility mandates are forcing wholesale replacement of legacy AFFF stockpiles with fluorine-free formulations, compressing supplier transition timelines and reordering procurement hierarchies across emirates.
Growth Catalysts
- ICAO Performance Mandates:Aviation authorities at Dubai International and Al Maktoum International enforce stringent foam discharge standards that sustain premium concentrate demand for aircraft rescue and firefighting fleets.
- Abu Dhabi Petrochemical Corridor:Tank farm expansions at Ruwais and Das Island drive bulk concentrate procurement for hydrocarbon storage protection, anchoring volume demand.
- UAE Civil Defence Certification Framework:Federal approval requirements for all foam concentrates sold domestically create regulated demand pull that favors compliant domestic manufacturers.
Market Restraints
- Fluorosurfactant Input Volatility:Specialty chemical feedstock costs for legacy AFFF production fluctuate with global fluorochemical supply constraints, pressuring margin structures for transitional product lines.
- Supplier Concentration Risk:Domestic manufacturing capacity clusters in Sharjah and Dubai industrial zones, creating geographic vulnerability to logistics disruptions or localized regulatory enforcement variations.
- Technical Performance Gaps:Fluorine-free alternatives currently exhibit shorter drain times on polar solvent fires, limiting substitution rates in high-risk chemical processing applications.
Strategic Opportunities
- Northern Emirates Industrial Zones:Ras Al Khaimah and Fujairah port expansions present underpenetrated demand for marine-certified foam systems in bulk liquid storage and bunkering operations.
- Data Center Automated Suppression:Dubai's hyperscale cloud infrastructure buildout creates emerging demand for clean-agent foam hybrids that protect sensitive electronics without water damage.
- Gulf Standardization Organization Alignment:Anticipated harmonization of UAE Civil Defence specifications with GSO protocols would enable cross-border certification portability for domestic manufacturers.
Industry Challenges
- PFAS Remediation Liability:Legacy AFFF stockpile disposal and site contamination assessment require specialized environmental contracting capabilities that strain municipal fire department operational bandwidth.
- Multi-Tier Certification Timelines:Products must sequentially secure UAE Civil Defence approval, Emirates Authority for Standardization and Metrology quality benchmarks, and MOHAP environmental health clearances, extending time-to-revenue cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Firefighting Foam Market |
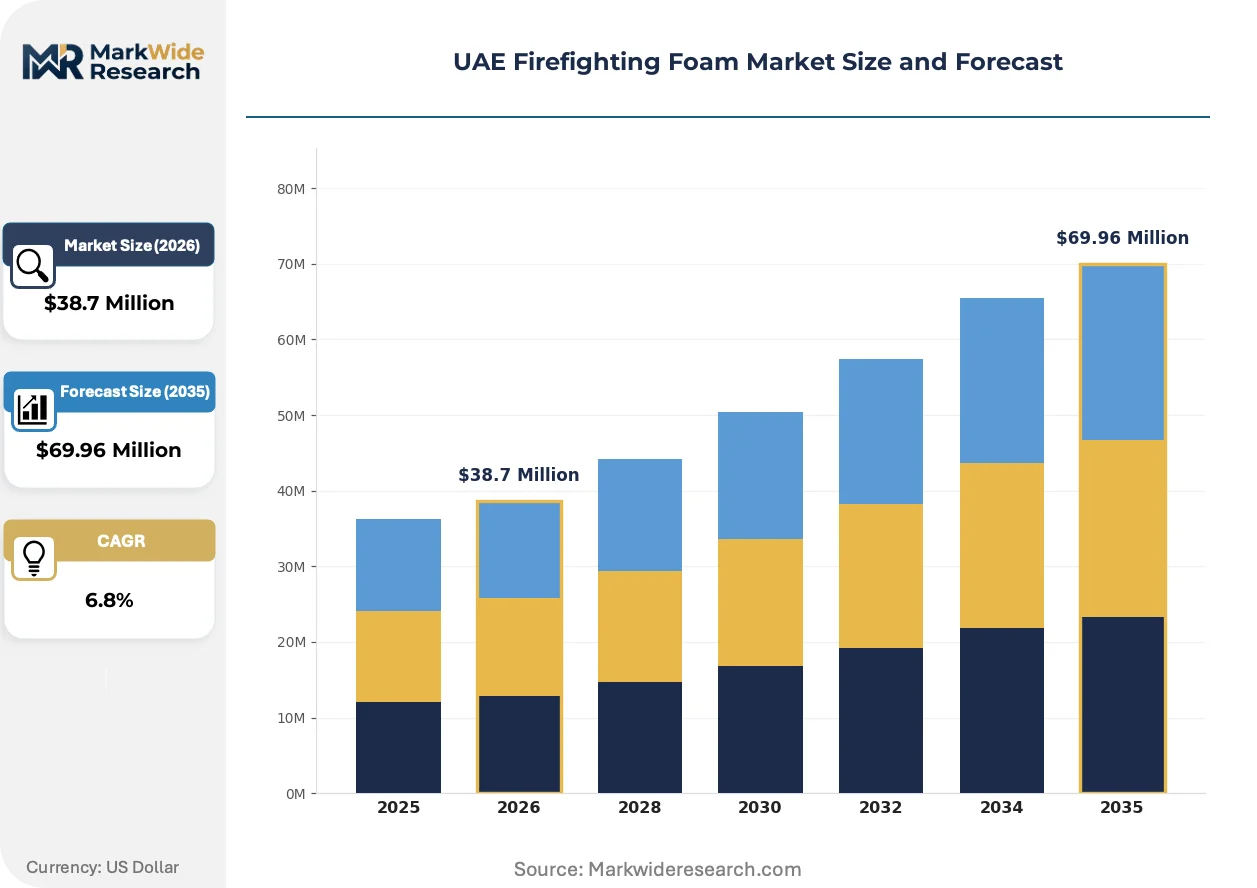
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $69.96 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AFFF, FFFP, AR-AFFF, High-Expansion Foam End User: Industrial, Marine, Aviation, Municipal Form: Concentrates, Ready-to-Use, Portable, Bulk Installation: Fixed, Mobile, Automatic, Manual |
| Companies Covered | FIREX, BRISTOL Fire Engineering LLC, NAFFCO, Loshareh Chemical Industries, Johnson Controls, SFFECO Global, NATIONAL FOAM INC., SEPPIC, Albilad Fighting Systems Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Firefighting Foam Market Evolving Landscape
Formulation chemistry and procurement architecture are undergoing parallel transformation as environmental compliance deadlines compress product lifecycles and buyer-seller relationships restructure around long-term performance guarantees rather than transactional supply.
Fluorine-free foam concentrates employ synthetic hydrocarbon surfactants and polysaccharide polymers to achieve film-forming performance without per- and polyfluoroalkyl substances. Municipal fire departments in Dubai and Abu Dhabi are accelerating adoption ahead of federal deadlines. This technology is expanding into aviation applications previously dominated by legacy AFFF, though ICAO-mandated performance thresholds maintain rigorous certification barriers.
MOHAP oversight of environmental health standards is tightening restrictions on PFAS-containing formulations in coastal protection zones, creating direct regulatory pressure on stockpile composition. Industrial end-users face accelerated write-down schedules for non-compliant inventory. The petrochemical corridor spanning Ruwais and Jebel Ali is most affected, with tank farm operators front-loading replacement purchases to preempt enforcement actions.
Long-term supply agreements are displacing spot procurement across UAE municipal fire departments and aviation authorities, concentrating purchasing power with fewer suppliers. NAFFCO and FIREX anchor multi-year contracts through performance-based pricing that ties payments to discharge test outcomes. Dubai Civil Defence and Abu Dhabi Police Aviation are most visible in this transition, consolidating previously fragmented emirate-level buying.
UAE Firefighting Foam Market Segmentation
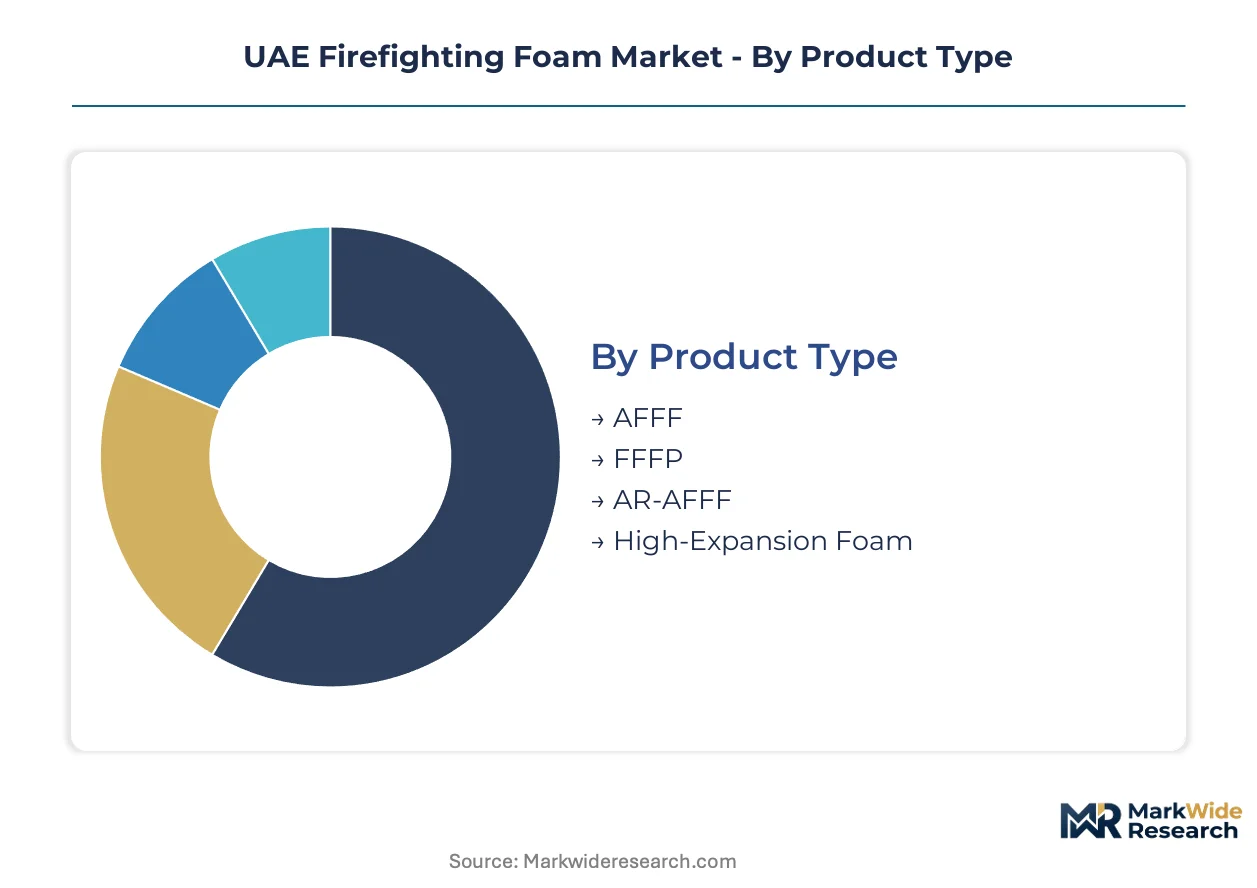
Segmentation in the UAE firefighting foam market tracks how environmental mandates and application-specific performance standards fragment procurement decisions across emirate-level buyers. Each dimension reveals distinct cost structures, certification requirements, and supplier relationships that shape competitive positioning.
Product Type:
Procurement teams weigh environmental compliance deadlines against legacy stockpile replacement costs when selecting formulations.
- AFFF:Fluorinated aqueous film-forming foam delivers superior film stability on hydrocarbon fires through fluorosurfactant chemistry. Dubai and Abu Dhabi municipal departments are phasing out existing inventories ahead of MOHAP restrictions, though aviation authorities maintain limited exemptions for critical infrastructure protection.
- AR-AFFF:Alcohol-resistant variants incorporate polymer additives to form protective membranes on polar solvent fires. Abu Dhabi's Ruwais petrochemical corridor drives concentrated demand for AR-AFFF in ethanol and methanol storage facilities where standard formulations fail.
- FFFP:Film-forming fluoroprotein foam combines protein hydrolysate bases with synthetic surfactants for enhanced burnback resistance. Marine applications at Port Khalifa and Fujairah bunkering terminals favor FFFP for its saltwater compatibility.
- High-Expansion Foam:Synthetic detergent-based concentrates achieve expansion ratios exceeding 200:1 for enclosed space flooding. Warehouse and tunnel protection systems in Dubai's logistics zones deploy high-expansion systems for rapid total-flood suppression.
Volume sits with AFFF; growth tilts toward AR-AFFF as petrochemical capacity expands.
End User:
Application environments determine concentrate specification, discharge equipment, and regulatory approval pathways.
- Aviation:ICAO-mandated performance thresholds for aircraft rescue and firefighting fleets sustain premium concentrate demand at Dubai International and Al Maktoum International. Foam discharge rates and burnback resistance specifications exceed industrial standards, creating certification barriers that limit supplier pools.
- Industrial:Tank farm operators across Jebel Ali, Ruwais, and Das Island procure bulk concentrates for hydrocarbon storage protection. MOHAP's tightening PFAS restrictions are compressing replacement timelines and reordering procurement hierarchies toward fluorine-free alternatives.
- Municipal:Civil Defence departments in Dubai, Abu Dhabi, and Sharjah are consolidating procurement through multi-year supply agreements. Performance-based pricing ties payments to discharge test outcomes, concentrating purchasing power with compliant domestic manufacturers.
- Marine:Port operations at Khalifa, Jebel Ali, and Fujairah require marine-certified foam systems for bulk liquid storage and bunkering. Specialized certifications for saltwater compatibility and environmental discharge limits create distinct supplier qualification requirements.
Industrial buyers anchor volume demand; aviation sustains margin premiums through performance mandates.
Form:
Scale of operations and storage infrastructure dictates concentrate versus ready-to-use procurement economics.
- Concentrates:Bulk concentrate procurement dominates refinery and tank farm deployments where on-site proportioning systems enable cost-efficient large-volume protection. Ruwais and Das Island operators maintain strategic concentrate inventories to ensure continuous coverage across expanded storage capacity.
- Ready-to-Use:Pre-mixed solutions eliminate proportioning equipment requirements for smaller municipal fleets and rapid-response vehicles. Dubai Civil Defence's mobile command units specify ready-to-use formulations to reduce deployment complexity during multi-site incidents.
- Portable:Self-contained extinguishers and mobile units serve confined-space applications and supplemental protection. Data center operators in Dubai's hyperscale cloud infrastructure cluster specify portable foam units for localized electrical fire risks.
- Bulk:Tanker-delivered bulk shipments serve fixed installation replenishment at major industrial complexes. Sharjah manufacturing zones receive bulk deliveries through dedicated logistics corridors to minimize supply interruption risks.
Concentrates capture the largest volume share; portable forms are gaining share fastest in emerging data center and logistics applications.
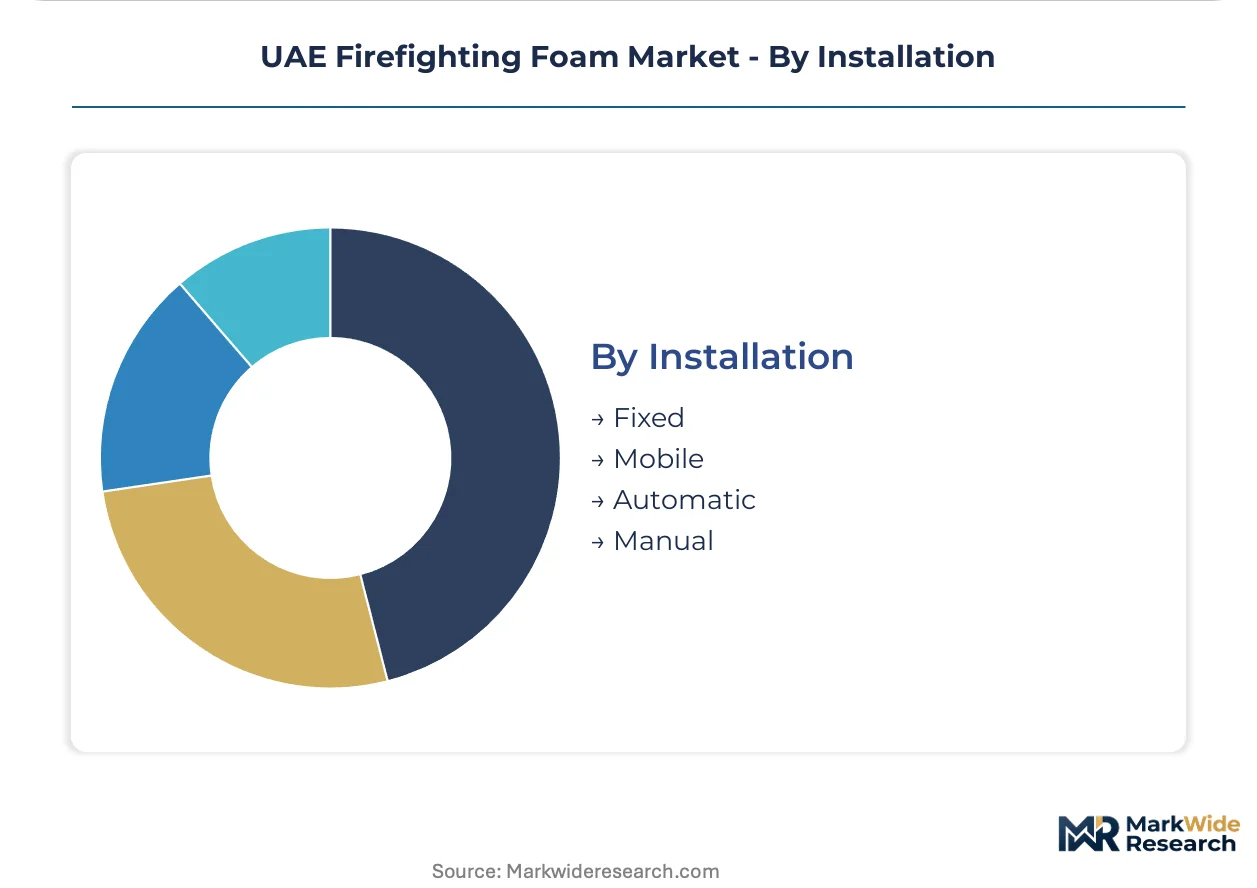
Installation:
Capital expenditure profiles and response-time requirements separate fixed infrastructure from mobile deployment strategies.
- Fixed:Permanent foam systems with dedicated concentrate storage, proportioning equipment, and distribution networks protect high-value static assets. Tank farms across Abu Dhabi's petrochemical corridor rely on fixed installations for continuous coverage of million-barrel storage tanks.
- Mobile:Vehicle-mounted foam systems and portable proportioning units enable flexible response across distributed facilities. Municipal departments in Dubai and Sharjah maintain mobile foam capabilities for multi-site industrial corridor protection.
- Automatic:Detection-triggered foam suppression systems protect unmanned facilities and rapid-response applications. Data centers and automated warehouses in Dubai's logistics zones specify automatic systems to minimize water damage and response latency.
- Manual:Handline and monitor operations remain standard for municipal firefighting and supplemental industrial response. Training requirements and equipment maintenance protocols favor manual systems where staffing levels support deployment.
Fixed installations dominate capital deployment; automatic systems show steepest expansion trajectory in unmanned facility protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Abu Dhabi's petrochemical corridor and Dubai's aviation hubs, with procurement patterns diverging between industrial bulk concentrate buyers and municipal fire departments pursuing fluorine-free transitions.
Dubai
Dubai International and Al Maktoum International airports sustain premium concentrate demand through ICAO-mandated aircraft rescue and firefighting standards. Dubai Civil Defence is consolidating procurement through multi-year supply agreements with performance-based pricing. Data center and logistics warehouse buildouts in Dubai South are driving automatic foam suppression system deployments.
Abu Dhabi
Tank farm expansions at Ruwais and Das Island anchor bulk concentrate procurement for hydrocarbon storage protection. The Abu Dhabi National Oil Company is front-loading fluorine-free replacement purchases to preempt MOHAP enforcement timelines. The Ruwais petrochemical corridor remains the highest-volume demand cluster for AR-AFFF formulations.
Sharjah
Sharjah's industrial manufacturing zones host concentrated domestic foam production capacity serving emirate-level procurement frameworks. The Sharjah Civil Defence maintains mobile foam capabilities for multi-site industrial corridor protection. Bulk delivery logistics corridors minimize supply interruption risks for fixed installation replenishment.
Northern Emirates
Ras Al Khaimah and Fujairah port expansions present underpenetrated demand for marine-certified foam systems in bulk liquid storage and bunkering operations. Fujairah's bunkering terminals favor FFFP formulations for saltwater compatibility. Port Khalifa operations are driving specialized marine foam certifications among suppliers.
UAE Firefighting Foam Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized certification niches and automated system integration. Domestic manufacturing capacity clusters in Sharjah and Dubai industrial zones, creating geographic concentration that favors localized supply relationships. Three archetypes dominate: integrated building-systems providers, specialized marine foam certifiers, and domestic manufacturers leveraging federal approval frameworks. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers position for multi-year municipal contracts.
Among UAE-based specialists, NAFFCO and FIREX exemplify contrasting positioning strategies. NAFFCO leverages its domestic manufacturing footprint to anchor government contracts across emirates, representing the integrated domestic archetype. FIREX competes through specialized marine foam certifications for Port Khalifa operations, occupying the niche certification tier. Johnson Controls extends its building-systems integration expertise into automated foam suppression, exemplifying the cross-sector technology transfer archetype.
| Leading Market Players |
|---|
| FIREX |
| BRISTOL Fire Engineering LLC |
| NAFFCO |
| Loshareh Chemical Industries |
| Johnson Controls |
| SFFECO Global |
| NATIONAL FOAM INC. |
| SEPPIC |
| Albilad Fighting Systems Ltd. |
| Others |
Value Network & Pricing Analysis
Municipal fire department consolidation into multi-year supply agreements is compressing supplier margins while rewarding scale-compliant domestic manufacturers with volume commitments and performance-based pricing structures.
Pricing Analysis
Volume concentrates in bulk concentrate procurement for Abu Dhabi's petrochemical corridor, while aviation-grade formulations at Dubai International and Al Maktoum International sustain margin premiums through ICAO-mandated performance thresholds. Price differentiation hinges on UAE Civil Defence certification tier and fluorine-free formulation compliance. Cost compression in legacy AFFF stockpiles is intensifying because MOHAP environmental deadlines are accelerating write-down schedules. Municipal departments show highest price sensitivity due to consolidated procurement frameworks, while aviation authorities exhibit lowest sensitivity given regulatory non-negotiability.
Supply Chain Analysis
UAE Civil Defence domestic-content requirements and federal approval frameworks are reshaping sourcing toward Sharjah and Dubai manufacturing zones, reducing import dependency for concentrate formulations. Geographic supply concentration centers on the UAE, with specialty surfactant feedstock draws from Germany and China. Raw material dependencies include synthetic hydrocarbon surfactants, polysaccharide polymers, and protein hydrolysate bases. Single-source vulnerability persists in fluorosurfactant inputs for transitional AFFF production. Distribution runs through emirate-level Civil Defence procurement corridors with dedicated logistics networks for bulk tank farm replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE firefighting foam market functions as a cost-of-compliance story where UAE Civil Defence certification frameworks create barrier-to-entry moats that favor incumbent domestic manufacturers with established federal approval pathways.
For Market Incumbents: Anchor multi-year performance contracts with Dubai and Abu Dhabi Civil Defence departments to lock out emerging competitors before GSO harmonization expands addressable markets. Deepen backward integration into surfactant production to offset fluorochemical input volatility threatening transitional product margins. Prioritize certification pre-positioning for anticipated ICAO fluorine-free amendments that would obsolete current aviation exemptions. For New Entrants and Emerging Players: Direct-to-municipal digital procurement platforms offer lower-friction entry than legacy distributor networks dominated by NAFFCO and FIREX. Target Ras Al Khaimah and Fujairah marine port expansions where specialized FFFP certification requirements have left incumbent coverage gaps. Pursue data center automatic suppression partnerships with Johnson Controls ecosystem integrators as the fastest-penetrating white-space application. For Investors and Strategic Acquirers: Re-rating potential sits with fluorine-free formulation specialists given MOHAP enforcement timeline acceleration compressing replacement demand into concentrated windows. Long-term viability favors manufacturers with captive UAE Civil Defence approval infrastructure rather than import-dependent distributors. Watch for GSO protocol ratification as the signal indicating cross-border certification portability and expanded TAM for domestic players.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Formulation Transition | MOHAP deadlines are forcing AFFF stockpile replacement, creating concentrated demand spikes for compliant suppliers. |
| UAE Civil Defence Certification Investment | Federal approval frameworks create multi-year revenue visibility through performance-tied municipal contracts. |
| Marine Foam Certification Acquisition | Port Khalifa and Fujairah bunkering expansion demands FFFP specialization with saltwater compatibility credentials. |
| Automatic Suppression System Integration | Dubai hyperscale data center buildout requires clean-agent foam hybrids protecting sensitive electronics infrastructure. |
| GSO Harmonization Pre-Positioning | Anticipated Gulf Standardization Organization alignment enables cross-border certification portability for domestic manufacturers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with UAE Civil Defence procurement officers, petrochemical tank farm operations managers, aviation authority fire chiefs, foam concentrate plant managers, and marine port safety directors. Secondary sources included UAE Civil Defence certification databases, Emirates Authority for Standardization and Metrology quality benchmarks, MOHAP environmental health directives, and Gulf Standardization Organization protocol drafts. Bottom-up concentrate volume estimates triangulated against top-down emirate-level procurement budget allocations.
Segmentation granularity modeled product type at formulation chemistry level, end user at application environment level, form at logistics economics level, and installation at capital deployment level across the projection horizon. CAGRs derived from emirate-level procurement pipeline analysis and replacement cycle compression effects. Industry-specific forecast inputs included ICAO amendment timelines and MOHAP enforcement phase-in schedules.
Inputs from UAE regulatory filings and port authority expansion plans were available through the study window; gaps in Northern Emirates municipal procurement data introduce uncertainty bands around Ras Al Khaimah and Fujairah demand trajectories. Forecasts reflect assumptions regarding GSO protocol ratification timing and fluorine-free formulation technical performance maturation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Heptafluoropropane Fire Suppression System Market
Fire Safety & Protection
Global Fire Suppression System Market
Fire Safety & Protection
Powder Fire Suppression System Market
Fire Safety & Protection
Wireless Fire Detection Systems Market
Fire Safety & Protection
Global Flame Arrestors Market
Fire Safety & Protection
Europe Fire-Resistant Glass Market
Fire Safety & Protection
Africa Fire Suppression Market
Fire Safety & Protection
Fire Safety Equipment Market
Fire Safety & Protection
Fire Pump Market
Fire Safety & Protection
Smoke Pressure System Market
Fire Safety & Protection
Australia Emergency Lighting Market
Fire Safety & Protection
US Fire Safety Equipment Market
Fire Safety & Protection
Smart Smoke Alarm Market
Fire Safety & Protection
Fire Extinguisher Market
Fire Safety & Protection
Fire Protection Systems Market
Fire Safety & Protection
Passive Fire Proofing System Market