
 United States Fire Sprinklers Market | 2026-2036
United States Fire Sprinklers Market Size, Share, and Industry Trends Forecast 2026-2036
United States Fire Sprinklers Market Intelligence
The gap between premium engineered systems and commodity-grade sprinklers is expanding as fire codes tighten and insurance underwriters demand higher performance documentation. Viking Group leverages its vertical manufacturing footprint to control component quality from alloy casting to final assembly. Johnson Controls anchors its position through deep integration with building automation platforms, while Reliable Automatic Sprinkler Co. specializes in custom fabrication for complex industrial hazards.
Fire sprinklers are thermally activated water distribution devices engineered to discharge pressurized water at designated flow rates once fusible elements reach specific temperature thresholds, primarily functioning to suppress or control fire growth until emergency response arrives. Wet pipe systems dominate installed base volume due to simplicity and reliability, though pre-action technology captures premium margins in data center and museum applications where accidental discharge carries catastrophic asset risk. Wireless detection technology is displacing conventional hardwired architectures in retrofit commercial environments where conduit installation proves prohibitively disruptive.
National Fire Protection Association standards, International Building Code adoption at state and municipal levels, and OSHA workplace safety directives collectively mandate sprinkler coverage across expanding building categories and occupancy types. The Department of Housing and Urban Development and state-level fire marshals enforce compliance timelines that directly shape replacement cycles and new construction specifications. Stakeholders must monitor emerging proposals around residential sprinkler mandates in single-family construction and evolving environmental standards for fire suppression chemistry.
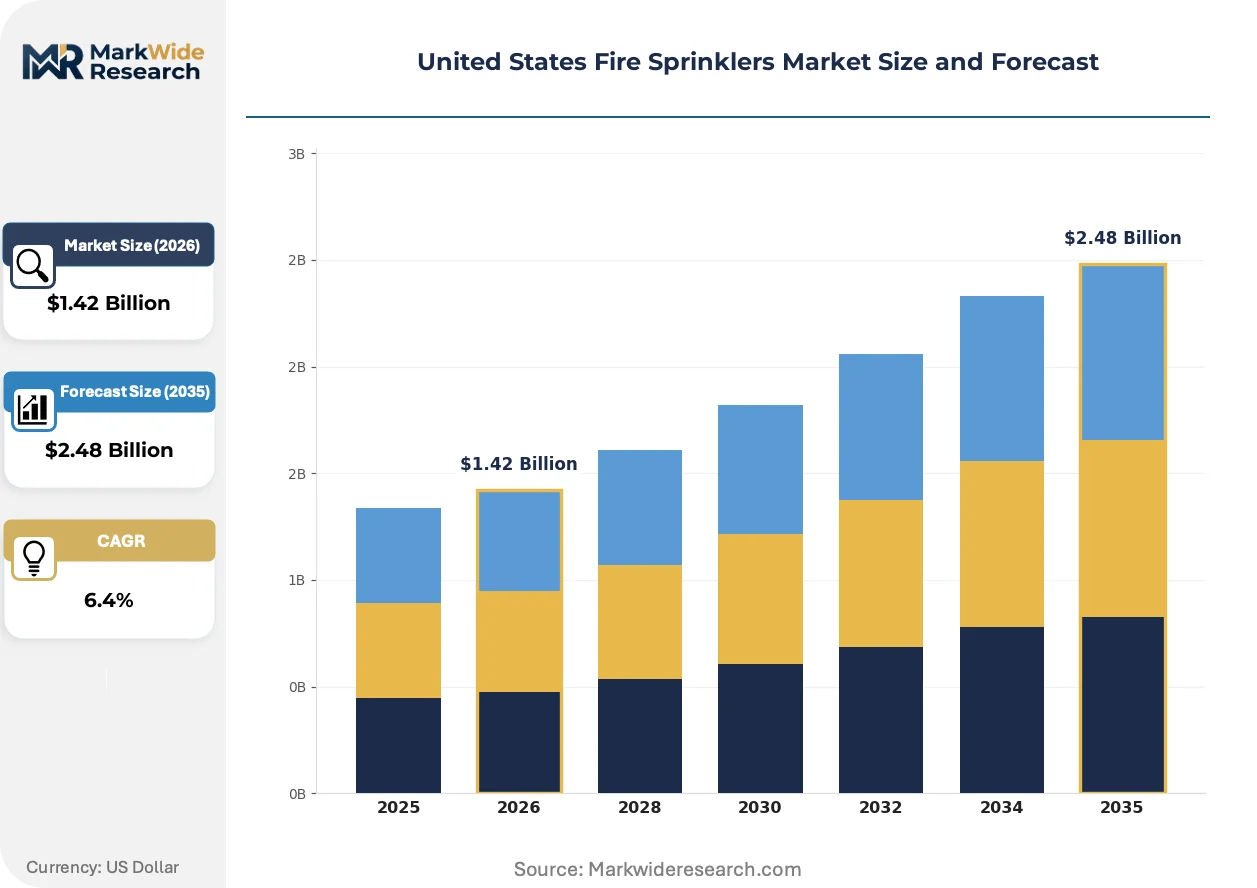
Market Dynamics
NFPA 13 code revisions and smart sensor integration are tightening performance thresholds across the installed base. Commercial building owners in high-rise corridors face accelerated retrofit timelines as insurance underwriters demand higher documentation standards.
Growth Catalysts
- NFPA 13 Compliance Mandates:Code revisions expanding sprinkler coverage to previously exempt occupancy types are forcing wholesale system upgrades in aging commercial stock. State fire marshals in Texas, Florida, and California enforce the strictest adoption timelines.
- Wildfire Exposure Concentration:California's wildland-urban interface expansion is driving residential sprinkler mandates into single-family construction zones. Local jurisdictions are preempting state legislation with accelerated ordinances.
- Smart Detection Convergence:Wireless sensor networks paired with cloud-based monitoring platforms are reducing retrofit installation costs by eliminating conduit runs. Facility managers in historic buildings are prioritizing these architectures.
Market Restraints
- Copper and Brass Input Volatility:Alloy casting feedstock prices fluctuate with commodity cycles, compressing margins for component fabricators. Foundry capacity concentrates in the Great Lakes region.
- Licensed Contractor Scarcity:NICET-certified technicians and master sprinkler fitters face generational workforce gaps. Training pipeline limitations extend project timelines in high-demand metros.
- Pre-Action System Complexity:Double-interlock configurations for data center applications require specialized engineering that commodity installers cannot execute. Technical capability fragmentation limits addressable market expansion.
Strategic Opportunities
- Residential Single-Family Underpenetration:Voluntary sprinkler installation rates in new detached housing remain below fifteen percent outside mandate zones. Homebuilder education partnerships could accelerate voluntary adoption.
- Industrial Hazard Custom Fabrication:Chemical processing and cold storage facilities require engineered solutions outside standard catalog offerings. Application-specific design capabilities command premium pricing.
- Building Automation Integration:API-native sprinkler systems communicating directly with Johnson Controls and Siemens BAS platforms are displacing standalone architectures. Integration partnerships with controls vendors create channel leverage.
Industry Challenges
- NICET Certification Bottlenecks:Examination backlogs and limited testing center availability delay technician credentialing. Project staffing constraints force wage inflation in competitive labor markets.
- Legacy Infrastructure Compatibility:Wet pipe systems installed before 1990 often lack pressure monitoring and flow detection capabilities. Retrofit sensor integration requires invasive pipe modifications.
- Environmental Chemistry Standards:Proposed EPA restrictions on per- and polyfluoroalkyl substances in fire suppression foams may cascade into sprinkler system material specifications. Formulation transitions demand recertification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Fire Sprinklers Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Pipe, Dry Pipe, Pre-Action, Deluge Application: Commercial Buildings, Industrial Facilities, Residential Areas, Warehouses Technology: Conventional, Addressable, Wireless, Hybrid Installation Type: New Construction, Retrofit, Maintenance, Testing |
| Companies Covered | Viking Group, Honeywell, API Group Inc., The Viking Corporation, Potter Electric Signal Company, EMCOR Group Inc., Reliable Automatic Sprinkler Co. Inc, Victaulic Company, Johnson Controls, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Fire Sprinklers Market Strategic Shifts & Innovations
Wireless detection architectures and modular system designs are compressing installation timelines while expanding addressable retrofit opportunities. Regulatory pressure and buyer sophistication are converging to reward integrated performance documentation.
Smart sprinkler nodes incorporating temperature, pressure, and flow sensors in single housing units are modularizing system architecture. Data center operators and museum facilities are adopting these configurations fastest. Component standardization is enabling faster field configuration and reducing custom engineering overhead.
OSHA workplace safety directives and state-level fire marshal enforcement timelines are mandating documented inspection frequencies and digital record retention. Commercial property insurers are requiring NFPA 25 compliance verification as a condition of coverage renewal. High-rise office buildings in Chicago, Houston, and Los Angeles face the most aggressive compliance deadlines.
Facility managers are consolidating vendor relationships around single-source accountability for detection, suppression, and monitoring. National account procurement teams at retail and hospitality chains are replacing fragmented local contractor networks with master service agreements. This concentration is most visible in the Sun Belt states where construction velocity supports dedicated regional service infrastructure.
United States Fire Sprinklers Market Segmentation
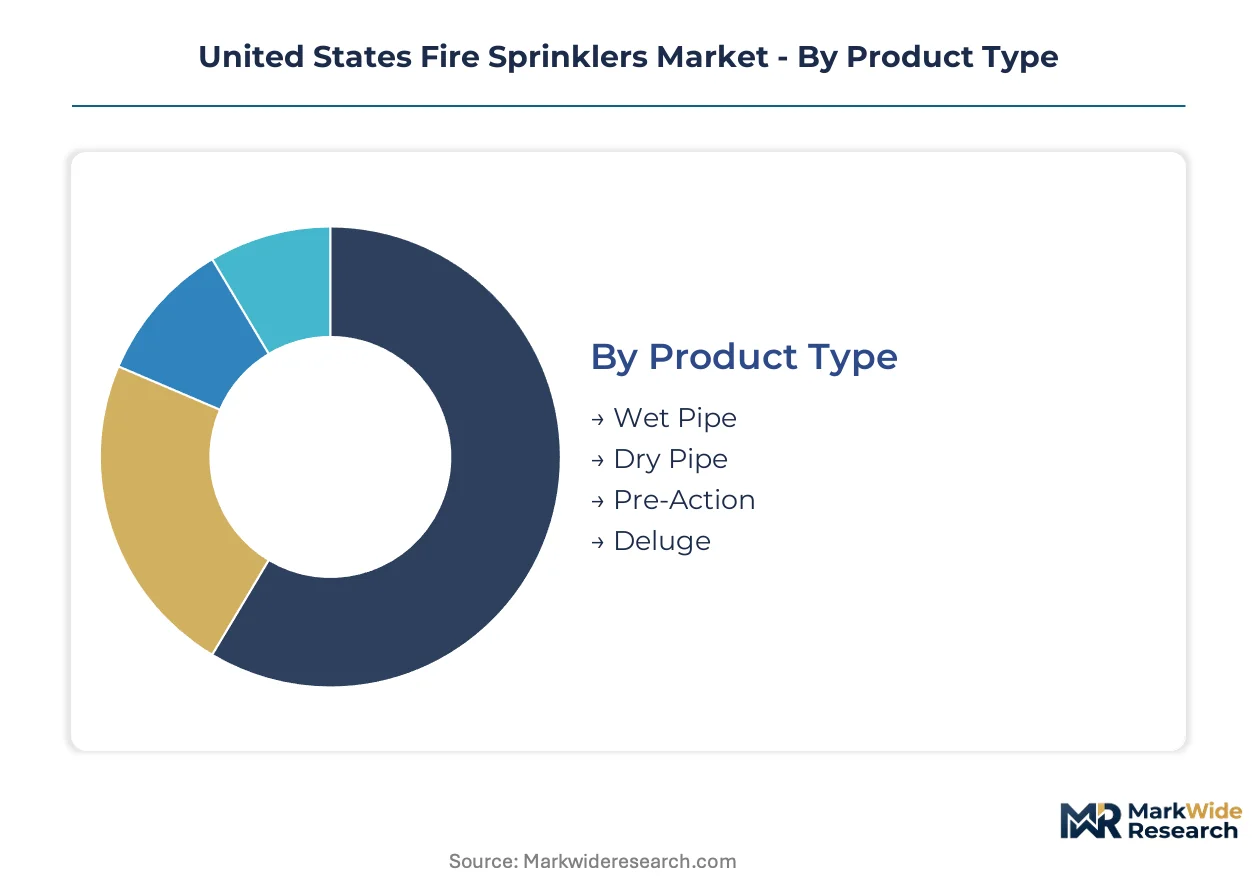
Fire sprinkler market segmentation reflects divergent buyer priorities across risk tolerance, construction timing, and regulatory exposure. System selection hinges on asset criticality, environmental conditions, and integration requirements with building automation infrastructure.
Product Type:
Cost tier differentiation separates commodity-specified projects from engineered performance mandates.
- Wet Pipe:Constantly pressurized water-filled piping delivers immediate discharge upon fusible element activation. Demand concentrates in Texas and Florida commercial mid-rise construction where simplicity and reliability outweigh freeze-risk concerns. Municipal code adoption timelines in Sun Belt metros accelerate specification.
- Pre-Action:Double-interlock pneumatic-electronic activation prevents accidental discharge in spaces housing irreplaceable assets. California data centers and Chicago museums specify these systems despite premium engineering costs. Water damage exposure drives substitution away from wet pipe in critical facilities.
- Dry Pipe:Pressurized air or nitrogen holds water back until activation, protecting unheated warehouse and parking structures in cold-climate states.
- Deluge:Open-nozzle systems flood entire zones simultaneously for high-hazard industrial chemical processing environments.
Wet pipe leads volumes today; pre-action is gaining share fastest.
Application:
Volume concentration tracks construction velocity and regulatory enforcement intensity across occupancy categories.
- Commercial Buildings:High-rise office and retail corridors in Houston, Los Angeles, and Chicago face accelerated retrofit deadlines under NFPA 13 expansion mandates. Insurance underwriters now require documented NFPA 25 compliance verification for coverage renewal.
- Industrial Facilities:Chemical processing, cold storage, and heavy manufacturing demand custom-engineered hazard-specific suppression architectures. Texas Gulf Coast petrochemical clusters and Ohio River Valley manufacturing corridors specify application-designed systems outside standard catalogs.
- Residential Areas:Single-family detached construction in California wildland-urban interface zones faces emerging sprinkler mandates. Local jurisdictions preempt state legislation.
- Warehouses:E-commerce fulfillment center construction in Georgia and Pennsylvania drives specification of early suppression fast-response systems for high-piled storage.
Commercial buildings anchor current revenue; industrial facilities show steepest expansion trajectory.
Technology:
Installation disruption tolerance determines architecture selection in retrofit versus new construction contexts.
- Wireless:Battery-powered sensor networks eliminate conduit runs in historic building renovations where structural penetration is prohibited. Facility managers in Boston and Philadelphia prioritize these architectures for accelerated compliance timelines.
- Addressable:Digital device identification enables pinpoint location reporting to fire alarm control panels and building automation systems. Data center operators in Northern Virginia and Dallas specify addressable loops for maintenance efficiency.
- Conventional:Hardwired zone-based detection remains specified in cost-sensitive new construction where conduit installation is unobstructed.
- Hybrid:Combined wired-wireless architectures bridge legacy infrastructure with expanded coverage requirements in campus environments.
Conventional technology retains installed base dominance; wireless is climbing the fastest.
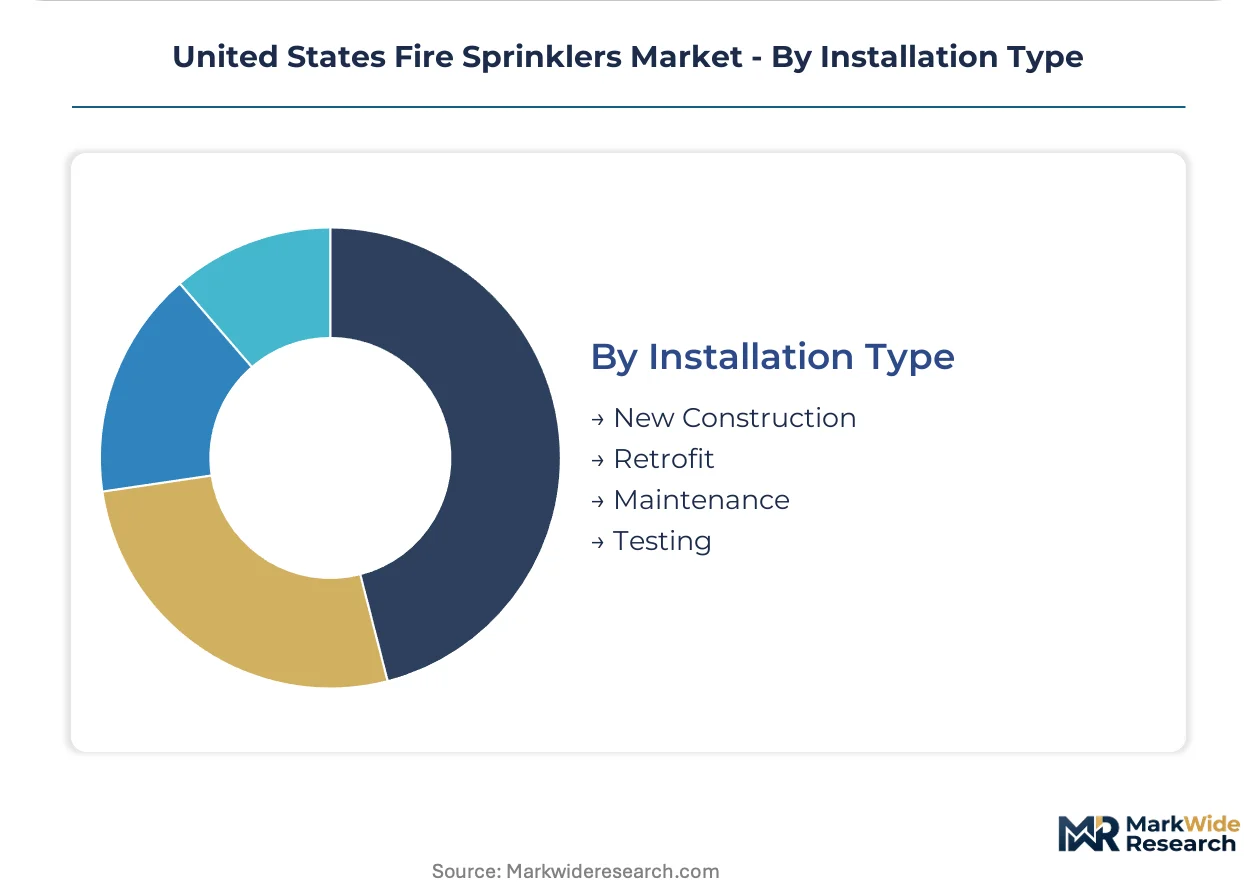
Installation Type:
Project timing relative to construction cycle determines margin structure and contractor capability requirements.
- Retrofit:Existing building sprinkler additions in pre-1990 commercial stock require invasive ceiling and structural modifications. NICET-certified technician scarcity extends timelines in high-demand metros including Miami and Seattle.
- New Construction:Integrated design-build specifications allow optimal routing and coordination with mechanical and electrical trades. Volume concentrates in Texas, Florida, and California where permitting velocity supports dedicated regional contractor infrastructure.
- Maintenance:NFPA 25-mandated inspection, testing, and maintenance contracts generate recurring revenue streams.
- Testing:Hydrostatic and flow testing verification requirements intensify under insurer documentation demands.
New construction drives absolute volumes; retrofit commands premium pricing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Licensed sprinkler fitters and NICET-certified technicians concentrate in Sun Belt construction corridors, creating regional service capacity imbalances that shape project timelines and pricing power across state markets.
Texas
Houston and Dallas-Fort Worth metroplexes drive commercial high-rise retrofit demand as insurers enforce NFPA 25 documentation deadlines. The Texas State Fire Marshal's office mandates accelerated compliance timelines for pre-1990 office stock. Gulf Coast petrochemical clusters around Baytown and Beaumont specify custom-engineered deluge systems for chemical processing hazards.
California
Wildland-urban interface expansion in Los Angeles, San Diego, and Sacramento metro areas is forcing residential sprinkler mandates into single-family construction zones. The California State Fire Marshal and local jurisdictions preempt state legislation with accelerated ordinances. Silicon Valley data centers in Santa Clara County specify pre-action double-interlock systems to protect irreplaceable server assets from accidental discharge.
Florida
Miami and Tampa commercial corridors face aggressive NFPA 13 retrofit deadlines as hurricane-resistant construction codes intersect with fire safety mandates. The Florida State Fire Marshal enforces strict adoption timelines for aging high-rise inventory. Orlando hospitality and retail chains are consolidating vendor relationships around master service agreements with dedicated regional infrastructure.
Illinois
Chicago's historic high-rise office stock requires invasive ceiling modifications for wireless sensor retrofit in buildings where structural penetration is prohibited. The Illinois State Fire Marshal coordinates with municipal inspectors on compliance verification. Northern Illinois distribution and logistics corridors specify early suppression fast-response systems for e-commerce fulfillment center construction.
Pennsylvania
Philadelphia historic building renovations prioritize wireless detection architectures to eliminate conduit runs in protected structures. The Pennsylvania Department of Labor and Industry oversees NICET certification requirements that constrain technician supply. Pittsburgh and Harrisburg industrial facilities demand custom fabrication for cold storage and heavy manufacturing hazards outside standard catalog offerings.
United States Fire Sprinklers Market Key Industry Players
Capital-heavy producers with captive foundry and casting operations compete with asset-light designers and system integrators who source components through distributed supply chains. The vendor base organizes around three strategic archetypes: vertically integrated manufacturers controlling alloy feedstock through final assembly, building automation platforms embedding suppression into integrated control stacks, and specialized fabricators engineering hazard-specific solutions for industrial applications. Dominant competitive moves include backward integration into component manufacturing and strategic partnerships with controls vendors for API-native integration.
Among integrated manufacturers, Viking Group exemplifies the foundry-to-assembly archetype with upstream control over alloy casting quality. Johnson Controls anchors the building automation convergence tier, while Reliable Automatic Sprinkler Co. occupies a position within the custom fabrication specialist segment. These three patterns represent the structural positioning available to competitors navigating tightening code enforcement and buyer consolidation around single-source accountability.
| Leading Market Players |
|---|
| Viking Group |
| Honeywell |
| API Group Inc. |
| The Viking Corporation |
| Potter Electric Signal Company |
| EMCOR Group Inc. |
| Reliable Automatic Sprinkler Co. Inc |
| Victaulic Company |
| Johnson Controls |
| Others |
Cost & Logistics Intelligence
Backward integration into captive foundry operations anchors pricing power for alloy casting specialists while insulating margin structures from commodity feedstock cycles. Johnson Controls and Viking Group leverage in-house component manufacturing to command premium positioning against asset-light system integrators who source through distributed supplier networks.
Pricing Analysis
The bundled-versus-unbundled service split separates project-based installation contracts from recurring maintenance agreements. Three-tier pricing structure across premium engineered, standard catalog, and economy commodity levels reflects certification grade differentiation and after-sales service bundling. Cost compression in the economy tier is intensifying because copper and brass input volatility squeezes fabricator margins. National account procurement teams at retail and hospitality chains exhibit lowest price sensitivity due to single-source accountability requirements, while independent commercial building owners in secondary metros drive hardest bargain negotiations.
Supply Chain Analysis
NICET-certified technician scarcity in the Great Lakes foundry corridor and Sun Belt installation markets constrains output velocity and extends project timelines. Alloy casting feedstock draws from domestic Great Lakes smelters and imported brass billet, while fusible element manufacturing sources from precision metalworking clusters in Ohio and Pennsylvania. Single-source vulnerability concentrates in specialized pre-action valve assembly where qualified engineering houses number fewer than twenty nationwide. Distribution runs through master service agreements with national account procurement teams replacing fragmented local contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in fire sprinklers rests on smart sensor premiumization and workforce automation offsetting labor scarcity cost inflation. The shift from commodity wet pipe specification toward pre-action engineered systems elevates average selling prices across commercial and industrial verticals.
For Market Incumbents: Acquire wireless detection technology IP to defend against building automation platform encroachment. Deepen API-native integration partnerships with Siemens and Honeywell BAS architectures to lock out standalone competitors. Expand NICET-certified training pipeline capacity in Texas and Florida to capture retrofit demand before contractor scarcity forces project delays. Prioritize backward integration into sensor module fabrication rather than relying on distributed electronics suppliers exposed to semiconductor allocation volatility. For New Entrants and Emerging Players: Cloud-based monitoring platform subscriptions offer the lowest competitive density entry vector. Target California residential single-family construction zones where wildland-urban interface mandates are accelerating faster than incumbent service infrastructure can deploy. Position around wireless retrofit architectures for historic Boston and Philadelphia commercial buildings where conduit prohibition creates specification preference. Pursue direct facility manager relationships bypassing established mechanical contractor channels through digital specification tools. For Investors and Strategic Acquirers: Roll-up economics work for regional sprinkler service consolidators because NICET certification bottlenecks create artificial scarcity premiums for credentialed technician bases. The five-to-ten year viability window favors platforms assembling master service agreement portfolios with national account retail and hospitality chains. Acquisition target archetype: Sun Belt-based contractors with captive NICET-certified crews and existing Johnson Controls or Viking Group distribution authorization. Watch California State Fire Marshal residential mandate enforcement velocity as inflection indicator for single-family penetration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Sensor Module Development | API-native temperature-pressure-flow nodes integrate directly with Johnson Controls BAS platforms. |
| NICET Certification Pipeline Expansion | In-house technician training programs bypass examination backlogs constraining competitor staffing. |
| Pre-Action System Engineering Capability | Double-interlock specialization captures data center and museum premium specification. |
| Wireless Retrofit Architecture Rollout | Battery-powered sensor networks eliminate conduit runs in historic building compliance projects. |
| Master Service Agreement Consolidation | Single-source accountability contracts displace fragmented local contractor networks. |
Research Approach
Bottom-up commercial building retrofit and new construction modeling reconciled against top-down alloy casting and component manufacturing tracking forms the analytical core. Primary interviews with fire protection engineers, NICET-certified technicians, state fire marshal enforcement officers, commercial property insurance underwriters, and national account procurement directors combined with secondary validation against NFPA technical committee minutes, HUD enforcement guidance, state building code adoption databases, and OSHA workplace safety directive filings. Triangulation across installation volume estimates and foundry production capacity assessments ensures consistency.
Input-output matrices map copper and brass feedstock flows through casting operations to finished sprinkler assembly, cross-referenced against contractor licensing databases and permitting velocity by metro. Segmentation dimensions include system type, application category, technology architecture, and installation timing relative to construction cycle. CAGRs derive from regression against construction spending indices, code adoption timeline acceleration, and insurance mandate enforcement intensity. Wildland-urban interface expansion rates and data center construction pipelines provide industry-specific forecast inputs across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for wireless detection convergence would alter the outlook if hardwired architectures retain preference in new construction cost optimization. Forecasts reflect assumptions around NICET certification pipeline expansion, NFPA 13 adoption timeline enforcement, and copper commodity price stabilization. Material deviation in state fire marshal staffing levels, EPA fire suppression chemistry restrictions, or master service agreement procurement consolidation velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Flame Detector System Market
Fire Safety & Protection
Fire Extinguisher Market
Fire Safety & Protection
GCC Firefighting Foam Market
Fire Safety & Protection
Commercial Smoke Alarm Market
Fire Safety & Protection
Heptafluoropropane Fire Suppression System Market
Fire Safety & Protection
Fire and Rescue Helmets Market
Fire Safety & Protection
North America Fire Protection Water Storage Tanks Market
Fire Safety & Protection
China Thermal Protector Market
Fire Safety & Protection
Fire Suppression Agent Market
Fire Safety & Protection
Global Fire Suppression System Market
Fire Safety & Protection
Global Fixed Firefighting Misting System Market
Fire Safety & Protection
Cellulosic Fire Protection Market
Fire Safety & Protection
Smoke and Carbon Monoxide Alarm Market
Fire Safety & Protection
Fire Door Market
Fire Safety & Protection
US Fire Alarm and Detection Market
Fire Safety & Protection
Earthing Lightning Protection System Market