
 Smart Smoke Detector Market | 2026-2036
Smart Smoke Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Smoke Detector Market Outlook
UL 217 and EN 54 certification expansion is expanding the cost-of-entry calculus for manufacturers targeting cross-border sales. Honeywell International Inc. leverages its building automation ecosystem to bundle detection with HVAC controls. Johnson Controls International Plc anchors its position through professional installation channels in commercial real estate. Resideo Technologies differentiates on DIY retrofit compatibility with legacy alarm panels.
A smart smoke detector is an electromechanical safety device employing photoelectric or ionization sensors with embedded wireless transceivers, typically operating at 2.4 GHz or sub-GHz frequencies to relay alarm states to central monitoring systems or mobile applications; its primary purpose is to reduce fire-related fatalities and property damage through faster alert distribution and remote status verification. Wireless product types now capture the fastest growth trajectory as mesh networking protocols eliminate hardwiring costs in renovation projects. Photoelectric technology leads installed base volumes due to superior smoldering-fire detection and reduced nuisance alarms, though combination units command premium positioning. Residential end users dominate unit shipments while commercial installations generate higher per-node revenue through integrated systems and professional monitoring contracts.
The US Consumer Product Safety Commission works alongside state fire marshals to mandate interconnected alarms in multi-family dwellings, while the EU Construction Products Regulation harmonizes safety device compliance across member borders. China's SAMR enforces GB standards for domestic IoT device cybersecurity, creating parallel certification burdens for exporters. Stakeholders must monitor fragmentation between regional radio frequency allocations and cloud data residency rules when designing unified product platforms.
Market Dynamics
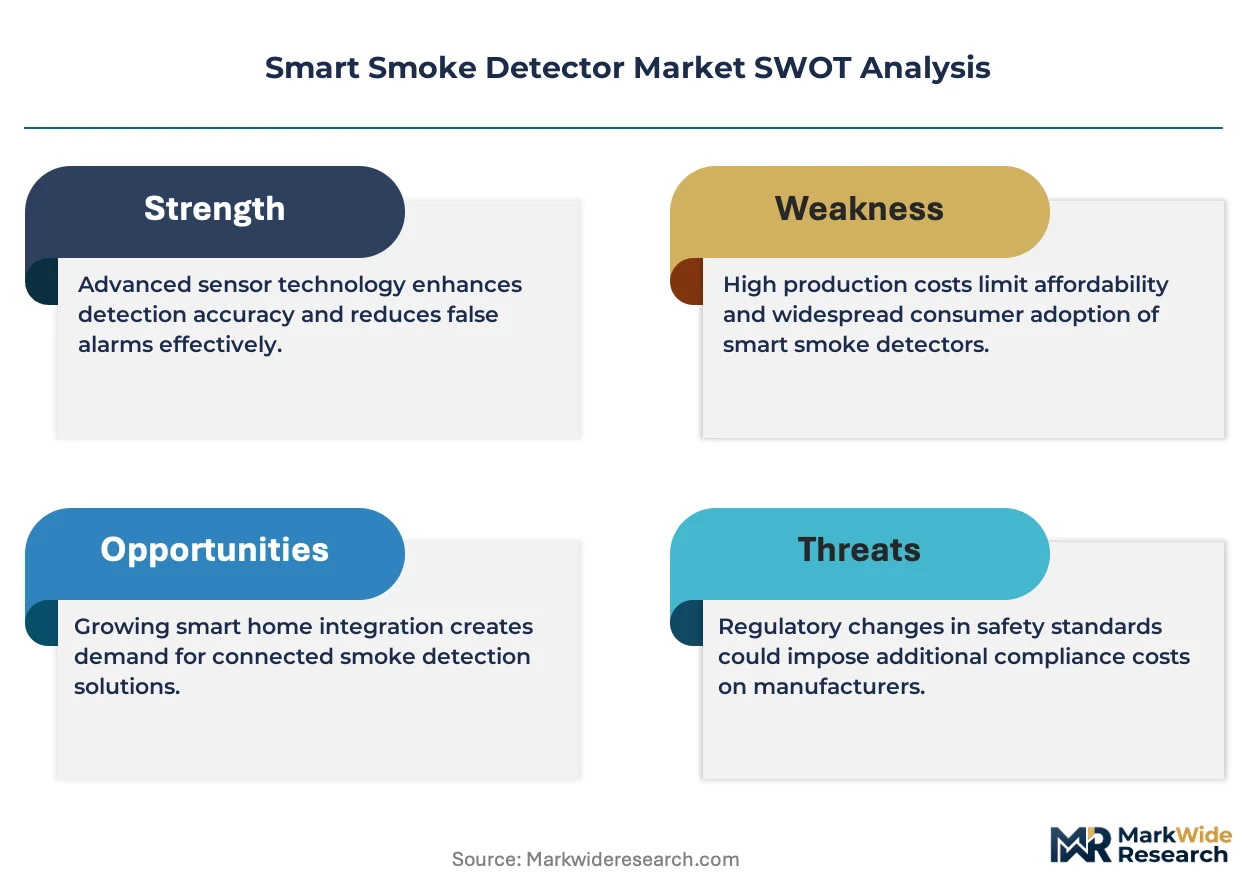
The smart smoke detector market is restructuring around mesh networking protocol adoption, which eliminates hardwiring infrastructure in renovation projects and shifts value capture toward software-integrated platform providers.
Growth Catalysts
- EU Green Deal building renovation targets:Municipal housing authorities across Germany, France, and the Netherlands mandate networked detection in public buildings, creating mandated retrofit demand.
- Photoelectric sensor superiority:Smoldering-fire detection capabilities and reduced nuisance alarm rates drive replacement of ionization units in residential installations.
- Multi-family dwelling codes:US state fire marshals enforce interconnected alarm requirements in apartment construction, accelerating specification of wireless mesh systems.
Market Restraints
- Silicon chip supply concentration:Taiwan-based foundry capacity constraints create lead time volatility for embedded wireless transceiver modules.
- Parallel certification burdens:China's SAMR enforces GB cybersecurity standards for domestic IoT devices, forcing exporters to maintain separate product variants.
- Legacy alarm panel incompatibility:Hardwired 12V notification appliance circuits in pre-2010 commercial buildings resist seamless wireless retrofit without gateway hardware.
Strategic Opportunities
- Professional monitoring channel expansion:Commercial real estate operators bundle detection with HVAC controls through building automation integrators, capturing recurring revenue streams.
- Sub-GHz frequency adoption:Lower band wireless protocols penetrate dense concrete structures in high-rise residential towers where 2.4 GHz experiences interference.
- India's smart city infrastructure:Municipal fire departments in Mumbai and Delhi pilot city-wide mesh networks for centralized incident response coordination.
Industry Challenges
- RF engineering talent scarcity:Embedded systems developers with sub-GHz protocol expertise command premium compensation, constraining product development velocity for mid-tier manufacturers.
- UL 217 Edition 8 transition timelines:Revised smoke sensitivity and nuisance alarm testing protocols extend certification cycles by four to six months for multi-sensor units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Smoke Detector Market |
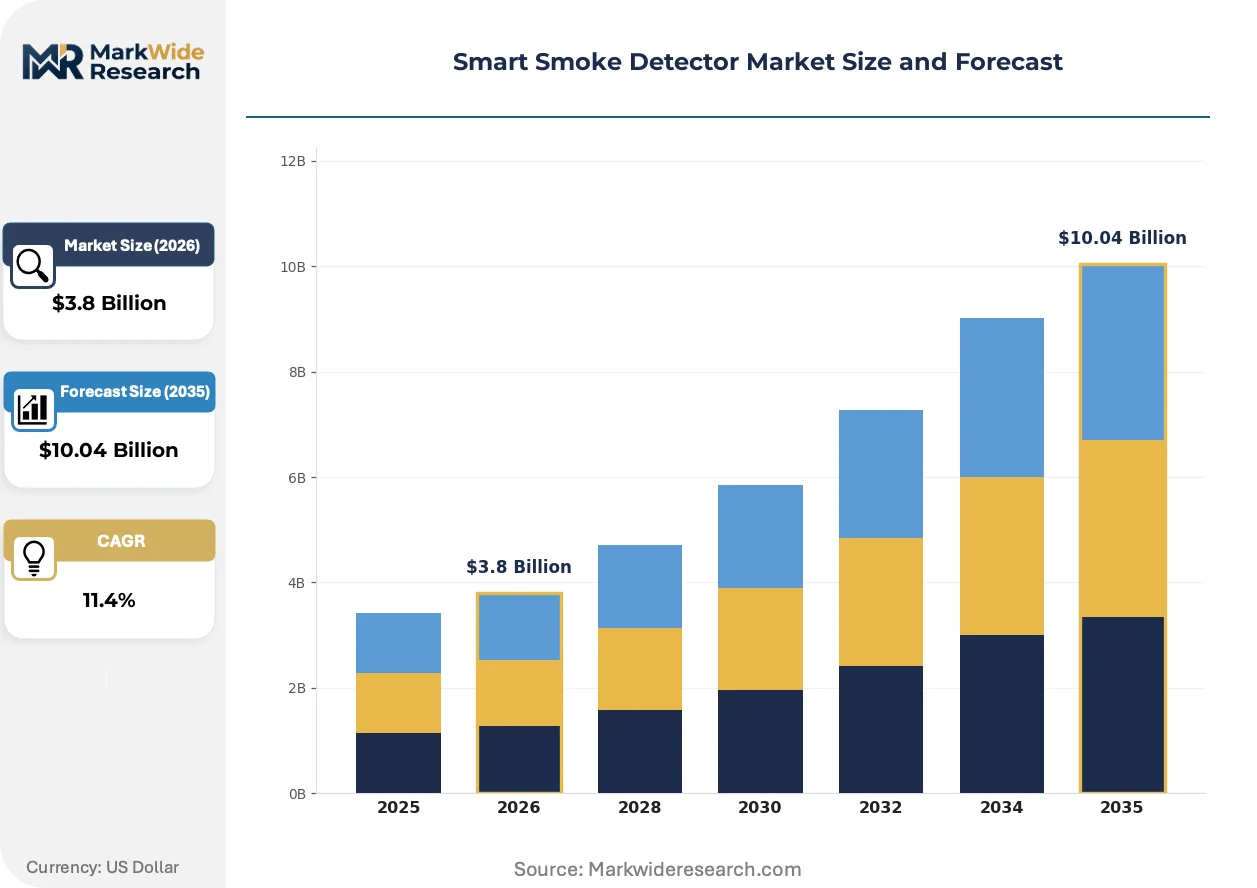
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery-Powered, Wired, Wireless, Smart Hub Technology: Photoelectric, Ionization, Combination, Smart Connectivity End User: Residential, Commercial, Industrial, Government Installation: Do-It-Yourself, Professional, Integrated Systems, Retrofit |
| Companies Covered | Honeywell International Inc., Johnson Controls International Plc, Robert Bosch GmbH, Siemens AG, Google Nest, Resideo Technologies, Schneider Electric SE, Kidde, First Alert, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Smoke Detector Market Strategic Shifts
Product architecture is converging around platform-centric models where detection hardware serves as a data node within broader building automation ecosystems rather than standalone safety equipment.
Multi-criteria detection technology is absorbing environmental sensing capabilities beyond smoke particles. Advanced units now integrate carbon monoxide, temperature, and humidity sensors into unified sensor arrays. Residential builders in North America specify these enhanced platforms as standard in new construction, compressing margins for single-function competitors.
REACH chemical restrictions and RoHS substance limitations are forcing reformulation of ionization chamber materials across European supply chains. Manufacturers must qualify americium-241 alternative detection methods or shift entirely to photoelectric architectures. German industrial safety distributors report accelerated stocking of combination photoelectric-CO units ahead of compliance deadlines.
Facility managers increasingly specify outcome-based service agreements rather than capital equipment purchases. Commercial real estate owners in the United States contract with Johnson Controls and Honeywell for per-square-foot fire safety coverage, transferring sensor maintenance and monitoring liability to installation partners. This procurement compression is most visible in Class A office towers across Chicago, Houston, and Seattle.
Smart Smoke Detector Market Segmentation
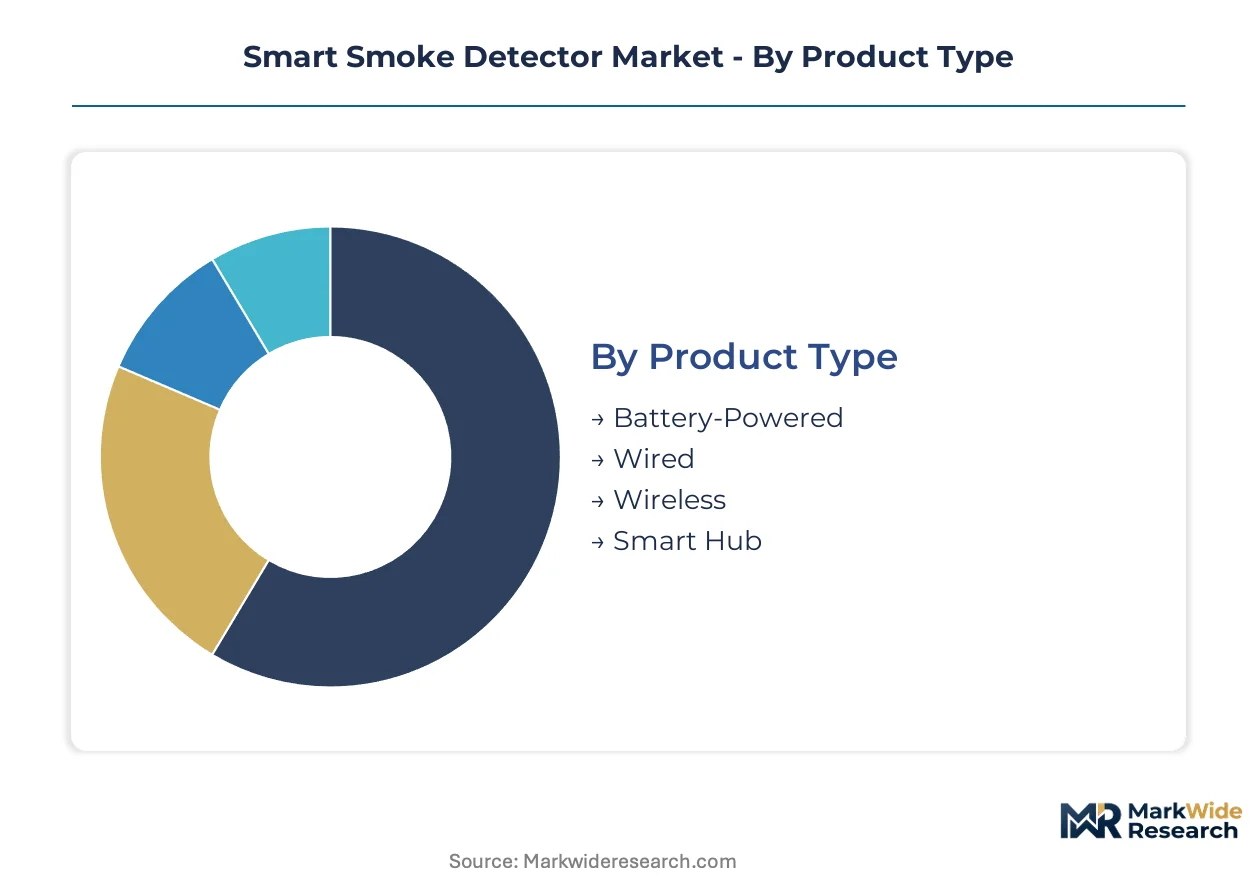
Smart smoke detector purchasing decisions hinge on installation constraints, retrofit feasibility, and integration depth with existing building infrastructure. Segmentation reveals how mesh networking protocols and professional monitoring contracts reshape value capture across hardware categories.
Product Type:
Buyers weigh upfront hardware cost against lifetime wiring and maintenance expenses when selecting power and connectivity architectures.
- Battery-Powered:Self-contained units with 10-year lithium cells eliminate electrical contractor requirements. Residential landlords in Germany specify these for rapid deployment across municipal housing portfolios ahead of EU Green Deal renovation deadlines.
- Wireless:Embedded 2.4 GHz or sub-GHz transceivers enable mesh networking without hardwiring. Commercial real estate operators in Chicago and Houston favor these for Class A office retrofits where concrete cores obstruct traditional cabling.
- Wired:Hardwired 120V or 12V notification appliance circuits dominate pre-2010 commercial installations. Legacy panel incompatibility forces gateway hardware purchases during wireless migration.
- Smart Hub:Centralized coordination nodes aggregate sensor data for building automation platforms. HVAC integrators bundle these with climate controls to capture recurring service revenue.
Volume sits with Battery-Powered; growth tilts toward Wireless.
Technology:
Detection method selection tracks fire type risk profiles and regulatory sensitivity mandates across end-use environments.
- Photoelectric:Light-scattering sensors detect smoldering fires with reduced nuisance alarm rates. REACH chemical restrictions and RoHS limitations accelerate replacement of ionization units across European supply chains.
- Combination:Multi-criteria arrays fuse smoke, carbon monoxide, temperature, and humidity sensing. Residential builders in North America specify these as standard in new construction, compressing single-function competitor margins.
- Ionization:Americium-241 chambers detect fast-flaming combustion. Reformulation requirements under ECHA substance limitations force manufacturers to qualify alternative detection methods or abandon this architecture entirely.
- Smart Connectivity:Protocol-agnostic transceivers support multiple wireless standards simultaneously. China's SAMR GB cybersecurity standards create parallel certification burdens for exporters maintaining separate domestic and international product variants.
Installed base concentrates in Photoelectric; expansion runs fastest through Combination.
End User:
Contract structure and liability allocation determine whether buyers prefer capital purchase or outcome-based service agreements.
- Residential:Single-family and multi-family dwellings generate highest unit shipments. US state fire marshals mandate interconnected alarms in apartment construction, accelerating wireless mesh specification.
- Commercial:Office towers, retail centers, and hospitality properties yield elevated per-node revenue through integrated systems. Facility managers increasingly procure per-square-foot fire safety coverage rather than equipment ownership.
- Industrial:Manufacturing facilities and warehousing operations demand ruggedized housings with extended temperature tolerances. Dust and vapor environments require specialized sensor shielding.
- Government:Municipal buildings, military installations, and transportation infrastructure prioritize centralized monitoring integration. Mumbai and Delhi fire departments pilot city-wide mesh networks for incident response coordination.
Unit volume flows to Residential; value capture concentrates in Commercial.
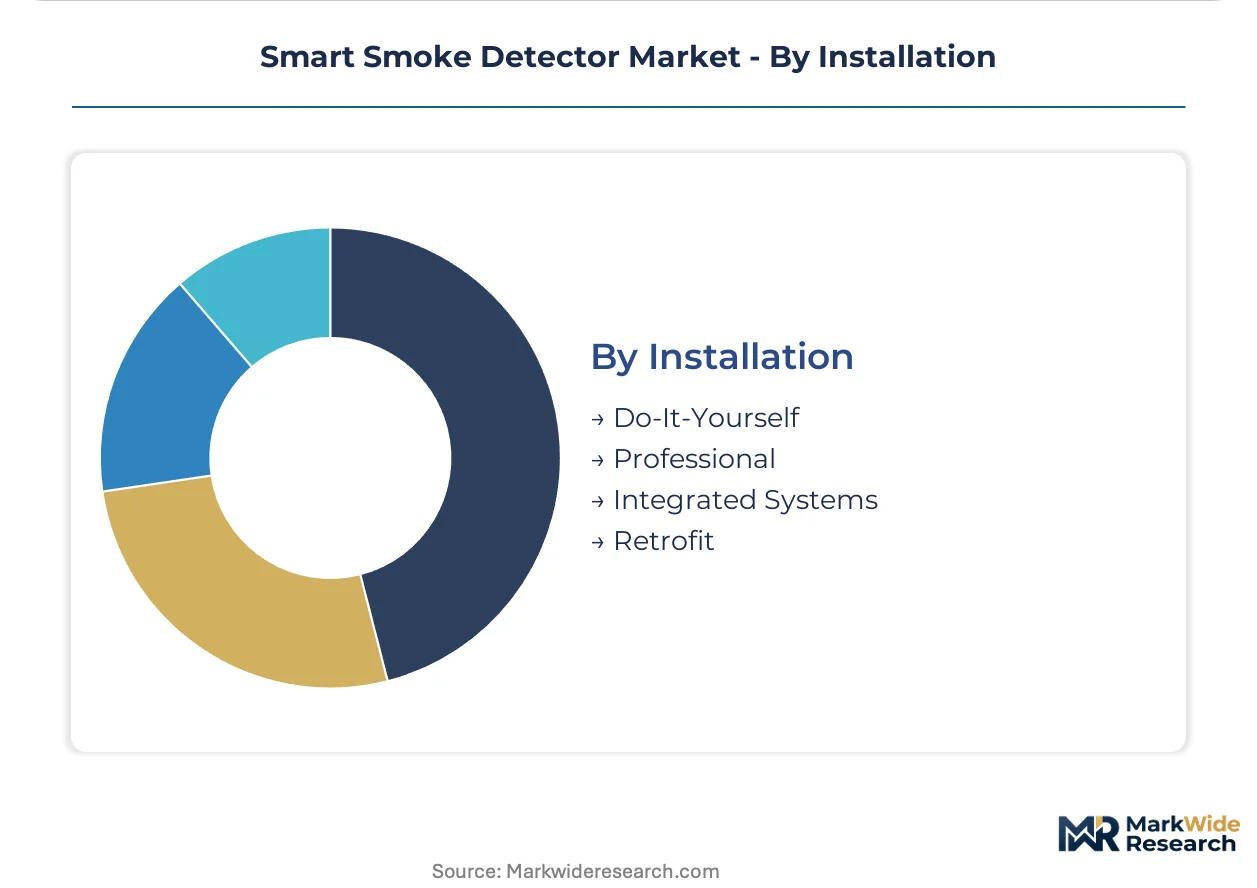
Installation:
Skill requirements and system complexity segment buyers between self-service and contracted deployment models.
- Do-It-Yourself:Consumer-facing packaging with mobile app provisioning targets replacement of standalone legacy units. Compatibility with existing alarm panels differentiates retail-positioned brands.
- Professional:Certified technician deployment ensures code compliance and monitoring center registration. Johnson Controls and Honeywell anchor market position through installation channel control in commercial real estate.
- Integrated Systems:Pre-engineered detection-HVAC-access control bundles ship from factory with unified configuration. Building automation integrators capture margin through single-source accountability.
- Retrofit:Wireless mesh protocols eliminate hardwiring infrastructure in renovation projects. EU Green Deal building renovation targets across Germany, France, and Netherlands mandate networked detection in public buildings.
Transaction volume clusters in Do-It-Yourself; margin expansion favors Integrated Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free economic zones in Shenzhen and Dongguan concentrate wireless transceiver module manufacturing, drawing component suppliers into clustered supply networks that reduce logistics costs for smart smoke detector assembly.
United States
Multi-family dwelling construction in Texas and Florida drives specification of interconnected wireless mesh systems. State fire marshals enforce alarm interconnection codes in apartment buildings above four stories. Chicago's Class A office towers favor professional installation channels for integrated fire safety coverage.
Germany
Municipal housing authorities in Berlin and Hamburg mandate networked detection in public building renovations ahead of EU Green Deal deadlines. ECHA REACH restrictions accelerate replacement of ionization-based units with photoelectric alternatives. Industrial safety distributors in the Ruhr region report elevated stocking of combination sensor arrays.
China
Shenzhen's electronics manufacturing clusters supply embedded wireless modules to domestic and export markets. SAMR enforces GB cybersecurity standards that force parallel certification tracks for IoT safety devices. Delhi and Mumbai fire departments pilot city-wide mesh networks using Chinese-manufactured gateway hardware.
India
Smart city infrastructure investments in Maharashtra and Karnataka create demand for centralized monitoring platforms. The Bureau of Indian Standards mandates fire safety compliance in high-rise residential towers above 15 stories. Bengaluru's technology parks specify integrated detection-HVAC systems for LEED certification.
United Kingdom
London's commercial real estate retrofit market shifts toward outcome-based service contracts. Building Regulations Approved Document B requires interconnected alarms in new residential construction above three stories. Manchester's municipal housing stock upgrades specify battery-powered wireless units for rapid deployment.
Smart Smoke Detector Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Building automation integrators capture recurring revenue through bundled service contracts, while consumer-facing brands compete on DIY installation simplicity. Three archetypes dominate: full-stack platform providers, component specialists, and channel-anchored installation partners. Consolidation pressure favors M&A activity among mid-tier wireless module suppliers, while technology licensing agreements proliferate around mesh networking protocols.
Among diversified industrial conglomerates, Honeywell International Inc. and Johnson Controls International Plc exemplify platform-centric positioning through building automation ecosystem integration. Resideo Technologies occupies a distinct tier focused on legacy panel compatibility for residential retrofit channels. These three anchors represent divergent strategic bets on professional installation control versus consumer self-service adoption.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Johnson Controls International Plc |
| Robert Bosch GmbH |
| Siemens AG |
| Google Nest |
| Resideo Technologies |
| Schneider Electric SE |
| Kidde |
| First Alert |
| Others |
Value Chain & Pricing Dynamics
Captive vertical integration into photoelectric sensor manufacturing anchors both supply security and margin control for tier-one platform providers, while outsourced wireless module assembly exposes mid-tier competitors to Taiwan foundry pricing volatility and certification timeline compression.
Pricing Analysis
Premium pricing for UL 217 Edition 8-certified units with sub-6-month lead times contrasts with spot-market discounts on legacy ionization inventory facing REACH compliance deadlines. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and bundled monitoring service depth. Pricing pressure stems from silicon chip supply concentration and parallel GB cybersecurity certification burdens for China-bound exports. Residential DIY buyers exhibit highest price sensitivity; commercial real estate operators prioritize outcome-based service contracts over unit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore orchestrate hub-and-spoke patterns for European and Asia-Pacific deployment. Manufacturing concentrates in China, Taiwan, and South Korea for wireless transceiver modules and photoelectric sensors. Raw material dependencies include lithium battery cells, americium-241 alternatives, and RoHS-compliant plastics. Single-source vulnerability around Taiwan-based foundry capacity creates lead time volatility. Distribution runs through building automation integrators for commercial segments and retail channels for residential retrofit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UL 217 Edition 8 certification timelines function as a cost-of-compliance moat, compressing margin recovery windows for non-compliant inventory and favoring manufacturers with pre-positioned testing resources.
For Market Incumbents: Hedge against Taiwan foundry concentration by qualifying secondary wireless module suppliers in South Korea and diversifying photoelectric sensor sourcing. Lock in professional installation channel control through exclusive HVAC integration partnerships before Resideo Technologies expands commercial retrofit compatibility. Prioritize sub-GHz RF engineering talent retention as embedded systems developers command premium compensation. For New Entrants and Emerging Players: The gap between premium Honeywell-Johnson Controls service contracts and economy battery-powered retail units creates white-space for mid-tier wireless mesh specialists. Target municipal housing authorities in Germany and the Netherlands facing EU Green Deal retrofit mandates with rapid-deployment battery-powered portfolios. Pursue white-label partnerships with industrial safety distributors in the Ruhr region lacking combination sensor array inventory. For Investors and Strategic Acquirers: Exit pathways concentrate in building automation conglomerates seeking wireless mesh protocol capabilities and professional installation channel density. Long-term viability hinges on platform-centric positioning where detection hardware serves as data nodes within integrated building systems. Monitor India's smart city infrastructure pilots in Mumbai and Delhi as inflection indicators for centralized monitoring platform adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Sub-GHz Protocol Certification | Premium positioning in high-rise concrete structures where 2.4 GHz experiences interference. |
| Professional Monitoring Channel Expansion | Recurring revenue capture through Johnson Controls-style per-square-foot service contracts. |
| Photoelectric Sensor Backward Integration | Margin defense against REACH-driven ionization chamber material cost volatility. |
| GB Cybersecurity Parallel Certification | Market access preservation under SAMR enforcement for China-bound IoT safety devices. |
| City-Wide Mesh Network Pilot Participation | First-mover positioning in India's smart city infrastructure investments across Maharashtra. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with building automation integrators, fire safety distributors, municipal housing authority procurement officers, and RF engineering specialists. UL certification databases, ECHA REACH substance restriction updates, SAMR GB standard disclosures, and EU Construction Products Regulation harmonization documents provided compliance tracking baselines. Bottom-up unit shipment estimates triangulated against top-down building construction permit data.
Data-stream reconciliation across product type, technology architecture, end-user segment, and installation mode dimensions shaped the analytical framework throughout the projection horizon. CAGRs derived from installed base turnover rates, regulatory mandate effective dates, and wireless protocol adoption curves. Industry-specific inputs included multi-family dwelling code enforcement timelines, EU Green Deal renovation target phasing, and sub-GHz frequency allocation harmonization progress.
Inputs from fire safety trade associations and municipal procurement databases were available through the study window; gaps in real-time wireless module inventory positioning introduce uncertainty bands around near-term shipment estimates. Forecasts reflect documented assumptions regarding certification timeline adherence and foundry capacity normalization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Smoke Detector Market
Fire Safety & Protection
Portable Fire Extinguisher Market
Fire Safety & Protection
Smoke Pressure System Market
Fire Safety & Protection
Deflagration Flame Arresters Market
Fire Safety & Protection
Fire Rated Cables Market
Fire Safety & Protection
Fire Hose Market
Fire Safety & Protection
Powder Fire Suppression System Market
Fire Safety & Protection
United States Fire Sprinklers Market
Fire Safety & Protection
Fire Extinguisher Market
Fire Safety & Protection
UAE Firefighting Foam Market
Fire Safety & Protection
Fire Suppression Equipment Market
Fire Safety & Protection
Europe Passive Fire Protection Market
Fire Safety & Protection
Global Portable Foam Fire Extinguisher Market
Fire Safety & Protection
Fire Pump Market
Fire Safety & Protection
Fire Alarm Systems Market
Fire Safety & Protection
Global Fire Barrier Sealant Market