
 Global Fire Suppression System Market | 2026-2036
Global Fire Suppression System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fire Suppression System Market Analysis
Project finance for large infrastructure portfolios is rewriting competitive access in fire suppression, allowing systems integrators to bid on multi-year facility contracts without full capital deployment. Johnson Controls leverages its building automation footprint to bundle suppression with HVAC and security. Siemens AG anchors its position through digital twin integration that ties fire detection to predictive maintenance. Honeywell International competes on sensor density, extending its addressable market into legacy building retrofits.
Fire suppression systems encompass engineered assemblies of detection, control, and extinguishing technologies designed to identify combustion events and discharge water, foam, powder, or inert gas agents within ten to sixty seconds of activation. Water-based systems dominate installed base volume across commercial and residential buildings due to lower agent cost and simpler recharge protocols. Gas systems command premium positioning in data centers and healthcare settings where water damage to electronics or sterile environments is unacceptable. Fixed installations generate recurring inspection and component replacement revenue through sprinklers, valves, and control panels.
NFPA standards in the United States, the EU F-Gas Regulation, and China's GB standards collectively determine agent chemistry legality, system testing intervals, and cross-border equipment certification. The EU F-Gas Regulation is accelerating fluorinated gas phase-outs, forcing reformulation investments across European suppliers while creating compliance gaps for imported systems. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and recertification costs.
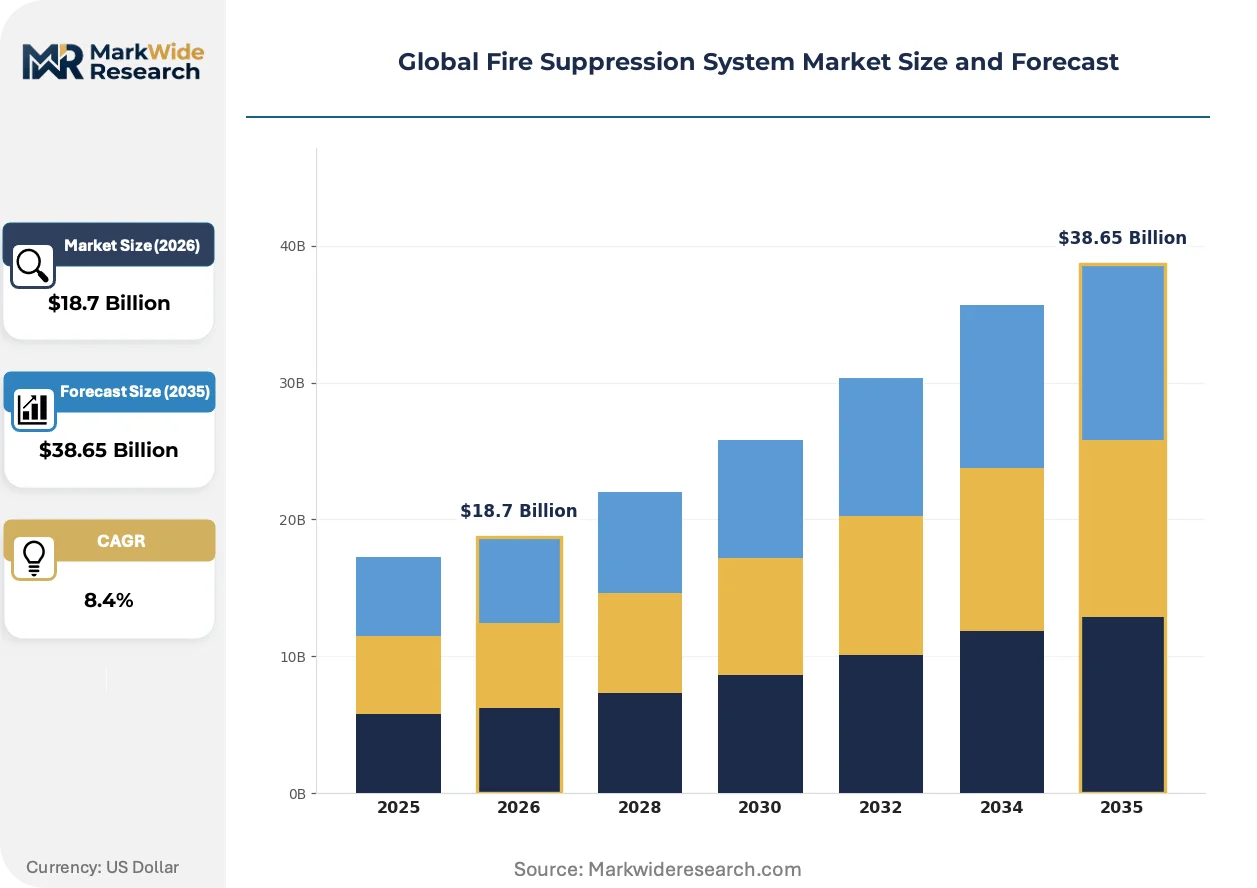
Market Dynamics
The EU F-Gas Regulation is forcing rapid agent chemistry reformulation across European supply chains while data center asset density creates parallel demand for water-free suppression technologies. This dual pressure is compressing product development cycles and redrawing competitive boundaries between gas-based and water-based system architectures.
Growth Catalysts
- Data Center Expansion:Hyperscale facilities in the United States, Germany, and India are mandating clean agent systems to protect server racks from water damage. This specification pull is accelerating premium system deployment.
- EU Green Deal:The F-Gas Regulation phase-out timeline is compelling infrastructure owners to replace hydrofluorocarbon-based suppression with fluorinated ketone or inert gas alternatives before mandated deadlines.
- NFPA 13D Adoption:Residential sprinkler mandates in California, Florida, and Pennsylvania are expanding addressable volume for residential system integrators.
Market Restraints
- Agent Cost Volatility:Inert gas cylinder prices fluctuate with specialty steel and helium supply constraints, compressing margins for fixed-installation contractors.
- Supply Concentration:European fluorinated ketone production concentrates among three chemical conglomerates, creating bottlenecks for system OEMs seeking F-Gas-compliant alternatives.
- Technical Limitation:Water mist systems face ceiling height constraints in atrium spaces, restricting their deployability in modern commercial architecture.
Strategic Opportunities
- India Infrastructure Buildout:Smart Cities Mission investments in Mumbai, Delhi, and Bangalore are specifying addressable fire suppression for metro stations and commercial complexes.
- Digital Twin Convergence:Integration of IoT sensors with building management platforms enables predictive maintenance contracts that extend customer lifetime value.
- Healthcare Retrofit Wave:China's GB 50016 standard updates are forcing hospital upgrades in Shanghai and Guangzhou, opening replacement demand for gas-based systems.
Industry Challenges
- Certification Timeline Compression:UL and FM Global testing queues for new fluorinated ketone blends extend lead times, delaying project revenue recognition.
- Legacy System Interoperability:Integration of addressable detection panels with 1980s-era valve assemblies requires custom engineering, inflating commissioning costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fire Suppression System Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based Systems, Foam Systems, Powder Systems, Gas Systems End User: Manufacturing, Automotive, Healthcare, Data Centers Installation Type: Fixed Systems, Portable Systems, Semi-Fixed Systems, Hybrid Systems Component: Sprinklers, Valves, Nozzles, Control Panels |
| Companies Covered | Robert Bosch GmbH, Carrier Global Corporation, Johnson Controls, Minimax Viking Group, Hochiki Corporation, Honeywell International, Halma plc, Viking Group, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fire Suppression System Market Emerging Trajectories
Agent chemistry innovation, detection sensor density, and procurement model transformation are converging to redefine how suppression systems are specified, installed, and maintained across commercial and industrial infrastructure.
Addressable photoelectric detection arrays are digitizing how facilities monitor combustion precursors. Data center operators in Northern Virginia and Frankfurt are deploying sensor networks with sub-zone granularity to enable targeted agent discharge. This granularity is digitizing maintenance workflows by pinpointing contamination sources before system-wide calibration becomes necessary.
The EU F-Gas Regulation is accelerating fluorinated gas phase-outs with mandatory quota reductions through 2030. Chemical suppliers are reformulating with Novec 1230 and inert blends to retain market access. German and French system integrators are responding by stockpiling transitional agents while qualifying alternative chemistries for CE marking.
Performance-based maintenance contracts are displacing scheduled inspection models in commercial real estate portfolios. Blackstone and Brookfield asset managers in Manhattan and London are unbundling suppression upkeep from bundled facility management. This unbundling is most visible in Class A office towers where sensor data enables condition-based service triggers rather than calendar-driven technician visits.
Global Fire Suppression System Market Segmentation
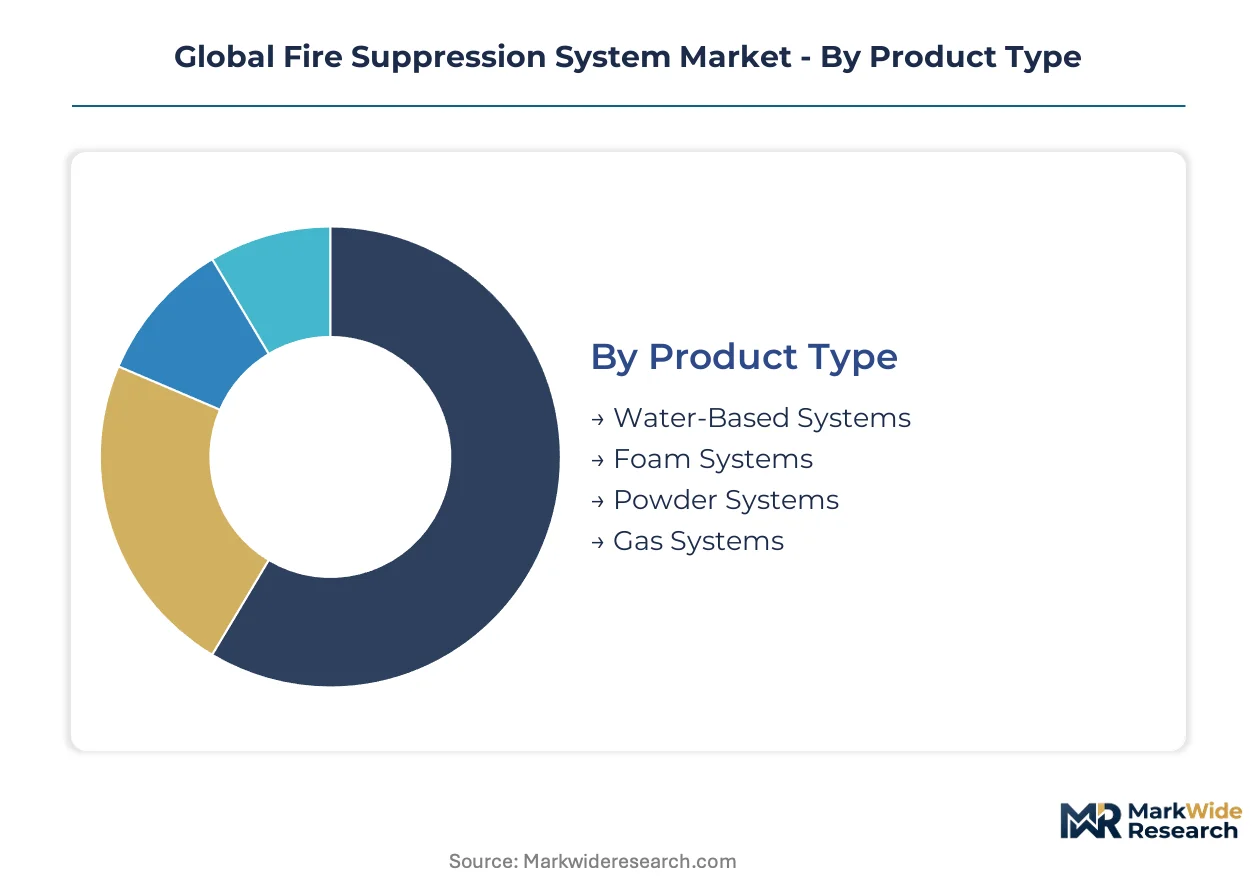
Fire suppression system segmentation reveals distinct replacement cycles and margin profiles across product architectures. Understanding these structural differences enables targeted resource allocation across installation types and component categories.
Product Type:
Water-based systems turn over fastest due to corrosion wear and mandatory inspection intervals, while gas systems operate on decade-long replacement cycles tied to agent shelf life and cylinder recertification.
- Water-Based Systems:Sprinkler networks using wet, dry, or pre-action pipe configurations dominate commercial building infrastructure. Demand concentrates in California, Florida, and Pennsylvania where NFPA 13D residential mandates expand addressable volume for contractors.
- Gas Systems:Clean agent and inert gas assemblies discharge non-conductive suppressants for electronics protection. Northern Virginia and Frankfurt data center clusters specify these systems to eliminate water damage risk to server infrastructure.
- Foam Systems:Aqueous film-forming foam (AFFF) and fluorine-free alternatives protect fuel storage and aircraft hangars. European ports and Gulf Coast petrochemical facilities drive specification.
- Powder Systems:Dry chemical suppressants using ABC or BC formulations serve mobile and industrial applications. Mining operations in Western Australia and Chilean copper belts sustain demand.
Water-based systems dominate installed base. Gas systems are where expansion concentrates.
End User:
Cost tier stratification separates mission-critical facilities willing to pay premium pricing from commodity-driven verticals where suppression competes with other capital priorities.
- Data Centers:Hyperscale operators in the United States, Germany, and India mandate addressable clean agent systems with sub-zone discharge granularity. Frankfurt and Northern Virginia clusters drive specification for fluorinated ketone alternatives.
- Healthcare:Hospitals and pharmaceutical manufacturing require sterile environment protection with zero residue discharge. Shanghai and Guangzhou facilities face GB 50016 upgrade deadlines.
- Manufacturing:Automotive, electronics, and heavy industry plants deploy mixed suppression architectures. German automotive OEMs integrate digital twin monitoring into production line protection.
- Automotive:Electric vehicle battery assembly and charging infrastructure create new hazard categories. Michigan and Bavaria production lines specify specialized water mist for lithium-ion thermal events.
Manufacturing commands the largest addressable spend. Data centers are climbing the fastest.
Installation Type:
Volume concentration favors permanent infrastructure, though mobility requirements in remote extraction and temporary construction sustain portable and hybrid categories.
- Fixed Systems:Permanent pipe networks with integrated detection and control panels constitute the revenue core. Mumbai metro stations and Bangalore commercial towers under India's Smart Cities Mission specify addressable fixed installations.
- Portable Systems:Wheeled and handheld extinguishers serve construction sites, marine vessels, and mobile equipment. Offshore platforms in the North Sea and Gulf of Mexico maintain extensive portable inventories.
- Semi-Fixed Systems:Hose reel and monitor configurations combine fixed supply with manual deployment. Airport terminals in Dubai and Singapore deploy these for apron protection.
- Hybrid Systems:Modular assemblies bridge permanent and temporary requirements. Film production stages in Los Angeles and London use hybrid configurations for location shooting.
Fixed systems anchor manufacturer revenue. Portable systems are where replacement frequency concentrates.
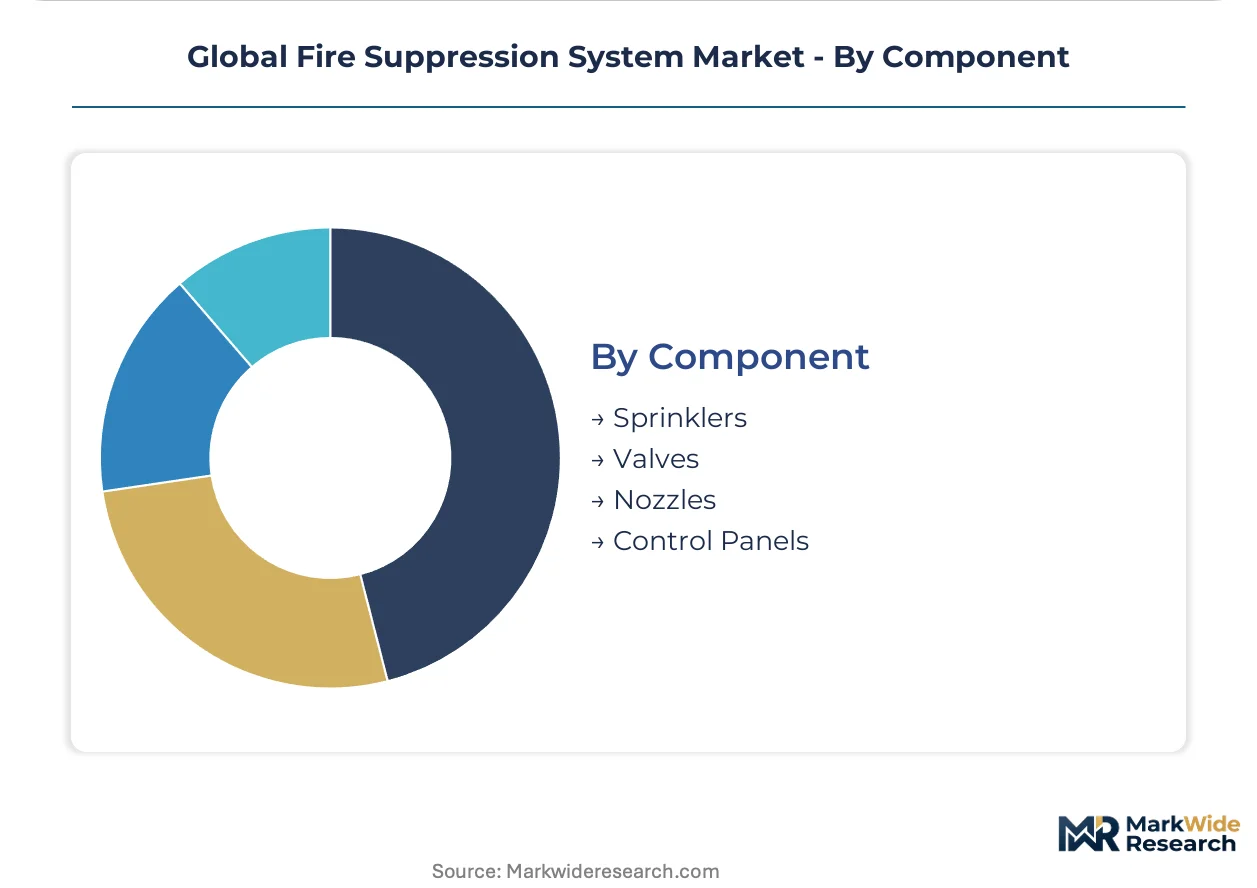
Component:
Supply concentration varies dramatically across component categories, with control panel electronics consolidating faster than mechanical sprinklers and valves.
- Control Panels:Addressable detection processors with IoT connectivity enable predictive maintenance contracts. Siemens and Johnson Controls compete on digital twin integration.
- Sprinklers:Fusible link and glass bulb discharge heads generate recurring replacement demand. Residential mandates in California and Florida expand volume for standard and quick-response variants.
- Valves:Alarm check, deluge, and pre-action valve assemblies require periodic replacement. Corrosion-prone coastal installations in Florida and Louisiana drive above-average turnover.
- Nozzles:Water mist and gas discharge orifices determine suppression effectiveness. Data center specifications in Frankfurt and Northern Virginia demand precision-engineered nozzles for agent distribution.
Sprinklers generate the highest unit volume. Control panels are where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation is compressing product development cycles across European supply chains while data center expansion in the United States and India pulls investment toward clean agent alternatives. Infrastructure owners in Germany and China face parallel compliance deadlines that are redrawing procurement priorities.
United States
Hyperscale data center clusters in Northern Virginia and Dallas-Fort Worth are mandating addressable clean agent systems with sub-zone discharge granularity. NFPA 13D residential sprinkler mandates in California, Florida, and Pennsylvania are expanding contractor addressable volume. Michigan electric vehicle battery assembly lines specify specialized water mist systems for lithium-ion thermal event protection.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are integrating digital twin monitoring into production line fire protection systems. The EU F-Gas Regulation quota reductions through 2030 are forcing rapid reformulation of hydrofluorocarbon-based suppression agents. Frankfurt data center operators are stockpiling transitional fluorinated ketone agents while qualifying inert gas alternatives for CE marking.
China
GB 50016 standard updates are compelling hospital fire suppression upgrades in Shanghai and Guangzhou. The country's national building safety regulator is tightening inspection intervals for high-rise commercial towers. Yangtze River Delta manufacturing hubs are deploying mixed suppression architectures across electronics and pharmaceutical production facilities.
India
Smart Cities Mission investments in Mumbai, Delhi, and Bangalore are specifying addressable fixed installations for metro stations and commercial complexes. The Central Electricity Authority is mandating enhanced fire protection for grid-scale battery storage installations. Gujarat and Maharashtra industrial corridors are driving demand for foam systems at petrochemical and fuel storage facilities.
United Arab Emirates
Dubai International Airport and Abu Dhabi commercial tower developments are specifying semi-fixed hose reel configurations for apron and atrium protection. The country's civil defense authority is enforcing stricter certification requirements for imported suppression components. Port facilities in Jebel Ali are transitioning from AFFF to fluorine-free foam alternatives under environmental compliance timelines.
Global Fire Suppression System Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Building automation conglomerates leverage integrated HVAC-security-suppression bundles to capture multi-year facility contracts. Independent system integrators defend position through project finance flexibility and regional certification expertise. Dominant competitive moves include M&A activity targeting digital twin capabilities and strategic partnerships with chemical suppliers for F-Gas-compliant agent formulations.
Within the building automation tier, Johnson Controls and Siemens AG exemplify channel-controlling archetypes that bundle suppression with broader facility infrastructure. Honeywell International occupies a position among sensor-dense detection specialists extending into legacy retrofit markets. Robert Bosch GmbH and Carrier Global Corporation represent diversified industrial conglomerates with cross-border certification capabilities. Minimax Viking Group and Halma plc exemplify European specialists with concentrated expertise in gas-based suppression architectures.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Carrier Global Corporation |
| Johnson Controls |
| Minimax Viking Group |
| Hochiki Corporation |
| Honeywell International |
| Halma plc |
| Viking Group |
| Siemens AG |
| Others |
Supply Flow & Price Mechanics
Shanghai-to-Rotterdam container freight corridors transmit cost volatility from specialty steel and helium markets directly into inert gas cylinder pricing, amplifying margin compression for European system integrators while enabling premium capture by fluorinated ketone suppliers with F-Gas-compliant formulations.
Pricing Analysis
Certification level creates the primary spread across system tiers, with UL/FM Global-rated clean agent installations commanding substantial premiums over standard commercial sprinkler networks. Three-tier pricing structure separates mission-critical data center specifications from mid-market commercial retrofits and commodity residential mandates. Cost compression in inert gas systems is intensifying because specialty steel supply constraints and helium allocation bottlenecks squeeze cylinder margins. Data center operators exhibit the least price sensitivity due to asset density imperatives, while residential contractors in mandated states face acute pressure from volume-driven competition.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from German chemical conglomerates are stabilizing agent procurement for system OEMs navigating F-Gas transition timelines. Manufacturing concentrates in Germany, China, and the United States for control panels and detection electronics, with valve and sprinkler fabrication anchored in India and Mexico. Raw material dependencies center on specialty steel for cylinders, fluorinated ketone feedstocks, and precision-machined brass components. Single-source vulnerability in European fluorinated ketone production creates systemic risk for CE-marking compliance. Distribution runs through certified system integrators with regional installation licenses, bypassing direct OEM-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation's accelerated phase-out timeline constitutes a technological-regulatory inflection that compresses product development cycles and redraws competitive boundaries between gas-based and water-based architectures.
For Market Incumbents: Build switching-cost moats through digital twin integration that ties fire detection to predictive maintenance contracts, locking in multi-year facility relationships. Deepen backward integration into fluorinated ketone agent formulation to secure F-Gas-compliant supply against chemical supplier bottlenecks. Channel control through building automation bundling with HVAC and security systems defends against independent integrators with project finance flexibility. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, as regulatory enforcement lags create specification windows for cost-competitive water mist alternatives. India's Smart Cities Mission metro station deployments offer white-space access through addressable fixed installation tenders with localized certification requirements. Go-to-market execution should prioritize partnerships with regional system integrators possessing civil defense authority relationships over direct OEM competition. For Investors and Strategic Acquirers: Specialist gas-based suppression firms with concentrated CE-marking expertise and established chemical supplier partnerships represent the highest-probability acquisition targets for platform consolidation. Long-term viability hinges on positioning for fluorinated gas phase-out completion and inert gas scale-up across the projection horizon. Signal to monitor: UL and FM Global testing queue compression for new agent blends, which indicates certification velocity and near-term revenue recognition capacity for qualified formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Agent Chemistry Reformulation | F-Gas-compliant fluorinated ketone blends retain European market access against quota reductions. |
| Digital Twin Integration | Siemens and Johnson Controls leverage predictive maintenance contracts to extend customer lifetime value. |
| Project Finance Structuring | Systems integrators bid multi-year facility contracts without full capital deployment, rewriting competitive access. |
| Regional Certification Investment | CE marking and GB standard compliance enable penetration of Frankfurt and Shanghai data center clusters. |
| Sensor Density Expansion | Honeywell extends addressable market into legacy building retrofits through sub-zone detection granularity. |
Methodological Framework
A spread of perspectives from fire suppression system integrators, facility managers at hyperscale data centers, chemical procurement leads at agent suppliers, and civil defense certification officers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against NFPA technical standards documentation, EU F-Gas Regulation filings, SEC 10-K disclosures from building automation conglomerates, and customs trade data for specialty steel and fluorinated chemical flows. Bottom-up installation volume estimates triangulated against top-down infrastructure capex projections across the analysis window.
Demand-supply balance framing anchored the forecast framework, with segmentation modeled across product architecture, end-use vertical, installation type, and component category throughout the projection horizon. CAGRs derived from installation base turnover rates, replacement cycle analysis, and regulatory compliance deadline clustering. Industry-specific inputs included data center power density trends, electric vehicle battery assembly line specifications, and residential sprinkler mandate adoption curves by state jurisdiction.
Practitioners should monitor agent chemistry certification queues, specialty steel price indices, and civil defense authority enforcement intensity for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Powder Fire Suppression System Market
Fire Safety & Protection
Fire Safety Systems Market
Fire Safety & Protection
Laser Smoke Detector Market
Fire Safety & Protection
Fire Suppression Market
Fire Safety & Protection
Global Flame Arrestors Market
Fire Safety & Protection
Africa Fire Suppression Market
Fire Safety & Protection
Fire Protection Valves and Fittings Market
Fire Safety & Protection
Global Flame Detector Market
Fire Safety & Protection
Passive Fire Proofing System Market
Fire Safety & Protection
GCC Firefighting Foam Market
Fire Safety & Protection
Fire and Explosion Proof Lights Market
Fire Safety & Protection
UAE Firefighting Foam Market
Fire Safety & Protection
Smart Smoke Detector Market
Fire Safety & Protection
North America Fire Protection Water Storage Tanks Market
Fire Safety & Protection
US Fire Alarm and Detection Market
Fire Safety & Protection
Fire Protection Systems for Industrial Cooking Market