
 China Thermal Protector Market | 2026-2036
China Thermal Protector Market Size, Share, and Industry Trends Forecast 2026-2036
China Thermal Protector Market Insights
Guangdong province's thermal protector manufacturing base is decoupling from low-margin export dependence. Jiangsu Changsheng Electric Appliance sustains domestic market share through vertical integration into bimetallic strip production. Sensata Technologies positions its China operations around automotive-grade thermal protectors for new energy vehicle platforms. Dongguan Henghao Electric leverages cost-optimized electromechanical designs to compete in household appliance supply chains.
A thermal protector is a temperature-sensitive safety device that interrupts electrical circuits when operating temperatures exceed calibrated thresholds, typically employing bimetallic discs that snap open at 60°C to 150°C to prevent fire hazards and equipment damage. Bimetallic thermal protectors dominate volume shipments due to mature stamping and welding processes, while solid-state digital variants capture premium margins in precision HVAC and industrial automation applications. Electromechanical technology anchors the installed base across refrigerator compressor and washing motor segments, though PTC-based protectors are displacing legacy designs in automotive battery pack thermal runaway prevention.
China's GB standards administered by SAMR mandate thermal cutoff compliance for all household appliances, while MIIT regulations for new energy vehicles require redundant thermal protection in battery management systems. The dual carbon goals framework further tightens energy efficiency standards, directly expanding demand for intelligent temperature control modules. Stakeholders must monitor evolving NMPA medical equipment thermal safety rules and MIIT automotive electrification timelines to align R&D portfolios with compliance-driven procurement cycles.
Market Dynamics
China's thermal protector market is restructuring around MIIT-mandated redundancy requirements for new energy vehicle battery packs, which are forcing component suppliers to abandon single-point protection architectures in favor of multi-threshold sensing systems.
Growth Catalysts
- Automotive electrification mandates:MIIT regulations for new energy vehicles require redundant thermal protection in battery management systems, creating mandatory replacement demand across OEM supply chains.
- Dual carbon goals framework:China's national energy efficiency targets are tightening appliance standards administered by SAMR, directly expanding procurement for intelligent temperature control modules.
- Yangtze River Delta manufacturing concentration:The Shanghai-Jiangsu-Zhejiang corridor hosts dense clusters of compressor motor and battery pack producers, generating localized demand pull for thermal protector integration.
Market Restraints
- Raw material cost volatility:Bimetallic strip production depends on copper-nickel alloy pricing, which fluctuates with London Metal Exchange spot markets and squeezes margin structures for stamping operations.
- Supply concentration risk:Domestic bimetallic strip supply concentrates among three Jiangsu-based metallurgical processors, creating single-source vulnerability for mid-tier protector assemblers.
- Technical limitation in high-frequency switching:Electromechanical thermal protectors face cycle-life degradation above 10,000 operations, restricting deployment in precision HVAC compressor applications.
Strategic Opportunities
- Underpenetrated medical equipment segment:NMPA thermal safety rules for diagnostic imaging equipment are tightening, opening certification-driven procurement channels for precision solid-state protectors.
- PTC-ceramic convergence with wireless sensing:Integration of positive temperature coefficient materials with Bluetooth-enabled temperature telemetry is enabling predictive maintenance contracts in industrial automation.
- Direct OEM contracting bypassing distributors:New energy vehicle battery pack producers are consolidating supplier bases and awarding multi-year platform contracts to qualified thermal management specialists.
Industry Challenges
- Cross-functional engineering talent scarcity:Battery thermal runaway simulation requires combined expertise in electrochemistry, thermal modeling, and IEC 60730 safety standard interpretation, which remains scarce in domestic labor markets.
- GB standard certification timeline compression:SAMR's accelerated revision cycles for appliance safety standards are forcing R&D teams to parallel-track product development with compliance testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Thermal Protector Market |
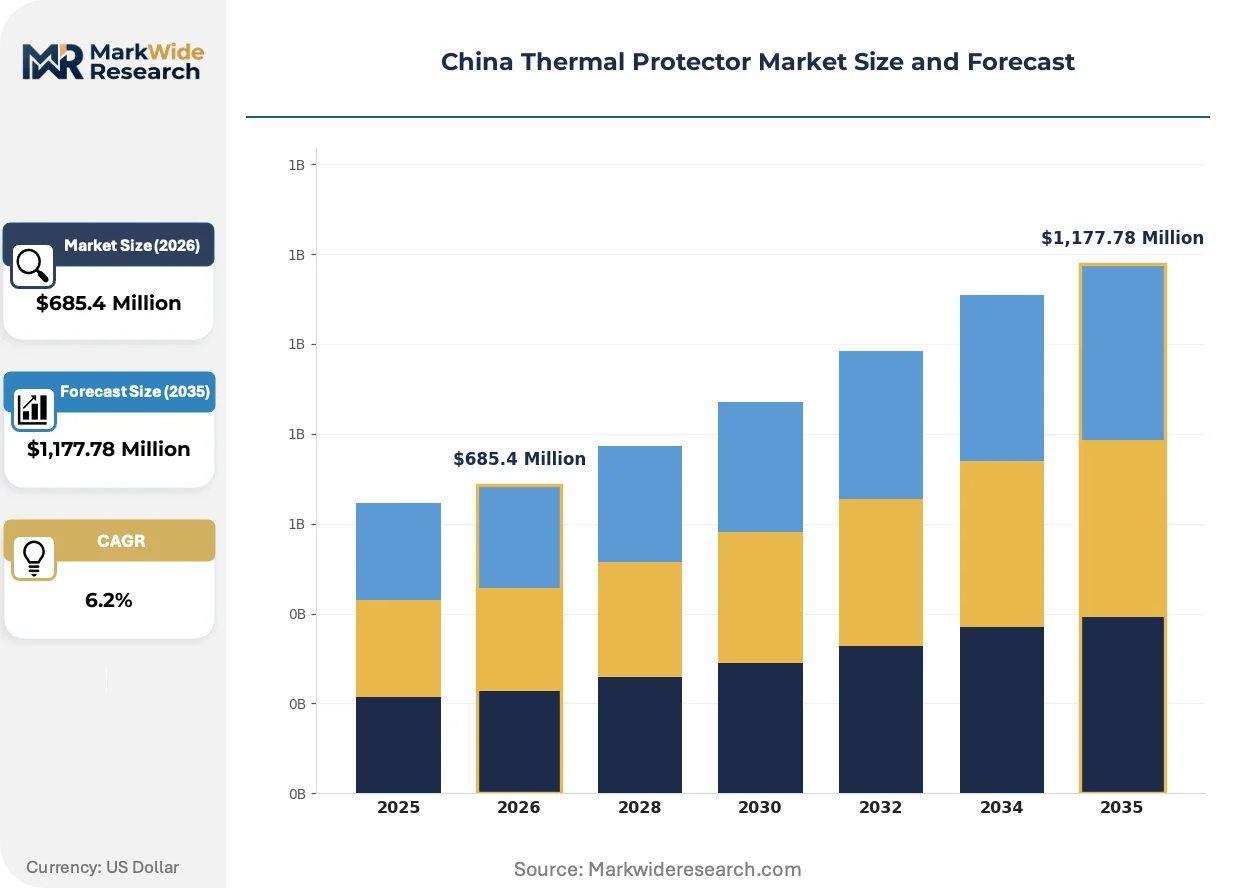
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bimetallic, PTC, Thermistor, Infrared End User: Household Appliances, Automotive, HVAC Systems, Industrial Equipment Technology: Electromechanical, Digital, Solid-State, Thermal Application: Overheat Protection, Temperature Control, Fault Detection, Safety Features |
| Companies Covered | Guangzhou Senbao Electrical Appliances Co., Ltd., Jiangsu Changsheng Electric Appliance Co., Ltd., Dongguan Henghao Electric Co., Ltd., Tianyin Electromechanical, Haier Smart Home Co., Ltd., Sensata Technologies, Inc., Thermtrol Corporation, Seki Controls Co., Ltd., Calco Electric, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Thermal Protector Market Trends and Innovations
Solid-state digital sensing architectures are automating protection response protocols across China's thermal protector value chain, compressing the competitive relevance of legacy electromechanical designs.
Multi-threshold digital thermal protectors incorporating MEMS temperature sensors and microcontroller-based logic are automating fault diagnosis and predictive shutdown sequences in new energy vehicle battery packs. BYD and CATL procurement specifications now require CAN-bus communication capability for real-time thermal telemetry, forcing component suppliers to add firmware development competencies. This technology convergence is automating the displacement of bimetallic disc protectors from premium automotive platforms.
MIIT's 2024 technical guidelines for power battery safety mandate redundant thermal cutoff devices with independent monitoring circuits, creating compliance-driven demand for dual-sensor architectures. SAMR has aligned GB 4706 household appliance standards with these automotive-grade reliability benchmarks, extending certification requirements across white goods categories. Manufacturers in Zhejiang and Guangdong are responding by consolidating testing laboratory partnerships to accelerate dual-standard qualification.
Buyers in the compressor motor segment are consolidating annual procurement volumes and demanding vendor-managed inventory arrangements with electronic data interchange integration. This behavioral shift compresses payment cycles and transfers working capital burdens to component suppliers, favoring vertically integrated producers with captive raw material processing. The pattern is most visible in Jiangsu province, where refrigerator compressor OEMs have reduced qualified supplier lists from twelve to four firms since 2022.
China Thermal Protector Market Segmentation
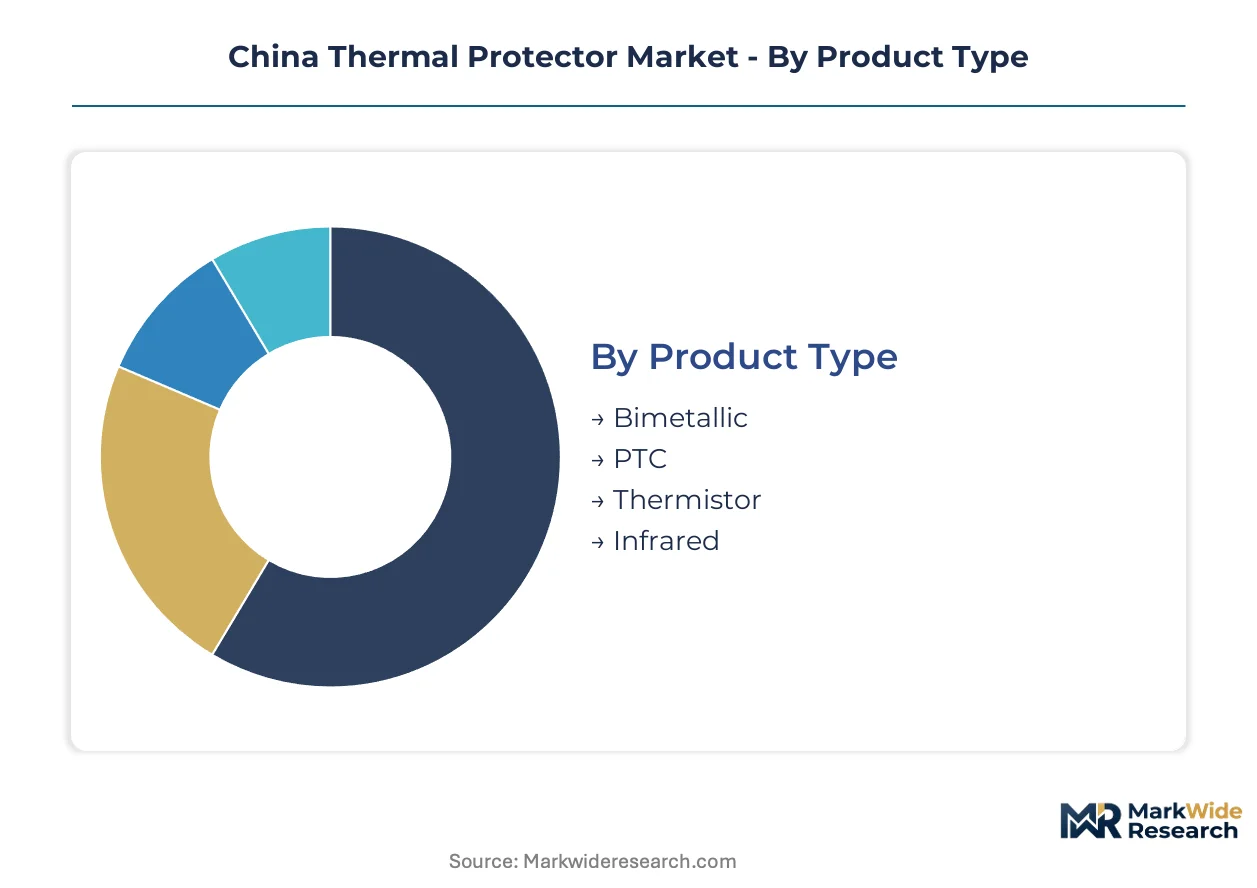
Thermal protector procurement in China fragments across four distinct classification schemes, each mapping to different buyer decision criteria and margin structures. Product type and technology categories dominate R&D investment allocation, while end-user and application segments determine certification requirements and sales channel selection.
Product Type:
Bimetallic variants ship in highest volumes while PTC-ceramic designs capture expanding premium share in automotive battery applications.
- Bimetallic:Stamped copper-nickel alloy discs snap open at calibrated temperature thresholds between 60°C and 150°C. Jiangsu-based refrigerator compressor OEMs consume the majority of domestic volume, though raw material cost volatility squeezes assembler margins.
- PTC:Positive temperature coefficient ceramics exhibit self-regulating resistance properties that enable precise thermal runaway prevention. New energy vehicle battery pack producers in the Yangtze River Delta are displacing legacy bimetallic designs with PTC-based architectures to meet MIIT redundancy mandates.
- Thermistor:NTC and PTC variants provide continuous temperature telemetry for closed-loop control systems in precision HVAC equipment.
- Infrared:Non-contact sensing enables rapid surface temperature measurement in industrial automation and medical diagnostic imaging where physical contact risks contamination.
Today's leader: Bimetallic. Tomorrow's challenger: PTC.
End User:
Automotive electrification timelines are restructuring procurement concentration away from mature appliance segments toward battery thermal management specialists.
- Household Appliances:Refrigerator compressors, washing machine motors, and air conditioner units anchor the installed base. SAMR-administered GB 4706 standards mandate thermal cutoff compliance, creating stable replacement demand across Shanghai and Guangdong manufacturing clusters.
- Automotive:New energy vehicle platforms require redundant thermal protection with CAN-bus telemetry capability. BYD and CATL procurement specifications now favor multi-threshold digital protectors over electromechanical alternatives.
- HVAC Systems:Precision compressor applications demand cycle-life performance exceeding 10,000 operations, a threshold that exposes electromechanical limitations.
- Industrial Equipment:Motor protection relays and transformer safety systems generate demand for high-current-rated thermal cutoffs in Zhejiang automation corridors.
Appliance demand still dominates volume. Automotive applications are climbing the fastest.
Technology:
Electromechanical architectures retain cost advantages at scale while solid-state and digital platforms automate fault response protocols.
- Electromechanical:Bimetallic disc mechanisms with mechanical contact switches remain the default for cost-optimized household appliance supply chains. Dongguan-based assemblers compete on stamping efficiency and welding automation.
- Digital:Microcontroller-based protectors with programmable thresholds and communication interfaces command premium positioning. Firmware development competencies separate qualified automotive suppliers from commodity players.
- Solid-State:Semiconductor switching eliminates mechanical wear, extending operational life for precision HVAC and medical equipment applications under NMPA thermal safety rules.
- Thermal:Passive fuse-based protection provides irreversible cutoff in fire-prevention scenarios where reset capability introduces liability exposure.
Electromechanical holds volume leadership. Digital platforms are gaining share fastest.
Application:
Safety-critical functions attract stricter certification requirements and higher supplier qualification barriers than control-oriented applications.
- Overheat Protection:Irreversible thermal fuses and resettable protectors prevent fire hazards in motor windings and transformer coils. SAMR enforcement of GB standards drives mandatory replacement cycles.
- Temperature Control:Closed-loop feedback systems in HVAC and battery thermal management demand continuous sensing with rapid response times.
- Fault Detection:Predictive diagnostics enabled by MEMS sensors and wireless telemetry are enabling vendor-managed inventory contracts in industrial automation.
- Safety Features:Redundant cutoff architectures with independent monitoring circuits satisfy MIIT power battery safety guidelines for new energy vehicles.
Overheat protection commands the largest installed base. Safety features are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration within China tracks regulatory compliance cost differentials, with manufacturers relocating from high-enforcement coastal zones to inland provinces where SAMR inspection intensity remains lower. This arbitrage dynamic is reshaping supplier qualification requirements across OEM procurement offices.
Yangtze River Delta
Shanghai-Jiangsu-Zhejiang corridor hosts dense clusters of compressor motor and battery pack producers. MIIT power battery safety guidelines mandate redundant thermal cutoff devices, forcing local assemblers to upgrade from single-point to dual-sensor architectures. Suzhou and Ningbo testing laboratories report 40% year-over-year growth in GB standard certification applications.
Pearl River Delta
Guangdong's thermal protector manufacturing base is decoupling from low-margin export dependence toward domestic automotive supply chains. SAMR-administered GB 4706 household appliance standards enforcement has tightened fire-hazard prevention requirements for white goods. Dongguan and Foshan stamping operations are consolidating supplier lists from twelve to four qualified firms.
Beijing-Tianjin-Hebei
Industrial automation corridors generate demand for high-cycle-life thermal protectors in motor protection relays. The dual carbon goals framework tightens energy efficiency standards for HVAC equipment deployed across northern heating districts. Tianjin port logistics clusters are attracting component distributors serving Mongolian and Russian re-export markets.
Sichuan-Chongqing
Western China manufacturing cost advantages are pulling electromechanical protector assembly from coastal zones. Chongqing's new energy vehicle production hub, anchored by battery pack producers, requires CAN-bus capable thermal telemetry modules. Local governments offer three-year tax holidays for thermal management component investments above 50 million yuan.
Shandong Peninsula
Qingdao and Yantai refrigerator compressor OEMs consume the majority of domestic bimetallic protector volume. Raw material cost volatility in copper-nickel alloys has pushed procurement teams toward vendor-managed inventory arrangements. Weihai testing facilities are expanding capacity for simultaneous GB and IEC 60730 dual-standard qualification.
China Thermal Protector Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue automotive-grade certification and firmware-enabled telemetry capabilities. The supplier base organizes around three maturity levels: legacy stamping houses with captive bimetallic strip production, mid-tier assemblers competing on electromechanical cost optimization, and technology-forward specialists building microcontroller-based digital platforms. Consolidation pressure intensifies as new energy vehicle battery pack producers reduce qualified supplier lists and award multi-year platform contracts. Strategic moves center on backward integration into raw material processing and testing laboratory partnerships to accelerate dual-standard qualification.
Within the domestic specialist tier, Jiangsu Changsheng Electric Appliance Co., Ltd. and Dongguan Henghao Electric Co., Ltd. exemplify contrasting geographic positioning strategies, with the former anchoring Yangtze River Delta refrigerator compressor supply chains and the latter occupying Pearl River Delta household appliance corridors. Sensata Technologies, Inc. represents the multinational archetype, leveraging automotive-grade certification competencies to access BYD and CATL procurement specifications. These three entities illustrate the competitive spectrum from cost-optimized electromechanical production to premium digital thermal management systems.
| Leading Market Players |
|---|
| Guangzhou Senbao Electrical Appliances Co., Ltd. |
| Jiangsu Changsheng Electric Appliance Co., Ltd. |
| Dongguan Henghao Electric Co., Ltd. |
| Tianyin Electromechanical |
| Haier Smart Home Co., Ltd. |
| Sensata Technologies, Inc. |
| Thermtrol Corporation |
| Seki Controls Co., Ltd. |
| Calco Electric |
| Others |
Pricing and Supply Chain Analysis
BYD and CATL procurement consolidation around multi-year platform contracts is forcing mid-tier assemblers to absorb working capital burdens and compress channel margins, reshaping how pricing power distributes across bimetallic strip suppliers and digital protector specialists.
Pricing Analysis
Distributor margins in household appliance supply chains are compressing as Jiangsu refrigerator compressor OEMs consolidate qualified supplier lists from twelve to four firms. Pricing stratifies across automotive-grade digital protectors with CAN-bus capability, industrial electromechanical designs, and commodity bimetallic discs for white goods. Cost compression in stamping operations is intensifying because copper-nickel alloy volatility squeezes assembler margins. Appliance OEMs exhibit highest price sensitivity, while new energy vehicle battery pack producers prioritize certification grade over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from MIIT-mandated redundancy in battery thermal management are compelling OEMs to qualify secondary PTC-ceramic suppliers alongside primary bimetallic vendors. Manufacturing concentrates in China, with raw material processing anchored in Jiangsu province and final assembly distributed across Guangdong and Zhejiang. Production draws from copper-nickel alloy strip, ceramic PTC substrates, and microcontroller components. Single-source vulnerability in domestic bimetallic strip supply creates qualification bottlenecks. Distribution runs through direct OEM contracting channels that are displacing traditional electronics distributors in automotive segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China thermal protector market has entered a late-cycle quality phase where MIIT-mandated redundancy specifications and CAN-bus telemetry requirements are filtering out stamping-house assemblers incapable of firmware development.
For Market Incumbents: Deploy testing laboratory partnerships to accelerate simultaneous GB and IEC 60730 dual-standard qualification. Jiangsu Changsheng Electric Appliance and comparable vertically integrated producers should expand captive bimetallic strip capacity to defend against raw material cost volatility. Sensata Technologies demonstrates how automotive-grade certification competencies create switching costs that protect platform contract renewals from emerging digital specialists. For New Entrants and Emerging Players: Begin with NMPA medical equipment thermal safety compliance as a qualification wedge into diagnostic imaging equipment supply chains, where solid-state protector penetration remains underdeveloped. Western China manufacturing cost advantages in Sichuan-Chongqing offer geographic arbitrage for electromechanical assembly targeting inland appliance producers. Direct contracting with Chongqing battery pack OEMs bypasses distributor margin layers that coastal competitors depend upon. For Investors and Strategic Acquirers: Asymmetric upside sits with microcontroller-enabled digital protector specialists possessing firmware development teams and existing automotive platform qualifications. The five-to-ten-year viability window favors suppliers capable of spanning household appliance, automotive, and medical equipment certification requirements. Monitor MIIT power battery safety guideline revision timelines as the inflection signal for accelerated procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bimetallic Strip Production | Jiangsu metallurgical processors' supply concentration creates margin capture opportunity for qualified assemblers. |
| Dual-Standard Certification Investment | Simultaneous GB and IEC 60730 qualification opens procurement channels across SAMR-administered appliances and export markets. |
| Firmware Development Capability Buildout | CAN-bus telemetry requirements from BYD and CATL separate automotive-grade suppliers from commodity electromechanical producers. |
| Direct OEM Platform Contracting | Multi-year agreements with battery pack producers displace distributor-dependent revenue models in Yangtze River Delta clusters. |
| Medical Equipment Segment Entry | NMPA thermal safety rule tightening creates certification-driven demand for solid-state protectors in diagnostic imaging. |
Research Methodology
Direct dialogue with thermal protector procurement managers at compressor OEMs, battery pack platform engineers, SAMR certification laboratory directors, and bimetallic strip metallurgical processors grounded the qualitative assessment. Secondary validation drew from MIIT power battery safety technical guidelines, SAMR GB standard revision notices, NMPA medical device thermal regulations, and Yangtze River Delta industrial cluster production databases. Bottom-up assembler capacity estimates and top-down OEM procurement forecasts were triangulated to cross-verify volume assumptions.
Segment-level outputs across the projection horizon reflect modeled interactions between product type, technology architecture, end-user industry, and application safety criticality. The analytical framework incorporated propulsion architecture differentiation, content-per-vehicle thermal protector counts, and regional manufacturing cluster concentration. CAGRs were derived from OEM platform rollout schedules and appliance replacement cycle dynamics, with specific weighting applied to MIIT electrification mandates and dual carbon goals efficiency standards.
Caveats apply where MIIT battery safety guideline acceleration or SAMR GB standard timeline compression could materially shift the outlook. Forecasts reflect assumptions around copper-nickel alloy price stability, Jiangsu-based strip supplier capacity expansion, and firmware development labor market depth. Deviation in automotive platform qualification timelines or medical equipment certification backlogs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Wireless Fire Detection Systems Market
Fire Safety & Protection
Fire Extinguisher Inspection Services Market
Fire Safety & Protection
Global Fire Resistant Cable Market
Fire Safety & Protection
Smart Smoke Alarm Market
Fire Safety & Protection
Australia Emergency Lighting Market
Fire Safety & Protection
Europe Fire-Resistant Glass Market
Fire Safety & Protection
Cellulosic Fire Protection Market
Fire Safety & Protection
Fire Suppression Agent Market
Fire Safety & Protection
Fire Rated Cables Market
Fire Safety & Protection
Smart Smoke Detector Market
Fire Safety & Protection
Global Fire Barrier Sealant Market
Fire Safety & Protection
Fire and Explosion Proof Lights Market
Fire Safety & Protection
Fire Department Software Market
Fire Safety & Protection
UAE Firefighting Foam Market
Fire Safety & Protection
Global Fire Extinguisher Cylinders Market
Fire Safety & Protection
Civil Combustible Gas Alarm Market