
 Automatic Fire Suppression System (AFSS) Market | 2026-2036
Automatic Fire Suppression System (AFSS) Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Fire Suppression System (AFSS) Market Outlook
Capital-intensity divergence between integrated manufacturers and component assemblers is rotating competitive advantage toward firms with in-house agent formulation and testing infrastructure. Johnson Controls leverages its captive supply of fluorinated clean agents to sustain margin pools in institutional contracts. Siemens AG anchors European market access through certified testing partnerships with Germany's KBA and TÜV entities. Minimax GmbH competes on specialized marine and offshore system integration where regulatory stringency blocks generic entrants.
An automatic fire suppression system constitutes an engineered assembly of detection sensors, control panels, extinguishing agent storage, and distribution nozzles designed to activate without human intervention when thermal, optical, or ionization thresholds register combustion signatures; systems typically operate within 10-30 seconds of detection to discharge water, foam, gas, or wet chemical agents based on protected-asset classification. Gas-based technology leads in data center and archival applications where water damage exceeds fire damage risk, while wet chemical systems dominate commercial kitchen installations governed by NFPA 17A and UL 300 test protocols. Water-based products occupy the largest installation volume through new construction pipelines, though clean-agent retrofits command premium pricing in heritage building upgrades where structural preservation mandates non-residue suppression.
The National Fire Protection Association shapes US product certification through NFPA 13, 17A, and 2001 standards that govern system design density and agent concentration thresholds, while the EU F-Gas Regulation and REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of legacy halocarbon clean agents toward fluoroketone and inert gas blends. China's GB standards and Japan's JIS certification requirements create parallel compliance tracks that fragment vendor qualification costs across Asia-Pacific supply chains. Stakeholders must monitor regulatory phase-out timelines for synthetic fluorinated gases to anticipate capital redeployment between agent chemistries and detection architectures.
Market Dynamics
Clean-agent chemistry transitions are forcing wholesale system redesigns as fluoroketone formulations replace legacy halocarbons, compressing margins for assemblers lacking captive formulation capabilities while rewarding integrated manufacturers with in-house testing infrastructure.
Growth Catalysts
- NFPA 2001 concentration mandates:US data center operators face mandatory system recertification, driving retrofit demand for fluoroketone-based clean-agent architectures that protect server infrastructure without water damage risk.
- Commercial kitchen expansion:Wet chemical systems certified to UL 300 protocols capture installation volume as quick-service restaurant chains standardize automated suppression across franchise networks.
- Marine regulatory stringency:Specialized offshore platform certifications from Germany's KBA and TÜV entities block generic competitors, concentrating premium contracts with system integrators possessing type-approval documentation.
Market Restraints
- Raw material concentration:Fluorinated agent precursors concentrate among Chinese chemical manufacturers, exposing European and North American system builders to supply disruption and input cost volatility.
- REACH substance restrictions:The EU F-Gas Regulation and per- and polyfluoroalkyl substance phase-outs force premature obsolescence of installed halocarbon systems before depreciation cycles complete.
- Water-based substitution ceiling:Heritage building preservation mandates and electronics-dense environments structurally limit water mist penetration in premium retrofit segments.
Strategic Opportunities
- India infrastructure buildout:Metro rail systems and commercial high-rise construction in Mumbai and Delhi create first-mover advantage for vendors establishing GB-standard certification partnerships.
- AI-driven detection convergence:Machine-vision smoke recognition fused with thermal sensor arrays enables predictive activation, reducing false discharge incidents in archival and museum applications.
- Japan hydrogen economy:METI safety protocols for hydrogen fueling stations mandate specialized high-pressure gas suppression, opening niche demand for inert gas system specialists.
Industry Challenges
- Agent formulation expertise scarcity:Fluoroketone blending and stability testing require chemists with halocarbon substitution experience, constraining R&D throughput for mid-tier assemblers.
- Multi-jurisdiction certification lag:Parallel GB, JIS, and NFPA approval tracks extend product launch timelines by 18-24 months for vendors without established testing partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Fire Suppression System (AFSS) Market |
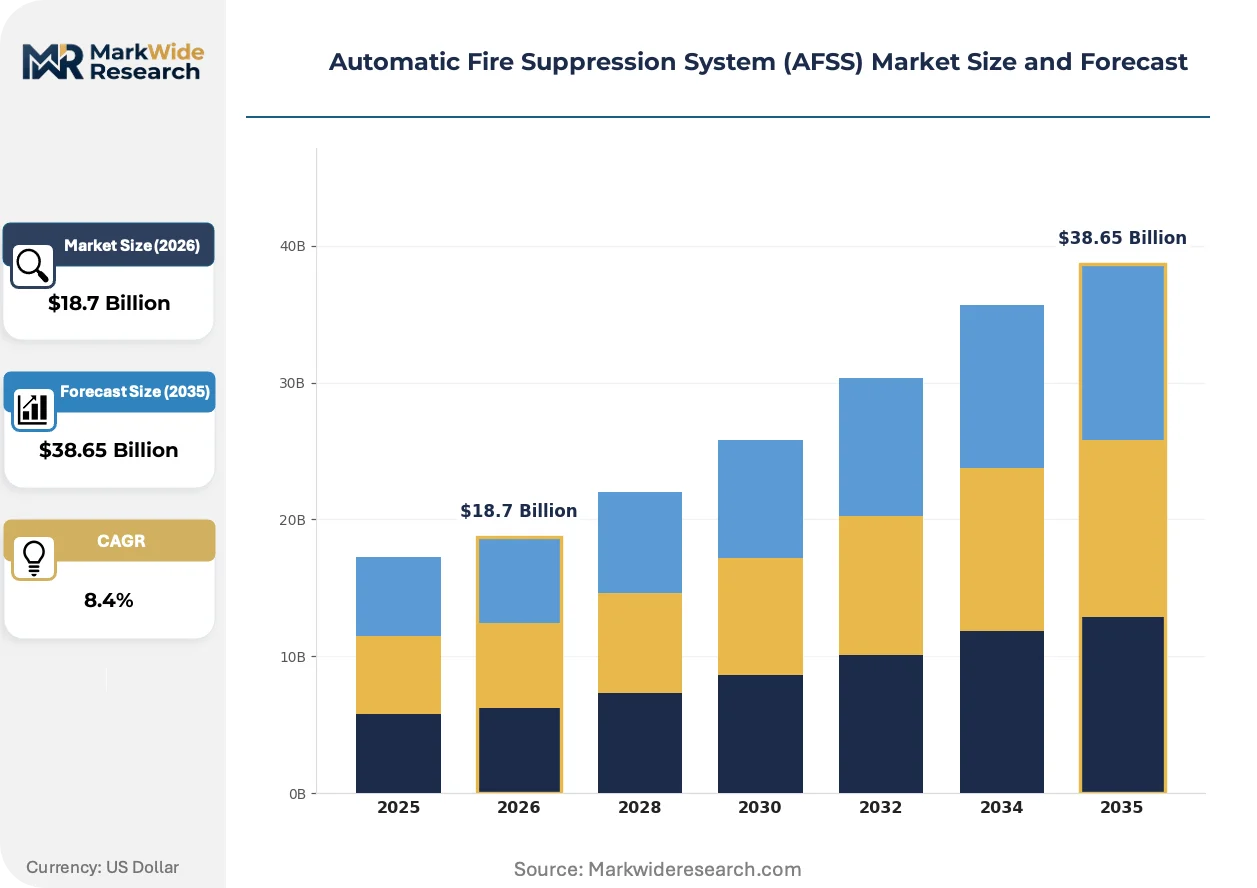
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Chemical, Foam, Gas, Water-based Technology: Spray Nozzle, Deluge, Pre-action, Clean Agent End User: Industrial, Commercial, Residential, Institutional Installation: Retrofitting, New Construction, Modular, Customized |
| Companies Covered | Johnson Controls, Siemens AG, Robert Bosch GmbH, Honeywell International, Minimax GmbH, Fike Corporation, Carrier Global, Kidde-Fenwal, Halma PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Fire Suppression System (AFSS) Market Strategic Shifts
Detection-to-discharge latency compression is reshaping competitive positioning as optical-thermal sensor fusion enables sub-10-second response thresholds, eliminating the performance gap between conventional and intelligent suppression architectures.
Fluoroketone 1230 is decomposing the clean-agent competitive structure through its zero-ozone-depletion profile and lower global-warming potential versus legacy halocarbons. Data center operators in Virginia and Texas are specifying FK-5-1-12 formulations for new construction, accelerating specification obsolescence for HFC-227ea and HFC-125 inventories. This chemistry migration is decomposing margin pools for distributors holding legacy agent stocks while concentrating formulation advantage with integrated manufacturers.
The EU F-Gas Regulation's phasedown schedule for hydrofluorocarbons is forcing agent substitution across installed bases in Germany, France, and the Netherlands. System recertification costs now exceed 40% of replacement value for pre-2015 installations, redirecting capital toward full system upgrades rather than component retrofits. Commercial high-rise portfolios in Frankfurt and Rotterdam are prioritizing inert gas alternatives to eliminate ongoing regulatory exposure.
Building automation integration is compressing procurement cycles as facilities managers specify suppression systems through master service agreements with integrated fire-safety providers rather than discrete equipment purchases. Germany's industrial manufacturing sector leads this consolidation, bundling detection, suppression, and monitoring under single-vendor accountability. Munich and Stuttgart automotive plants now require API-accessible system diagnostics as standard procurement terms.
Automatic Fire Suppression System (AFSS) Market Segmentation
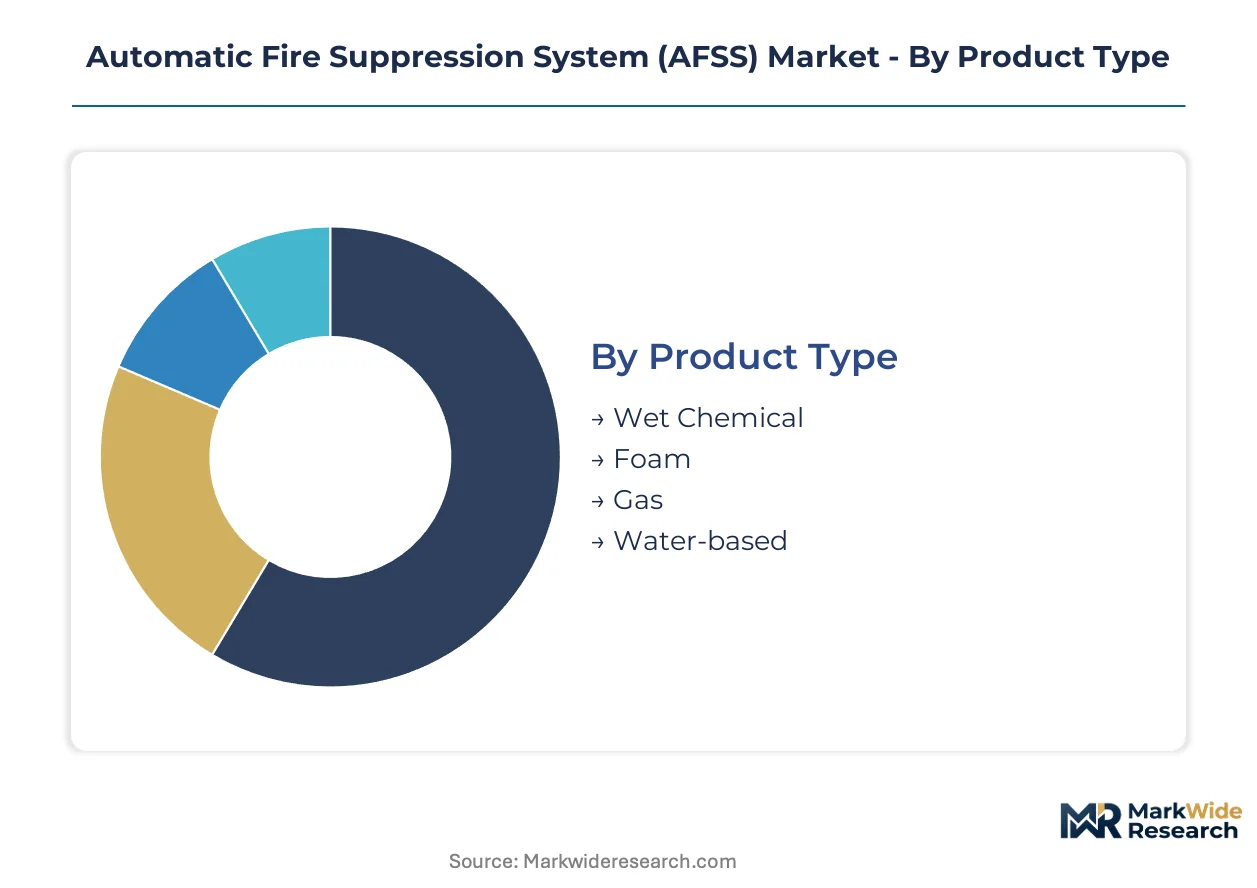
Agent chemistry and activation architecture determine compliance pathways and lifecycle economics across protected-asset categories. Segmentation reveals where formulation advantage concentrates versus where installation volume accumulates.
Product Type:
NFPA 13, NFPA 17A, and NFPA 2001 standards impose distinct concentration thresholds and discharge densities that segment product selection by protected-asset classification.
- Water-based:Sprinkler and water mist architectures dominate new construction pipelines through lower installed cost and straightforward maintenance protocols. German industrial manufacturing plants and Japanese commercial high-rises specify these systems for general hazard protection where water damage presents acceptable risk.
- Gas:Clean-agent and inert gas systems protect electronics-dense environments where discharge residue would exceed fire damage costs. Data center operators in Virginia and Texas prioritize fluoroketone FK-5-1-12 formulations to satisfy NFPA 2001 mandates while eliminating ozone depletion liability.
- Foam:Aqueous film-forming foam concentrates serve flammable liquid hazards in aviation fueling facilities and petrochemical storage terminals. REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation toward fluorine-free alternatives.
- Wet Chemical:Potassium acetate or potassium carbonate solutions extinguish cooking oil fires through saponification. Quick-service restaurant chains standardize UL 300-certified installations across franchise networks.
Established volume favors water-based installations; emerging adoption favors gas systems in electronics protection.
Technology:
Detection-to-discharge latency and agent distribution precision separate premium architectures from commodity specifications.
- Clean Agent:Total flooding systems utilizing fluoroketone or inert gas blends achieve sub-10-second discharge initiation through addressable detection loops. Museum and archival facilities specify these architectures where artifact preservation mandates zero-residue suppression.
- Pre-action:Double-interlock configurations requiring both detection and sprinkler activation prevent accidental discharge in data centers and telecommunications facilities. The dual-trigger architecture commands 25-40% installation premium over wet pipe alternatives.
- Deluge:Open-nozzle systems flood entire zones upon detection activation, serving high-hazard industrial processes with rapid fire spread potential. Chemical processing plants and aircraft hangars mandate these configurations.
- Spray Nozzle:Directed discharge patterns optimize agent distribution for specialized hazards including transformer vaults and turbine enclosures. Marine and offshore platforms require KBA and TÜV type-approval for salt-corrosion resistance.
Pre-action systems gain share fastest in data center construction; deluge configurations retain dominance in heavy industrial hazard protection.
End User:
Procurement sophistication and regulatory exposure vary sharply across occupancy classifications.
- Commercial:Office towers, retail complexes, and hospitality properties balance life safety with business continuity requirements. Facilities managers increasingly specify suppression through integrated fire-safety master service agreements.
- Industrial:Manufacturing plants and warehousing operations prioritize rapid suppression to protect production continuity and inventory value. Germany's automotive sector bundles detection, suppression, and monitoring under single-vendor accountability.
- Institutional:Healthcare, education, and government facilities face stringent inspection protocols and extended asset holding periods. These buyers emphasize lifecycle cost over first-cost procurement.
- Residential:Single-family and multi-family housing installations concentrate in code-mandated new construction with limited retrofit penetration. Builders specify contractor-grade systems to minimize cost impact on project budgets.
Industrial buyers concentrate premium spending; residential installations represent volume base with compressed margins.
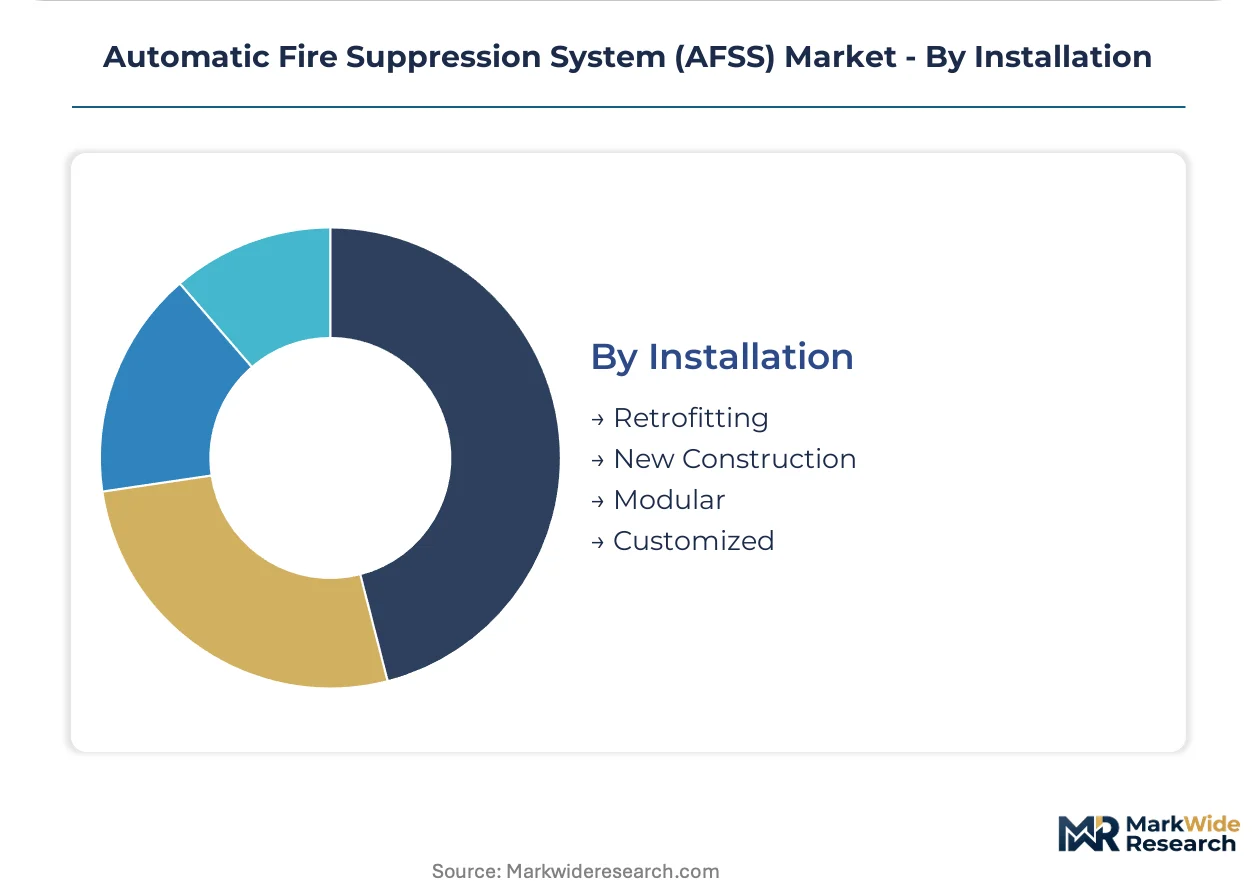
Installation:
Project delivery mode shapes vendor qualification requirements and margin capture potential.
- New Construction:Design-build and plan-spec delivery channels dominate, with suppression systems specified during architectural design phase. Coordination with structural, mechanical, and electrical trades determines installation efficiency.
- Retrofitting:Heritage building upgrades and code-mandated recertifications drive demand for clean-agent conversions. EU F-Gas Regulation phase-downs force premature replacement of HFC-based systems.
- Modular:Pre-engineered skid-mounted systems reduce field installation labor for standardized hazards. Containerized data centers and modular manufacturing facilities specify these configurations for accelerated deployment.
- Customized:Engineered solutions address unique hazard geometries including atrium spaces, museum galleries, and specialized industrial processes. These projects require certified testing partnerships and extended approval timelines.
New construction channels capture volume concentration; retrofit and customized installations command premium pricing through specialized engineering requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate low price elasticity for heritage building retrofits and clean-agent specifications, while Indian infrastructure tenders and US residential construction segments compress margins through standardized water-based procurement.
United States
Data center construction in Virginia and Texas drives fluoroketone FK-5-1-12 adoption as NFPA 2001 concentration mandates force system recertification. The EPA enforces phasedown schedules for hydrofluorocarbons that accelerate agent chemistry transitions. Quick-service restaurant chains across the Southeast standardize UL 300-certified wet chemical installations.
Germany
Automotive manufacturing plants in Munich and Stuttgart bundle detection, suppression, and monitoring under single-vendor master service agreements. The EU F-Gas Regulation and REACH restrictions force premature obsolescence of installed halocarbon systems. KBA and TÜV type-approvals block generic competitors from marine and offshore platform contracts.
Japan
Commercial high-rise construction in Tokyo and Osaka specifies water mist systems for general hazard protection where residue-free discharge is not critical. METI safety protocols for hydrogen fueling stations mandate specialized high-pressure gas suppression architectures. JIS certification requirements create parallel compliance tracks that extend product launch timelines.
India
Metro rail systems and commercial high-rise construction in Mumbai and Delhi create first-mover advantage for vendors establishing GB-standard certification partnerships. The Bureau of Indian Standards governs product safety and performance benchmarks. Infrastructure buildout concentrates demand in Maharashtra and Gujarat where state-level fire safety codes tighten enforcement.
China
Fluorinated agent precursor manufacturing concentrates among domestic chemical suppliers, exposing European and North American system builders to input cost volatility. GB standards create fragmented vendor qualification requirements across Asia-Pacific supply chains. Data center clusters in the Yangtze River Delta specify clean-agent architectures to protect server infrastructure.
Automatic Fire Suppression System (AFSS) Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated manufacturers commanding premium positioning through in-house agent formulation while component assemblers compete on installation volume. The market structure consolidates around firms with captive testing infrastructure and certified regulatory partnerships. Two strategic archetypes dominate: vertically integrated specialists controlling upstream agent chemistry, and system integrators leveraging multi-jurisdiction certification networks. Competitive moves concentrate on strategic partnerships with testing authorities and geographic expansion through local certification acquisitions.
Within the integrated formulation tier, Johnson Controls and Siemens AG occupy positions that exemplify technology-led positioning, with the former leveraging captive supply advantages and the latter anchoring European market access through Germany's KBA and TÜV entities. Minimax GmbH represents the specialized integration archetype where regulatory stringency in marine and offshore applications blocks generic entrants.
| Leading Market Players |
|---|
| Johnson Controls |
| Siemens AG |
| Robert Bosch GmbH |
| Honeywell International |
| Minimax GmbH |
| Fike Corporation |
| Carrier Global |
| Kidde-Fenwal |
| Halma PLC |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at fluorinated agent precursor plants in China and India sets floor pricing for clean-agent formulations worldwide, compressing margin pools for European and North American system assemblers while rewarding integrated manufacturers with captive chemical production. This scale asymmetry concentrates pricing power among firms controlling upstream fluoroketone blending capacity, particularly as REACH and F-Gas Regulation phase-downs accelerate chemistry transitions.
Pricing Analysis
After-sales service contracts and recertification revenue streams now drive lifetime value for system integrators, shifting commercial focus from equipment margins to multi-year maintenance agreements. Project-based pricing dominates new construction channels, while retrofit installations command 40-60% premiums over replacement value due to engineering complexity. Price differentiation rests on UL/FM certification tiers and NFPA 2001 compliance verification. Cost compression in water-based commodity tiers is intensifying because Chinese manufacturers are exporting pre-assembled sprinkler packages. Quick-service restaurant chains exhibit highest price sensitivity, whereas data center operators prioritize agent performance over first cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail for standardized water-based components, but strategic stockpiling of fluoroketone precursors has become standard practice among integrated manufacturers anticipating F-Gas Regulation supply disruptions. Fluorinated agent production concentrates in China, Germany, and the United States, with specialty inert gas blending anchored in France and Japan. Raw material dependencies include hexafluoropropylene, potassium carbonate for wet chemical formulations, and specialized corrosion-resistant alloys for marine nozzles. Single-source vulnerability runs through Chinese fluorochemical feedstock suppliers. Distribution runs through certified system integrators and fire-safety master service agreements rather than open equipment markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
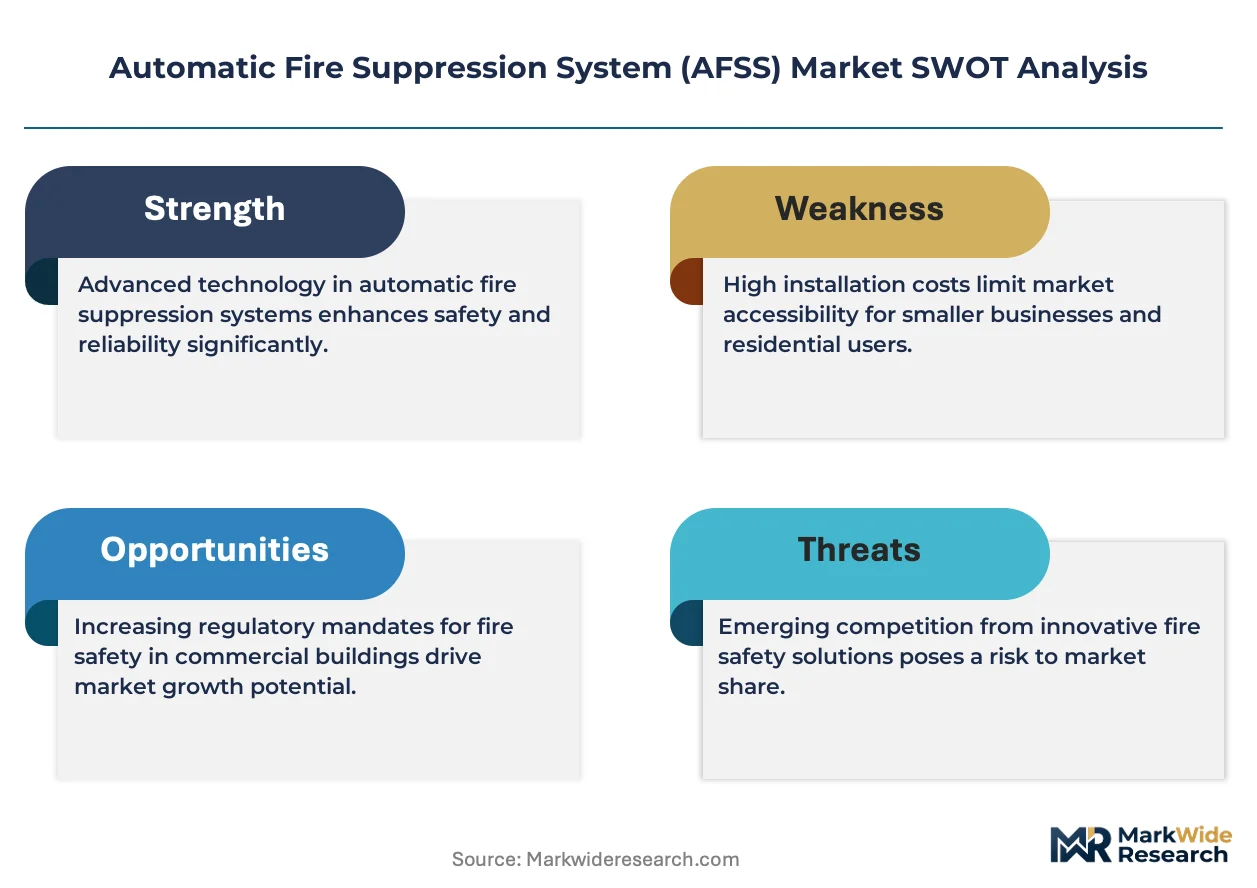
The Automatic Fire Suppression System market is entering a cyclical recovery phase as NFPA 2001 recertification mandates and EU F-Gas Regulation phase-downs force replacement demand ahead of normal depreciation cycles.
For Market Incumbents: Shield installed base revenue by embedding API-accessible diagnostics into master service agreements, locking facilities managers into multi-year recertification contracts before competitors can displace agent chemistry choices. Accelerate backward integration into fluoroketone formulation capacity to neutralize Chinese precursor supply risk and capture margin pools that pure assemblers cannot access.
For New Entrants and Emerging Players: Modular pre-engineered skid systems for containerized data centers represent a service-layer gap where incumbents under-serve rapid-deployment infrastructure needs. Target India's metro rail and commercial high-rise construction in Maharashtra and Gujarat through GB-standard certification partnerships, using localized testing alliances as the primary go-to-market angle rather than competing head-to-head on agent chemistry.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated specialists with in-house fluoroketone blending and KBA/TÜV type-approval documentation over pure-play assemblers facing margin compression. Long-term viability hinges on regulatory compliance infrastructure rather than installation volume. The acquisition target archetype is regional system integrators possessing certified testing partnerships in underserved jurisdictions. Watch for F-Gas Regulation acceleration or halocarbon ban extensions as the inflection signal that would trigger rapid consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Agent Chemistry Reformulation | Fluoroketone FK-5-1-12 substitution eliminates ozone depletion liability under EPA phasedown schedules. |
| Certified Testing Partnership Expansion | KBA and TÜV type-approvals block generic competitors from German marine and offshore platform contracts. |
| Backward Integration into Precursor Supply | Captive hexafluoropropylene production insulates margin pools from Chinese supply disruption. |
| AI-Driven Detection Convergence | Machine-vision smoke recognition reduces false discharge incidents in museum and archival applications. |
| Modular System Pre-engineering | Skid-mounted configurations accelerate deployment for containerized data centers and manufacturing facilities. |
Study Parameters
Initial hypotheses were tested against primary input from fire safety engineering directors, facilities management procurement leads, marine classification surveyors, and aftermarket service heads, then refined through secondary validation against NFPA technical committee minutes, EPA enforcement action databases, EU ECHA substance restriction filings, and customs trade data on fluorinated chemical flows. Bottom-up installation volume estimates triangulated with top-down agent chemistry consumption data.
Variance decomposition across the projection horizon isolates growth contributions from retrofit replacement cycles, new construction penetration, and regulatory-forced obsolescence. Segmentation dimensions modeled include agent chemistry type, activation architecture, protected-asset classification, and regional regulatory cluster. CAGRs were derived from installed base turnover rates and replacement value capture assumptions. Industry-specific forecast inputs include NFPA 2001 concentration mandate compliance timelines and EU F-Gas Regulation phasedown schedules.
Forecasts assume regulatory continuity in US EPA enforcement, EU REACH and F-Gas frameworks, and China's GB standards development; material policy shifts would require re-modeling agent substitution trajectories and recertification cost assumptions. Revision becomes warranted when fluoroketone precursor supply disruption or accelerated halocarbon bans cross thresholds that alter replacement economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
United States Fire Sprinklers Market
Fire Safety & Protection
Fire Resistant Silicone Sealant Market
Fire Safety & Protection
Fire Extinguisher Inspection Services Market
Fire Safety & Protection
Global Fire Resistant Cable Market
Fire Safety & Protection
Europe Passive Fire Protection Market
Fire Safety & Protection
Civil Combustible Gas Alarm Market
Fire Safety & Protection
Smart Smoke Alarm Market
Fire Safety & Protection
Flame Detector System Market
Fire Safety & Protection
Firefighting Hose Market
Fire Safety & Protection
Fire Fighting Foam Market
Fire Safety & Protection
Fire Resistant Glass Market
Fire Safety & Protection
Smoke Detector Market
Fire Safety & Protection
Automatic Fire Ball Extinguisher Market
Fire Safety & Protection
UAE Firefighting Foam Market
Fire Safety & Protection
Fire Extinguisher Market
Fire Safety & Protection
Global Fire Suppression System Market