
 UAE Fire Protection System Market | 2026-2036
UAE Fire Protection System Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Fire Protection System Market Insights
NFPA 13 and UAE Civil Defence Tier-1 certification standards is rotating procurement specifications toward addressable smart architectures. NAFFCO leverages in-house manufacturing of UL-listed panels to sustain pricing power across Gulf Cooperation Council tenders. Honeywell International Inc. dominates building management integration, while Johnson Controls anchors large-scale infrastructure contracts through its Tyco fire products division.
UAE fire protection systems encompass active and passive suppression technologies engineered to detect, control, and extinguish fire events through water-based, gaseous, or chemical agents, with operating pressures typically ranging from 175 psi for wet-pipe sprinklers to 450 psi for high-pressure mist systems. These installations serve to safeguard occupant evacuation timelines and preserve structural integrity in steel-frame commercial towers exceeding 50 stories. Sprinkler systems generate the largest installed base revenue pool given mandatory retrofit deadlines in existing Dubai commercial stock, while smart fire systems represent the fastest-expanding technology segment as IoT-enabled sensor networks displace conventional zone architectures. Installation services capture disproportionate margin concentration due to specialist labor scarcity and Civil Defence sign-off requirements.
MOHAP and the UAE Civil Defence enforce NFPA 101 life safety codes alongside local amendments mandating quarterly inspection intervals and certified installer registries for addressable systems. The Emirates Authority for Standardization and Metrology (ESMA) administers product conformity schemes that block uncertified equipment from federal procurement channels. Stakeholders must monitor evolving smart building interoperability mandates as Dubai's building code revisions integrate fire systems with city-wide emergency response networks.
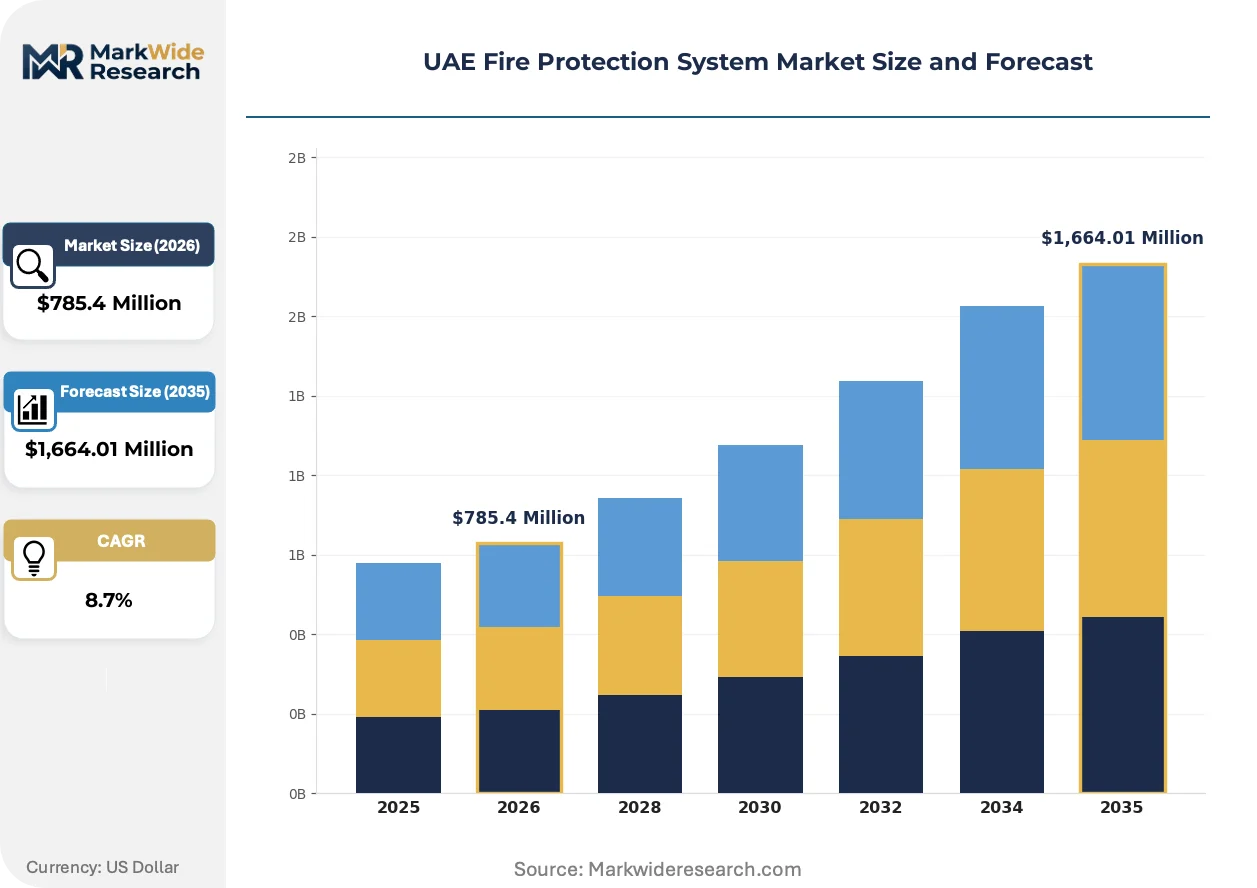
Market Dynamics
The UAE Civil Defence mandate for smart addressable systems is compressing installation timelines while specialist labor scarcity inflates service margins across Dubai and Abu Dhabi's commercial corridors.
Growth Catalysts
- NFPA 13 Retrofit Deadlines:Mandatory sprinkler upgrades in existing Dubai commercial stock are accelerating replacement cycles across aging high-rise inventory.
- Smart Building Integration Mandates:Dubai's building code revisions require fire systems to interface with city-wide emergency response networks, forcing architecture upgrades.
- Mega-Project Pipelines:Sustained development in Dubai's commercial corridor generates concentrated demand for integrated suppression infrastructure in towers exceeding 50 stories.
Market Restraints
- Specialist Labor Scarcity:Certified installer registries maintained by UAE Civil Defence constrain field execution capacity during peak construction windows.
- Steel and Copper Input Volatility:Wet-pipe sprinkler fabrication depends on commodity metal pricing that compresses equipment margins unpredictably.
- Legacy Zone Architecture Persistence:Existing installed base of conventional detection systems creates upgrade friction in budget-constrained facilities.
Strategic Opportunities
- Abu Dhabi Commercial Expansion:Secondary emirate development outside Dubai's saturated corridor offers untapped addressable system penetration.
- IoT-Enabled Predictive Maintenance:Sensor network convergence with building management platforms enables recurring service revenue streams.
- ESMA Conformity Scheme Gatekeeping:Federal procurement channel restrictions on uncertified equipment create compliance-based competitive moats for certified suppliers.
Industry Challenges
- Civil Defence Sign-Off Bottlenecks:Quarterly inspection intervals and documentation requirements extend project closeout timelines unpredictably.
- Interoperability Certification Complexity:Smart system integration with third-party building management platforms demands multi-vendor testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Fire Protection System Market |
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,664.01 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire Alarm Systems, Sprinkler Systems, Fire Extinguishers, Smoke Detectors End User: Commercial Buildings, Industrial Facilities, Residential Properties, Government Institutions Service Type: Installation, Maintenance, Inspection, Consulting Technology: Conventional Systems, Addressable Systems, Wireless Technology, Smart Fire Systems |
| Companies Covered | Emirates Fire Fighting Equipment Factory (FIREX), Bristol Fire Engineering LLC, NAFFCO, SFFECO, MMJ, Honeywell International Inc., Robert Bosch Middle East FZE, Holmatro, Johnson Controls, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Fire Protection System Market Trends and Innovations
Addressable detection architectures are supplanting conventional zone systems across UAE commercial towers, while regulatory pressure accelerates compliance technology refresh cycles.
High-pressure water mist systems are decomposing traditional sprinkler specifications in UAE data center and heritage building applications. Facility managers in Dubai's financial district are specifying mist infrastructure to minimize water damage during discharge events. This technology is decomposing the historical wet-pipe monopoly in sensitive-asset verticals.
UAE Civil Defence Tier-1 certification standards are tightening equipment eligibility for federal tenders. The mandate disqualifies non-addressable panels from new commercial installations above 15 stories. Dubai's high-rise developers are responding by specifying UL-listed smart architectures exclusively in procurement packages.
Maintenance contracting is unbundling from initial installation across UAE commercial properties. Facility management firms are separating detection system upkeep from construction-phase contracts. This pattern concentrates in Abu Dhabi's government-owned commercial portfolio, where long-term service agreements now outlast builder warranties.
UAE Fire Protection System Market Segmentation
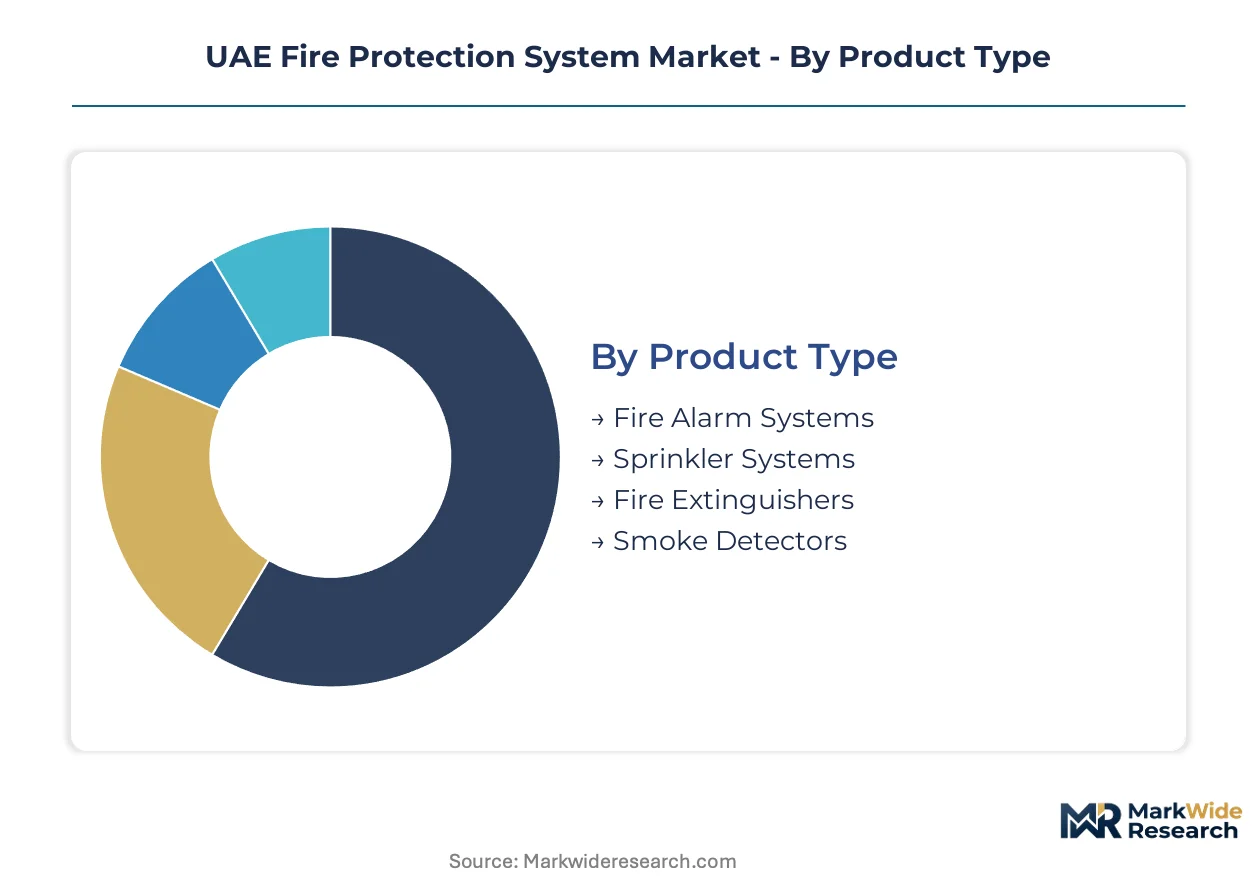
Segmentation reveals how procurement flows diverge across UAE construction channels. Channel specialization dictates margin capture and certification requirements for each product and service category.
Product Type:
Installation contractors route equipment through Civil Defence-certified distributors, with specification-grade products commanding premium placement in Dubai's high-rise developments.
- Fire Alarm Systems:Addressable control panels with loop-isolation capabilities serve as the central nervous system for multi-zone detection. Dubai commercial towers above 50 stories specify these exclusively to meet Tier-1 certification mandates from UAE Civil Defence.
- Sprinkler Systems:Wet-pipe configurations utilizing steel and copper distribution networks constitute the dominant installed base. Mandatory NFPA 13 retrofit deadlines in aging Dubai commercial stock sustain replacement demand despite commodity metal price volatility.
- Fire Extinguishers:Portable suppression units certified to ESMA conformity schemes populate mandatory placement schedules across all occupancy classes.
- Smoke Detectors:Photoelectric and ionization sensors deploy in networked arrays for early-stage fire identification.
Sprinkler systems dominate installed base. Smart fire systems are where expansion concentrates.
End User:
Cost tier differentiation separates specification-grade infrastructure from commodity-grade residential installations, with certification burden scaling directly with building height and occupancy density.
- Commercial Buildings:Steel-frame towers exceeding 50 stories demand integrated suppression infrastructure with building management system interoperability. Dubai's financial district developers specify high-pressure mist systems to minimize water damage discharge risks in sensitive-asset environments.
- Industrial Facilities:Oil and gas processing plants and petrochemical complexes require specialized gaseous suppression for Class B and Class C fire risks. Abu Dhabi's industrial zones drive concentrated demand for foam-based and clean-agent systems.
- Residential Properties:Mid-rise apartment complexes and villa compounds utilize conventional zone architectures with lower compliance thresholds.
- Government Institutions:Federal procurement channels restrict equipment eligibility to ESMA-certified and Civil Defence-approved manufacturers exclusively.
Commercial buildings anchor revenue concentration. Government institutions represent the most tightly regulated procurement channel.
Service Type:
Margin structure inverts across the project lifecycle, with post-installation services capturing disproportionate returns due to specialist labor scarcity and mandatory sign-off requirements.
- Installation:Turnkey system deployment requiring Civil Defence witness testing and commissioning documentation. Dubai's compressed construction windows strain certified installer registry capacity during peak development cycles.
- Maintenance:Recurring service agreements now outlast builder warranties in Abu Dhabi's government-owned commercial portfolio. Facility management firms unbundle detection system upkeep from construction-phase contracts to capture long-term revenue streams.
- Inspection:Quarterly intervals mandated by MOHAP and UAE Civil Defence generate predictable compliance expenditure.
- Consulting:Fire safety engineering services support design-phase specification development for complex high-rise integration.
Installation commands front-loaded project value. Maintenance is climbing the fastest as contract structures shift toward lifecycle service models.
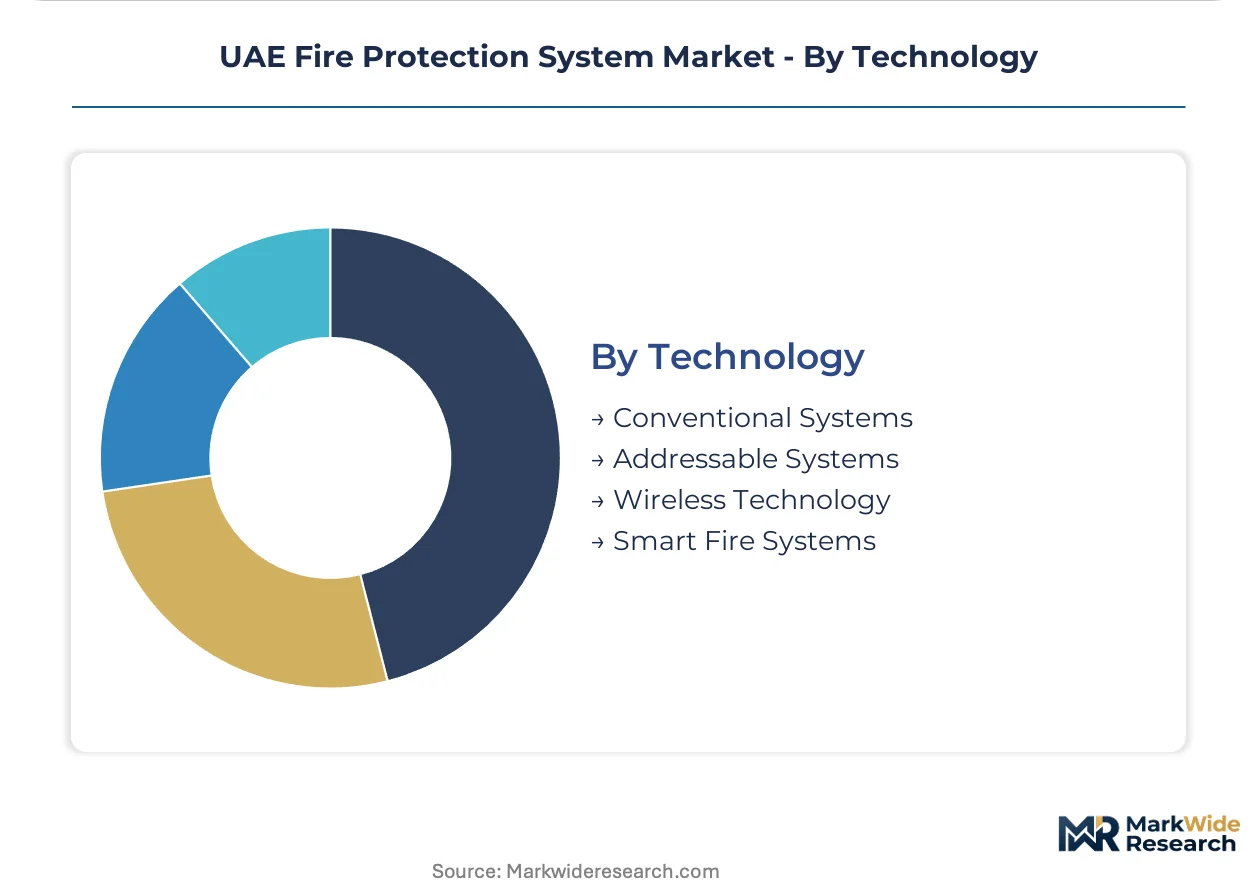
Technology:
Application requirements drive technology selection, with height thresholds and asset sensitivity determining system architecture complexity.
- Conventional Systems:Zone-based detection architectures with hardwired initiating device circuits. Budget-constrained facilities in legacy building stock retain these configurations despite upgrade friction.
- Addressable Systems:Smart panels with individual device identification and loop-isolation capabilities. UAE Civil Defence mandates disqualify non-addressable panels from new commercial installations above 15 stories.
- Wireless Technology:Radio-frequency communication links eliminating conduit runs in retrofit applications and heritage building environments.
- Smart Fire Systems:IoT-enabled sensor networks with predictive analytics and building management platform convergence. Dubai's building code revisions require interface with city-wide emergency response networks.
Addressable systems are gaining share fastest in new construction. Conventional systems persist in retrofit-constrained installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Dubai's commercial corridor demonstrate the lowest price elasticity given mandatory Tier-1 certification requirements, while Northern Emirates facilities exhibit higher sensitivity to equipment costs. Abu Dhabi government portfolios prioritize compliance over procurement economics.
Dubai
Mega-project pipelines in Business Bay and Downtown Dubai drive concentrated demand for integrated suppression infrastructure in towers exceeding 50 stories. UAE Civil Defence mandates disqualify non-addressable panels from new commercial installations above 15 stories. Dubai's financial district developers specify high-pressure mist systems exclusively to minimize water damage discharge risks in sensitive-asset environments.
Abu Dhabi
Government-owned commercial portfolios unbundle maintenance contracting from initial installation to capture long-term service revenue streams. MOHAP enforces quarterly inspection intervals that generate predictable compliance expenditure across federal properties. Yas Island and Al Maryah Island developments anchor specification-grade infrastructure deployment with building management system interoperability requirements.
Sharjah
Mid-rise residential and industrial facilities retain conventional zone architectures due to budget-constrained upgrade cycles. ESMA conformity schemes block uncertified equipment from federal procurement channels, filtering supplier participation. Industrial City Sharjah generates concentrated demand for foam-based suppression systems serving manufacturing and logistics occupancies.
Northern Emirates
Ras Al Khaimah and Fujairah construction activity concentrates in hospitality and mixed-use developments with lower compliance thresholds than Dubai or Abu Dhabi. Legacy zone architecture persistence creates upgrade friction as facility managers weigh retrofit investments against operational budgets. New resort developments in Al Marjan Island and Dibba specify addressable systems to align with Emirates-wide insurance underwriting standards.
UAE Fire Protection System Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the UAE fire protection system market. Gulf-based manufacturers with in-house fabrication capabilities anchor the mid-market with vertically integrated cost structures, while multinational building technology conglomerates dominate premium-tier integration contracts. Three archetypes define competitive positioning: domestic fabrication specialists, global fire safety systems integrators, and diversified building management platform providers. Consolidation pressure intensifies as ESMA conformity requirements raise certification barriers, while specialist labor scarcity drives service-oriented players toward recurring revenue models.
Among UAE-based specialists, NAFFCO occupies a position exemplifying captive manufacturing advantages through UL-listed panel production. Honeywell International Inc. and Johnson Controls represent the multinational integration tier, anchoring large-scale infrastructure contracts through building management convergence capabilities. These three players illustrate the market's bifurcation between compliance-driven domestic fabrication and platform-scale global integration.
| Leading Market Players |
|---|
| Emirates Fire Fighting Equipment Factory (FIREX) |
| Bristol Fire Engineering LLC |
| NAFFCO |
| SFFECO |
| MMJ |
| Honeywell International Inc. |
| Robert Bosch Middle East FZE |
| Holmatro |
| Johnson Controls |
| Others |
Pricing and Supply Chain Analysis
Long-term maintenance contracting structures lock in both supply access and price visibility across UAE commercial portfolios, as facility management firms unbundle service agreements from construction-phase contracts to secure recurring revenue streams under MOHAP-mandated quarterly inspection regimes.
Pricing Analysis
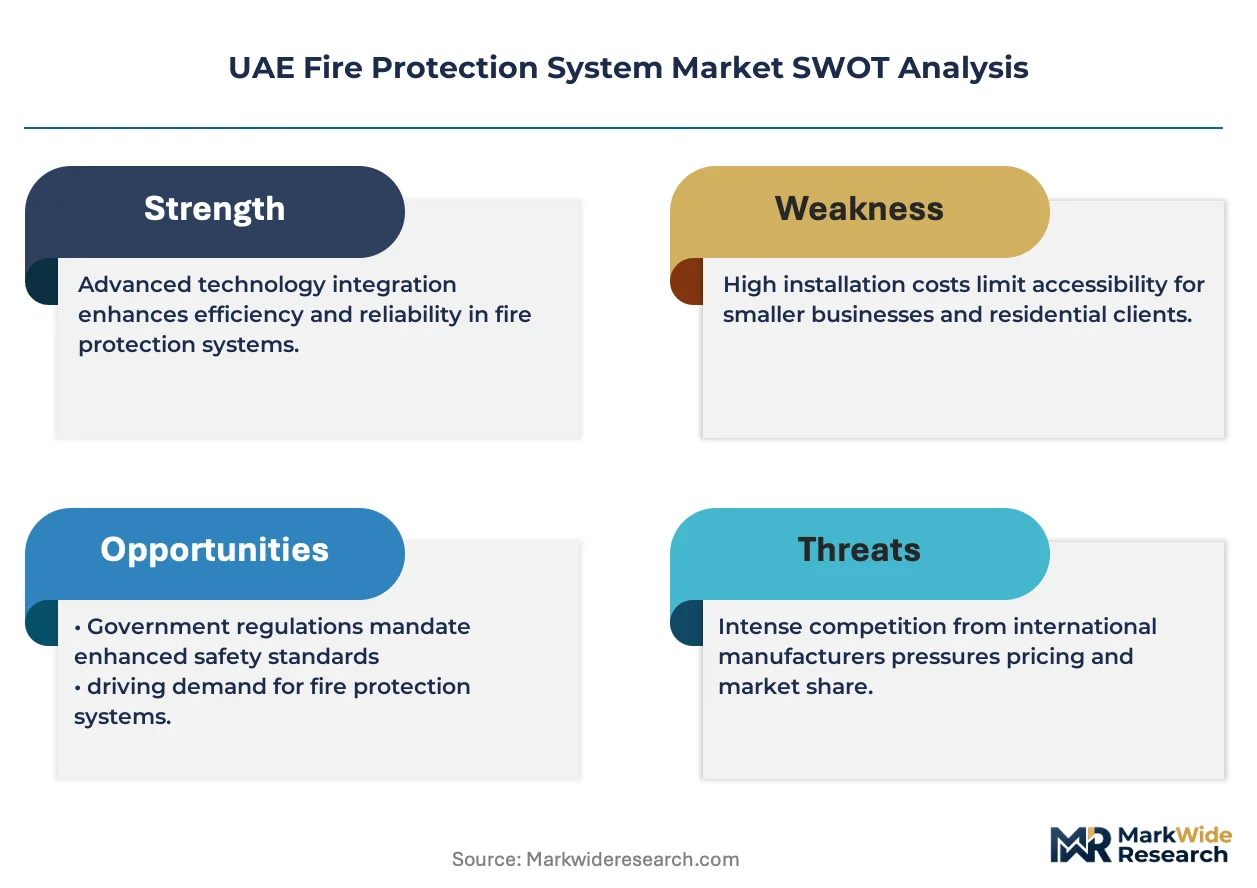
UAE Civil Defence Tier-1 certification dictates the pricing tier structure across fire protection procurement channels. Three-tier pricing separates addressable smart architectures from conventional zone systems and economy-grade residential installations. Cost compression in wet-pipe sprinkler fabrication intensifies because steel and copper commodity volatility squeezes equipment margins unpredictably. Government institutions exhibit the lowest price sensitivity given ESMA conformity gatekeeping, while Northern Emirates residential developers demonstrate highest elasticity to equipment costs.
Supply Chain Analysis
Port congestion along Jebel Ali-Dubai trade lanes elevates inbound logistics costs for UL-listed control panels and specialized detection components sourced from manufacturing hubs in the United States, Germany, and China. Raw material provisioning draws from steel mills in India, copper refineries in Chile, and electronic component clusters in South Korea. Single-source vulnerability concentrates in semiconductor-dependent addressable panel production. Distribution runs through Civil Defence-certified distributors with exclusive territory rights across emirate-level construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE fire protection system market represents high-growth disruption as IoT-enabled sensor networks displace conventional zone architectures under regulatory mandates for city-wide emergency response integration.
For Market Incumbents: Fortify certification moats by deepening backward integration into UL-listed panel manufacturing and expanding captive installer training capacity to offset UAE Civil Defence registry constraints. Addressable system commoditization from multinational building technology conglomerates threatens mid-market positioning. Prioritize ESMA conformity scheme navigation to maintain federal procurement channel access. For New Entrants and Emerging Players: Lead with predictive maintenance software platforms targeting Abu Dhabi's government-owned commercial portfolio where long-term service agreements now outlast builder warranties. Sharjah's industrial corridor offers penetrable white-space for foam-based suppression specialization. Deploy direct facility management partnerships bypassing distributor-controlled Dubai procurement channels. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated domestic fabrication specialists with captive Civil Defence installer registries and established ESMA certification pathways. Long-term viability hinges on recurring service revenue capture as hardware margins compress. Monitor Dubai building code revision timelines for smart building interoperability mandates as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | ESMA conformity scheme compliance unlocks federal procurement channel participation. |
| Installer Capacity Expansion | Civil Defence registry positions capture margin-concentrated maintenance contracting. |
| Smart System Integration | Building management platform convergence meets Dubai emergency network mandates. |
| Geographic Diversification | Abu Dhabi and Northern Emirates development pipelines reduce Dubai corridor dependence. |
| Predictive Maintenance Platform | IoT sensor analytics enable recurring revenue streams beyond hardware installation. |
Research Methodology
The analysis maps active suppression technologies, passive fire protection systems, detection architectures, and service contracting models, each validated through fire safety engineers, Civil Defence certification officers, facility management procurement leads, and installation contractor operations directors. Primary fieldwork combined with secondary validation from UAE Civil Defence regulatory filings, ESMA conformity scheme databases, NFPA technical standards, and emirate-level building permit records. Bottom-up equipment shipment tracking and top-down construction spend estimates provided triangulation anchors.
Model outputs were consistency-checked against external benchmarks including regional building automation market trajectories and Gulf Cooperation Council infrastructure investment disclosures. Segmentation dimensions spanned product type, end-user vertical, service category, and technology architecture across the projection horizon. CAGRs were derived from fitted growth curves calibrated to regulatory mandate implementation schedules and mega-project pipeline visibility. Forecast inputs incorporated specialist labor scarcity metrics and commodity metal price trend assumptions.
Forecasts assume regulatory continuity in UAE Civil Defence Tier-1 mandates and Dubai building code smart integration requirements; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Flame Barrier Market
Fire Safety & Protection
Firefighting Hose Market
Fire Safety & Protection
Civil Combustible Gas Alarm Market
Fire Safety & Protection
Global Fire Control System Market
Fire Safety & Protection
Global Smoke Evacuation Systems Market
Fire Safety & Protection
High Pressure Fixed Firefighting Misting System Market
Fire Safety & Protection
Smart Smoke Alarm Market
Fire Safety & Protection
Global Fire Suppression System Market
Fire Safety & Protection
Europe Fire-Resistant Glass Market
Fire Safety & Protection
Fire Extinguisher Inspection Services Market
Fire Safety & Protection
Fire Protection Systems for Industrial Cooking Market
Fire Safety & Protection
Fire Extinguisher Market
Fire Safety & Protection
Fire Resistant Silicone Sealant Market
Fire Safety & Protection
Fire Protection Coating Market
Fire Safety & Protection
Fire Department Software Market
Fire Safety & Protection
Wireless Fire Detection Systems Market