
 Fire Resistant Silicone Sealant Market | 2026-2036
Fire Resistant Silicone Sealant Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Resistant Silicone Sealant Market Insights
Advanced intumescent chemistry is narrowing the performance gap between standard silicone sealants and specialized firestop systems, enabling single-product solutions for combined weatherproofing and fire-rating applications. Sika AG leverages its global construction chemicals footprint to sustain specification relationships with tier-one contractors across Europe and Asia-Pacific. Dow anchors its position through captive silicone polymer supply and deep R&D into low-VOC, neutral-cure formulations that meet evolving emissions standards. Hilti Group differentiates by integrating firestop sealants with its engineered fastening and passive fire protection systems, creating bundled specification pathways for commercial projects.
Fire resistant silicone sealant denotes an elastomeric joint sealant formulated with silicone polymers and fire-retardant additives, typically achieving ASTM E814/UL 1479 ratings for through-penetration firestopping and exhibiting service temperatures from minus 50 degrees Celsius to over 200 degrees Celsius while maintaining adhesion to concrete, steel, and gypsum substrates. Its primary industrial purpose is to maintain the integrity of fire-rated compartment barriers by sealing joints, gaps, and service penetrations against flame propagation and smoke passage during fire events. Neutral cure formulations command the dominant share among product types due to their compatibility with sensitive substrates like marble and coated metals, while specialty sealants represent the fastest-expanding category as architects specify customized solutions for curtainwall and expansion joint applications. Construction absorbs the largest application volume, though aerospace demand is accelerating as OEMs seek lighter-weight fire barrier materials that reduce fuel consumption without sacrificing FST (flame, smoke, toxicity) compliance.
NFPA standards, IBC model codes, and UL 1479 certification requirements collectively shape product development priorities and market access conditions across North America, with manufacturers investing in third-party testing to maintain listing validity. ECHA REACH restrictions on certain flame-retardant chemistries and the EU Construction Products Regulation mandating CE marking for firestopping products impose parallel compliance burdens on suppliers serving European projects. China's GB 8624 classification system and mandatory CCC certification for fire-resistant building materials create additional technical barriers that favor domestic producers with established testing relationships. Stakeholders must monitor the divergence between regional fire-test protocols, as harmonization failures between ASTM, EN, and GB methods threaten to fragment product portfolios and inflate certification costs for multinational suppliers.
Market Dynamics
Building code harmonization failures between ASTM E814, EN 1366-3, and GB/T 9978 test protocols are fragmenting product portfolios and inflating third-party certification costs for multinational sealant suppliers.
Growth Catalysts
- IBC Chapter 7 mandates:Updated penetration firestopping requirements in US commercial high-rises are accelerating specification of UL 1479-certified silicone systems for electrical and mechanical service openings.
- Intumescent chemistry advances:Single-product solutions now combine weatherproofing with fire-rating capabilities, reducing contractor material complexity on curtainwall projects.
- China's megacity infrastructure:GB 50016 enforcement in transit hubs and residential towers is expanding procurement of certified firestop sealants in Shanghai, Beijing, and Shenzhen developments.
Market Restraints
- Silicone polymer supply concentration:Captive production by integrated chemical conglomerates limits independent formulator access to base polymers, compressing margin structures for regional specialists.
- ECHA REACH restrictions:Flame-retardant chemistry bans on halogenated additives are forcing reformulation cycles that extend product development timelines by 12-18 months.
- Hybrid polyurethane alternatives:Lower-cost intumescent PU sealants are capturing share in non-critical residential applications where full silicone performance is not specified.
Strategic Opportunities
- India's urban housing stock:BIS fire safety standard adoption in Mumbai and Delhi NCR high-rises creates first-mover positioning for certified suppliers before domestic production scales.
- Aerospace FST compliance:OEM demand for lighter fire barrier materials that maintain flame, smoke, and toxicity ratings is opening specification pathways in commercial aircraft interiors.
- EU Construction Products Regulation:Mandatory CE marking for firestopping products creates technical barriers that favor suppliers with established Notified Body relationships.
Industry Challenges
- Fire-test engineer scarcity:Specialized expertise in ASTM, EN, and GB protocol execution is concentrating at third-party laboratories, extending certification queue times.
- Multi-protocol portfolio complexity:Maintaining parallel UL, Intertek, and CCC listings for identical product chemistries duplicates testing expenditure without volume guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Resistant Silicone Sealant Market |
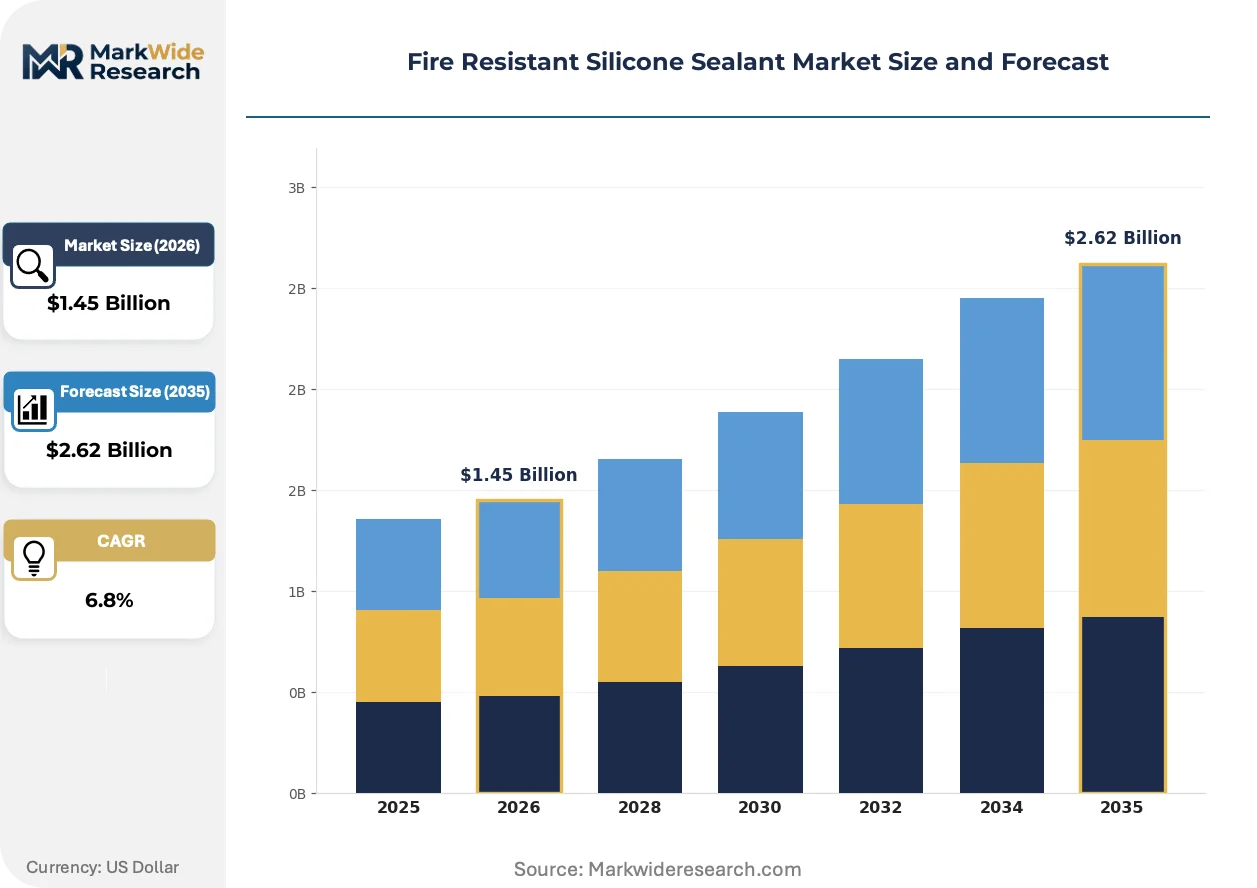
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neutral Cure, Acetic Cure, Specialty Sealants, One-Part Sealants Application: Construction, Automotive, Aerospace, Marine End User: Manufacturers, Contractors, Retailers, DIY Enthusiasts Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | 3M Company, Sika AG, Hilti Group, Dow, RectorSeal, H.B. Fuller Company, Tremco Incorporated, Fosroc, Inc., Promat International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Resistant Silicone Sealant Market Trends and Innovations
Formulation chemistry and procurement models are converging to compress the traditional separation between weatherproofing and fire-rated sealant categories. Three developments are restructuring competitive positioning.
Self-expanding intumescent silicone hybrids are rendering obsolete the two-step application process that required separate weatherseal and firestop products on curtainwall joints. Façade contractors in Germany and Singapore are adopting these systems to reduce labor hours and eliminate compatibility failures between dissimilar materials. The technology is compressing specification decisions toward single-source suppliers capable of dual-certification.
REACH authorization timelines for novel phosphorus-based flame retardants are extending raw material qualification periods for European formulators. ECHA's substance evaluation workload has created bottlenecks that delay new product introductions by 8-14 months. Specialty sealant producers are responding by pre-registering alternative chemistries and building buffer inventories of listed additives.
Consolidated procurement by tier-one construction groups is displacing fragmented distributor purchasing for major commercial projects. General contractors in the United Arab Emirates and Australia are mandating direct manufacturer relationships with certified testing documentation to reduce subcontractor compliance risk. This concentration is visible most acutely in mixed-use developments where firestop warranty chains must remain intact across 10-year defect liability periods.
Fire Resistant Silicone Sealant Market Segmentation
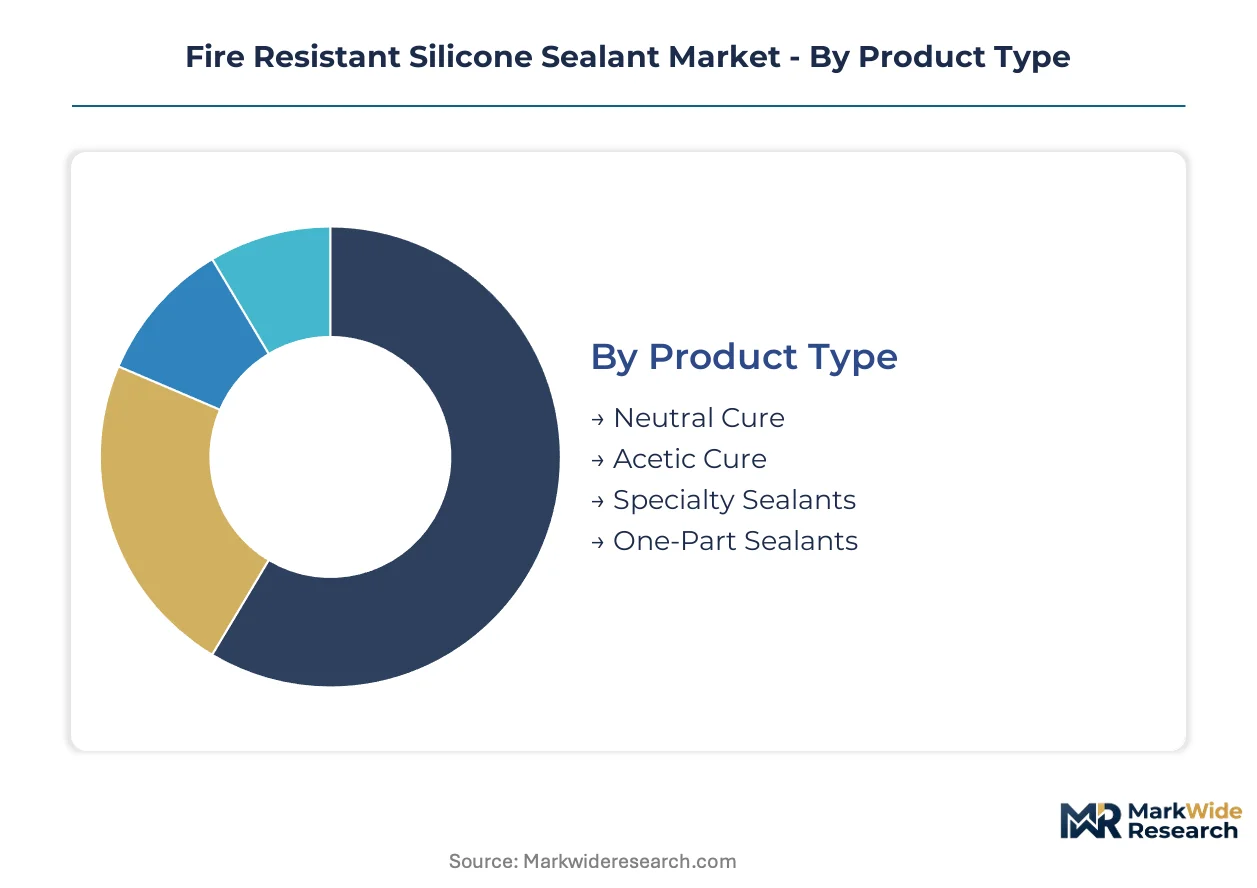
Fire resistant silicone sealant procurement splits across formulation chemistry, installation environment, buyer sophistication, and supply chain access. Each dimension carries distinct margin structures and certification burdens that reshape competitive positioning.
Product Type:
Use-case spectrum spans sensitive substrate compatibility through specialized architectural performance tiers.
- Neutral Cure:Formulations release alcohol during cure rather than acetic acid, preserving adhesion to marble, anodized aluminum, and galvanized steel without corrosion. Demand concentrates in US commercial high-rises where IBC Chapter 7 mandates penetrate firestopping across mixed-material curtainwall assemblies. ASTM C920 compliance and low-VOC emissions certification drive specification decisions among tier-one contractors.
- Specialty Sealants:Custom-engineered products integrate intumescent expansion with movement accommodation for expansion joints and dynamic building interfaces. Architects in Shanghai and Beijing megaprojects specify these for GB 50016-compliant transit hub installations where thermal cycling meets fire-rating continuity. The segment commands premium positioning through dual-certification complexity.
- Acetic Cure:Acid-releasing formulations offer faster skin time and stronger adhesion to glass and ceramics, though substrate limitations restrict deployment.
- One-Part Sealants:Pre-mixed, moisture-cure systems eliminate on-site mixing errors and accelerate contractor productivity in field applications.
The dominant share belongs to Neutral Cure, while Specialty Sealants are climbing the fastest as architects consolidate weatherproofing and firestop functions.
Application:
Volume distribution follows capital expenditure cycles across built environment and transportation manufacturing.
- Construction:Penetration firestopping, control joints, and perimeter sealing in commercial, residential, and infrastructure verticals absorb the bulk of procurement. China's GB 50016 enforcement in Shenzhen and Chengdu residential towers accelerates certified product specification. NFPA 101 life safety code updates in the United States tighten compliance thresholds for high-rise compartment barriers.
- Aerospace:OEM demand for FST-compliant cabin sealing and fire barrier materials reduces aircraft weight while maintaining flame, smoke, and toxicity ratings. Boeing and Airbus tier suppliers qualify lighter silicone formulations against FAA fireworthiness standards. The segment rewards technical partnership depth over price competition.
- Automotive:Battery enclosure sealing and firewall applications in electric vehicle platforms require thermal runaway containment capabilities.
- Marine:IMO SOLAS-compliant sealing for bulkhead penetrations and deck joints in commercial shipping and offshore structures.
Construction retains volume leadership, though Aerospace exhibits the steepest expansion trajectory as electrification reshapes mobility fire safety requirements.
End User:
Buyer sophistication tiers separate specification influence from transaction scale.
- Contractors:General and specialty trade contractors hold specification authority on commercial projects, demanding certified testing documentation and warranty-backed supply chains. UAE and Australian tier-one construction groups now mandate direct manufacturer relationships to reduce subcontractor compliance risk across 10-year defect liability periods. Procurement concentration favors suppliers with established Notified Body relationships.
- Manufacturers:OEMs and system integrators embed sealants into finished products, requiring batch consistency and technical collaboration. Aerospace tier suppliers and automotive battery pack assemblers drive qualification timelines and chemistry customization.
- Retailers:Distributor and big-box channels serve maintenance, repair, and small-scale renovation demand with stocked standard formulations.
- DIY Enthusiasts:Consumer purchasers respond to packaging clarity and application guidance for residential firestop and weatherseal projects.
Contractors command specification leverage, while Manufacturers are gaining procurement sophistication fastest through OEM technical integration demands.
Distribution Channel:
Channel structure balances compliance documentation requirements against logistics cost minimization.
- Direct Sales:Manufacturer-to-contractor relationships dominate major commercial projects where firestop warranty chains must remain intact. Consolidated procurement by UAE and Australian construction groups displaces fragmented distributor purchasing. Direct channels capture premium positioning through technical service bundling and certified documentation custody.
- Distributors:Regional specialists maintain inventory breadth and local technical support for mid-tier contractors and maintenance operations.
- Online Retail:E-commerce platforms expand access for standardized products to remote project sites and small-scale buyers.
- Wholesalers:Volume aggregation serves retailer and contractor networks with inventory financing and logistics efficiency.
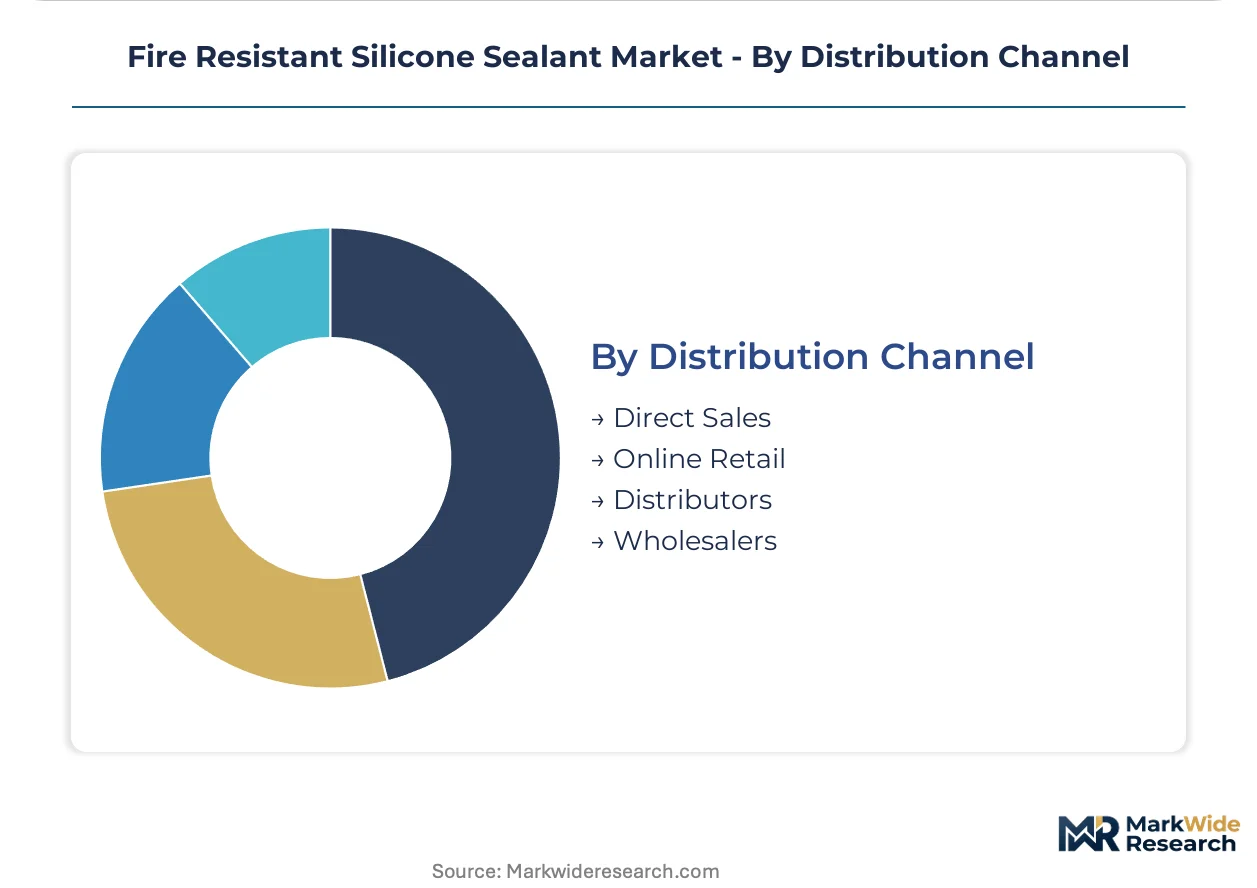
Direct Sales holds the largest revenue share, though Distributors are expanding footprint fastest through regional compliance expertise development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical conglomerates export formulated silicone sealants to construction hubs across the Middle East and Southeast Asia, while Chinese manufacturers supply certified firestop products to Belt and Road infrastructure projects in Central Asia and Africa.
United States
Commercial high-rise construction in New York, Chicago, and Los Angeles drives procurement of UL 1479-certified penetration sealants. NFPA 101 life safety code updates mandate enhanced firestopping in electrical and mechanical service openings. Texas and Florida metropolitan developments concentrate specification activity for intumescent silicone systems in mixed-use towers.
China
Megacity infrastructure investment in Shanghai, Beijing, and Shenzhen accelerates demand for GB 50016-compliant firestop sealants in transit hubs and residential towers. GB 8624 classification requirements and mandatory CCC certification create technical barriers favoring domestic producers with established testing relationships. Chengdu and Chongqing developments in western China expand procurement volumes for certified silicone products.
Germany
Curtainwall and façade engineering excellence in Frankfurt, Munich, and Hamburg sustains specification of dual-certified weatherproofing and fire-rated sealants. ECHA REACH restrictions on halogenated flame retardants force reformulation cycles that extend product development timelines. The Ruhr industrial corridor hosts testing laboratories executing EN 1366-3 protocols for European market access.
United Arab Emirates
Mixed-use developments in Dubai and Abu Dhabi mandate direct manufacturer relationships to maintain firestop warranty chains across 10-year defect liability periods. MOHAP building safety regulations align with international fire-test standards for high-rise compartment barriers. Tier-one construction groups consolidate procurement away from fragmented distributor channels.
India
Urban housing stock expansion in Mumbai and Delhi NCR creates first-mover positioning for certified suppliers before domestic production scales. BIS fire safety standard adoption in high-rise residential towers tightens compliance thresholds for penetration firestopping. Bengaluru and Hyderabad commercial developments accelerate specification of imported silicone sealants pending local certification infrastructure maturation.
Fire Resistant Silicone Sealant Market Competitive Landscape
On the supply side, the industry is consolidating around integrated chemical conglomerates with captive silicone polymer production and specialized construction chemical groups with deep specification relationships. Three archetypes dominate: diversified materials conglomerates controlling upstream polymer supply, construction chemical specialists bundling firestop with passive protection systems, and regional formulators competing on certification agility for local code compliance. Capacity expansion and strategic partnerships represent the dominant competitive moves, as players seek to secure testing laboratory relationships and accelerate multi-protocol certification timelines.
Within the diversified materials tier, 3M Company and Dow exemplify supply-side concentration through integrated silicone polymer operations and global distribution infrastructure. Sika AG occupies a position among construction chemical specialists, leveraging specification relationships with tier-one contractors across European and Asia-Pacific markets. Hilti Group anchors the systems-integration archetype, bundling firestop sealants with engineered fastening and passive fire protection portfolios to create consolidated procurement pathways for commercial project developers.
| Leading Market Players |
|---|
| 3M Company |
| Sika AG |
| Hilti Group |
| Dow |
| RectorSeal |
| H.B. Fuller Company |
| Tremco Incorporated |
| Fosroc, Inc. |
| Promat International |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Antwerp chemical corridor freight costs compress margin structures for independent formulators sourcing silicone polymers from integrated conglomerates, while downstream price differentiation widens between certified UL 1479 systems and uncertified alternatives. Supply concentration in Germany and China enables captive producers to sustain premium positioning through direct contractor relationships.
Pricing Analysis
Technology-generation pricing gaps separate legacy acetic-cure formulations from neutral-cure standards and emerging intumescent hybrids. Project-based contract pricing dominates major commercial developments, with differentiation driven by UL certification tier and volume scale. Cost compression in standard-grade tiers intensifies as hybrid polyurethane alternatives capture non-critical residential share. Tier-one contractors exhibit lowest price sensitivity due to warranty liability exposure, while regional distributors face margin pressure from consolidated procurement mandates.
Supply Chain Analysis
Extended payment terms from tier-one construction groups in the UAE and Australia concentrate working capital demands on sealant manufacturers, favoring integrated chemical conglomerates with balance sheet depth. Supply concentrates in Germany, China, and the United States, with raw material dependencies on silicone monomers, phosphorus-based flame retardants, and specialty fillers. Single-source vulnerability in halogenated additive supply chains intensifies as ECHA REACH restrictions force chemistry transitions. Distribution runs through direct manufacturer-contractor channels for major projects, with regional distributors serving mid-tier maintenance demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against lower-cost intumescent polyurethane sealants eroding share in residential applications where full silicone performance specifications are relaxed.
For Market Incumbents: Pre-empt hybrid polyurethane encroachment by accelerating dual-certification investments that combine weatherproofing and firestop functions in single-product solutions. Captive silicone polymer supply and deep testing laboratory relationships anchor defensive positioning against emerging regional formulators in India and Southeast Asia. For New Entrants and Emerging Players: India's urban housing stock in Mumbai and Delhi NCR offers first-mover positioning before domestic production scales and BIS certification infrastructure matures. Target aerospace FST compliance pathways where technical partnership depth outweighs price competition, leveraging lightweight formulation expertise to qualify against FAA fireworthiness standards. For Investors and Strategic Acquirers: Regional formulators with established CCC and GB 50016 testing relationships in China present consolidation targets as multinational suppliers face harmonization failures between ASTM, EN, and GB protocols. Watch ECHA REACH authorization timelines for novel phosphorus-based flame retardants as inflection indicators for European formulator margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Certification Investment | Parallel UL, Intertek, and CCC listings reduce fragmentation costs for multinational suppliers serving ASTM, EN, and GB test standards. |
| Backward Integration into Silicone Polymers | Captive monomer production insulates margin structures from supply concentration among German and Chinese chemical conglomerates. |
| Aerospace FST Partnership Development | Technical collaboration with Boeing and Airbus tier suppliers opens specification pathways for lighter fire barrier materials. |
| India Market Entry Before Domestic Scale | BIS fire safety standard adoption in Mumbai and Delhi NCR high-rises creates positioning ahead of local certification infrastructure maturation. |
| Direct Contractor Relationship Consolidation | UAE and Australian tier-one construction groups mandate manufacturer-direct procurement to maintain firestop warranty chains. |
Research Methodology
The analysis maps neutral-cure, specialty, and acetic-cure formulation sub-sectors, each validated through procurement directors at tier-one construction groups, firestop specification engineers, aerospace tier supplier technical leads, and EHS compliance officers at chemical formulators. Primary interview intelligence triangulates against secondary sources including UL certification databases, ECHA REACH substance registrations, GB standard filings with SAMR, and construction permit data from Shanghai and Shenzhen development authorities. Bottom-up volume builds from project-level procurement data reconcile with top-down chemical industry production estimates.
Assumptions hold IBC Chapter 7 and GB 50016 enforcement trajectories constant across the analysis window, with variable sensitivity applied to REACH authorization timelines and aerospace OEM qualification cycles. Segmentation models incorporate formulation chemistry, installation environment certification tier, buyer sophistication archetype, and supply chain access mode. CAGRs derive from installed base penetration curves and replacement cycle analysis, with inputs from high-rise construction permit pipelines and transit hub infrastructure budgets.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic producers or accelerated hybrid polyurethane substitution would shift outcomes. Macroeconomic deviation in construction lending, regulatory harmonization breakthroughs between ASTM and EN protocols, or breakthrough intumescent chemistry advances would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Smoke and Carbon Monoxide Alarm Market
Fire Safety & Protection
Fire and Explosion Proof Lights Market
Fire Safety & Protection
Commercial Smoke Alarm Market
Fire Safety & Protection
Fire Extinguisher Inspection Services Market
Fire Safety & Protection
High Pressure Fixed Firefighting Misting System Market
Fire Safety & Protection
Australia Emergency Lighting Market
Fire Safety & Protection
Powder Fire Suppression System Market
Fire Safety & Protection
United States Fire Sprinklers Market
Fire Safety & Protection
Smoke Detector Market
Fire Safety & Protection
Fire Resistant Glass Market
Fire Safety & Protection
US Fire Safety Equipment Market
Fire Safety & Protection
Marine Fire Extinguishing System Market
Fire Safety & Protection
Global Smoke Evacuation Systems Market
Fire Safety & Protection
Global Fire Resistant Cable Market
Fire Safety & Protection
Fire Suppression Agent Market
Fire Safety & Protection
GCC Firefighting Foam Market