
 Flame Barrier Market | 2026-2036
Flame Barrier Market Size, Share, and Industry Trends Forecast 2026-2036
Flame Barrier Market Intelligence
Modular firestop kits and pre-cut barrier assemblies is decoupling flame protection from traditional site-fabricated installation, forcing buyers to evaluate bundled performance warranties rather than commodity material costs. 3M Company leverages its adhesive science portfolio to anchor premium positioning in intumescent coating systems. Saint-Gobain sustains manufacturing scale across mineral wool barrier lines through captive raw material sourcing. Specified Technologies competes on code-certification breadth, maintaining UL-listed assemblies that span multiple penetration configurations.
A flame barrier is a passive fire-protection assembly engineered to maintain structural integrity and prevent flame propagation across designated compartments, typically rated by ASTM E119 or EN 1363 fire-resistance duration under standardized thermal load. Intumescent coatings dominate specification in steel-frame commercial buildings where thin-film expansion creates insulating char layers, while fire-resistant fabrics occupy growing share in transportation interiors driven by FAA and EASA burn-through requirements. Fire retardant foams remain margin-diluted due to commodity polyurethane feedstock volatility, though silicone-based variants command price premiums for high-temperature industrial applications.
FDA, EPA, and OSHA frameworks in the United States govern worker exposure limits and VOC emissions during flame barrier installation, while REACH and the EU Green Deal restrict halogenated flame retardants in European construction products. These regulatory layers elevate compliance costs for imported materials and create asymmetric market access between regional certification holders and uncertified suppliers. Stakeholders must monitor evolving MEE enforcement in China and emerging GB standard revisions that could redirect export-oriented capacity toward domestic retrofit programs.
Market Dynamics
Retrofit mandates across Germany's existing building stock are compressing contractor procurement cycles and elevating specification authority toward engineering consultancies over traditional distributor channels.
Growth Catalysts
- EN 1363 Standard Updates:Tighter fire-resistance testing protocols across EU member states are forcing replacement of legacy barrier assemblies in commercial high-rises.
- Steel-Frame Commercial Construction:Thin-film intumescent coatings now dominate specification in mid-rise office towers where aesthetic load-bearing requirements exclude mineral wool alternatives.
- German Retrofit Acceleration:Federal building energy mandates are channeling public procurement toward fire-resistant envelope upgrades in pre-1990s residential blocks.
Market Restraints
- Polyurethane Feedstock Volatility:Fire retardant foams face margin compression from commodity chemical price swings, limiting R&D reinvestment capacity among mid-tier producers.
- Halogenated Compound Bans:REACH restrictions on brominated flame retardants create formulation discontinuity costs for suppliers serving both European and export markets.
- Intumescent Coating Cure Times:Extended drying windows in high-humidity climates restrict application seasonality and labor productivity in coastal construction zones.
Strategic Opportunities
- Transportation Interior Fabrics:FAA and EASA burn-through requirements are opening specification pathways for silicone-coated fiberglass barriers in narrow-body aircraft refurbishment programs.
- Pre-Cut Barrier Assemblies:Offsite manufacturing convergence with BIM workflows allows fabricators to capture margin from installation-labor arbitrage in unionized metropolitan markets.
- China Domestic Retrofit Pivot:Emerging GB standard revisions and MEE enforcement tightening could redirect export-oriented production capacity toward state-funded building safety programs.
Industry Challenges
- Multinational Certification Burden:Maintaining concurrent UL, EN, and GB listings for penetration assemblies requires dedicated compliance teams and extended retesting cycles.
- Intumescent Applicator Skill Shortage:Specialized spray technicians command wage premiums that erode contractor margins on fixed-price commercial bids.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flame Barrier Market |
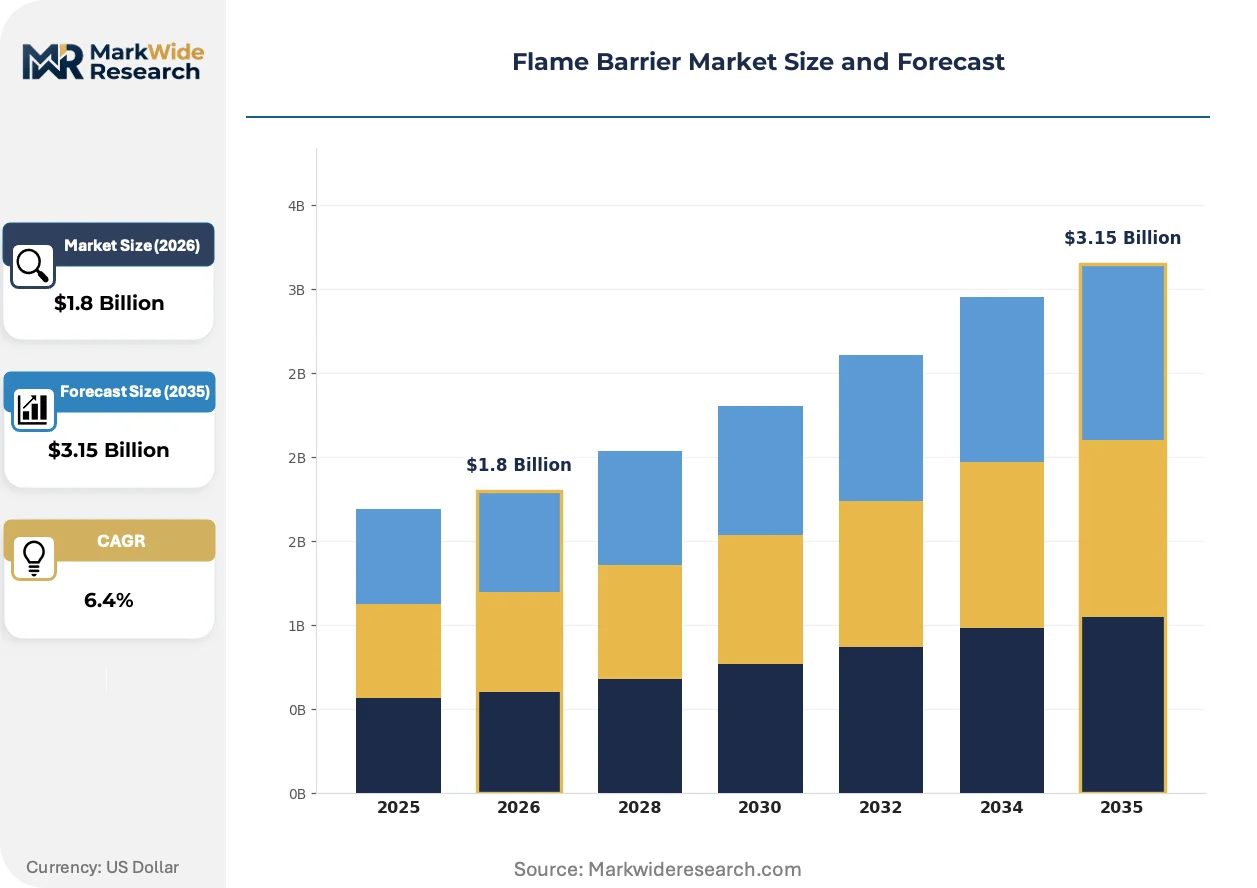
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intumescent Coatings, Fire-Resistant Fabrics, Fire Retardant Foams, Fire-Resistant Barriers Application: Commercial Buildings, Residential Construction, Industrial Facilities, Transportation Material: Polyurethane, Silicone, Glass Fiber, Mineral Wool End User: Construction Companies, Government Agencies, Manufacturing Units, Project Developers |
| Companies Covered | Metacaulk (Balco), Everbuild Building Products, 3M Company, Saint-Gobain, BASF SE, Specified Technologies, Trafalgar Passive Fire Protection Systems, Johnson Controls International, H.B. Fuller, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flame Barrier Market Strategic Shifts & Innovations
Passive fire protection is fragmenting from monolithic material supply toward performance-guaranteed subsystem contracting, rewiring how engineering firms evaluate supplier relationships.
Modular firestop kits are modularizing specification logic across commercial high-rise projects. General contractors in Germany and the Netherlands now procure pre-engineered penetration assemblies with bundled UL certification rather than site-fabricated mineral wool plugs. This shift compresses installation labor hours and transfers liability exposure from installer to manufacturer.
REACH authorization procedures for halogenated flame retardants are accelerating formulation turnover across European construction product portfolios. Suppliers serving the German market must maintain dual-track R&D pipelines to ensure continuity of supply during substance sunset periods. Mineral wool and intumescent alternatives are capturing specification share in public procurement tenders where chemical transparency scoring applies.
Engineering consultancies are consolidating specification authority through performance-based fire engineering contracts. Large commercial developers in London and Frankfurt now delegate barrier selection to fire safety engineers who specify certified assemblies rather than commodity materials. This procurement elevation disadvantages distributor-centric suppliers lacking in-house fire testing capabilities.
Flame Barrier Market Segmentation
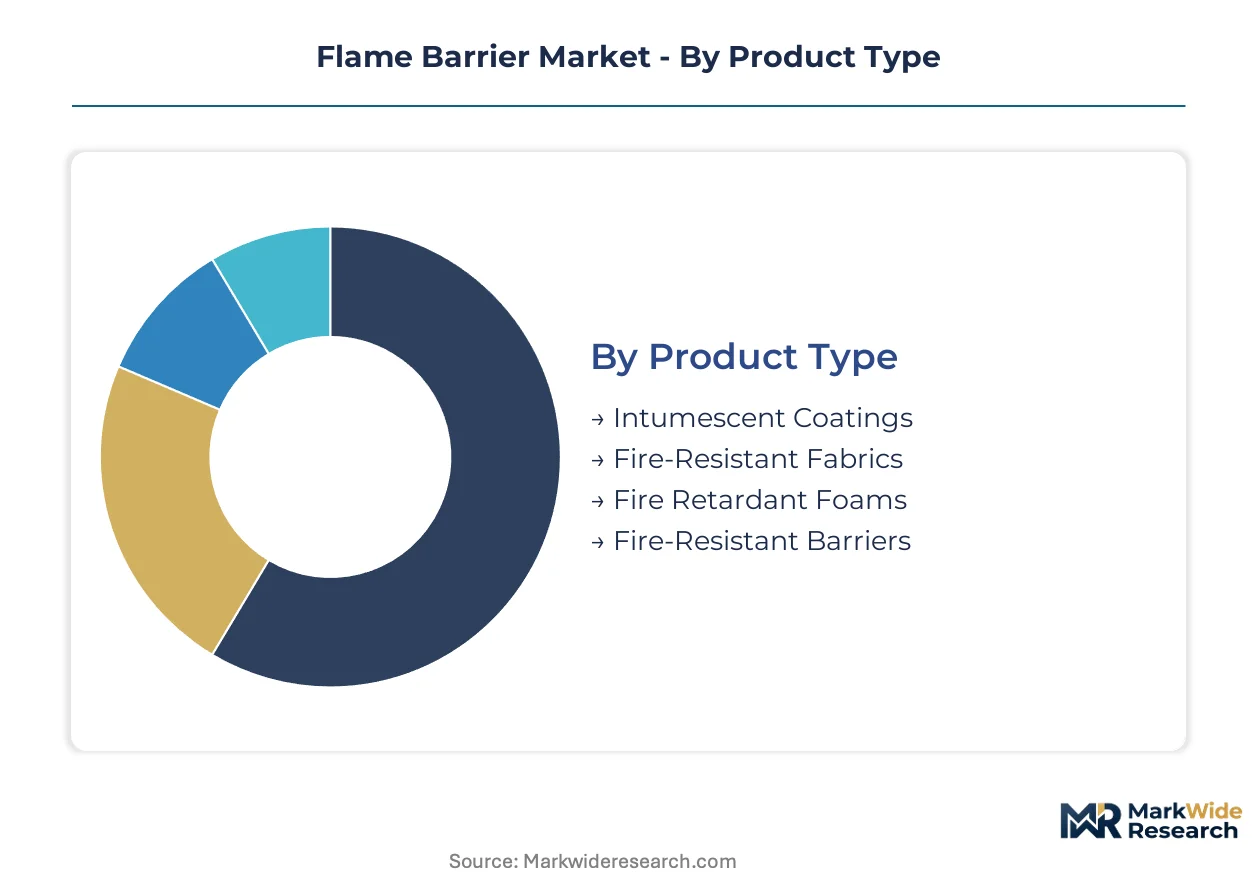
Flame barrier procurement patterns diverge sharply across product categories, with specification authority concentrating in engineering consultancies for high-performance assemblies while commodity materials flow through distributor channels. Understanding these segment boundaries reveals where margin pools accumulate and where price competition erodes returns.
Product Type:
Supply concentration in intumescent coatings and mineral wool barriers has created asymmetric competitive dynamics, with captive raw material access determining cost position.
- Intumescent Coatings:Thin-film epoxy or acrylic formulations expand into insulating char layers when exposed to temperatures exceeding 300°C. Steel-frame commercial towers in Germany and the Netherlands specify these systems where aesthetic load-bearing steel must remain exposed, with EN 1363-1 certification now mandatory for public procurement.
- Fire-Resistant Fabrics:Silicone-coated fiberglass and ceramic fiber textiles resist burn-through for specified durations under FAA and EASA testing protocols. Narrow-body aircraft refurbishment programs across France and Spain are absorbing expanding production capacity as airlines accelerate cabin modernization cycles.
- Fire Retardant Foams:Polyurethane and silicone-based spray or boardstock products fill penetration voids and cavity walls. Commodity feedstock volatility compresses margins for independent producers lacking backward integration into chemical precursors.
- Fire-Resistant Barriers:Pre-cut mineral wool and cementitious board assemblies compartmentalize vertical and horizontal fire separations. German retrofit mandates for pre-1990s residential blocks are channeling volume toward modular, UL-listed penetration kits.
Intumescent coatings absorb the bulk of installed capacity in new commercial construction; fire-resistant fabrics are expanding most quickly on transportation safety upgrades.
Application:
End-use fragmentation creates divergent certification burdens, with transportation and industrial facilities demanding multi-jurisdictional testing that smaller suppliers cannot sustain.
- Commercial Buildings:High-rise office towers, healthcare facilities, and retail complexes require compartmentation rated to ASTM E119 or EN 1363-2 durations. London and Frankfurt developers now delegate specification to fire safety engineers who demand certified assemblies rather than commodity materials.
- Residential Construction:Multi-family housing and retrofit programs drive specification of pre-cut barrier systems. Federal German building energy mandates are compressing procurement cycles for fire-resistant envelope upgrades in existing stock.
- Industrial Facilities:Petrochemical, power generation, and manufacturing plants specify high-temperature barriers for equipment protection and personnel safety. Silicone-based foams command price premiums in these settings due to thermal stability requirements.
- Transportation:Aircraft, rail, and marine interiors face burn-through and smoke toxicity standards from FAA, EASA, and IMO. Certification breadth separates qualified suppliers from regional competitors locked out of international programs.
Commercial buildings retain the largest share of specification volume; transportation applications are climbing the fastest on regulatory tightening.
Material:
REACH authorization timelines for halogenated additives are forcing formulation turnover, elevating mineral wool and intumescent alternatives where chemical transparency scoring applies.
- Polyurethane:Open-cell and closed-cell foams incorporate reactive or additive flame retardants to achieve Class A surface burning ratings. Feedstock price volatility from MDI and polyol markets limits R&D reinvestment capacity among mid-tier producers.
- Silicone:Elastomeric coatings and foams maintain flexibility across temperature extremes from -50°C to 300°C. High-temperature industrial applications in German manufacturing corridors absorb premium-priced silicone barrier systems.
- Glass Fiber:Woven and non-woven textiles serve as substrate for intumescent coatings and standalone fire-resistant fabrics. EASA burn-through requirements for aircraft cabin linings are elevating specification of silicone-impregnated glass fiber composites.
- Mineral Wool:Stone wool and glass wool batts, boards, and loose-fill provide non-combustible insulation and fire-stopping. Saint-Gobain and Rockwool sustain manufacturing scale through captive access to basalt and slag feedstocks.
Mineral wool captures the dominant share of passive fire protection tonnage; silicone formulations are gaining share fastest on industrial specification.
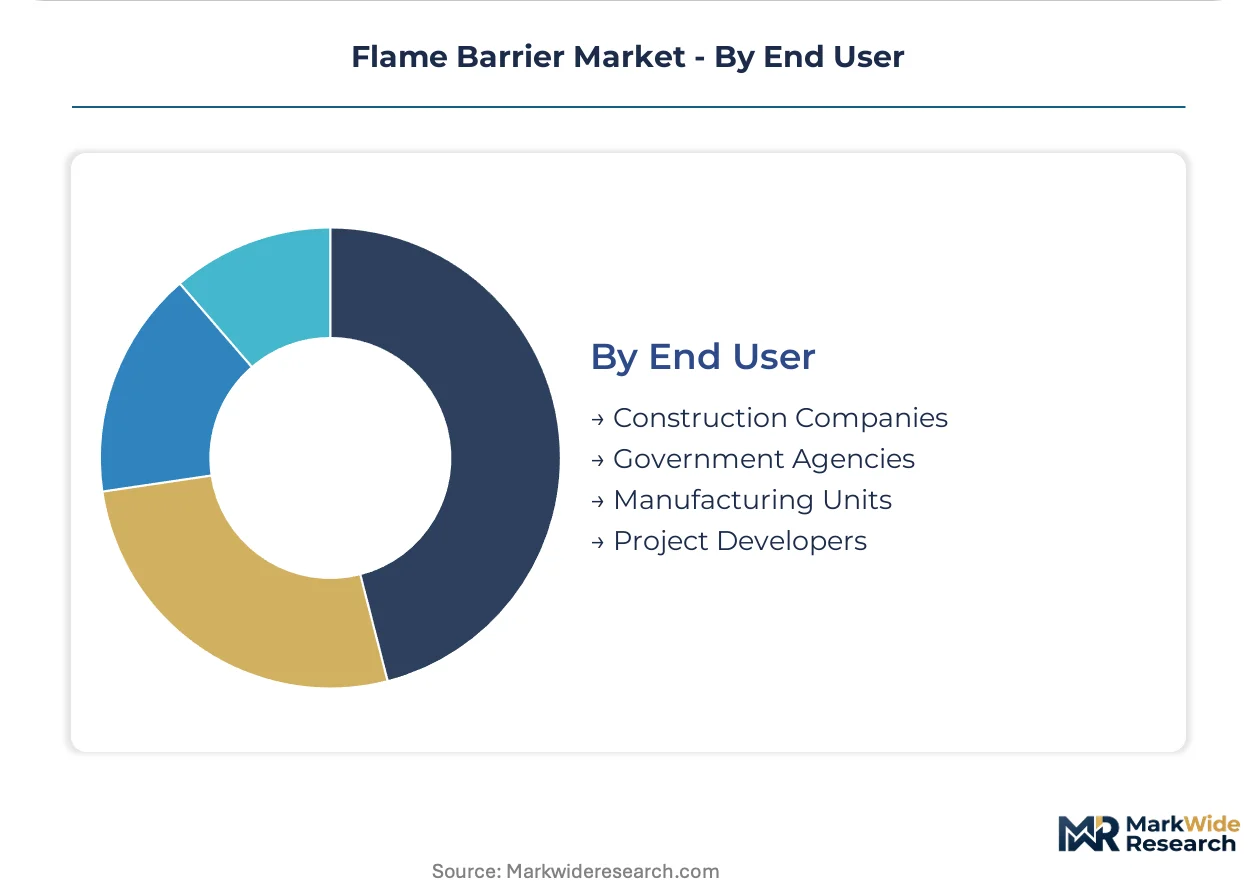
End User:
Procurement authority is elevating from general contractors toward engineering consultancies, rewiring supplier relationship economics across all end-user categories.
- Construction Companies:Commercial and residential general contractors procure barrier materials through distributor relationships or direct manufacturer agreements. Unionized metropolitan markets in Germany and the Netherlands are shifting toward pre-cut assemblies that reduce on-site labor hours.
- Government Agencies:Federal, state, and municipal entities specify fire-resistant barriers for public buildings and infrastructure. German federal procurement now mandates chemical transparency scoring that disadvantages halogenated formulations.
- Manufacturing Units:Industrial facility operators specify high-performance barriers for process equipment protection and employee safety. In-house maintenance teams favor modular penetration kits that minimize production downtime during installation.
- Project Developers:Large commercial real estate developers delegate fire safety specification to retained engineering consultancies. London and Frankfurt developers now procure performance-guaranteed subsystem contracts rather than commodity material supply.
Construction companies account for the largest volume of material procurement; project developers are shifting specification authority fastest toward engineered performance contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Germany and the United States while retrofit demand concentrates in European urban centers. Chinese producers supply export markets but face redirection toward domestic building safety programs. Distribution networks prioritize EN-certified assemblies for EU public procurement and UL-listed systems for North American commercial construction.
Germany
Federal building energy mandates accelerate fire-resistant envelope upgrades in pre-1990s residential blocks. REACH authorization timelines force formulation turnover away from halogenated flame retardants toward mineral wool alternatives. The Rhine-Ruhr industrial corridor hosts captive basalt sourcing operations that sustain manufacturing scale for stone wool barrier lines.
United States
Steel-frame commercial towers in Texas and Florida specify thin-film intumescent coatings where aesthetic exposed steel excludes mineral wool alternatives. OSHA and EPA frameworks govern applicator exposure limits and VOC emissions during installation. The Southeast construction belt faces seasonal productivity constraints from extended cure times in high-humidity coastal zones.
China
MEE enforcement tightening redirects export-oriented production capacity toward state-funded domestic retrofit programs. GB standard revisions elevate compliance thresholds for penetration assemblies in high-rise residential construction. The Yangtze River Delta concentration of chemical producers faces feedstock volatility that compresses margins for polyurethane-based barrier formulations.
United Kingdom
London developers delegate fire safety specification to retained engineering consultancies who demand certified assemblies over commodity materials. Updated Building Safety Regulations post-Grenfell impose stricter accountability on dutyholders for passive fire protection systems. The Midlands manufacturing base supplies modular penetration kits for unionized metropolitan markets seeking installation-labor arbitrage.
France
Narrow-body aircraft refurbishment programs across Toulouse and Bordeaux absorb expanding production capacity for silicone-coated fiberglass barriers. EASA burn-through requirements for cabin linings elevate specification of advanced fabric composites. The country's national pharmaceutical regulator framework influences chemical transparency scoring in adjacent construction product procurement.
Flame Barrier Market Key Industry Players
The competitive structure tilts toward diversified material science conglomerates with captive raw material access. Consolidation around adhesive chemistry, mineral wool manufacturing, and code-certification breadth creates tiered positioning. Three archetypes dominate: integrated chemical producers with backward control over polymer feedstocks, specialty coating formulators leveraging applied research portfolios, and certification-heavy assembly suppliers bundling liability transfer. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms seek to capture modular firestop kit demand.
Within the diversified conglomerate tier, 3M Company and Saint-Gobain occupy positions anchored by distinct capability foundations. 3M exemplifies specialty adhesive and coating science application, while Saint-Gobain represents mineral wool manufacturing scale through upstream control over basalt and slag feedstocks. Specified Technologies sits within the certification-intensive assembly tier, bundling UL-listed penetration configurations that transfer liability exposure from installer to manufacturer. These three anchors illustrate how competitive positioning diverges between chemical formulation depth and performance-guaranteed subsystem contracting.
| Leading Market Players |
|---|
| Metacaulk (Balco) |
| Everbuild Building Products |
| 3M Company |
| Saint-Gobain |
| BASF SE |
| Specified Technologies |
| Trafalgar Passive Fire Protection Systems |
| Johnson Controls International |
| H.B. Fuller |
| Others |
Cost & Logistics Intelligence
Basalt and slag feedstock costs flow from captive quarry operations through mineral wool manufacturing into three-tier pricing structures across premium, standard, and economy levels. Polyurethane MDI and polyol volatility compresses margins for independent foam producers lacking backward integration into chemical precursors.
Pricing Analysis
Margin tightening in fire retardant foams traces to commodity chemical price swings that limit R&D reinvestment capacity among mid-tier producers. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale. Cost-down pressure on mineral wool barriers accelerates because Saint-Gobain and Rockwool leverage captive raw material sourcing. Government agencies exhibit lowest price sensitivity due to mandated chemical transparency scoring, while residential construction contractors face acute pressure from compressed procurement cycles.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and China anchor hub-and-spoke patterns for EN-certified and UL-listed assemblies. Manufacturing draws from basalt deposits in the Rhine-Ruhr corridor, MDI/polyol chemical clusters in the Yangtze River Delta, and silicone precursor facilities in Texas. Single-source vulnerability concentrates in European halogenated flame retardant feedstocks facing REACH sunset timelines. Distribution runs through engineering consultancies in London and Frankfurt, bypassing traditional distributor channels for high-performance penetration kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive raw material sourcing and certified assembly manufacturing defines competitive positioning. Players securing basalt quarries or UL testing laboratories capture margin pools unavailable to commodity suppliers.
For Market Incumbents: Anchor manufacturing scale through quarry acquisition or long-term basalt offtake agreements in the Rhine-Ruhr corridor. Invest in concurrent UL, EN, and GB certification teams to defend against emerging Chinese producers pivoting toward domestic retrofit programs. Certification breadth serves as the primary defensive moat as engineering consultancies consolidate specification authority. For New Entrants and Emerging Players: The price-point gap between premium intumescent coatings and economy mineral wool batts creates entry space for mid-tier silicone-based foam specialists. Target German residential retrofit contractors seeking modular penetration kits with bundled performance warranties. Pursue white-label manufacturing partnerships with established UL-listed assembly fabricators to bypass multi-year certification timelines. For Investors and Strategic Acquirers: German federal procurement mandating chemical transparency scoring is the leading indicator that mineral wool and intumescent alternatives will displace halogenated formulations. Acquire specialists with captive basalt sourcing or established EASA certification for aircraft interior fabrics. Watch for MEE enforcement tightening in China as the signal for export capacity redirection toward state-funded building safety programs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Basalt Quarrying | Saint-Gobain secures captive feedstock for stone wool barrier lines in the Rhine-Ruhr corridor. |
| Concurrent Multi-Jurisdictional Certification | Specified Technologies maintains UL, EN, and GB listings that transfer liability from installer to manufacturer. |
| Modular Pre-Cut Assembly Manufacturing | Fabricators capture margin from installation-labor arbitrage in unionized German metropolitan markets. |
| Silicone-Based High-Temperature Formulation R&D | Specialists command price premiums in petrochemical and power generation equipment protection applications. |
| Engineering Consultancy Partnership Programs | Suppliers embed specification influence as London and Frankfurt developers delegate fire safety decisions. |
Research Approach
Independent corroboration across fire safety engineering consultancies, commercial general contractors, and regulatory compliance officers underwrites the qualitative findings. Primary interviews with plant managers at mineral wool manufacturing facilities, procurement leads at German residential retrofit developers, and technical R&D directors at coating formulators were cross-referenced against customs/trade data, EN standard revision documents, and SEC 10-K filings. Bottom-up volume estimates from product category shipments were reconciled with top-down construction spending allocations across the analysis window.
Comparable historical reference periods anchored the projection horizon to observed retrofit mandate acceleration in Germany and EASA certification timelines for aircraft refurbishment. The forecast framework modeled segmentation across product type, application, material chemistry, and end-user procurement authority. CAGRs were derived from elasticity-adjusted demand curves incorporating EN 1363 standard update implementation schedules and REACH authorization sunset timelines.
Inputs from regulatory filing databases and industry association technical committees were available through the study window; gaps in real-time Chinese GB standard revision drafts introduce uncertainty bands around domestic retrofit pivot assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Marine Fire Extinguishing System Market
Fire Safety & Protection
North America Fire Protection Water Storage Tanks Market
Fire Safety & Protection
Fire Suppression Agent Market
Fire Safety & Protection
Flame Detector System Market
Fire Safety & Protection
Fire Alarm Systems Market
Fire Safety & Protection
Cellulosic Fire Protection Market
Fire Safety & Protection
Powder Fire Suppression System Market
Fire Safety & Protection
Smart Smoke Detector Market
Fire Safety & Protection
UAE Fire Protection System Market
Fire Safety & Protection
Global Flame Detector Market
Fire Safety & Protection
Fire Protection Systems for Industrial Cooking Market
Fire Safety & Protection
Fire Resistant Silicone Sealant Market
Fire Safety & Protection
Smoke Detector Market
Fire Safety & Protection
Fire Alarm and Detection System Market
Fire Safety & Protection
Fire Suppression Equipment Market
Fire Safety & Protection
Fire Extinguisher Inspection Services Market