
 US Fire Alarm and Detection Market | 2026-2036
US Fire Alarm and Detection Market Size, Share, and Industry Trends Forecast 2026-2036
US Fire Alarm and Detection Market Insights
Equipment leasing and fire-safety-as-a-service financing is fragmenting the competitive landscape by lowering capital barriers for mid-size property managers and school districts. Johnson Controls International PLC leverages its building automation integration to bundle detection with HVAC and access control, anchoring long-term service contracts. Honeywell International, Inc. competes through its Gentex Corporation subsidiary's specialization in audible-visual notification appliances, while Hochiki America Corporation differentiates on photoelectric sensor precision for high-ceiling industrial environments.
Fire alarm and detection systems comprise networked sensors, control panels, and notification appliances engineered to sense smoke, heat, or combustion gases and initiate evacuation protocols within seconds of activation. Photoelectric technology dominates new commercial installations due to superior smoldering-fire detection and reduced nuisance alarms compared to ionization counterparts. Addressable systems command premium positioning by pinpointing exact device locations to first responders, while wireless segments gain traction in historic building retrofits where conduit installation proves cost-prohibitive. The educational end-user category drives replacement demand as K-12 districts modernize legacy bell systems toward integrated mass notification architectures.
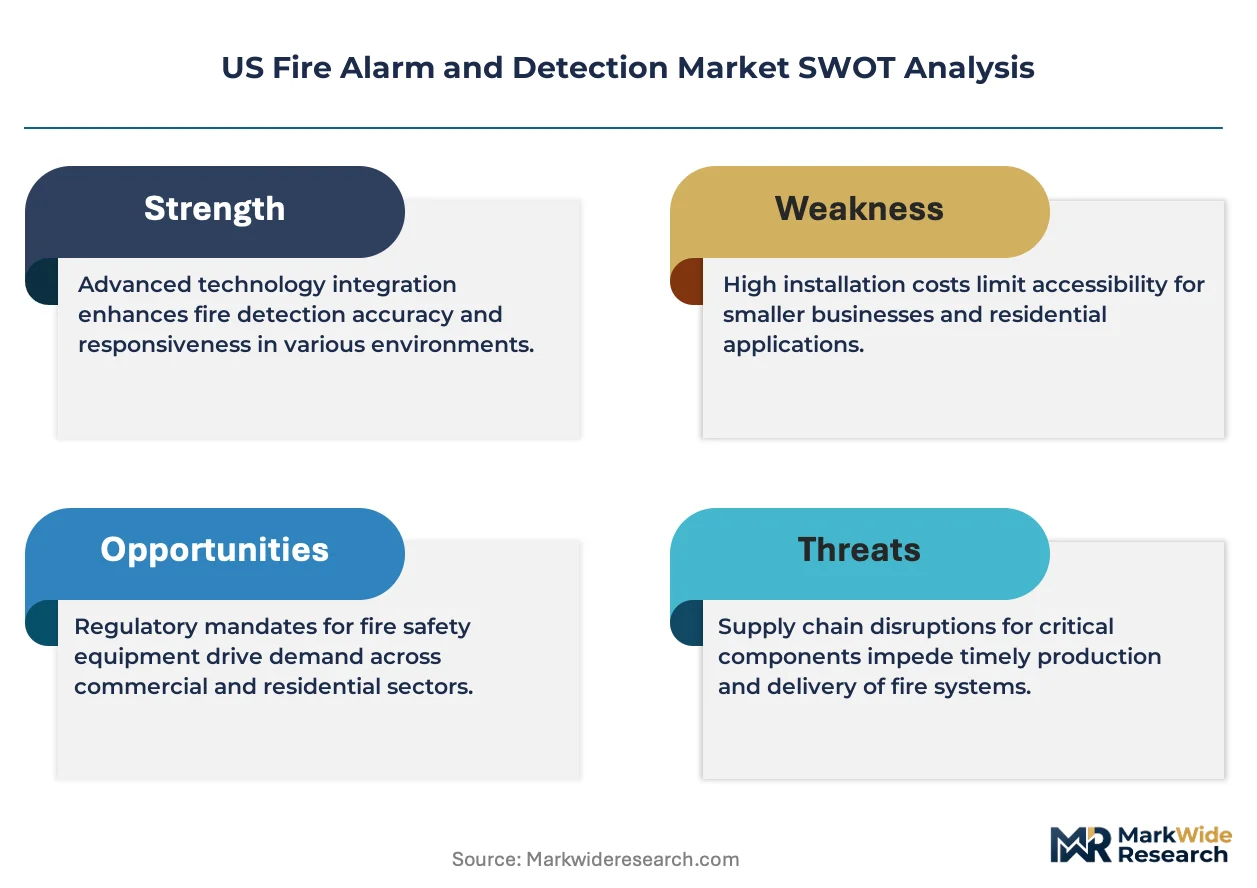
National Fire Protection Association standards, particularly NFPA 72, mandate inspection frequencies and device replacement timelines that institutionalize recurring revenue streams for installed-base service providers. Underwriters Laboratories certification requirements and local Authority Having Jurisdiction enforcement create tiered market access where non-listed products face automatic disqualification from municipal bid processes. Stakeholders must weigh the capital intensity of smart system migration against the operational savings from remote diagnostics and predictive maintenance capabilities.
Market Dynamics
NFPA 72 code enforcement and mass notification integration mandates are compressing replacement cycles across institutional portfolios, pulling forward capital deployment that would otherwise phase across decades. This regulatory acceleration is restructuring vendor-customer relationships toward long-term service anchoring.
Growth Catalysts
- Multi-family residential construction:Sun Belt permit volumes in Texas, Florida, and California are accelerating device deployment in new vertical developments where sprinkler-alarm integration is mandatory.
- NFPA 72 inspection mandates:The code's prescribed testing frequencies institutionalize recurring revenue for service providers maintaining installed bases across K-12 and healthcare facilities.
- Photoelectric sensor superiority:Smoldering-fire detection accuracy and reduced nuisance-alarm rates are displacing ionization technology in new commercial specifications.
Market Restraints
- Copper and semiconductor input costs:Control panel manufacturing faces margin pressure from commodity volatility in wiring harnesses and microprocessor sourcing.
- UL certification timeline friction:Underwriters Laboratories listing requirements create 12-18 month product qualification delays that disqualify non-listed competitors from municipal bid processes.
- Wireless protocol fragmentation:Proprietary mesh networks from major manufacturers limit interoperability and lock buyers into single-vendor ecosystems.
Strategic Opportunities
- Historic building retrofit channel:Wireless detection systems bypass conduit installation costs in protected structures across New England and Mid-Atlantic preservation districts.
- Fire-safety-as-a-service financing:Equipment leasing models lower capital barriers for mid-size property managers and independent school districts.
- Industrial high-ceiling specialization:Precision photoelectric sensors address warehouse and distribution center applications where ceiling heights exceed standard device range.
Industry Challenges
- Licensed technician scarcity:NICET-certified fire alarm technicians are concentrated in metropolitan markets, constraining installation capacity in secondary metros.
- Legacy system integration complexity:Addressable panel migration requires protocol bridging with 1990s-era hardwired zones in aging institutional infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Fire Alarm and Detection Market |
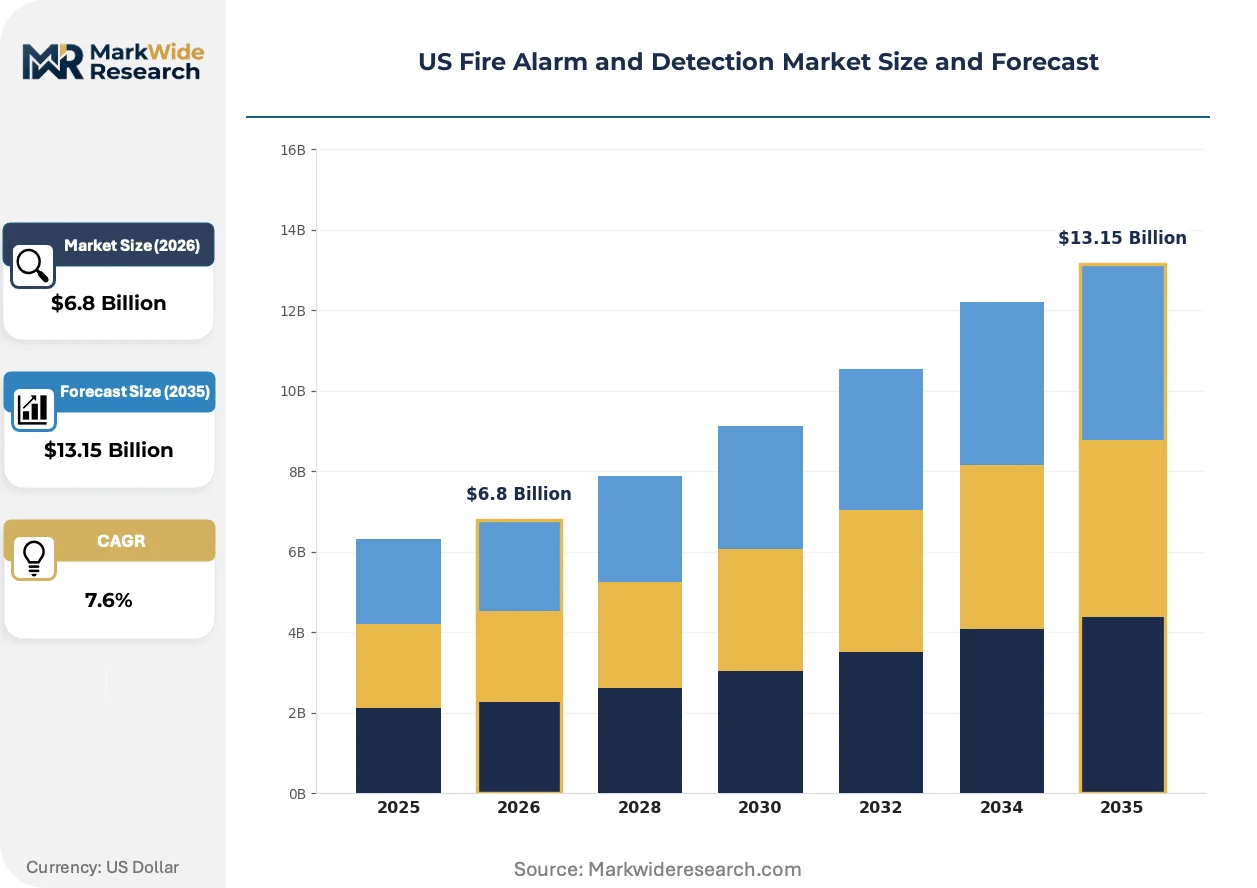
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Addressable, Wireless, Smart Technology: Photoelectric, Ionization, Dual Sensor, Gas Detection End User: Commercial, Industrial, Residential, Educational Installation Type: New, Retrofit, Integrated, Standalone |
| Companies Covered | Honeywell International, Inc., Johnson Controls International PLC, The Bosch Group, Siemens AG, Gentex Corporation, Hochiki America Corporation, Carrier, Fike Corporation, Napco Security Technologies, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Fire Alarm and Detection Market Trends and Innovations
Detection technology convergence with building automation platforms is collapsing traditional product boundaries. Integration depth now determines competitive positioning more than standalone device performance.
Multi-sensor fusion technology combining photoelectric, thermal, and carbon monoxide sensing in single housings is collapsing the market for discrete single-criteria devices. Large commercial property managers in Class A office portfolios are specifying these units to reduce device density and wiring complexity. The consolidation is compressing SKU proliferation and favoring suppliers with integrated manufacturing of all three sensor types.
OSHA workplace safety enforcement expansion is elevating fire system documentation requirements beyond NFPA 72 minima. Industrial facilities in manufacturing-heavy states face elevated inspection scrutiny and penalty exposure. This is accelerating investment in cloud-based testing log platforms that automate compliance documentation.
Consolidated facilities management vendors are unbundling fire alarm service from bundled mechanical contracts. Institutional buyers in higher education and healthcare are issuing standalone detection RFPs to capture specialist expertise. This disintermediation is most visible in university systems across California and Texas where centralized procurement offices are segmenting technical trades.
US Fire Alarm and Detection Market Segmentation
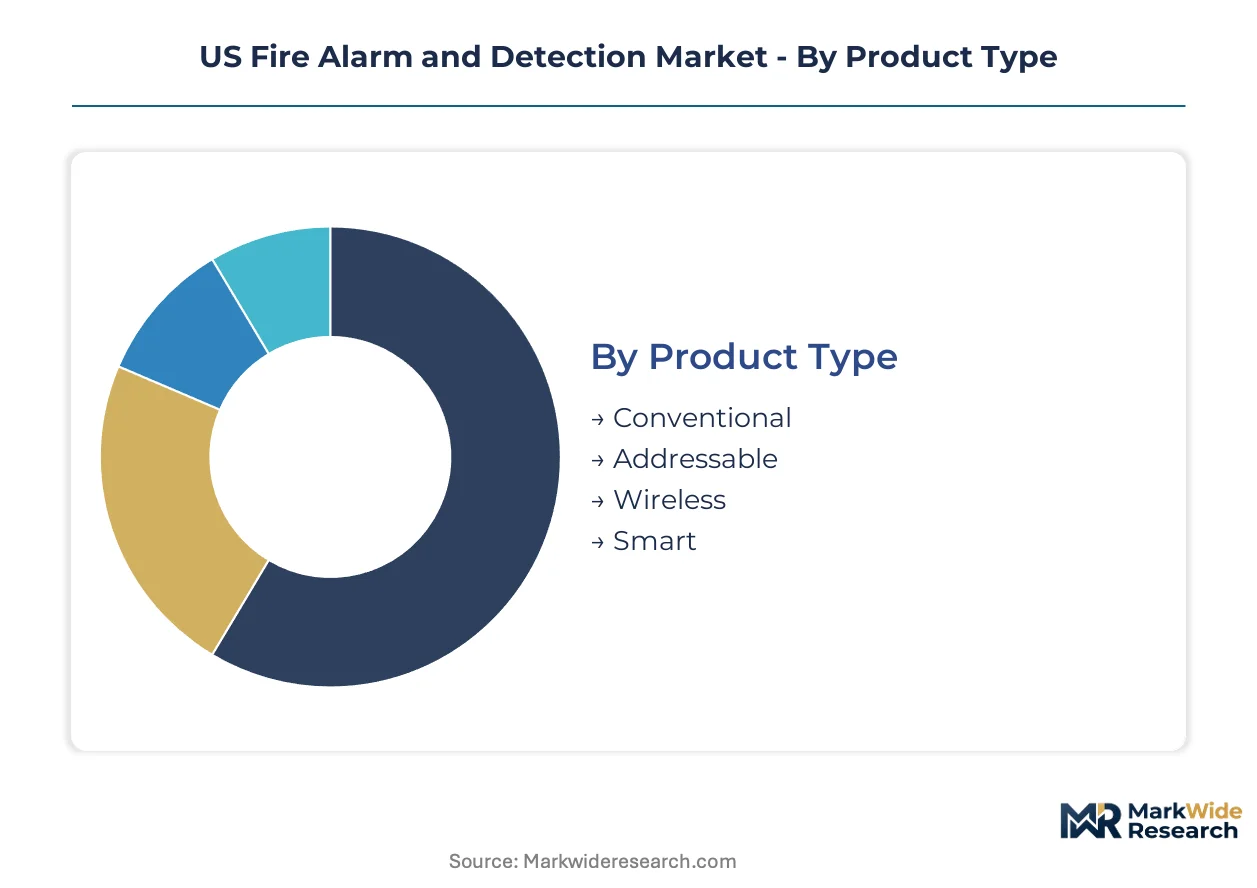
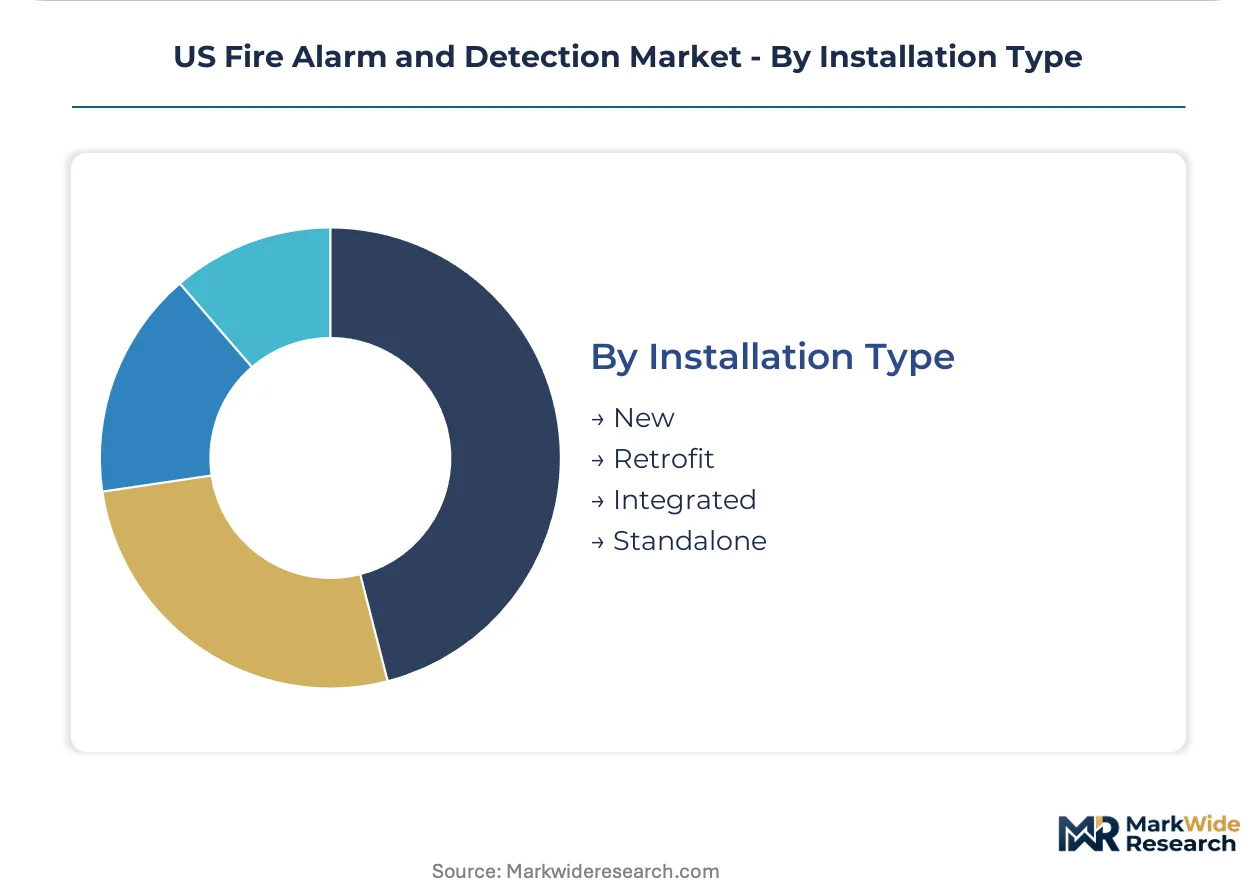
Fire alarm and detection market segmentation reveals distinct service intensity profiles across product architectures and installation contexts. Each category carries differentiated lifecycle revenue potential based on inspection mandates, replacement cycles, and integration complexity.
Product Type:
After-sales-service intensity varies sharply across product architectures, with addressable and smart systems generating recurring inspection revenue through NFPA 72-mandated testing protocols.
- Conventional:Hardwired zone-based panels divide building areas into detection circuits without individual device identification. Texas and Florida multi-family developers specify these for cost-sensitive garden-style apartments where simplified wiring reduces upfront capital.
- Addressable:Each device transmits a unique identifier to the control panel, enabling precise fault location and reducing technician dispatch costs. K-12 districts across California prioritize addressable migration to satisfy mass notification integration mandates while minimizing maintenance labor.
- Wireless:Battery-powered detectors communicate via proprietary mesh protocols, eliminating conduit installation. Historic building retrofits in New England preservation districts drive adoption where structural modifications face regulatory restriction.
- Smart:Cloud-connected systems enable remote diagnostics, predictive maintenance scheduling, and automated compliance logging. Large commercial property managers in Class A office portfolios specify these platforms to reduce NICET-certified technician dependency.
Conventional systems hold the largest share; momentum sits with smart platforms expanding most quickly through facilities management outsourcing contracts.
Technology:
Sensor technology selection directly determines nuisance alarm rates, inspection frequency, and long-term maintenance burden for institutional facility managers.
- Photoelectric:Light-scattering detection chambers sense smoldering fires with superior accuracy to ionization counterparts. Commercial specifications across Sun Belt states now default to photoelectric after NFPA guidance discouraged ionization in sleeping areas.
- Ionization:Americium-241 radioactive sources detect fast-flaming combustion through air ionization measurement. Legacy installations persist in industrial facilities where rapid flame detection outweighs smoldering-fire sensitivity requirements.
- Dual Sensor:Combined photoelectric and thermal elements reduce false alarms through cross-verification algorithms. High-occupancy healthcare facilities in California specify these units to minimize disruptive evacuations during cooking or steam events.
- Gas Detection:Electrochemical and infrared sensors identify carbon monoxide, natural gas, or refrigerant leaks before combustion initiation. Warehouse and distribution center applications in Texas industrial corridors drive specification where material handling equipment creates combustion risk.
Photoelectric technology holds the largest share; momentum sits with dual sensor configurations gaining share fastest through integrated life-safety specifications.
End User:
End-user category determines procurement authority structure, with educational and healthcare segments subject to centralized district-level purchasing and federal funding compliance.
- Commercial:Office, retail, and hospitality properties prioritize system integration with building automation platforms. Class A landlords in Florida and Texas bundle detection with HVAC and access control through long-term service contracts.
- Industrial:Manufacturing and logistics facilities face elevated OSHA documentation requirements beyond NFPA 72 minima. High-ceiling distribution centers in California Central Valley specify extended-range photoelectric sensors.
- Residential:Single-family and multi-family construction drives volume deployment through mandatory sprinkler-alarm integration. Sun Belt permit acceleration concentrates demand in Texas master-planned communities and Florida condominium towers.
- Educational:K-12 and higher education modernization replaces legacy bell systems with integrated mass notification architectures. California and Texas university systems issue standalone detection RFPs to capture specialist expertise outside bundled mechanical contracts.
Commercial end use holds the largest share; momentum sits with educational modernization showing steepest expansion trajectory through ESSER funding deployment.
Installation Type:
Installation context shapes contractor margin structure, with retrofit and integrated deployments requiring specialized labor and protocol bridging expertise.
- New:Greenfield construction enables optimized device placement and clean-sheet system architecture. Sun Belt multi-family vertical developments specify addressable systems during rough-in phase to minimize change orders.
- Retrofit:Legacy system replacement demands protocol bridging and structural accommodation. Historic districts across New England and the Mid-Atlantic drive wireless retrofit adoption where conduit installation proves cost-prohibitive.
- Integrated:Fire alarm convergence with building automation, security, and mass notification platforms collapses traditional product boundaries. Johnson Controls and Honeywell compete through bundled system integration anchoring long-term service relationships.
- Standalone:Discrete fire alarm systems without external platform connectivity persist in small commercial and residential applications. Independent property managers in secondary metros favor these configurations to avoid vendor ecosystem lock-in.
New installation holds the largest share; momentum sits with integrated systems climbing the fastest through facilities management vendor consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Property managers, school district procurement offices, and healthcare facilities directors concentrate demand across distinct state regulatory environments. Each sub-region exhibits differentiated code enforcement intensity and construction permit velocity.
Texas
Master-planned communities in Dallas-Fort Worth and Houston drive multi-family vertical construction where sprinkler-alarm integration is mandatory. The Texas State Fire Marshal enforces NFPA 72 adoption through local Authority Having Jurisdiction review. Austin and San Antonio metropolitan clusters concentrate addressable system deployment in Class A office developments.
California
K-12 districts leverage ESSER funding to modernize legacy bell systems toward mass notification architectures. CAL FIRE and the Office of the State Fire Marshal administer Title 19 code compliance with inspection frequency mandates. The Central Valley warehouse corridor specifies extended-range photoelectric sensors for high-ceiling distribution centers.
Florida
Condominium towers across Miami-Dade and Broward counties accelerate device deployment through mandatory high-rise fire safety ordinances. The Florida State Fire Marshal coordinates local enforcement of NFPA 72 and building code amendments. Tampa and Orlando metropolitan areas concentrate integrated system bundling with HVAC and access control platforms.
New England
Historic preservation districts in Boston and Providence drive wireless retrofit adoption where conduit installation faces regulatory restriction. State fire marshals in Massachusetts and Rhode Island enforce NFPA 72 with localized amendments for protected structures. Hartford and New Haven metropolitan areas concentrate battery-powered detector deployment in 19th-century institutional buildings.
Southwest
Industrial facilities in Phoenix and Las Vegas face elevated OSHA documentation requirements beyond NFPA 72 minima. Arizona and Nevada state fire marshals coordinate workplace safety enforcement with federal compliance timelines. The Reno-Sparks distribution corridor specifies precision photoelectric sensors for material handling environments.
US Fire Alarm and Detection Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement access. The vendor base organizes around building automation integrators, sensor technology specialists, and regional service contractors. Three strategic archetypes dominate: multi-platform building systems providers, precision sensor manufacturers, and fire-safety-as-a-service financiers. M&A activity concentrates on service contract portfolios, while technology licensing agreements address wireless protocol standardization.
Among building automation integrators, Johnson Controls International PLC and Honeywell International, Inc. anchor the bundled system tier. Hochiki America Corporation occupies a specialist position in photoelectric sensor precision for industrial applications. These three exemplify the competitive divergence between platform breadth and component specialization that structures procurement RFP segmentation across institutional buyers.
| Leading Market Players |
|---|
| Honeywell International, Inc. |
| Johnson Controls International PLC |
| The Bosch Group |
| Siemens AG |
| Gentex Corporation |
| Hochiki America Corporation |
| Carrier |
| Fike Corporation |
| Napco Security Technologies, Inc. |
| Others |
Pricing and Supply Chain Analysis
Semiconductor input volatility determines both tier spreads and supply chain configuration across US fire alarm manufacturing. Copper wiring harness costs and microprocessor sourcing constraints compress margins in conventional system production while amplifying premium capture in addressable and smart platforms.
Pricing Analysis
Cost-plus contracts with copper and semiconductor indexation dominate procurement between control panel manufacturers and multi-family developers. Three-tier pricing structure across premium addressable, standard conventional, and economy wireless levels separates UL-certified systems from non-listed alternatives. Pricing pressure stems from commodity volatility in wiring harnesses and microprocessor sourcing. School districts exhibit highest price sensitivity due to ESSER funding timelines, while Class A commercial property managers prioritize integration depth over unit cost.
Supply Chain Analysis
Supplier financing through extended payment terms anchors relationships between Tier 1 manufacturers and regional distributors serving secondary metros. Semiconductor fabrication concentrates in Taiwan, South Korea, and domestic US foundries, while copper refining draws from Chile and domestic smelters. Single-source vulnerability in proprietary wireless protocol chipsets creates qualification bottlenecks. Distribution runs through authorized dealer networks requiring NICET-certified technician alignment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fire alarm and detection markets approach a platform-economics inflection as building automation convergence collapses standalone product boundaries. Interoperability mandates and mass notification integration requirements favor ecosystem orchestrators over component specialists.
For Market Incumbents: Build switching-cost moats through cloud-based compliance logging platforms that automate NFPA 72 documentation. Deepen backward integration into photoelectric sensor manufacturing to offset semiconductor cost volatility. Anchor long-term service contracts by bundling detection with HVAC and access control through Johnson Controls and Honeywell integration architectures.
For New Entrants and Emerging Players: Secondary metros in Texas and Florida outside Dallas-Fort Worth and Houston cores present underpenetrated installation capacity. Wireless retrofit channels in New England preservation districts offer lowest competitive density. Target fire-safety-as-a-service financing models to bypass capital barriers constraining mid-size property managers and independent school districts.
For Investors and Strategic Acquirers: The market sits at a regulatory-acceleration phase that favors service-contract aggregators over hardware manufacturers. Acquisition targets should demonstrate installed-base density with recurring inspection revenue and NICET-certified technician networks. Monitor NFPA 72 code amendment timing as the signal for replacement cycle inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Bundling detection with HVAC and access control anchors long-term service relationships through Johnson Controls and Honeywell ecosystems. |
| Wireless Protocol Standardization | Interoperability investment reduces single-vendor lock-in and expands addressable market in historic building retrofit channels. |
| Fire-Safety-as-a-Service Financing | Equipment leasing models lower capital barriers for mid-size property managers and independent Texas school districts. |
| Photoelectric Sensor Specialization | Precision manufacturing for high-ceiling industrial applications differentiates Hochiki America in warehouse and distribution center segments. |
| Cloud-Based Compliance Logging | Automated NFPA 72 documentation platforms reduce NICET-certified technician dependency for California and Florida institutional buyers. |
Research Methodology
Operator-level perspectives from fire alarm installation contractors, NICET-certified technicians, school district facilities directors, and commercial property managers anchored the qualitative base. Primary interviews combined with secondary validation from NFPA code documentation, UL certification databases, and municipal procurement records. Bottom-up device shipment analysis triangulated against top-down construction permit data from Texas, Florida, and California building authorities.
Scenario-bracketing around regulatory enforcement intensity and copper price volatility informed projection boundaries across the analysis window. Segmentation dimensions modeled include product architecture, sensor technology, end-user category, and installation context. CAGRs derived from installed-base replacement cycle analysis and new construction permit velocity. Forecast inputs incorporated ESSER funding deployment timelines and OSHA workplace safety enforcement expansion.
Practitioners should monitor NFPA 72 amendment schedules and copper futures movements for early signals of replacement cycle acceleration or compression. Forecasts reflect assumptions regarding code enforcement continuity and semiconductor supply normalization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Cellulosic Fire Protection Market
Fire Safety & Protection
Smoke Detector Market
Fire Safety & Protection
Fire Protection Systems for Industrial Cooking Market
Fire Safety & Protection
Fire Extinguisher Market
Fire Safety & Protection
Global Portable Foam Fire Extinguisher Market
Fire Safety & Protection
Global Fire Suppression System Market
Fire Safety & Protection
Earthing Lightning Protection System Market
Fire Safety & Protection
Smoke and Carbon Monoxide Alarm Market
Fire Safety & Protection
Fire Department Software Market
Fire Safety & Protection
Smart Smoke Alarm Market
Fire Safety & Protection
Fire Protection Valves and Fittings Market
Fire Safety & Protection
Fire Fighting Foam Market
Fire Safety & Protection
Powder Fire Suppression System Market
Fire Safety & Protection
North America Fire Protection Water Storage Tanks Market
Fire Safety & Protection
Automatic Fire Ball Extinguisher Market
Fire Safety & Protection
Australia Emergency Lighting Market