
 Global IoT for Public Safety Market | 2026-2036
Global IoT for Public Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Global IoT for Public Safety Market Foresight
Mission-critical grade connectivity is bifurcating the competitive landscape into hardened first-responder networks and commercial IoT overlays. Honeywell International Inc. leverages its building automation heritage to anchor smart city safety deployments across North American metros. Motorola Solutions, Inc. dominates dedicated public-safety LTE spectrum allocations, while Cisco Systems, Inc. extends enterprise-grade networking into hybrid emergency infrastructures.
Global IoT for Public Safety comprises networked sensor arrays, edge computing nodes, and low-latency communication protocols designed to detect, analyze, and respond to threats within sub-second thresholds. These systems integrate thermal imaging, acoustic gunshot detection, and AI-powered video analytics to protect personnel and civilian populations. Cloud-based deployment leads in scalability for multi-agency coordination, though edge computing captures the fastest expansion as jurisdictions demand localized data sovereignty. Incident analytics within the solution layer commands premium pricing due to predictive policing applications, while surveillance systems remain the mature revenue base.
FCC spectrum rules for Band 14 and the EU AI Act's biometric surveillance restrictions shape procurement standards and vendor eligibility across jurisdictions. ETSI mission-critical standards and ISO 22320 emergency management frameworks further dictate interoperability requirements for cross-border deployments. Stakeholders must weigh spectrum licensing timelines against edge infrastructure capex cycles as public agencies transition from legacy narrowband to broadband-first architectures.
Market Dynamics
First-responder agencies are abandoning narrowband legacy systems for broadband-first architectures, forcing vendors to rebuild around hardened LTE networks and localized edge sovereignty requirements.
Growth Catalysts
- EU AI Act biometric restrictions:Jurisdictions across Germany, France, and Italy are procuring privacy-preserving edge nodes to maintain surveillance capabilities while complying with algorithmic transparency mandates.
- Acoustic gunshot detection:Urban police departments in Chicago, São Paulo, and Johannesburg are layering sensor grids onto existing CCTV infrastructure to compress incident response windows.
- Critical infrastructure protection:Energy transmission operators and transit authorities in Japan, South Korea, and Saudi Arabia are deploying thermal imaging arrays to preempt sabotage and equipment failure.
Market Restraints
- Semiconductor supply concentration:Edge AI chip fabrication depends on Taiwan-based foundries, exposing procurement timelines to geopolitical friction and export control volatility.
- FCC Band 14 licensing timelines:Public-safety LTE spectrum allocation delays in the United States extend deployment cycles for mission-critical voice and data services.
- Interoperability fragmentation:ETSI, ISO 22320, and national emergency frameworks lack unified certification pathways, forcing vendors to maintain multiple hardware SKUs.
Strategic Opportunities
- India smart city mandates:The Ministry of Housing and Urban Affairs is channeling PLI scheme incentives toward integrated command-and-control centers in Surat, Pune, and Ahmedabad.
- Digital twin convergence:Fire departments in Singapore and Dubai are fusing IoT sensor feeds with building information modeling to simulate evacuation scenarios in real time.
- Subscription-based fleet management:Sheriff's offices across Texas and Florida are shifting from capital-intensive radio purchases to managed service agreements for portable device refresh cycles.
Industry Challenges
- Cyber-physical systems engineering talent:Vendors struggle to recruit firmware developers with simultaneous expertise in encryption protocols and RF hardware optimization.
- Legacy P25 integration complexity:Agencies in Australia and Canada face multi-year migration paths to bridge analog voice systems with IP-based multimedia platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IoT for Public Safety Market |
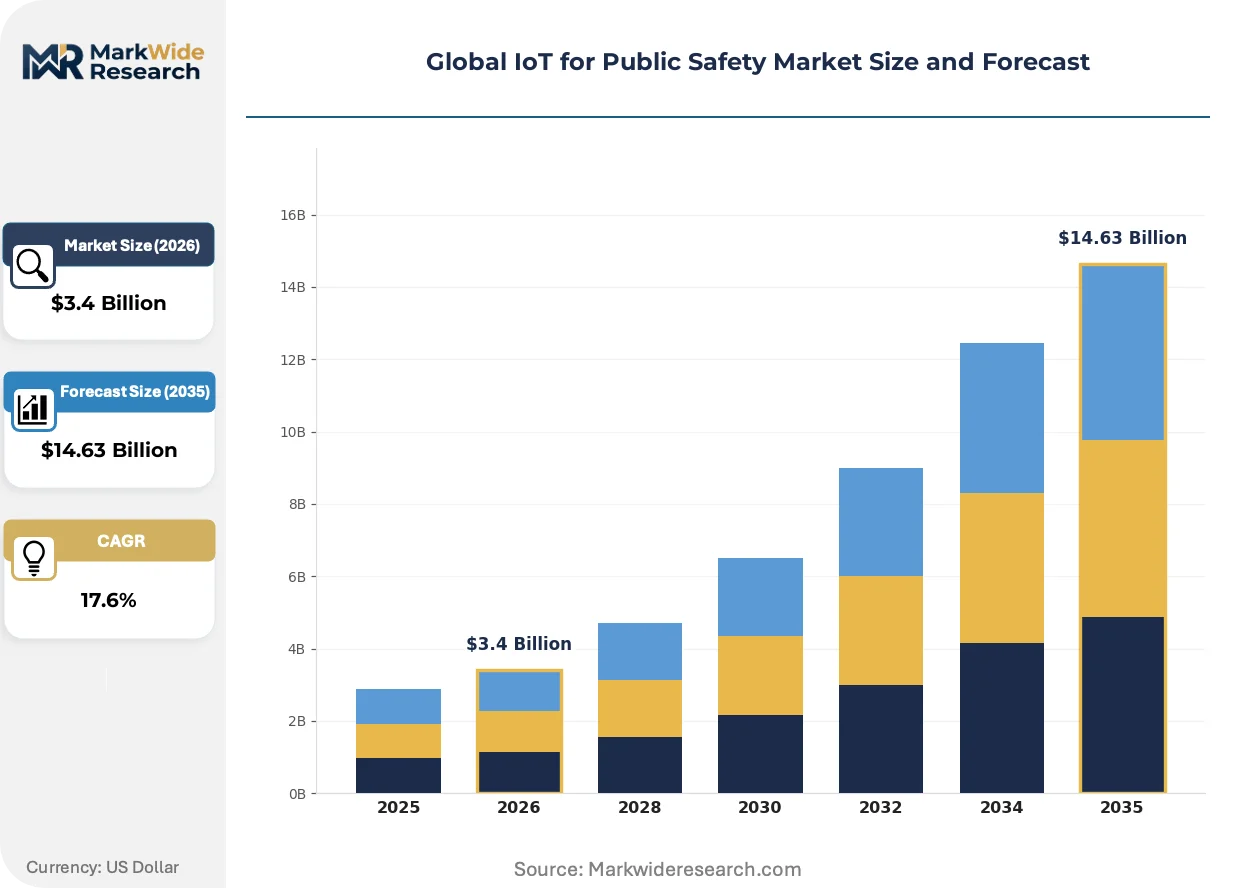
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $14.63 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution/Offering: Emergency Response, Surveillance Systems, Disaster Management, Incident Analytics Application: Critical Infrastructure Protection, Crowd Monitoring, Fire Detection, Vehicle Tracking End User: Law Enforcement, Fire Departments, Emergency Medical Services, Government Agencies |
| Companies Covered | Honeywell International Inc., Hexagon AB, Motorola Solutions, Inc., Verizon Communications Inc., AT&T Inc., Axon Enterprise, Inc., Microsoft Corporation, ShotSpotter, Inc., Cisco Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IoT for Public Safety Market Shifts & Advancements
Edge computing architectures are fragmenting procurement patterns as agencies weigh cloud scalability against data sovereignty imperatives. Vendors are responding with modular hardware platforms that straddle both deployment models.
AI-powered video analytics is bifurcating the competitive landscape between cloud-trained models and edge-inferred inference engines. Large metropolitan police forces in London and New York are piloting localized neural processing to reduce latency for facial recognition and anomaly detection. This shift is compressing margins for pure-cloud software vendors while rewarding semiconductor-integrated system builders.
The EU AI Act's prohibited-practices list is forcing biometric surveillance vendors to reengineer product roadmaps for European markets. Systems capable of real-time remote identification in public spaces face outright bans, redirecting R&D investment toward post-event forensic analysis tools. German and French procurement offices are now requiring algorithmic impact assessments as standard tender documentation.
Consolidated purchasing by multi-agency regional authorities is displacing single-department procurement in the United States. State-level emergency management offices in California and Texas are negotiating enterprise licenses that span municipal police, county sheriff, and campus security departments. This concentration is squeezing mid-tier vendors unable to meet scaled cybersecurity certification requirements.
Global IoT for Public Safety Market Segmentation
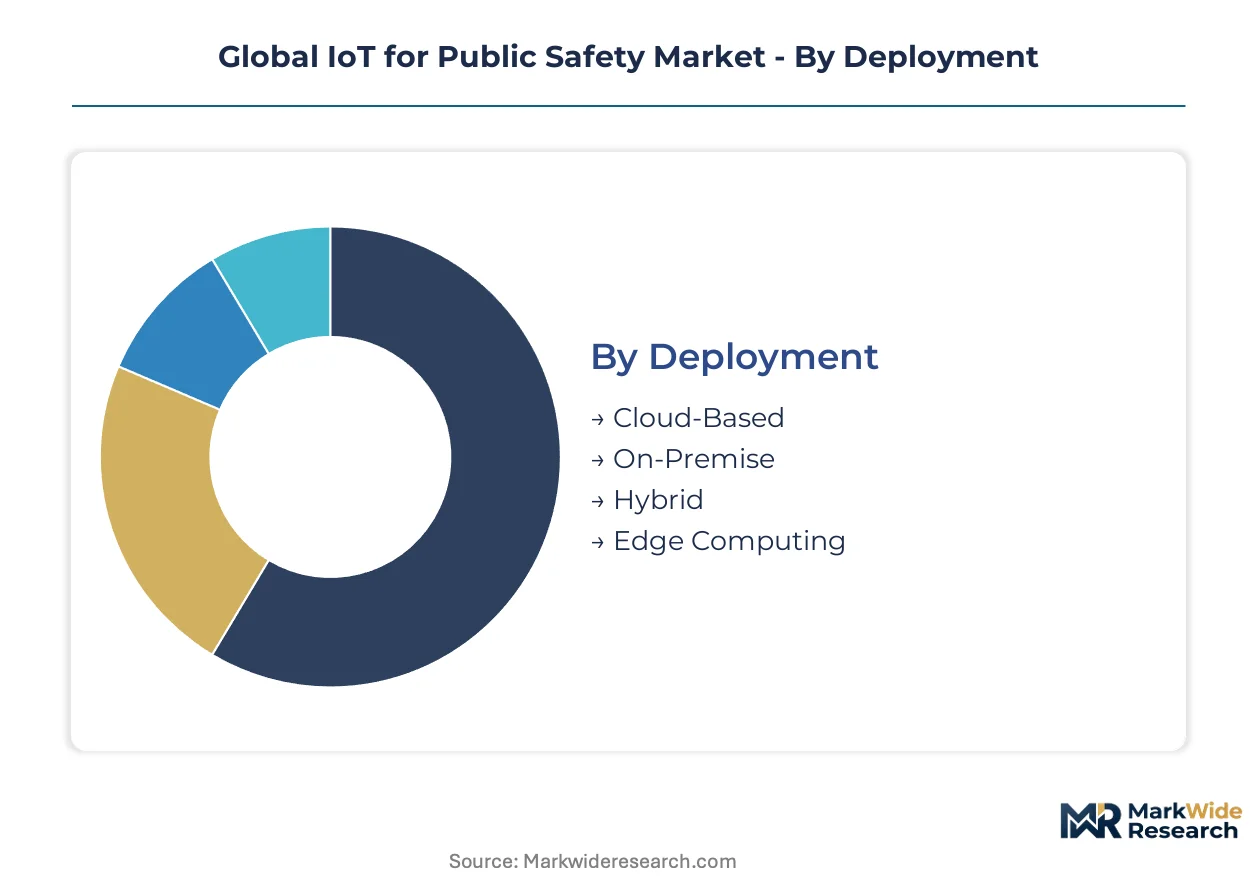
IoT for public safety procurement patterns diverge sharply across deployment architectures and end-user mandates. Understanding these segment boundaries clarifies why edge infrastructure vendors and cloud-native platforms rarely compete head-to-head.
Deployment:
Cloud-based platforms dominate North American and Western European procurement, while edge computing nodes concentrate in jurisdictions with strict data sovereignty laws.
- Cloud-Based:Centralized architectures enable multi-agency coordination across municipal, county, and state boundaries. Police departments in California and Texas favor these platforms for predictive analytics requiring massive compute pools.
- Edge Computing:Localized processing nodes keep biometric and location data within jurisdictional borders. German and French agencies mandate these deployments under GDPR and EU AI Act biometric restrictions.
- On-Premise:Air-gapped installations serve defense-adjacent facilities and nuclear sites in Japan and Saudi Arabia.
- Hybrid:Split architectures route routine analytics to cloud while reserving sensitive inference for local nodes.
Cloud-based deployment commands the established base. The steepest expansion runs through edge computing.
Solution/Offering:
Solution tiers separate mature hardware revenue from software analytics premiums, with incident analytics commanding the widest margin spreads.
- Incident Analytics:AI-powered pattern recognition platforms compress emergency response windows through predictive routing and resource pre-positioning. Metropolitan police forces in London and New York pay substantial premiums for real-time anomaly detection capabilities.
- Surveillance Systems:Integrated sensor arrays combining thermal imaging, acoustic detection, and video feeds form the revenue foundation. Legacy deployments across Chicago, São Paulo, and Johannesburg continue refreshing camera infrastructure.
- Emergency Response:Coordinated dispatch platforms integrate 911 call handling with field unit tracking.
- Disaster Management:Flood, earthquake, and wildfire early-warning networks deploy across Japan, South Korea, and Australia's state emergency services.
Surveillance systems anchor current procurement volumes. Incident analytics is climbing the fastest as agencies prioritize predictive capabilities over reactive monitoring.
Application:
Application demand clusters around perimeter defense and population-scale monitoring, with critical infrastructure protection absorbing the highest per-site investment.
- Critical Infrastructure Protection:Thermal and vibration sensor networks guard energy transmission, water treatment, and transit systems. Japanese and Saudi operators deploy these arrays against sabotage and equipment failure risks.
- Crowd Monitoring:Dense sensor grids track population flow at stadiums, transit hubs, and protest zones. Singapore and Dubai authorities fuse these feeds with digital twin simulations for evacuation planning.
- Fire Detection:Multi-spectral sensors identify ignition signatures before visible flame emergence.
- Vehicle Tracking:GPS and cellular triangulation monitor first-responder fleet location and status.
Critical infrastructure protection represents the deepest per-deployment spending. Crowd monitoring is gaining share fastest as urban density and event security budgets rise.
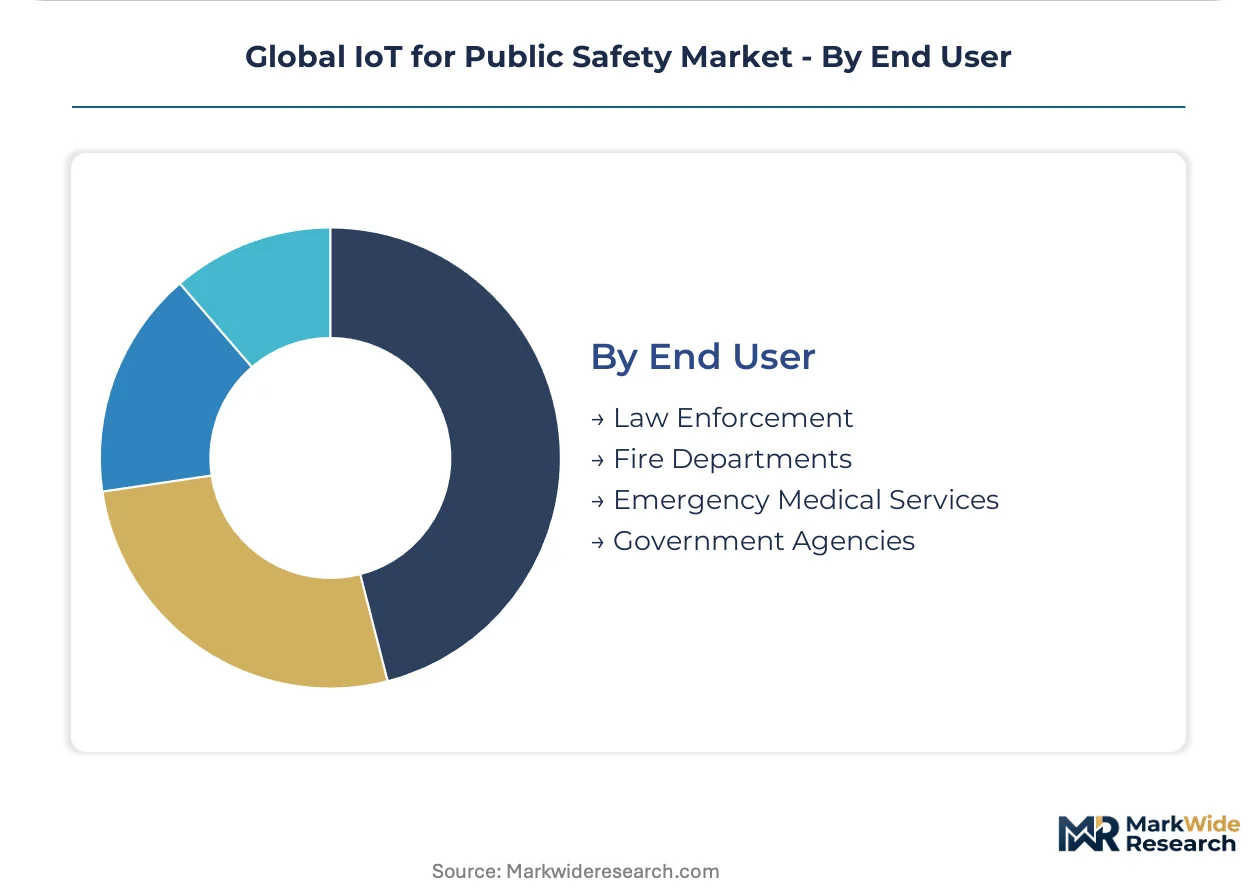
End User:
End-user procurement authority is consolidating from individual departments toward regional multi-agency bodies, reshaping vendor sales cycles.
- Law Enforcement:Police and sheriff departments drive sensor density for real-time crime centers. Chicago, São Paulo, and Johannesburg are layering gunshot detection onto existing CCTV infrastructure.
- Government Agencies:State-level emergency management offices in California and Texas negotiate enterprise licenses spanning police, fire, and campus security. This concentration squeezes vendors unable to meet scaled cybersecurity certifications.
- Fire Departments:Sensor networks for structural collapse prediction and hazardous material detection.
- Emergency Medical Services:Fleet telemetry and patient monitoring integration with hospital systems.
Law enforcement retains the largest installed base. Government agencies are expanding most quickly as consolidated purchasing displaces single-department procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public safety agencies in Germany and Japan demonstrate the lowest price elasticity, absorbing premium edge infrastructure costs to satisfy biometric surveillance restrictions under GDPR and the EU AI Act. Buyers in India and Brazil remain highly price-sensitive, favoring cloud-scalable platforms over capital-intensive localized deployments.
United States
FCC Band 14 spectrum allocations and FirstNet deployment timelines drive hardened LTE procurement across municipal police departments. The IRA's broadband infrastructure provisions channel federal funding toward rural emergency response modernization. Chicago, Los Angeles, and Houston anchor sensor density for real-time crime centers layering gunshot detection onto legacy CCTV grids.
Germany
Bundesdatenschutzgesetz amendments and EU AI Act biometric prohibitions mandate privacy-preserving edge architectures for urban surveillance. BSI cybersecurity certification requirements filter vendor eligibility for critical infrastructure protection contracts. The Rhine-Ruhr metropolitan cluster concentrates command-and-control center deployments integrating thermal imaging with predictive policing platforms.
Japan
METI's Society 5.0 initiative accelerates disaster-resilient IoT networks for earthquake and tsunami early warning. The country's national pharmaceutical regulator collaborates with emergency services on hazardous material detection sensor standards. Tokyo and Osaka prefectures deploy multi-agency digital twin simulations fusing building information modeling with evacuation telemetry.
India
Ministry of Housing and Urban Affairs PLI scheme incentives reduce procurement costs for integrated smart city command centers. TRAI's data localization guidelines push agencies toward hybrid cloud-edge architectures. Surat, Pune, and Ahmedabad represent the fastest-scaling deployments, consolidating municipal police, fire, and traffic management under unified sensor networks.
Saudi Arabia
SFDA and MOHAP coordination mandates biometric-integrated emergency medical response systems for pilgrimage-scale crowd events. The country's national pharmaceutical regulator enforces data sovereignty requirements for critical infrastructure sensor feeds. NEOM and Riyadh anchor thermal imaging arrays guarding energy transmission and water treatment facilities against sabotage risks.
Global IoT for Public Safety Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the public safety IoT ecosystem. The market structures around three tiers: diversified industrial conglomerates with building automation heritage, dedicated public-safety communications specialists, and cloud-native platform providers. Strategic moves concentrate on spectrum licensing partnerships and edge AI semiconductor integration rather than pure software expansion.
Within the diversified industrial tier, Honeywell International Inc. and Motorola Solutions, Inc. exemplify contrasting approaches to mission-critical infrastructure. Honeywell leverages North American building automation relationships to anchor smart city safety deployments, while Motorola Solutions dominates dedicated public-safety LTE spectrum allocations. Cisco Systems, Inc. occupies a bridging position, extending enterprise-grade networking into hybrid emergency architectures that straddle cloud and edge deployment models.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Hexagon AB |
| Motorola Solutions, Inc. |
| Verizon Communications Inc. |
| AT&T Inc. |
| Axon Enterprise, Inc. |
| Microsoft Corporation |
| ShotSpotter, Inc. |
| Cisco Systems, Inc. |
| Others |
Supply & Pricing Matrix
Ninety-day edge AI chip lead times compress vendor margins while amplifying pricing power for Taiwan-based foundries serving German and Japanese agencies with strict data sovereignty mandates. This inventory tension forces procurement officers to choose between premium localized nodes and deferred cloud deployments.
Pricing Analysis
Managed service contracts and subscription renewals drive lifetime value as sheriff's offices across Texas and Florida abandon capital-intensive radio purchases. Three-tier pricing structure across premium, standard, and economy levels separates mission-critical hardened LTE deployments from commercial IoT overlays. Price differentiation rests on FCC Band 14 spectrum certification and BSI cybersecurity tiers. Cost compression in mid-tier surveillance hardware intensifies because semiconductor supply concentration limits volume discounts. Indian smart city buyers exhibit highest price sensitivity; Japanese critical infrastructure operators absorb premium thermal imaging arrays with minimal elasticity.
Supply Chain Analysis
Taiwan and South Korea anchor edge AI chip fabrication for acoustic gunshot detection and thermal imaging arrays. South Korean memory suppliers and Japanese sensor component manufacturers feed into modular hardware platforms. Single-source vulnerability concentrates in Taiwan-based foundry capacity for neural processing units. Distribution runs through systems integrators and regional command-and-control center contractors rather than direct agency sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Public safety IoT investment cycles track infrastructure modernization waves, with current procurement acceleration reflecting post-pandemic emergency response digitization mandates across OECD jurisdictions.
For Market Incumbents: Fortify spectrum licensing partnerships and edge AI semiconductor integration to defend against cloud-native platform encroachment. Deepen backward integration into RF hardware optimization to offset firmware developer scarcity. Prioritize BSI and FCC certification maintenance as procurement consolidates toward multi-agency regional authorities with scaled cybersecurity requirements.
For New Entrants and Emerging Players: EU AI Act algorithmic impact assessment fast-tracks open procurement pathways in German and French urban surveillance tenders. Target India's PLI scheme subsidized command-and-control centers in Surat, Pune, and Ahmedabad as the most penetrable geography. Lead with privacy-preserving edge node architectures that satisfy GDPR biometric restrictions without legacy P25 integration burden.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates divesting non-core public safety communications units. Long-term viability hinges on mission-critical LTE spectrum access and edge AI chip supply security rather than pure software scale. Watch FCC Band 14 licensing timeline acceleration as the inflection signal for hardened network deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Chip Supply Agreement | Taiwan foundry partnerships secure neural processing capacity for German biometric-restricted deployments. |
| Spectrum Licensing Partnership | FCC Band 14 access enables Motorola Solutions and Verizon to dominate first-responder LTE procurement. |
| Privacy-Preserving Architecture Certification | EU AI Act compliance opens French and Italian municipal tenders to non-incumbent vendors. |
| Multi-Agency Enterprise License | California and Texas state-level consolidation rewards vendors with scaled cybersecurity certifications. |
| Digital Twin Platform Integration | Singapore and Dubai fire department simulations fuse IoT feeds with building information modeling. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with emergency management directors, public safety CTOs, spectrum policy officers, and systems integration specialists; and secondary validation against FCC licensing databases, ETSI mission-critical standards filings, EU AI Act implementation guidance, and municipal procurement records. Bottom-up sensor deployment estimates triangulated against top-down infrastructure budget allocations.
Across the projection horizon, the analytical framework modeled deployment architecture, solution tier, application intensity, and end-user consolidation patterns. CAGRs derived from infrastructure replacement cycles and regulatory compliance deadlines. Forecast inputs incorporated FirstNet deployment timelines and EU AI Act biometric restriction phase-in schedules.
Decision-makers should treat outputs as directional under assumptions of stable Taiwan semiconductor supply and FCC Band 14 licensing continuity; material deviation would warrant model refresh. Specific risk factors include export control volatility affecting edge AI chip availability and interoperability fragmentation across ETSI and ISO certification pathways. Recalibration cycles align with material shifts in spectrum allocation policy and data sovereignty regulation enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
Voice Evacuation Systems Market
Public Safety
Public Safety Market
Public Safety
North America Road Safety Market
Public Safety
Counter Terror and Public Safety Technology Market
Public Safety
Latin America Public Safety Market
Public Safety
Europe Public Safety Market
Public Safety
Safe City Market
Public Safety
Global Public Safety and Security Market
Public Safety
Global Public Safety in Building Wireless Das System Market
Public Safety
Europe Wireless Broadband in Public Safety Market
Public Safety
LAMEA Wireless Broadband in Public Safety Market
Public Safety
Public Safety Drones Market
Public Safety
Middle East Crime and Combat Market
Public Safety
Public Safety in-Building Wireless Distributed Antenna System (DAS) Market
Public Safety
US Mass Notification Systems Market
Public Safety
Outdoor Public Safety Market