
 Fire Rated Cables Market | 2026-2036
Fire Rated Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Rated Cables Market Analysis
Cross-linked polyethylene is recalibrating insulation economics across fire rated cable portfolios by displacing older PVC formulations at comparable cost structures. Prysmian Group leverages integrated compound manufacturing to secure feedstock consistency across European plants. Nexans S.A. anchors its position through deep specialization in medium-voltage fire resistant architectures for tunnel and metro networks. LS Cable & System Limited dominates supply relationships with Korean EPC contractors executing Middle Eastern infrastructure contracts.
Fire rated cables are electrical conductors engineered to maintain circuit integrity for specified durations under flame exposure, typically incorporating mica tape wraps, silicone rubber insulation, or mineral compounds to achieve temperature ratings between 750°C and 1,050°C. Their primary purpose is to sustain emergency power, fire alarm, and evacuation system functionality during combustion events in occupied structures. Low voltage configurations command the largest volume share across building applications, while specialty cables incorporating fiber optic elements represent the fastest-expanding margin pool for manufacturers targeting smart building integration. Material segmentation shows copper conductors sustaining premium positioning due to thermal conductivity advantages, though aluminum alternatives are gaining specification in cost-sensitive infrastructure tenders.
NFPA 70, IEC 60332, and BS 5839 collectively establish the compliance baseline that determines product marketability across North American, European, and Commonwealth markets respectively. Regulatory divergence between UL 1666 vertical shaft testing and European flame spread protocols forces manufacturers to maintain dual certification inventories, elevating working capital requirements. Stakeholders must monitor evolving EU CPR classification thresholds and emerging Middle Eastern national building codes to anticipate specification migration before tender cycles lock in cable selections.
Market Dynamics
Cross-linked polyethylene insulation is recalibrating procurement economics by matching PVC cost structures while exceeding fire performance thresholds, forcing compound suppliers and cable fabricators to retool production lines simultaneously.
Growth Catalysts
- NFPA 70 enforcement:Stricter National Electrical Code adoption across US commercial high-rises is mandating enhanced circuit integrity specifications in new construction and major renovation projects.
- Mineral-insulated cable technology:MICC architectures are penetrating data center emergency power applications where temperature resilience above 1,000°C is non-negotiable.
- Urban infrastructure buildout:China's metro expansion and tunnel electrification programs are generating concentrated demand for medium-voltage fire resistant cable systems.
Market Restraints
- Copper price volatility:LME copper fluctuations compress margin predictability for manufacturers locked into fixed-price infrastructure tenders spanning multi-year execution windows.
- Dual certification inventory burden:Divergence between UL 1666 vertical shaft testing and IEC 60332 flame spread protocols forces manufacturers to maintain parallel stockpiles for transatlantic projects.
- Aluminum conductor substitution ceiling:Thermal conductivity limitations prevent aluminum from displacing copper in high-density emergency power applications despite 40% raw material cost advantages.
Strategic Opportunities
- Smart building integration:Fiber optic hybrid fire rated cables are converging with building automation networks to enable real-time temperature monitoring and predictive maintenance in intelligent structures.
- Middle Eastern national building codes:Emerging unified fire safety standards across Gulf Cooperation Council jurisdictions are creating specification harmonization opportunities for certified suppliers.
- Tunnel and metro specialization:Deep expertise in medium-voltage fire resistant architectures for underground transit networks commands premium positioning in European and Asian procurement cycles.
Industry Challenges
- Compound formulation expertise scarcity:Cross-linked polyethylene processing requires specialized polymer engineering talent that outpaces current vocational training pipeline output.
- EU CPR classification migration:Extended retesting timelines for enhanced fire performance ratings are delaying product launches and locking out speculative inventory investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Rated Cables Market |
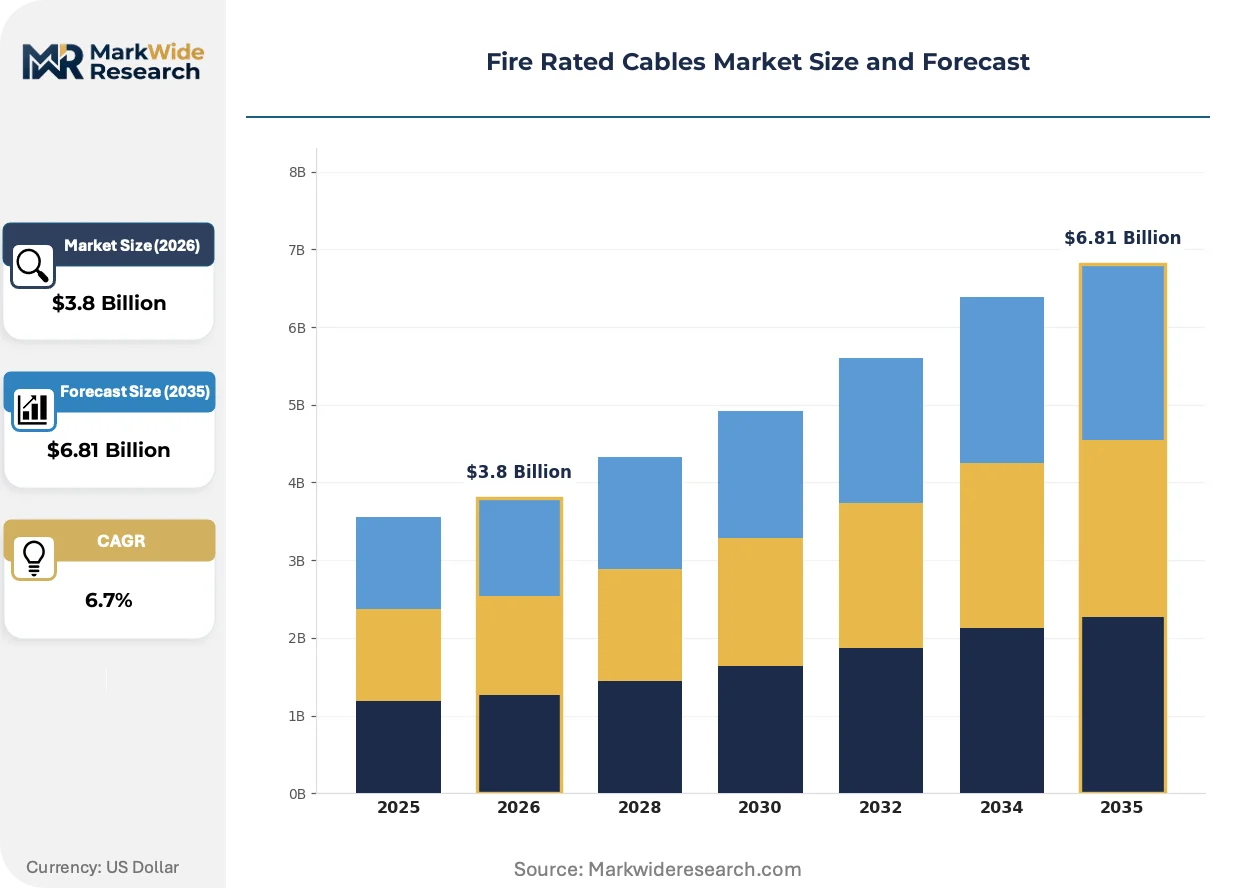
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Low Voltage, Medium Voltage, High Voltage, Specialty Material: Copper, Aluminum, Fiber Optic, Thermoplastic Application: Building, Industrial, Infrastructure, Transportation Standards: IEC 60332, UL 1666, BS 5839, NFPA 70 |
| Companies Covered | Prysmian Group, Nexans S.A., NKT Group, LEONI AG, LS Cable & System Limited, Elsewedy Electric Company, Tratos Limited, Sumitomo Electric Industries, Southwire Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Rated Cables Market Emerging Trajectories
Material science breakthroughs and regulatory classification upgrades are compressing product lifecycles while opening margin pools in specialized applications previously served by commodity alternatives.
Silicone rubber insulation is converging with mica tape wrapping systems to deliver 950°C temperature ratings at weight profiles 30% below mineral-insulated alternatives. Data center operators in Northern Europe are specifying these hybrid constructions for emergency generator feeder circuits. The structural consequence is compression in traditional heavy-sheath MICC market share within price-sensitive segments.
EU Construction Products Regulation classification thresholds are elevating from basic flame spread containment to comprehensive smoke opacity and toxicity metrics. German and French specification bodies are now mandating ca and s1 ratings for high-occupancy structures. Low-smoke zero-halogen compound suppliers are capturing specification share from legacy PVC formulators in hospital and airport terminal projects.
Engineering-procurement-construction contractors are consolidating cable procurement into multi-year framework agreements with compound-to-cable integrated manufacturers. Korean EPC specialists executing Middle Eastern infrastructure contracts are bypassing traditional distributor networks entirely. This channel compression is most visible in UAE and Saudi Arabia metro electrification tenders where direct manufacturer relationships lock out speculative traders.
Fire Rated Cables Market Segmentation
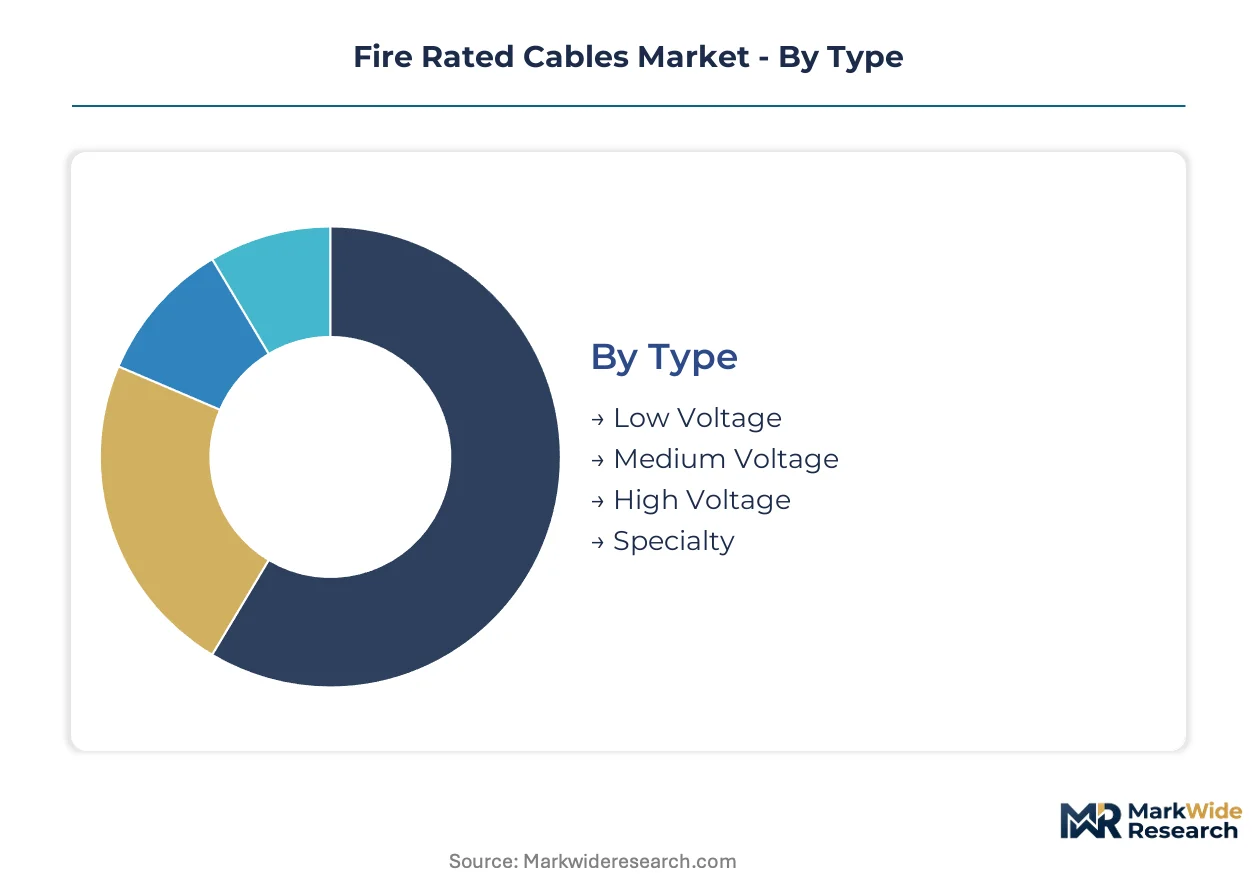
Fire rated cable procurement decisions cascade through multiple technical and commercial dimensions simultaneously. Specification engineers, procurement officers, and regulatory consultants each weight different segmentation axes when validating cable selections for tender submissions.
Type:
Insulation voltage ratings determine fire performance thresholds and installation economics across project portfolios.
- Low Voltage:These cables operate below 1kV and incorporate mica tape wraps with cross-linked polyethylene or silicone rubber insulation. Building automation and emergency lighting circuits in Germany's high-rise commercial towers generate concentrated procurement volume under EU CPR ca and s1 mandates.
- Medium Voltage:Rated between 1kV and 35kV, these architectures deploy mineral-insulated or advanced polymer compounds for tunnel electrification and metro feeder systems. China's urban rail expansion programs in Chengdu, Xi'an, and Zhengzhou are absorbing significant medium-voltage fire resistant cable capacity.
- High Voltage:Above 35kV ratings require specialized mineral compounds and heavy-gauge copper conductors for substation interconnects and grid resilience applications.
- Specialty:Hybrid constructions incorporating fiber optic elements for smart building integration and predictive temperature monitoring.
Low voltage leads on scale; specialty configurations lead on momentum.
Material:
Conductor and insulation material selection directly determines thermal performance ceilings and raw material cost exposure.
- Copper:Superior thermal conductivity above 750°C sustains circuit integrity in dense emergency power applications. LME price volatility compresses margin predictability for manufacturers locked into multi-year infrastructure tenders.
- Aluminum:Raw material cost advantages near 40% drive specification in cost-sensitive infrastructure tenders, though thermal conductivity limitations prevent full copper displacement.
- Fiber Optic:Hybrid fire rated cables converging with building automation networks enable real-time monitoring in intelligent structures.
- Thermoplastic:Low-smoke zero-halogen formulations are displacing legacy PVC in hospital and airport terminal projects under elevated EU smoke opacity requirements.
Copper dominates premium specification; fiber optic hybrid constructions are climbing the fastest.
Application:
End-use environment dictates fire duration requirements, installation methods, and certification complexity.
- Building:Commercial high-rises, hospitals, and airport terminals require 950°C ratings with low-smoke zero-halogen insulation. NFPA 70 enforcement across US commercial construction is mandating enhanced circuit integrity specifications.
- Infrastructure:Tunnel and metro networks demand medium-voltage fire resistant architectures with 1,050°C temperature resilience and mechanical crush resistance.
- Industrial:Petrochemical facilities and data centers specify mineral-insulated cable technology where temperature resilience above 1,000°C is non-negotiable.
- Transportation:Rail electrification and airport ground support systems require specialized flame spread containment under IEC 60332 protocols.
Building applications anchor volume concentration; infrastructure projects command the steepest expansion trajectory.
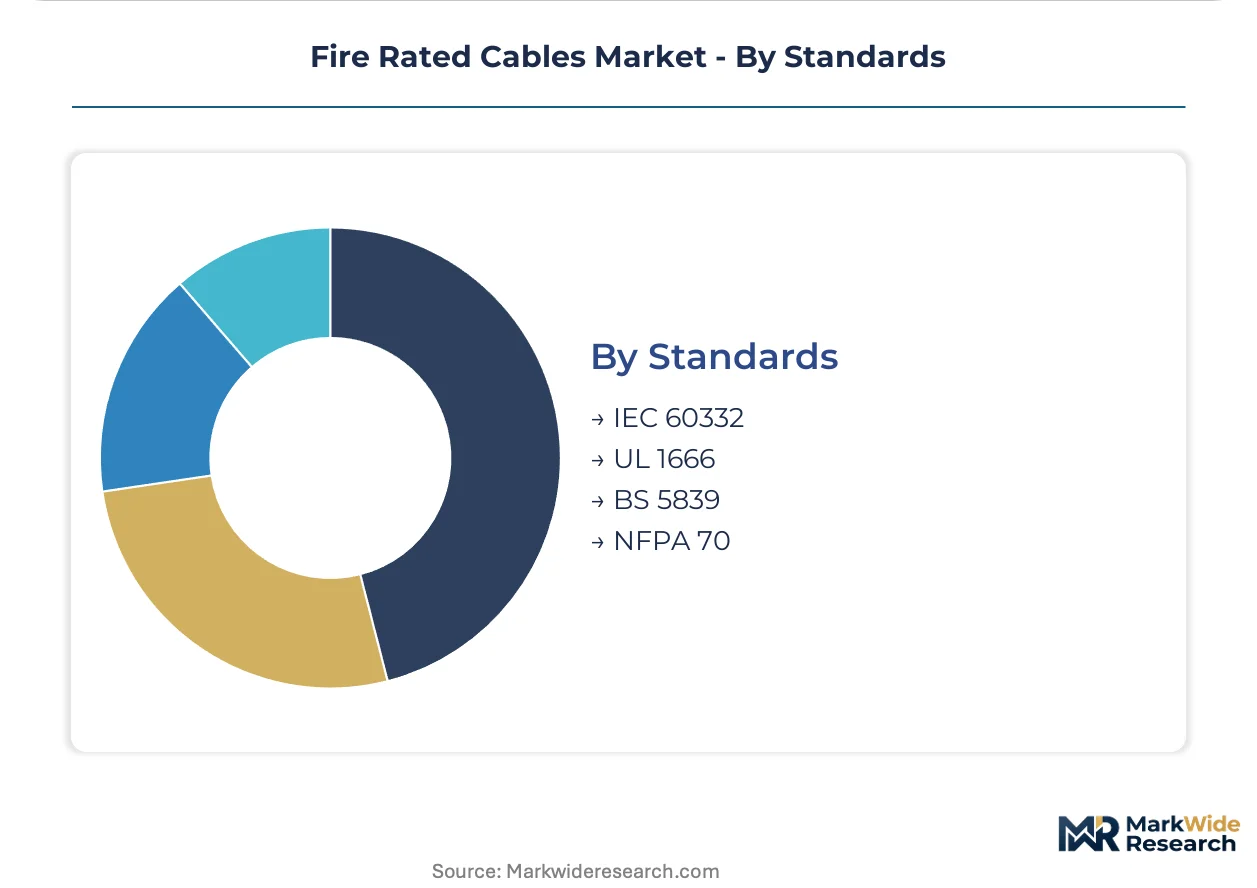
Standards:
Regulatory certification determines product marketability across procurement jurisdictions and tender eligibility.
- IEC 60332:European flame spread protocols establish baseline fire performance for Commonwealth and Asian markets. Extended retesting timelines for enhanced EU CPR classifications are delaying product launches.
- UL 1666:Vertical shaft testing requirements govern North American commercial high-rise installations. Divergence from IEC protocols forces manufacturers to maintain dual certification inventories.
- BS 5839:British fire detection and alarm cable standards influence specification across Middle Eastern and African markets with Commonwealth procurement heritage.
- NFPA 70:National Electrical Code adoption across US jurisdictions mandates enhanced circuit integrity in new construction and major renovation projects.
IEC 60332 certification covers the broadest geographic footprint; NFPA 70 compliance is gaining specification weight fastest in high-rise construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's urban infrastructure buildout concentrates procurement volume for medium-voltage fire resistant cable systems across metro electrification and tunnel networks. Regulatory divergence between UL 1666 vertical shaft testing and IEC 60332 flame spread protocols forces manufacturers to maintain dual certification inventories. Construction activity clusters in Chengdu, Xi'an, and Zhengzhou are absorbing significant regional capacity.
United States
Commercial high-rise construction in New York, Chicago, and Miami is mandating enhanced circuit integrity specifications under NFPA 70 National Electrical Code adoption. Stricter enforcement across new construction and major renovation projects elevates specification thresholds for emergency power and fire alarm systems. Data center operators in Northern Virginia and Phoenix are specifying mineral-insulated cable technology where temperature resilience above 1,000°C is non-negotiable.
Germany
EU Construction Products Regulation classification thresholds are elevating from basic flame spread containment to comprehensive smoke opacity and toxicity metrics. German specification bodies now mandate ca and s1 ratings for high-occupancy structures under REACH compliance frameworks. Industrial clusters in North Rhine-Westphalia and Bavaria are driving low-smoke zero-halogen compound adoption in hospital and airport terminal projects.
United Arab Emirates
Emerging unified fire safety standards across Gulf Cooperation Council jurisdictions are creating specification harmonization opportunities for certified suppliers. Korean EPC contractors executing infrastructure contracts are bypassing traditional distributor networks through direct manufacturer relationships. Dubai and Abu Dhabi metro electrification tenders are locking out speculative traders via multi-year framework agreements.
India
Stricter IEC 60332 enforcement is elevating specification thresholds across commercial high-rise construction in Mumbai, Bangalore, and Hyderabad. BIS certification requirements are tightening procurement standards for fire rated cable systems in urban infrastructure buildout. Delhi-Mumbai Industrial Corridor projects are generating concentrated demand for medium-voltage fire resistant architectures in tunnel electrification applications.
South Korea
LS Cable & System Limited dominates supply relationships with domestic EPC contractors executing Middle Eastern infrastructure contracts. Korean manufacturers leverage integrated compound manufacturing to secure feedstock consistency across regional plants. Seoul Capital Area and Busan-Ulsan industrial clusters are anchoring export-oriented production capacity for tunnel and metro network specifications.
Fire Rated Cables Market Vendor Landscape
Global majors compete with regional champions across certification breadth and compound formulation expertise. The vendor base organizes around three strategic tiers: integrated compound-to-cable manufacturers with captive polymer engineering capabilities, specialized medium-voltage architects for tunnel and metro networks, and scale-driven producers serving cost-sensitive infrastructure tenders. Competitive moves concentrate on backward integration into cross-linked polyethylene compound manufacturing and direct EPC contractor relationship formation.
Among European-integrated manufacturers, Prysmian Group and Nexans S.A. exemplify the compound-to-cable archetype with captive feedstock control. LS Cable & System Limited represents the Asia-Pacific specialist model anchored in EPC contractor direct relationships. These three occupy positions across the premium specification tier where EU CPR ca and s1 ratings and NFPA 70 compliance determine tender eligibility.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans S.A. |
| NKT Group |
| LEONI AG |
| LS Cable & System Limited |
| Elsewedy Electric Company |
| Tratos Limited |
| Sumitomo Electric Industries |
| Southwire Company |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap compound specialists across South Korea and Italy anchor feedstock supply for cross-linked polyethylene insulation, translating captive polymer engineering into pricing discipline that resists commodity volatility in long-term EPC framework agreements.
Pricing Analysis
Copper LME fluctuations pass through to cable fabricators via quarterly price adjustment clauses in multi-year infrastructure tenders. Pricing stratifies across EU CPR ca-rated premium constructions, standard IEC 60332-certified volumes, and economy-grade PVC alternatives for cost-sensitive procurement. Downward pressure runs through aluminum conductor tiers as buyers in India's Delhi-Mumbai Industrial Corridor exploit 40% raw material savings despite thermal conductivity trade-offs. Data center operators in Northern Virginia and Phoenix exhibit lowest price sensitivity, prioritizing mineral-insulated 1,050°C ratings over unit economics.
Supply Chain Analysis
Direct-to-EPC channels handle hyperscale metro electrification demand in China, the UAE, and Saudi Arabia, bypassing distributor markups entirely. Manufacturing concentrates in South Korea, Germany, and China, with each hub feeding distinct certification ecosystems—UL 1666 for North American projects, IEC 60332 for Commonwealth and Asian markets. Raw material flows draw from Chilean copper cathode, Qatari petrochemical feedstock for XLPE compounds, and Finnish mica tape for high-temperature wrapping. Single-source vulnerability concentrates in specialized polymer engineering talent for cross-linked polyethylene processing, with vocational training pipelines lagging retooling timelines across European plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with specification migration toward EU CPR ca and s1 smoke opacity ratings in German hospital and airport terminal projects justifying premium positioning over commodity alternatives.
For Market Incumbents: Deepen backward integration into cross-linked polyethylene compound manufacturing to secure feedstock consistency against polymer engineering talent scarcity. Lock multi-year framework agreements with Korean and Chinese EPC contractors executing Middle Eastern metro electrification before emerging Gulf Cooperation Council harmonization standards crystallize competitive eligibility. For New Entrants and Emerging Players: Fiber optic hybrid constructions enabling real-time temperature monitoring in smart building networks offer the most penetrable wedge against entrenched mineral-insulated cable incumbents. Target UAE and Saudi Arabia specification harmonization windows before tender cycles lock in certified supplier rosters, positioning through direct relationships with European engineering-procurement-construction specialists. For Investors and Strategic Acquirers: Valuations sit cheapest among compound-to-cable integrated manufacturers with captive XLPE formulation capabilities and dual UL 1666/IEC 60332 certification breadth. Long-term viability hinges on regulatory compliance moats widening through EU CPR threshold elevation and NFPA 70 enforcement expansion across US commercial high-rises. Watch for BIS certification tightening in India's urban infrastructure buildout as the inflection signal for specification-grade margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into XLPE Compounds | Captive polymer engineering secures feedstock consistency for Prysmian and Nexans against South Korean specialist competition. |
| Dual Certification Inventory Buildout | Parallel UL 1666 and IEC 60332 testing capacity unlocks tender eligibility across transatlantic infrastructure projects. |
| Direct EPC Relationship Formation | LS Cable & System's Korean contractor anchor demonstrates channel compression potential in UAE and Saudi Arabia metro awards. |
| Smart Building Fiber Optic Hybrid Development | Real-time temperature monitoring convergence with building automation networks captures predictive maintenance specification share. |
| EU CPR ca and s1 Rating Migration | German and French high-occupancy mandates displace legacy PVC formulators in hospital and airport terminal procurement. |
Methodological Framework
Coverage spans North America, Europe, Asia-Pacific, and the Middle East, with primary inputs from each region combining interviews with EPC procurement directors, cable manufacturer technical leads, regulatory compliance consultants, and compound supplier R&D heads against secondary validation from IEC certification databases, NFPA code revision dockets, EU Construction Products Regulation classification registries, and national building code harmonization notices across Gulf Cooperation Council jurisdictions. Bottom-up project pipeline tracking triangulates with top-down construction spend forecasts to anchor volume assumptions.
Granularity-level framing models voltage tier, insulation material, conductor composition, end-use application, and certification standard at the country level, with cross-segment elasticity parameters estimated through historical specification migration patterns. CAGRs derive from regression against construction output indices, regulatory enforcement intensity proxies, and raw material cost trajectory assumptions. Copper price volatility bands, XLPE adoption curves, and smart building integration penetration rates serve as industry-specific forecast inputs across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU CPR classification timeline delays, Gulf Cooperation Council code unification pace, and LME copper fluctuation amplitude. Periodic stress-testing of base assumptions against regulatory enforcement variance and compound formulation expertise pipeline output is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
North America Fire Extinguisher Market
Fire Safety & Protection
North America Fire Protection Water Storage Tanks Market
Fire Safety & Protection
Global Fire Extinguisher Cylinders Market
Fire Safety & Protection
Smart Smoke Alarm Market
Fire Safety & Protection
High Pressure Fixed Firefighting Misting System Market
Fire Safety & Protection
Global Flame Detector Market
Fire Safety & Protection
Fire Department Software Market
Fire Safety & Protection
Flame Barrier Market
Fire Safety & Protection
Fire Suppression Agent Market
Fire Safety & Protection
Global Fire Control System Market
Fire Safety & Protection
Automatic Fire Suppression System (AFSS) Market
Fire Safety & Protection
Firefighting Hose Market
Fire Safety & Protection
Laser Smoke Detector Market
Fire Safety & Protection
Powder Fire Suppression System Market
Fire Safety & Protection
Fire and Explosion Proof Lights Market
Fire Safety & Protection
Cellulosic Fire Protection Market