
 Household Eye Protection Lamp Market | 2026-2036
Household Eye Protection Lamp Market Size, Share, and Industry Trends Forecast 2026-2036
Household Eye Protection Lamp Market Insights
Parents of school-age children is redrawing demand patterns in the household eye protection lamp sector, displacing traditional office-procurement channels as the primary volume driver. Philips Lighting (Signify) leverages its medical-grade optical engineering heritage to dominate premium positioning in European households. Xiaomi Corporation competes through aggressive channel control across e-commerce platforms in mainland China. BenQ Corporation specializes in flicker-free panel technology for extended reading applications, sustaining margins in the high-performance tier.
Household eye protection lamps are engineered luminaires designed to minimize retinal strain through controlled spectral output, typically incorporating diffused LED arrays with color temperatures below 4000K for evening use and zero visible flicker below 100Hz. Their primary purpose is to reduce accommodative fatigue during prolonged near-vision tasks in domestic environments. LED lamps occupy the largest volume share due to semiconductor cost curves and energy efficiency mandates, while smart lamps represent the fastest-expanding margin pool as connectivity and circadian programming command price premiums. Blue light filtering technology leads R&D allocation, though adjustable brightness systems capture the broadest household penetration across income tiers.
The EU Ecodesign Directive and China's GB 7000 standards jointly shape minimum efficacy and photobiological safety thresholds, forcing redesign cycles among export-oriented manufacturers. The US FDA maintains oversight of lamps marketed with therapeutic claims, creating compliance friction for brands positioning products as myopia-prevention devices. Stakeholders must monitor divergence between voluntary eye-comfort certifications and mandatory efficiency regulations, as alignment gaps threaten cross-border product strategies and inventory fungibility.
Market Dynamics
Parental anxiety over juvenile myopia is compressing replacement cycles and elevating willingness-to-pay for certified eye-safe luminaires, restructuring how household lighting is evaluated and purchased.
Growth Catalysts
- China's GB 7000 standards:Mandatory photobiological safety testing is filtering out uncertified competitors and legitimizing premium pricing for compliant manufacturers.
- Extended screen-time protocols:School districts in Shanghai, Seoul, and Singapore now recommend home eye-protection lighting, converting institutional guidance into household procurement mandates.
- Dual-carbon policy alignment:China's MIIT efficiency mandates for domestic appliances are accelerating LED retrofit demand while disqualifying legacy incandescent inventory.
Market Restraints
- Semiconductor input volatility:LED driver IC shortages and rare-earth phosphor price swings compress assembler margins and destabilize production schedules.
- Regulatory fragmentation:Divergence between China's GB standards and EU Ecodesign Directive efficacy thresholds forces dual-SKU strategies that erode inventory fungibility.
- Substitute lighting categories:General-purpose smart bulbs with tunable white functionality capture price-sensitive households unwilling to pay eye-comfort premiums.
Strategic Opportunities
- India's underpenetrated tier-2 cities:Low household penetration of task-specific lighting in Ahmedabad, Pune, and Chandigarh offers first-mover positioning before BIS certification requirements tighten.
- Circadian programming convergence:Integration of melanopic lux sensors with home automation platforms commands subscription revenue streams beyond hardware sales.
- Direct-to-parent digital channels:Bypassing traditional home-improvement retail through education-adjacent content marketing reduces customer acquisition costs.
Industry Challenges
- Optical engineering talent scarcity:Shortage of photometric specialists capable of integrating human-centric lighting metrics into consumer product design.
- Multi-jurisdiction certification timelines:Parallel FDA, CE marking, and GB testing protocols extend product launch windows by 8-14 months.
- Legacy fixture incompatibility:Smart lamp connectivity standards fragment across Matter, Tuya, and proprietary ecosystems, complicating user experience design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Eye Protection Lamp Market |
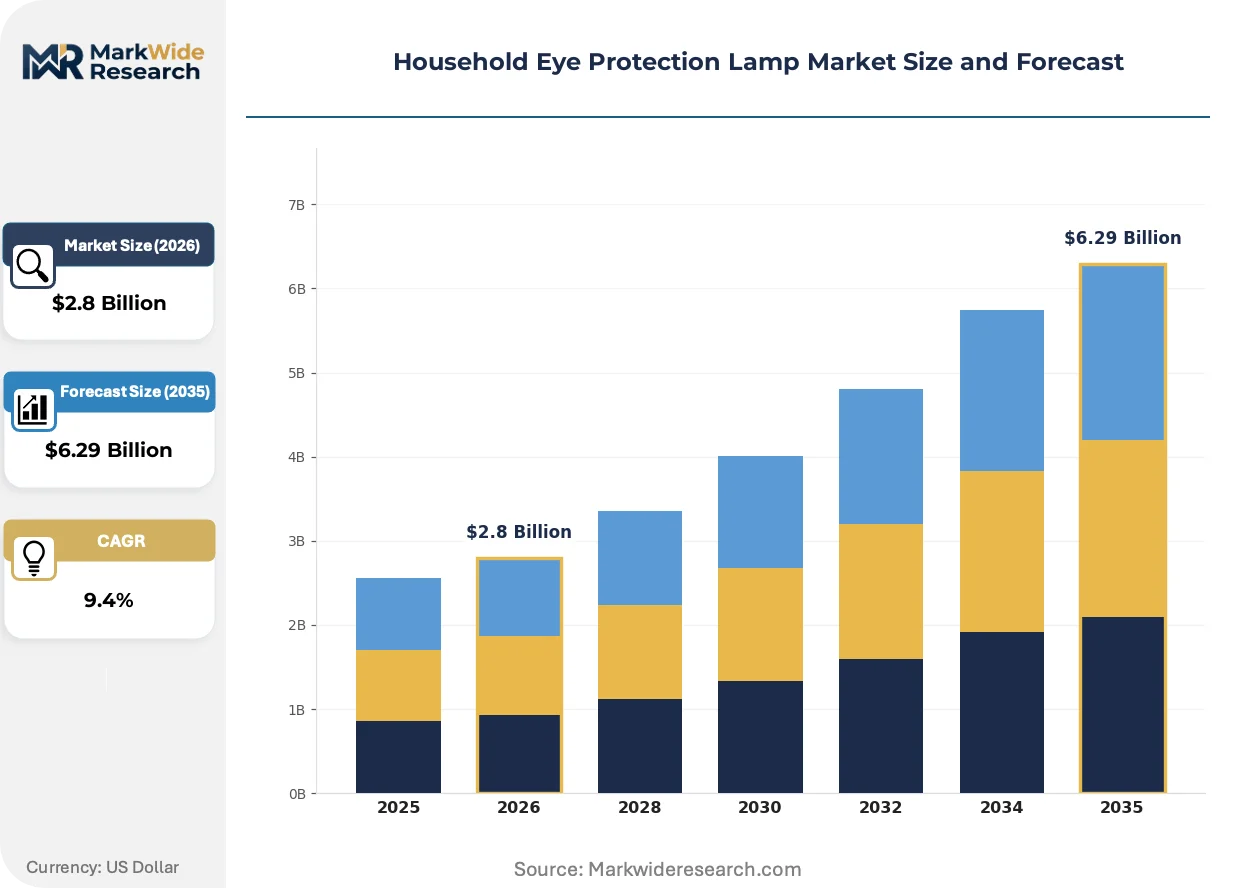
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Lamps, Fluorescent Lamps, Incandescent Lamps, Smart Lamps Technology: Blue Light Filtering, Dimmable, Adjustable Brightness, Color Temperature Control End User: Households, Offices, Educational Institutions, Health Facilities Application: Reading, Workstations, Gaming, General Lighting |
| Companies Covered | Philips Lighting (Signify), BenQ Corporation, Xiaomi Corporation, OSRAM, Dyson Ltd., Opple Lighting, Panasonic, Humanscale Corporation, Herman Miller Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Eye Protection Lamp Market Trends and Innovations
Spectral engineering and connectivity integration are redefining what household lighting must deliver, shifting competitive advantage from lumens-per-watt to biological impact metrics and software-enabled personalization.
Micro-LED array technology is miniaturizing. These chip-scale packages enable uniform surface illumination without diffuser depth, allowing lamp profiles under 15mm. Furniture-integrated task lighting manufacturers in Guangdong and Zhejiang are adopting these emitters to embed eye-safe illumination directly into desks and headboards. The form-factor compression is miniaturizing the standalone lamp category and blurring boundaries between fixture and furniture.
The EU Ecodesign Directive's 2023 amendment tightens standby power limits and mandates repairability documentation for lighting products. Manufacturers serving German and French markets must redesign power supplies and modularize driver components. Premium European brands are responding by marketing upgradeable optical engines as sustainability credentials, converting regulatory burden into competitive differentiation against disposable Asian imports.
Parental purchasing now originates in pediatric ophthalmology waiting rooms and school WeChat groups rather than retail showrooms. Shanghai and Beijing households discover eye-protection lamps through myopia-prevention seminars and peer recommendations, then complete transactions on Tmall or Pinduoduo within the same session. This discovery-to-purchase compression is collapsing traditional brand-building timelines and rewarding agile supply-chain responsiveness over heritage marketing investment.
Household Eye Protection Lamp Market Segmentation
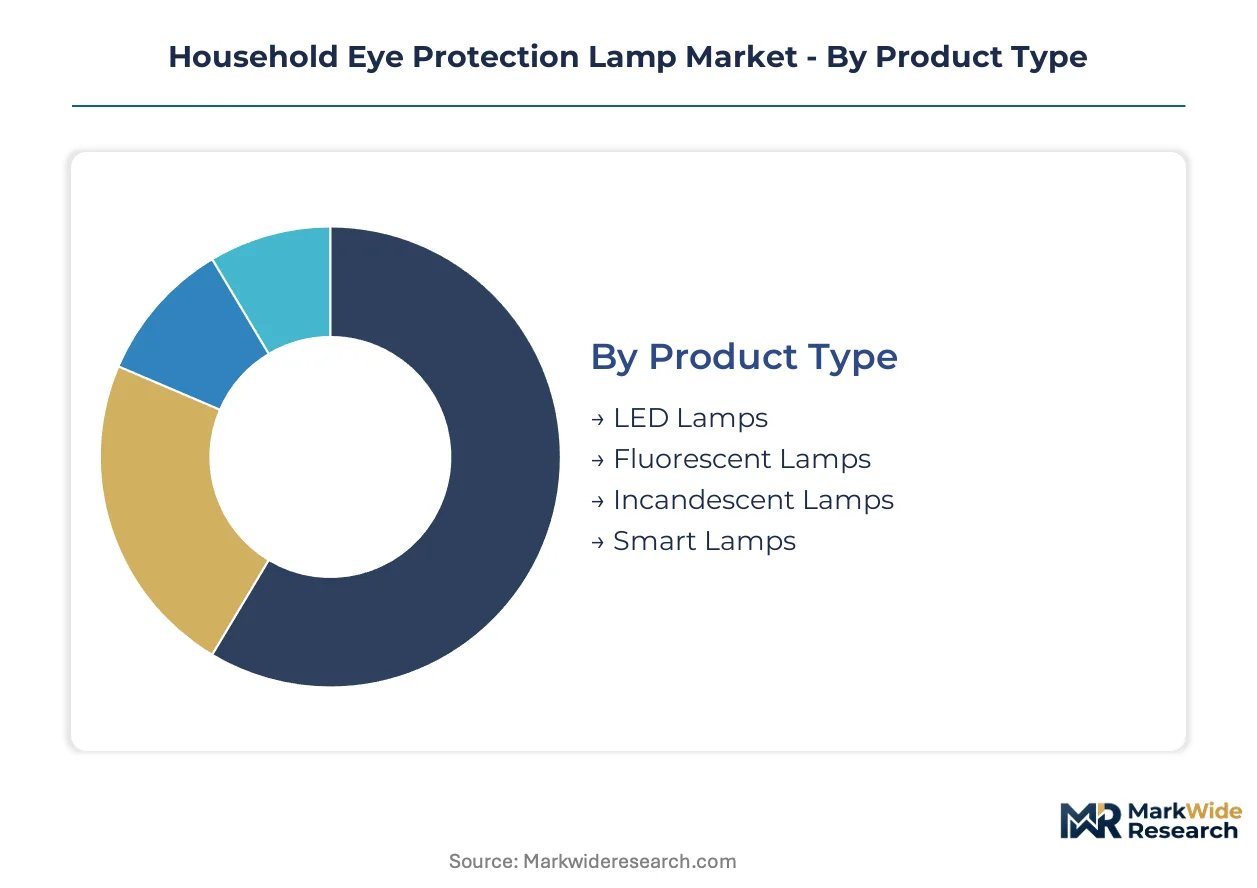
Segmentation in household eye protection lamps reveals how technical specifications map onto distinct procurement channels and price tolerance thresholds. Manufacturers configure product portfolios around optical performance tiers rather than luminaire form factors alone.
Product Type:
Domestic consumption in East Asia concentrates on LED and smart variants, while export manufacturing to Southeast Asia and the Middle East still ships fluorescent units for price-sensitive institutional tenders.
- LED Lamps:Semiconductor-based solid-state emitters with efficacy above 90 lumens per watt dominate volume manufacturing in Guangdong and Zhejiang provinces. Demand clusters in Shanghai, Beijing, and Seoul households where MIIT efficiency mandates and K-12 academic competition drive replacement of legacy sources.
- Smart Lamps:Wi-Fi and Bluetooth-enabled luminaires with circadian programming and app-based spectral control command the highest margins in European and North American direct-to-consumer channels. Philips Hue and Xiaomi ecosystems anchor consumer expectations for connectivity integration.
- Fluorescent Lamps:Compact fluorescent tubes with electronic ballasts persist in Indian tier-3 cities and Indonesian educational procurement where capital constraints override operating cost considerations.
- Incandescent Lamps:Tungsten-halogen sources with minimal blue emission retain niche demand in Russian and Iranian markets with weaker enforcement of incandescent phase-out directives.
LED lamps command the established base. The steepest expansion runs through smart lamps.
Technology:
Cost-tier stratification separates premium optical engineering from mass-market brightness adjustment, with filtering technologies capturing certification-linked price premiums.
- Blue Light Filtering:Phosphor-converted or dichroic filter systems suppressing melanopic irradiance below 480nm dominate R&D allocation at BenQ and Signify. Pediatric ophthalmology recommendations in Singapore and Taiwan validate premium positioning.
- Adjustable Brightness:Pulse-width modulation circuits with flicker indices below 0.5 capture the broadest household penetration across income tiers in China and Vietnam.
- Dimmable:Phase-cut or 0-10V analog dimming compatibility targets retrofit replacement of legacy desk lamps in European residential renovation markets.
- Color Temperature Control:CCT-tunable systems spanning 2700K to 5000K address circadian health positioning in wellness-focused North American and Australian retail channels.
Adjustable brightness systems anchor volume manufacturing. Blue light filtering delivers the steepest margin expansion trajectory.
End User:
Application context determines certification requirements and procurement authority, with household purchases increasingly bypassing traditional electrical retail.
- Households:Parent-driven procurement through e-commerce platforms and school-adjacent channels now represents the dominant volume driver in East Asian metropolitan clusters.
- Educational Institutions:Kindergarten and primary school procurement in Shenzhen, Seoul, and Tokyo operates through municipal tender processes with mandatory GB 7000 or JIS compliance documentation.
- Offices:Corporate facilities management in Frankfurt, London, and New York specifies task lighting with WELL Building Standard alignment for employee wellness credentials.
- Health Facilities:Hospital patient rooms and ophthalmology clinics in Paris, Munich, and Milan require medical-grade photobiological safety certification beyond consumer standards.
Households generate the volume base. Educational institutions are climbing the fastest as procurement formalizes.
Application:
Usage intensity and duration requirements separate high-performance task specifications from ambient replacement markets.
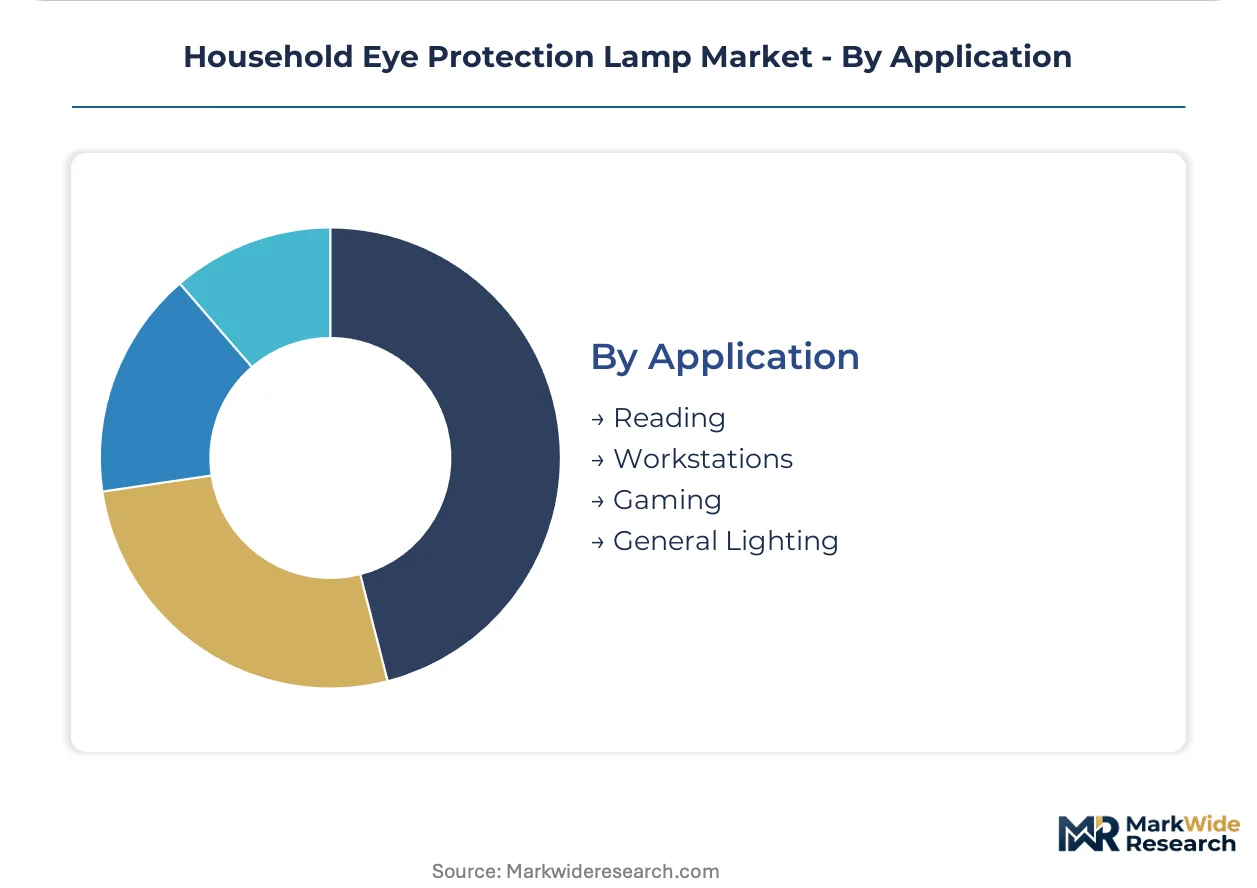
- Reading:Extended near-vision tasks demand uniform illuminance above 500 lux with glare indices below 19, driving premium desk lamp specifications in academic-competitive households.
- Workstations:Dual-monitor and video-conferencing setups in hybrid work arrangements require asymmetric light distribution to eliminate screen reflection in home offices across London, Amsterdam, and Copenhagen.
- Gaming:Extended session durations among adolescent and young adult users in Seoul, Taipei, and Los Angeles drive demand for low-latency, high-CRI ambient lighting with RGB synchronization.
- General Lighting:Replacement of ceiling and floor fixtures with eye-comfort positioning targets broad household renovation cycles with lower specification intensity.
Reading applications anchor the premium tier. Gaming is gaining share fastest among younger demographic cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong and Zhejiang provinces export finished lamps to Germany, France, and the United Kingdom, while component shipments flow from South Korea and Japan into Chinese assembly lines. This trade architecture concentrates manufacturing intelligence in East Asian industrial clusters and distributes finished goods through European retail channels.
China
Parental anxiety over juvenile myopia drives replacement cycles in Shanghai and Beijing households. MIIT enforces GB 7000 photobiological safety standards that filter uncertified competitors from domestic shelves. Shenzhen manufacturers integrate micro-LED arrays into furniture-embedded task lighting for export to German and French markets.
Germany
Corporate facilities managers specify WELL Building Standard-aligned task lighting for Frankfurt and Munich office renovations. The EU Ecodesign Directive mandates repairability documentation and standby power limits below 0.5 watts. Bavarian lighting engineers develop modular optical engines marketed as upgradeable sustainability credentials against disposable imports.
United States
Hybrid work arrangements in New York and Los Angeles drive asymmetric light distribution specifications for dual-monitor home offices. FDA oversight of therapeutic claims creates compliance friction for brands positioning products as myopia-prevention devices. Seattle-based smart home platforms integrate circadian programming with melanopic lux sensors.
South Korea
Extended gaming sessions among Seoul and Busan adolescents fuel demand for low-latency RGB-synchronized ambient lighting. K-12 districts in the capital region recommend home eye-protection lighting, converting institutional guidance into household procurement mandates. Gyeonggi Province assemblers source LED driver ICs from domestic foundries to mitigate semiconductor volatility.
Japan
Kindergarten procurement in Tokyo and Osaka operates through municipal tender processes with mandatory JIS compliance documentation. METI efficiency mandates accelerate LED retrofit demand while disqualifying legacy fluorescent inventory. Nagoya-based optical specialists integrate human-centric lighting metrics into consumer product designs for premium European export.
Household Eye Protection Lamp Market Competitive Landscape
Listed leaders compete with private specialists across channel control and optical engineering depth. Signify and Panasonic leverage capital market access for R&D scale, while Zhejiang and Guangdong private manufacturers dominate cost-optimized export production. Three archetypes define competitive positioning: heritage lighting conglomerates with medical-grade optical credentials, consumer electronics platforms with e-commerce channel dominance, and regional private-label assemblers serving institutional tenders. Consolidation pressures favor M&A between component suppliers and finished-goods brands, alongside geographic expansion into underpenetrated Indian and Southeast Asian markets.
Within the heritage conglomerate tier, Philips Lighting (Signify) and Panasonic occupy positions anchored by decades of photometric research and medical-device adjacent credibility. Xiaomi Corporation exemplifies the platform-archetype, leveraging ecosystem lock-in and direct-to-consumer logistics across mainland Chinese e-commerce. BenQ Corporation sits within the specialist tier, representing concentrated investment in flicker-free panel technology for extended near-vision applications. These three anchors illustrate how competitive advantage stratifies across optical engineering depth, channel control intensity, and vertical integration posture rather than scale alone.
| Leading Market Players |
|---|
| Philips Lighting (Signify) |
| BenQ Corporation |
| Xiaomi Corporation |
| OSRAM |
| Dyson Ltd. |
| Opple Lighting |
| Panasonic |
| Humanscale Corporation |
| Herman Miller Inc. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day LED driver IC lead times concentrate pricing power among Guangdong assemblers with captive component inventories, while spot-market buyers absorb margin compression from rare-earth phosphor volatility. This inventory asymmetry stratifies the market between vertically integrated manufacturers and import-dependent brands.
Pricing Analysis
Micro-LED array pricing gaps separate current-generation furniture-embedded emitters from prior-generation diffused LED panels and next-generation chip-scale packages. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and optical engineering depth. Cost compression in the economy tier stems from substitute smart bulbs with tunable white functionality. Price-sensitive households in Indian tier-2 cities resist eye-comfort premiums, while certified medical-grade positioning commands least elasticity in European health-facility procurement.
Supply Chain Analysis
China and South Korea anchor LED epitaxy wafer and driver IC fabrication, while Japan supplies precision phosphor formulations and optical-grade polymers. Finished lamp assembly draws from Guangdong and Zhejiang provinces, feeding from rare-earth phosphor deposits concentrated in Jiangxi and Inner Mongolia. Single-source vulnerability runs through LED driver IC foundries in Gyeonggi Province. Distribution runs through Tmall and Pinduoduo direct-to-consumer channels in mainland China, with Amazon and specialist lighting retailers handling European and North American fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photometric specialist scarcity constrains product development velocity, as human-centric lighting metrics demand interdisciplinary expertise spanning ophthalmology, semiconductor physics, and industrial design. This capability gap separates heritage conglomerates from commodity assemblers.
For Market Incumbents: Consolidate optical engineering talent through targeted acquisition of Nagoya and Munich photometric specialists. Deepen backward integration into LED driver IC supply through joint ventures with Gyeonggi Province foundries. Defensive positioning against Xiaomi's ecosystem lock-in requires proprietary circadian programming platforms with melanopic lux sensor integration.
For New Entrants and Emerging Players: Lead with furniture-embedded micro-LED task lighting for Ahmedabad and Pune households before BIS certification requirements tighten. Capture parent-driven procurement through education-adjacent content marketing on WeChat and Instagram, bypassing traditional home-improvement retail customer acquisition costs. White-space positioning targets circadian programming subscription revenue beyond hardware sales.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with underutilized lighting divisions and dormant medical-grade optical credentials. Long-term viability hinges on software-enabled recurring revenue attachment rates rather than hardware replacement cycles. Watch for FDA enforcement actions against myopia-prevention therapeutic claims as inflection indicator for compliance-heavy premium positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Optical Engineering Talent Acquisition | Human-centric lighting metrics integration differentiates premium positioning against commodity competitors. |
| Circadian Programming Platform Development | Melanopic lux sensor integration commands subscription revenue beyond hardware sales in European markets. |
| GB 7000 Certification Pre-Positioning | MIIT photobiological safety compliance filters uncertified competitors from domestic Chinese shelves. |
| Furniture-Embedded Micro-LED Integration | Guangdong manufacturers compress form factors below 15mm for German and French export markets. |
| Direct-to-Parent Digital Channel Buildout | Education-adjacent content marketing reduces customer acquisition costs in Shanghai and Beijing metropolitan clusters. |
Research Methodology
A standing panel of pediatric ophthalmologists, LED component procurement managers, e-commerce platform category directors, and municipal tender officers provided ongoing calibration across the analysis window. Primary interviews with these stakeholders combined with secondary validation from MIIT efficiency mandate filings, EU Ecodesign Directive amendments, FDA therapeutic claim warning letters, and Tmall category transaction data. Bottom-up assembler capacity assessments and top-down household penetration modeling generated convergent volume estimates.
Consistency checks validated projections against external benchmarks including semiconductor cost curve trajectories and regulatory adoption timelines across multiple jurisdictions. The analytical framework modeled product type, technology tier, end-user application, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level replacement cycle compression and premium tier margin expansion assumptions, with specific inputs from K-12 screen-time protocol adoption rates and dual-carbon policy implementation schedules.
Forecasts assume regulatory continuity in China's GB standards regime and EU Ecodesign Directive enforcement; material policy shifts would require re-modeling around divergent photobiological safety thresholds or accelerated incandescent phase-out schedules. Recalibration cycles align with material shifts in semiconductor input availability, pediatric myopia prevalence data, and municipal tender formalization in East Asian metropolitan clusters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Locker Market
Safety Equipment and Personal Protective Equipment (PPE)
Blast Monitoring Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Saudi Arabia Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Head Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Emergency Oxygen Deployment Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Bicycle Safety Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Analyzers Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Power Air Purifying Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Seat Belt System Market
Safety Equipment and Personal Protective Equipment (PPE)
Riot Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa N95 Mask Market