
 Fire Resistant Glass Market | 2026-2036
Fire Resistant Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Resistant Glass Market Analysis
Commercial building developers is unwinding legacy procurement patterns toward specification-grade fire resistant glass, while residential property investors retreat from premium certified products. Saint-Gobain leverages its dual-brand architecture through Vetrotech Saint-Gobain International AG to dominate European specification channels. SCHOTT AG anchors its position through proprietary borosilicate ceramic technology that sustains performance thresholds above standard laminated alternatives. AGC Inc. competes aggressively in Asian commercial tower projects where curtain wall integration demands customized fire-rated glazing solutions.
Fire resistant glass incorporates intumescent interlayers, tempered substrates, or ceramic compositions engineered to maintain structural integrity and limit radiant heat transfer for defined fire ratings measured in minutes of resistance. The primary industrial purpose centers on compartmentalizing fire spread in occupied structures while preserving visual transparency and daylighting function. Laminated glass configurations with intumescent cores command the deepest specification margins in commercial high-rises, whereas ceramic glass variants lead growth trajectories due to superior thermal shock performance in curtain wall applications. Wired glass retains residual presence in legacy industrial retrofits but faces displacement as building codes tighten on impact safety alongside fire ratings.
BS EN 13501 and ASTM E119 establish divergent testing protocols that fragment global product certification requirements and complicate cross-border manufacturing scale. EMA-aligned frameworks in Europe push manufacturers toward extended fire resistance durations and stricter smoke control integration, while UL 9 and NFPA 251 govern North American market access with emphasis on hose stream testing protocols. Stakeholders must monitor regulatory convergence pressures between ISO standardization initiatives and regional code bodies to anticipate which certification investments will unlock multi-jurisdictional product eligibility.
Market Dynamics
Urban densification across Asia-Pacific and Europe is forcing building codes toward stricter fire compartmentalization standards, while curtain wall engineering demands glass that simultaneously satisfies thermal, optical, and fire-resistance specifications.
Growth Catalysts
- EN 13501-2 harmonization:European regulatory convergence around extended fire resistance durations is standardizing product specifications across Germany, France, and Italy, reducing certification fragmentation for manufacturers.
- Curtain wall integration:Commercial tower developers in Shanghai, Mumbai, and Singapore are specifying fire-rated glazing systems that combine structural glazing with passive fire protection in single-source procurement.
- Retrofit mandates:Municipal fire safety ordinances in legacy industrial districts of the UK and Germany are triggering replacement cycles for obsolete wired glass installations.
Market Restraints
- Borosilicate ceramic supply concentration:Production of high-performance ceramic substrates concentrates among limited specialty glass manufacturers, creating input bottlenecks for fire-rated glazing fabricators.
- Intumescent interlayer cost volatility:Sodium silicate and graphite-based interlayer materials face raw material price swings that compress margins on laminated fire-resistant products.
- Testing protocol divergence:BS EN 13501, ASTM E119, and ISO 834 maintain incompatible fire resistance testing methodologies, forcing manufacturers to maintain parallel certification inventories.
Strategic Opportunities
- India commercial construction:Fire safety code enforcement is tightening in Bengaluru, Hyderabad, and Mumbai commercial towers where specification-grade fire glazing penetration remains below European levels.
- Smart building convergence:Integration of fire-resistant glazing with electrochromic tinting and embedded sensor networks is opening premium specification tiers in intelligent building projects.
- Green building incentives:EU Green Deal-aligned building renovation passports are creating regulatory tailwinds for fire-rated glazing that simultaneously improves thermal envelope performance.
Industry Challenges
- Fire testing laboratory capacity:Extended lead times at accredited testing facilities for EN 13501 and UL 9 certification are delaying product launches and contract bids.
- Curtain wall system integration:Fire-rated glazing must coordinate with aluminum framing, gaskets, and anchoring systems where thermal expansion coefficients and fire-induced deformation create engineering complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Resistant Glass Market |
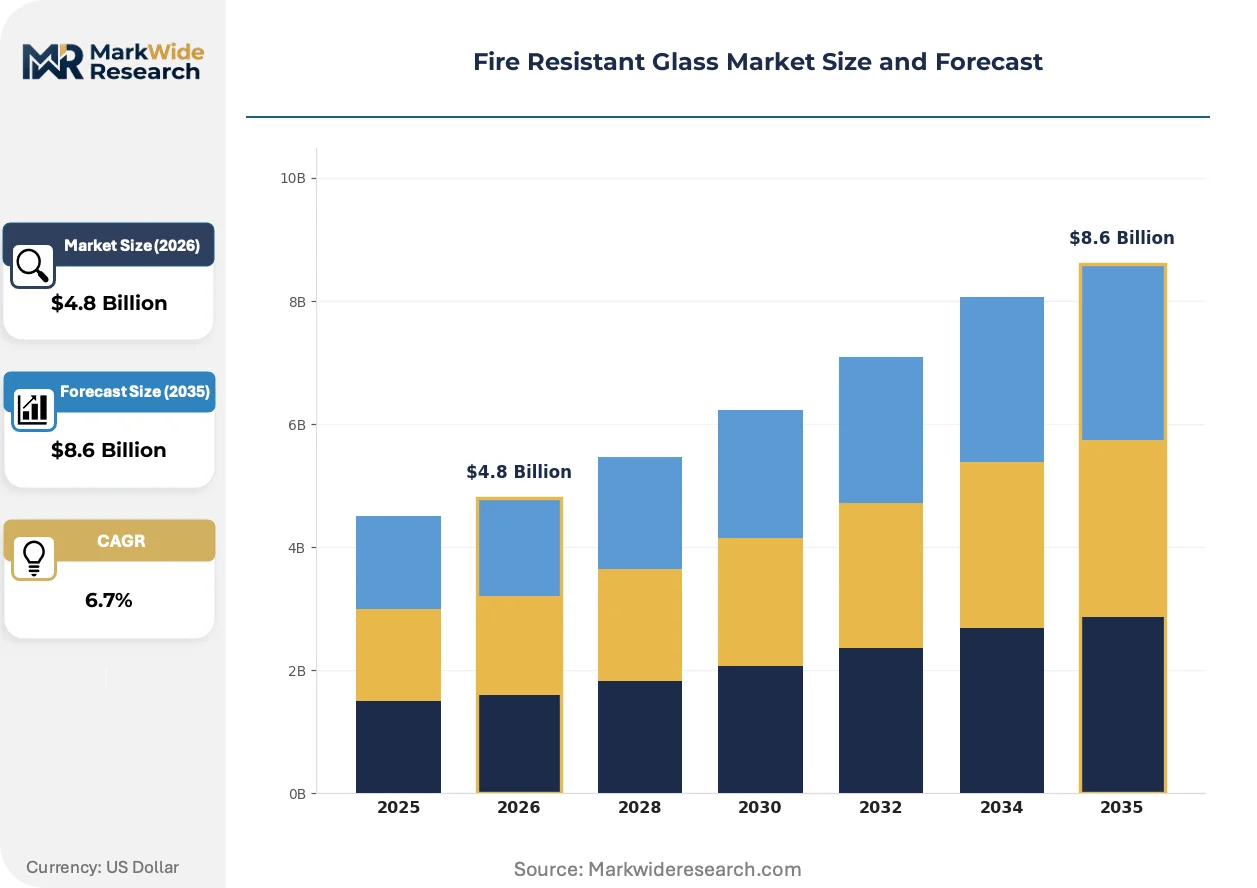
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Glass, Laminated Glass, Wired Glass, Ceramic Glass End User: Commercial Buildings, Residential Properties, Industrial Facilities, Transportation Installation Method: Frame Mounted, Flush Glazing, Curtain Wall, Single Glazing Certification: BS EN 13501, ASTM E119, NFPA 251, UL 9 |
| Companies Covered | Saint-Gobain, SCHOTT AG, AGC Inc., Nippon Sheet Glass Co., Ltd., Pyroguard, Vetrotech Saint-Gobain International AG, Glas Trösch, POLFLAM, SAFTI FIRST, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Resistant Glass Market Emerging Trajectories
Product engineering in fire-resistant glazing is pivoting from passive fire containment toward multifunctional performance systems that simultaneously address thermal, acoustic, and structural demands in high-rise envelopes.
Ceramic glass compositions engineered from proprietary borosilicate formulations are displacing traditional wired glass and standard laminated alternatives in curtain wall specifications. Tower developers in Frankfurt, London, and Tokyo are specifying these materials for their superior thermal shock resistance and optical clarity. The displacement is compressing specification margins for legacy wired glass while elevating performance thresholds across commercial high-rise procurement.
REACH regulation amendments targeting flame retardant substances in construction materials are reshaping formulation requirements for intumescent interlayers. Manufacturers must reformulate sodium silicate and graphite-based cores to maintain fire ratings while eliminating restricted chemical additives. German and French specification channels are most affected, with fabricators accelerating compliance timelines ahead of 2025 enforcement windows.
Specification-grade procurement is consolidating around performance-based contracts that unbundle fire resistance testing, installation, and maintenance into discrete service modules. Commercial developers in Singapore and Sydney are adopting this model to transfer liability for fire rating compliance to glazing contractors. The shift is most visible in design-build contracts for mixed-use towers where single-source accountability reduces interface risk between architects, engineers, and glazing subcontractors.
Fire Resistant Glass Market Segmentation
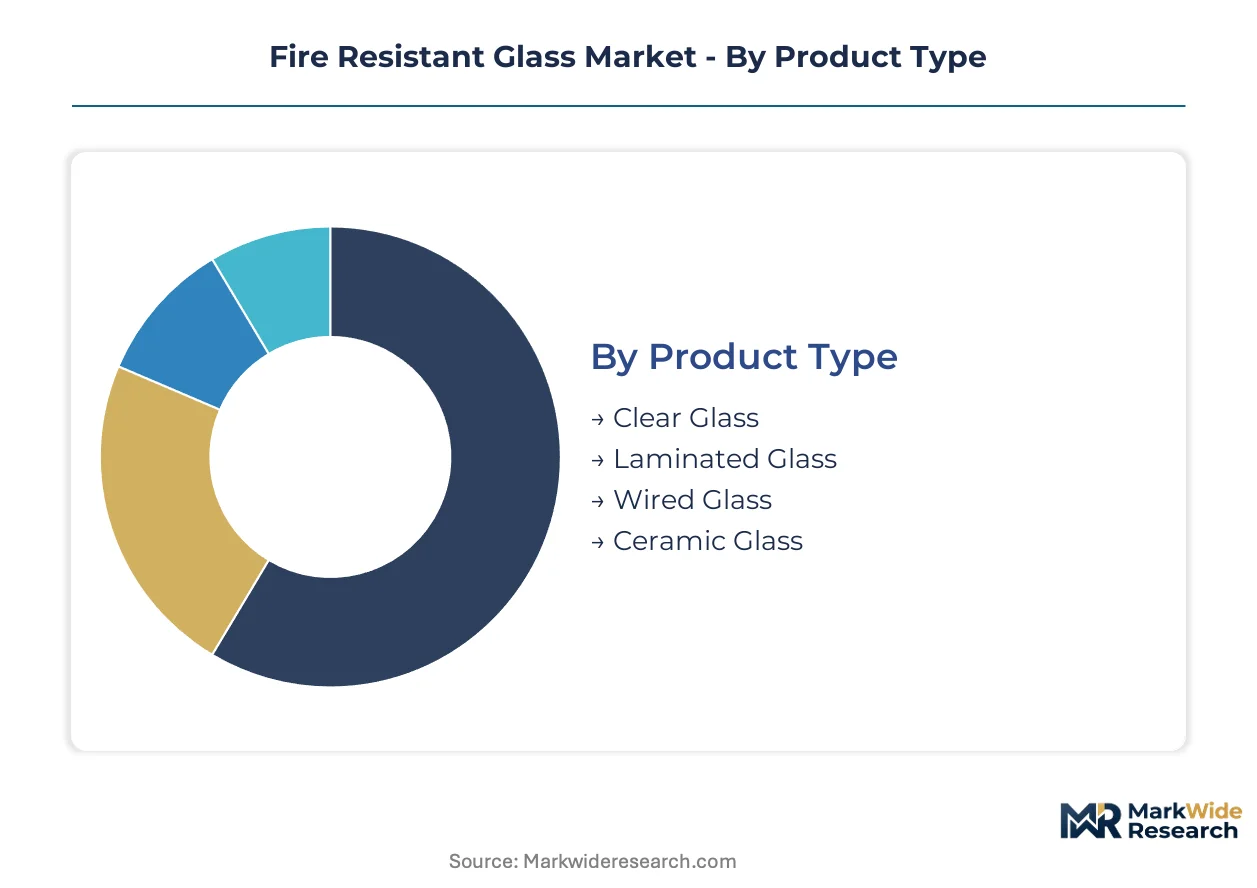
Fire resistant glass segmentation reveals how regulatory fragmentation and installation complexity fragment procurement decisions across construction verticals. Specification engineers must reconcile divergent certification requirements with structural glazing performance thresholds.
Product Type:
BS EN 13501-2 harmonization in Europe and ASTM E119 hose stream protocols in North America create divergent performance baselines that favor different substrate compositions.
- Laminated Glass:Intumescent interlayers sandwiched between tempered substrates expand under heat to form opaque insulating barriers. Commercial tower developers in Shanghai and Mumbai specify these configurations for 60-120 minute ratings where optical clarity must persist post-installation. REACH amendments on flame retardant additives are forcing reformulation of sodium silicate cores ahead of enforcement windows.
- Ceramic Glass:Proprietary borosilicate formulations withstand thermal shock exceeding 1000°C without structural failure. Curtain wall engineers in Frankfurt and Tokyo specify these for spandrel zones and atrium barriers where radiant heat suppression competes with daylighting mandates. Supply concentrates among specialty manufacturers, creating input bottlenecks for glazing fabricators.
- Clear Glass:Standard tempered variants achieve limited fire ratings through thickness and edge treatment alone, serving cost-sensitive retrofit applications in legacy industrial districts.
- Wired Glass:Embedded steel mesh retains glass fragments during fire exposure but faces displacement as building codes tighten impact safety requirements alongside fire ratings.
Laminated glass handles the majority of throughput; ceramic glass is the fastest mover on share.
End User:
Customer procurement sophistication varies sharply, with commercial developers demanding bundled testing-installation-maintenance contracts while residential investors retreat from premium certified products.
- Commercial Buildings:High-rise towers in Singapore and Sydney specify fire-rated glazing as part of integrated curtain wall systems where single-source procurement transfers liability compliance to contractors. Design-build contracts increasingly unbundle fire resistance testing, installation, and maintenance into discrete service modules.
- Industrial Facilities:Legacy manufacturing plants in Germany's Ruhr Valley and UK's Midlands face municipal retrofit mandates triggering replacement cycles for obsolete wired glass installations. Procurement prioritizes rapid certification turnaround over optical performance.
- Residential Properties:Property investors in multi-family developments specify downgraded fire ratings to contain capital costs, accepting wired glass or standard laminated alternatives where codes permit.
- Transportation:Rail and aviation applications demand specialized impact-fire dual certification, with limited fabricators qualified for EN 13501-2 plus sector-specific safety protocols.
Commercial buildings absorb the dominant share of specification-grade volume; industrial retrofits are climbing fastest as enforcement tightens.
Installation Method:
Structural engineering complexity escalates with system integration depth, as thermal expansion coefficients and fire-induced deformation create interface risks between glazing and framing.
- Curtain Wall:Unitized systems integrate fire-rated glazing with aluminum framing, gaskets, and anchoring in factory-controlled conditions. Tower developers in Frankfurt and London specify these for atrium barriers and spandrel zones where thermal, optical, and fire-resistance specifications must converge.
- Frame Mounted:Conventional perimeter anchoring in steel or aluminum frames dominates retrofit applications and mid-rise construction where curtain wall economics fail.
- Flush Glazing:Frameless edge details maximize optical continuity in prestige commercial lobbies and atrium spaces, demanding precision fabrication tolerances.
- Single Glazing:Standalone fire-rated panels without integrated framing serve compartmentalization barriers in legacy building upgrades where structural glazing is impractical.
Curtain wall integration commands the highest specification margins; frame mounted methods retain volume leadership across retrofit-dominant geographies.
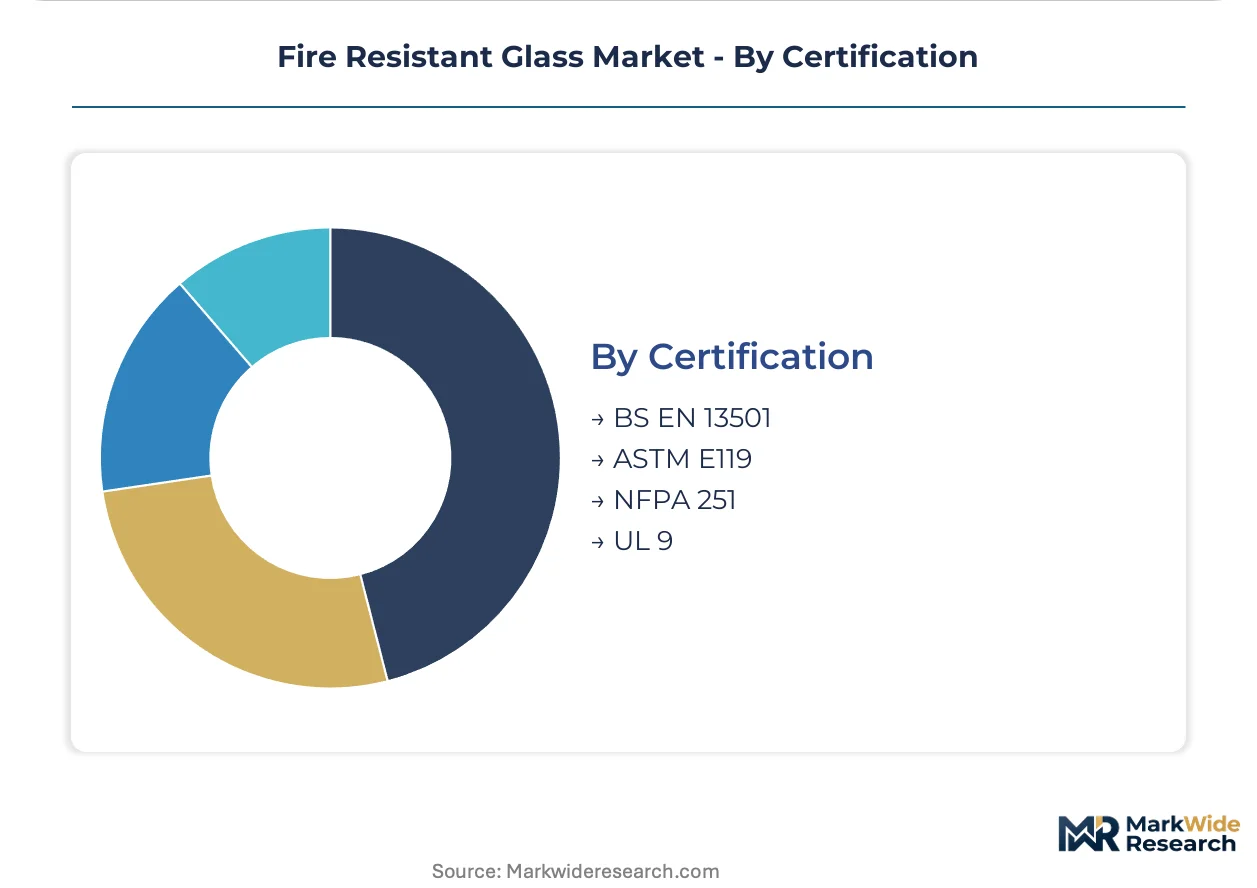
Certification:
Testing protocol divergence fragments global product eligibility, forcing manufacturers to maintain parallel certification inventories for multi-jurisdictional contracts.
- BS EN 13501:European regulatory convergence around extended fire resistance durations and stricter smoke control integration standardizes specifications across Germany, France, and Italy. EMA-aligned frameworks push manufacturers toward 90-180 minute ratings with integrated smoke seals.
- ASTM E119:North American market access requires hose stream testing protocols that simulate firefighter suppression efforts, creating technical barriers for European-certified products.
- UL 9:Fire resistance of window assemblies governs commercial tower specifications in the United States, with extended lead times at accredited testing facilities delaying product launches.
- NFPA 251:Standard methods of fire tests of building construction and materials underpin insurance and code compliance in legacy North American installations.
BS EN 13501 unlocks the broadest multi-country eligibility; UL 9 certification carries steepest expansion trajectory as North American high-rise construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Swiss specialty glass exports supply Asian commercial tower developers in Shanghai and Singapore, while Chinese ceramic substrate production feeds European fabricators facing REACH compliance deadlines.
China
Shanghai and Shenzhen commercial tower construction drives specification-grade ceramic glass procurement for curtain wall integration. GB standards from SAMR enforce stricter fire compartmentalization in buildings exceeding 100 meters. Yangtze River Delta fabricators concentrate borosilicate ceramic production for domestic high-rise projects and European export contracts.
Germany
Ruhr Valley industrial retrofits and Frankfurt commercial towers sustain demand across laminated and ceramic product categories. EMA-aligned frameworks through BS EN 13501-2 mandate extended fire resistance durations with integrated smoke control. North Rhine-Westphalia glazing contractors dominate specification channels for mixed-use developments across the Rhine-Ruhr metropolitan region.
India
Mumbai and Bengaluru commercial construction tightens enforcement of National Building Code fire safety provisions in high-rise envelopes. BIS certification requirements are accelerating for imported fire-rated glazing systems. Maharashtra and Karnataka state urban development authorities are mandating retrofit upgrades in legacy commercial districts.
United States
UL 9 certification governs commercial tower specifications in New York and Chicago where hose stream testing protocols create technical barriers for European-certified products. OSHA workplace safety standards intersect with municipal fire codes in high-occupancy structures. Pacific Northwest and Southeast construction markets show divergent adoption rates for specification-grade versus economy-tier fire glazing.
Japan
Tokyo and Osaka high-rise developments specify ceramic glass for thermal shock performance in seismic-resistant curtain wall systems. METI building energy efficiency standards intersect with fire resistance requirements in commercial envelope design. Kanto region fabricators concentrate precision manufacturing for domestic tower projects and selective Asian export markets.
Fire Resistant Glass Market Vendor Landscape
Listed leaders compete with private specialists across certification depth and geographic coverage, creating a tiered structure where scale advantages intersect with technical specialization. European-headquartered conglomerates anchor premium specification channels through dual-brand architectures, while mid-cap fabricators concentrate on regional certification mastery. Three archetypes dominate: integrated material-science conglomerates with captive glass production, specialized fire-glazing fabricators with testing laboratory partnerships, and regional construction-glass distributors with local code expertise. Competitive moves center on backward integration into borosilicate ceramic supply and strategic partnerships with curtain wall engineering firms.
Within the integrated conglomerate tier, Saint-Gobain and AGC Inc. exemplify scale-driven positioning across multiple certification jurisdictions. SCHOTT AG occupies a specialist position anchored in proprietary material science capabilities. Among European-focused fabricators, Vetrotech Saint-Gobain International AG represents the dual-brand architecture approach, while POLFLAM and Glas Trösch exemplify mid-cap specialists concentrating on EN 13501-2 mastery. SAFTI FIRST and Pyroguard occupy positions within North American-centric certification ecosystems. Nippon Sheet Glass Co., Ltd. anchors Asian market presence through regional production scale.
| Leading Market Players |
|---|
| Saint-Gobain |
| SCHOTT AG |
| AGC Inc. |
| Nippon Sheet Glass Co., Ltd. |
| Pyroguard |
| Vetrotech Saint-Gobain International AG |
| Glas Trösch |
| POLFLAM |
| SAFTI FIRST |
| Others |
Supply Flow & Price Mechanics
Ninety-day certification backlogs at EN 13501 testing facilities compress margins for glazing fabricators awaiting commercial approval, concentrating pricing power with pre-certified incumbents who can bid immediately on Shanghai and Frankfurt tower projects. This lead-time asymmetry rewards inventory-heavy balance sheets while penalizing smaller fabricators forced to absorb carrying costs during extended qualification windows.
Pricing Analysis
Current-generation ceramic glass commands substantial premiums over legacy wired glass and standard laminated alternatives, while next-generation smart-integrated fire glazing sits at speculative price points awaiting volume validation. Three-tier pricing structure across premium, standard, and economy levels separates BS EN 13501-2 certified systems from ASTM E119 equivalents and uncertified retrofit products. Cost compression in economy-tier laminated configurations is intensifying because REACH-driven interlayer reformulation raises input expenses. Residential property investors exhibit highest price sensitivity, retreating to downgraded ratings where codes permit, while commercial tower developers absorb premium certification costs to transfer liability risk.
Supply Chain Analysis
Germany and China anchor borosilicate ceramic substrate production, with Yangtze River Delta fabricators feeding both domestic high-rise projects and European export contracts facing REACH compliance deadlines. Specialty glass manufacturers draw from concentrated sodium silicate, graphite, and proprietary borosilicate formulations that rest on limited qualified suppliers. Single-source vulnerability concentrates in high-performance ceramic substrate capacity, where three global producers control qualification-grade output. Distribution runs through specification-grade glazing contractors who bundle testing, installation, and maintenance into design-build contracts for mixed-use towers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fire resistant glass market sits in cyclical recovery as commercial construction rebounds across Asia-Pacific and European retrofit mandates trigger replacement cycles for obsolete wired glass installations.
For Market Incumbents: Shield specification-grade market position by accelerating backward integration into borosilicate ceramic supply before input bottlenecks worsen. Cement channel control through exclusive testing laboratory partnerships that compress competitor certification timelines. Prioritize EN 13501-2 plus UL 9 dual certification investments to capture cross-border tower projects where procurement increasingly demands multi-jurisdictional eligibility.
For New Entrants and Emerging Players: UL 9 fast-track certification programs open immediate access to North American commercial tower specifications where incumbent concentration remains below European levels. Target India's Maharashtra and Karnataka state markets where BIS enforcement is tightening but specification-grade penetration lags European benchmarks. Pursue curtain wall engineering firm partnerships as the primary go-to-market angle, embedding fire-rated glazing into single-source procurement contracts that transfer compliance liability.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because EMA-aligned frameworks and evolving EN standards continuously raise performance thresholds that favor technical specialists over commodity producers. Acquisition targets should concentrate on mid-cap fabricators with captive EN 13501-2 certification depth and established curtain wall system integration capabilities. Watch municipal retrofit mandate announcements in Germany's Ruhr Valley and UK's Midlands as the signal for replacement cycle inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrate Supply | Captive borosilicate production insulates margins from specialty manufacturer input bottlenecks. |
| Dual Certification Investment (EN 13501-2 plus UL 9) | Multi-jurisdictional eligibility unlocks cross-border contracts from Singapore to Chicago tower developers. |
| Curtain Wall Engineering Partnership | Single-source procurement integration transfers fire rating compliance liability from architects to glazing contractors. |
| Smart Building Convergence Development | Electrochromic tinting and embedded sensor integration opens premium specification tiers in intelligent building projects. |
| REACH-Compliant Interlayer Reformulation | Elimination of restricted flame retardant additives maintains European market access ahead of enforcement windows. |
Methodological Framework
The analysis maps ceramic glass, laminated configurations, wired glass, and curtain wall integration segments, each validated through specification engineers, glazing contractors, testing laboratory directors, and commercial tower developers. Primary interviews with these stakeholders combined with secondary validation from SAMR GB standards documentation, EMA regulatory filings, BIS certification records, and customs trade data on specialty glass imports. Bottom-up project pipeline analysis triangulates against top-down construction spending forecasts across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs, with segmentation modeling across product type, end user, installation method, and certification jurisdiction. CAGRs derive from fitted growth curves applied to construction permit data and retrofit mandate implementation schedules. Forecast inputs incorporate fire safety code enforcement intensity indices and curtain wall specification penetration rates by metropolitan cluster.
Underlying assumptions cover sustained commercial construction activity in Shanghai, Mumbai, and Frankfurt, with deviation risk concentrated in testing laboratory capacity constraints and REACH amendment implementation timelines. Recalibration cycles align with material shifts in municipal retrofit mandate announcements and EN 13501-2 harmonization progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Cellulosic Fire Protection Market
Fire Safety & Protection
UAE Firefighting Foam Market
Fire Safety & Protection
Fireproof Insulation Market
Fire Safety & Protection
Global Flame Detector Market
Fire Safety & Protection
Fire Department Software Market
Fire Safety & Protection
Global Smoke Evacuation Systems Market
Fire Safety & Protection
Firefighting Hose Market
Fire Safety & Protection
Fire Alarm Systems Market
Fire Safety & Protection
Fire Suppression Agent Market
Fire Safety & Protection
Smart Smoke Alarm Market
Fire Safety & Protection
Smart Smoke Detector Market
Fire Safety & Protection
Global Fire Control System Market
Fire Safety & Protection
Passive Fire Proofing System Market
Fire Safety & Protection
Smoke Detector Market
Fire Safety & Protection
Global Fire Resistant Cable Market
Fire Safety & Protection
Fire Hose Market