
 Global Image Guided Therapy System Market | 2026-2036
Global Image Guided Therapy System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Image Guided Therapy System Market Foresight
Software-defined imaging subscriptions is expanding as the dominant commercial layer, converting capital-intensive hardware sales into recurring revenue streams. Siemens Healthineers leverages its digital twin architecture to sustain long-term client relationships across European hospital networks. GE Healthcare anchors its competitive stance through deep integration of AI-assisted navigation with existing CT and MRI install bases. Koninklijke Philips N.V. differentiates via its hybrid operating room ecosystem that combines real-time ultrasound with interventional planning software.
An image guided therapy system fuses multimodal anatomical and functional imaging with surgical or therapeutic instrumentation, typically achieving spatial resolution below one millimeter for instrument tracking in three-dimensional coordinate space. These systems serve primarily to enable minimally invasive procedures with reduced collateral tissue damage and shorter recovery trajectories. CT-based configurations retain the largest installed base among system types due to their versatility across thoracic and abdominal interventions, while MRI-based platforms command premium positioning in neurosurgical and soft-tissue oncology applications where superior contrast resolution justifies longer procedure times. Among clinical applications, oncology represents the fastest-expanding segment as stereotactic body radiation therapy and MRI-guided focused ultrasound ablation displace conventional open surgical approaches for localized tumors.
The FDA's 510(k) clearance framework governs software updates and algorithm modifications in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for CE marking across European markets. Japan's PMDA maintains distinct technical standards for electromagnetic compatibility and thermal safety that manufacturers must satisfy for market access. Stakeholders must monitor evolving reimbursement thresholds for intraoperative imaging add-on codes, as payor acceptance determines whether health systems can justify premium system acquisitions against constrained capital budgets.
Market Dynamics
Software-as-medical-device business models are restructuring capital deployment patterns across hospital procurement departments, converting upfront equipment purchases into multi-year subscription commitments that compress vendor switching flexibility.
Growth Catalysts
- FDA 510(k) pathway:The streamlined premarket notification framework accelerates algorithm updates for navigation software, reducing time-to-market for enhanced tracking capabilities.
- Hybrid operating room installations:University hospitals in Germany are anchoring procurement volumes for integrated intraoperative imaging suites that combine real-time visualization with surgical robotics.
- Stereotactic body radiation therapy:Oncology departments are displacing open surgical resection for localized tumors, driving system utilization rates in radiation therapy centers.
Market Restraints
- Superconducting magnet supply concentration:Cryogenic cooling system production clusters in a limited set of specialized component suppliers, creating vulnerability in MRI-guided platform manufacturing.
- EU MDR clinical evidence requirements:The Medical Device Regulation imposes extended documentation burdens for CE marking, stretching certification timelines for software updates.
- Fluoroscopy dose exposure limits:Ionizing radiation safety thresholds constrain intraoperative imaging duration during complex interventional procedures.
Strategic Opportunities
- Japan PMDA electromagnetic compatibility standards:Manufacturers satisfying distinct technical requirements for thermal safety gain first-mover positioning in Asia-Pacific's second-largest medical device market.
- MRI-guided focused ultrasound ablation:Soft-tissue oncology applications command premium positioning where superior contrast resolution justifies longer procedure times.
- Payor acceptance of intraoperative imaging add-on codes:Reimbursement threshold expansion enables health systems to justify premium system acquisitions against constrained capital budgets.
Industry Challenges
- Interoperability with legacy PACS infrastructure:Hospital IT departments face integration complexity when connecting modern navigation software to decade-old imaging archives.
- Electromagnetic tracking calibration expertise:Biomedical engineering teams require specialized training to maintain sub-millimeter spatial resolution across diverse surgical environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Image Guided Therapy System Market |
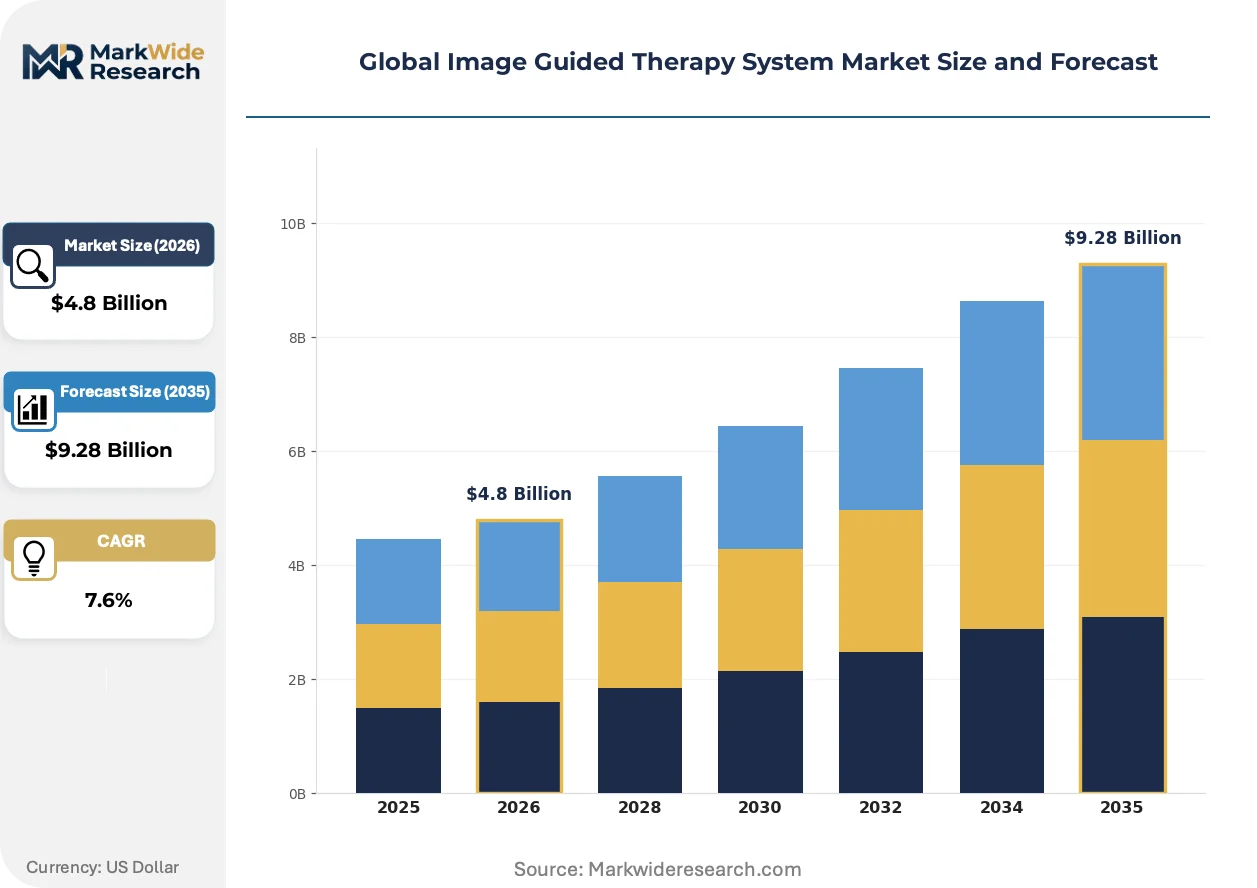
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: MRI-Based, CT-Based, Ultrasound-Based, Fluoroscopy-Based, PET-Based Clinical Application: Neurology, Orthopedics, Cardiology, Oncology, Gastroenterology End User: Hospitals, Ambulatory Surgery Centers, Diagnostic Imaging Centers, Rehabilitation Facilities, Specialized Clinics Deployment Mode: On-Premise, Cloud-Enabled, Hybrid, Standalone, Network-Integrated |
| Companies Covered | Koninklijke Philips N.V., Siemens Healthineers, GE Healthcare, Medtronic, Brainlab AG, Stryker Corporation, Olympus Corporation, Varian Medical Systems, Inc., KARL STORZ SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Image Guided Therapy System Market Shifts & Advancements
Real-time multimodal image fusion is compressing the gap between diagnostic imaging and therapeutic intervention, enabling single-session diagnosis-to-treatment workflows that reshape surgical department economics.
Magnetic resonance-guided focused ultrasound systems are overtaking conventional radiofrequency ablation for uterine fibroid and essential tremor indications. Gynecology and functional neurosurgery departments are prioritizing these platforms for their non-invasive tissue destruction capabilities. The technology is overtaking thermal ablation modalities that require percutaneous probe insertion, reducing infection risk and recovery timelines.
Japan's PMDA maintains distinct electromagnetic compatibility and thermal safety technical standards that manufacturers must satisfy for market access. These requirements create compliance differentiation for vendors investing in localized testing infrastructure. MRI-guided platform developers targeting Asia-Pacific expansion must architect products around PMDA specifications from initial design phases.
Subscription-based software licensing is displacing perpetual purchase models across European hospital networks. Procurement departments favor predictable operational expenditure structures over capital-intensive hardware ownership. Germany's university hospital consortia are negotiating enterprise-wide digital twin access agreements that bundle intraoperative navigation with predictive maintenance analytics.
Global Image Guided Therapy System Market Segmentation
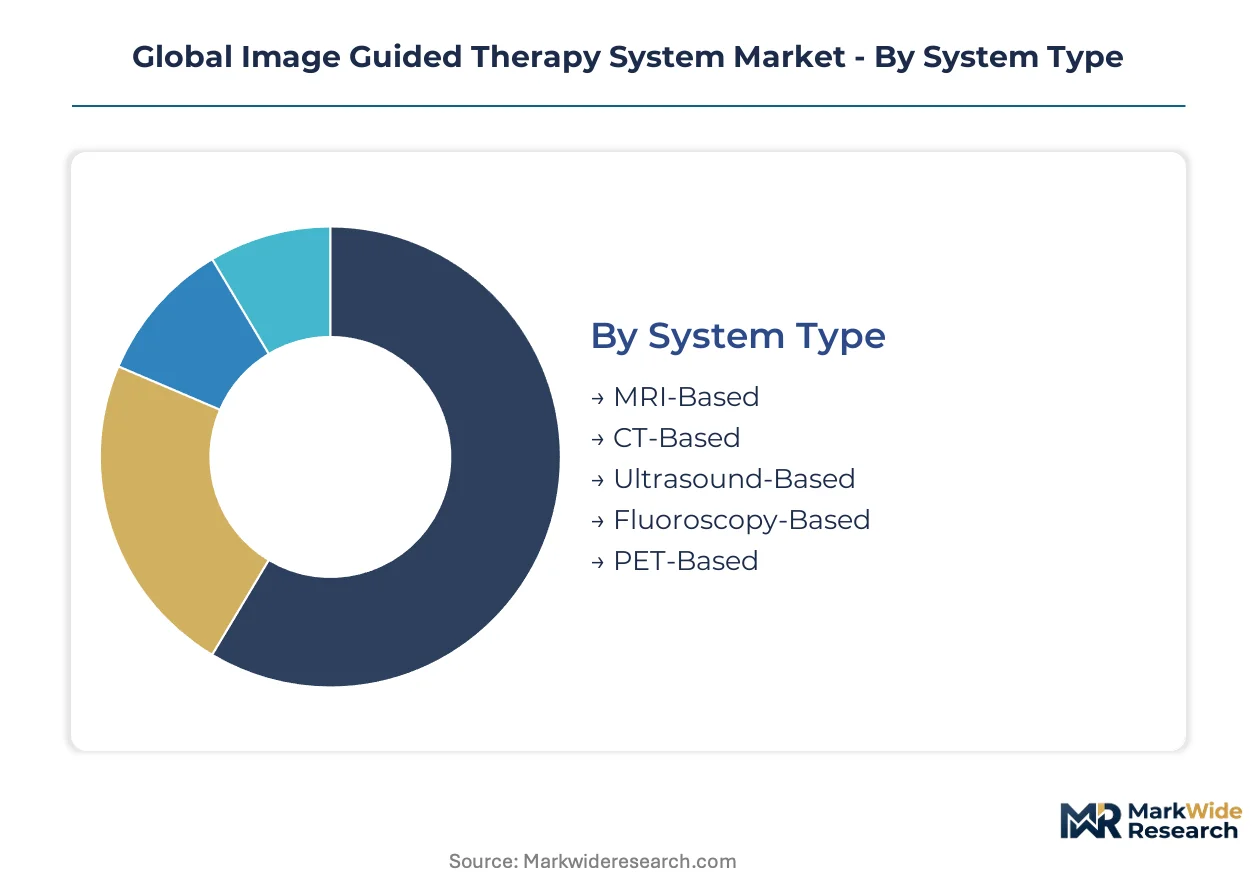
Technology heterogeneity across imaging modalities creates distinct upgrade cycles and replacement economics for procurement departments. Each segment category carries specific integration requirements that determine hospital IT capital allocation priorities and vendor lock-in intensity.
System Type:
Replacement cycles vary dramatically across imaging modalities, with superconducting magnet maintenance costs driving MRI platform refresh decisions while CT gantry mechanical wear dictates shorter hardware lifespans.
- CT-Based:X-ray computed tomography configurations dominate installed base volume through versatility across thoracic and abdominal interventions. Hospital networks in Germany anchor procurement for these systems given their compatibility with existing radiation therapy infrastructure and established reimbursement pathways for intraoperative CT add-on codes.
- MRI-Based:Magnetic resonance platforms command premium positioning through superior soft-tissue contrast resolution essential for neurosurgical navigation. Demand concentrates in university medical centers where longer procedure times justify the capital intensity for functional neurosurgery and soft-tissue oncology applications.
- Ultrasound-Based:Real-time acoustic imaging enables portable guidance without ionizing radiation exposure.
- Fluoroscopy-Based:Continuous X-ray visualization supports interventional cardiology and orthopedic procedures with high temporal resolution.
- PET-Based:Positron emission tomography integration offers metabolic guidance for oncologic interventions requiring functional rather than purely anatomical targeting.
CT-Based sits at the top of the volume ranking, with MRI-Based climbing the fastest.
Clinical Application:
Procedure reimbursement rates and clinical outcome evidence strength determine departmental budget allocation across therapeutic domains, with oncology commanding disproportionate capital share due to stereotactic radiation therapy expansion.
- Oncology:Tumor targeting applications are displacing open surgical resection through stereotactic body radiation therapy and MRI-guided focused ultrasound ablation. Radiation therapy centers in the United States prioritize these systems as FDA 510(k) clearance pathways accelerate algorithm updates for enhanced tracking capabilities.
- Neurology:Functional neurosurgery and deep brain stimulation procedures demand sub-millimeter spatial resolution for instrument tracking in three-dimensional coordinate space. Academic medical centers concentrate demand where superior contrast resolution justifies extended procedure durations for movement disorder interventions.
- Orthopedics:Joint reconstruction and spine procedures utilize navigation for implant positioning accuracy.
- Cardiology:Electrophysiology and structural heart interventions require real-time fluoroscopic guidance with reduced radiation dose protocols.
- Gastroenterology:Endoscopic ultrasound and biliary interventions leverage hybrid imaging approaches for minimally invasive access.
Oncology leads volume concentration, while Neurology gains share fastest through functional neurosurgery platform adoption.
End User:
Capital availability and procedure volume thresholds create tiered adoption patterns, with integrated delivery networks leveraging enterprise purchasing power against independent facility constraints.
- Hospitals:Academic medical centers and community hospital systems anchor procurement volume through hybrid operating room installations. University hospitals in Germany specifically drive integrated intraoperative imaging suite adoption that combines real-time visualization with surgical robotics.
- Ambulatory Surgery Centers:Outpatient procedural facilities concentrate demand for compact, multi-modality platforms with reduced footprint requirements. These settings prioritize CT-based and ultrasound-based configurations that avoid superconducting magnet infrastructure.
- Diagnostic Imaging Centers:Freestanding imaging providers focus on diagnostic-to-interventional workflow integration.
- Rehabilitation Facilities:Post-acute settings utilize navigation for precision injection therapies and pain management procedures.
- Specialized Clinics:Single-specialty practices concentrate on procedure-specific configurations with streamlined training requirements.
Hospitals maintain volume dominance, with Ambulatory Surgery Centers expanding most quickly through outpatient procedure migration.
Deployment Mode:
IT infrastructure maturity and cybersecurity risk tolerance determine architecture selection, with cloud adoption constrained by patient data sovereignty requirements and legacy PACS interoperability complexity.
- On-Premise:Local server installations retain preference among health systems with established biomedical engineering teams and strict data residency policies. Hospital IT departments facing legacy PACS integration complexity favor this architecture for predictable latency in surgical navigation.
- Cloud-Enabled:Subscription-based software licensing converts capital expenditure to operational expenditure structures. European hospital networks particularly favor this model for digital twin access agreements bundling intraoperative navigation with predictive maintenance analytics.
- Hybrid:Mixed architectures segment sensitive processing locally while leveraging cloud for non-critical analytics.
- Standalone:Self-contained systems serve facilities without enterprise network infrastructure or specialized IT support.
- Network-Integrated:Full enterprise connectivity enables centralized scheduling, billing, and quality assurance across multi-site systems.
On-Premise retains volume leadership, with Cloud-Enabled showing the steepest expansion trajectory through software-as-medical-device business model restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting manufacturing investment toward jurisdictions with streamlined device approval pathways, as vendors seek to minimize compliance costs while maintaining market access across major economies.
United States
The FDA's 510(k) premarket notification framework accelerates algorithm updates for navigation software, reducing time-to-market for enhanced tracking capabilities. Hospital networks in Texas and California anchor procurement volumes for hybrid operating room installations. Academic medical centers in Boston and the Bay Area concentrate demand for MRI-guided platforms in functional neurosurgery applications.
Germany
University hospitals in Bavaria and North Rhine-Westphalia drive integrated intraoperative imaging suite adoption that combines real-time visualization with surgical robotics. The EU Medical Device Regulation imposes stricter clinical evidence requirements for CE marking, stretching certification timelines for software updates. Siemens Healthineers leverages its digital twin architecture to sustain long-term client relationships across European hospital networks.
Japan
PMDA electromagnetic compatibility and thermal safety standards create compliance differentiation for vendors investing in localized testing infrastructure. Tokyo and Osaka medical centers concentrate demand for MRI-guided focused ultrasound ablation systems in soft-tissue oncology. Manufacturers satisfying distinct technical requirements gain first-mover positioning in Asia-Pacific's second-largest medical device market.
China
NMPA regulatory harmonization efforts are accelerating market access for multinational imaging system vendors. Shanghai and Beijing hospital consortia prioritize CT-based configurations for thoracic and abdominal interventions. Domestic procurement policies favor systems with localized software development and regional service infrastructure.
India
CDSCO medical device registration requirements are evolving toward risk-based classification alignment with international standards. Metro hospital networks in Maharashtra and Karnataka expand adoption of ultrasound-based guidance for portable interventions without superconducting magnet infrastructure. Price-sensitive procurement favors multi-modality platforms with reduced footprint requirements.
Global Image Guided Therapy System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with diversified health technology conglomerates commanding premium positioning in integrated system sales while focused navigation software vendors capture recurring subscription revenue. The vendor base clusters around three strategic archetypes: imaging modality incumbents leveraging install base dominance, surgical robotics integrators seeking navigation synergies, and pure-play software vendors monetizing algorithmic differentiation. Consolidation pressure intensifies as hardware margins compress and procurement departments favor enterprise-wide vendor relationships over point solutions.
Among imaging-centric conglomerates, Koninklijke Philips N.V., Siemens Healthineers, and GE Healthcare occupy positions defined by their legacy modality strengths and digital platform investments. These entities exemplify the integrated ecosystem archetype, bundling intraoperative navigation with predictive maintenance analytics and enterprise imaging infrastructure. Their competitive positioning rests on converting capital-intensive hardware sales into multi-year subscription commitments that compress vendor switching flexibility across hospital networks.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| GE Healthcare |
| Medtronic |
| Brainlab AG |
| Stryker Corporation |
| Olympus Corporation |
| Varian Medical Systems, Inc. |
| KARL STORZ SE & Co. KG |
| Others |
Supply & Pricing Matrix
EU MDR clinical evidence requirements gate qualified supply access and premium-tier pricing for MRI-guided platforms, compressing margins for vendors unable to absorb extended certification timelines while rewarding Siemens Healthineers and GE Healthcare with pricing power anchored in established CE marking portfolios.
Pricing Analysis
Capacity additions in China and South Korea are reshaping price floors for CT gantry components, intensifying cost competition in mid-tier system configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by magnet field strength and navigation software sophistication, with university hospitals in Germany exhibiting lowest price sensitivity due to bundled digital twin subscriptions while ambulatory surgery centers in India drive volume at economy tiers. Pricing pressure stems from procurement departments converting capital expenditure to multi-year SaaS commitments, compressing upfront hardware premiums.
Supply Chain Analysis
ISO 13485 and FDA 21 CFR Part 820 certification requirements filter component suppliers, concentrating qualified superconducting wire and cryogenic cooling system production in Japan, Germany, and the United States. Helium-3 and niobium-titanium superconductor supply draws from specialized foundries in Tokyo and Aachen, with single-source vulnerability in liquid helium logistics creating bottleneck risk for MRI-guided platform manufacturing. Distribution runs through authorized service networks rather than direct hospital fulfillment, extending lead times for spare parts in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on software-defined imaging subscriptions displacing perpetual licenses, converting one-time equipment sales into recurring revenue streams that improve lifetime customer value and reduce customer acquisition costs.
For Market Incumbents: Deploy digital twin architecture as the anchor lever to deepen hospital network lock-in and defend against pure-play navigation software vendors. Siemens Healthineers and Koninklijke Philips N.V. should accelerate backward integration into predictive maintenance analytics, capturing service revenue that offsets hardware margin compression. Counter emerging entrant threat by pre-empting ambulatory surgery center procurement with compact, multi-modality platforms that avoid superconducting magnet infrastructure requirements. For New Entrants and Emerging Players: AI-assisted real-time image fusion represents the most penetrable technology wedge, given interoperability gaps between legacy PACS infrastructure and modern navigation software. Target ultrasound-based guidance systems for outpatient procedural facilities in India and Southeast Asia, where price-sensitive procurement favors portable configurations without ionizing radiation exposure. Pursue hospital IT department partnerships as primary go-to-market angle, offering seamless legacy system integration that incumbents bundle less aggressively. For Investors and Strategic Acquirers: Roll-up economics work for regional navigation software specialists because hospital procurement departments increasingly favor enterprise-wide vendor relationships over point solutions, creating consolidation tailwinds. Focus acquisition screening on pure-play algorithm developers with FDA 510(k) clearance momentum and established reimbursement code alignment. Watch for inflection in payor acceptance of intraoperative imaging add-on codes as signal that premium system acquisitions will accelerate against constrained capital budgets.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerated clearance for AI navigation algorithms reduces time-to-market in United States hospital networks. |
| CE Marking Pathway | EU MDR compliance investment filters competition and sustains premium pricing for integrated imaging suites. |
| Hospital System Partnership | Enterprise-wide digital twin agreements with German university hospitals convert hardware sales into recurring subscriptions. |
| Software Companion Development | Predictive maintenance analytics bundling deepens client relationships and raises switching costs across European networks. |
| Reimbursement Strategy | CMS add-on code alignment determines whether radiation therapy centers justify premium MRI-guided platform acquisitions. |
Research Methodology
Coverage spans the United States, Germany, Japan, China, and India, with primary inputs from each market gathered through structured interviews with hospital purchasing committee members, biomedical engineering directors, radiation therapy center administrators, GPO contracts managers, and regulatory affairs specialists at imaging system manufacturers. Secondary validation draws from FDA 510(k) databases, EUDAMED CE marking records, NMPA registration filings, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up installed base modeling triangulates against top-down market sizing derived from vendor revenue disclosures and regional healthcare infrastructure investment data.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon, with segmentation modeling spanning system type, clinical application, end user, and deployment mode dimensions plus regional regulatory cluster as an industry-specific layer. CAGRs derive from logistic adoption curve fitting for software-as-medical-device transitions and replacement cycle analysis for hardware refresh patterns. Forecast inputs incorporate PMDA electromagnetic compatibility standard evolution and superconducting magnet supply concentration risk.
The model holds under stable reimbursement policy and superconducting wire supply continuity; deviation in FDA algorithm update pathways or helium supply disruption would shift hardware refresh timing and software subscription penetration trajectories. A model refresh is warranted upon material change in payor acceptance of intraoperative imaging add-on codes or EU MDR clinical evidence requirement enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Spain Nuclear Imaging Market
Medical Imaging
Argentina Digital X-Ray Market
Medical Imaging
Nuclear Imaging Devices Market
Medical Imaging
Brain PET-MRI Systems Market
Medical Imaging
Ultrasound Elastography Systems Market
Medical Imaging
Dental X-Ray Market
Medical Imaging
US Interventional Radiology Market
Medical Imaging
Germany Mammography Market
Medical Imaging
Australia Digital Radiology Market
Medical Imaging
Australia Digital X-Ray Market
Medical Imaging
India Mammography Market
Medical Imaging
Dental Diagnostic Imaging Equipment Market
Medical Imaging
Global Nuclear Imaging Equipment Market
Medical Imaging
South Africa Magnetic Resonance Imaging Market
Medical Imaging
Japan Magnetic Resonance Imaging Market
Medical Imaging
Medical X-Ray Films Market