
 Magnetoencephalography (MEG) Market | 2026-2036
Magnetoencephalography (MEG) Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetoencephalography (MEG) Market Foresight
Project finance and equipment leasing models are tilting competitive dynamics toward vendors capable of offering asset-light deployment structures. Cerca Magnetics Limited leverages its focus on next-generation optically pumped magnetometer systems to compete against legacy superconducting incumbents. MEGIN anchors its position through deep vertical integration in sensor manufacturing and installation services. FieldLine Inc. specializes in compact, cryogen-free architectures that reduce total cost of ownership for research buyers.
Magnetoencephalography measures magnetic fields generated by neuronal electrical activity through superconducting quantum interference device arrays or atomic vapor cell sensors, achieving spatial resolution of 2-3 millimeters and temporal resolution below one millisecond for real-time brain function mapping. Systems dominate installed base value while optically pumped magnetometer technology captures the fastest expansion trajectory as helium supply constraints and cooling infrastructure costs push buyers toward cryogen-free alternatives. Clinical diagnosis applications mature around established epilepsy and tumor resection planning protocols, whereas cognitive studies represent an emerging margin pool as pharmaceutical sponsors fund biomarker validation trials.
FDA 510(k) clearance pathways shape commercialization timelines for clinical MEG systems in the United States, while the EU Medical Device Regulation imposes strengthened conformity assessment requirements on manufacturers serving European hospitals. ISO 13485 quality management certification operates as a baseline market access condition across major jurisdictions. Stakeholders must monitor how reimbursement coding decisions at CMS and parallel national health technology assessment bodies influence hospital capital allocation toward MEG versus competing functional imaging modalities.
Market Dynamics
Optically pumped magnetometer (OPM) technology is compressing installed base economics by eliminating liquid helium dependency and reducing site preparation costs for hospital buyers.
Growth Catalysts
- FDA 510(k) clearance streamlining:The FDA's established pathway for clinical MEG systems accelerates hospital procurement cycles in the United States. Academic medical centers leverage this predictability to secure capital budget approvals.
- Epilepsy surgical planning protocols:Hospital networks in Germany and Japan are embedding MEG into standard pre-surgical workflows for drug-resistant epilepsy cases. This institutionalization drives replacement demand for aging superconducting systems.
- Atomic vapor cell sensor advances:Next-generation OPM arrays achieve sensitivity parity with SQUID systems at ambient temperatures. Research institutions in the United Kingdom are piloting these cryogen-free architectures for pediatric populations.
Market Restraints
- Helium supply chain concentration:Qatar and the United States control over three-quarters of global helium production. Price volatility and export restrictions threaten operating budgets for legacy superconducting MEG installations.
- EU Medical Device Regulation conformity costs:MDR's strengthened clinical evidence requirements extend certification timelines by 18-24 months for European market entrants. Small sensor manufacturers lack resources to navigate notified body bottlenecks.
- Functional MRI substitution in tumor mapping:Hospital radiology departments default to fMRI for pre-surgical language lateralization due to existing infrastructure and reimbursement familiarity. MEG requires specialized technician training that most imaging centers lack.
Strategic Opportunities
- Pharmaceutical biomarker validation trials:CNS drug sponsors in Switzerland are funding MEG-based neurophysiological endpoints for Alzheimer's and depression therapeutics. This creates recurring revenue streams outside traditional hospital sales.
- India's PLI scheme for medical devices:Domestic manufacturing incentives could localize sensor assembly and reduce import duties for South Asian hospital networks. Current installed base in India remains under ten systems.
- Equipment-as-a-service models:Leasing structures with performance-based maintenance clauses lower capital barriers for mid-tier neurology departments in France and Italy. Vendors capture lifetime value through consumables and software subscriptions.
Industry Challenges
- Magnetic shielding engineering expertise:OPM systems require novel active cancellation algorithms and lightweight shielding materials. The talent pool for magnetically clean room design concentrates at fewer than twenty research groups worldwide.
- ISO 13485 certification timelines:Quality management system implementation for OPM-based devices demands 12-18 months of documented design controls. Startups face cash runway compression during this pre-revenue phase.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetoencephalography (MEG) Market |
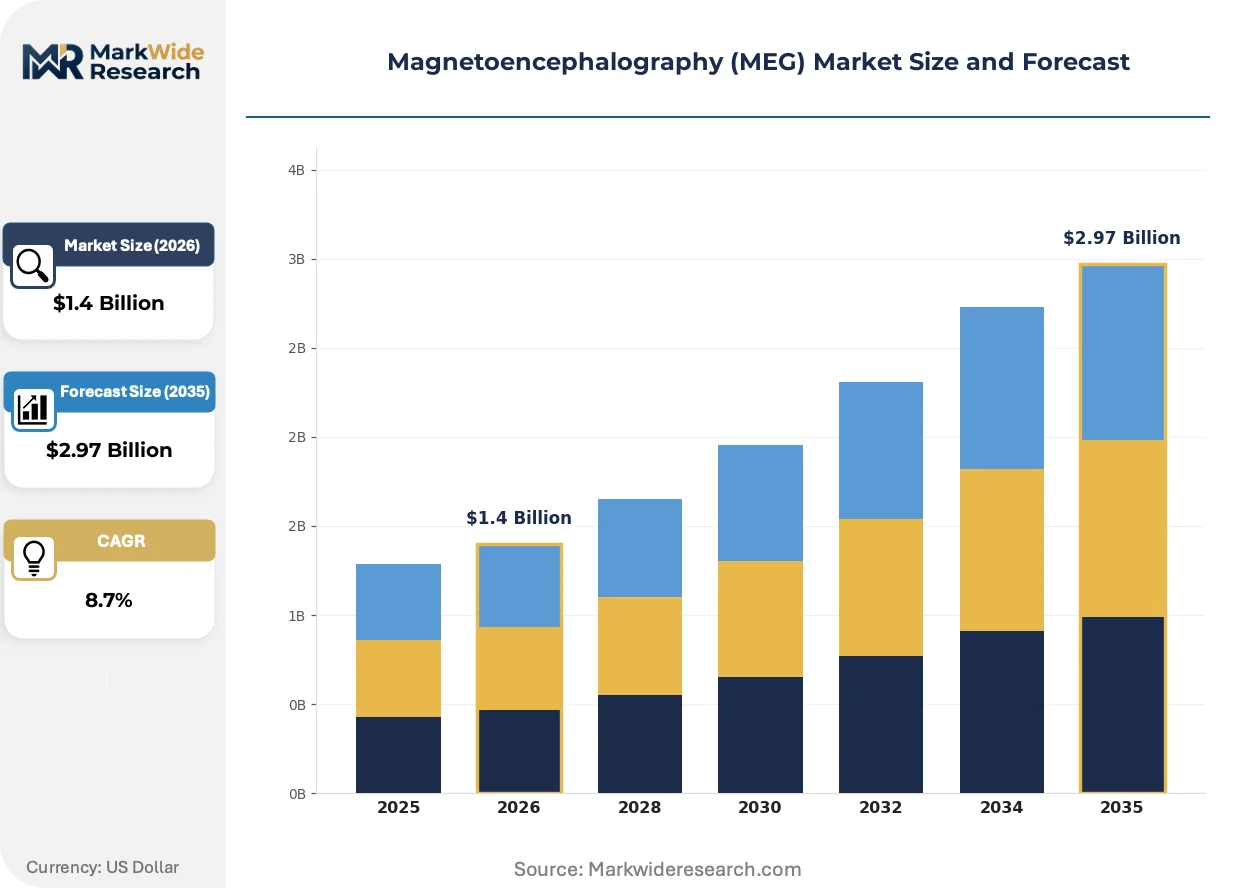
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Systems, Software, Accessories, Services End User: Hospitals, Research Institutions, Universities, Diagnostic Centers Technology: SBET, MEG-EEG Hybrid, Optically Pumped Magnetometers, High-Temperature Superconducting Application: Neuroscience Research, Brain Mapping, Clinical Diagnosis, Cognitive Studies |
| Companies Covered | CTF MEG, Cerca Magnetics Limited, Compumedics Limited, Tristan Technologies, Philips Healthcare, MEGIN, FieldLine Inc., Croton Healthcare, Ricoh, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetoencephalography (MEG) Market Shifts & Advancements
Sensor miniaturization and ambient-temperature operation are redefining deployment economics while regulatory frameworks struggle to keep pace with hardware iteration cycles.
Optically pumped magnetometer arrays are digitizing neuronal magnetic field detection by replacing cryogenic dewar assemblies with chip-scale atomic vapor cells. Pediatric hospitals in Sweden and the Netherlands are adopting these systems for infant epilepsy monitoring where patient motion tolerance is critical. The technology is digitizing patient throughput metrics by enabling seated or supine positioning without rigid head fixation.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is accelerating helium recovery system mandates for existing superconducting installations. German university hospitals face retrofit deadlines that compress replacement decisions into 2026-2028 procurement windows. Manufacturers are responding with trade-in programs that credit residual SQUID array value toward OPM platform purchases.
Academic medical centers are unbundling MEG data analysis from hardware procurement, contracting specialized neuroimaging core facilities for signal processing and source localization. This disintermediation pressures vendors to open software architectures and API access. The pattern is most pronounced in the United States where NIH-funded research centers pool instrumentation across institutional boundaries.
Magnetoencephalography (MEG) Market Segmentation
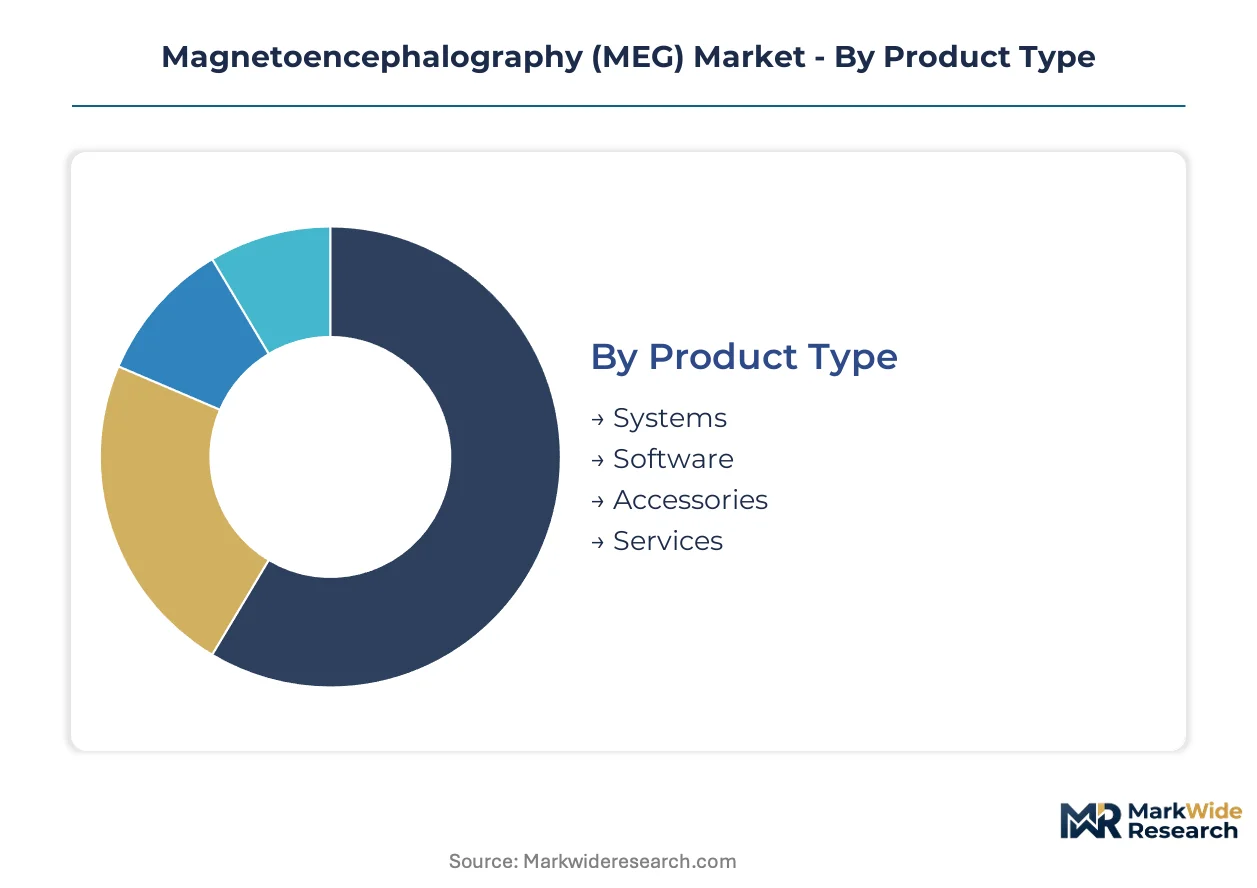
MEG market segmentation reveals divergent service intensity profiles across product tiers, with cryogen-free systems demanding novel maintenance protocols while legacy superconducting installations require specialized helium logistics support.
Product Type:
After-sales-service intensity varies dramatically across product tiers, with systems requiring multi-year field engineering contracts and software generating recurring subscription revenue streams.
- Systems:Superconducting quantum interference device arrays and optically pumped magnetometer platforms constitute capital-intensive hardware procurement. Hospital networks in the United States prioritize FDA 510(k)-cleared installations with bundled installation and magnetic shielding engineering.
- Software:Signal processing suites for source localization and real-time brain mapping command annual licensing fees. Academic medical centers in Germany unbundle analysis tools from hardware, creating standalone procurement categories.
- Accessories:Sensor arrays, dewar components, and patient positioning equipment represent replacement-driven demand.
- Services:Preventive maintenance, helium supply logistics, and technician training contracts extend vendor relationships beyond initial sale.
Systems holds the largest share; momentum sits with Services as equipment-as-a-service models expand.
End User:
Customer archetypes diverge sharply in procurement sophistication, with hospitals demanding regulatory clearance documentation and research institutions prioritizing experimental flexibility.
- Hospitals:Epilepsy surgical planning and pre-operative brain mapping drive capital allocation. German university hospitals embed MEG into standard clinical workflows, creating replacement demand cycles.
- Research Institutions:Cognitive neuroscience and pharmaceutical biomarker studies fund specialized installations. Swiss CNS drug sponsors commission dedicated systems for Alzheimer's and depression therapeutic endpoints.
- Universities:Shared instrumentation cores serve multiple principal investigators across departmental boundaries.
- Diagnostic Centers:Outpatient neurology practices adopt compact OPM systems for ambulatory epilepsy monitoring.
Hospitals dominate installed base value; Diagnostic Centers are expanding most quickly as cryogen-free architectures lower site preparation barriers.
Technology:
Technology selection determines lifetime operating economics, with cooling infrastructure requirements separating capital-light from capital-heavy deployment models.
- Optically Pumped Magnetometers:Chip-scale atomic vapor cells eliminate liquid helium dependency entirely. Pediatric hospitals in Sweden adopt these ambient-temperature systems for infant monitoring where patient motion tolerance is critical.
- SBET:Superconducting biomagnetometer equipment technology represents the established installed base with proven sensitivity specifications. Legacy installations in Japan face helium supply chain concentration risks from Qatar and United States export restrictions.
- MEG-EEG Hybrid:Combined magnetic and electrical recording systems improve source localization accuracy through multimodal data fusion.
- High-Temperature Superconducting:Reduced cooling requirements compared to conventional SQUID arrays offer intermediate total cost of ownership.
SBET retains the largest installed base; Optically Pumped Magnetometers are gaining share fastest as helium price volatility accelerates replacement decisions.
Application:
Application mix shifts with reimbursement coding decisions, with clinical procedures commanding premium pricing versus research contracts requiring volume discounting.
- Clinical Diagnosis:FDA-cleared protocols for epilepsy and tumor resection planning anchor hospital procurement justifications. Academic medical centers in the United States leverage CMS reimbursement familiarity to secure capital budget approvals.
- Brain Mapping:Pre-surgical language and motor cortex localization supports neurosurgical planning workflows. German hospital networks standardize MEG for drug-resistant epilepsy cases.
- Neuroscience Research:Basic science investigations into neural oscillations and network dynamics fund academic installations.
- Cognitive Studies:Pharmaceutical-sponsored biomarker validation trials create recurring revenue outside traditional hardware sales.
Clinical Diagnosis commands the largest revenue pool; Cognitive Studies show the steepest expansion trajectory as CNS drug development pipelines prioritize neurophysiological endpoints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEG equipment flows disproportionately into advanced healthcare systems with established neurosurgical infrastructure. The United States, Germany, and Japan absorb the majority of high-value installations, while helium supply constraints redirect procurement toward cryogen-free architectures in import-dependent markets.
United States
Academic medical centers in Boston and Houston anchor procurement volumes for epilepsy surgical planning. FDA 510(k) clearance pathways compress hospital capital approval cycles. The Cleveland Clinic and Mayo Clinic networks standardize MEG protocols for drug-resistant epilepsy cases.
Germany
University hospitals in Munich and Berlin embed MEG into routine pre-surgical workflows for tumor resection. EU Medical Device Regulation conformity assessments extend certification timelines for new entrants. The German university hospital sector drives replacement demand for aging superconducting systems.
Japan
Metropolitan Tokyo and Osaka clusters concentrate installed base value for cognitive neuroscience research. METI funding programs support domestic sensor manufacturing capabilities. National university hospitals face helium supply vulnerability from Qatar and United States export concentration.
United Kingdom
Pediatric hospitals in London and Manchester pilot optically pumped magnetometer systems for infant monitoring applications. NHS England technology assessment processes influence capital allocation toward cryogen-free alternatives. The University of Nottingham anchors OPM research translation.
India
PLI scheme incentives for medical devices could localize sensor assembly for South Asian hospital networks. CDSCO regulatory pathways remain underdeveloped for advanced neuroimaging equipment. Current installed base concentrates at All India Institute of Medical Sciences in Delhi and Christian Medical College in Vellore.
Magnetoencephalography (MEG) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in sensor manufacturing and magnetic shielding engineering. The vendor base concentrates around legacy superconducting incumbents and emerging cryogen-free challengers. Two strategic archetypes dominate: vertically integrated hardware manufacturers with captive installation services, and technology licensors supplying atomic vapor cell arrays to third-party integrators. Competitive moves center on trade-in programs for helium-dependent legacy systems and equipment-as-a-service leasing structures with performance-based maintenance clauses.
Among the named participants, CTF MEG and MEGIN occupy positions as established platform providers with deep vertical integration into sensor manufacturing. Cerca Magnetics Limited and FieldLine Inc. exemplify the cryogen-free specialization archetype, while Philips Healthcare anchors the diversified medical imaging conglomerate tier. Compumedics Limited, Tristan Technologies, Ricoh, and Croton Healthcare represent regional specialists and technology component suppliers serving niche installation footprints.
| Leading Market Players |
|---|
| CTF MEG |
| Cerca Magnetics Limited |
| Compumedics Limited |
| Tristan Technologies |
| Philips Healthcare |
| MEGIN |
| FieldLine Inc. |
| Croton Healthcare |
| Ricoh |
| Others |
Supply & Pricing Matrix
Qatar's helium export concentration shapes cost structures for legacy superconducting MEG systems, amplifying pricing power for cryogen-free alternatives as hospital buyers absorb volatile operating budgets.
Pricing Analysis
Hospital procurement teams anchor equipment pricing through multi-year service bundling and FDA 510(k) tier premiums. Pricing stratifies across superconducting legacy systems, hybrid configurations, and OPM-native platforms differentiated by helium independence and site preparation requirements. Cost compression in the legacy tier intensifies as Qatar supply constraints elevate operating expenditures. Academic medical centers in Germany and Japan show lowest price sensitivity due to institutionalized reimbursement pathways; mid-tier neurology departments in France and Italy face acute capital constraints.
Supply Chain Analysis
Extended payment terms from sensor manufacturers to magnetic shielding engineering firms stabilize working capital for OPM system integrators. Component manufacturing concentrates in the United States, Japan, and Germany for atomic vapor cells, superconducting arrays, and cryogenic dewar assemblies. Raw material dependencies span liquid helium, niobium-titanium superconducting wire, and specialized optical coatings. Single-source vulnerability sits with helium refining infrastructure. Distribution runs through hospital GPO contracts and academic medical center shared instrumentation cores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment: FDA 510(k) clearance timelines and ISO 13485 certification barriers protect incumbent positions against rapid displacement.
For Market Incumbents: Insulate installed base value through trade-in programs crediting residual SQUID array value toward OPM platform conversions. Deepen backward integration into atomic vapor cell manufacturing to capture margin from emerging cryogen-free demand. The threat of FieldLine Inc. and Cerca Magnetics Limited challenging with asset-light deployment models demands preemptive channel control through equipment-as-a-service leasing structures. For New Entrants and Emerging Players: India's underpenetrated hospital network offers white-space expansion with fewer than ten installed systems nationwide. CDSCO regulatory pathway development lags, creating first-mover advantage for domestic assembly partnerships under PLI scheme incentives. Target pediatric epilepsy monitoring applications where OPM motion tolerance commands premium positioning. Commission pilot installations at Christian Medical College Vellore to generate clinical evidence for hospital procurement committees. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component specialists with captive sensor manufacturing and magnetic shielding engineering capabilities. Long-term viability rests on pharmaceutical biomarker validation trial revenue streams diversifying beyond hospital capital equipment cycles. The signal to monitor is CMS reimbursement coding decisions for MEG-based neurophysiological endpoints, which would inflect hospital capital allocation toward functional imaging modality competition.| Strategic Initiative | Industry Significance |
|---|---|
| OPM Platform Migration Program | Helium supply volatility accelerates hospital replacement decisions toward cryogen-free architectures. |
| Pharmaceutical Biomarker Partnership | CNS drug sponsors in Switzerland fund recurring MEG-based endpoint validation trials. |
| Equipment-as-a-Service Leasing | Performance-based maintenance clauses lower capital barriers for mid-tier neurology departments. |
| Magnetic Shielding Engineering Acquisition | Talent scarcity in active cancellation algorithms concentrates at fewer than twenty research groups. |
| India PLI Localization | Domestic sensor assembly reduces import duties for South Asian hospital network expansion. |
Research Methodology
Cross-validation between primary interviews with hospital purchasing committees and secondary analysis of FDA 510(k) filings anchors the qualitative findings. Stakeholder engagement spanned biomedical engineers at academic medical centers, GPO contracts managers, and regulatory affairs leads at sensor manufacturers. Secondary sources included CMS reimbursement databases, EU MDR notified body documentation, and METI funding program disclosures. Bottom-up installed base enumeration triangulated against top-down capital expenditure flows from hospital network financial disclosures.
Calibration against historical replacement cycles for superconducting systems and OPM adoption trajectories shaped the analytical framework. Segmentation dimensions modeled technology type, end-user archetype, application protocol, and geographic regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating helium price volatility and reimbursement coding probability. Industry-specific inputs included pediatric motion tolerance requirements and pharmaceutical sponsor funding pipeline visibility.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by cryogen-free challengers or accelerated FDA clearance streamlining would shift outcomes. Macroeconomic deviation in hospital capital budgets, regulatory disruption from EU MDR enforcement, or breakthrough advances in fMRI substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Portable Ultrasound Market
Medical Imaging
China VNA and PACS Market
Medical Imaging
Medical X-Ray Films Market
Medical Imaging
Spain Computed Tomography Market
Medical Imaging
3D Medical and Surgical Imaging Market
Medical Imaging
Weightbearing Low Dose (CT) Systems Market
Medical Imaging
Germany Computed Tomography Market
Medical Imaging
Australia Magnetic Resonance Imaging Market
Medical Imaging
Forensic Imaging Market
Medical Imaging
Argentina Nuclear Imaging Market
Medical Imaging
Malaysia Digital Radiography Market
Medical Imaging
Digital X-Ray Imaging Market
Medical Imaging
South Korea Nuclear Imaging Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Equipment Market
Medical Imaging
Diagnostic Imaging Services Market
Medical Imaging
Global Cardiac Imaging Software Market