
 Global Doppler Ultrasound Systems Market | 2026-2036
Global Doppler Ultrasound Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Doppler Ultrasound Systems Market Foresight
Semiconductor-grade silicon is realigning transducer manufacturing economics as piezoelectric crystal suppliers face cost volatility. GE Healthcare leverages backward integration into probe assembly to sustain margin control across portable system lines. Siemens Healthineers anchors European hospital procurement through long-term service contracts bundled with spectral Doppler hardware. Koninklijke Philips N.V. dominates North American cardiology departments with advanced 4D Doppler imaging platforms.
A Doppler ultrasound system employs the frequency-shift principle to detect and quantify blood flow velocity, typically operating at transducer frequencies between two and fifteen megahertz depending on tissue penetration requirements. These systems generate real-time hemodynamic data that clinicians use to diagnose stenosis, thrombosis, and valvular dysfunction without ionizing radiation exposure. Color Doppler imaging commands the largest revenue pool among product types due to its ubiquity in obstetric and cardiac screening protocols, while 3D Doppler technology represents the fastest-expanding segment as interventional cardiologists adopt volumetric flow mapping for procedural guidance. Vascular applications generate concentrated demand from outpatient diagnostic centers seeking to replace traditional angiography for initial disease assessment.
The FDA enforces premarket notification requirements under 21 CFR 892.1550 for ultrasonic pulsed Doppler imaging systems, while the EU Medical Device Regulation mandates clinical evidence documentation for Class IIa and above Doppler equipment sold in member states. ISO 10993 biocompatibility testing governs transducer materials that contact patient skin during prolonged examinations. Stakeholders must monitor how cybersecurity patch mandates from the FDA interact with legacy system upgrade cycles in installed bases across multiple geographies.
Market Dynamics
Portable Doppler systems are absorbing capital allocation from fixed-installation platforms as cardiology departments prioritize point-of-care velocity over imaging suite throughput.
Growth Catalysts
- EU MDR Class IIa mandates:Clinical evidence requirements for spectral Doppler hardware are accelerating hospital laboratory retrofit cycles across Germany and France.
- Semiconductor-grade silicon:Transducer manufacturing economics are realigning as piezoelectric crystal suppliers face input cost volatility.
- Outpatient diagnostic centers:Vascular applications concentrate demand for non-invasive initial disease assessment protocols.
Market Restraints
- Piezoelectric crystal supply concentration:Specialty material sourcing bottlenecks in East Asian processing facilities create transducer production fragility.
- FDA cybersecurity patch mandates:Legacy system upgrade cycles face friction against installed base inertia across multi-site hospital networks.
- Angiography substitution ceiling:Confirmatory diagnostic protocols in interventional suites limit Doppler penetration for definitive stenosis grading.
Strategic Opportunities
- India tertiary hospital expansion:Vascular laboratory buildouts in tier-two cities present equipment installation white space.
- 3D volumetric flow mapping:Interventional cardiology procedural guidance applications are opening premium platform demand.
- ISO 10993 biocompatibility pathways:Extended skin-contact transducer materials certification creates differentiated supply positioning.
Industry Challenges
- Spectral Doppler technician certification:Specialized hemodynamic interpretation skills shortages constrain laboratory throughput expansion.
- Multi-frequency probe integration:Legacy 2-15 MHz system architectures complicate software-defined transducer upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Doppler Ultrasound Systems Market |
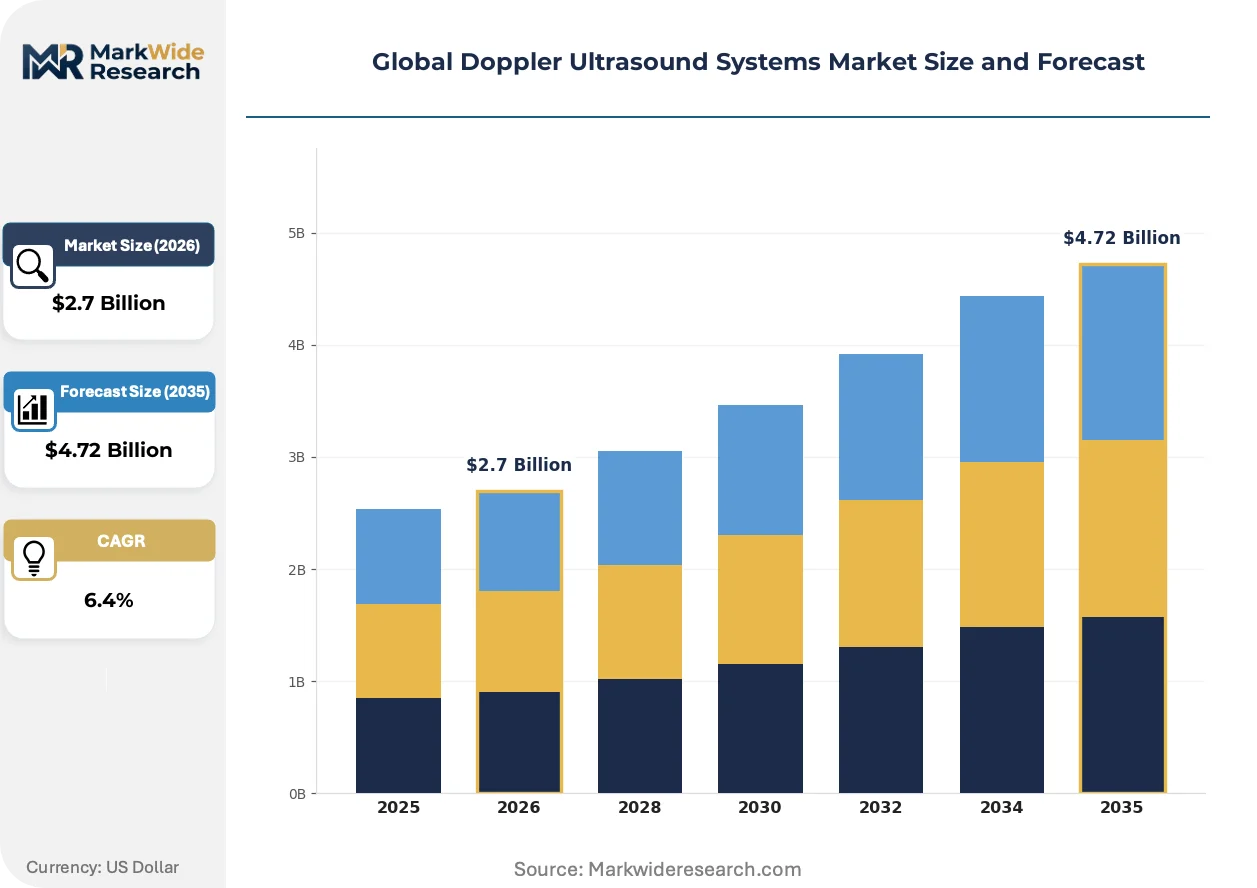
| Market Size in 2026 | $2.7 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Wave, Pulsed Wave, Color Doppler, Power Doppler, Spectral Doppler Application Area: Cardiology, Obstetrics & Gynecology, Neurology, Vascular, Musculoskeletal End User: Diagnostic Centers, Ambulatory Surgery Centers, Specialty Clinics, Academic Institutions Technology: 3D Doppler, 4D Doppler, Duplex Doppler, Triplex Doppler |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips N.V., Fujifilm Holdings Corporation, Esaote SpA, Canon Medical Systems, Hitachi Ltd., Samsung Medison Co., Ltd, Mindray Medical International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Doppler Ultrasound Systems Market Shifts & Advancements
Three simultaneous vectors are compressing product lifecycles: silicon transducer materials, cybersecurity-by-design architectures, and unbundled service contracting.
Semiconductor-grade silicon is absorbing the functional role of conventional piezoelectric crystals in next-generation probe assemblies. University hospitals in Germany are piloting these transducers for spectral Doppler retrofits. The technology is absorbing margin pressure from volatile rare-earth supply chains while enabling software-tunable frequency bands.
REACH substance restrictions are forcing reformulation of transducer housing polymers and acoustic coupling gels across EU member states. Manufacturers must resubmit technical documentation for CE-marked devices. Portable system lines face the steepest compliance timeline compression due to shorter development cycles.
Long-term service contracts are fragmenting into modular subscription tiers across North American cardiology departments. Siemens Healthineers anchors European procurement through bundled hardware-maintenance packages. Germany's university hospital networks exhibit the most pronounced preference for unbundled preventive maintenance agreements.
Global Doppler Ultrasound Systems Market Segmentation
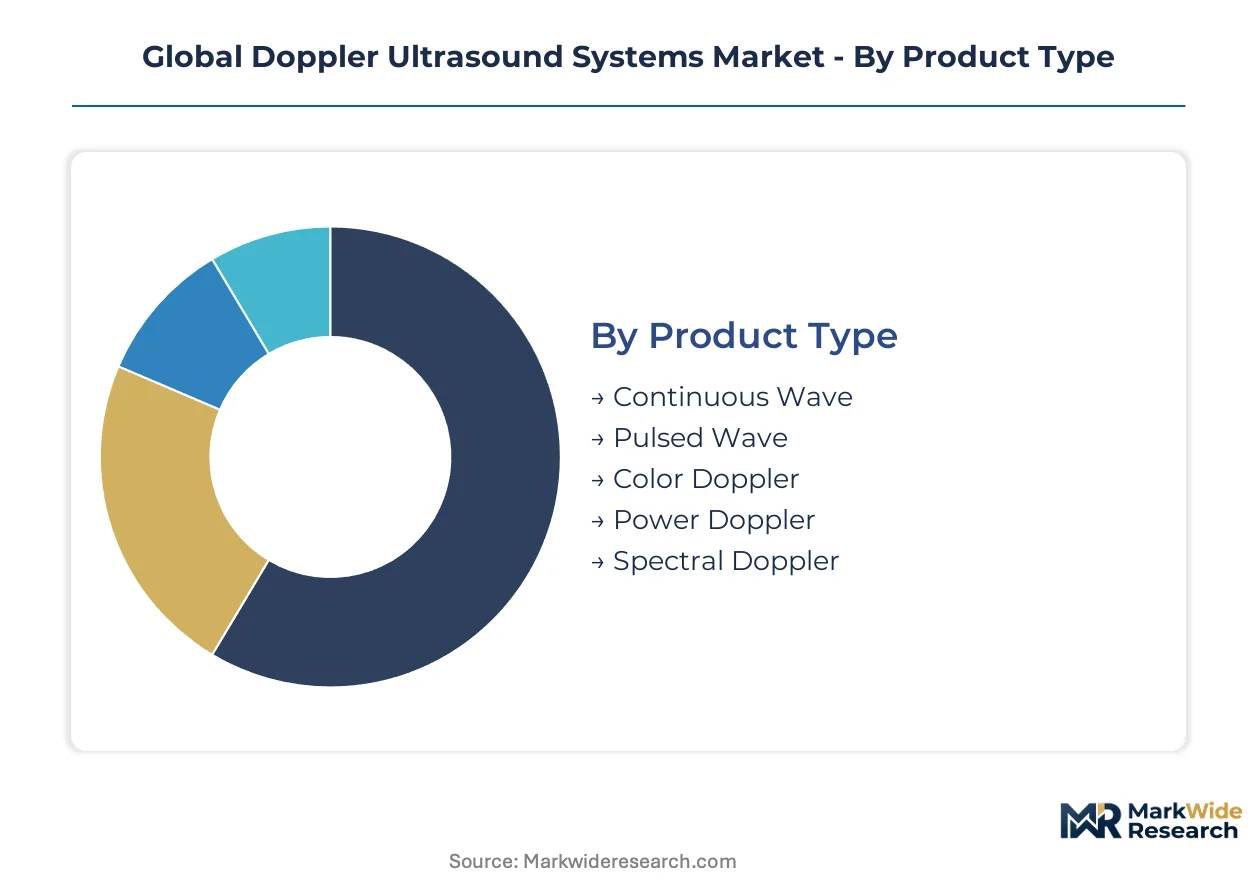
Segmentation in Doppler ultrasound reveals how procurement priorities diverge across clinical settings. Product type and technology choices reflect trade-offs between diagnostic depth and operational throughput, while end-user categories expose divergent capital deployment timelines.
Product Type:
Buyer differentiation hinges on whether the priority is real-time visualization or quantitative hemodynamic measurement.
- Color Doppler:This modality overlays flow velocity data onto anatomical grayscale images using phase-shift detection across thousands of sample volumes. Obstetric departments in Germany's university hospitals prioritize Color Doppler for fetal cardiac screening protocols, though spectral resolution limitations constrain its use in precise stenosis grading.
- Spectral Doppler:The system displays frequency-shift spectra as velocity-time waveforms, enabling calculation of resistive indices and pressure gradients. Vascular laboratories in France are retrofitting with spectral capabilities to meet EU MDR Class IIa clinical evidence mandates for quantified flow assessment.
- Continuous Wave:Employs separate transmit and receive crystals to measure high-velocity flows without aliasing artifacts.
- Pulsed Wave:Uses time-gated sampling to isolate flow signals from specific anatomical depths.
- Power Doppler:Displays flow amplitude rather than velocity or direction, improving sensitivity to low-flow states.
Volume sits with Color Doppler; growth tilts toward Spectral Doppler.
Application Area:
Clinical workflow constraints determine whether departments prioritize portability or imaging suite integration.
- Cardiology:Demand concentrates in point-of-care velocity measurement for valvular dysfunction assessment. Outpatient diagnostic centers in the United States are absorbing portable Doppler units to reduce catheterization lab referrals.
- Vascular:Applications span carotid, peripheral, and abdominal vessel assessment with emphasis on stenosis detection. Specialty clinics in India are building vascular laboratories to replace traditional angiography for initial disease screening.
- Obstetrics & Gynecology:Fetal cardiac and uterine artery flow assessment dominates procurement.
- Neurology:Transcranial Doppler applications focus on cerebral vasospasm monitoring.
- Musculoskeletal:Emerging use in inflammatory arthritis and soft tissue perfusion evaluation.
Revenue concentrates in cardiology; the steepest expansion trajectory belongs to vascular applications.
End User:
Capital availability and patient throughput expectations create distinct purchasing patterns across facility types.
- Diagnostic Centers:These facilities prioritize high-volume vascular screening with rapid turnaround protocols. Centers in tier-two Indian cities are installing spectral Doppler hardware to capture referrals from overstretched tertiary hospitals.
- Academic Institutions:Research-active university hospitals drive adoption of 3D volumetric flow mapping for interventional cardiology training. German institutions are unbundling preventive maintenance contracts to preserve equipment upgrade flexibility.
- Ambulatory Surgery Centers:Focus on pre-operative venous thrombosis screening with compact portable systems.
- Specialty Clinics:Cardiology and obstetrics practices favor dedicated single-application devices.
Procurement volume favors diagnostic centers; contract structures are shifting fastest in academic institutions.
Technology:
Software-defined architectures are compressing hardware refresh cycles across technology tiers.
- 3D Doppler:Volumetric acquisition enables offline reconstruction of flow dynamics from any plane. Interventional cardiologists in North American teaching hospitals are adopting 3D platforms for procedural guidance, though computational demands extend examination times.
- 4D Doppler:Adds temporal resolution to volumetric imaging for real-time flow visualization. Koninklijke Philips N.V. has captured premium positioning in this segment through advanced cardiac imaging platforms deployed across United States cardiology departments.
- Duplex Doppler:Combines grayscale imaging with spectral or color flow analysis in integrated display.
- Triplex Doppler:Simultaneously displays grayscale, color, and spectral data for comprehensive assessment.
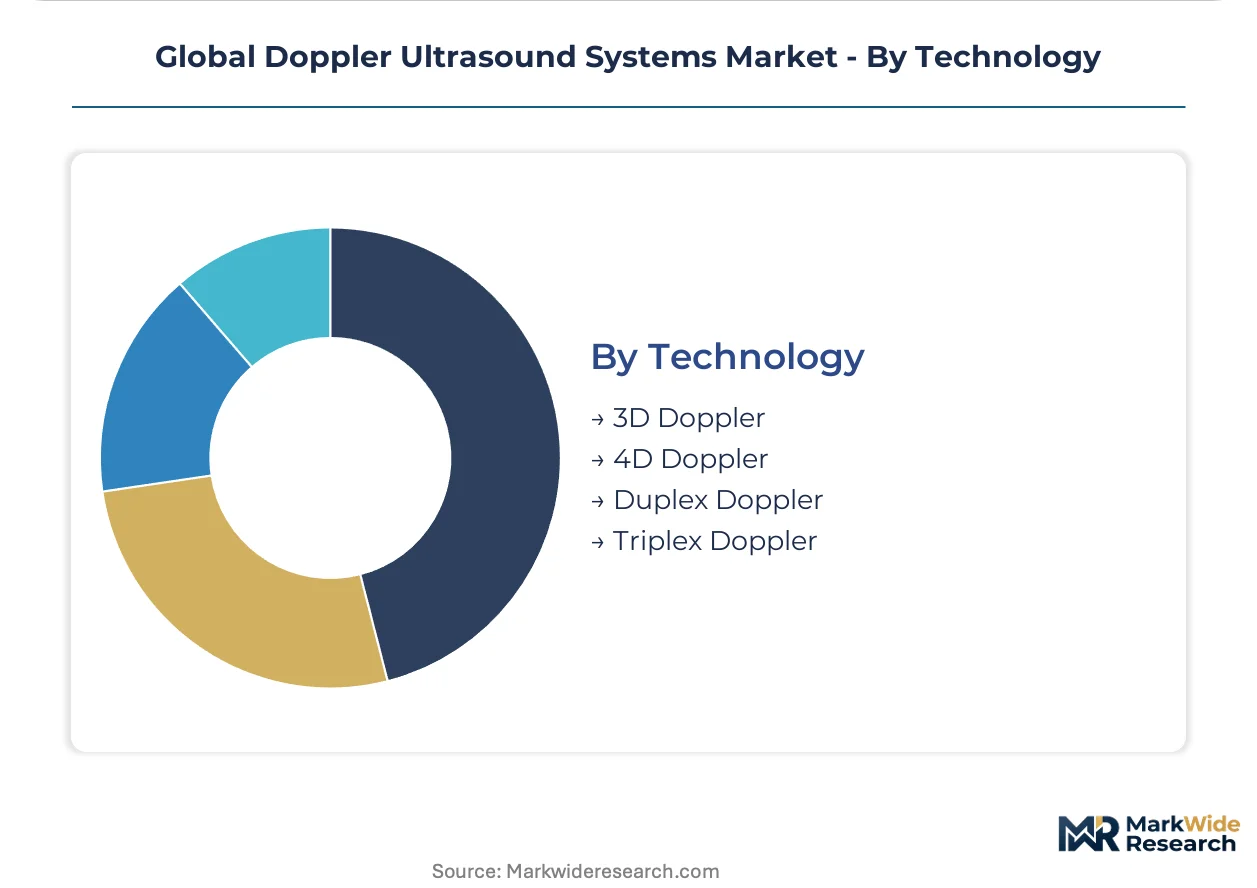
Installed base remains concentrated in Duplex systems; upgrade urgency is greatest for 4D Doppler.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Hamburg concentrate transducer manufacturing and vascular laboratory equipment distribution respectively, creating divergent procurement corridors across major economies.
United States
Cardiology departments in tertiary hospitals are absorbing portable Doppler units for point-of-care valvular assessment. The FDA's updated medical device cybersecurity guidance under 21 CFR 892.1550 is compelling encryption protocol integration into new system architectures. Boston's academic medical centers are retrofitting spectral Doppler capabilities to reduce catheterization lab referrals.
Germany
University hospitals in Bavaria and North Rhine-Westphalia are retrofitting vascular laboratories with spectral Doppler hardware to meet EU MDR Class IIa clinical evidence mandates. REACH substance restrictions are forcing transducer housing polymer reformulations across CE-marked device portfolios. The Eindhoven-Frankfurt medical technology corridor is absorbing silicon-based transducer pilot programs.
India
Diagnostic centers in tier-two cities including Pune and Ahmedabad are building vascular laboratories to capture referrals from overstretched tertiary hospitals. The CDSCO's medical device registration requirements are accelerating quality certification timelines for imported spectral Doppler equipment. Maharashtra's hospital networks are prioritizing unbundled preventive maintenance contracts to preserve upgrade flexibility.
Japan
Academic medical institutions in Tokyo and Osaka are adopting 3D volumetric flow mapping platforms for interventional cardiology training protocols. PMDA premarket approval processes for Class II medical devices are extending lead times for foreign manufacturers. The Kansai region's university hospitals are piloting semiconductor-grade silicon transducers for spectral Doppler applications.
China
Provincial hospital networks in Shanghai and Guangdong are expanding point-of-care Doppler deployment for vascular screening programs. NMPA medical device registration requirements under the 2021 revised regulations are mandating local clinical trial data for Class II ultrasound systems. The Yangtze River Delta manufacturing cluster is absorbing domestic transducer assembly capacity to reduce import dependency.
Global Doppler Ultrasound Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated control over premium 4D imaging platforms coexisting with fragmented competition in portable system lines. The vendor base organizes into three strategic archetypes: diversified conglomerates with healthcare divisions, pure-play ultrasound specialists, and emerging Asian manufacturers with cost-optimized portfolios. Capacity expansion in transducer assembly and strategic partnerships for software-defined imaging architectures represent the dominant competitive moves across tiers.
Within the diversified healthcare conglomerate tier, GE Healthcare, Siemens Healthineers, and Koninklijke Philips N.V. occupy positions that exemplify backward integration into probe assembly and long-term service contracting strategies. These Netherlands, German, and US-origin entities anchor procurement relationships through bundled hardware-maintenance packages across North American and European hospital networks.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Fujifilm Holdings Corporation |
| Esaote SpA |
| Canon Medical Systems |
| Hitachi Ltd. |
| Samsung Medison Co., Ltd |
| Mindray Medical International Limited |
| Others |
Supply & Pricing Matrix
Diversified healthcare conglomerates with captive probe assembly operations exercise asymmetric pricing power over pure-play competitors lacking backward integration into transducer manufacturing. Their bundled hardware-maintenance contracts across North American and European hospital networks create pricing discipline that resists spot-market volatility in piezoelectric crystal inputs.
Pricing Analysis
Premium positioning for short lead times commands substantial markups over standard-delivery contracts, while spot inventory liquidation triggers aggressive discounting in portable system lines. Three-tier pricing structure across premium 4D imaging, standard spectral Doppler, and economy portable units stratifies by certification tier and after-sales bundling intensity. Cost compression in economy portable tiers is intensifying because semiconductor-grade silicon transducers are displacing legacy piezoelectric architectures. Outpatient diagnostic centers exhibit the highest price sensitivity due to capital constraints, while academic medical centers prioritize performance specifications over unit economics.
Supply Chain Analysis
ISO 10993 biocompatibility certification and FDA 21 CFR 892.1550 premarket notification requirements gate transducer assembly access, creating qualification barriers for new component suppliers. Manufacturing concentrates in Germany, China, and the United States, with specialized piezoelectric crystal processing anchored in East Asian facilities. Raw material dependencies include semiconductor-grade silicon wafers, rare-earth piezoelectric ceramics, and acoustic coupling gel polymers. Single-source vulnerability in specialty crystal suppliers exposes production schedules to geographic concentration risk. Distribution runs through hospital procurement committees and group purchasing organizations in developed markets, alongside direct tender participation by provincial health authorities in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Doppler ultrasound market sits in a technology-transition phase as semiconductor-grade silicon transducers displace conventional piezoelectric crystal architectures, compressing legacy system margins while opening premium positioning for software-tunable frequency platforms.
For Market Incumbents: Anticipate margin erosion in fixed-installation platforms by accelerating backward integration into silicon transducer probe assembly. Defensive consolidation through long-term service contract extension with German university hospital networks preserves installed base loyalty against emerging Asian cost-optimized competitors. Priority investment in cybersecurity-by-design architectures addresses FDA patch mandate compliance before legacy system upgrade friction hardens customer switching costs. For New Entrants and Emerging Players: Begin with vascular laboratory buildouts in India's tier-two cities where spectral Doppler penetration remains underdeveloped and procurement committees prioritize unbundled preventive maintenance flexibility. White space concentrates in portable point-of-care systems for cardiology departments seeking to reduce catheterization lab referral volumes. Go-to-market execution through direct tender participation with Maharashtra's hospital networks bypasses established distributor relationships. For Investors and Strategic Acquirers: Siemens Healthineers' unbundling of preventive maintenance contracts in German academic institutions is the leading indicator that service revenue fragmentation will accelerate across European procurement. Long-term viability over the next decade hinges on software-defined transducer capabilities rather than hardware refresh cycles. Acquisition targets should screen for ISO 10993 certification pathways and silicon probe assembly competencies. Watch for CDSCO quality certification timeline compression in India as the signal for emerging market premiumization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor-Grade Silicon Transducer Development | Absorbs margin pressure from volatile rare-earth supply chains while enabling software-tunable frequency bands. |
| Cybersecurity-by-Design Architecture Integration | FDA 21 CFR 892.1550 encryption mandates compel embedded protocol adoption across new system lines. |
| EU MDR Class IIa Clinical Evidence Pathway | German university hospital retrofit cycles accelerate for spectral Doppler hardware compliance. |
| Unbundled Preventive Maintenance Contracting | Academic institutions in Germany and India prioritize upgrade flexibility over bundled hardware-service packages. |
| 3D Volumetric Flow Mapping Platform Launch | Interventional cardiology procedural guidance applications open premium demand in North American teaching hospitals. |
Research Methodology
Multi-period observation of hospital procurement database entries, GPO contract awards, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committee members, vascular laboratory directors, and GPO contracts managers. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR technical documentation repositories, CDSCO medical device registration records, and hospital capital expenditure disclosures. Bottom-up equipment installation tracking across diagnostic centers and academic institutions triangulated against top-down manufacturer revenue segmentation.
Input-output matrices mapped transducer frequency specifications, software architecture generations, and service contract structures to end-user facility types across the projection horizon. Segmentation dimensions modeled included product type, application area, end-user category, technology tier, and regional regulatory cluster. CAGRs were derived from installed base evolution, replacement cycle compression, and penetration rate trajectories. Forecast inputs incorporated semiconductor material cost curves and cybersecurity compliance cost burdens specific to medical device architectures.
Piezoelectric crystal supply disruption, FDA cybersecurity enforcement escalation, and REACH substance restriction expansion are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding hospital capital allocation priorities and technology substitution elasticities. A model refresh is warranted upon material change in silicon transducer yield rates or EU MDR clinical evidence interpretation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ultrasound Transducers Market
Medical Devices
Global Laparoscopy Devices Market
Medical Devices
Global Motion Preservation Devices Market
Medical Devices
Leadless Pacemakers Market
Medical Devices
Global Hernia Repair Devices Market
Medical Devices
Transilluminators Market
Medical Devices
Implantable Pump Catheter Market
Medical Devices
Smart Patches Market
Medical Devices
Global Medical Laser Systems Market
Medical Devices
LASIK Eye Surgery Devices Market
Medical Devices
Specimen Retrieval Market
Medical Devices
North America C-Arms Market
Medical Devices
3D Printed Prosthetics Market
Medical Devices
ePTFE Vascular Prosthesis Market
Medical Devices
Drainage Catheters Market
Medical Devices
Global Artificial Organ and Bionic Implants Market