
 Ultrasound Imaging Solution Market | 2026-2036
Ultrasound Imaging Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasound Imaging Solution Market Analytics
Software-defined subscription models for image analysis and remote diagnostics are restructuring how ultrasound vendors monetize hardware deployments. GE HealthCare leverages its Edison platform to bundle AI-powered quantification tools with system leases, creating recurring revenue streams alongside capital sales. Siemens Healthineers sustains deep integration between its ultrasound hardware and enterprise imaging networks, anchoring large hospital contracts through workflow interoperability. Philips Healthcare competes on portable-to-premium system continuity, allowing clinicians to maintain consistent image protocols across cart-based and handheld devices.
Ultrasound imaging solutions employ piezoelectric transducers generating acoustic waves between two and eighteen megahertz, with beamforming algorithms processing returning echoes into real-time anatomical visualizations for non-invasive diagnostic and interventional guidance. The portable product segment is capturing disproportionate growth as battery-powered systems achieve diagnostic parity with cart-based platforms in cardiac and abdominal applications. The cardiology application area leads value generation due to complex quantification requirements and high procedure volumes, while the musculoskeletal segment differentiates through specialized high-frequency transducers that command premium positioning in sports medicine and rheumatology practices.
The FDA governs ultrasound device safety through the 510(k) premarket notification process and maintains acoustic output limits under the Medical Imaging Drugs and Biologics guidance, while the IEC 60601-2-37 standard defines international electrical and mechanical safety benchmarks for diagnostic equipment. These frameworks shape vendor development timelines, as AI-enabled measurement packages require separate regulatory validation from base hardware clearances. Stakeholders must monitor evolving reimbursement policies for point-of-care ultrasound applications, as coding decisions by national health authorities will determine whether portable deployment expands beyond emergency departments into primary care settings.
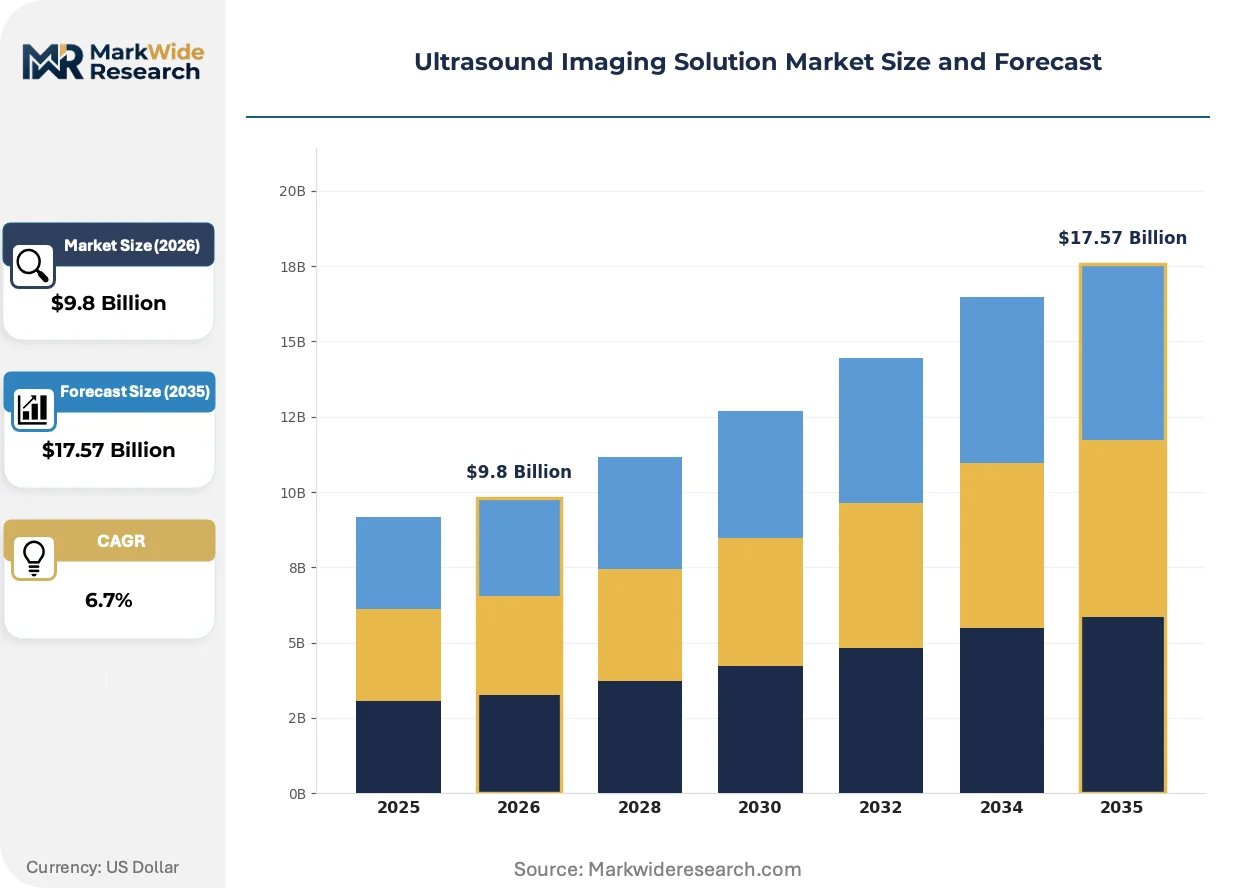
Market Dynamics
Software-defined ultrasound architectures are compressing hardware replacement cycles while expanding recurring revenue capture through AI-enabled image analysis subscriptions.
Growth Catalysts
- Point-of-care protocol expansion:Emergency departments in the United States are deploying handheld systems for trauma triage, creating pull-through demand for standardized training curricula and fleet management services.
- AI-enhanced 510(k) pathway:The FDA's streamlined premarket notification process for algorithmic diagnostic tools accelerates vendor commercialization timelines for automated measurement packages.
- Health system consolidation:Multi-hospital networks in North America are negotiating enterprise-wide ultrasound contracts that bundle equipment, software licenses, and long-term service agreements.
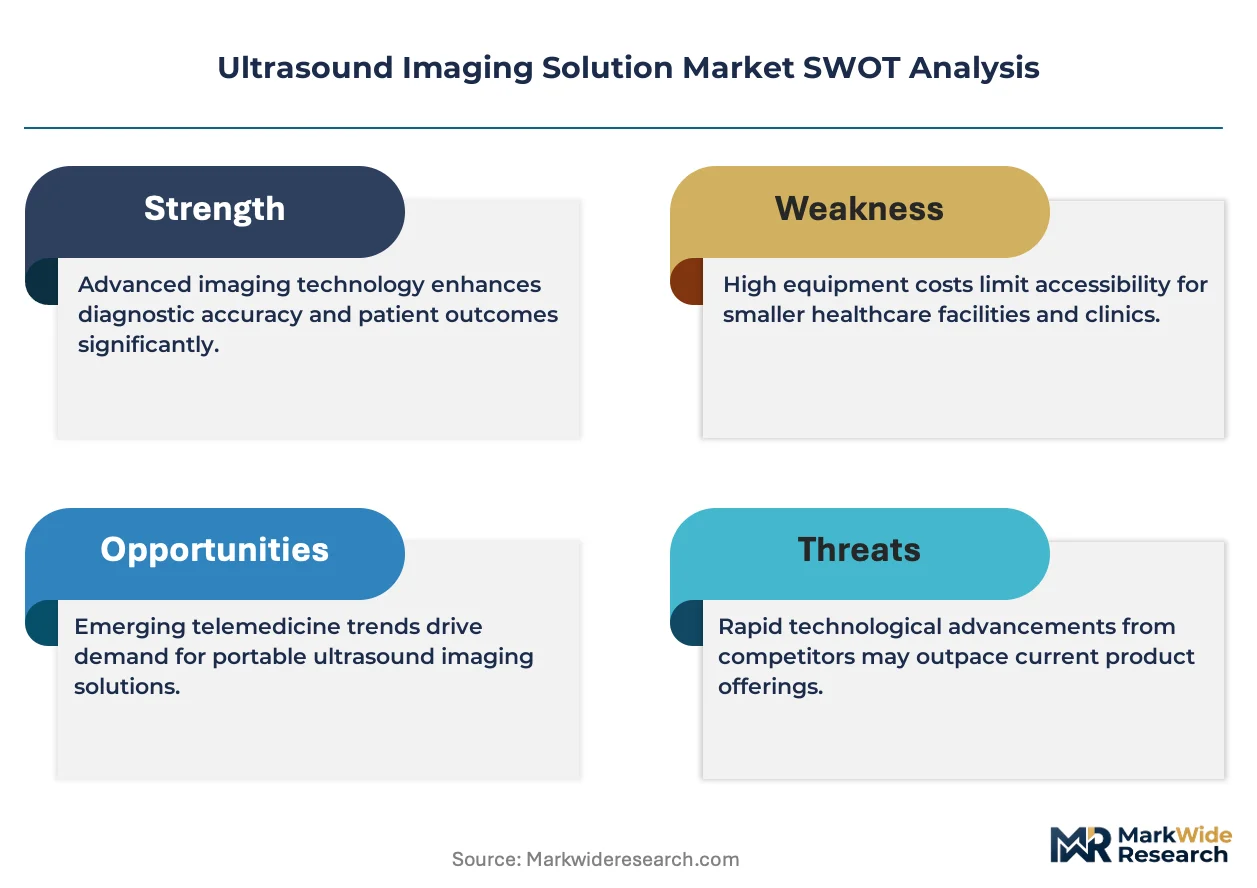
Market Restraints
- Piezoelectric crystal supply concentration:Specialized ceramic transducer materials depend on limited high-purity feedstock sources concentrated in East Asian manufacturing clusters.
- Acoustic output safety thresholds:FDA Medical Imaging Drugs and Biologics guidance imposes hard caps on mechanical and thermal indices, constraining probe design flexibility for deep-tissue imaging.
- Capital equipment budget compression:Hospital capital expenditure committees are extending depreciation schedules for cart-based systems, delaying replacement purchases.
Strategic Opportunities
- Primary care point-of-care penetration:Family medicine clinics in Germany and France represent underdeveloped deployment channels for pocket-sized cardiac screening devices.
- Cloud-native image archiving convergence:Integration of ultrasound workstations with vendor-neutral enterprise imaging archives enables remote diagnostic workflows and subscription-based storage monetization.
- Sports medicine specialization:High-frequency linear transducers for tendon and ligament assessment command premium positioning in orthopedic and athletic training facilities.
Industry Challenges
- Sonographer workforce scarcity:Specialized training programs for cardiac and vascular imaging cannot match health system hiring requirements, creating imaging backlogs.
- Legacy PACS interoperability friction:New ultrasound systems require costly middleware development to integrate with decade-old radiology information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasound Imaging Solution Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic, Therapeutic, Portable, 4D Technology: Conventional, Digital, 3D, High-frequency End User: Hospitals, Clinics, Specialty Centers, Diagnostics Labs Application: Cardiology, Obstetrics, Musculoskeletal, Urology |
| Companies Covered | GE HealthCare, Philips Healthcare, FUJIFILM Corporation, Canon Medical Systems Corporation, Mindray Medical International Limited, Siemens Healthineers, Samsung Medison, Esaote, Konica Minolta Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasound Imaging Solution Market Evolving Landscape
Three intersecting developments are compressing the traditional boundaries between hardware acquisition and software-enabled diagnostic services.
Beamforming-on-chip architectures are unifying analog front-end processing with digital signal computation in single semiconductor packages. Cardiology departments in tertiary hospitals are adopting these systems to reduce cart footprint while maintaining spectral Doppler fidelity. The technology is unifying previously separate hardware tiers into scalable platform families that share transducer inventories.
European MDR conformity assessment timelines are extending certification cycles for ultrasound software that performs automated biometry or lesion characterization. Manufacturers must now submit clinical evidence packages for algorithm updates that previously qualified as maintenance releases. Cardiovascular imaging suites face the longest validation delays due to the higher risk classification of quantitative ejection fraction tools.
Health systems are unbundling preventive maintenance contracts from capital equipment purchases and negotiating multi-vendor service agreements with third-party clinical engineering firms. Integrated delivery networks in the United States are leading this transition, consolidating ultrasound upkeep under single-source managed equipment service contracts. Radiology departments are responding by demanding remote diagnostic support and software update guarantees as separate line items.
Ultrasound Imaging Solution Market Segmentation
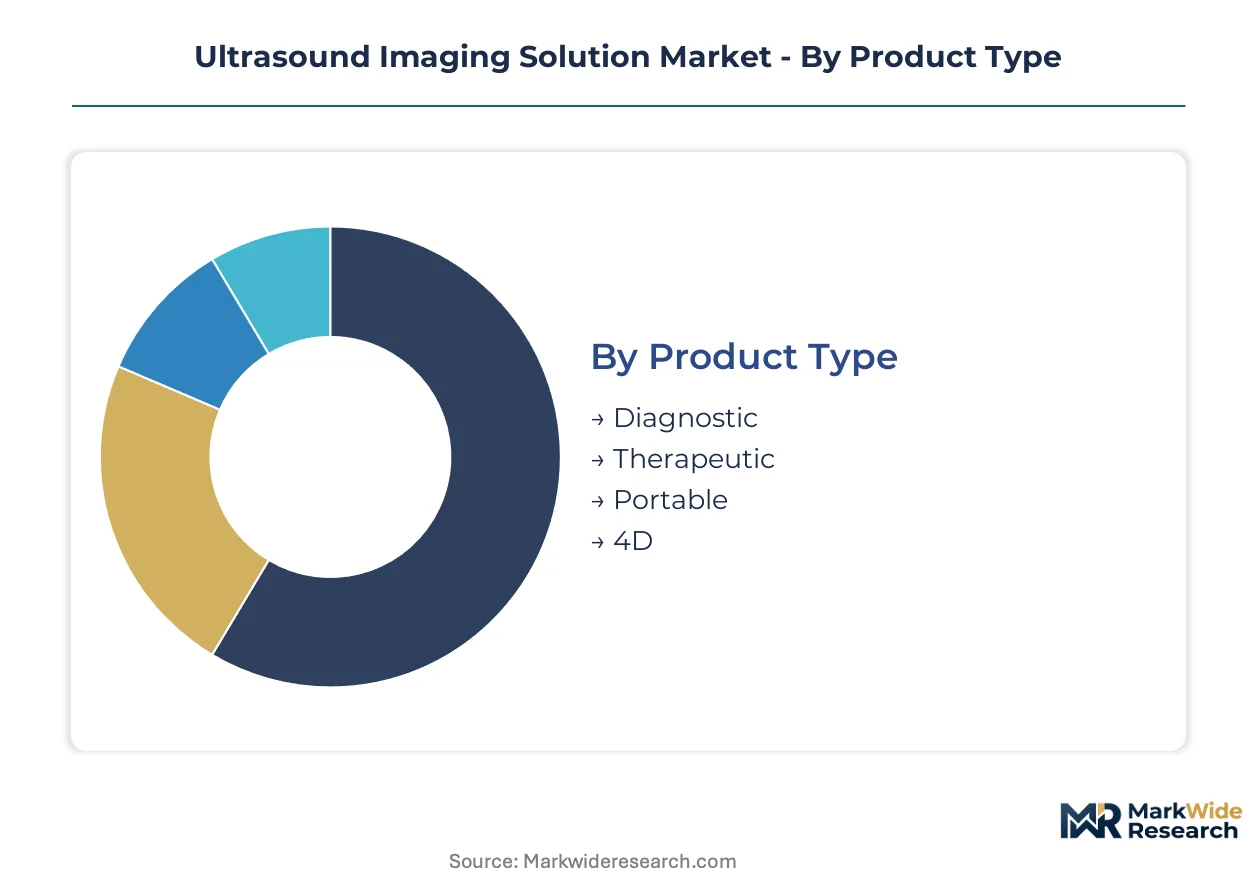
Ultrasound imaging solutions fragment across hardware form factors, signal processing architectures, clinical settings, and anatomical targets. Each dimension carries distinct procurement patterns, regulatory pathways, and margin structures that reshape competitive positioning.
Product Type:
Supply concentration in piezoelectric crystal fabrication favors vendors with captive transducer manufacturing or long-term material offtake agreements.
- Diagnostic:Cart-based systems with 128+ channel beamforming engines dominate tertiary hospital radiology departments. United States health systems concentrate procurement through group purchasing organizations that negotiate multi-year service bundles.
- Therapeutic:High-intensity focused ultrasound platforms for tumor ablation and lithotripsy require specialized acoustic power management. Regulatory clearance timelines through FDA 510(k) pathways extend due to thermal dose verification protocols.
- Portable:Battery-powered devices with solid-state transducer arrays achieve diagnostic parity in emergency medicine. German and French primary care networks represent underpenetrated deployment channels.
- 4D:Real-time volumetric rendering systems command premium positioning in maternal-fetal medicine. Hardware complexity limits vendor participation to established imaging conglomerates.
Diagnostic systems absorb the bulk of installed capacity; portable devices are expanding most quickly.
Technology:
Cost tier differentiation separates legacy analog architectures from software-defined platforms with subscription monetization potential.
- Conventional:Analog beamforming with discrete component front-ends persists in price-sensitive clinics. Replacement cycles extend as capital committees prioritize software-enabled upgrades over hardware refreshes.
- Digital:Software-defined architectures compress hardware replacement cycles while expanding recurring revenue through AI analysis subscriptions. Philips Healthcare and Siemens Healthineers anchor enterprise contracts on platform scalability.
- 3D:Mechanical or matrix array transducers with volumetric reconstruction algorithms serve obstetric and cardiac applications. Processing latency requirements favor on-premise workstation deployments over cloud rendering.
- High-frequency:Linear arrays operating above 15 MHz enable superficial tissue visualization in sports medicine and dermatology. Specialized ceramic compositions constrain supplier bases to Japanese and German material specialists.
Digital platforms absorb the bulk of vendor R&D investment; high-frequency systems command the steepest price premiums per channel.
End User:
Customer type determines procurement authority structures, with consolidated health systems negotiating enterprise terms that independent practices cannot match.
- Hospitals:Integrated delivery networks in the United States bundle ultrasound procurement with enterprise imaging contracts. Radiology departments demand vendor-neutral archive interoperability as a non-negotiable specification.
- Clinics:Outpatient facilities prioritize portable systems with simplified user interfaces. Reimbursement coding for point-of-care applications remains unsettled in multiple national health systems.
- Specialty Centers:Cardiovascular and orthopedic focused facilities require application-specific transducer portfolios. Training certification programs for sonographers create switching costs between vendor ecosystems.
- Diagnostics Labs:High-throughput screening operations emphasize workflow automation and structured reporting integration. Teleradiology partnerships drive demand for cloud-native image distribution capabilities.
Hospitals absorb the bulk of capital expenditure; specialty centers are gaining share fastest through procedure volume concentration.
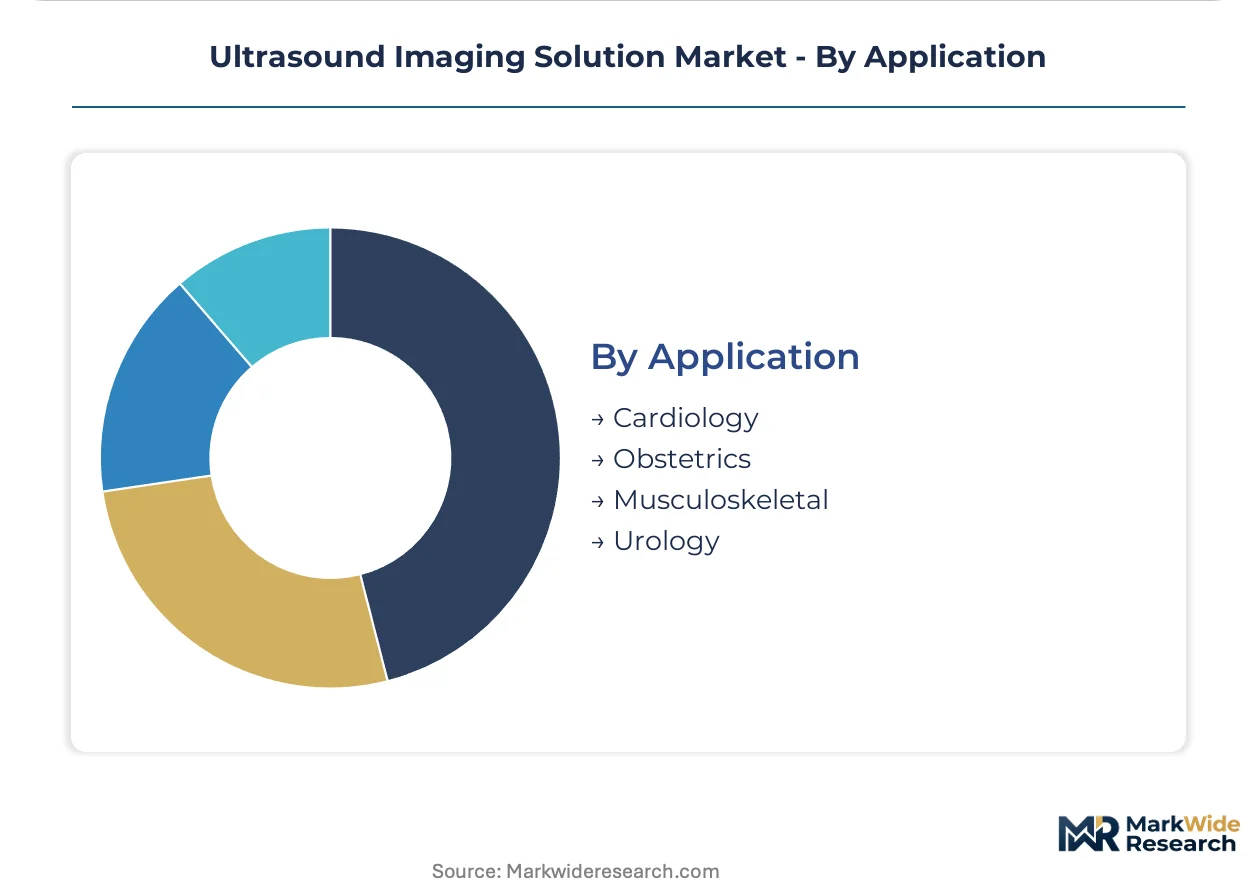
Application:
Maturity gradients separate established cardiology protocols from emerging musculoskeletal adoption curves.
- Cardiology:Quantitative ejection fraction measurement and spectral Doppler analysis require specialized training and premium transducer frequencies. European MDR conformity assessments impose extended validation timelines for automated biometry algorithms.
- Obstetrics:Nuchal translucency screening and fetal anomaly detection drive consistent replacement demand. Malpractice exposure limits vendor participation to established manufacturers with clinical evidence libraries.
- Musculoskeletal:Tendon, ligament, and joint visualization commands premium positioning in sports medicine practices. High-frequency linear transducers from specialized manufacturers penetrate this segment faster than generalist vendors.
- Urology:Prostate biopsy guidance and renal calculus assessment utilize both diagnostic and therapeutic modalities. Fusion imaging with MRI datasets creates interoperability requirements that favor integrated platform vendors.
Cardiology absorbs the bulk of quantitative software licensing revenue; musculoskeletal applications are climbing the fastest as sports medicine professionalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ultrasound hardware production concentrates in East Asian manufacturing clusters, while consumption tilts toward North American and European health systems with mature procurement infrastructure. This divergence shapes regional competitive dynamics and regulatory compliance priorities.
United States
Integrated delivery networks negotiate enterprise-wide ultrasound contracts bundling equipment, software licenses, and decade-long service agreements. The FDA's 510(k) premarket notification pathway governs device clearance, with separate validation requirements for AI-enhanced diagnostic algorithms. The Boston-Cambridge corridor hosts concentrated medical device engineering talent pools supporting vendor R&D operations.
Germany
Family medicine clinics represent underpenetrated deployment channels for pocket-sized cardiac screening devices despite sophisticated hospital infrastructure. The EU Medical Device Regulation extends conformity assessment timelines for automated biometry software, delaying commercialization. Bavaria's precision manufacturing ecosystem supplies specialized ceramic compositions for high-frequency transducer arrays.
China
Domestic manufacturers capture share in price-sensitive provincial hospital tiers while import-dependent premium segments persist in tertiary centers. The National Medical Products Administration aligns device registration requirements with international standards to accelerate local innovation. Shenzhen's electronics manufacturing clusters produce battery-powered portable systems for emerging market export.
Japan
Specialized ceramic transducer materials from domestic suppliers command premium positioning in sports medicine and rheumatology applications. The Pharmaceuticals and Medical Devices Agency maintains stringent acoustic output safety thresholds constraining probe design flexibility. Tokyo-Osaka metropolitan corridors concentrate high-throughput diagnostic imaging demand from aging demographics.
France
Primary care networks lag emergency department adoption of point-of-care ultrasound despite favorable clinician training infrastructure. National health authority reimbursement coding decisions will determine whether portable deployment expands beyond hospital settings. The Île-de-France region anchors radiology department procurement authority for multi-site hospital networks.
Ultrasound Imaging Solution Market Competitive Landscape
Top-tier vendors anchor the premium diagnostic systems tier, while mid-scale specialists and regional manufacturers populate price-sensitive portable segments. Consolidated health system procurement in North America and Western Europe favors vendors with enterprise imaging interoperability and multi-year service contract capabilities. Three archetypes dominate: diversified imaging conglomerates with platform breadth, transducer technology specialists with captive material supply, and software-native entrants leveraging AI-enabled diagnostic subscriptions. M&A activity concentrates on algorithm developers and cloud-native archiving platforms, while strategic partnerships target third-party clinical engineering service networks.
Within the diversified imaging conglomerate tier, GE HealthCare, Philips Healthcare, and Siemens Healthineers exemplify platform-scale positioning through hardware-software bundling and enterprise workflow integration. These vendors occupy positions defined by multi-decade installed base relationships and captive service revenue streams rather than discrete product specifications. Their geographic footprints span manufacturing and commercial operations across North American, European, and Asian markets.
| Leading Market Players |
|---|
| GE HealthCare |
| Philips Healthcare |
| FUJIFILM Corporation |
| Canon Medical Systems Corporation |
| Mindray Medical International Limited |
| Siemens Healthineers |
| Samsung Medison |
| Esaote |
| Konica Minolta Healthcare |
| Others |
Value Network & Pricing Analysis
EU MDR conformity assessment timelines gate qualified supply for premium-tier ultrasound systems, extending certification cycles for automated biometry software and concentrating pricing power among vendors with captive clinical evidence libraries. Health system procurement committees in the United States leverage this bottleneck to negotiate multi-year service bundles that lock in diagnostic cart pricing while extracting software subscription discounts.
Pricing Analysis
Margin tightening in portable device tiers reflects battery-powered system commoditization as Shenzhen manufacturing clusters achieve diagnostic parity with legacy cart platforms. Three-tier pricing structure across premium, standard, and economy levels separates AI-enhanced quantification suites from basic imaging packages and refurbished hardware. FDA 510(k) clearance tiering and ISO 13485 certification grade drive price differentiation between algorithm-validated systems and unverified imports. Emergency departments demonstrate highest price sensitivity due to capital budget fragmentation, while cardiovascular suites absorb premium positioning for spectral Doppler fidelity.
Supply Chain Analysis
Dual-sourcing mandates from United States integrated delivery networks require qualified ceramic transducer feedstock from both Japanese and German material specialists, mitigating single-source concentration in East Asian piezoelectric crystal fabrication. High-purity lead zirconate titanate compositions, solid-state transducer arrays, and specialized acoustic lens polymers anchor component dependencies. Tariff exposure on Chinese battery cell imports threatens portable system margin structures. Distribution runs through group purchasing organizations consolidating hospital procurement authority under enterprise imaging contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined beamforming architectures are displacing analog front-end processing, compressing hardware replacement cycles while expanding recurring revenue capture through AI-enabled diagnostic subscriptions.
For Market Incumbents: Cement installed base retention through captive transducer manufacturing and Edison-platform AI bundling, countering portable specialist erosion in emergency medicine. Deepen backward integration into piezoelectric ceramic supply to defend margin position against feedstock volatility. Prioritize European MDR clinical evidence investment to maintain premium-tier certification gates. For New Entrants and Emerging Players: Family medicine clinics in Germany and France represent the most penetrable white-space channel for pocket-sized cardiac screening devices, bypassing consolidated hospital procurement barriers. Cloud-native image archiving partnerships with third-party clinical engineering firms enable subscription monetization without capital equipment sales infrastructure. Target teleradiology workflow integration as the primary go-to-market angle. For Investors and Strategic Acquirers: FDA 510(k) clearance acceleration for algorithmic diagnostic tools is the leading indicator that AI-native software entrants will command acquisition premiums over hardware-legacy vendors. Long-term viability favors platform-scale positioning with enterprise imaging interoperability and multi-year service contract anchoring. Monitor health system unbundling of preventive maintenance contracts as the signal for third-party clinical engineering consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enhanced 510(k) Submission | FDA streamlined pathways accelerate automated measurement package commercialization timelines. |
| Hospital System Partnership | Integrated delivery network bundling secures decade-long equipment and service revenue streams. |
| Software Companion Development | Cloud-native quantification tools create recurring subscription monetization alongside hardware leases. |
| CE Marking Pathway Investment | European MDR clinical evidence packages defend premium positioning against unvalidated competitors. |
| Reimbursement Strategy Execution | National health authority coding decisions determine point-of-care expansion beyond emergency departments. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contract repositories, and CMS Medicare reimbursement filings underwrites the qualitative findings in this study. Primary interviews with biomedical engineers, GPO contracts managers, cardiac sonographers, and radiology department chairs combined with secondary validation against FDA 510(k) clearances, IEC 60601-2-37 standards documentation, and hospital capital expenditure disclosures. Bottom-up vendor shipment estimates and top-down health system spending analysis triangulate market sizing.
Comparable-period anchoring to historical ultrasound equipment replacement cycles and software subscription adoption curves structured the forecast window across the projection horizon. Segmentation modeling spanned hardware form factor, signal processing architecture, clinical setting, and anatomical application target. CAGRs derived from procedure volume growth coefficients and capital expenditure elasticity assumptions. Forecast inputs incorporated AI algorithm regulatory clearance velocity and point-of-care reimbursement policy trajectories.
Revisions become necessary when FDA acoustic output guidance thresholds tighten, piezoelectric feedstock supply disruptions materialize, or health system consolidation accelerates beyond modeled procurement authority concentration. Deviation in European MDR conformity assessment timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Computed Tomography (CT) Scanners Market
Medical Imaging
South America Mammography Market
Medical Imaging
Magnetic Resonance Imaging Equipment Coils Market
Medical Imaging
Dual and Multi-Energy Computed Tomography (CT) Market
Medical Imaging
Non-Invasive Coronary Imaging Market
Medical Imaging
Diagnostic Imaging Services Market
Medical Imaging
UK Imaging Services Market
Medical Imaging
Nuclear Medicine Market
Medical Imaging
Europe Mobile Tomography Market
Medical Imaging
United States Diagnostic Imaging Market
Medical Imaging
Argentina Computed Tomography Market
Medical Imaging
Japan Diagnostic Imaging Market
Medical Imaging
Fluorescein Angiography Market
Medical Imaging
India Digital X-Ray Market
Medical Imaging
India Diagnostic Imaging Equipment Market
Medical Imaging
PSMA-PET Imaging Market