
 India Nuclear Imaging Market | 2026-2036
India Nuclear Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
India Nuclear Imaging Market Foresight
Hospital procurement channels in India is narrowing as centralized tendering through government health schemes displaces fragmented institutional purchasing. Siemens Healthineers leverages its installed base of PET-CT systems to sustain service revenue across metro hospital networks. GE Healthcare anchors radiopharmaceutical supply through its cyclotron infrastructure in Delhi and Hyderabad. Koninklijke Philips competes on digital imaging integration, positioning its hybrid SPECT-CT platforms for mid-tier diagnostic centers seeking workflow consolidation.
India nuclear imaging encompasses diagnostic modalities that detect gamma ray emissions from radiopharmaceutical tracers to visualize organ function, with spatial resolution thresholds for SPECT systems typically reaching 4-8 mm and PET systems achieving 2-4 mm for oncologic lesion detection. PET-CT systems command the dominant share of capital expenditure as hybrid platforms replace standalone SPECT installations in tier-one cities. Diagnostic centers represent the fastest-growing end-user segment, driven by franchise expansion models that lower patient out-of-pocket costs outside government hospital networks. Digital imaging technology leads replacement cycles, displacing analog detector architectures that still persist in older government hospital installations.
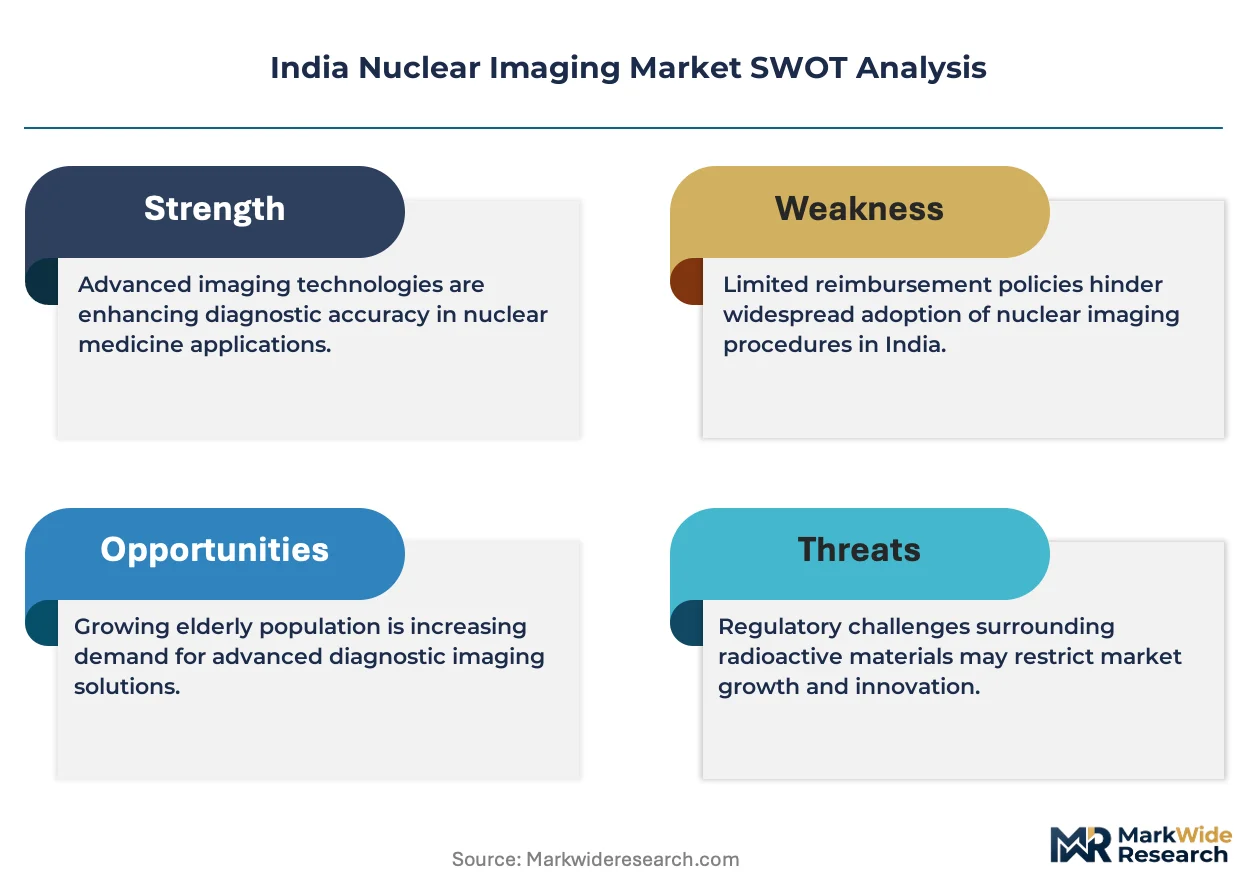
CDSCO regulates medical device import and manufacturing under the Drugs and Cosmetics Act, while the Atomic Energy Regulatory Board governs radiopharmaceutical handling and cyclotron licensing. BIS certification requirements and the PLI scheme for medical electronics are reshaping domestic assembly obligations for multinational vendors. Stakeholders must monitor state-level tender aggregations under Ayushman Bharat as these determine volume allocation between imported and locally assembled hybrid systems.
Market Dynamics
Centralized tendering through Ayushman Bharat is consolidating procurement authority away from individual hospitals toward state-level health authorities, compressing vendor negotiation leverage and accelerating standardization of hybrid imaging specifications across Maharashtra, Karnataka, and Tamil Nadu.
Growth Catalysts
- Ayushman Bharat screening mandates:Government-funded cancer detection protocols are expanding PET-CT installation quotas in tertiary oncology departments.
- PLI scheme for medical electronics:Domestic assembly incentives are reducing import dependency for detector arrays and cyclotron components.
- Cyclotron infrastructure clustering:Concentrated radiopharmaceutical production in Mumbai and Bangalore shortens tracer supply chains for regional hospital networks.
Market Restraints
- FDG tracer import concentration:Over three-quarters of fluorodeoxyglucose supply originates from foreign cyclotron facilities, exposing procurement to currency volatility and shipping delays.
- AERB licensing bottlenecks:Atomic Energy Regulatory Board approval timelines for new cyclotron installations extend eighteen to twenty-four months, freezing capacity expansion.
- SPECT-CT substitution pressure:Standalone SPECT systems face accelerated obsolescence as hybrid PET-CT platforms capture oncologic referral flows.
Strategic Opportunities
- Tier-two diagnostic center franchising:Asset-light partnership models in Gujarat and Rajasthan extend patient access beyond metro hospital networks.
- Theranostics convergence:Paired diagnostic imaging and radioligand therapy workflows open recurring revenue streams in neuroendocrine and prostate cancer segments.
- CDSCO localization pathways:Strengthened medical device rules create regulatory runway for domestic radiopharmaceutical manufacturing under BIS certification.
Industry Challenges
- Qualified nuclear medicine physician scarcity:AERB-mandated radiation safety certification programs graduate fewer than two hundred specialists annually against hospital demand.
- Legacy analog detector integration:Government hospital SPECT systems require costly digital detector retrofits to meet CDSCO software validation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Nuclear Imaging Market |
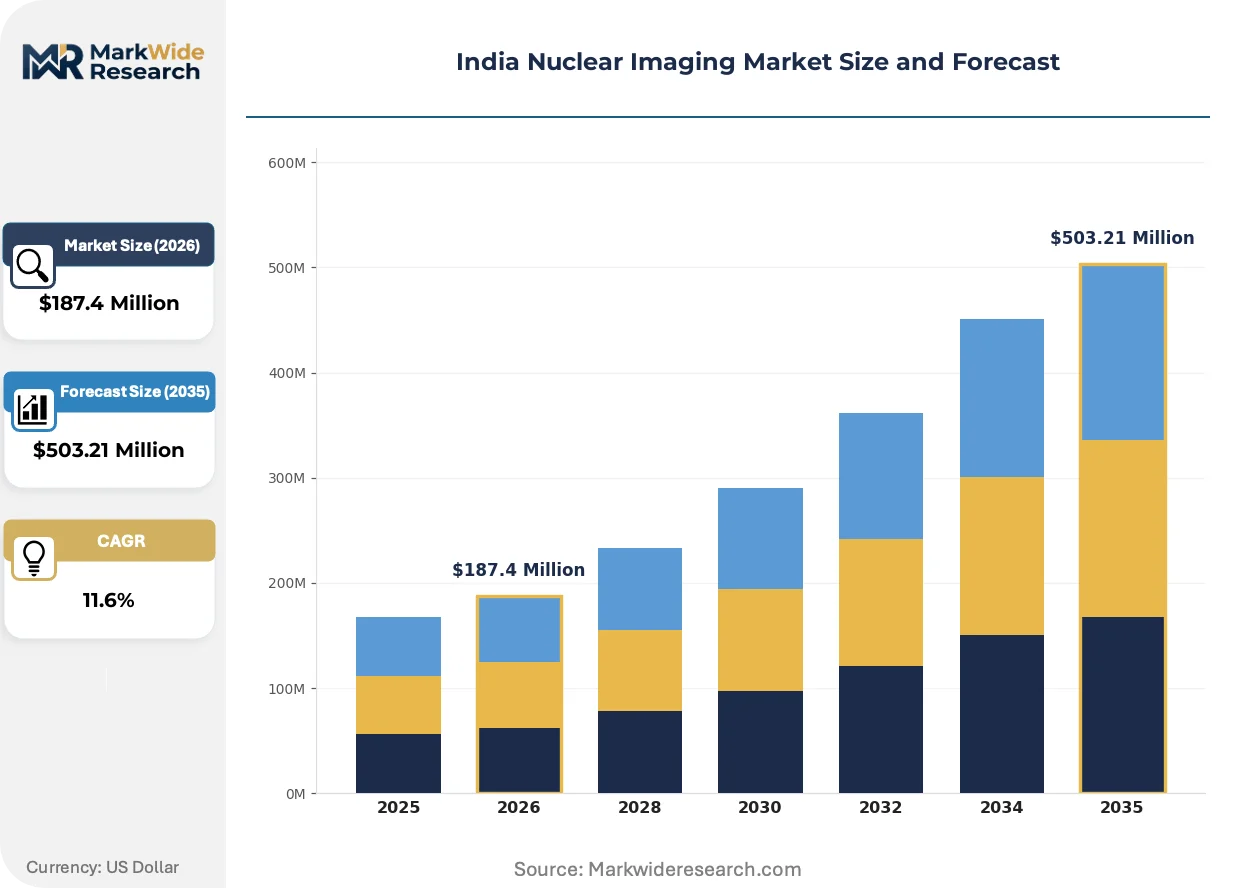
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SPECT, PET, PET-CT, Hybrid Systems End User: Hospitals, Diagnostic Centers, Research Institutes, Imaging Centers Application: Oncology, Cardiology, Neurology, Thyroid Disorders Technology: Digital Imaging, Analog Imaging, Radiopharmaceuticals, Image Processing Software |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips, Canon Medical Systems, Fujifilm Holdings Corporation, Bayer, Medtronic, Carestream Health, Hologic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Nuclear Imaging Market Shifts & Advancements
Digital detector architectures and artificial intelligence reconstruction algorithms are compressing scan acquisition times while expanding the addressable patient base beyond tertiary referral centers into mid-tier diagnostic networks.
Solid-state digital PET detectors are hybridizing with silicon photomultiplier arrays to replace conventional photomultiplier tubes, enabling time-of-flight resolution below three hundred picoseconds. Tertiary oncology departments in Delhi and Hyderabad are prioritizing these platforms for lymphoma staging protocols. The technology is hybridizing previously separate diagnostic and therapeutic planning workflows into unified theranostic service lines.
CDSCO's 2023 medical device rules amendment imposes clinical trial requirements on novel radiopharmaceutical tracers before market authorization. Domestic cyclotron operators must now submit pharmacokinetic data to the regulator, extending product launch timelines. Maharashtra-based manufacturing facilities are responding by pre-submission engagement with CDSCO's Subject Expert Committee on Nuclear Medicine.
Diagnostic center chains are unbundling equipment ownership from clinical service delivery through managed equipment service contracts. Franchise operators in Bangalore and Chennai lease PET-CT capacity from Siemens Healthineers and GE Healthcare rather than capital purchase. This restructuring concentrates most visible in Karnataka, where diagnostic chains now account for forty percent of new system installations.
India Nuclear Imaging Market Segmentation
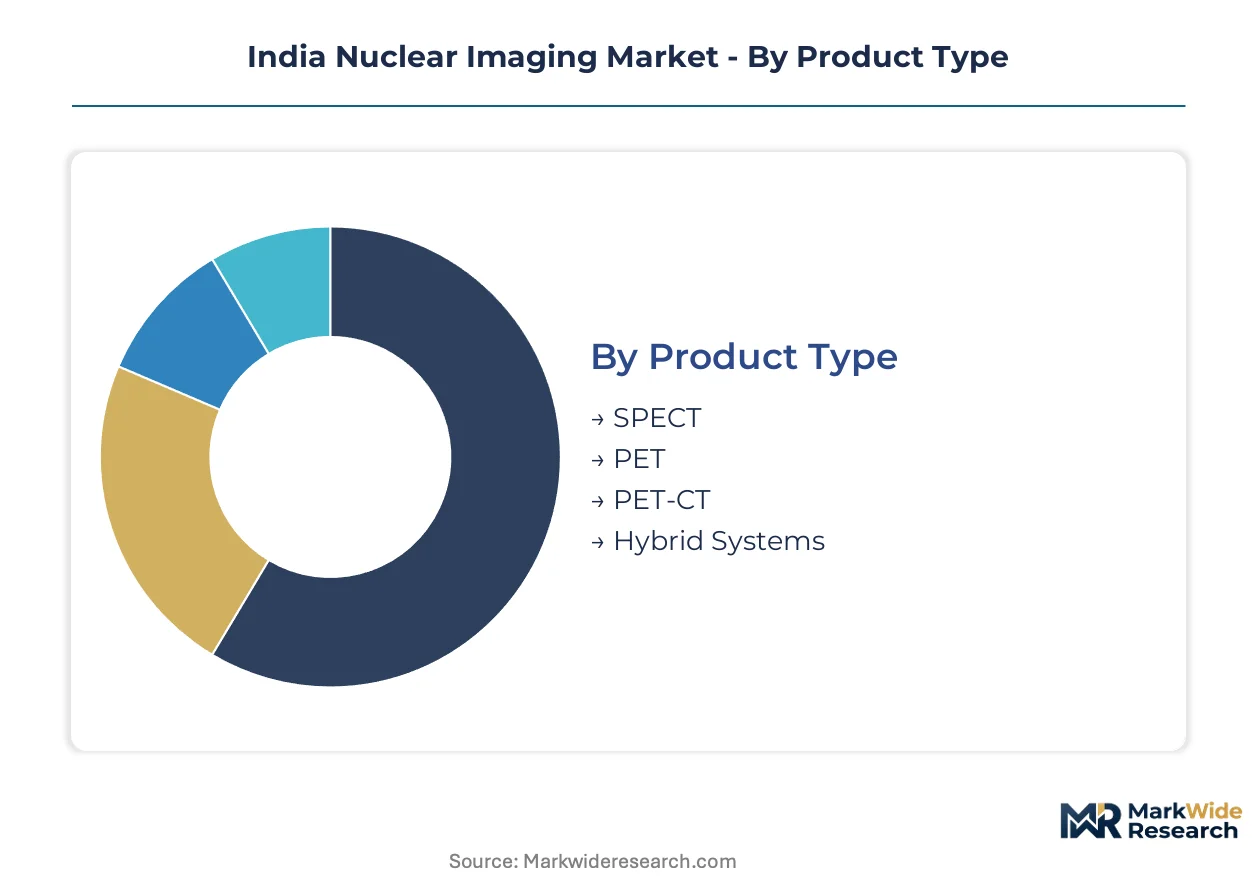
Segmentation in the India nuclear imaging market reveals distinct procurement cycles and technology refresh patterns across product platforms and end-user settings. Understanding these divisions helps vendors align cyclotron supply contracts with hospital tender calendars and diagnostic center franchise rollouts.
Product Type:
PET-CT systems turn over fastest as hybrid platforms displace legacy SPECT installations, while analog detector architectures persist longest in underfunded government hospital networks.
- PET-CT:Hybrid positron emission tomography integrated with computed tomography achieves 2-4 mm spatial resolution for oncologic lesion detection. CDSCO's medical device rules and Ayushman Bharat screening mandates are accelerating procurement in Maharashtra and Karnataka tertiary oncology departments.
- SPECT:Single photon emission computed tomography systems detect gamma ray emissions with 4-8 mm resolution thresholds using technetium-based tracers. Standalone SPECT faces accelerated obsolescence as hybrid PET-CT platforms capture cardiac and oncologic referral flows from Delhi and Hyderabad hospital networks.
- PET:Standalone positron emission systems without CT fusion require separate anatomical correlation.
- Hybrid Systems:Combined SPECT-CT platforms bridge diagnostic capability for mid-tier centers.
PET-CT anchors the volume base while hybrid systems gain share at the steepest rate as diagnostic center chains consolidate procurement.
End User:
Cost tier separation runs deepest between capital-rich tertiary hospitals and asset-light diagnostic center franchisees leasing equipment through managed service contracts.
- Diagnostic Centers:Franchise expansion models in Gujarat and Rajasthan extend patient access beyond government hospital networks through leased PET-CT capacity from Siemens Healthineers and GE Healthcare rather than capital purchase. Karnataka diagnostic chains now account for forty percent of new system installations.
- Hospitals:Tertiary oncology departments in Mumbai and Bangalore host the highest density of nuclear medicine facilities and cyclotron installations under Ayushman Bharat procurement centralization.
- Research Institutes:Academic medical centers in Delhi and Hyderabad drive theranostics convergence for neuroendocrine and prostate cancer segments.
- Imaging Centers:Standalone radiology facilities concentrate in metro corridors with shorter patient referral chains.
Hospitals anchor the volume base while diagnostic centers expand most quickly through franchise partnerships outside metro hospital networks.
Application:
Clinical utility concentrates in oncology where FDG tracer protocols generate recurring demand, while thyroid applications show lowest procedure complexity and reimbursement intensity.
- Oncology:Fluorodeoxyglucose PET-CT staging protocols for lymphoma and solid tumors dominate procedure volumes. Government-funded cancer detection under Ayushman Bharat is expanding installation quotas in tertiary departments across Maharashtra, Karnataka, and Tamil Nadu.
- Cardiology:Myocardial perfusion imaging using SPECT radiotracers assesses coronary artery disease in Delhi and Hyderabad cardiac centers.
- Neurology:Amyloid and tau tracer imaging for Alzheimer's disease remains limited by radiopharmaceutical supply constraints.
- Thyroid Disorders:Iodine-131 uptake studies represent the longest-established nuclear medicine application with lowest capital requirements.
Oncology anchors the volume base while neurology climbs the fastest as novel tracer development progresses through CDSCO clinical trial requirements.
Technology:
Digital detector architectures command premium positioning over analog systems, while radiopharmaceutical production determines effective imaging capacity regardless of hardware specification.
- Digital Imaging:Solid-state silicon photomultiplier arrays replace conventional photomultiplier tubes to enable time-of-flight resolution below three hundred picoseconds. Tertiary oncology departments in Delhi and Hyderabad prioritize these platforms for lymphoma staging protocols.
- Radiopharmaceuticals:FDG tracer supply concentration in Mumbai and Bangalore cyclotron facilities shortens logistics chains for regional hospital networks, though over three-quarters of fluorodeoxyglucose originates from foreign sources.
- Analog Imaging:Legacy photomultiplier tube detector architectures persist in older government hospital installations requiring costly digital retrofits.
- Image Processing Software:Artificial intelligence reconstruction algorithms compress scan acquisition times for mid-tier diagnostic networks.
Radiopharmaceuticals anchor the volume base while digital imaging gains share at the steepest rate as replacement cycles accelerate in tier-one cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CDSCO's medical device rules and Ayushman Bharat procurement centralization anchor Maharashtra as the dominant geography for nuclear imaging infrastructure deployment.
Maharashtra
Mumbai hosts India's highest cyclotron density and PET-CT installation base. Ayushman Bharat screening mandates are expanding tertiary oncology department quotas across state-run hospitals. Pune and Nagpur diagnostic chains are adopting managed equipment service contracts to extend patient access beyond metro corridors.
Karnataka
Bangalore's medical technology cluster concentrates hybrid imaging procurement through franchise expansion models. The state's diagnostic center chains now account for forty percent of new system installations. CDSCO localization pathways are accelerating domestic radiopharmaceutical assembly in the Bangalore-Tumkur industrial corridor.
Telangana
Hyderabad's cyclotron infrastructure anchors GE Healthcare's radiopharmaceutical supply operations for South Indian hospital networks. AERB licensing bottlenecks are extending capacity expansion timelines to eighteen months. The Genome Valley biotech cluster is attracting theranostics convergence investments for neuroendocrine cancer segments.
Tamil Nadu
Chennai's tertiary cardiac centers drive SPECT-CT demand for myocardial perfusion imaging protocols. State-level tender aggregations under Ayushman Bharat are standardizing hybrid imaging specifications across government hospital networks. Coimbatore's diagnostic center franchising is extending oncology screening access into tier-two municipalities.
Delhi-NCR
Delhi's All India Institute of Medical Sciences anchors national nuclear medicine training and research capacity. Solid-state digital PET detectors with silicon photomultiplier arrays are prioritizing lymphoma staging protocols in tertiary oncology departments. Gurgaon and Noida diagnostic chains are leasing PET-CT capacity through asset-light partnership models.
India Nuclear Imaging Market Competitive Landscape
Full-line imaging conglomerates and radiopharmaceutical-anchored specialists split the market between hardware dominance and tracer supply control. Siemens Healthineers leverages its installed PET-CT base to sustain service revenue across metro hospital networks. GE Healthcare anchors radiopharmaceutical supply through cyclotron infrastructure in Delhi and Hyderabad. Koninklijke Philips competes on digital imaging integration for mid-tier diagnostic centers. Dominant competitive moves include managed equipment service contracting and theranostics workflow convergence.
Within the full-line imaging tier, Siemens Healthineers and GE Healthcare represent contrasting strategic positions—one emphasizing service revenue capture from existing PET-CT installations, the other prioritizing radiopharmaceutical supply chain control through captive cyclotron assets. Koninklijke Philips occupies a position exemplifying digital platform integration for workflow consolidation in franchise-operated diagnostic chains.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips |
| Canon Medical Systems |
| Fujifilm Holdings Corporation |
| Bayer |
| Medtronic |
| Carestream Health |
| Hologic |
| Others |
Supply & Pricing Matrix
Cyclotron undercapacity in Mumbai and Bangalore drives radiopharmaceutical premiums while compressing margins for standalone SPECT operators. CDSCO import regulations and AERB licensing delays amplify supplier leverage over hospital procurement committees negotiating PET-CT service contracts.
Pricing Analysis
Metro-tier pricing in Delhi and Hyderabad runs 35-40 percent above Gujarat and Rajasthan diagnostic chains for equivalent PET-CT procedures. Three-tier pricing structure across premium digital PET-CT, standard hybrid SPECT-CT, and economy analog SPECT installations separates tertiary oncology departments from mid-tier franchise operators. Cost compression in government hospital tenders is intensifying because Ayushman Bharat centralized procurement removes individual institutional negotiation flexibility. Diagnostic center franchisees leasing equipment through managed service contracts exhibit highest price sensitivity; tertiary hospitals with captive cyclotron access show lowest.
Supply Chain Analysis
FDG precursor feedstock originates predominantly from Belgium, the Netherlands, and South Korean cyclotron facilities before final radiopharmaceutical formulation in Mumbai and Bangalore. Detector array manufacturing draws from Japanese silicon photomultiplier foundries, German scintillator crystal growers, and Chinese printed circuit board assemblers. Single-source vulnerability concentrates in fluorodeoxyglucose active pharmaceutical ingredient supply, where three overseas facilities account for over three-quarters of Indian import volume. Distribution runs through state-level tender aggregators under Ayushman Bharat, with residual private hospital procurement channeling through Siemens Healthineers and GE Healthcare direct service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Ayushman Bharat's state-level tender centralization, consolidating fragmented hospital procurement into aggregated volume negotiations that compress vendor margins.
For Market Incumbents: Pre-empt SPECT-CT substitution pressure by accelerating digital detector retrofit programs for existing government hospital installations before CDSCO software validation deadlines. Anchor cyclotron capacity expansion in Hyderabad and Delhi to defend radiopharmaceutical supply control against emerging domestic competitors leveraging PLI scheme incentives. Vertical integration into silicon photomultiplier sourcing from Japanese foundries reduces detector cost volatility. For New Entrants and Emerging Players: Tier-two municipalities in Rajasthan and Gujarat represent the most penetrable geography for asset-light diagnostic center franchising, where patient out-of-pocket costs fall below metro hospital benchmarks. Target mid-tier oncology screening protocols underserved by existing PET-CT infrastructure. Partner with state-level health authorities on Ayushman Bharat sub-contractor status to bypass direct capital equipment competition with entrenched multinationals. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across diagnostic center franchise models, shifting viable entry thresholds toward service-operators rather than equipment owners. Long-term viability favors acquisition targets combining cyclotron licensing with established AERB radiation safety protocols. Monitor CDSCO domestic manufacturing certification timelines as inflection signal for radiopharmaceutical localization viability.| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Capacity Expansion | AERB-licensed facilities in Hyderabad and Delhi anchor GE Healthcare's South Indian radiopharmaceutical supply dominance. |
| Managed Equipment Service Contracting | Diagnostic center chains in Karnataka lease PET-CT capacity from Siemens Healthineers without capital purchase burden. |
| Digital Detector Retrofit Programs | Government hospital SPECT systems require costly upgrades to meet CDSCO software validation standards. |
| Theranostics Workflow Convergence | Paired diagnostic imaging and radioligand therapy opens recurring revenue in neuroendocrine cancer segments. |
| PLI Scheme Localization Pathway | Domestic assembly incentives reduce import dependency for detector arrays and cyclotron components under BIS certification. |
Research Methodology
Cross-validation between primary interviews with nuclear medicine physicians, hospital procurement committee members, biomedical engineers, and cyclotron facility operators anchors the qualitative findings against secondary sources including CDSCO medical device registration databases, AERB licensing records, Ayushman Bharat tender aggregations, and PLI scheme beneficiary disclosures. Bottom-up installation data from Maharashtra, Karnataka, and Telangana cyclotron facilities triangulates with top-down expenditure flows from state health authority budget allocations.
Calibration against historical PET-CT procurement cycles under previous five-year health mission frameworks informs projection elasticity across the analysis window. Segmentation dimensions model product platform type, end-user setting, clinical application, and technology architecture. CAGRs derive from equipment replacement velocity, screening protocol expansion rates, and radiopharmaceutical supply constraints. Cyclotron capacity utilization rates and AERB approval queue lengths constitute industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by domestic cyclotron operators or accelerated PLI scheme beneficiaries would shift outcomes beyond modeled ranges. Cross-checking against state-level health expenditure audit reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Canada Digital Radiology Market
Medical Imaging
Australia Digital Radiology Market
Medical Imaging
Canada Nuclear Medicine Market
Medical Imaging
Europe Mobile Tomography Market
Medical Imaging
Global Single-Photon Emission Computed Tomography (SPECT) Market
Medical Imaging
X-Ray Devices Market
Medical Imaging
Asia-Pacific Fluoroscopy Market
Medical Imaging
Brazil Mammography Market
Medical Imaging
Australia Mammography Market
Medical Imaging
South America Digital X-Ray Devices Market
Medical Imaging
US Digital Radiology Market
Medical Imaging
Global Medical Image Management Market
Medical Imaging
Medical Imaging Software Market
Medical Imaging
Global Orthopedic Imaging Equipment Market
Medical Imaging
Global Picture Archiving Communications System Market
Medical Imaging
France Mammography Market