
 Polyvinylidene Fluoride (PVDF) Market | 2026-2036
Polyvinylidene Fluoride (PVDF) Market Size, Share, and Industry Trends Forecast 2026-2036
Polyvinylidene Fluoride (PVDF) Market Intelligence
The basis for PVDF pricing is shifting from volume-based commodity grades to performance-specified, high-purity battery grades. This creates a two-tiered market structure. European producers like Arkema and Solvay focus on high-margin specialty applications in aerospace and chemical processing. Meanwhile, Chinese manufacturers such as Dongyue Group and Zhejiang Juhua are rapidly scaling capacity to meet battery sector demand.
Polyvinylidene fluoride is a highly non-reactive thermoplastic fluoropolymer produced by the polymerization of vinylidene difluoride. Its inherent properties include high purity, resistance to solvents and acids, and piezoelectric characteristics. Homopolymer grades dominate the market by volume, especially for coatings and chemical processing applications. However, copolymer formulations used in membrane filtration and electrical & electronics, specifically for battery binders, represent the fastest-growing segment.
Material standards are influenced by regulations governing end-use applications, such as the EU's REACH framework for chemical safety and FDA requirements in the United States for food contact materials. In Asia, China's GB standards dictate quality for materials used in domestic electronics and automotive supply chains. Suppliers must navigate these divergent regional specifications while deciding where to allocate capital for new capacity, either in mature industrial markets or high-growth battery ecosystems.
Market Dynamics
The central dynamic shaping the market is the bifurcation between high-purity, battery-grade PVDF and traditional industrial grades. Escalating demand from the electric vehicle sector for lithium-ion battery binders is concentrating investment and innovation on performance-specific formulations, creating a distinct, high-value market tier.
Growth Catalysts
- EV Policy Incentives:Government mandates and subsidies, such as the US Inflation Reduction Act (IRA), accelerate domestic battery production, directly stimulating demand for PVDF as a critical cathode binder and separator coating material.
- Water Treatment Expansion:The material's use in membrane filtration is growing due to global investments in desalination and wastewater treatment facilities, where PVDF's chemical resistance and durability are essential.
- Advanced Battery Chemistries:The development of next-generation lithium-ion batteries with higher energy densities requires advanced PVDF copolymer binders that offer superior electrochemical stability and adhesion, driving material innovation.
Market Restraints
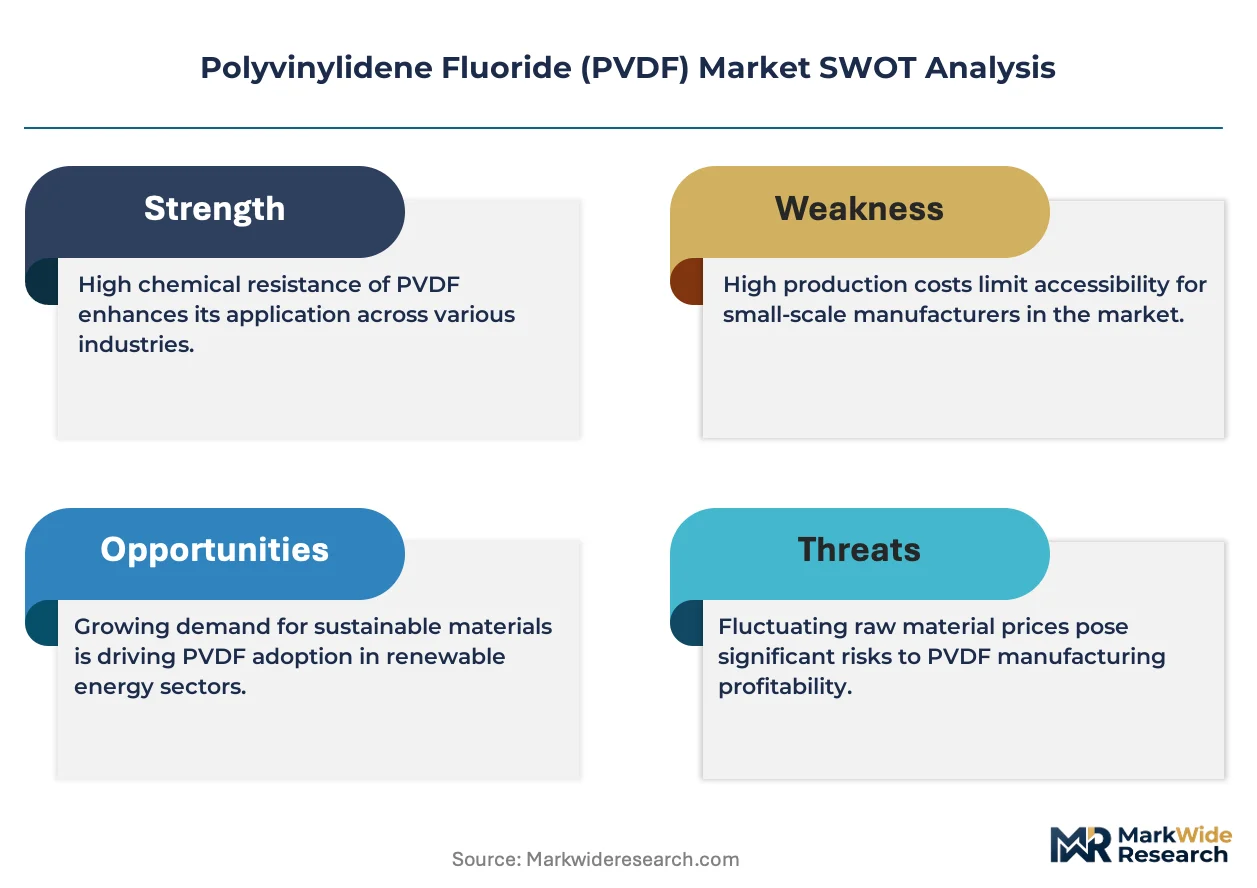
- Raw Material Volatility:The supply and cost of fluorspar, the primary feedstock for vinylidene difluoride monomer, are subject to geopolitical tensions and mining regulations, creating price instability for PVDF producers.
- Threat of Substitution:In certain battery anode applications, alternative binders like styrene-butadiene rubber (SBR) and carboxymethyl cellulose (CMC) present a lower-cost substitute, limiting PVDF's penetration in some segments.
- Regulatory Scrutiny:The classification of some fluorochemicals under broad regulatory frameworks like the EU's REACH presents compliance hurdles and potential restrictions, adding to long-term market uncertainty.
Strategic Opportunities
- Piezoelectric Applications:The inherent piezoelectric properties of PVDF create opportunities in high-sensitivity sensors, actuators, and energy harvesting devices for the industrial internet of things (IIoT) and wearable electronics.
- Indian Industrial Growth:Expansion of chemical processing, pharmaceutical, and semiconductor manufacturing in India provides an underpenetrated market for PVDF coatings, piping, and ultra-pure fluid handling systems.
- Solid-State Batteries:The shift toward solid-state battery architectures opens new applications for PVDF as a component in composite solid electrolytes or as a flexible separator, representing a significant future growth vector.
Industry Challenges
- Capital-Intensive Expansion:Constructing new polymerization plants capable of producing the high-purity PVDF required for battery applications demands significant capital investment and long lead times, slowing supply response.
- Standardization Gaps:Divergent quality specifications between regions, such as China's GB standards for automotive components and FDA food-contact requirements in the US, complicate global supply chain management for multinational producers.
- Specialized Talent Shortage:A lack of available polymer scientists and process engineers with expertise in fluoropolymer synthesis and high-purity manufacturing constrains research and development as well as production scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyvinylidene Fluoride (PVDF) Market |
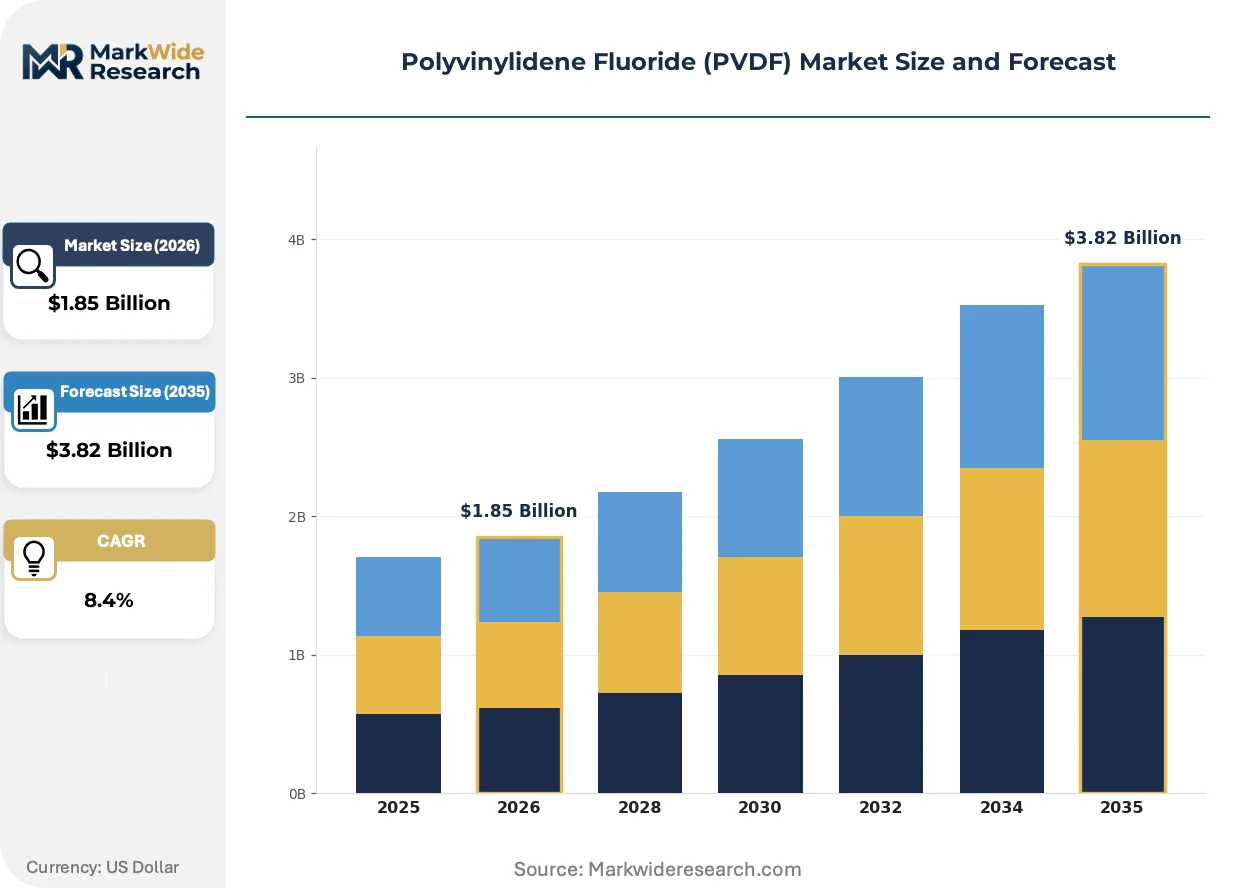
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homopolymer, Copolymer, Terpolymer, Blend Form: Film, Membrane, Tubing, Pellets, Powder Application: Electrical & Electronics, Chemical Processing, Membrane Filtration, Coatings, Architectural End User Industry: Electronics Manufacturing, Water Treatment, Construction, Chemical Manufacturing, Aerospace |
| Companies Covered | Dongyue Group, 3M, Arkema, Zhejiang Juhua, Sinochem Lantian, Solvay, Kureha Corporation, Saint-Gobain, Daikin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyvinylidene Fluoride (PVDF) Market Strategic Shifts & Innovations
Material development is pivoting toward functional specialization, driven by performance demands from the electronics and renewable energy sectors. This evolution is reshaping PVDF from a versatile industrial polymer into a critical enabling material for advanced technologies, influencing both production processes and supply chain priorities.
Copolymer formulations of PVDF provide enhanced flexibility and solubility compared to homopolymers. Battery manufacturers are rapidly adopting these copolymers for cathode binders to accommodate the volumetric changes in high-capacity active materials during charging cycles. Consequently, PVDF copolymer technology is expanding into separator coatings and solid-state electrolyte composites, moving beyond its binder function to improve overall cell safety and longevity.
European regulatory proposals under REACH to restrict a broad range of per- and polyfluoroalkyl substances (PFAS) are creating significant market uncertainty. This action is forcing a re-evaluation of fluoropolymer use, even for stable polymers like PVDF, which are considered polymers of low concern. The coatings and chemical processing industries in the EU are most affected, prompting preemptive research into non-fluorinated materials for applications requiring chemical resistance.
Certification-driven procurement is becoming standard in high-purity applications. End-users in the semiconductor and biopharmaceutical industries now specify PVDF grades that meet stringent non-leaching and purity standards, such as those for ultra-pure water systems. This behavior shifts purchasing decisions away from cost-per-kilogram and toward validated performance, a trend most visible in components for single-use bioprocessing assemblies and microelectronics fabrication.
Polyvinylidene Fluoride (PVDF) Market Segmentation
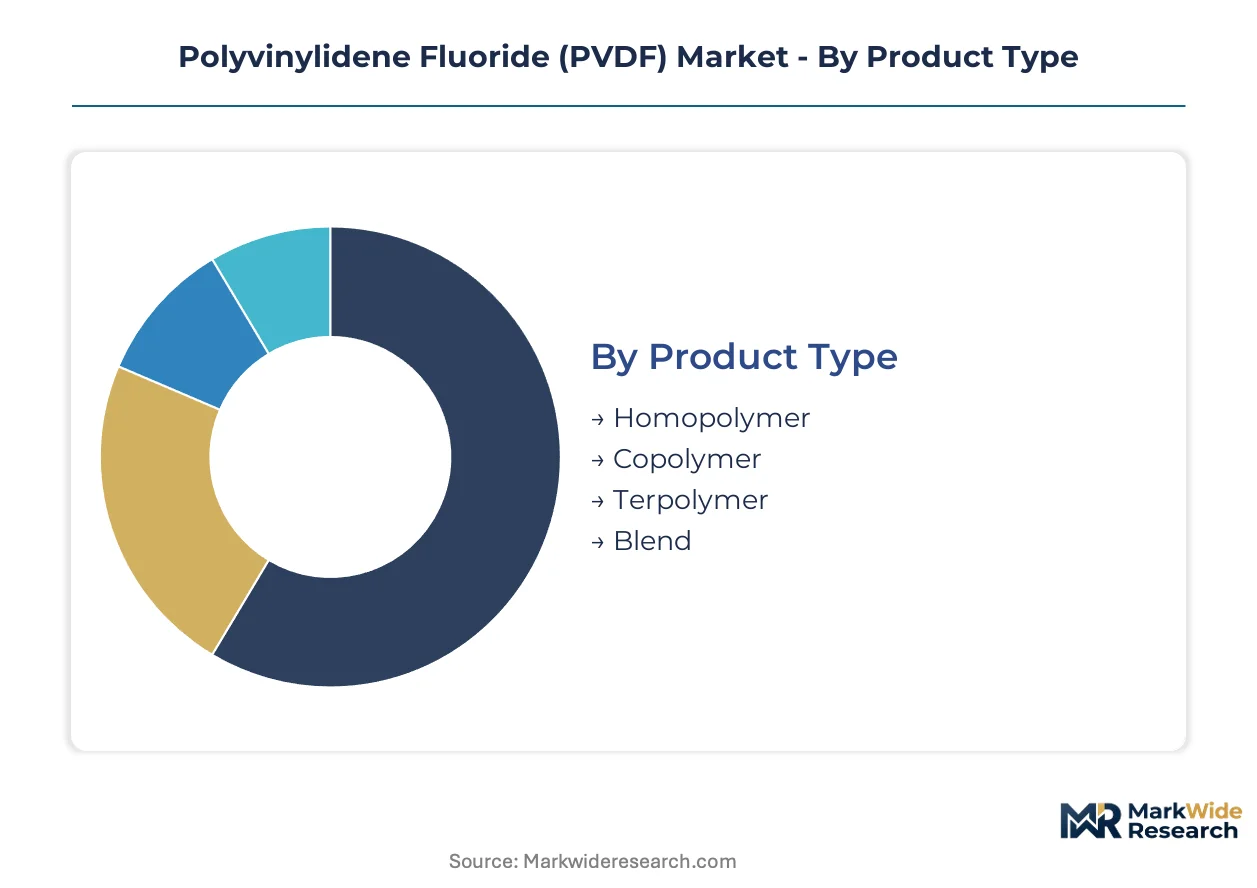
The Polyvinylidene Fluoride (PVDF) market segmentation highlights the material's diverse applications and evolving product forms. This structural breakdown helps identify distinct value pools and growth vectors, from commodity grades to high-purity specialty formulations. Understanding these segments is crucial for strategic investment and capacity planning across the supply chain.
Product Type:
Product type segmentation reveals the spectrum from standardized, high-volume materials to highly customized, performance-driven formulations.
- Homopolymer:This PVDF grade consists solely of vinylidene difluoride repeating units, offering high crystallinity, stiffness, and chemical resistance for general industrial uses. Demand for homopolymers remains significant in coatings and traditional chemical processing applications due to their cost-effectiveness and proven durability.
- Copolymer:These PVDF grades incorporate comonomers like hexafluoropropylene (HFP) or chlorotrifluoroethylene (CTFE), enhancing flexibility, processability, and solubility. Copolymer formulations are experiencing rapid demand growth as cathode binders in lithium-ion batteries for electric vehicles, where their electrochemical stability is critical.
- Terpolymer:Terpolymers include three different monomer units, providing even greater flexibility and lower melting points for specialized film and membrane applications.
- Blend:PVDF blends combine the fluoropolymer with other polymers to achieve specific property enhancements, such as improved impact strength or reduced cost, serving niche industrial requirements.
Most installed capacity flows through Homopolymer grades. Expansion is steepest in Copolymer formulations.
Form:
The various forms of PVDF underscore its adaptability, enabling diverse end-use applications through specific manufacturing processes.
- Pellets:These are the primary raw material form for most PVDF processing, used in extrusion, molding, and compounding to create other product shapes. Global manufacturers convert PVDF pellets into films, tubes, and other components for industrial and consumer goods.
- Membrane:PVDF membranes, typically produced via phase inversion, offer high chemical resistance, thermal stability, and mechanical strength for filtration applications. The water treatment sector relies on PVDF membranes for ultrafiltration and microfiltration in desalination and wastewater purification plants.
- Film:PVDF films are thin, flexible sheets utilized in electrical insulation, protective laminates, and piezoelectric sensors due to their dielectric and mechanical properties.
- Tubing:PVDF tubing provides excellent chemical inertness and purity, making it suitable for fluid handling systems in semiconductor manufacturing and pharmaceutical processing.
- Powder:PVDF powder is employed in coatings, binders, and battery electrode slurries, offering fine dispersion and specific rheological properties for specialized formulations.
The largest volume consumption occurs in Pellets, driving subsequent downstream processing. Demand for Membrane forms is gaining significant traction in environmental applications.
Application:
PVDF applications demonstrate the material's critical role across various industries, with some segments contributing significantly more volume than others.
- Electrical & Electronics:This segment includes PVDF use as a binder in lithium-ion battery electrodes, a dielectric in capacitors, and a piezoelectric material in sensors. The electrification trend, particularly in electric vehicles, drives substantial demand for battery-grade PVDF in this category.
- Chemical Processing:PVDF's exceptional resistance to harsh chemicals, acids, and solvents makes it ideal for lining pipes, tanks, and pumps in chemical manufacturing facilities. This application represents a mature but stable segment, ensuring safe and durable infrastructure for industrial processes.
- Membrane Filtration:PVDF is widely used in water treatment and industrial filtration membranes due to its hydrophobicity and resistance to fouling agents.
- Coatings:PVDF-based coatings provide weatherability, UV resistance, and corrosion protection for architectural surfaces and industrial equipment.
- Architectural:This application leverages PVDF's durability and aesthetic retention for long-lasting exterior building panels and roofing materials.
The Chemical Processing segment represents a foundational market for PVDF. The Electrical & Electronics segment is currently experiencing the most dynamic expansion.
End User Industry:
The end-user industry segmentation highlights the diverse customer bases and specific demand drivers influencing PVDF consumption patterns.
- Electronics Manufacturing:This industry segment consumes PVDF primarily for battery production, semiconductor components, and electronic device casings. Policy incentives like the US Inflation Reduction Act directly stimulate PVDF demand from electronics manufacturers focusing on electric vehicle battery cells.
- Chemical Manufacturing:Chemical manufacturers are significant end-users, relying on PVDF for corrosion-resistant piping, valves, and storage solutions within their production plants. The material's inertness ensures operational safety and extends equipment lifespan in aggressive chemical environments.
- Water Treatment:This sector utilizes PVDF in membrane modules for desalination, wastewater purification, and industrial process water filtration systems.
- Construction:The construction industry uses PVDF in architectural coatings and weather-resistant membranes for building envelopes, valuing its durability and low maintenance.
- Aerospace:PVDF finds application in aerospace for wire insulation, fuel system components, and interior panels due to its flame retardancy and high-temperature performance.
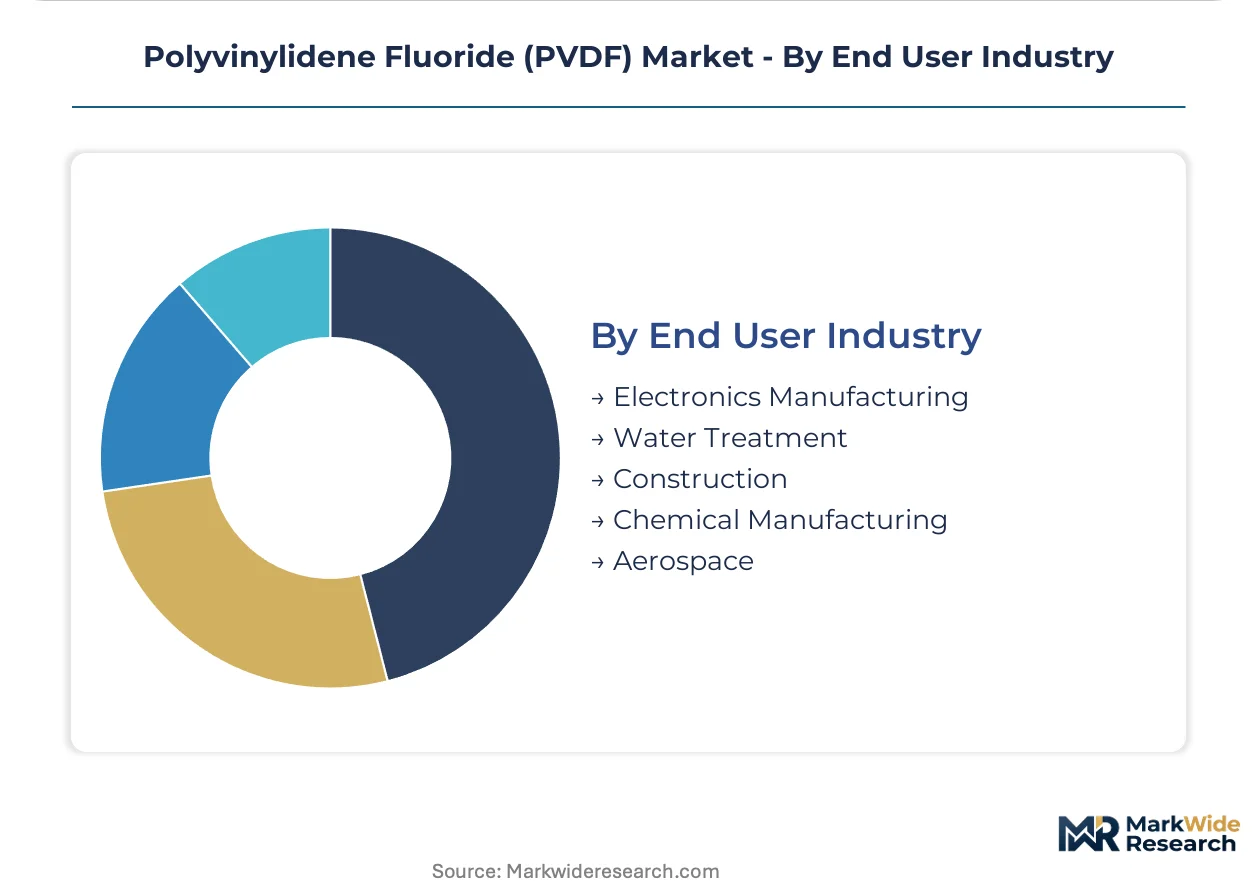
Chemical Manufacturing historically drives consistent PVDF demand. However, the Electronics Manufacturing sector exhibits the most significant growth potential due to battery technology advancements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While China dominates the production of battery-grade PVDF, the United States is rapidly stimulating demand through policy incentives. This dynamic creates distinct regional investment patterns and supply chain configurations for the material.
China
Demand for PVDF in China is driven by the rapid expansion of electric vehicle battery manufacturing and electronics production. The country's GB standards dictate quality for materials used in domestic automotive and electronics supply chains. Major industrial clusters in the Yangtze River Delta and Pearl River Delta are concentrating PVDF capacity for local battery cell producers.
United States
The United States sees strong PVDF demand from the domestic battery manufacturing sector, spurred by EV policy incentives. The US Inflation Reduction Act (IRA) directly stimulates investment in local battery production. States like Georgia and Michigan are becoming hubs for new battery gigafactories, requiring significant PVDF supply.
Germany
Germany's PVDF consumption is significant in its advanced chemical processing industry and growing electric vehicle sector. European regulations like REACH influence material specifications for chemical safety and environmental compliance. The industrial heartland of North Rhine-Westphalia hosts major chemical companies utilizing PVDF in infrastructure.
Japan
Japan's electronics manufacturing and chemical processing industries create consistent demand for high-performance PVDF. METI initiatives support advanced materials research and development for next-generation battery chemistries. Industrial centers around Tokyo and Osaka are key areas for PVDF application in specialized electronic components.
India
India presents an underpenetrated market for PVDF, with demand growing from its expanding chemical processing and pharmaceutical sectors. The country's PLI scheme for advanced chemistry cell batteries could stimulate future PVDF use. States like Gujarat and Maharashtra are witnessing investments in chemical and manufacturing facilities requiring PVDF materials.
Polyvinylidene Fluoride (PVDF) Market Key Industry Players
Top-tier vendors anchor the high-purity specialty PVDF market, while a growing number of manufacturers compete aggressively in the volume-driven battery-grade segment. This market structure supports distinct strategic archetypes, including established fluoropolymer giants and specialized battery material suppliers. Dominant competitive moves include significant capacity expansion in Asia and strategic partnerships within the electric vehicle supply chain.
On the high-purity specialty vector, European producers like Arkema and Solvay exemplify a focus on advanced applications in aerospace and chemical processing, leveraging their established technological expertise. Meanwhile, Dongyue Group, a prominent Chinese manufacturer, represents the rapid scaling of capacity to meet the substantial demand from the battery sector. These companies collectively shape the market's evolving supply dynamics and product specialization.
| Leading Market Players |
|---|
| Dongyue Group |
| 3M |
| Arkema |
| Zhejiang Juhua |
| Sinochem Lantian |
| Solvay |
| Kureha Corporation |
| Saint-Gobain |
| Daikin Industries |
| Others |
Cost & Logistics Intelligence
Fluorspar price volatility, a key raw material for PVDF, cascades through the supply chain, influencing the two-tiered pricing structure of commodity and specialty grades.
Pricing Analysis
Capacity additions in China are reshaping price floors for homopolymer PVDF grades, establishing a commodity spot pricing model. Price differentiation stems from quality grade, particularly for high-purity battery formulations, and specific end-use certifications like FDA requirements. Pricing softness affects traditional industrial grades due to increased supply. Chemical processing and general industrial buyers often exhibit higher price sensitivity compared to specialized electronics manufacturers.
Supply Chain Analysis
US Inflation Reduction Act (IRA) domestic-content mandates are reshaping sourcing strategies for battery-grade PVDF, encouraging localized production. Geographic supply concentration for PVDF manufacturing remains significant in China, with specialty producers in Europe and Japan. The supply chain relies on fluorspar and vinylidene difluoride monomer. Regulatory scrutiny, such as the EU's REACH framework, presents a structural risk for fluorochemicals. Distribution runs through direct long-term contracts for battery and specialty applications, complemented by regional distributors for industrial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PVDF market presents a significant margin-expansion story, driven by the increasing demand for high-purity battery-grade formulations. This shift enables premium pricing for performance-specified materials.
For Market Incumbents:
Anchor existing market share in traditional homopolymer applications by optimizing production efficiency and securing long-term raw material contracts. Invest in R&D for advanced copolymer binders to counter the threat of alternative battery materials like SBR and CMC. Pursue strategic partnerships with electric vehicle battery manufacturers to integrate into their supply chains. Expand high-purity PVDF capacity in strategic regions like the United States to align with policy incentives.
For New Entrants and Emerging Players:
Enter via specialized niche applications requiring unique PVDF properties, such as piezoelectric sensors or components for solid-state batteries. Target underpenetrated markets like India's expanding industrial and pharmaceutical sectors, offering customized PVDF formulations. A go-to-market angle focused on technical support and performance validation, rather than solely on cost, can differentiate new players. Focus on specific copolymer blends for advanced battery chemistries where performance demands are highest.
For Investors and Strategic Acquirers:
Asymmetric upside sits with mid-sized producers possessing proprietary copolymer technologies or established high-purity manufacturing expertise. The long-term viability of specialty PVDF remains strong, supported by global electrification trends and advanced material requirements. An acquisition target archetype includes companies with strong intellectual property in fluoropolymer synthesis or strategic production assets in key battery manufacturing hubs. A signal to watch is the acceleration of large-scale battery-grade PVDF capacity announcements outside of traditional Asian production centers.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Battery-Grade PVDF | Meets the growing demand from electric vehicle battery manufacturers globally. |
| Strategic Partnerships with EV Battery OEMs | Secures long-term supply agreements and integrates PVDF suppliers into critical value chains. |
| R&D Investment in Advanced Copolymers | Enhances material performance for next-generation lithium-ion and solid-state batteries. |
| Compliance with Regional Regulatory Standards | Navigates diverse specifications like EU REACH and China's GB standards for market access. |
| Geographic Diversification of Manufacturing | Mitigates supply chain risks and capitalizes on policy incentives such as the US IRA. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, forming a robust data collection strategy. Primary research involved discussions with polymer scientists, R&D directors, procurement leads at battery manufacturers, and chemical plant managers. Secondary validation drew from industry association reports, government energy and automotive policy documents, company SEC filings, and patent databases. This approach facilitated both bottom-up market sizing and top-down validation.
The forecast framework anchored the projection period to historical reference periods, analyzing market evolution through comparable cycles. Segmentation dimensions modeled included product type, form, application, end-user industry, and regional production capacity. Compound annual growth rates were derived from historical trends, future demand projections, and expert consensus. Key industry-specific forecast inputs included electric vehicle production targets, advancements in battery energy density, and global water treatment infrastructure investments.
Inputs from industry reports and company disclosures were available through the study window; gaps in proprietary R&D budgets and specific long-term supply contracts introduce uncertainty bands. Forecasts reflect assumptions regarding regulatory stability, raw material availability, and technological adoption rates. A small set of named triggers, including new regulatory proposals or significant material substitution breakthroughs, warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Semiconductor Grade PTFE Market
Semiconductor Material
North America Semiconductor Materials Market
Semiconductor Material
Wet Chemicals for Electronics and Semiconductor Application Market
Semiconductor Material
Polysilicon for Solar Semiconductor Market
Semiconductor Material
Polycrystalline Silicon Market
Semiconductor Material
Polysilicon Market
Semiconductor Material
India Liquid Silicon Rubber Market
Semiconductor Material
Titanium Diboride Market
Semiconductor Material
Metallurgical Grade Silicon Market
Semiconductor Material
Sputtering Target Market
Semiconductor Material
Semiconductor Silicon Material Market
Semiconductor Material
Electronic Thermal Management Materials Market
Semiconductor Material
Vietnam Semiconductor Materials Market
Semiconductor Material
Tungsten Market
Semiconductor Material
Global Thermal Paste Market
Semiconductor Material
Semiconductor Grade Neon Gas Market