
 North America Semiconductor Materials Market | 2026-2036
North America Semiconductor Materials Market Size, Share, and Industry Trends Forecast 2026-2036
North America Semiconductor Materials Market Intelligence
The EPA's emerging PFAS restrictions under TSCA Section 6 is pivoting semiconductor materials procurement toward fluorine-free chemistries. DuPont de Nemours, Inc. anchors North American photoresist supply through deep R&D investment in non-fluorinated formulations. Applied Materials, Inc. dominates equipment-integrated materials delivery, leveraging its installed base to bundle consumables. II-VI Incorporated specializes in compound semiconductor substrates, competing on silicon carbide and gallium nitride wafer quality for power electronics.
North America semiconductor materials encompass high-purity substrates, process chemicals, gases, and deposition targets engineered to atomic-scale tolerances for integrated circuit fabrication. Silicon wafers require single-crystal ingots with defect densities below one per square centimeter to yield functional dies at advanced nodes. Photoresists lead product type margins due to formulation complexity and duopoly-like supply concentration among qualified vendors. Front-end manufacturing stage consumption outpaces back-end in absolute volume, though packaging materials accelerate fastest as chiplet architectures multiply die-count per device.
The EPA enforces TSCA Section 6 restrictions on per- and polyfluoroalkyl substances that directly impact photoresist and etchant formulations used in U.S. fabs. OSHA's permissible exposure limits for semiconductor process chemicals shape cleanroom ventilation and worker safety equipment standards across Arizona, Texas, and Oregon facilities. Canada's PMRA coordinates with EPA on chemical substance reviews, creating cross-border compliance obligations for suppliers serving Ontario and Quebec packaging houses. Stakeholders must monitor state-level chemical disclosure laws in California and Washington that extend beyond federal minimums.
Market Dynamics
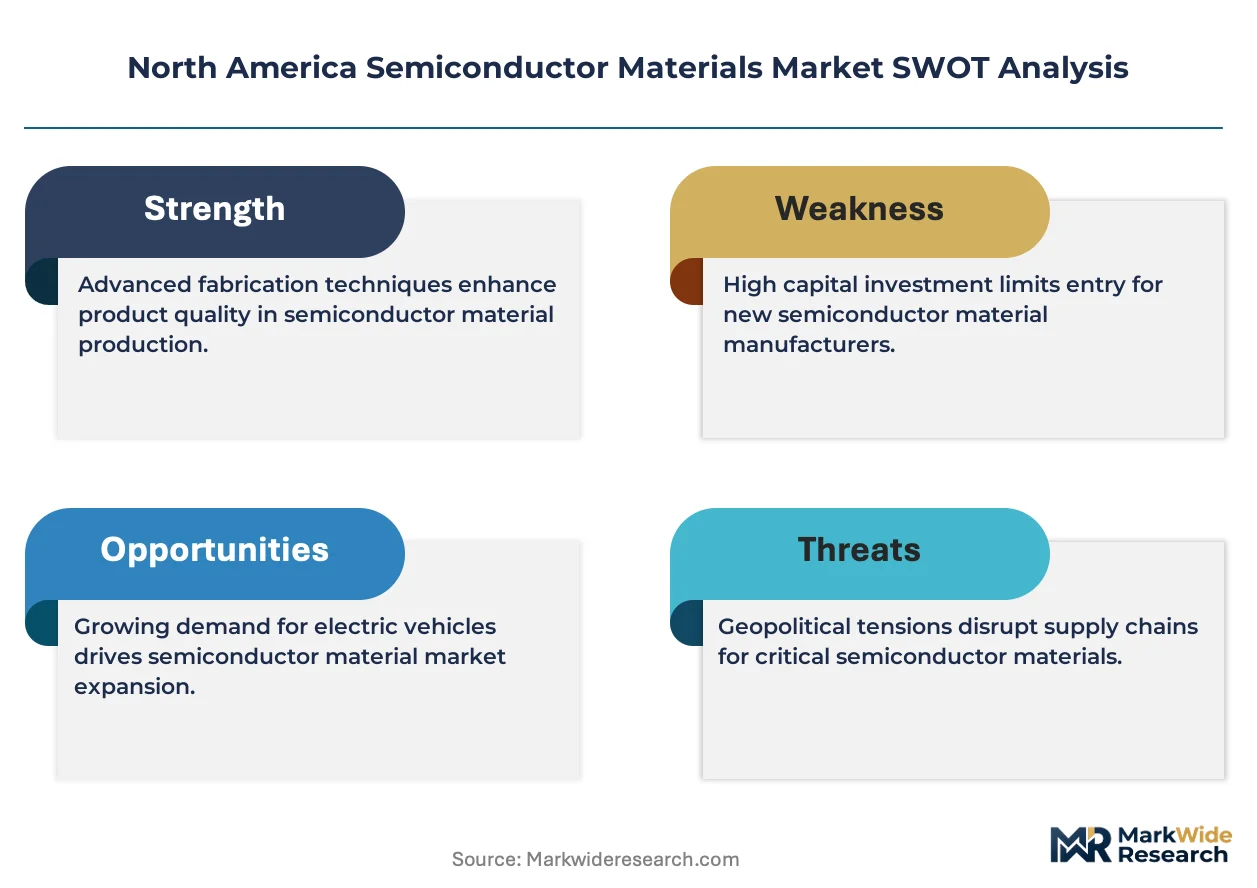
EPA's TSCA Section 6 restrictions on PFAS chemistries are forcing immediate photoresist reformulation across Texas and Arizona fab clusters, compressing supplier qualification timelines while redirecting R&D spend toward fluorine-free alternatives.
Growth Catalysts
- Automotive electronics demand:Michigan and Ontario manufacturing corridors are scaling silicon carbide substrate consumption for electric vehicle powertrains.
- CHIPS Act funding:Federal capital allocation is accelerating wafer start capacity in Phoenix and Austin metro areas.
- Advanced packaging proliferation:Chiplet architectures are multiplying die-count per device, expanding back-end materials volume faster than front-end.
Market Restraints
- High-purity gas supply concentration:Bulk specialty gas production clusters in Gulf Coast petrochemical corridors, creating hurricane exposure risk.
- PFAS regulatory friction:EPA's evolving TSCA Section 6 restrictions are forcing premature depreciation of qualified chemistries before replacements achieve parity.
- Silicon carbide substrate yield limitations:Defect densities in wide-bandgap ingots remain above silicon baselines, constraining power electronics scaling.
Strategic Opportunities
- Mexico packaging expansion:Guadalajara and Tijuana are attracting OSAT investment seeking tariff-advantaged access to US end-markets.
- Fluorine-free photoresist qualification:First-mover suppliers achieving EPA-compliant formulation parity will capture share during mandatory transition windows.
- Deposition target remanufacturing:Closed-loop recycling of high-purity tantalum and copper targets is reducing virgin material dependence for Arizona sputtering operations.
Industry Challenges
- Cleanroom technician scarcity:Phoenix and Austin metro areas face acute shortages of contamination control specialists qualified at ISO Class 1 standards.
- Dual-use export control alignment:BIS Entity List restrictions are complicating equipment and materials procurement for fabs with cross-border supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Semiconductor Materials Market |
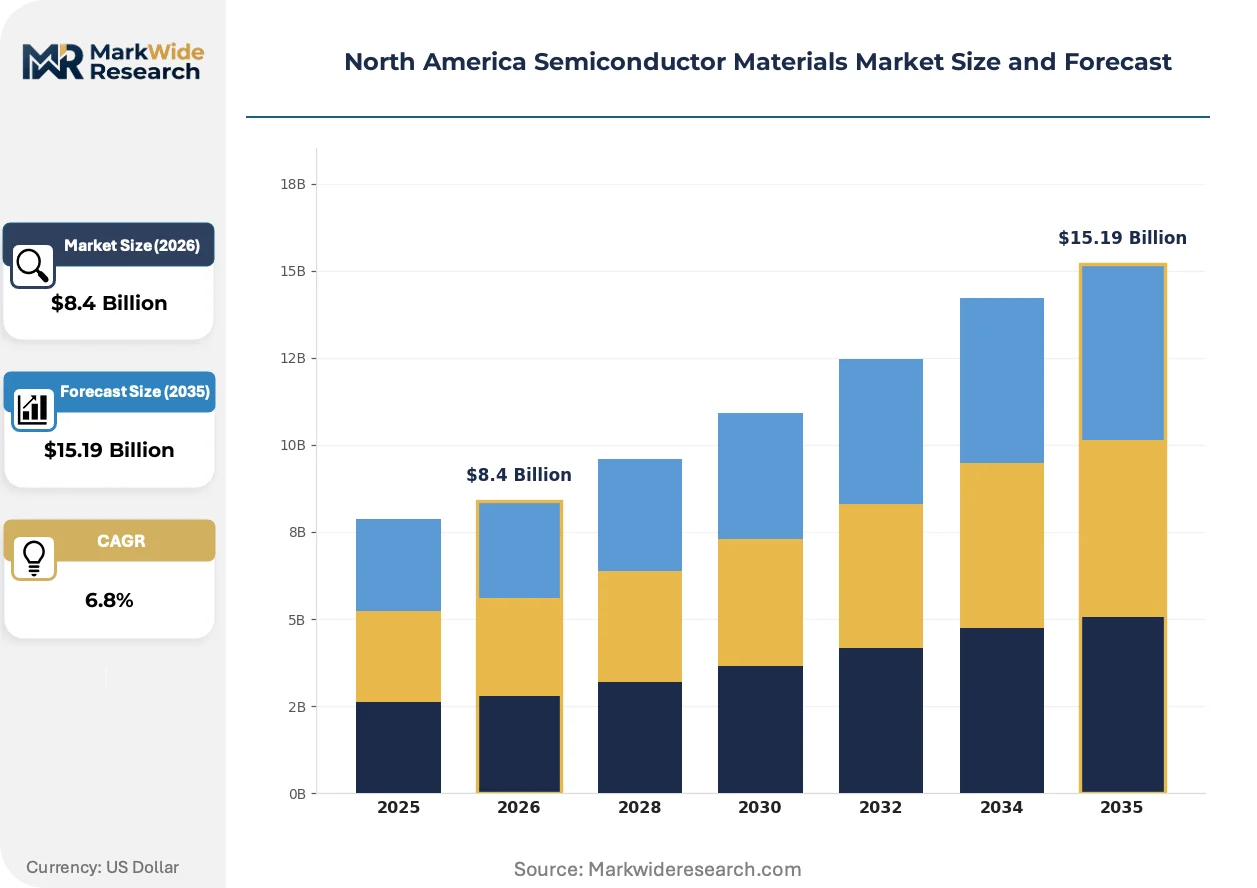
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Wafers, Photoresists, Conductive Polymers, Epoxy Resins Manufacturing Stage: Front-End, Back-End, Packaging, Testing End User: Consumer Electronics, Automotive Electronics, Telecommunications, Industrial Automation Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Applied Materials, Inc., DuPont de Nemours, Inc., Honeywell International Inc., Air Liquide S.A., II-VI Incorporated, Skyworks Solutions, Inc., Qorvo, Inc., Merck KGaA, Fujifilm Electronic Materials, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Semiconductor Materials Market Strategic Shifts & Innovations
Atomic-scale deposition control and chemistry reformulation are converging to reshape materials specification and supplier qualification protocols across North American fabrication facilities.
EUV lithography is consolidating photoresist supply around non-fluorinated chemistries as TSMC Arizona and Intel New Mexico operations scale 3nm-class wafer starts. These fabs are accelerating vendor requalification timelines to meet EPA compliance deadlines. The technology is consolidating formulation R&D spend toward DuPont and JSR alternatives that achieve line-edge roughness parity without perfluorinated backbones.
EPA's TSCA Section 6 rulemaking on PFAS is mandating full chemical disclosure across photoresist and etchant supply chains. Industrial consequence includes forced inventory drawdown of legacy formulations before replacement qualification completion. Arizona fabs are most affected, responding with accelerated alternative vendor onboarding and temporary process window compression.
Buyer concentration among TSMC, Intel, and Samsung Austin is compressing supplier negotiation cycles from annual to quarterly frameworks. Direct procurement teams are displacing distributor intermediaries for high-volume gases and sputtering targets. This shift is most visible in Texas, where fab clusters are consolidating spend under master service agreements with penalty clauses for supply interruption.
North America Semiconductor Materials Market Segmentation
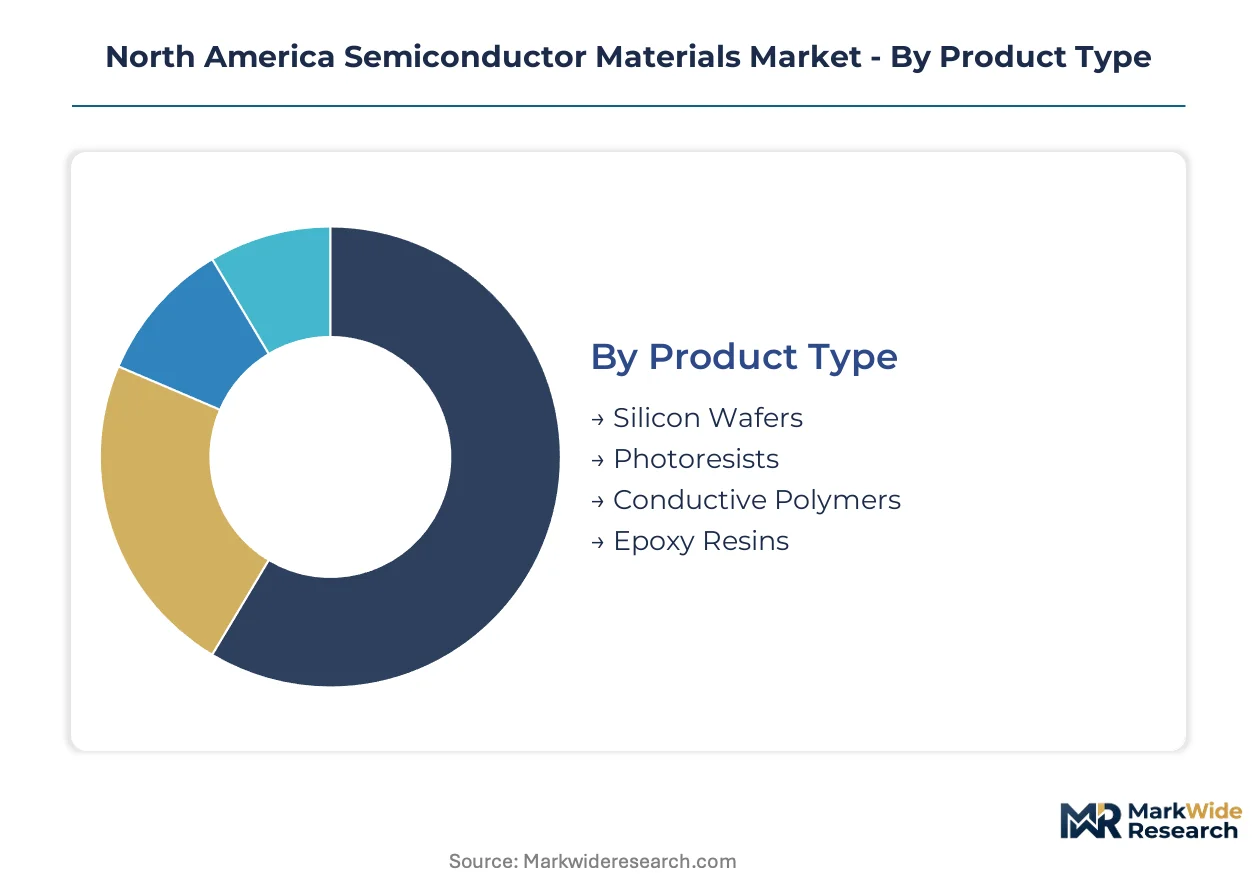
Semiconductor materials command sharply divergent pricing and qualification protocols depending on product purity, process integration depth, and end-use reliability requirements. Understanding how volume tiers map to margin structures reveals where supplier power concentrates and where new entrants face lowest barriers.
Product Type:
Volume consumption concentrates in commodity substrates while formulation complexity drives premium capture in lithography chemistries.
- Silicon Wafers:Single-crystal ingots sliced to atomic-scale flatness specifications dominate physical volume across Arizona and Texas fab clusters. TSMC and Intel procurement contracts favor 300mm diameter formats with defect densities below one per square centimeter.
- Photoresists:Formulation intricacy creates the steepest margin tier in this category. EPA TSCA Section 6 PFAS restrictions are forcing immediate reformulation of fluorinated chemistries, compressing DuPont and JSR qualification timelines for fluorine-free alternatives.
- Conductive Polymers:Organic semiconductors and printable electronics substrates serve emerging flexible display and sensor applications.
- Epoxy Resins:Underfill and molding compounds protect die interconnects in advanced packaging operations across Guadalajara and Tijuana OSAT facilities.
Today's leader: Silicon Wafers. Tomorrow's challenger: Photoresists.
Manufacturing Stage:
Front-end materials absorb the majority of absolute spend while back-end consumption multiplies fastest as chiplet architectures proliferate.
- Front-End:Deposition targets, high-purity gases, and photoresists feed lithography, etch, and thin-film processing at TSMC Arizona and Intel New Mexico fabs. Process chemical consumption scales directly with wafer start capacity expansion under CHIPS Act funding.
- Back-End:Die attach adhesives, wire bonding materials, and substrate laminates serve assembly operations. Michigan and Ontario automotive electronics corridors are driving silicon carbide substrate demand for power module packaging.
- Packaging:Emerging as the steepest expansion trajectory as chiplets multiply die-count per device. Redistribution layer dielectrics and microbump metallurgies command premium pricing in 2.5D and 3D configurations.
- Testing:Probe card materials and test socket contacts consume specialized alloys and ceramic substrates for wafer-level and final test operations.
Front-End retains spend dominance. Packaging climbs the fastest.
End User:
Automotive qualification standards create the steepest entry barriers while consumer electronics offers the deepest volume.
- Consumer Electronics:Smartphones, tablets, and personal computing devices drive baseline silicon wafer consumption. Arizona and Texas fab output feeds Qualcomm and Apple processor demand with high-volume, cost-optimized material specifications.
- Automotive Electronics:Functional safety requirements under AEC-Q100 standards impose stringent traceability and reliability testing on materials suppliers. Silicon carbide power devices for electric vehicle inverters are concentrating demand in Michigan and Ontario manufacturing corridors.
- Telecommunications:5G base station and optical networking components require compound semiconductor substrates for high-frequency performance.
- Industrial Automation:Motor drives, power supplies, and sensor systems consume discrete power semiconductors and mixed-signal devices.
Automotive Electronics sets the reliability benchmark. Consumer Electronics anchors volume scale.
Distribution Channel:
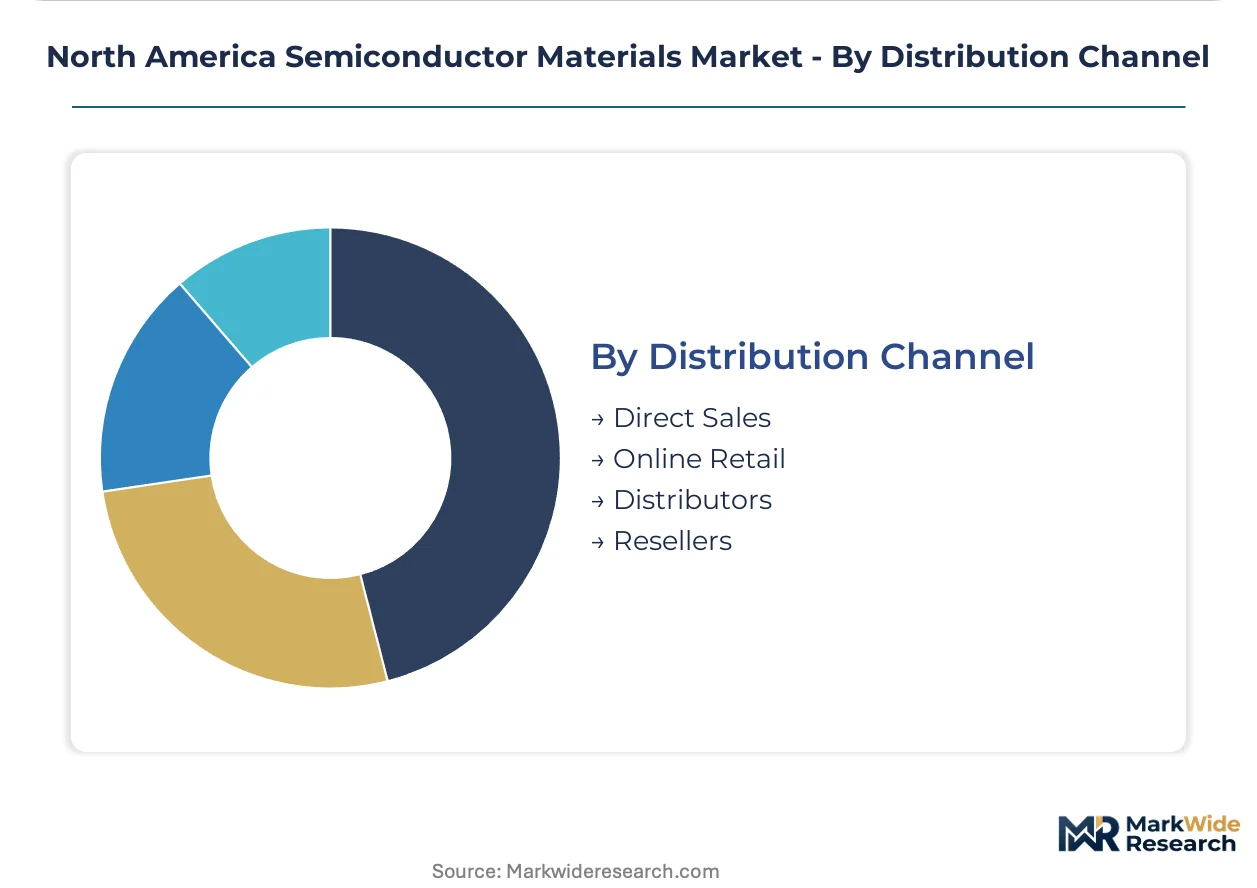
Buyer concentration among TSMC, Intel, and Samsung Austin is displacing intermediary layers for high-volume categories.
- Direct Sales:Master service agreements with penalty clauses for supply interruption dominate Texas fab cluster procurement for gases and sputtering targets. Quarterly negotiation cycles have replaced annual frameworks at major accounts.
- Distributors:Remain critical for mid-tier fabs and packaging houses requiring technical support and inventory buffering. Arrow Electronics and Avnet maintain regional stocking points for Arizona and Oregon facilities.
- Online Retail:Limited to prototype quantities and research institution purchases for specialty chemicals in small lot sizes.
- Resellers:Serve secondary market for excess inventory and obsolete formulations facing EPA-mandated phase-out.
Direct Sales commands strategic accounts. Distributors defend mid-market access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor materials manufacturing in North America traces its modern lineage to the 1950s transistor revolution in California's Santa Clara Valley, later expanding through federal defense procurement and venture capital concentration into the integrated circuit era. Texas Instruments and Fairchild Semiconductor established early process chemistry standards that persist in today's atomic-scale tolerances. The region's current materials demand concentrates in three sovereign markets with distinct regulatory and industrial profiles.
United States
CHIPS Act appropriations exceeding $50 billion are accelerating wafer start capacity in Phoenix and Austin metro corridors. EPA's TSCA Section 6 PFAS restrictions are forcing immediate photoresist reformulation timelines across Arizona fabs. Intel's New Mexico operations and TSMC Arizona anchor the highest-purity materials consumption clusters in the desert Southwest.
Canada
Automotive electronics qualification under AEC-Q100 standards is concentrating silicon carbide substrate demand in Ontario's Windsor-Toronto manufacturing corridor. PMRA coordinates chemical substance reviews with EPA, creating cross-border compliance obligations for suppliers serving Quebec packaging houses. Ottawa's Strategic Innovation Fund is targeting compound semiconductor substrate fabrication in the National Capital Region.
Mexico
Tariff-advantaged access to US end-markets is attracting OSAT investment to Guadalajara and Tijuana for advanced packaging operations. SEMARNAT chemical handling regulations govern specialty gas distribution to Baja California assembly facilities. The Bajío Region's Querétaro corridor is emerging as a secondary hub for automotive electronics module integration serving Detroit OEMs.
North America Semiconductor Materials Market Key Industry Players
Capital-heavy producers compete with asset-light designers across materials supply tiers. The North American semiconductor materials sector exhibits oligopolistic concentration in photoresist formulations alongside fragmented competition in deposition targets and specialty gases. Three strategic archetypes dominate: integrated equipment-materials bundlers, pure-play chemistry formulators, and compound substrate specialists. Competitive maneuvering centers on fluorine-free qualification racing and master service agreement consolidation with fab operators.
Among US-based diversified technology conglomerates, Honeywell International Inc. and Applied Materials, Inc. occupy positions spanning equipment-integrated materials delivery. DuPont de Nemours, Inc. exemplifies the chemistry formulator archetype through deep R&D positioning in photoresist innovation. II-VI Incorporated anchors the compound semiconductor substrate specialist tier, with its corporate name directly signaling focus on wide-bandgap materials for power electronics applications.
| Leading Market Players |
|---|
| Applied Materials, Inc. |
| DuPont de Nemours, Inc. |
| Honeywell International Inc. |
| Air Liquide S.A. |
| II-VI Incorporated |
| Skyworks Solutions, Inc. |
| Qorvo, Inc. |
| Merck KGaA |
| Fujifilm Electronic Materials |
| Others |
Cost & Logistics Intelligence
Captive photoresist formulation by DuPont and JSR anchors both supply security and premium pricing power across Arizona and Texas fab clusters, with EPA-mandated fluorine-free transitions reinforcing vendor lock-in through accelerated requalification timelines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EUV-grade photoresists from ArF immersion and legacy i-line formulations. Price differentiation hinges on certification tier and volume scale, with TSMC and Intel master service agreements commanding 15-20 point discounts against mid-tier fabs. Cost compression in commodity silicon wafers is intensifying because Chinese substrate oversupply is bleeding into spot markets. Packaging houses in Guadalajara exhibit highest price sensitivity, while automotive-qualified materials in Michigan show lowest.
Supply Chain Analysis
Photoresist supply rests on Japanese specialty chemical producers, with bulk gases drawing from Gulf Coast petrochemical corridors and silicon carbide substrates feeding from US and European ingot growers. Critical dependencies span high-purity hydrogen fluoride, neon gas for EUV lasers, and tantalum sputtering targets. Single-source vulnerability concentrates in PFAS-free photoresist precursors where DuPont and JSR maintain duopoly positions. Distribution runs through direct procurement teams at TSMC, Intel, and Samsung Austin, with Arrow Electronics buffering mid-tier accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America semiconductor materials market compounds steadily as CHIPS Act wafer start expansion creates durable demand pull through 2035.
For Market Incumbents: Anticipate PFAS regulatory tightening by accelerating fluorine-free formulation R&D and securing EPA pre-qualification ahead of mandatory transition windows. Consolidate position through backward integration into high-purity gas distribution networks across Arizona and Texas corridors. Lock in multi-year master service agreements with penalty structures that raise switching costs for TSMC and Intel procurement teams. For New Entrants and Emerging Players: Enter via deposition target remanufacturing services, where closed-loop recycling economics and lower capital barriers create viable entry points against virgin material suppliers. Target Mexico's Guadalajara packaging corridor for epoxy resin and underfill compounds, where OSAT investment is outpacing qualified local supply. Lead with technical service intensity and rapid qualification support rather than price undercutting. For Investors and Strategic Acquirers: Roll-up economics work for specialty gas distributors because fragmented regional players lack scale to serve CHIPS Act-funded fab expansions with required inventory buffers and technical support. Five-to-ten year viability hinges on exposure to advanced packaging materials growth vectors rather than commodity substrate cyclicality. Watch EPA TSCA Section 6 enforcement velocity as inflection signal—accelerated timelines favor incumbents with qualified alternatives, delays reopen windows for challengers.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Photoresist Qualification | EPA TSCA Section 6 compliance creates first-mover capture during mandatory chemistry transitions. |
| Deposition Target Remanufacturing | Closed-loop tantalum and copper recycling reduces virgin material dependence for Arizona sputtering operations. |
| Mexico Packaging Corridor Expansion | Guadalajara and Tijuana OSAT investment attracts tariff-advantaged materials supply for US end-markets. |
| Direct Procurement Team Buildout | TSMC and Intel displacement of distributors compresses negotiation cycles and raises switching costs. |
| Silicon Carbide Substrate Yield Improvement | Defect density reduction in wide-bandgap ingots unlocks Michigan and Ontario automotive power module demand. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fab procurement directors, cleanroom operations managers, specialty gas distribution executives, and photoresist R&D leads with secondary validation against SEC filings, EPA regulatory dockets, CHIPS Act appropriation disclosures, and customs trade data. Bottom-up wafer start capacity modeling and top-down materials intensity benchmarks were triangulated against supplier revenue disclosures.
Segment-weighting across product type, manufacturing stage, end user, and distribution channel dimensions drove value allocation throughout the projection horizon. CAGRs were derived from installed capacity buildout schedules, materials consumption per wafer start ratios, and pricing trajectory assumptions. Forecast inputs incorporated EPA regulatory timeline scenarios, CHIPS Act funding disbursement patterns, and automotive electronics qualification standards under AEC-Q100.
Inputs from primary stakeholder interviews and regulatory agency filings were available through the study window; gaps in proprietary supplier cost structures and unannounced fab expansion timelines introduce uncertainty bands around outer-year projections. Forecasts reflect documented assumptions regarding PFAS substitution pace, silicon carbide yield improvement curves, and Mexico OSAT investment velocity. Material deviation in EPA enforcement intensity, CHIPS Act funding continuity, or automotive demand cyclicality warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
DCB and AMB Substrate Market
Semiconductor Material
Yttrium Oxide Market
Semiconductor Material
Global Silicone Market
Semiconductor Material
Zinc Oxide Market
Semiconductor Material
Hafnium Market
Semiconductor Material
Europium Market
Semiconductor Material
Ultra High Purity Silicon Carbide Market
Semiconductor Material
Semiconductor Glass Market
Semiconductor Material
Europe Semiconductor Materials Market
Semiconductor Material
Polysilicon Market
Semiconductor Material
Global Strontium Market
Semiconductor Material
Semiconductor Grade PTFE Market
Semiconductor Material
Battery Silver Paste Market
Semiconductor Material
Global Inorganic Scintillators Market
Semiconductor Material
Taiwan Semiconductor Materials Market
Semiconductor Material
Metallurgical Grade Silicon Market