
 United States Semiconductor Memory Market | 2026-2036
United States Semiconductor Memory Market Size, Share, and Industry Trends Forecast 2026-2036
United States Semiconductor Memory Market Insights
Compute architectures is tilting toward memory-centric designs where data movement dominates performance ceilings. Micron Technology leverages its Idaho-based R&D footprint to sustain advanced DRAM process leadership. Samsung Austin Semiconductor anchors a significant share of domestic NAND output through its Texas fabrication complex. SK Hynix differentiates via HBM3E stack technology aimed at AI accelerator cards.
United States semiconductor memory encompasses volatile and non-volatile solid-state storage cells fabricated through photolithographic processes on silicon wafers, with critical parameters including cell density measured in gigabits per square millimeter, refresh rates for DRAM, and endurance cycles for NAND flash. These devices serve as primary working memory and persistent storage across computing systems. DRAM remains the margin pool leader in consumer electronics and data center applications, while AI-Driven technology segments show the fastest structural expansion due to training workload requirements. Flash Memory occupies the dominant position in mobile devices and automotive systems where form factor and shock tolerance matter.
The CHIPS and Science Act administered by the Department of Commerce shapes fab construction timelines and subsidy eligibility for domestic producers. NIST standards govern reliability testing protocols that determine qualification for defense and aerospace procurement channels. EPA emissions rules affect wet chemistry processes used in wafer fabrication. Stakeholders must monitor how BIS export controls on advanced manufacturing equipment alter capacity expansion plans and supplier qualification pathways.
Market Dynamics
Memory-centric compute architectures are forcing a structural reallocation of value from processors to storage hierarchies, as data movement bottlenecks now dominate system performance ceilings in AI training clusters across Virginia and Texas.
Growth Catalysts
- CHIPS Act incentives:Subsidies from the Department of Commerce compress fab construction timelines and lower capital barriers for domestic DRAM and NAND capacity expansion.
- Generative AI workloads:Data center operators in Northern Virginia and Dallas-Fort Worth are scaling HBM and high-density flash deployments to support training infrastructure.
- Automotive electronics:Michigan and California OEM procurement is concentrating around embedded memory for ADAS and infotainment systems requiring AEC-Q100 qualification.
Market Restraints
- Equipment concentration risk:BIS export controls on advanced lithography tools constrain capacity expansion timelines for sub-10nm nodes.
- Input cost volatility:Neon gas supply from Ukrainian purification facilities remains disrupted, elevating wafer processing costs for excimer laser operations.
- Technical limitation:DRAM cell scaling is approaching the capacitor aspect ratio physical limit, constraining bit density gains without 3D stacking.
Strategic Opportunities
- Edge AI deployment:Arizona and Oregon data center corridors present underpenetrated demand for low-latency memory pools serving inference at the network edge.
- Regulatory tailwind:NIST cybersecurity framework updates are mandating supply chain provenance documentation, favoring domestic qualified suppliers.
- Technology convergence:Compute Express Link (CXL) protocol adoption is virtualizing memory pooling across disaggregated server architectures.
Industry Challenges
- Process engineering talent scarcity:Advanced node development requires atomic layer deposition expertise that outpaces university pipeline output in Idaho and Texas.
- Cleanroom construction delays:EPA air quality permitting for wet chemistry exhaust systems extends fab readiness timelines in Phoenix and Austin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Semiconductor Memory Market |
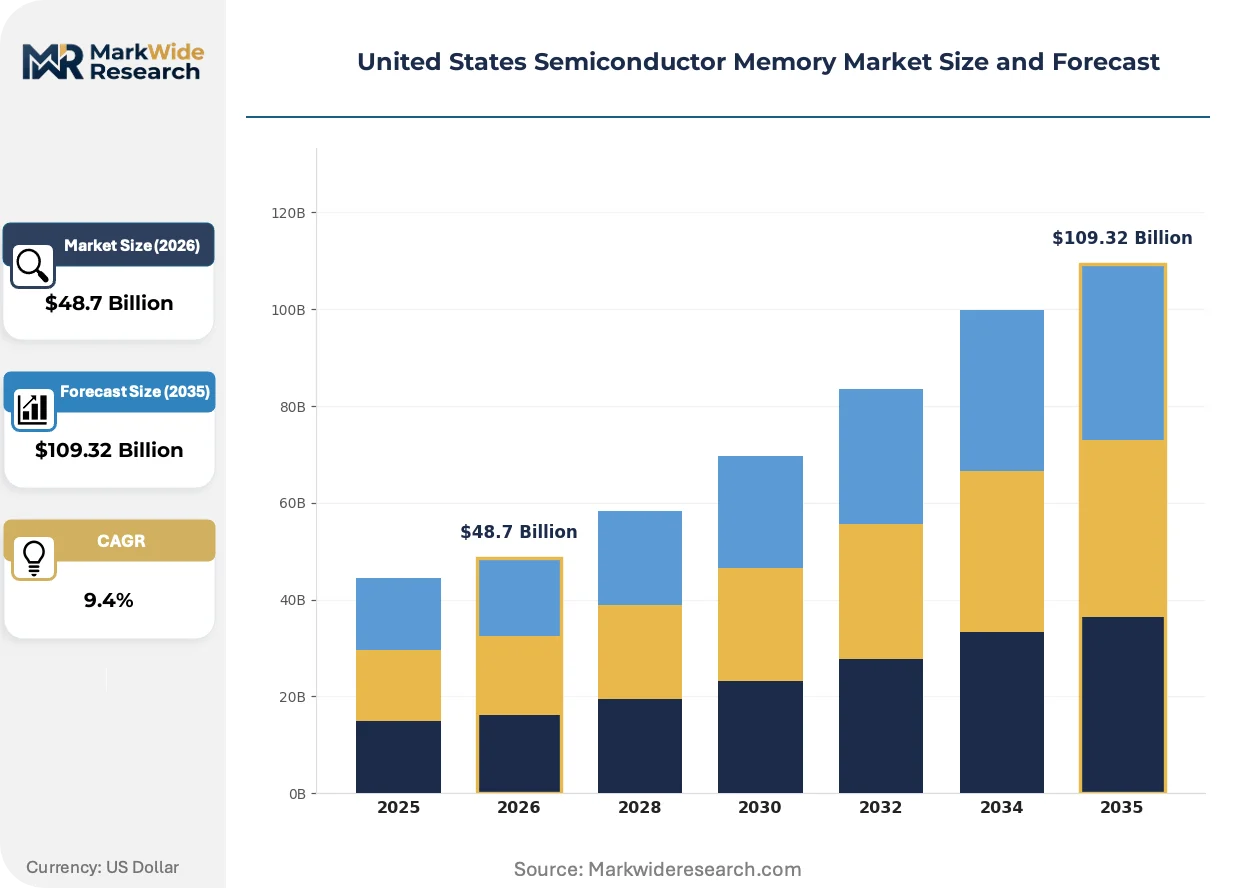
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $109.32 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DRAM, SRAM, Flash Memory, EEPROM End User: Consumer Electronics, Automotive, Telecommunications, Industrial Technology: 4G, 5G, AI-Driven, Cloud-Based Application: Mobile Devices, Computers, Networking, Gaming |
| Companies Covered | Micron Technology, Intel Corporation, Samsung Austin Semiconductor, SK Hynix, Broadcom, Qualcomm, Texas Instruments, Analog Devices, GlobalFoundries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Semiconductor Memory Market Trends and Innovations
Silicon photonics integration and memory pooling protocols are compressing the traditional server motherboard layout, forcing a redesign of power delivery and thermal management in hyperscale facilities.
Compute Express Link (CXL) 3.0 is virtualizing memory resource allocation across rack-scale systems. Hyperscale operators in Northern Virginia are deploying CXL-enabled switches to disaggregate DRAM from CPU sockets. This protocol shift is virtualizing the traditional server-as-a-unit procurement model into composable infrastructure pools.
EPA emissions rules under the Clean Air Act are constraining perfluorocarbon releases from wafer etch processes. Domestic fabs in Texas and Idaho are installing abatement systems to meet NESHAP standards. Memory producers are responding by qualifying alternative chemistries with lower global warming potential for oxide removal steps.
Hyperscale buyers are consolidating procurement around qualified supplier lists with proven domestic traceability. Cloud operators in Virginia and California are shifting from spot-market memory purchases to multi-year supply agreements with volume commitments. This concentration is most visible in data center DRAM contracts where three operators now account for the majority of domestic high-bandwidth memory offtake.
United States Semiconductor Memory Market Segmentation
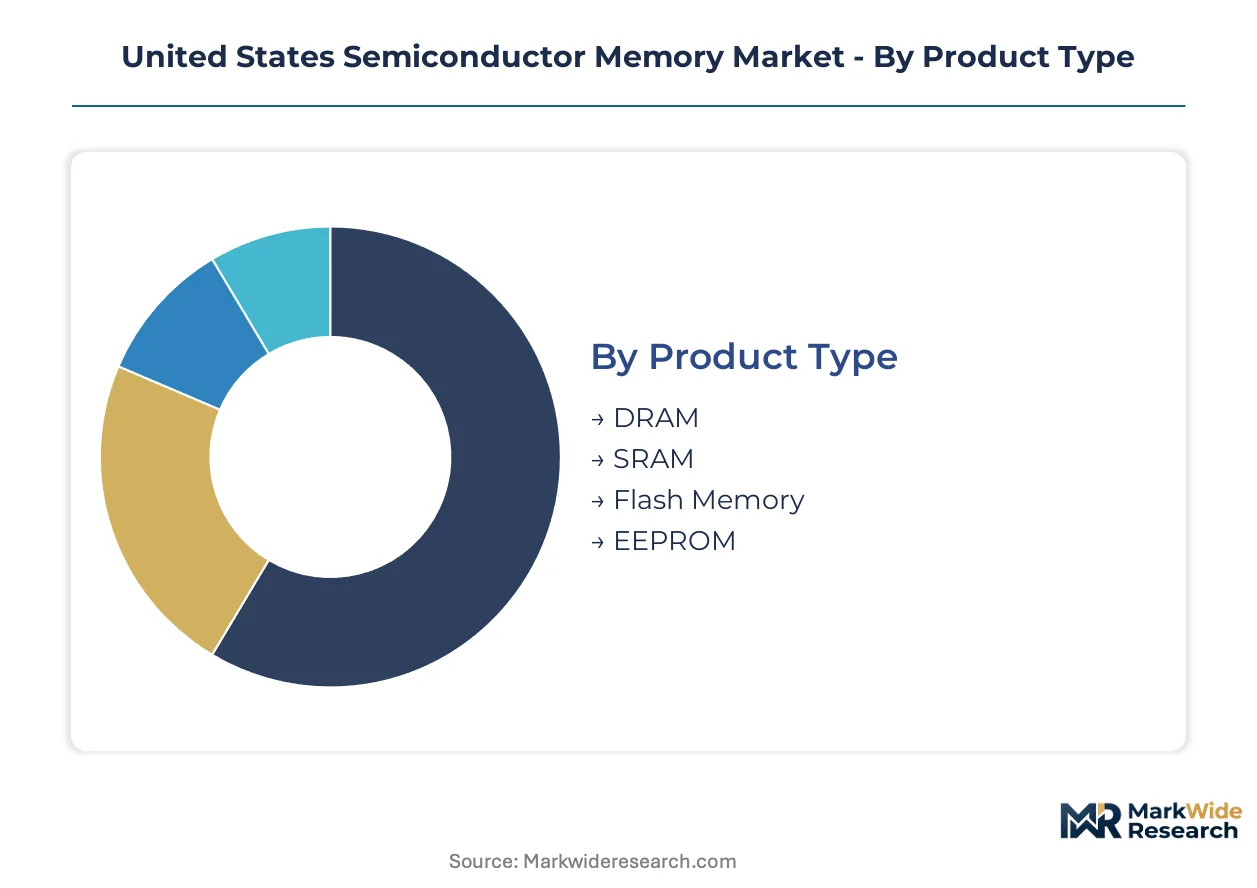
Semiconductor memory segmentation reveals how distinct technical requirements and procurement patterns fragment demand across the United States. Each dimension—product architecture, end-use vertical, connectivity protocol, and device category—carries unique qualification standards and margin structures that shape supplier positioning.
Product Type:
Mature commodity segments coexist with emerging specialized architectures, creating a bifurcated technology landscape where capacitor-based cells dominate volume while stacked alternatives capture premium positioning.
- DRAM:Capacitor-based volatile memory cells requiring constant refresh cycles serve as primary working memory in data center servers and personal computing systems. Northern Virginia hyperscale operators are scaling DDR5 and HBM3E deployments to support generative AI training clusters, constrained by capacitor aspect ratio limits below 10nm nodes.
- Flash Memory:Floating-gate non-volatile cells retain data without power, enabling solid-state storage in mobile and automotive applications. Texas and California procurement for electric vehicle ADAS systems is concentrating around automotive-grade NAND with AEC-Q100 qualification and extended temperature tolerance.
- SRAM:Six-transistor cell structures provide fastest access speeds for cache hierarchies in processor architectures.
- EEPROM:Electrically erasable programmable read-only memory serves configuration storage in industrial controllers and embedded systems.
DRAM handles the majority of throughput; Flash Memory is expanding most quickly on share as automotive and data center storage demands accelerate.
End User:
Cost tier differentiation separates high-volume consumer procurement from qualification-intensive industrial and automotive channels where failure tolerance approaches zero.
- Consumer Electronics:Smartphones, laptops, and wearables drive high-volume, price-sensitive demand for LPDDR and mobile NAND packages. California and Washington-based device OEMs are consolidating supplier lists around domestic traceability requirements under NIST cybersecurity framework mandates.
- Automotive:Michigan and California OEMs require AEC-Q100 qualified embedded memory for ADAS, infotainment, and powertrain control systems. Functional safety ISO 26262 certification is becoming a non-negotiable procurement filter as software-defined vehicle architectures proliferate.
- Telecommunications:Base station and network infrastructure operators in Texas and Illinois specify industrial-temperature memory for edge equipment deployments.
- Industrial:Factory automation and process control systems in Ohio and Pennsylvania demand extended lifecycle availability and radiation tolerance for harsh environments.
Consumer Electronics maintains the steepest volume base; Automotive is climbing the fastest as electrification and autonomy multiply memory content per vehicle.
Technology:
Application-specific processing requirements segment demand across connectivity generations and workload types, with AI-centric architectures commanding premium pricing over legacy cloud infrastructure.
- AI-Driven:Training and inference workloads require high-bandwidth memory stacks and specialized DRAM architectures with massive parallelism. Virginia and Texas data center corridors are deploying HBM3E and CXL-enabled memory pooling to eliminate data movement bottlenecks in GPU-accelerated clusters.
- 5G:Millimeter-wave base stations and edge computing nodes demand low-latency memory subsystems for real-time signal processing.
- Cloud-Based:Hyperscale storage and compute instances in Oregon and Arizona prioritize cost-optimized NAND and commodity DRAM for virtualized workloads.
- 4G:Legacy infrastructure maintenance supports mature DDR3 and eMMC specifications in rural network extensions.
Cloud-Based technology carries the dominant installed base; AI-Driven configurations are gaining share fastest as training cluster deployments accelerate.
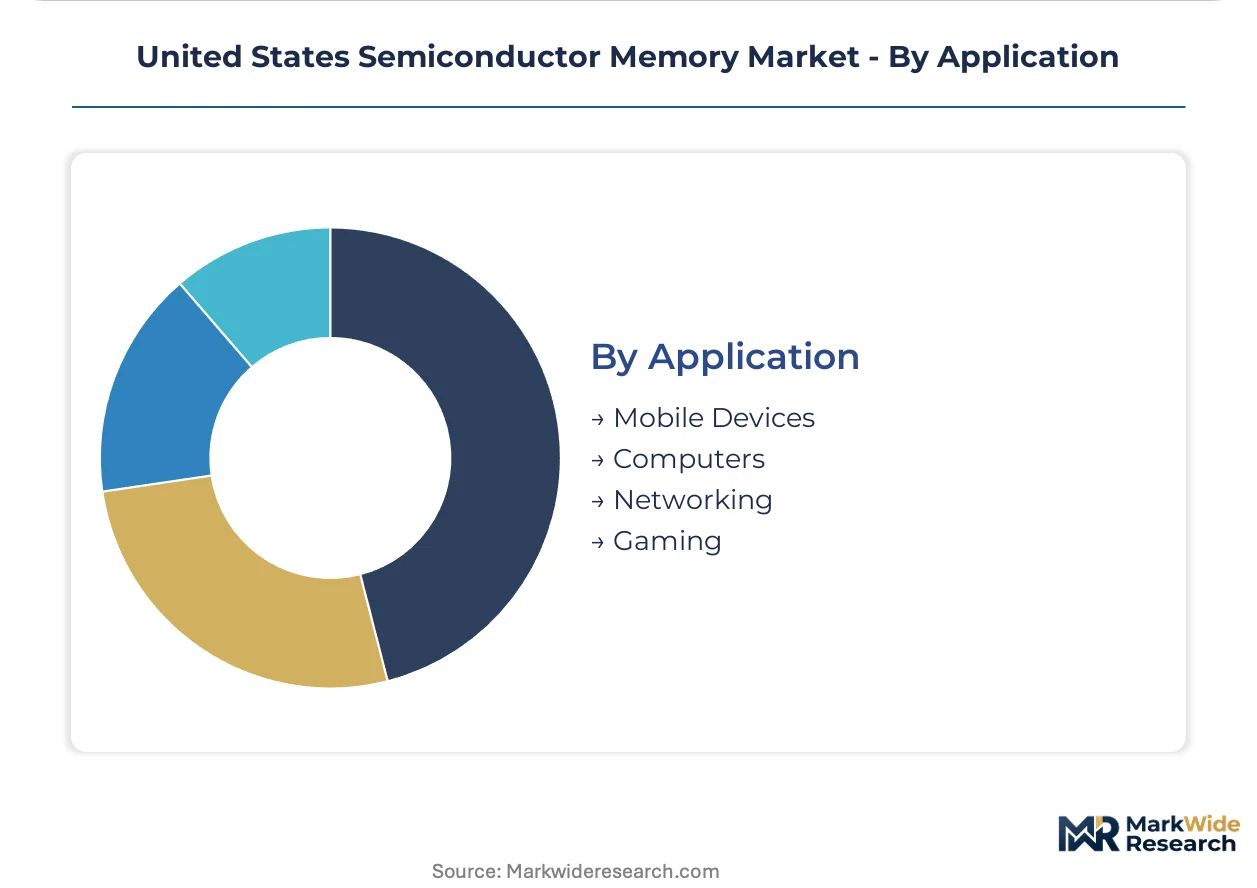
Application:
Form factor constraints and thermal envelopes create distinct memory packaging requirements across device categories, with mobile and gaming applications pushing density limits in confined spaces.
- Mobile Devices:Smartphones and tablets require stacked package-on-package configurations combining LPDRAM and NAND in minimal z-height profiles. California-based OEMs are driving adoption of UFS 4.0 interfaces for flagship devices, constrained by thermal dissipation in sealed enclosures.
- Computers:Client and server systems utilize DIMM and M.2 form factors with standardized JEDEC interfaces for modular upgrade paths.
- Networking:Routers, switches, and optical transport equipment in Dallas-Fort Worth and Ashburn buffer memory for packet processing and lookup tables.
- Gaming:Consoles and graphics cards in Washington and California integrate GDDR6X and high-speed GDDR variants for texture streaming and frame buffering.
Computers anchor the majority of unit demand; Mobile Devices is expanding most quickly as foldable form factors and on-device AI double memory content per handset.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea exports high-bandwidth memory stacks to data center operators in Northern Virginia and Dallas-Fort Worth, while Taiwanese foundries supply advanced logic that pairs with domestic DRAM and NAND fabrication.
California
Automotive electronics procurement from Silicon Valley and Los Angeles OEMs concentrates around AEC-Q100 qualified NAND for ADAS systems. EPA emissions rules under the Clean Air Act constrain perfluorocarbon releases from wafer etch processes in San Jose fabrication facilities. The Bay Area cluster anchors fabless design activity for memory controllers and interface IP.
Texas
Samsung Austin Semiconductor anchors domestic NAND output through its fabrication complex serving hyperscale storage demand. CHIPS Act incentives from the Department of Commerce compress fab construction timelines for capacity expansion in the Austin metro. The Dallas-Fort Worth corridor hosts data center operators scaling flash deployments for generative AI training infrastructure.
Idaho
Micron Technology leverages its Boise-based R&D footprint to sustain advanced DRAM process leadership for data center and consumer applications. NIST standards govern reliability testing protocols that determine qualification for defense procurement channels. The Boise metro concentration supports atomic layer deposition expertise for sub-10nm node development.
Virginia
Data center operators in Loudoun County and Prince William County are expanding HBM3E deployments to support GPU-accelerated AI training clusters. BIS export controls on advanced lithography tools constrain capacity expansion timelines for domestic producers serving these facilities. The Northern Virginia corridor represents the densest concentration of hyperscale memory demand in the United States.
Arizona
Phoenix-area cleanroom construction faces EPA air quality permitting delays for wet chemistry exhaust systems, extending fab readiness timelines. The state presents underpenetrated demand for low-latency memory pools serving edge AI inference workloads. TSMC's advanced packaging operations in Phoenix create co-location opportunities for memory-logic integration.
United States Semiconductor Memory Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around three dominant archetypes: integrated device manufacturers with captive fabrication, fabless designers licensing memory IP, and pure-play foundries offering specialty processes. The competitive terrain rewards scale in commodity DRAM and NAND while preserving niche margins in automotive-qualified and radiation-hardened segments. Two dominant competitive moves define current positioning: strategic partnerships between memory producers and logic foundries for advanced packaging integration, and geographic expansion through CHIPS Act-subsidized domestic fab construction.
Among Idaho-based integrated manufacturers, Micron Technology occupies a position exemplifying captive fabrication depth from R&D through wafer output. Samsung Austin Semiconductor and SK Hynix represent the Korean-headquartered archetype with significant United States production footprint, each anchoring distinct technology specializations within the domestic supply base. These three entities collectively illustrate how foreign-headquartered firms with domestic manufacturing assets compete against indigenous producers for hyperscale and automotive procurement contracts.
| Leading Market Players |
|---|
| Micron Technology |
| Intel Corporation |
| Samsung Austin Semiconductor |
| SK Hynix |
| Broadcom |
| Qualcomm |
| Texas Instruments |
| Analog Devices |
| GlobalFoundries |
| Others |
Pricing and Supply Chain Analysis
Austin's Samsung fabrication complex anchors domestic NAND capacity and shapes pricing power for hyperscale storage contracts. Texas-based output concentration lets integrated manufacturers command premium positioning in enterprise flash while constraining spot-market volatility.
Pricing Analysis
DDR5-to-DDR4 generational spreads exceed prior-cycle gaps as HBM3E stacks capture outsized premiums in AI accelerator procurement. Three-tier pricing structure across premium AEC-Q100 automotive, standard enterprise, and economy consumer segments stratifies by certification grade and volume commitment. Pricing pressure stems from neon gas supply disruption elevating excimer laser processing costs. Hyperscale data center operators exhibit lowest price sensitivity; consumer electronics OEMs drive hardest bargain.
Supply Chain Analysis
TSMC and Samsung Foundry concentrate advanced logic capacity while SK Hynix and Micron anchor memory-specific fabrication. Taiwan, South Korea, and the United States dominate geographic supply concentration for leading-edge nodes. Raw material dependencies center on Ukrainian neon purification, Japanese photoresist, and South Korean precursor chemicals. Single-source lithography equipment vulnerability from ASML concentration presents structural risk. Distribution runs through direct long-term offtake agreements with hyperscale operators bypassing traditional component distributors.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Memory-as-a-service and managed refresh programs expand faster than bare silicon sales as data center operators outsource lifecycle management. Recurring firmware optimization and predictive failure monitoring attach rates outpace hardware shipment growth.
For Market Incumbents: Pre-empt Chinese memory producer entry by accelerating CHIPS Act-funded capacity additions in Idaho and Texas. Fortify against HBM stack commoditization through captive packaging integration with TSMC Arizona. Deepen AEC-Q100 qualification pipelines to lock automotive OEM procurement before ISO 26262 mandates tighten.
For New Entrants and Emerging Players: Pursue CXL-enabled memory pooling software and controller IP as white-space targets outside capital-intensive fabrication. Edge AI inference clusters in Arizona and Oregon present most penetrable geography. Lead with disaggregated memory resource orchestration as go-to-market angle against incumbent hardware-centric positioning.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty packaging houses with HBM stack expertise and automotive qualification credentials. Long-term viability hinges on domestic traceability compliance and defense channel access. Watch BIS equipment export control enforcement intensity as inflection signal for capacity expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| HBM3E Stack Production Scale-Up | Captures premium positioning in NVIDIA and AMD accelerator card supply chains. |
| Automotive Qualification Investment | Locks AEC-Q100 and ISO 26262 certification for Michigan and California OEM procurement. |
| CXL Protocol Platform Integration | Enables memory pooling software revenue recurring beyond hardware refresh cycles. |
| CHIPS Act Fab Construction | Accelerates domestic DRAM and NAND capacity eligible for hyperscale and defense channels. |
| Strategic Partnership with Logic Foundry | Secures advanced packaging co-location for memory-logic integration in Phoenix corridor. |
Research Methodology
Desk research of SEC 10-K filings, hyperscaler capex disclosures, and CHIPS Act subsidy announcements preceded structured interviews with data center procurement officers, fab operations directors, automotive Tier 1 supplier executives, and memory controller IP architects. Primary fieldwork across Virginia, Texas, Idaho, and California validated secondary estimates. Bottom-up wafer capacity modeling and top-down end-use demand aggregation enabled triangulation.
Assumptions held CHIPS Act funding disbursement timelines and BIS export control scope as fixed while varying AI training cluster deployment intensity and automotive electrification penetration. Segmentation dimensions spanned product architecture, end-use vertical, connectivity protocol, and device category. CAGRs derived from node transition pacing and content-per-unit expansion across the analysis window. Forecast inputs incorporated foundry utilization rates and AEC-Q100 qualification pipeline visibility.
Macroeconomic conditions sit as an overlay; deviation in federal semiconductor subsidy continuity and neon gas supply restoration would shift the trajectory. Forecasts reflect documented assumptions on equipment delivery lead times and cleanroom construction permitting velocity. Quarterly review of BIS entity list updates and EPA NESHAP enforcement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
GDDR6 Market
Memory Chips
Americas Dynamic Random Access Memory (DRAM) Market
Memory Chips
Memory Chip Market
Memory Chips
Second-Gen Magneto Resistive RAM (STT MRAM) Market
Memory Chips
LPDDR5 DRAM Market
Memory Chips
Europe Dynamic Random Access Memory (DRAM) Market
Memory Chips
Next Generation Memory Market
Memory Chips
Next Generation Non Volatile Memory Market
Memory Chips
Contactless Memory Market
Memory Chips
Memory IC Market
Memory Chips
DRAM Market
Memory Chips
NAND-Based Multi-Chip Packages Market
Memory Chips
Asia Pacific Semiconductor Memory Market
Memory Chips
Digital RF Memory Market
Memory Chips
In-Memory Computing Market
Memory Chips
China Dynamic Random Access Memory (DRAM) Market