
 North America Non-Phthalate Plasticizers Market | 2026-2036
North America Non-Phthalate Plasticizers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Non-Phthalate Plasticizers Market Analytics
REACH-compliant substance registration is rotating competitive access in the North American supply base, favoring producers with pre-validated dossiers. BASF SE leverages its integrated adipic acid chain to sustain cost positions in terephthalate esters. Eastman Chemical Company anchors the trimellitate segment through dedicated hydrogenation capacity in Kingsport, Tennessee. Arkema Inc. differentiates via bio-based sebacate routes derived from castor oil feedstocks.
Non-phthalate plasticizers are specialty ester compounds—typically terephthalates, trimellitates, or sebacates—with molecular weights above 390 g/mol and glass transition suppression efficiency matching ortho-phthalates at 30–50 phr loadings in flexible PVC. These compounds primarily soften vinyl formulations for applications requiring low migration, reduced volatility, and regulatory compliance in human-contact environments. Terephthalate esters dominate volume in building materials where cost parity with DINP drives specification switches, while citric acid esters capture premium margins in medical devices governed by USP Class VI extractables limits. Sebacate esters lead growth in automotive interiors as OEMs enforce interior air quality standards below 100 µg/m³ total VOC.
FDA 21 CFR 177.1210, EPA TSCA Section 5(b) Significant New Use Rules, and California Proposition 65 warning requirements collectively constrain phthalate retention in food-contact and consumer-touch applications. The EPA's ongoing evaluation of 1,2-cyclohexanedicarboxylic acid diisononyl ester under TSCA risk assessment protocols will determine whether DINCH maintains its unrestricted status. Stakeholders must monitor state-level chemical disclosure laws in Washington and Maine, where reporting thresholds for plasticizer content in children's products already fall below federal benchmarks.
Market Dynamics
California Proposition 65 enforcement has triggered a cascade of reformulation mandates across consumer goods supply chains, compressing specification timelines and forcing compounders to validate non-phthalate alternatives at accelerated cadences.
Growth Catalysts
- FDA biocompatibility tightening:Medical device manufacturers face expanded testing protocols for phthalate-free formulations, pulling demand toward terephthalate and trimellitate esters with established USP Class VI dossiers.
- Automotive interior air quality mandates:OEMs enforce total VOC thresholds below 100 µg/m³, accelerating sebacate ester adoption in dashboard skins and seating foams across Detroit and Southern Ontario assembly corridors.
- Castor oil bio-feedstock commercialization:Sebacate producers leveraging North American castor derivative supply chains capture premium positioning in sustainability-indexed procurement tenders.
Market Restraints
- Adipic acid cost volatility:Terephthalate ester margins compress when cyclohexane oxidation feedstock prices spike, exposing non-integrated compounders to raw material pass-through risk.
- Gulf Coast production concentration:Specialty ester capacity clusters along the Texas-Louisiana petrochemical corridor, creating hurricane exposure and logistics bottleneck vulnerabilities.
- Performance gaps in low-temperature flex:Citrate esters exhibit inferior cold-crack resistance versus ortho-phthalates, limiting specification in outdoor building membrane applications.
Strategic Opportunities
- Underpenetrated Canadian medical tubing:Health Canada device licensing harmonization with FDA standards opens reformulation windows for extrusion houses serving Toronto and Montreal healthcare manufacturing zones.
- US-Mexico cross-border automotive integration:OEM tier suppliers in Querétaro and Puebla seek DINCH and DOTP alternatives qualifying for USMCA content rules and California CARB compliance.
- Washington State children's product disclosure law:Reporting thresholds below federal benchmarks create first-mover advantage for plasticizers with pre-validated toxicology dossiers.
Industry Challenges
- Extractables validation timelines:USP Class VI and ISO 10993 biocompatibility testing cycles extend 18-24 months, freezing specification decisions during regulatory transition periods.
- Legacy equipment retrofit costs:Vinyl compounders must reconfigure extrusion and calendering lines optimized for ortho-phthalate rheology, demanding capital outlays without guaranteed volume commitments.
- Formulation IP fragmentation:Patent thickets around specific terephthalate-trimellitate blends complicate freedom-to-operate assessments for mid-scale compounders entering medical-grade segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Non-Phthalate Plasticizers Market |
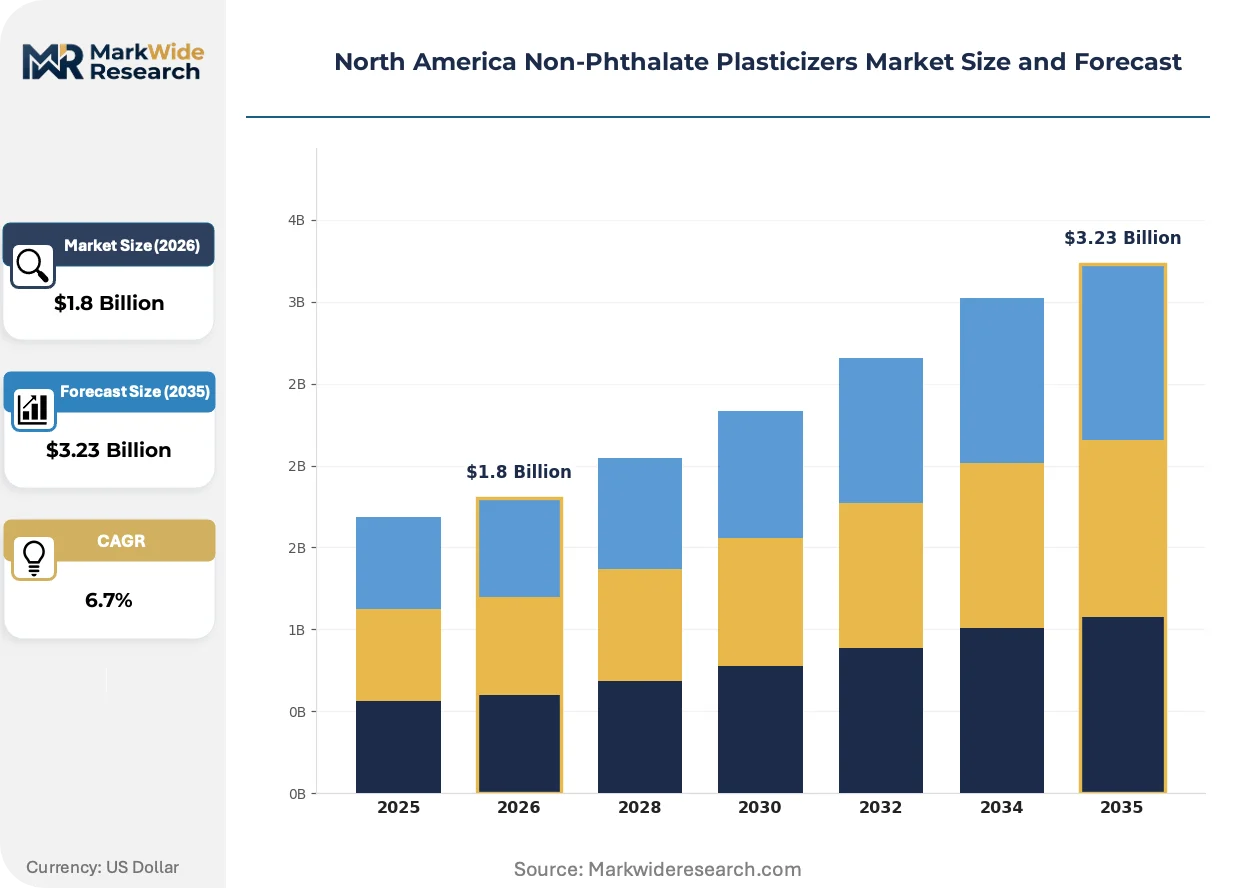
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Terephthalate Esters, Trimellitate Esters, Sebacate Esters, Citric Acid Esters Application: Building Materials, Automotive Interiors, Consumer Goods, Medical Devices End User: Construction, Automotive, Packaging, Healthcare Distribution Channel: Online Retail, Direct Sales, Wholesale, Specialty Suppliers |
| Companies Covered | BASF SE, Eastman Chemical Company, Arkema Inc., Dow Chemical Company, Avient Corporation, LANXESS, Evonik Industries AG, ExxonMobil Chemical Company, Emery Oleochemicals Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Non-Phthalate Plasticizers Market Evolving Landscape
Non-phthalate plasticizer technology is fragmenting along application-specific performance vectors, with manufacturers abandoning universal substitutes in favor of tailored ester architectures optimized for thermal stability, migration resistance, or bio-content credentials.
Bio-based sebacate esters derived from castor oil oligomers are fragmenting the automotive interior segment. Tier 1 seating suppliers in Michigan and Ohio have accelerated qualification timelines from 36 to 18 months. This compression is enabling smaller bio-specialty producers to bypass incumbent petrochemical gatekeepers in OEM approved-source lists.
EPA TSCA Section 5(b) Significant New Use Rules are constraining phthalate retention in food-contact applications. The agency's ongoing DINCH risk assessment has frozen specification decisions in beverage gasket and conveyor belt segments. Compounders are pre-emptively shifting to terephthalate esters pending final determinations.
Medical device procurement has pivoted toward certified-sustainable supply chains. Hospital purchasing consortiums in the Northeast and California now mandate Environmental Product Declarations for disposable tubing and blood bags. This behavioral shift favors plasticizers with third-party verified bio-content and carbon footprint disclosures over conventional petrochemical alternatives.
North America Non-Phthalate Plasticizers Market Segmentation
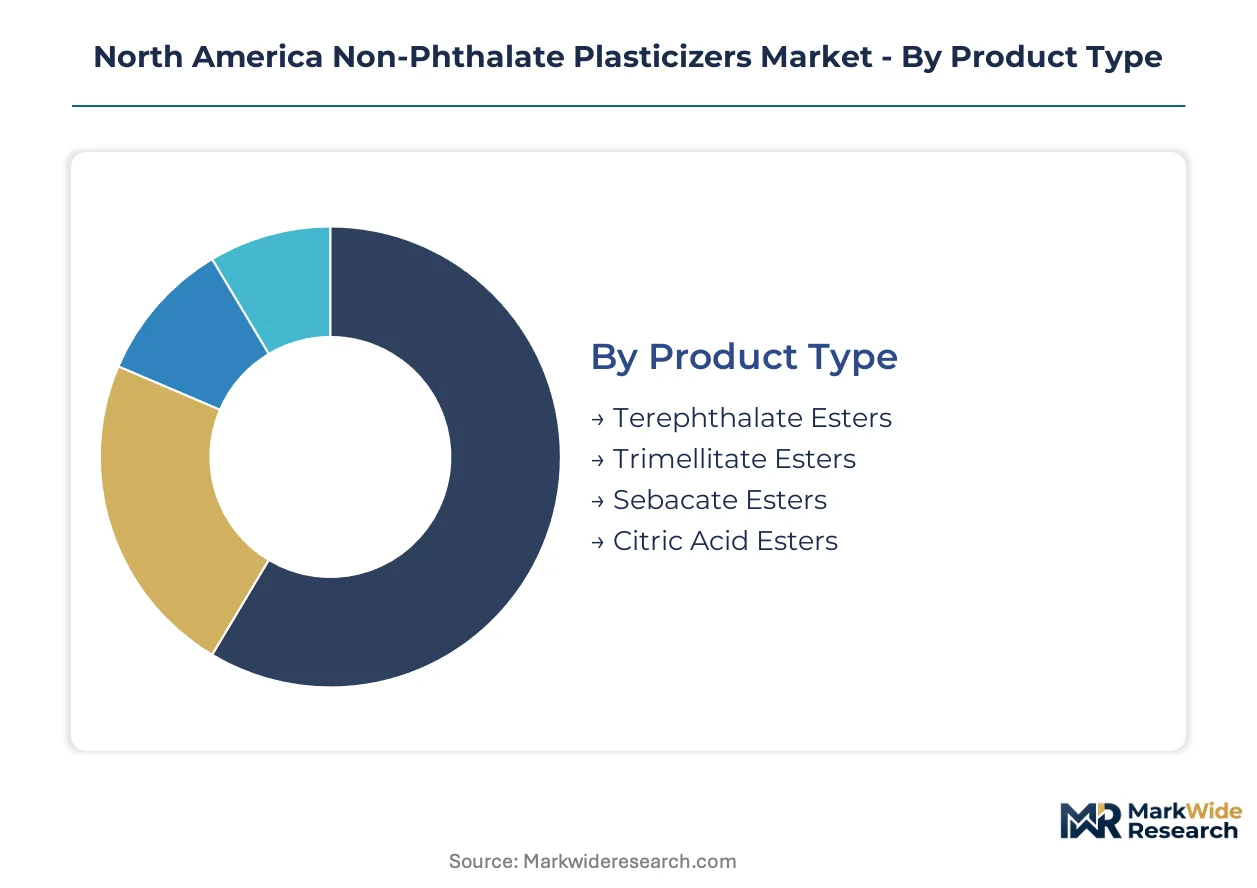
Non-phthalate plasticizer specifications diverge sharply across regulatory exposure tiers, with FDA biocompatibility requirements and California Proposition 65 enforcement creating distinct performance and compliance thresholds that reshape procurement patterns. Segmentation reveals how compounders prioritize migration resistance, thermal stability, and extractables profiles when matching ester chemistry to end-use risk categories.
Product Type:
FDA 21 CFR food-contact approvals and USP Class VI biocompatibility certifications segment this category by regulatory burden rather than molecular architecture alone.
- Terephthalate Esters:DOTP and related terephthalates achieve cost parity with DINP in flexible PVC flooring and wallcoverings through adipic acid chain integration. Demand concentrates in US Gulf Coast vinyl compounders supplying California building materials distributors facing Proposition 65 reformulation mandates.
- Trimellitate Esters:High-molecular-weight trimellitates deliver superior thermal stability and low volatility for automotive wire insulation and high-temperature gaskets. Tennessee-based hydrogenation capacity anchors North American supply for Detroit OEM wiring harness specifications.
- Sebacate Esters:Castor oil-derived sebacates command premium positioning in automotive interior air quality applications.
- Citric Acid Esters:Citrate esters serve medical device segments requiring USP Class VI extractables compliance.
Established volume favors terephthalate esters; emerging adoption favors sebacate esters climbing the fastest on sustainability-indexed procurement tenders.
Application:
Automotive interior air quality mandates and medical device biocompatibility tightening create divergent specification timelines across application clusters.
- Building Materials:Vinyl flooring, wallcoverings, and roofing membranes drive terephthalate ester volume through cost-driven specification switches from ortho-phthalates. California distributors enforce Proposition 65-compliant formulations across residential and commercial construction supply chains.
- Automotive Interiors:Dashboard skins, seating foams, and door panels demand sebacate esters meeting OEM total VOC thresholds below 100 µg/m³. Michigan and Southern Ontario assembly corridors concentrate qualification activity for bio-based alternatives.
- Consumer Goods:Toys, food-contact articles, and personal care packaging face fragmented state-level disclosure requirements.
- Medical Devices:Blood bags, tubing, and IV connectors require 18-24 month USP Class VI validation cycles.
Building materials capture current volume leadership; medical devices represent the steepest expansion trajectory pending FDA harmonization with international biocompatibility standards.
End User:
Customer procurement sophistication separates specification-driven healthcare buyers from cost-optimized construction and automotive purchasing organizations.
- Construction:Vinyl siding, window profiles, and geomembrane producers prioritize terephthalate cost parity.
- Automotive:Tier 1 seating and interior suppliers in Detroit and Querétaro accelerate sebacate qualification.
- Packaging:Beverage gaskets and conveyor belts face frozen specifications pending EPA TSCA DINCH risk assessment completion.
- Healthcare:Hospital purchasing consortiums in California and the Northeast mandate Environmental Product Declarations.
Healthcare procurement is shifting fastest toward certified-sustainable supply chains; construction retains volume dominance through specification inertia in non-coastal markets.
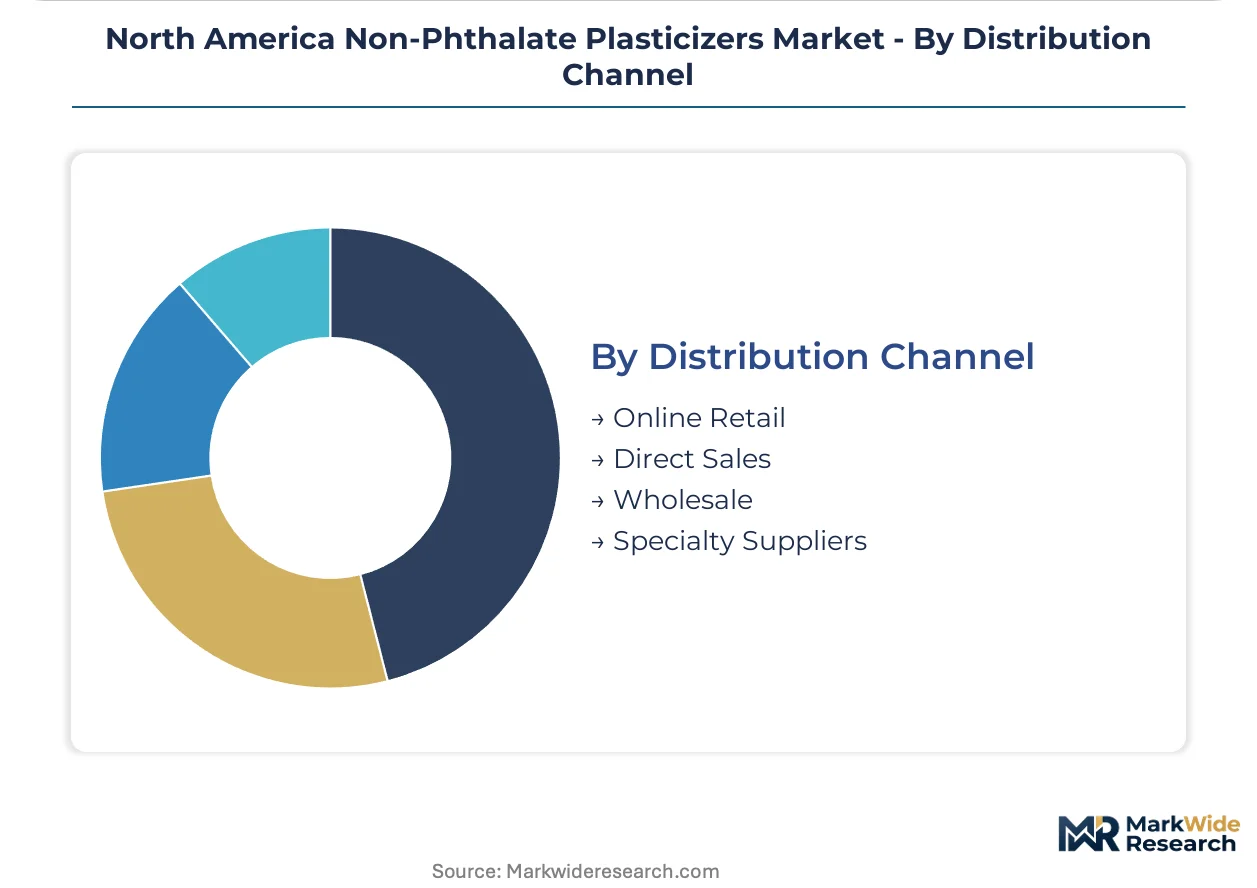
Distribution Channel:
Supply chain configuration separates bulk commodity flows from technical service-intensive specialty ester segments requiring formulation support.
- Direct Sales:Large vinyl compounders along the Texas-Louisiana corridor purchase terephthalate esters through annual volume contracts with integrated adipic acid producers.
- Specialty Suppliers:Medical device extruders and automotive tier suppliers source trimellitate and sebacate esters through distributors providing USP Class VI dossiers and OEM approval documentation.
- Wholesale:Regional chemical distributors serve mid-scale building materials compounders with standardized DOTP grades.
- Online Retail:Small-batch procurement for R&D and pilot-scale medical device development occurs through digital channels.
Direct sales anchor volume throughput; specialty suppliers gain share fastest on technical service differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement sophistication separates specification-driven healthcare buyers in the Northeast from cost-optimized construction purchasers in the Sun Belt. The US Gulf Coast petrochemical corridor anchors specialty ester production capacity near downstream vinyl compounders. Canadian medical device extruders and Mexican automotive tier suppliers create cross-border reformulation demand as regulatory harmonization accelerates.
United States
California Proposition 65 enforcement compresses specification timelines for consumer goods compounders. FDA biocompatibility tightening pulls medical device manufacturers toward terephthalate and trimellitate esters with established USP Class VI dossiers. The Texas-Louisiana Gulf Coast corridor clusters hydrogenation and esterification capacity serving Detroit automotive and Northeast healthcare manufacturing zones.
Canada
Health Canada device licensing harmonization with FDA standards opens reformulation windows for Toronto and Montreal extrusion houses. Hospital purchasing consortiums in Ontario and Quebec mandate Environmental Product Declarations for disposable tubing. Western Canadian construction markets lag coastal regulatory pressure, maintaining ortho-phthalate specification inertia in vinyl flooring and geomembrane applications.
Mexico
USMCA content rules and California CARB compliance converge on OEM tier suppliers in Querétaro and Puebla. Automotive interior air quality mandates below 100 µg/m³ total VOC accelerate sebacate ester qualification for dashboard skins and seating foams. Northern border state maquiladoras face dual pressure from US customer specifications and domestic industrial safety regulations.
North America Non-Phthalate Plasticizers Market Competitive Landscape
Player mix skews toward integrated petrochemical conglomerates with captive adipic acid and hydrogenation assets. Specialty ester production concentrates among three to four producers with pre-validated REACH dossiers and dedicated medical-grade manufacturing lines. Strategic archetypes separate integrated adipic acid-to-ester producers, bio-based sebacate specialists leveraging castor oil feedstocks, and regional compounders with formulation technical service capabilities. Capacity expansion and strategic partnerships dominate competitive moves as producers secure downstream vinyl compounder offtake agreements.
Within the integrated petrochemical tier, BASF SE and Eastman Chemical Company exemplify scale-driven positions anchored by backward integration into key feedstocks. BASF SE represents the adipic acid-integrated archetype sustaining cost positions in terephthalate esters through captive cyclohexane oxidation supply. Eastman Chemical Company occupies a position exemplifying dedicated hydrogenation capacity deployment for high-molecular-weight trimellitate production. Arkema Inc. sits within the bio-based differentiation vector, leveraging castor oil derivative supply chains for sustainability-indexed procurement positioning.
| Leading Market Players |
|---|
| BASF SE |
| Eastman Chemical Company |
| Arkema Inc. |
| Dow Chemical Company |
| Avient Corporation |
| LANXESS |
| Evonik Industries AG |
| ExxonMobil Chemical Company |
| Emery Oleochemicals Group |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day adipic acid contract lead times concentrate pricing power among Gulf Coast integrated producers while forcing non-integrated compounders into volatile spot-market exposure. This inventory compression amplifies cost pass-through vulnerability when cyclohexane oxidation feedstock prices spike.
Pricing Analysis
Cost-plus contracts indexed to ICIS adipic acid assessments dominate terephthalate ester transactions between integrated producers and large vinyl compounders. Three-tier pricing structure across medical-grade, automotive-specification, and standard industrial grades reflects USP Class VI certification premiums and bio-content verification costs. Cost compression in standard-grade DOTP is intensifying because Gulf Coast capacity additions outpace California-driven demand acceleration. Construction sector buyers exhibit highest price sensitivity, while medical device extruders accept sustained premiums for pre-validated toxicology dossiers.
Supply Chain Analysis
Strategic stockpiling of castor oil derivatives characterizes sebacate ester procurement, contrasting with just-in-time adipic acid flows for terephthalate producers. Supply concentrates in the United States, Canada, and Mexico, with hydrogenation and esterification capacity clustering along the Texas-Louisiana corridor. Raw material flows draw from cyclohexane oxidation, castor oil crushing, and trimellitic anhydride hydrogenation. Hurricane exposure along the Gulf Coast petrochemical corridor constitutes the dominant structural risk. Distribution runs through direct annual contracts for large compounders and specialty distributors serving medical and automotive tier suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California Proposition 65 enforcement and EPA TSCA Section 5(b) Significant New Use Rules constitute a regulatory inflection reshaping formulation specifications across consumer goods and medical device supply chains. This compliance compression creates asymmetric growth windows for pre-validated non-phthalate alternatives.
For Market Incumbents: Fortify backward integration into adipic acid supply to defend margin positions against cyclohexane price volatility. Secure captive hydrogenation capacity for high-molecular-weight trimellitate production serving Detroit OEM wiring harness specifications. Invest in USP Class VI dossier maintenance to preempt emerging bio-based sebacate competitors in medical tubing segments. For New Entrants and Emerging Players: Anchor in Canadian medical device extrusion houses awaiting Health Canada-FDA harmonization completion. Target Ontario and Quebec hospital purchasing consortiums mandating Environmental Product Declarations as the most penetrable healthcare entry point. Pursue sustainability-indexed procurement tenders through third-party verified bio-content certification rather than cost-competing with integrated petrochemical majors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized esterification assets and dormant REACH-compliant substance registrations. Long-term viability hinges on regulatory compliance durability rather than commodity cost cycles. Monitor EPA TSCA DINCH risk assessment completion as the critical signal for specification freeze resolution in food-contact applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adipic Acid | Captive cyclohexane oxidation supply insulates terephthalate margins from feedstock volatility spikes. |
| USP Class VI Dossier Investment | Pre-validated toxicology documentation accelerates medical device qualification timelines against competitors. |
| Castor Oil Supply Agreement | Secured bio-feedstock access enables premium positioning in automotive interior air quality mandates. |
| Long-term OEM Offtake Contract | Volume commitments from Detroit seating suppliers de-risk sebacate ester capacity expansion decisions. |
| Joint Venture with Vinyl Compounder | Co-located production reduces logistics costs for Gulf Coast building materials distributors facing Proposition 65 deadlines. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with vinyl compounder procurement directors, medical device extrusion engineers, automotive tier supplier material scientists, and specialty ester distribution channel managers; and secondary validation through FDA 510(k) filings, EPA TSCA chemical substance inventories, ACC resin statistics, SEC 10-K chemical segment disclosures, and California OEHHA Proposition 65 settlement documents. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down capacity assessments from identified production facilities.
Across the projection horizon, the analytical framework modeled demand trajectories by plasticizer chemistry type, application risk tier, end-user procurement sophistication, and distribution channel configuration. CAGRs were derived from regression analysis of historical substitution rates against regulatory enforcement intensity metrics. Forecast inputs incorporated OEM interior air quality threshold adoption curves and hospital purchasing consortium sustainability mandate penetration rates.
Material uncertainties — EPA TSCA risk assessment outcomes, hurricane frequency along the Gulf Coast corridor, and castor oil crop yield volatility — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory harmonization timelines and specification inertia in non-coastal construction markets. Revision becomes warranted when Health Canada device licensing divergence or state-level chemical disclosure threshold changes cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Isoeicosane Market
Specialty Chemicals
Precipitated Barium Sulfate Market
Specialty Chemicals
Pyrrolidone Market
Specialty Chemicals
Technical Aerosol Market
Specialty Chemicals
Global Release Agents Market
Specialty Chemicals
Silicone Derivative Market
Specialty Chemicals
Optical Whitening Agents Market
Specialty Chemicals
Cellulose Esters and Ethers Market
Specialty Chemicals
Avobenzone Market
Specialty Chemicals
Specialty Chemicals Market
Specialty Chemicals
Glucosinolates Market
Specialty Chemicals
Lactic Acid Blend Market
Specialty Chemicals
Lanolin Market
Specialty Chemicals
Europe Malic Acid Market
Specialty Chemicals
Crystal Hard Wax Market
Specialty Chemicals
Alkoxide Market