
 Environmentally Friendly RPET Webbing Market | 2026-2036
Environmentally Friendly RPET Webbing Market Size, Share, and Industry Trends Forecast 2026-2036
Environmentally Friendly RPET Webbing Market Insights
Mechanical recycling of post-consumer PET flakes into high-tenacity filament yarns is tilting the cost-performance curve for synthetic webbing manufacturers. Weaver Textile leverages proprietary extrusion lines to sustain quality parity with virgin polyester in tubular webbing grades. National Webbing Products anchors North American supply through backward integration into flake sourcing and chip production. Pfeiffer dominates European certification pathways, navigating ECHA registration requirements for imported recycled content.
Environmentally friendly RPET webbing comprises woven or knitted strap structures fabricated from 100% recycled polyethylene terephthalate filament, typically achieving tenacity ratings of 7.5–9.0 grams per denier through ring-spinning or air-jet texturing processes. The material serves load-bearing, binding, and reinforcement functions across industrial, consumer, and safety-critical applications where lifecycle carbon reduction carries procurement weight. Flat webbing occupies the largest volume share due to its ubiquity in furniture frame suspension and cargo strapping, though tubular webbing generates superior margins through specialty outdoor gear contracts. Automotive grade material commands the tightest certification thresholds, with textile grade experiencing the fastest qualification pipeline as fashion brands adopt RPET for bag straps and accessories.
The EPA oversees recycled content claims under FTC Green Guides in the United States, while REACH and the EU Green Deal establish substance restrictions and circularity mandates across European supply chains. ECHA's SCIP database requirements for articles containing SVHCs above threshold concentrations are forcing webbing importers to document recycled feedstock provenance. Stakeholders must monitor evolving extended producer responsibility schemes and chemical transparency protocols that will determine which RPET webbing suppliers retain market access.
Market Dynamics
Mechanical recycling of post-consumer PET flakes is compressing cost differentials against virgin polyester filament, forcing synthetic webbing manufacturers to reconfigure extrusion lines and flake-sourcing strategies to maintain margin parity.
Growth Catalysts
- EU Green Deal circularity mandates:Binding recycled content thresholds for automotive textiles and consumer goods are pulling RPET webbing into seatbelt and harness specifications across German and French supply chains.
- Outdoor gear procurement pivot:Backpack and climbing equipment manufacturers are specifying 100% recycled polyester webbing in sustainability scorecards, creating volume anchors for certified filament suppliers.
- REACH SVHC transparency requirements:ECHA's SCIP database obligations are disqualifying uncertified virgin polyester competitors who cannot document feedstock provenance.
Market Restraints
- Post-consumer flake supply concentration:Collection and sorting infrastructure for food-grade PET bottles clusters in Germany, the Netherlands, and select US states, creating geographic feedstock vulnerability.
- High-tenacity yarn technical ceiling:Mechanical recycling degrades PET molecular weight, limiting recycled filament tenacity to approximately 8.5 grams per denier versus 9.5+ for virgin high-performance grades.
- Automotive certification friction:ECE R16 and FMVSS 209 testing timelines for seatbelt webbing extend 18-24 months, locking qualified suppliers into incumbent positions.
Strategic Opportunities
- India textile manufacturing expansion:Bureau of Indian Standards (BIS) adoption of recycled content labeling for technical textiles opens qualification pathways for RPET webbing in domestic automotive and luggage sectors.
- Chemical recycling convergence:Pyrolysis and glycolysis technologies approaching commercial scale promise food-grade PET flake quality from mixed waste streams, bypassing mechanical recycling purity constraints.
- Direct-to-brand digital channels:Fashion and accessories brands are bypassing traditional textile distributors to source certified RPET webbing through traceability-platform marketplaces.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise for rPET viscosity stabilization during melt-spinning concentrates among aging specialists in European and Japanese filament houses.
- Multi-standard certification complexity:Simultaneous pursuit of OEKO-TEX, GRS, and automotive OEM approvals demands dedicated compliance teams and extended qualification budgets.
- Extrusion line reconfiguration capex:Retrofitting virgin polyester spinning equipment for recycled flake feedstock requires vacuum solid-state polymerization units and enhanced filtration systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Environmentally Friendly RPET Webbing Market |
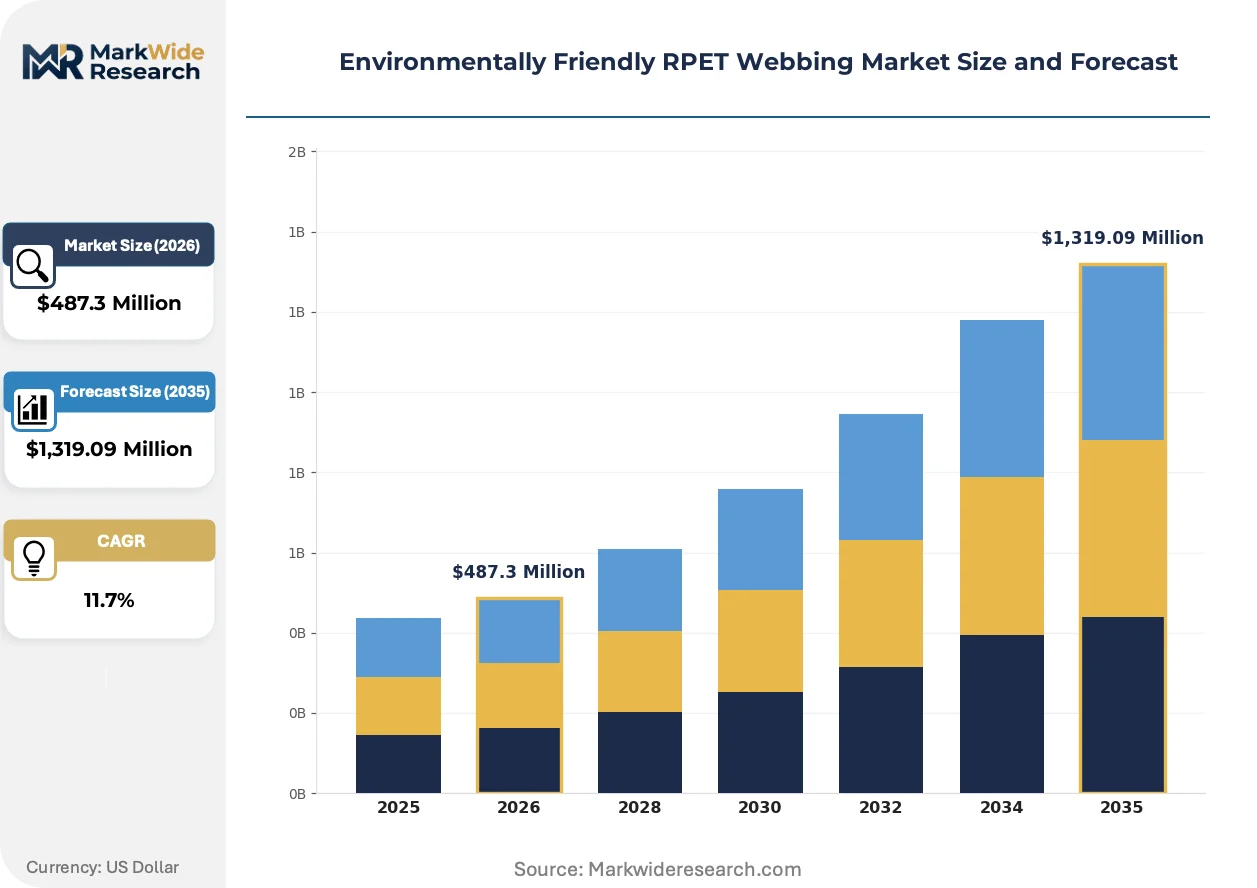
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Webbing, Tubular Webbing, Solid Webbing, Woven Webbing Material Grade: Food Grade, Industrial Grade, Automotive Grade, Textile Grade End Use Application: Outdoor Gear, Furniture Manufacturing, Packaging Solutions, Safety Equipment Distribution Channel: Online Retailers, Specialty Stores, Direct Sales, Wholesale Distributors |
| Companies Covered | Weaver Textile, Original Webbing, Pfeiffer, Huida Webbing, Eternes Industry & Development, National Webbing Products, Strapworks, Jude Webbing, BOLIN WEBBING, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Environmentally Friendly RPET Webbing Market Trends and Innovations
Digital traceability infrastructure is overlaying physical supply chains, enabling real-time verification of recycled content claims and compressing the window between flake collection and finished webbing certification.
Blockchain-based material passports are digitizing custody documentation for post-consumer PET flakes from collection through extrusion. Automotive tier-one suppliers in Germany and France are mandating platform integration for seatbelt webbing contracts. This is digitizing audit workflows and compressing supplier qualification cycles from months to weeks.
REACH authorization requirements for diisocyanates and selected plasticizers are tightening substance restrictions in textile finishing treatments. Webbing manufacturers serving EU automotive and furniture markets are reformulating coatings and dyes to maintain market access. German automotive suppliers are accelerating substitution timelines, with several seatbelt weavers completing chemical transition by late 2025.
Brand-led sustainability scorecards are reshaping procurement evaluation criteria for bag straps and accessories. Fashion houses in Italy and the United States are weighting recycled content percentage and carbon footprint data equally with price and lead time. This behavioral shift favors RPET webbing suppliers with certified lifecycle assessments and penalizes virgin polyester competitors lacking transparent environmental declarations.
Environmentally Friendly RPET Webbing Market Segmentation
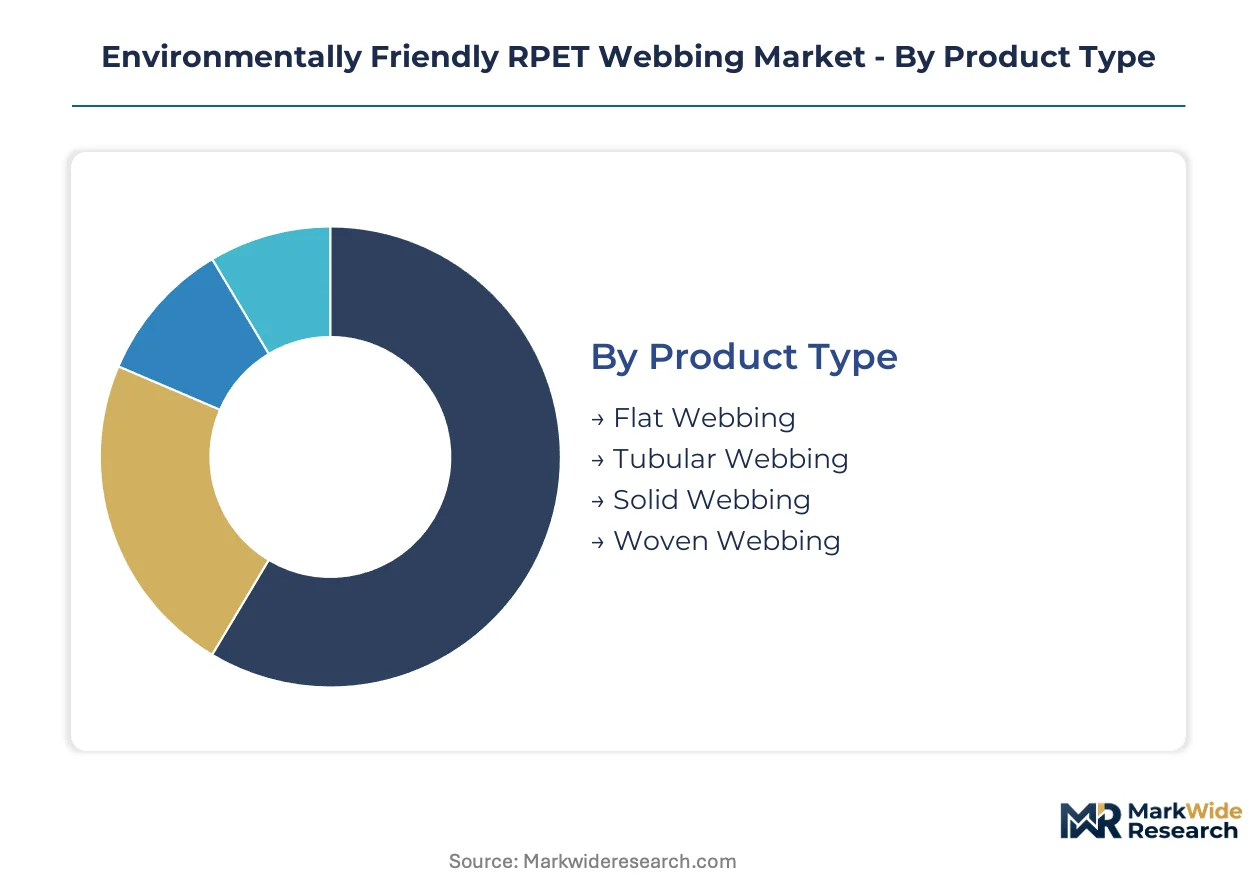
Segmentation in the RPET webbing market reveals how technical specifications, certification tiers, and procurement channels fragment demand across divergent end-use requirements. Manufacturers configure extrusion lines and sourcing strategies differently for automotive seatbelt contracts versus fashion accessory supply, creating distinct competitive arenas within the same material category.
Product Type:
The use-case spectrum spans load-bearing industrial strapping to specialized tubular structures for climbing equipment, with each geometry demanding distinct weaving looms and tenacity specifications.
- Flat Webbing:Two-dimensional woven straps fabricated on needle looms achieve widths from 25mm to 100mm for cargo securing and furniture suspension. German automotive suppliers source flat webbing variants for seatbelt applications where ECE R16 certification mandates precise elongation characteristics.
- Tubular Webbing:Hollow cylindrical structures knit or woven in the round deliver superior edge protection and load distribution for climbing harnesses and backpack shoulder straps. Specialty outdoor gear manufacturers in France and Italy specify tubular grades for premium product lines where sustainability credentials command price premiums.
- Solid Webbing:Dense, non-hollow extrusions suited for heavy-duty industrial binding where abrasion resistance outweighs weight considerations.
- Woven Webbing:Traditional interlaced constructions serving general-purpose strapping across packaging and logistics applications.
The dominant share belongs to Flat Webbing, while Tubular Webbing is closing the gap fastest.
Material Grade:
Certification intensity separates these tiers, with automotive and food-contact applications imposing molecular purity standards that mechanical recycling struggles to satisfy.
- Automotive Grade:Highest-tenacity filaments meeting ECE R16 and FMVSS 209 specifications for occupant restraint systems. German seatbelt weavers dominate this segment through 18-24 month qualification pipelines that lock in supplier relationships.
- Textile Grade:Medium-tenacity yarns for bag straps, accessories, and apparel applications where GRS certification satisfies brand sustainability requirements. Italian fashion houses are accelerating procurement of textile-grade RPET for traceability-platform-verified collections.
- Food Grade:Flake purity standards matching virgin PET for incidental food-contact applications in packaging.
- Industrial Grade:Standard recycled content for non-critical binding and reinforcement where cost minimization drives selection.
Automotive Grade captures the premium pricing tier, yet Textile Grade is expanding most quickly as brand sustainability scorecards proliferate.
End Use Application:
Customer procurement behavior varies sharply across these verticals, from automotive tier-one supplier integration to outdoor brand sustainability marketing.
- Outdoor Gear:Backpacks, climbing harnesses, and tent straps where 100% recycled content claims support retail differentiation. French and Italian equipment manufacturers specify certified RPET webbing in product sustainability labeling.
- Safety Equipment:Fall protection and load-bearing harnesses where EN 361 and EN 358 standards govern material performance. German industrial distributors source high-tenacity grades for professional safety equipment.
- Furniture Manufacturing:Upholstery suspension and frame binding where cost pressures favor standard recycled grades.
- Packaging Solutions:Strapping and reinforcement for logistics applications with minimal certification requirements.
Outdoor Gear holds the volume lead, while Safety Equipment is gaining share fastest through regulatory tightening on workplace protection.
Distribution Channel:
Channel selection reflects order scale and traceability requirements, with large automotive contracts bypassing intermediaries entirely.
- Direct Sales:Long-term supply agreements between filament producers and automotive tier-ones or major outdoor brands. German seatbelt weavers and French climbing equipment manufacturers negotiate multi-year contracts with vacuum-solid-state-polymerization-equipped extruders.
- Wholesale Distributors:Inventory-holding intermediaries serving mid-size furniture and packaging manufacturers across fragmented European markets.
- Specialty Stores:Technical textile retailers catering to small-batch outdoor gear producers and repair shops.
- Online Retailers:Digital platforms enabling direct-to-brand sourcing for fashion accessories and custom bag manufacturers.
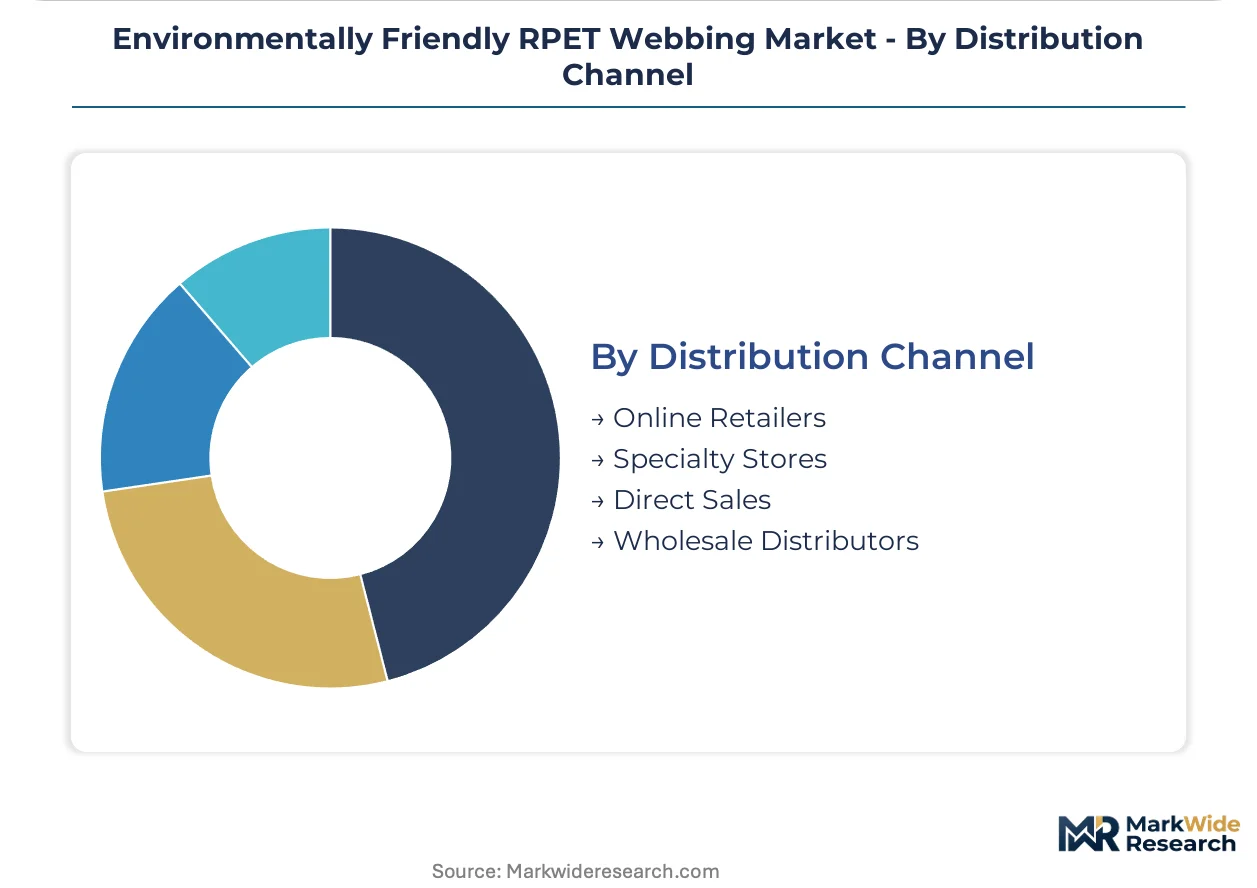
Direct Sales commands the revenue concentration, though Online Retailers are climbing the fastest as traceability-platform marketplaces mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive suppliers and French outdoor equipment manufacturers concentrate procurement of certified RPET webbing, while US furniture producers and Indian textile exporters are expanding qualification pipelines for recycled filament supply.
Germany
Seatbelt weavers in Stuttgart and Wolfsburg source automotive-grade RPET webbing for ECE R16-compliant occupant restraint systems. The EU Green Deal mandates binding recycled content thresholds for automotive textiles by 2030. Bavarian filament producers operate vacuum solid-state polymerization lines to sustain tenacity parity with virgin polyester in tubular webbing grades.
United States
EPA oversight of recycled content claims under FTC Green Guides shapes procurement behavior among furniture manufacturers in North Carolina and outdoor gear brands in Colorado. California's extended producer responsibility schemes for textiles are accelerating flake-to-fiber traceability requirements. National Webbing Products anchors North American supply through backward integration into PET chip production.
France
Climbing equipment manufacturers in the Alps specify 100% recycled polyester webbing for harness and backpack applications where sustainability credentials command retail premiums. REACH authorization timelines for diisocyanates in textile finishing are compressing supplier transition windows. Lyon-based textile distributors are consolidating inventory positions ahead of ECHA SCIP database enforcement.
India
Bureau of Indian Standards adoption of recycled content labeling for technical textiles is opening qualification pathways for domestic automotive and luggage sectors. Tamil Nadu filament producers are retrofitting extrusion lines for post-consumer flake feedstock to serve export contracts. Mumbai-based bag manufacturers are sourcing GRS-certified webbing through direct-to-brand digital channels.
Italy
Fashion houses in Milan and Florence weight recycled content percentage equally with price in sustainability scorecards for bag straps and accessories. ECHA substance restrictions on selected plasticizers are forcing coating reformulations among Como-based finishing specialists. Prato's textile cluster is digitizing custody documentation through blockchain-based material passport platforms.
Environmentally Friendly RPET Webbing Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Weaver Textile and National Webbing Products anchor distinct regional positions through captive flake sourcing and extrusion capacity. Pfeiffer occupies the European certification pathway segment. The competitive arena splits between automotive-grade qualification holders and textile-grade volume suppliers. Dominant moves include backward integration into chip production and multi-standard certification stacking.
Among North American fabricators, National Webbing Products exemplifies the integrated archetype through upstream control over PET flake sourcing. Weaver Textile represents the product-specialist tier with proprietary extrusion capabilities for high-tenacity applications. Pfeiffer occupies a position within the European compliance-focused segment, navigating ECHA registration requirements for imported recycled content. These three anchors illustrate how geographic concentration and certification intensity stratify competitive positioning across the RPET webbing supply base.
| Leading Market Players |
|---|
| Weaver Textile |
| Original Webbing |
| Pfeiffer |
| Huida Webbing |
| Eternes Industry & Development |
| National Webbing Products |
| Strapworks |
| Jude Webbing |
| BOLIN WEBBING |
| Others |
Pricing and Supply Chain Analysis
German flake collection infrastructure concentrates upstream feedstock control, anchoring margin pools with extrusion houses operating vacuum solid-state polymerization lines for automotive-grade filament. Cost-plus contracts with PET bottle indexation dominate procurement between filament producers and seatbelt weavers, compressing margin volatility for qualified suppliers while locking out uncertified competitors.
Pricing Analysis
Cost-plus contracts with monthly PET flake indexation govern long-term supply agreements between extruders and automotive tier-ones in Germany and France. Three-tier pricing structure across automotive, textile, and industrial grades reflects certification intensity and tenacity specifications. Pricing pressure stems from mechanical recycling yield losses degrading PET molecular weight below virgin parity. Furniture manufacturers in North Carolina exhibit highest price sensitivity, while German seatbelt weavers accept premiums for ECE R16 traceability.
Supply Chain Analysis
Tariff exposure between post-consumer flake collectors in Germany and extrusion houses in Tamil Nadu dominates supply chain risk planning for European automotive contracts. Feedstock draws from Germany, the Netherlands, and select US states where bottle deposit schemes ensure food-grade purity. Dependence on post-consumer PET flakes, virgin PET chip spot markets, and specialized vacuum polymerization equipment creates single-source vulnerability around German flake preprocessing. Distribution runs through direct sales for automotive contracts and wholesale distributors for furniture and packaging segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
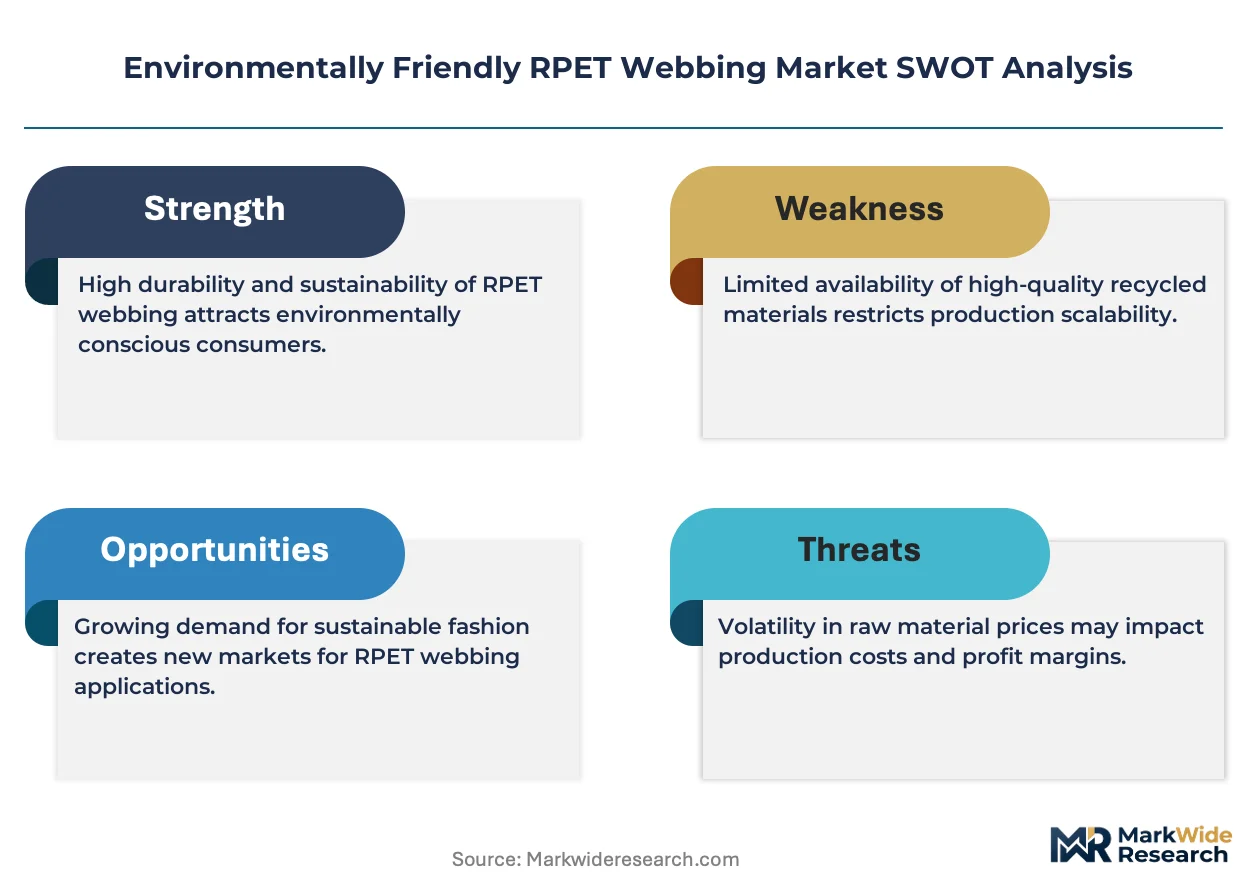
The RPET webbing market sits in early-cycle expansion as EU Green Deal recycled content mandates pull certified filament into seatbelt specifications ahead of 2030 thresholds. Brand sustainability scorecards in fashion accessories accelerate textile-grade qualification pipelines.
For Market Incumbents: Build certification moats through simultaneous GRS, OEKO-TEX, and automotive OEM approval stacking. National Webbing Products demonstrates upstream control through captive PET chip production. Pfeiffer navigates ECHA registration requirements to lock European market access. Threats emerge from chemical recycling entrants promising virgin-equivalent molecular weight. Priority lever rests on vacuum solid-state polymerization capacity expansion in Bavaria and Stuttgart clusters. For New Entrants and Emerging Players: Establish a beachhead in India's domestic automotive and luggage sectors where BIS recycled content labeling opens qualification pathways. Tamil Nadu extrusion retrofitting serves export contracts with lower certification friction than European automotive tier-ones. White-space targets include direct-to-brand digital channels for fashion accessories and chemical recycling partnerships bypassing mechanical purity constraints. Go-to-market angle centers on blockchain-verified material passports compressing audit cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European filament houses holding automotive qualification pipelines. Five-to-ten-year viability hinges on chemical recycling scale-up resolving mechanical degradation ceilings. Acquisition targets include mid-cap extruders with vacuum polymerization units and established ECHA registration pathways. Signal to watch: automotive OEM substitution timelines for diisocyanate-free finishing treatments accelerating supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flake Sourcing | Captive PET chip production insulates National Webbing Products from feedstock volatility. |
| Multi-Standard Certification Stacking | Simultaneous GRS and OEKO-TEX approval opens fashion and automotive procurement channels. |
| Vacuum Solid-State Polymerization Expansion | Bavarian extrusion retrofitting sustains tenacity parity with virgin polyester for seatbelt grades. |
| Blockchain Material Passport Deployment | Prato textile cluster digitization compresses supplier qualification from months to weeks. |
| Chemical Recycling Partnership Formation | Pyrolysis technology access bypasses mechanical recycling purity constraints for food-grade applications. |
Research Methodology
A spread of perspectives from extrusion line engineers, automotive tier-one procurement leads, textile sustainability directors, and ECHA compliance officers converged on the working assumptions driving this analysis. Primary interviews with filament producers in Germany, France, and Tamil Nadu combined with secondary validation from EU Green Deal implementation documents, ECHA SCIP database guidance, BIS technical textile notifications, and SEC filings from listed textile manufacturers. Bottom-up modeling of extrusion capacity and flake supply triangulated against top-down demand projections from automotive production and outdoor gear shipment data.
Demand-supply balance framing anchored the forecast architecture across the analysis window, with segmentation modeled by product geometry, material grade tier, end-use vertical, and distribution channel. Automotive-grade, textile-grade, and industrial-grade distinctions captured certification intensity differentials. Outdoor gear, safety equipment, furniture, and packaging applications reflected divergent procurement behaviors. CAGRs derived from elasticity-adjusted penetration curves against regulatory mandate timelines. Industry-specific inputs included ECE R16 qualification pipeline durations and REACH authorization substitution schedules.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, PET resin pricing, or EU Green Deal implementation pacing would shift the trajectory. Forecasts reflect assumptions around mechanical recycling yield stability and chemical recycling commercialization timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
South Korea Recycled Plastics Market
Recycled Plastics
Plastic Pellets Market
Recycled Plastics
Iron Recycling Market
Recycled Plastics
North America Plastic Waste Management Market
Recycled Plastics
Vietnam Plastics Market
Recycled Plastics
Bioplastic Recycling Market
Recycled Plastics
USA Plastic-To-Fuel Market
Recycled Plastics
Plastic Recycling Market
Recycled Plastics
North America Recycled Plastics Market
Recycled Plastics
Waste Plastic Bricks Market
Recycled Plastics
Recycled Leather Market
Recycled Plastics
Circular Plastic Feedstock Traceability Market
Recycled Plastics
Recycled Polypropylene Market
Recycled Plastics
Myanmar Plastics Market
Recycled Plastics
Germany Plastics Market
Recycled Plastics
Plastic Compounds Market