
 Bioplastic Recycling Market | 2026-2036
Bioplastic Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Bioplastic Recycling Market Outlook
The bioplastic recycling sector is pivoting between premium chemically recycled grades and commodity mechanically reprocessed streams. NatureWorks LLC leverages its integrated PLA production network to sustain feedstock quality across multiple collection zones. Novamont S.p.A. anchors European capacity for starch-based polymer recovery, while BASF SE competes through specialized chemical recycling infrastructure for complex multilayer packaging.
Bioplastic recycling encompasses the recovery and reprocessing of bio-based polymers such as PLA, PHA, and starch blends through mechanical, chemical, or organic pathways to restore material properties for subsequent manufacturing cycles. Mechanical recycling of PLA dominates current volume flows due to lower energy intensity, though chemical recycling of PHA captures expanding margin pools as pharmaceutical and medical applications demand virgin-equivalent purity. Organic recycling through industrial composting channels occupies a mature position for food-contact starch blends where contamination levels preclude mechanical routes.
EMA guidelines on recycled material contact with foodstuffs, EU REACH registration requirements for reprocessed biopolymers, and the EU Green Deal circular plastics targets collectively reshape product standards and market access conditions across member states. Germany's national packaging ordinance and France's AGEC law extend these frameworks with mandatory recycled content floors and extended producer responsibility fees. Stakeholders must monitor evolving certification thresholds for chemically versus mechanically recycled grades as regulatory bodies tighten traceability requirements without harmonized testing protocols.
Market Dynamics
The bioplastic recycling sector is bifurcating sharply between high-purity chemical recycling output for food-contact applications and mechanically reprocessed commodity grades for non-sensitive packaging, with EFSA traceability mandates forcing processors to segregate feedstock streams from collection through pelletization.
Growth Catalysts
- EU Green Deal circular plastics targets:Mandatory recycled content floors in packaging are pulling investment into PLA depolymerization infrastructure across Belgium and the Netherlands.
- Food packaging chains:Major retailers in Germany and France now require post-consumer recycled bioplastic content, creating guaranteed offtake for certified recyclers.
- Chemical recycling of PHA:Pharmaceutical and medical applications demand virgin-equivalent purity, commanding substantial margin premiums over mechanical routes.
Market Restraints
- Feedstock contamination:Food residue and multilayer packaging complexity degrade mechanical recycling yields, forcing reliance on costly chemical pathways.
- Collection infrastructure gaps:Industrial composting facilities in Southern Europe lack separate sorting lines for bioplastics, diverting material to incineration.
- Petrochemical resin pricing:Virgin PP and PE price volatility compresses recycled bioplastic price premiums during oil market downturns.
Strategic Opportunities
- Extended Producer Responsibility expansion:France's AGEC law and Germany's packaging ordinance are extending collection targets to agricultural mulch films and food service ware.
- Starch-based polymer recovery:Industrial composting channels for contaminated food-contact blends remain underdeveloped outside Italy and Spain.
- Blockchain traceability integration:Digital product passports are emerging as a certification differentiator for chemically recycled grades entering premium packaging.
Industry Challenges
- Skilled technician scarcity:Chemical recycling operations require polymer chemists and process engineers with specialized biopolymer expertise, concentrated in Dutch and Belgian technical universities.
- Certification timeline compression:EFSA and national regulators lack harmonized testing protocols for mechanically versus chemically recycled grades, delaying market entry.
- Legacy equipment retrofitting:Mechanical recyclers must reconfigure extrusion lines to handle PLA's lower thermal stability compared to conventional thermoplastics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioplastic Recycling Market |
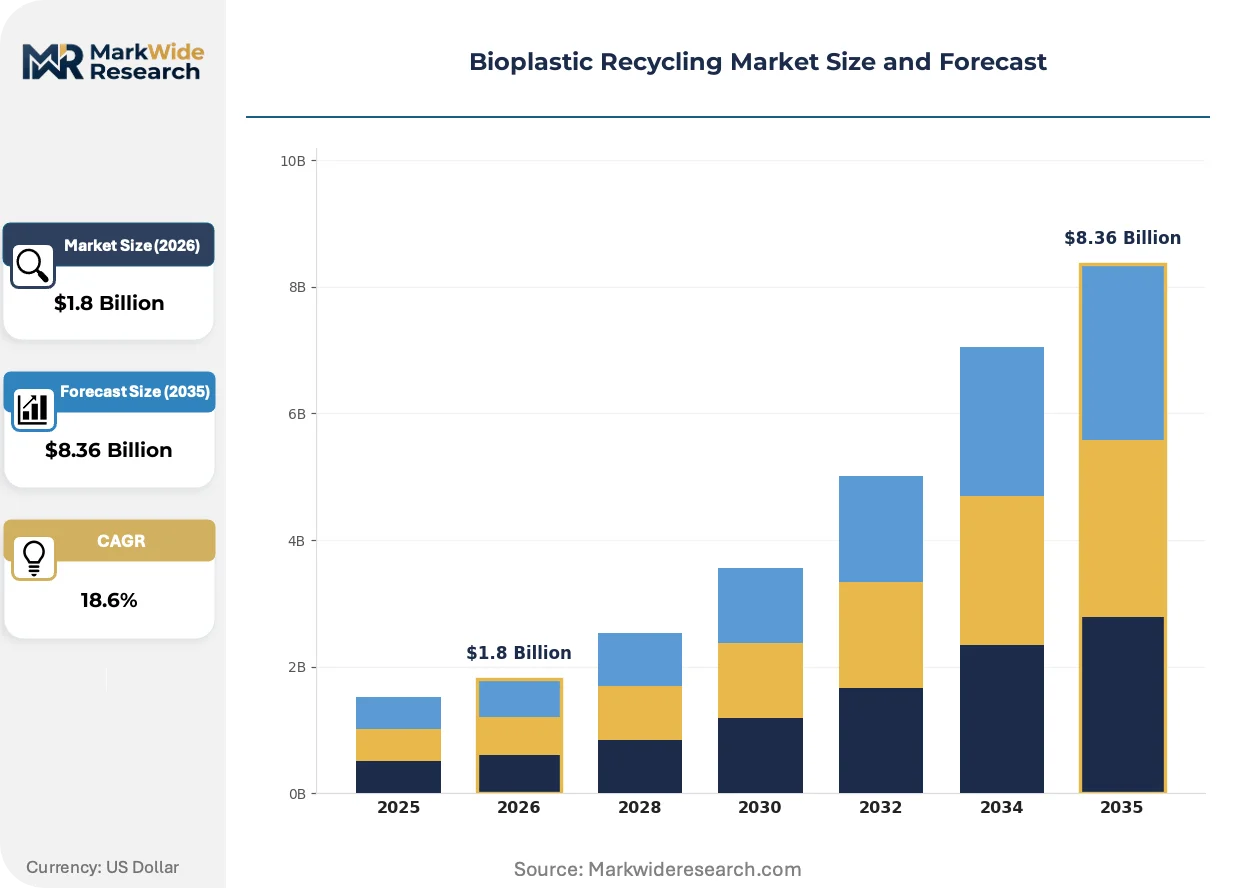
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PLA, PHA, PBS, Starch Blends Recycling Method: Chemical Recycling, Mechanical Recycling, Organic Recycling, Biodegradable Processing End User: Packaging, Textiles, Consumer Goods, Automotive Distribution Channel: Online Retail, Direct Sales, Distributors, Imports |
| Companies Covered | NatureWorks LLC, Novamont S.p.A., BASF SE, Biome Bioplastics, TotalEnergies Corbion, BioLogiQ, Inc., Braskem S.A., FKuR Kunststoff GmbH, Danimer Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioplastic Recycling Market Strategic Shifts
Enzymatic depolymerization is emerging as a selective alternative to thermal chemical recycling, enabling recovery of food-contaminated PLA streams that mechanical processes cannot handle. This biological pathway is attracting capital from pharmaceutical and specialty chemical investors seeking circular feedstock security.
Depolymerization catalysts targeting stereochemical purity are electrifying PLA chemical recycling economics by reducing re-polymerization costs and enabling closed-loop food-contact applications. Dutch biotechnology firms are deploying these systems at pilot scale for major packaging converters. The technology is compressing the cost gap between virgin and recycled PLA grades in Western European markets.
REACH registration requirements for reprocessed biopolymers are tightening substance characterization obligations, forcing recyclers to document additive migration profiles and degradation byproducts. ECHA guidance on polymer registration is pushing processors to invest in analytical laboratories or outsource testing to certified facilities. Small and mid-scale mechanical recyclers in Eastern Europe face disproportionate compliance burdens relative to integrated chemical operators.
Buyer concentration among multinational food and beverage brands is rotating procurement criteria toward mass-balance certification and blockchain-verified chain of custody. Large retailers are unbundling recycled content verification from traditional resin supply agreements, creating standalone certification services. This shift is most visible in German and French packaging markets where AGEC and national ordinance enforcement has accelerated.
Bioplastic Recycling Market Segmentation
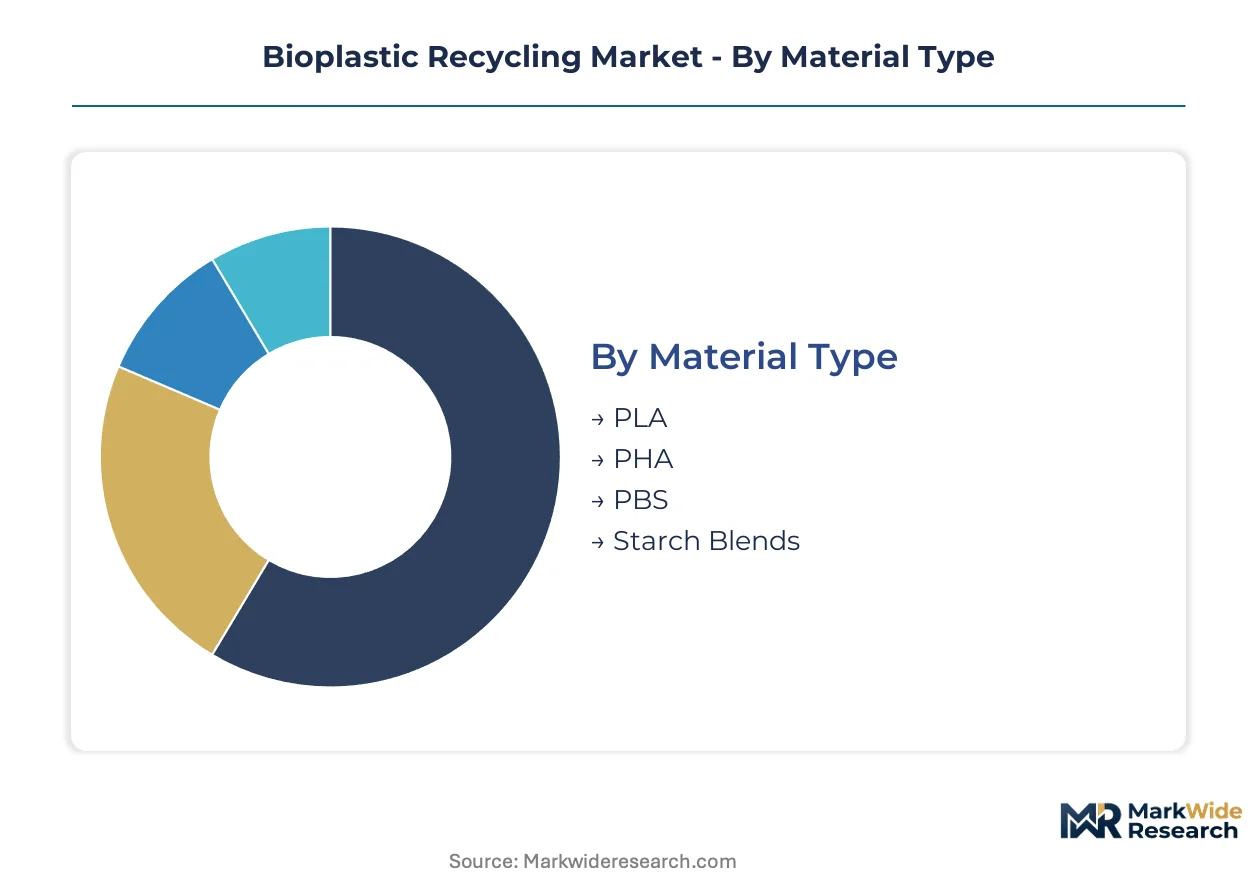
Bioplastic recycling value chains fragment sharply across material chemistries and purity requirements. Segmentation determines which processors capture premium pricing versus commodity margins.
Material Type:
Standalone polymer grades command distinct recycling infrastructure investments versus embedded multilayer systems requiring separation.
- PLA:Polylactic acid dominates current collection volumes due to established food packaging penetration. Mechanical reprocessing in Germany and the Netherlands serves non-contact applications, while chemical depolymerization in Belgium targets EFSA-certified food-contact loops. PLA leads volumes today; PHA is gaining share fastest.
- PHA:Polyhydroxyalkanoates require solvent-based or enzymatic recovery to preserve molecular weight distribution for medical-grade purity. Pharmaceutical demand in France and Switzerland sustains premium pricing far above mechanical recycling yields.
- PBS:Polybutylene succinate recycling concentrates in Italian composting corridors where industrial biodegradation certificates align with agricultural mulch film collection.
- Starch Blends:Thermoplastic starch recovery depends entirely on organic recycling pathways due to moisture sensitivity and contamination tolerance.
Starch blends anchor composting volumes across Southern Europe; PHA commands the steepest price premiums.
Recycling Method:
Cost tiers separate capital-intensive chemical operations from asset-light mechanical reprocessors serving commodity markets.
- Chemical Recycling:Depolymerization and purification restore virgin-equivalent properties for closed-loop food contact. Dutch biotechnology clusters and Belgian petrochemical corridors concentrate capacity due to skilled technician availability and REACH compliance infrastructure.
- Mechanical Recycling:Extrusion and pelletization of sorted PLA streams operates at lower energy intensity but degrades thermal stability through chain scission. German mechanical recyclers serve secondary packaging applications with relaxed purity thresholds.
- Organic Recycling:Industrial composting channels handle contaminated food-contact starch blends that mechanical routes cannot process. Italian and Spanish facilities maintain separate bioplastic sorting lines absent in Portuguese or Greek infrastructure.
- Biodegradable Processing:Anaerobic digestion and soil biodegradation pathways apply specifically to agricultural films and horticultural applications with localized collection in France's AGEC-mandated schemes.
Mechanical recycling leads volumes today; chemical recycling is expanding most quickly.
End User:
Application maturity determines certification burden and traceability investment requirements.
- Packaging:Food-contact mandates from German and French retailers drive certified recycled content demand. Multilayer complexity forces chemical recycling adoption for premium segments.
- Textiles:Fiber-to-fiber PHA recovery remains nascent due to dye contamination and blend complexity. Italian technical textile clusters experiment with mechanical reprocessing of pure PLA industrial fibers.
- Consumer Goods:Durable applications tolerate lower purity grades, sustaining mechanical recycling margins when oil prices compress bioplastic premiums.
- Automotive:Interior trim and under-hood applications specify flame-retardant grades requiring additive migration testing under REACH.
Packaging leads volumes today; automotive is climbing the fastest.
Distribution Channel:
Customer scale and geographic concentration shape channel economics and working capital intensity.
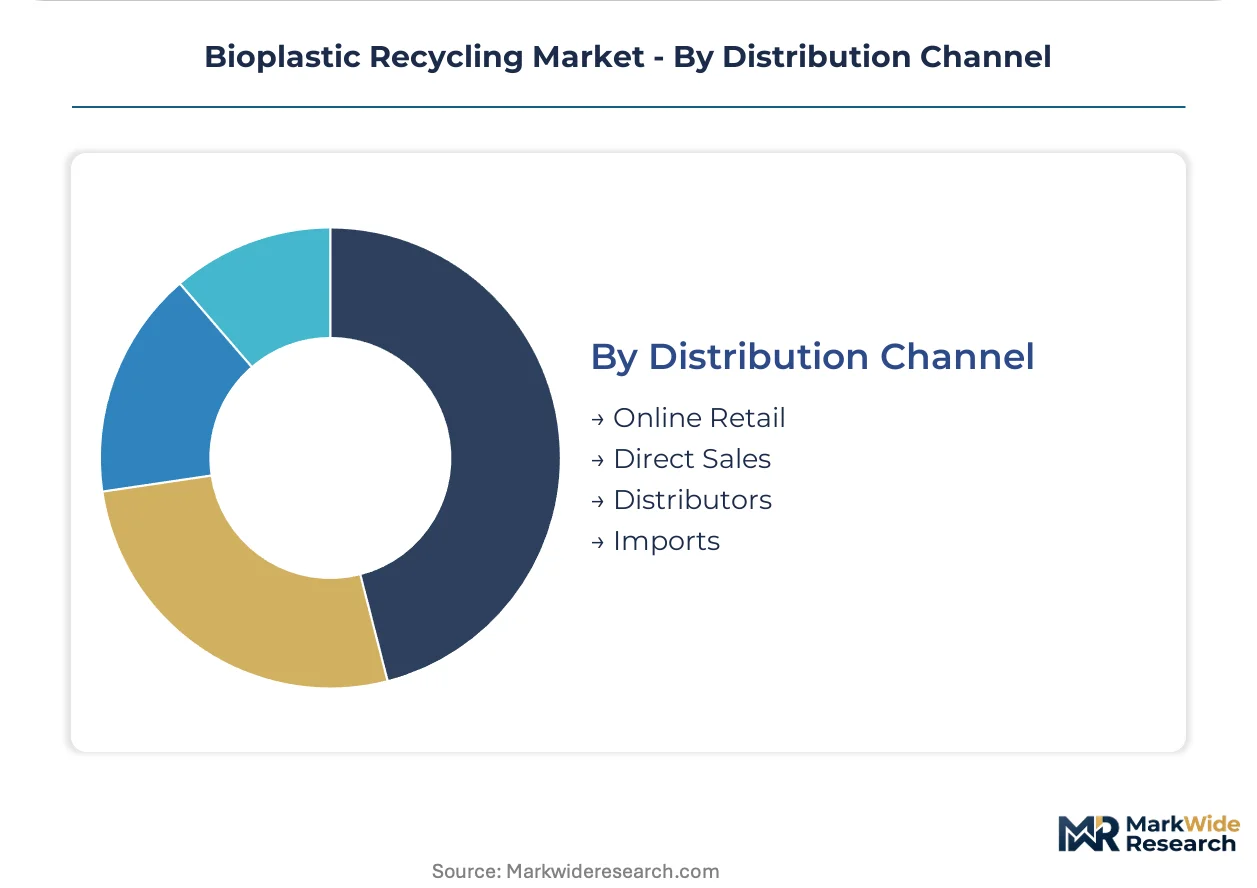
- Direct Sales:Large packaging converters in Germany and France negotiate multi-year offtake agreements with integrated chemical recyclers, securing volume commitments against certification investments.
- Distributors:Regional polymer distributors stock mechanically recycled PLA grades for mid-tier processors lacking direct supplier relationships, particularly in Eastern European markets.
- Online Retail:Specialty compounders sell small-lot certified grades through digital platforms to niche medical device manufacturers and research institutions.
- Imports:Dutch and Belgian ports serve as entry points for chemically recycled bioplastics from North American producers seeking EU Green Deal compliance positioning.
Direct sales leads volumes today; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the steepest recycled content mandates among European markets, while the Netherlands concentrates chemical recycling infrastructure that Belgium and France increasingly tap for feedstock security.
Germany
Retail chains in Bavaria and North Rhine-Westphalia enforce post-consumer recycled bioplastic floors for private-label packaging. The national packaging ordinance extends producer responsibility fees to agricultural mulch films and food service ware. Mechanical recyclers around Cologne serve secondary packaging applications with relaxed purity thresholds.
Netherlands
Chemical depolymerization clusters in Rotterdam and Eindhoven process PLA waste streams for EFSA-certified food-contact loops. REACH registration infrastructure and skilled polymer chemists from Delft and Eindhoven technical universities anchor capacity expansion. Dutch biotechnology firms deploy stereochemical purity catalysts at pilot scale for major packaging converters.
Belgium
Antwerp's petrochemical corridor integrates bioplastic chemical recycling with conventional polymer infrastructure. The EU Green Deal circular plastics targets pull investment into PLA depolymerization from packaging converters seeking compliance positioning. Flemish facilities handle multilayer packaging complexity that mechanical routes cannot process.
France
AGEC law mandates recycled content floors and extended producer responsibility schemes for food packaging chains across Île-de-France and Auvergne-Rhône-Alpes. Pharmaceutical demand in Lyon and Geneva-adjacent regions sustains premium PHA chemical recycling margins. Major retailers in Paris now require blockchain-verified chain of custody for certified grades.
Italy
Industrial composting facilities in Lombardy and Emilia-Romagna maintain separate bioplastic sorting lines absent in Portuguese or Greek infrastructure. Starch-based polymer recovery through organic recycling channels dominates contaminated food-contact applications. Northern Italian technical textile clusters experiment with mechanical reprocessing of pure PLA industrial fibers.
Bioplastic Recycling Market Competitive Environment
Top-tier vendors anchor integrated chemical recycling infrastructure, while mid-scale mechanical reprocessors compete on volume throughput and regional collection contracts. The vendor base stratifies across three tiers: multinational petrochemical incumbents with captive biopolymer divisions, specialized bioplastic producers backward-integrated into recovery networks, and independent recyclers serving commodity packaging markets. Strategic archetypes include integrated PLA producers controlling feedstock quality across collection zones, starch-based specialists with composting channel partnerships, and chemical technology licensors deploying depolymerization catalysts. Capacity expansion and certification investments represent the dominant competitive moves as EFSA traceability mandates tighten.
Within the integrated producer tier, NatureWorks LLC exemplifies upstream control over PLA collection networks, while Novamont S.p.A. anchors European capacity for starch-based polymer recovery. BASF SE occupies a position among petrochemical incumbents competing through specialized chemical recycling infrastructure. These three entities represent distinct strategic archetypes: biopolymer-native vertical integration, regional composting channel dominance, and conventional petrochemical technology transfer into circular bioplastic systems.
| Leading Market Players |
|---|
| NatureWorks LLC |
| Novamont S.p.A. |
| BASF SE |
| Biome Bioplastics |
| TotalEnergies Corbion |
| BioLogiQ, Inc. |
| Braskem S.A. |
| FKuR Kunststoff GmbH |
| Danimer Scientific |
| Others |
Value Chain & Pricing Dynamics
Depolymerization catalyst costs flow from Dutch biotechnology clusters through Belgian chemical corridors into EFSA-certified PLA grades, compressing price premiums as stereochemical purity investments diffuse across Western European packaging converters.
Pricing Analysis
Capacity additions in Belgium and the Netherlands are reshaping price floors for chemically recycled PLA grades. Three-tier pricing structure across EFSA-certified food-contact, industrial-grade mechanical, and commodity composting tiers separates premium pharmaceutical PHA from standard packaging PLA. Cost compression in mechanical recycling runs through German secondary packaging markets as virgin petrochemical resin volatility erodes bioplastic premiums. Mid-tier processors lacking direct converter relationships exhibit highest price sensitivity; pharmaceutical buyers in Lyon and Geneva-adjacent regions show lowest.
Supply Chain Analysis
Dual-sourcing requirements from French retailers and German packaging chains mandate multi-supplier qualification across Dutch chemical recyclers and Belgian depolymerization facilities. Feedstock draws from German post-consumer collection networks, Italian industrial composting corridors, and French agricultural mulch film recovery schemes. Single-source vulnerability concentrates in Rotterdam-Eindhoven catalyst supply chains. Distribution runs through direct sales to large converters, regional distributors for Eastern European mid-tier processors, and digital platforms for specialty medical compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between Germany's national packaging ordinance and France's AGEC law creates geographic cost differentials for collection infrastructure investment, favoring cross-border feedstock aggregation strategies.
For Market Incumbents: Extend EFSA traceability certification downstream into blockchain-verified chain of custody systems to defend against emerging enzymatic depolymerization entrants. Deepen backward integration into Dutch and Belgian collection zones before skilled polymer chemist scarcity tightens further. Prioritize capacity additions in Flemish multilayer processing corridors where mechanical routes fail.
For New Entrants and Emerging Players: Regional polymer distributors in Poland and Czechia represent the most penetrable channel partner type for mechanically recycled PLA grades lacking direct converter relationships. Target Italian composting facilities for starch blend recovery partnerships absent in Portuguese or Greek infrastructure. Pursue white-label certification services for retailers unbundling recycled content verification from resin supply agreements.
For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration infrastructure concentrates in Dutch and Belgian technical university corridors, leaving Eastern European mechanical recyclers with disproportionate compliance burdens. Mid-scale chemical recyclers with pilot-scale stereochemical purity catalysts represent prime acquisition targets. Watch enzymatic depolymerization capital flows from pharmaceutical investors as inflection signal for biological pathway economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Belgian PLA depolymerization investments align with EU Green Deal circular plastics targets. |
| Backward Integration | German mechanical recyclers securing post-consumer collection contracts reduce feedstock volatility. |
| Green Manufacturing Transition | Dutch biotechnology clusters deploying electrified catalyst systems compress virgin-recycled PLA cost gaps. |
| Long-term Supply Agreement | French retailers mandating blockchain-verified chain of custody lock in certified recycler volumes. |
| Joint Venture | Italian composting partnerships for starch blend recovery exploit Southern European infrastructure gaps. |
Study Parameters
Direct dialogue with chemical recycling plant managers, polymer procurement leads at German packaging converters, EFSA regulatory affairs specialists, and Dutch biotechnology R&D directors grounded qualitative insights. Secondary validation drew from ECHA polymer registration guidance, EU Green Deal circular plastics policy documents, national packaging ordinance filings, and industrial composting facility capacity databases. Bottom-up feedstock flow modeling and top-down regulatory impact assessment triangulated market sizing.
Segmented outputs across material type, recycling method, end user, and distribution channel dimensions over the projection horizon informed value chain economics. CAGRs derived from installed capacity buildout curves, EFSA certification timeline assumptions, and Extended Producer Responsibility fee structures. Forecast inputs incorporated enzymatic depolymerization pilot scale announcements and REACH substance characterization obligation phase-ins.
Revisions become necessary when EFSA harmonizes testing protocols for mechanically versus chemically recycled grades, or when petrochemical resin price volatility shifts bioplastic premium thresholds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Industrial Plastic Market
Recycled Plastics
BPA Free Plastic Market
Recycled Plastics
Global Recycled PET (R-PET) Bottles Market
Recycled Plastics
Recycled Leather Market
Recycled Plastics
North America Plastic Waste Management Market
Recycled Plastics
Recycled Plastic and Plastic Waste to Oil Market
Recycled Plastics
North America Recycled Plastics Market
Recycled Plastics
Plastic Recycling Market
Recycled Plastics
Iron Recycling Market
Recycled Plastics
Global Recycled Base Oil Market
Recycled Plastics
Aluminum Recycling Market
Recycled Plastics
Malaysia Plastics Market
Recycled Plastics
Japan Recycled Plastics Market
Recycled Plastics
Plastic Waste Management Market
Recycled Plastics
Green Polyvinyl Chloride Market
Recycled Plastics
Vietnam Recycling Market