
 Non PVC Plasticizers Market | 2026-2036
Non PVC Plasticizers Market Size, Share, and Industry Trends Forecast 2026-2036
Non PVC Plasticizers Market Outlook
REACH registration compliance is bifurcating the competitive landscape into qualified suppliers and marginal participants. BASF SE leverages its integrated oxo-alcohol backbone to sustain supply security across European coating houses. Eastman Chemical Company anchors its position through specialized adipate and trimellitate portfolios that serve automotive interior specifications. Evonik Industries differentiates via bio-based platform chemistry that navigates tightening substance restrictions in consumer-facing applications.
Non PVC plasticizers are organic additives that impart flexibility, workability, and elasticity to rigid polymer matrices without chlorine-containing resin backbones, typically functioning through intermolecular lubrication at loadings of 15 to 50 parts per hundred resin. Phthalate-free formulations now dominate value generation as formulators eliminate ortho-phthalate esters from food-contact and pediatric product streams. Citrate esters represent the fastest-growing structural segment, capturing margin pools in medical device and pharmaceutical packaging applications where biocompatibility certifications gate market access. Epoxidized oil variants occupy mature volume positions in construction sealants and flooring compounds where cost-performance thresholds resist premium substitution.
REACH substance restrictions, FDA food-contact notifications, and ECHA authorization requirements collectively reshape product portfolios by disqualifying chemistries that lack toxicological dossiers or migration testing compliance. The EU Green Deal chemical sustainability targets and state-level phthalate disclosure laws in California and Maine extend regulatory fragmentation that complicates formulation standardization. Stakeholders must monitor evolving substance candidate lists and pre-register next-generation ester platforms before authorization deadlines foreclose market participation.
Market Dynamics
REACH substance restrictions and FDA food-contact notifications are compressing the addressable chemistry set, forcing formulators to rebuild portfolios around certified alternatives before authorization deadlines foreclose legacy participation.
Growth Catalysts
- REACH Authorization Requirements:ECHA's tightening ortho-phthalate restrictions in Europe accelerate migration toward citrate ester and adipate platforms that carry full toxicological dossiers.
- Medical Device Biocompatibility:ISO 10993 certification requirements for blood-contact applications pull specialized trimellitate formulations into catheter and tubing specifications.
- East Asian Coating Demand:Epoxy-functionalized plasticizers displace legacy chemistry in waterborne industrial coatings across manufacturing clusters in China and South Korea.
Market Restraints
- Oxo-Alcohol Feedstock Volatility:Propylene and n-butanol price swings transmit directly into ester production economics, compressing margin stability for non-integrated compounders.
- German Supply Concentration:BASF SE and Evonik Industries anchor European adipate and specialty ester output, creating single-source vulnerability for coating houses without qualified second suppliers.
- Performance Gap in High-Temperature Applications:Bio-based alternatives exhibit thermal stability limitations above 150°C that resist substitution in under-the-hood automotive specifications.
Strategic Opportunities
- India Pharmaceutical Packaging:CDSCO's alignment with ICH Q3C residual solvent guidelines creates first-mover advantage for citrate ester suppliers qualifying blow-fill-seal container systems.
- California Proposition 65 Disclosures:State-level phthalate warning mandates drive brand-owner specification changes that favor pre-certified alternatives in consumer goods supply chains.
- Epoxy-Citrate Hybrid Platforms:Convergence of epoxidized vegetable oils with citrate backbone chemistry yields dual-function additives serving both flexibility and heat-stabilization roles in PVC-free flooring.
Industry Challenges
- Migration Testing Throughput:FDA food-contact notification timelines stretch 18-24 months for novel ester structures, delaying revenue recognition for reformulated product lines.
- Legacy Equipment Compatibility:Processing temperature windows for bio-based alternatives diverge from phthalate-optimized extrusion lines, requiring capital retooling at compounder facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non PVC Plasticizers Market |
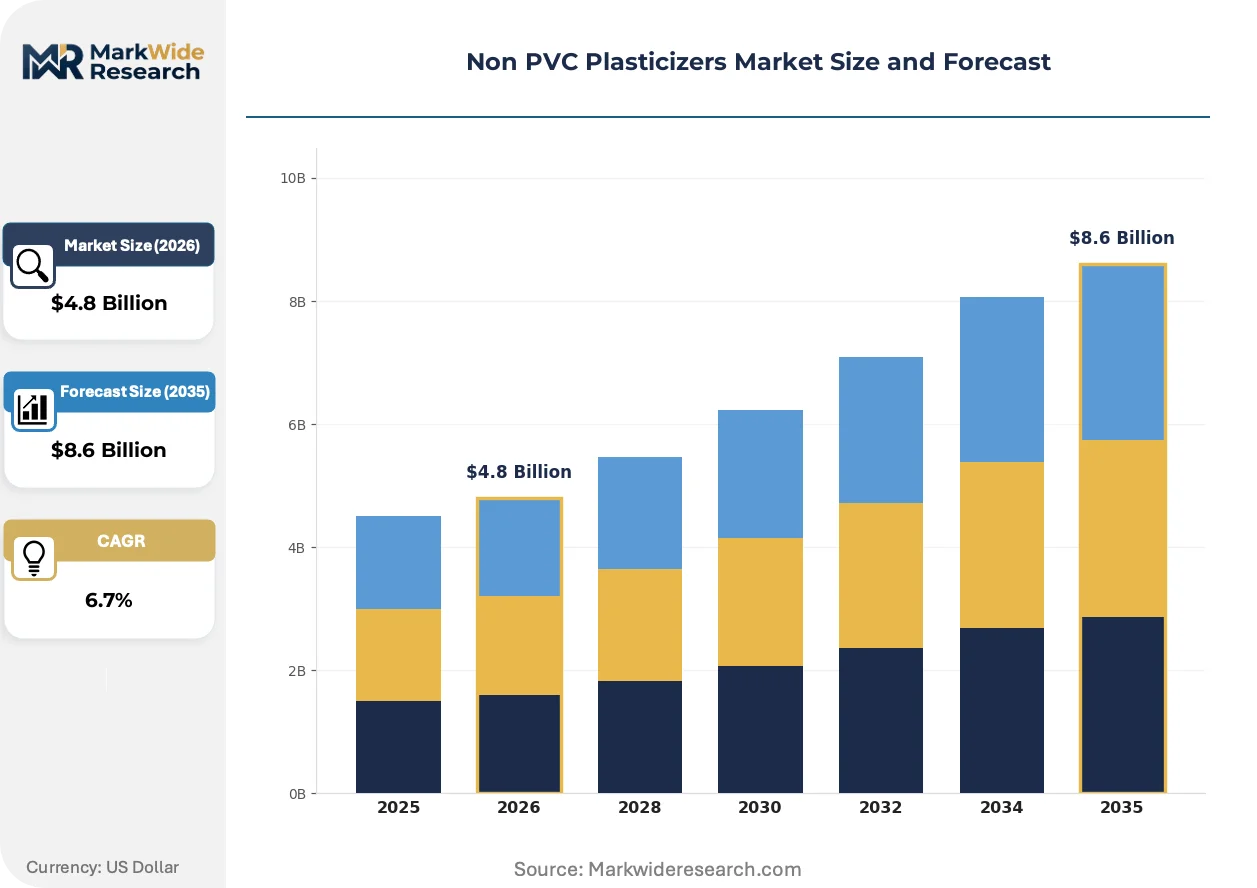
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phthalate-Free, Epoxidized Oils, Citrate Esters, Natural Oil Esters Application: Coatings, Adhesives, Sealants, Flooring End User: Construction, Automotive, Packaging, Consumer Goods Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | BASF SE, Eastman Chemical Company, Evonik Industries, ExxonMobil Chemical, LG Chem, Nan Ya Plastics Corporation, Lanxess AG, Mitsubishi Chemical Corporation, KLJ Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non PVC Plasticizers Market Strategic Shifts
Formulation chemistry is pivoting toward multifunctional additives that combine plasticization with secondary performance attributes, compressing the traditional additive package count while raising the technical bar for supplier qualification.
Bio-based polyol esters derived from epoxidized soybean and linseed oils are supplanting petroleum-derived adipates in construction sealant formulations. European flooring manufacturers have accelerated qualification timelines from 36 to 18 months for these alternatives. The shift is compressing addressable volume for conventional esters in cost-sensitive building materials segments.
EU Green Deal chemical sustainability targets are mandating carbon footprint disclosure across the full ester value chain. BASF SE and Eastman Chemical Company have restructured supply contracts to include Scope 3 reporting clauses. Automotive interior specifications in Germany now require mass-balance certification for bio-attributed content, forcing tier-two compounders to upgrade documentation systems.
Specification-driven procurement now dominates medical device and food-contact segments, displacing price-primary sourcing models. Brand-owner compliance teams in the United States have centralized plasticizer qualification authority, extending vendor onboarding cycles. The pattern is most visible in pediatric product supply chains where California and Maine disclosure laws create multi-state compliance complexity.
Non PVC Plasticizers Market Segmentation
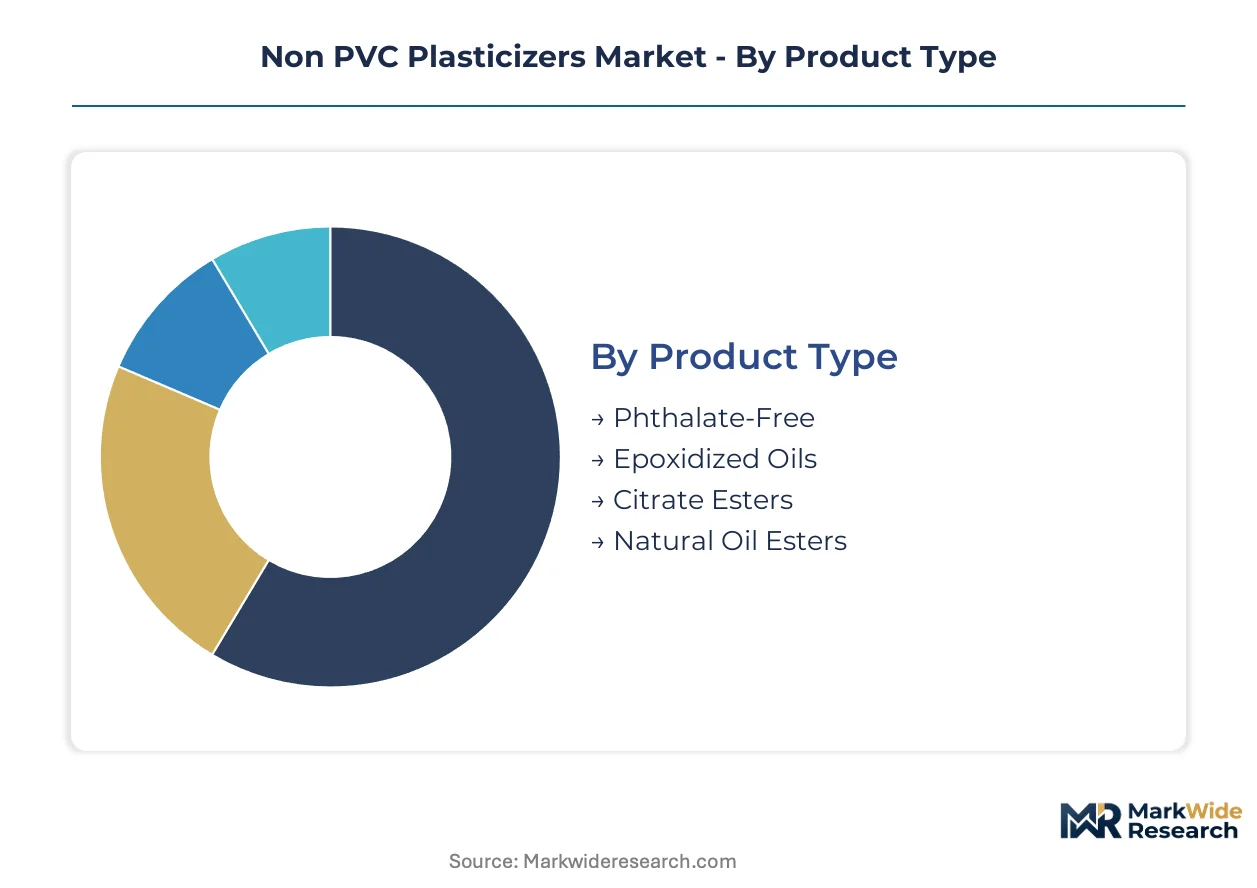
Segmentation in the Non PVC Plasticizers Market reveals how regulatory pressure and end-use certification requirements fragment supply strategies. Formulators must match specific ester chemistry to application migration limits and biocompatibility standards.
Product Type:
REACH substance restrictions and FDA food-contact notifications bifurcate qualification pathways, concentrating procurement among certified suppliers while marginalizing legacy phthalate portfolios.
- Citrate Esters:Acetyl tributyl citrate and triethyl citrate formulations deliver low-toxicity flexibility for blood-contact medical devices and pharmaceutical blister packs. German automotive interior specifications now mandate these for pediatric-safety-rated components as ECHA tightens ortho-phthalate authorization requirements.
- Phthalate-Free:Adipate and trimellitate esters dominate reformulation efforts where DINP and DEHP face displacement. East Asian coating houses in South Korea and China specify these for waterborne industrial systems to meet export-market substance declarations.
- Epoxidized Oils:Soybean and linseed oil derivatives provide dual-function plasticization with heat stabilization for construction sealants.
- Natural Oil Esters:Bio-based polyol platforms from renewable feedstocks serve EU Green Deal carbon-footprint mandates in flooring compounds.
Established volume favors epoxidized oils; emerging adoption favors citrate esters.
Application:
Performance thresholds and processing temperature windows determine formulation selection across construction and industrial end-uses.
- Coatings:Epoxy-functionalized plasticizers enable low-VOC waterborne systems for automotive refinish and industrial maintenance applications in China and Germany.
- Sealants:Construction-grade formulations demand thermal stability above 150°C for structural glazing and expansion joint compounds.
- Adhesives:Pressure-sensitive and reactive systems in packaging laminates require controlled migration profiles to meet FDA food-contact boundaries.
- Flooring:PVC-free resilient surfaces specify bio-based esters for mass-balance certification under EU Green Deal disclosure rules.
Coatings command the steepest expansion trajectory; flooring maintains the deepest volume base.
End User:
Specification authority has migrated from procurement teams to compliance officers, extending vendor qualification cycles.
- Automotive:German OEMs now require ISO 10993-5 cytotoxicity screening for all interior plasticizers, favoring citrate and trimellitate platforms with full toxicological dossiers.
- Packaging:Blow-fill-seal pharmaceutical containers in India face CDSCO alignment with ICH Q3C residual solvent limits, pulling citrate esters into qualification pipelines.
- Construction:Sealant and flooring compounders prioritize cost-performance ratios where epoxidized oils resist premium substitution.
- Consumer Goods:California Proposition 65 and Maine disclosure laws force brand-owner specification changes in pediatric and food-contact product streams.
Packaging generates the fastest specification turnover; construction retains the highest volume concentration.
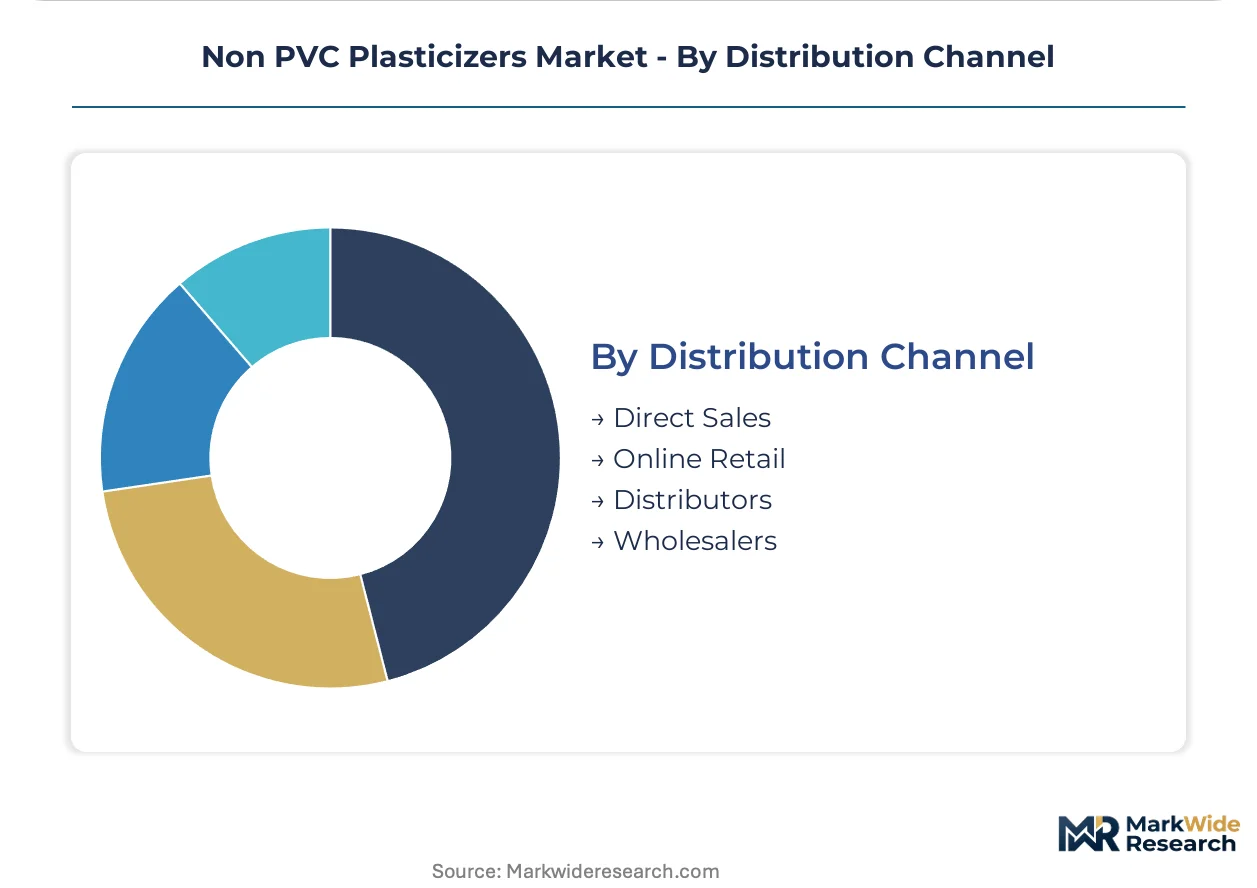
Distribution Channel:
Supply security concerns and technical service requirements reshape channel selection for qualified ester platforms.
- Direct Sales:BASF SE and Eastman Chemical Company anchor European coating supply through dedicated account management for REACH-registered portfolios.
- Distributors:Regional chemical distributors in Germany and South Korea maintain qualified inventory for mid-tier compounders lacking direct supplier relationships.
- Online Retail:Specialty esters for R&D and pilot-scale formulation appear on B2B platforms with certificate-of-analysis documentation.
- Wholesalers:Volume commodity adipates flow through construction-focused wholesale networks serving flooring and sealant compounders.
Direct sales capture the most qualified volume; distributors bridge the widest geographic coverage gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH authorization deadlines and FDA food-contact notification requirements are redirecting procurement flows toward jurisdictions with established toxicological dossier infrastructure. German automotive OEMs and East Asian coating clusters now anchor qualified supply networks.
Germany
Automotive interior specifications from BMW, Mercedes-Benz, and Volkswagen mandate ISO 10993-5 cytotoxicity screening for all cabin plasticizers. ECHA's tightening ortho-phthalate substance restrictions under REACH authorization protocols favor citrate ester and trimellitate platforms. The Rhine-Ruhr industrial corridor concentrates compounding capacity for coating houses serving export markets.
United States
California Proposition 65 warning mandates and Maine disclosure laws force brand-owner specification changes in pediatric and food-contact product streams. FDA food-contact notification timelines stretching 18-24 months delay revenue recognition for novel ester structures. The Gulf Coast petrochemical corridor maintains adipate production infrastructure for construction sealant compounders.
China
Waterborne industrial coating demand in manufacturing clusters drives epoxy-functionalized plasticizer qualification. NMPA alignment with ICH Q3C residual solvent guidelines shapes pharmaceutical packaging material selection. The Yangtze River Delta concentrates formulation R&D for automotive refinish applications serving domestic EV manufacturers.
India
CDSCO's harmonization with ICH Q3C standards creates first-mover advantage for citrate ester suppliers qualifying blow-fill-seal container systems. Domestic pharmaceutical packaging investment accelerates migration away from legacy phthalate chemistry. Gujarat and Maharashtra host expanding compounding capacity for medical device tubing specifications.
South Korea
Industrial coating exports to EU markets require REACH-registered plasticizer platforms with full toxicological documentation. MFDS pharmaceutical packaging regulations align with international migration testing standards. The Ulsan-Busan petrochemical corridor supplies epoxy-functionalized alternatives for waterborne automotive refinish systems.
Non PVC Plasticizers Market Competitive Environment
Player mix skews toward integrated petrochemical majors with captive oxo-alcohol supply and specialized ester compounders with certification depth. The vendor base separates into three tiers: multinational chemical conglomerates with REACH registration infrastructure, regional compounders serving construction and coating segments, and bio-based platform specialists navigating EU Green Deal disclosure mandates. Dominant competitive moves include backward integration into renewable feedstock cultivation and strategic partnerships with automotive tier-one suppliers for pre-qualified material streams.
Among European-integrated chemical majors, BASF SE and Evonik Industries exemplify the REACH-registered tier with supply security across coating houses. Eastman Chemical Company occupies a specialist position through adipate and trimellitate portfolio depth. These three entities represent contrasting archetypes: the petrochemical-integrated conglomerate, the specialty ester compounder, and the bio-based platform developer.
| Leading Market Players |
|---|
| BASF SE |
| Eastman Chemical Company |
| Evonik Industries |
| ExxonMobil Chemical |
| LG Chem |
| Nan Ya Plastics Corporation |
| Lanxess AG |
| Mitsubishi Chemical Corporation |
| KLJ Group |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day inventory cycles for REACH-registered citrate esters concentrate pricing power with German and South Korean producers who control oxo-alcohol feedstock access. This lead-time band tightens whenever propylene volatility disrupts ester production economics, forcing coating houses to accept premium terms or face formulation gaps.
Pricing Analysis
Certification level (REACH-registered vs. non-registered) creates the primary spread between qualified and marginal suppliers. Three-tier pricing structure separates FDA food-contact grades from industrial coating specifications and commodity construction grades. Pricing pressure stems from oxo-alcohol feedstock volatility transmitting directly into ester production costs. Construction sealant compounders exhibit highest price sensitivity; medical device manufacturers show lowest sensitivity due to biocompatibility certification requirements.
Supply Chain Analysis
Strategic stockpiling of REACH-registered citrate esters dominates procurement behavior among German automotive tier-one suppliers, while just-in-time inventory prevails in cost-sensitive construction segments. Supply concentrates in Germany, China, and South Korea for epoxy-functionalized and adipate platforms. Production draws from propylene, n-butanol, and epoxidized soybean oil feedstocks. Single-source vulnerability from BASF SE and Evonik Industries in European adipate output creates qualification bottlenecks. Distribution runs through direct sales for certified volumes and regional distributors for mid-tier compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non PVC plasticizers sit in early-cycle expansion as REACH authorization deadlines force wholesale portfolio rebuilding before legacy chemistry exits the addressable market. This regulatory tailwind compresses vendor qualification timelines and concentrates procurement among pre-certified suppliers.
For Market Incumbents: Consolidate REACH registration infrastructure through dedicated toxicological dossier investment, particularly for citrate ester platforms facing ECHA authorization deadlines. Lock in long-term offtake agreements with German automotive OEMs before second suppliers achieve ISO 10993 certification. Backward integration into renewable feedstock cultivation defends margin position against commodity price swings in epoxidized oils.
For New Entrants and Emerging Players: Lead with CDSCO-aligned citrate ester qualification for Indian pharmaceutical packaging, where blow-fill-seal container investment outpaces domestic supply capacity. Target California Proposition 65-driven specification changes in pediatric product supply chains as the most penetrable white-space entry point. Pursue joint development agreements with East Asian coating houses seeking REACH-registered alternatives for EU export markets.
For Investors and Strategic Acquirers: Carve-out targets emerge from petrochemical majors divesting non-core ester portfolios under EU Green Deal carbon-footprint disclosure pressure. Five-to-ten-year viability favors bio-based platform specialists with mass-balance certification infrastructure. Watch FDA food-contact notification approval velocity as the signal indicating whether novel ester structures can achieve revenue recognition timelines competitive with legacy chemistry.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Investment | Full toxicological dossiers gate market access as ECHA authorization deadlines tighten. |
| Backward Integration into Renewable Feedstocks | Captive supply of epoxidized soybean oil hedges commodity volatility in bio-based platforms. |
| Joint Venture with Automotive Tier-One Suppliers | Pre-qualified material streams secure specification authority before competitors complete certification. |
| CDSCO-Aligned Qualification for Indian Pharma Packaging | First-mover advantage in blow-fill-seal container systems accelerates revenue recognition. |
| Mass-Balance Certification Infrastructure | EU Green Deal disclosure mandates force tier-two compounders to upgrade documentation systems. |
Study Parameters
Desk research of customs trade data, ECHA substance registration databases, and SEC chemical sector filings preceded structured interviews with plant managers at European coating houses, procurement leads at German automotive OEMs, distribution channel partners in South Korea, and technical R&D directors at adipate compounders. Primary fieldwork combined with secondary validation through customs records and Cefic industry reports enabled bottom-up volume triangulation against top-down value estimates.
Variance decomposition across product type, application, end-use industry, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume build-ups incorporating REACH authorization timelines, FDA food-contact notification throughput, and East Asian coating demand trajectories. Modeled inputs included propylene price elasticity coefficients and ISO 10993 certification penetration rates by medical device category.
Forecasts assume regulatory continuity in REACH authorization protocols and FDA food-contact notification procedures; material policy shifts would require re-modeling. Specific risks include ECHA accelerating ortho-phthalate restrictions, CDSCO delaying ICH Q3C alignment, or oxo-alcohol supply disruptions from feedstock volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Waterborne Curing Agents Market
Chemicals
North America Methanol Market
Chemicals
Global Bleaching Agents Market
Chemicals
Global Boron Trifluoride Market
Chemicals
Concrete Surface Treatment Chemicals Market
Chemicals
Global Diacetone Alcohol Market
Chemicals
Global Monochloroacetic Acid Market
Chemicals
Welding Chemicals Market
Chemicals
Global Photoresist Chemicals Market
Chemicals
Superplasticizer Market
Chemicals
Methyldiisopropanolamine Market
Chemicals
Trichlorosilane Market
Chemicals
Potassium Zirconium Fluoride Market
Chemicals
Chromium Trioxide Market
Chemicals
Asia-Pacific Methyl Acrylate Market
Chemicals
Sulfur Chemicals Market