
 Solvent-Based Plastic Recycling Market | 2026-2036
Solvent-Based Plastic Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Solvent-Based Plastic Recycling Market Intelligence
A shortage of chemical engineers trained in polymer dissolution kinetics is unwinding capacity expansion timelines across the value chain. PureCycle Technologies leverages its proprietary purification platform to anchor North American production of ultra-pure recycled polypropylene. Carbios competes through enzymatic depolymerization R&D, while Eastman Chemical Company dominates methanolysis-based polyester recycling at industrial scale.
Solvent-based plastic recycling deploys selective dissolution and precipitation to separate target polymers from mixed waste streams, operating at temperatures below thermal degradation thresholds to preserve molecular weight and mechanical properties. Polyethylene and polypropylene fractions command the deepest margin pools due to their prevalence in post-industrial and post-consumer feedstocks, though polystyrene recovery is accelerating as dissolution kinetics prove favorable for food-contact applications. Chemical recycling and solvent extraction technologies lead deployment, while mechanical recycling occupies lower-value loops where contamination tolerance permits.
The EPA's emerging framework for advanced recycling facility permitting under the Resource Conservation and Recovery Act is reshaping project economics in the United States, while REACH compliance in Europe governs solvent residue thresholds in recycled pellets destined for consumer goods. The EU Green Deal's recycled content mandates for packaging are tightening product standards and channeling capital toward food-grade solvent purification systems. Stakeholders must monitor how regulatory divergence between jurisdictions fragments equipment certification requirements and feedstock qualification protocols.
Market Dynamics
Polymer dissolution kinetics expertise scarcity is compressing capacity expansion timelines across the value chain, forcing project sponsors to extend commissioning schedules or accept suboptimal yield curves during ramp-up phases.
Growth Catalysts
- EU Green Deal packaging mandates:Recycled content thresholds for food-contact applications are pulling solvent-purified resins into converter procurement portfolios ahead of mechanical recycling qualification.
- Automotive lightweighting clusters:German OEMs are co-locating dissolution infrastructure near chemical parks to secure closed-loop polypropylene feedstocks for interior components.
- Methanolysis platform maturation:Polyester-specific solvent recovery systems are achieving food-grade purity at industrial throughput, opening beverage bottle applications previously reserved for virgin resin.
Market Restraints
- Specialized solvent cost volatility:Polar aprotic solvent prices fluctuate with acetic acid and petrochemical feedstock indices, eroding project IRR sensitivity in tolling arrangements.
- German engineering concentration:Dissolution reactor fabrication capacity clusters in Baden-Württemberg and Bavaria, creating single-source dependency for North American project developers.
- REACH residue thresholds:ECHA-mandated solvent limits in recycled pellets add analytical certification burdens that mechanical recyclers bypass entirely.
Strategic Opportunities
- India industrial waste streams:Post-industrial polyolefin arisings from Gujarat and Maharashtra chemical zones remain largely unaddressed by dissolution infrastructure, offering first-mover feedstock access.
- Enzymatic-solvent hybrid platforms:Carbios-style enzymatic depolymerization paired with selective dissolution is opening mixed-polyester-polyolefin streams previously rejected as uneconomical.
- Extended producer responsibility schemes:France's Citeo-modulated fees are creating preferential gate fees for solvent-recycled output versus mechanical alternatives.
Industry Challenges
- Polymer dissolution kinetics talent gap:Chemical engineering programs produce few graduates trained in non-thermal separation, forcing operators to poach from pharmaceutical extraction sectors.
- Food-contact certification timelines:EFSA novel food approvals for recycled content extend 18-24 months, delaying revenue recognition for packaging-focused investments.
- Legacy mechanical recycling integration:Dissolution lines must interface with existing sortation infrastructure designed for flake output, requiring feedstock preprocessing investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solvent-Based Plastic Recycling Market |
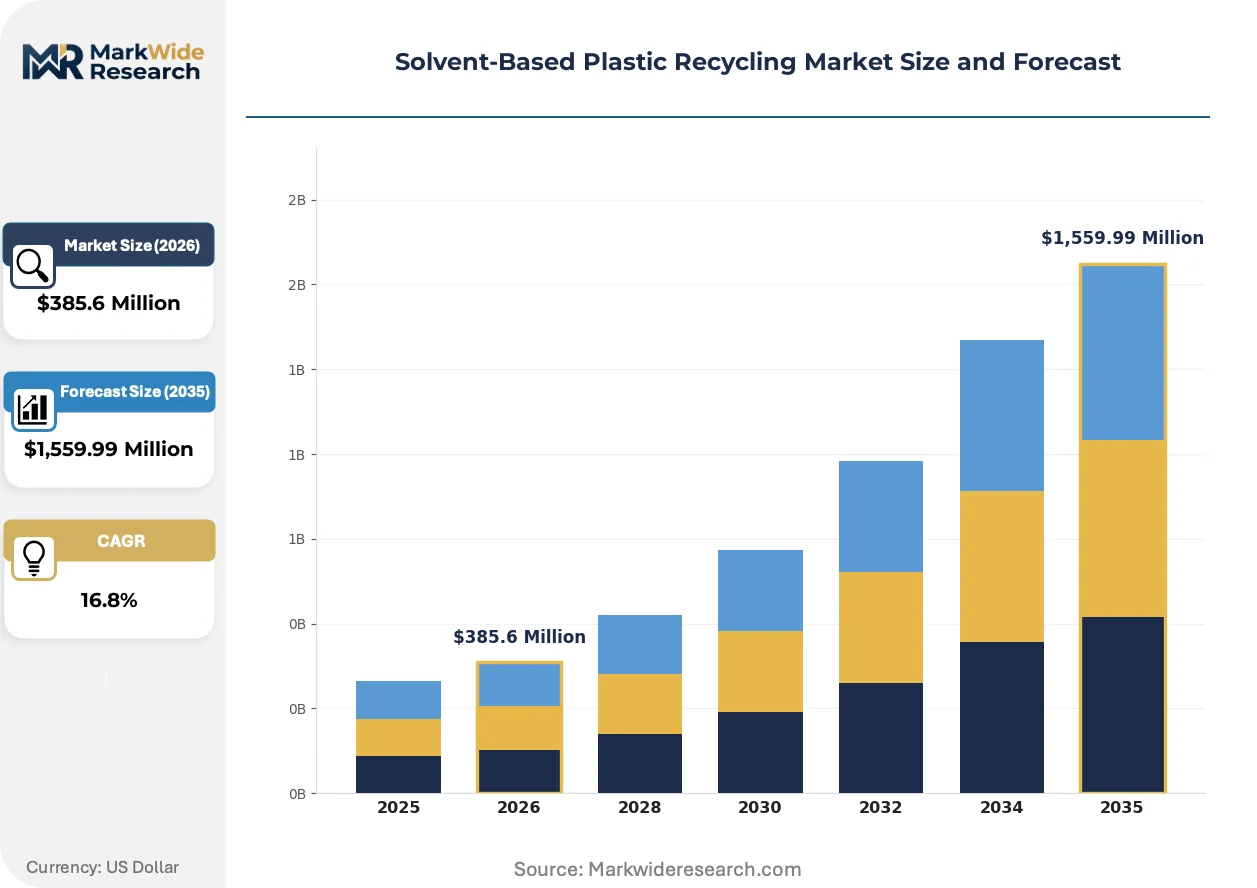
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,559.99 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polystyrene, Polyvinyl Chloride Technology: Chemical Recycling, Mechanical Recycling, Solvent Extraction, Thermal Depolymerization End User: Automotive, Consumer Goods, Packaging, Construction Application: Injection Molding, Extrusion, Blow Molding, Coating |
| Companies Covered | Agilyx, Carbios, PureCycle Technologies, Itero Technologies, Aduro Clean Technologies, PLASTIC ENERGY Limited, Eastman Chemical Company, Clariter, Ioniqa Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solvent-Based Plastic Recycling Market Strategic Shifts & Innovations
Selective dissolution technology is fragmenting the recycling value chain into purity-tiered output streams, with molecular-weight-preserving processes capturing premium applications previously inaccessible to thermal methods.
Supercritical solvent extraction is bifurcating the polyolefin recovery landscape. This platform operates below thermal degradation thresholds to preserve mechanical properties in polypropylene and polyethylene fractions. Packaging converters in Germany and the Netherlands are qualifying supercritical output for thin-film applications at accelerated pace. The technology is bifurcating margin pools between food-grade solvent-purified resins and lower-tier mechanical outputs.
REACH Annex XVII amendments governing solvent residue limits in consumer goods are tightening pellet specifications across EU member states. Industrial consequence includes mandatory gas chromatography-mass spectrometry testing protocols that add EUR 40-60 per tonne to certification costs. Food-contact packaging segments are responding by consolidating procurement around tollers with in-house analytical laboratories.
Brand-owner sustainability procurement is compressing supplier qualification cycles from 24 months to 8-12 months for chemically recycled content. Tier-1 packaging suppliers are disintermediating traditional resin distributors to secure direct offtake agreements with solvent recycling operators. This compression is most visible in German automotive supply chains, where BMW and Mercedes-Benz sustainability targets are forcing tier-n suppliers to validate dissolution-sourced polypropylene by Q3 2026.
Solvent-Based Plastic Recycling Market Segmentation
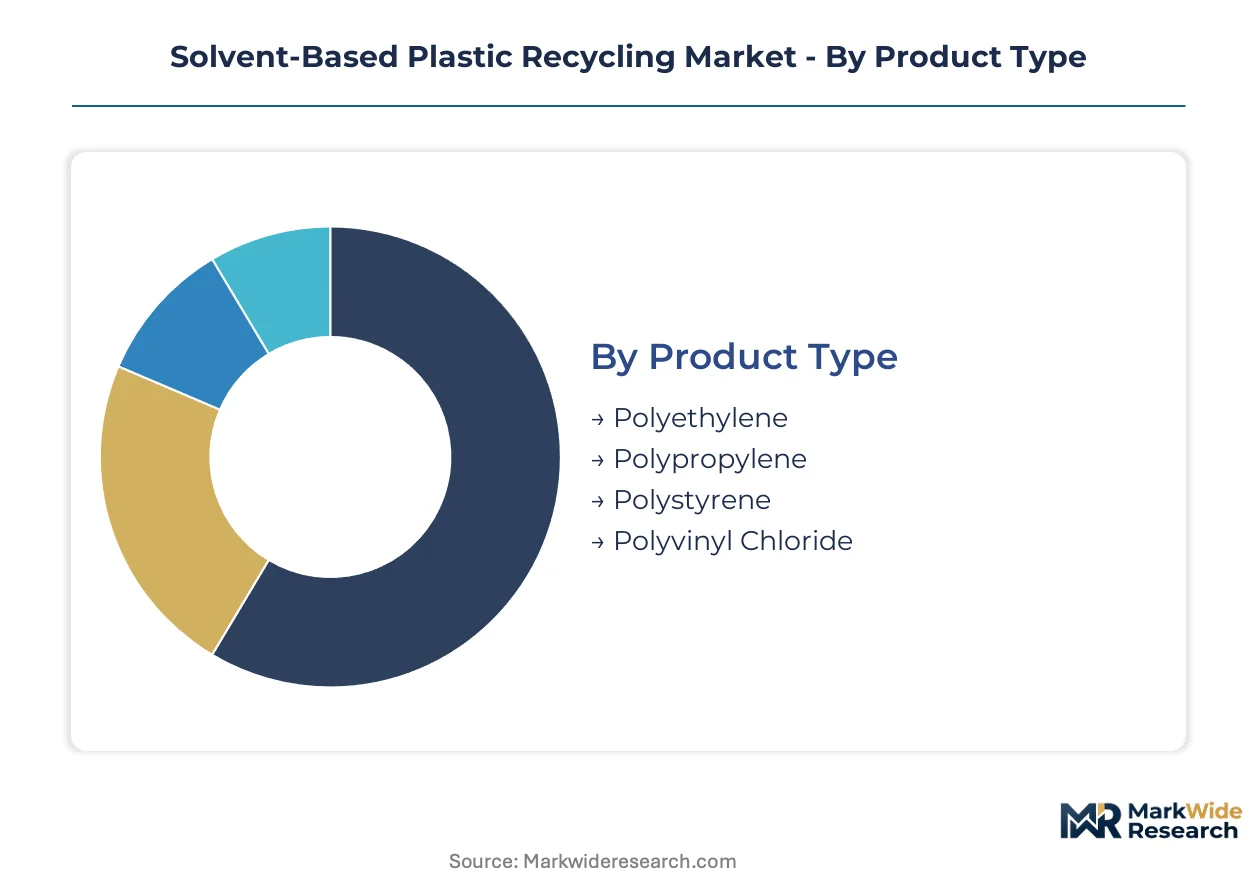
Solvent-based plastic recycling segments flow through distinct commercial channels shaped by polymer compatibility, purity requirements, and end-use certification barriers. Channel selection determines margin capture and regulatory burden across each segment tier.
Product Type:
Channel mix varies sharply by polymer density and dissolution kinetics, with high-volume polyolefins moving through bulk chemical distribution and specialty resins requiring direct converter relationships.
- Polyethylene:Low-density and linear-low-density fractions dominate post-consumer film feedstock streams. German packaging converters are qualifying dissolution-purified polyethylene for flexible food-contact applications ahead of mechanical recycling alternatives. REACH residue compliance adds EUR 40-60 per tonne in analytical certification costs.
- Polypropylene:Automotive interior specifications demand molecular-weight preservation that thermal methods degrade. BMW and Mercedes-Benz sustainability procurement is compressing supplier qualification cycles to 8-12 months for dissolution-sourced homopolymer and copolymer grades.
- Polystyrene:Favorable dissolution kinetics enable food-contact recovery with lower solvent intensity than polyolefin systems.
- Polyvinyl Chloride:Chlorine content complicates solvent selection and requires specialized precipitation protocols.
Polyethylene dominates installed base. Polypropylene is where expansion concentrates.
Technology:
Cost tier stratification separates capital-intensive chemical platforms from lower-barrier mechanical systems, with solvent extraction occupying the premium middle tier.
- Chemical Recycling:Methanolysis and glycolysis platforms achieve monomer-grade purity for polyester streams. Eastman Chemical Company's industrial-scale methanolysis operations are opening beverage bottle applications previously reserved for virgin resin.
- Solvent Extraction:Selective dissolution preserves mechanical properties below thermal degradation thresholds. Supercritical CO2 systems in the Netherlands and Germany are qualifying polyolefin output for thin-film applications at accelerated pace.
- Mechanical Recycling:Lower capital requirements attract feedstock competition where contamination tolerance permits.
- Thermal Depolymerization:Pyrolysis and gasification routes sacrifice molecular weight for feedstock flexibility.
Solvent extraction commands margin premium. Chemical recycling is climbing the fastest.
End User:
Customer type determines specification stringency, with automotive and food-contact packaging imposing the tightest residue and mechanical property standards.
- Packaging:EU Green Deal mandates are pulling solvent-purified resins into converter procurement portfolios. EFSA novel food approvals extend 18-24 months, delaying revenue recognition for packaging-focused investments.
- Automotive:German OEMs are co-locating dissolution infrastructure near chemical parks in Baden-Württemberg and Bavaria to secure closed-loop polypropylene feedstocks for interior components.
- Consumer Goods:Brand-owner sustainability commitments are forcing tier-n suppliers to validate chemically recycled content.
- Construction:Lower purity tolerance permits mechanical recycling competition in non-structural applications.
Packaging leads procurement volume. Automotive is gaining share fastest.
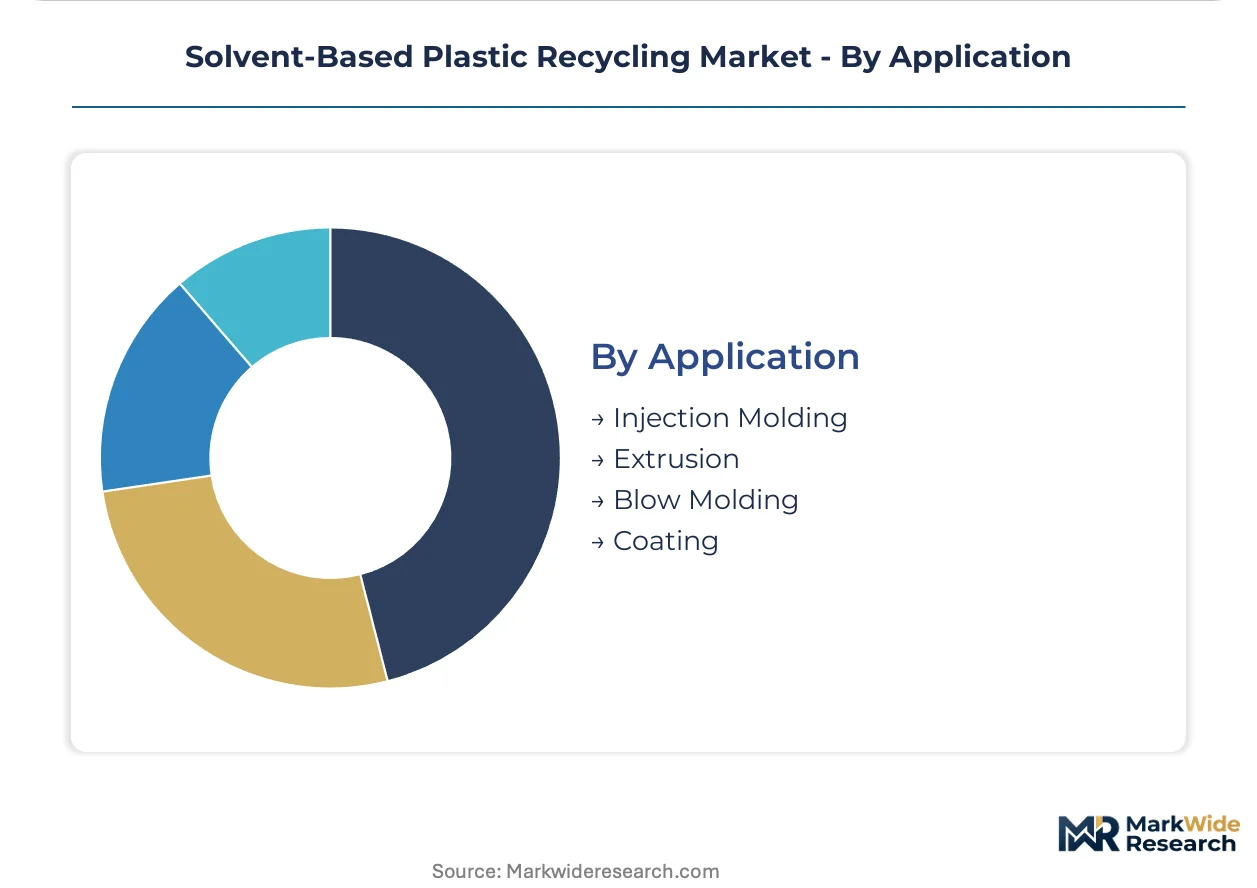
Application:
Processing method dictates viscosity and thermal stability requirements, with injection molding demanding the tightest molecular-weight distribution control.
- Injection Molding:Thin-wall packaging and automotive components require narrow polydispersity indices that dissolution-preserved resins deliver. PureCycle Technologies anchors North American production of ultra-pure recycled polypropylene for this segment.
- Extrusion:Sheet and profile applications tolerate broader molecular-weight distributions than injection grades.
- Blow Molding:Bottle and container applications are opening to methanolysis-purified polyester at food-grade specifications.
- Coating:Lower mechanical property requirements permit blended feedstock strategies.
Injection molding dominates specification premium. Blow molding is where food-contact certification concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany, where automotive OEMs and chemical clusters co-locate dissolution infrastructure, while North American project developers face single-source dependency for reactor fabrication and extended commissioning timelines.
Germany
Automotive lightweighting clusters in Baden-Württemberg and Bavaria are co-locating solvent recycling infrastructure near chemical parks to secure closed-loop polypropylene feedstocks for interior components. The EU Green Deal's packaging mandates are tightening recycled content specifications for food-contact applications. BMW and Mercedes-Benz sustainability procurement is compressing supplier qualification cycles to 8-12 months for dissolution-sourced resins.
United States
The EPA's emerging framework for advanced recycling facility permitting under the Resource Conservation and Recovery Act is reshaping project economics across state jurisdictions. FDA food-contact certification timelines extend 18-24 months for novel recycled content, delaying revenue recognition. PureCycle Technologies anchors North American production of ultra-pure recycled polypropylene from facilities in the Southeast.
Netherlands
Supercritical CO2 systems are qualifying polyolefin output for thin-film applications at accelerated pace, bifurcating margin pools between food-grade solvent-purified resins and lower-tier mechanical outputs. REACH Annex XVII amendments governing solvent residue limits are tightening pellet specifications. Packaging converters in Rotterdam and Eindhoven are consolidating procurement around tollers with in-house analytical laboratories.
India
Post-industrial polyolefin arisings from Gujarat and Maharashtra chemical zones remain largely unaddressed by dissolution infrastructure, offering first-mover feedstock access to operators willing to navigate BIS certification requirements. The country's extended producer responsibility schemes are creating preferential gate fees for chemically recycled output. Mumbai-Pune industrial corridor clusters present co-location opportunities for solvent recovery systems serving textile and automotive component manufacturers.
France
Citeo-modulated extended producer responsibility fees are creating preferential economics for solvent-recycled output versus mechanical alternatives. EFSA novel food approvals for recycled content in packaging applications are channeling capital toward food-grade solvent purification systems. Lyon and Paris Basin chemical parks are emerging as dissolution infrastructure hubs serving converter procurement portfolios.
Solvent-Based Plastic Recycling Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with proprietary purification platforms commanding premium positioning while scale operators compete on feedstock throughput. The vendor base clusters around three strategic archetypes: chemical majors with integrated methanolysis operations, pure-play dissolution specialists with patented reactor designs, and enzymatic platform developers pursuing hybrid depolymerization routes. Dominant competitive moves include capacity expansion near automotive OEM clusters and technology licensing agreements that accelerate geographic penetration without capital-heavy greenfield investments.
Within the pure-play dissolution tier, PureCycle Technologies and Ioniqa Technologies exemplify technology-first positioning anchored by proprietary reactor configurations, while Carbios occupies the enzymatic-solvent hybrid vector. Eastman Chemical Company represents the integrated chemical major archetype, leveraging existing petrochemical infrastructure to deploy methanolysis-based polyester recycling at industrial scale. These three players collectively illustrate the competitive tension between molecular preservation purity and feedstock flexibility breadth.
| Leading Market Players |
|---|
| Agilyx |
| Carbios |
| PureCycle Technologies |
| Itero Technologies |
| Aduro Clean Technologies |
| PLASTIC ENERGY Limited |
| Eastman Chemical Company |
| Clariter |
| Ioniqa Technologies |
| Others |
Cost & Logistics Intelligence
Industrial-scale dissolution reactor fabrication capacity clusters in Baden-Württemberg and Bavaria, creating scale economies that concentrate supply-side pricing power among German engineering houses while elevating price floors for North American project developers facing single-source dependency.
Pricing Analysis
Configured-to-order pricing for food-grade solvent-purified resins commands a 15-25% premium over standard mechanical recycling grades, with contract-based long-term offtake agreements dominating procurement between automotive OEMs and tolling operators. Price differentiation rests on EFSA certification status and molecular-weight preservation metrics, with REACH-compliant pellet grades capturing the highest tier. Cost compression in standard-grade polyolefin recovery is intensifying as mechanical recyclers expand flake output capacity. Packaging converters show the greatest price sensitivity, while automotive interior suppliers accept premium positioning for molecular-weight-specified homopolymer grades.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp chemical corridors and container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for polar aprotic solvent imports. Feedstock supply concentrates in Germany, the Netherlands, and the United States, with dissolution infrastructure drawing from post-industrial polyolefin arisings in Gujarat and Maharashtra chemical zones. Raw material dependencies center on acetic acid derivatives, supercritical CO2 systems, and specialized precipitation solvents. Single-source vulnerability in German reactor fabrication creates supply chain risk. Distribution runs through bulk chemical distribution networks for standard grades and direct converter relationships for certified food-contact resins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward tier-1 packaging suppliers and automotive OEMs as sustainability procurement consolidation compresses supplier qualification cycles and disintermediates traditional resin distributors.
For Market Incumbents: Shield margin position by deepening captive supply of dissolution-purified polypropylene through backward integration into feedstock preprocessing infrastructure near Baden-Württemberg chemical parks. Accelerate EFSA novel food approval investments to preempt emerging enzymatic depolymerization platforms from capturing packaging converter procurement portfolios. For New Entrants and Emerging Players: Anchor in the Mumbai-Pune industrial corridor to secure first-mover access to unaddressed post-industrial polyolefin arisings from Maharashtra chemical zones. Target automotive component manufacturers with closed-loop tolling arrangements that bypass established mechanical recycling channels. Pursue BIS certification partnerships as the primary go-to-market angle for Indian market entry. For Investors and Strategic Acquirers: Pure-play dissolution specialists with proprietary reactor configurations and established food-contact certification pipelines represent the most defensible acquisition archetype for long-term viability across the 5-10 year projection horizon. Monitor EFSA approval velocity for recycled content as the critical inflection signal for packaging-focused asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Preprocessing | Captures margin lost to mechanical recycling sortation infrastructure and secures qualified arisings for dissolution lines. |
| Food-Grade Solvent Purification System Investment | Positions tolling operators for EU Green Deal packaging mandates pulling purified resins ahead of mechanical alternatives. |
| Joint Venture with Automotive OEM Clusters | Locks in closed-loop polypropylene offtake for interior components through co-location near Bavarian chemical parks. |
| Technology Licensing for Geographic Expansion | Accelerates penetration into Indian industrial corridors without capital-heavy greenfield reactor fabrication. |
| Long-Term Supply Agreement with Brand-Owner Consortia | Secures revenue visibility as BMW and Mercedes-Benz sustainability targets force tier-n supplier validation. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with dissolution plant managers, procurement leads at packaging converters, automotive OEM sustainability officers, and REACH compliance consultants; and secondary validation through ECHA regulatory filings, EU Green Deal implementation documents, customs trade data on solvent imports, and SEC filings from publicly traded chemical recyclers. Bottom-up capacity buildout estimates triangulated against top-down demand projections from packaging and automotive end-use segments.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation dimensions spanning polymer type, technology platform, end-use industry, and regional production hub. CAGRs were derived from capacity utilization trajectories, feedstock availability curves, and regulatory implementation timelines. Industry-specific inputs included EFSA novel food approval velocity, REACH Annex XVII amendment schedules, and automotive OEM sustainability procurement cycle compression.
Material uncertainties — regulatory divergence between EPA and REACH frameworks, solvent cost volatility tied to acetic acid indices, and polymer dissolution kinetics talent scarcity — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding certification timeline standardization and feedstock quality stabilization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Waste Plastic Bricks Market
Recycled Plastics
Polyvinyl Chloride (PVC) Market
Recycled Plastics
Vietnam Recycling Market
Recycled Plastics
Germany Plastics Market
Recycled Plastics
Recyclability-Optimized Impact Modifiers for Polyolefins Market
Recycled Plastics
India Plastic Market
Recycled Plastics
Graphite Recycling Market
Recycled Plastics
Plastic Drums Market
Recycled Plastics
Engineering Plastic Recycling Market
Recycled Plastics
US Plastics Market
Recycled Plastics
Myanmar Plastics Market
Recycled Plastics
North America BPA Free Plastic Market
Recycled Plastics
Americas Plastic Sheets Market
Recycled Plastics
Plastic Compounds Market
Recycled Plastics
China Plastics Market
Recycled Plastics
Advanced-Recycled Polyolefin Resins for Consumer and Industrial Applications Market