
 Recycled Plastic and Plastic Waste to Oil Market | 2026-2036
Recycled Plastic and Plastic Waste to Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled Plastic and Plastic Waste to Oil Market Outlook
The capital-intensity divergence between large-scale pyrolysis operators and modular unit developers is unwinding competitive assumptions about minimum viable scale. Agilyx Inc. leverages its proprietary conversion platform to process mixed plastic waste streams that conventional recyclers reject. Plastic Energy anchors European project development through long-term supply contracts with petrochemical majors. Brightmark LLC dominates the North American landscape with concentrated facility investments in the US Midwest.
Recycled plastic and plastic waste to oil encompasses thermochemical processes that decompose polymer chains into synthetic crude, distillates, or monomer precursors through oxygen-starved heating at 300–800°C. Pyrolysis systems currently lead technology deployment due to lower operational complexity and compatibility with contaminated feedstocks, while catalytic conversion commands premium margins for its higher selectivity toward gasoline-range hydrocarbons. Post-consumer waste constitutes the dominant feedstock category as municipal collection infrastructure expands, though agricultural plastics represent a faster-growing input stream driven by silage film and greenhouse sheeting retirement cycles. Chemical manufacturers constitute the most concentrated end-user segment, with fuel retailers increasingly offtaking diesel and jet fuel outputs for blending pools.
EPA regulations on hazardous waste combustion and the EU Green Deal's circular economy action plan jointly shape facility permitting, emission thresholds, and product qualification for fuel markets. REACH compliance requirements for pyrolysis oil constituents determine access to European chemical manufacturing value chains. Stakeholders must monitor how carbon border adjustment mechanisms redefine the cost competitiveness of fossil-derived versus waste-derived hydrocarbons.
Market Dynamics
Chemical manufacturers' procurement departments are rewriting feedstock specifications to accept pyrolysis-derived naphtha, compressing qualification timelines from years to months and forcing technology licensors to standardize output quality.
Growth Catalysts
- EU Green Deal circular economy mandates:Binding plastic-waste reduction targets accelerate permitting for waste-to-oil facilities across member states, with Germany's Rhine corridor industrial clusters securing integrated offtake agreements.
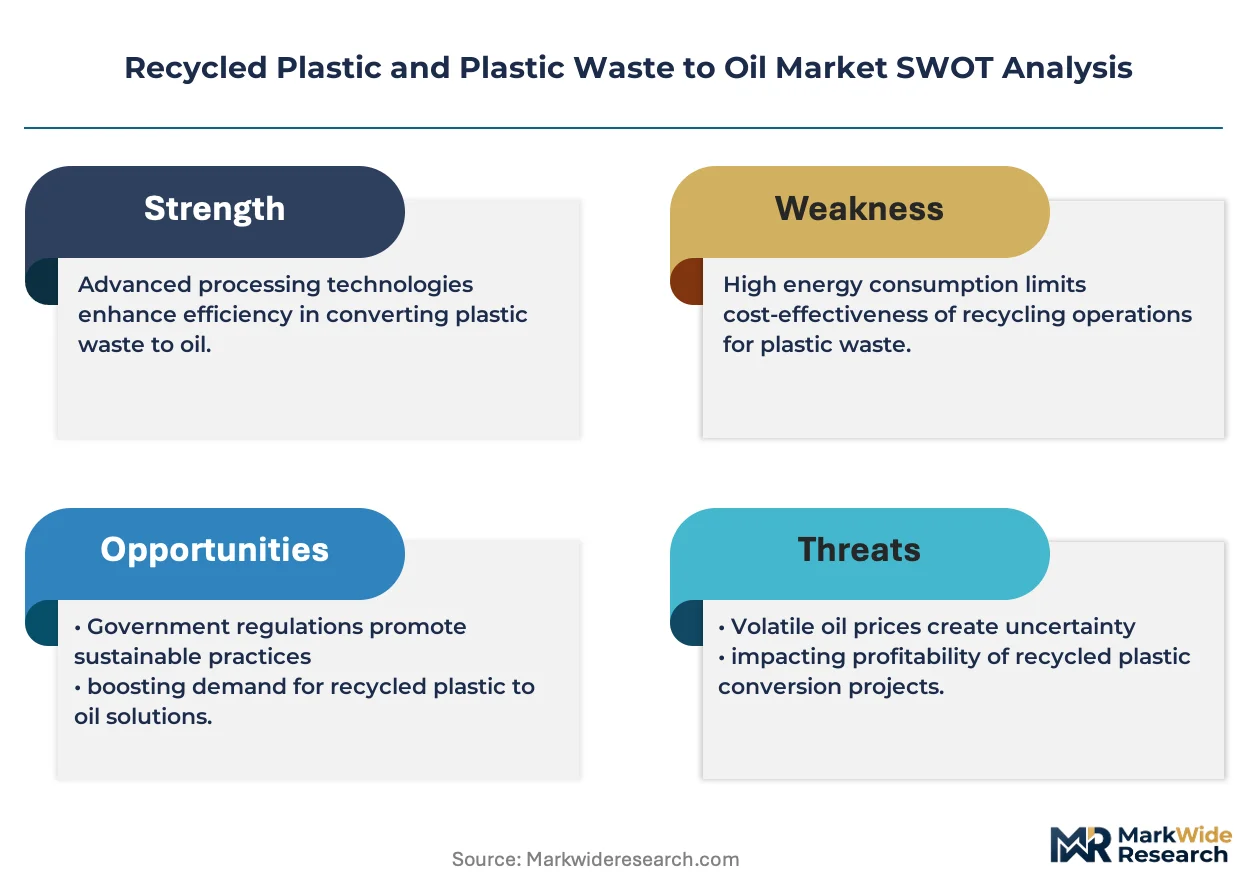
- Pyrolysis technology maturation:Oxygen-starved thermal decomposition at 300–800°C now processes contaminated mixed-plastic streams that mechanical recyclers reject, expanding addressable feedstock pools.
- Carbon border adjustment mechanisms:The EU's CBAM redefines cost competitiveness by penalizing fossil-derived hydrocarbon imports, redirecting petrochemical procurement toward waste-derived alternatives.
Market Restraints
- Feedstock cost volatility:Municipal solid waste gate fees fluctuate with landfill capacity and regional collection infrastructure gaps, compressing unit economics for operators dependent on post-consumer streams.
- Catalytic conversion capex premiums:Higher selectivity toward gasoline-range hydrocarbons requires precious-metal catalysts and reactor complexity that modular pyrolysis units cannot amortize at small scale.
- REACH compliance friction:ECHA registration requirements for pyrolysis oil constituent substances create timeline uncertainty for European chemical manufacturing value chain access.
Strategic Opportunities
- Agricultural plastics retirement cycles:Silage film and greenhouse sheeting replacement schedules in Spain and Italy generate concentrated polyethylene feedstock streams with lower contamination than municipal waste.
- Fuel retailer blending pools:Diesel and jet fuel outputs from waste-to-oil processes qualify for renewable fuel standards, opening aviation and road transport offtake channels beyond petrochemicals.
- Modular unit distributed deployment:Containerized pyrolysis systems enable on-site processing at waste generation points, reducing feedstock logistics costs for remote industrial facilities.
Industry Challenges
- Pyrolysis oil characterization expertise:Laboratories capable of analyzing complex hydrocarbon mixtures for fuel and chemical specifications remain concentrated in Germany and the Netherlands, creating bottlenecks for new market entrants.
- Legacy refinery integration:Existing petrochemical assets require retrofitting to handle oxygenated and heteroatom-containing pyrolysis streams, demanding capital coordination between waste-to-oil developers and incumbent processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled Plastic and Plastic Waste to Oil Market |
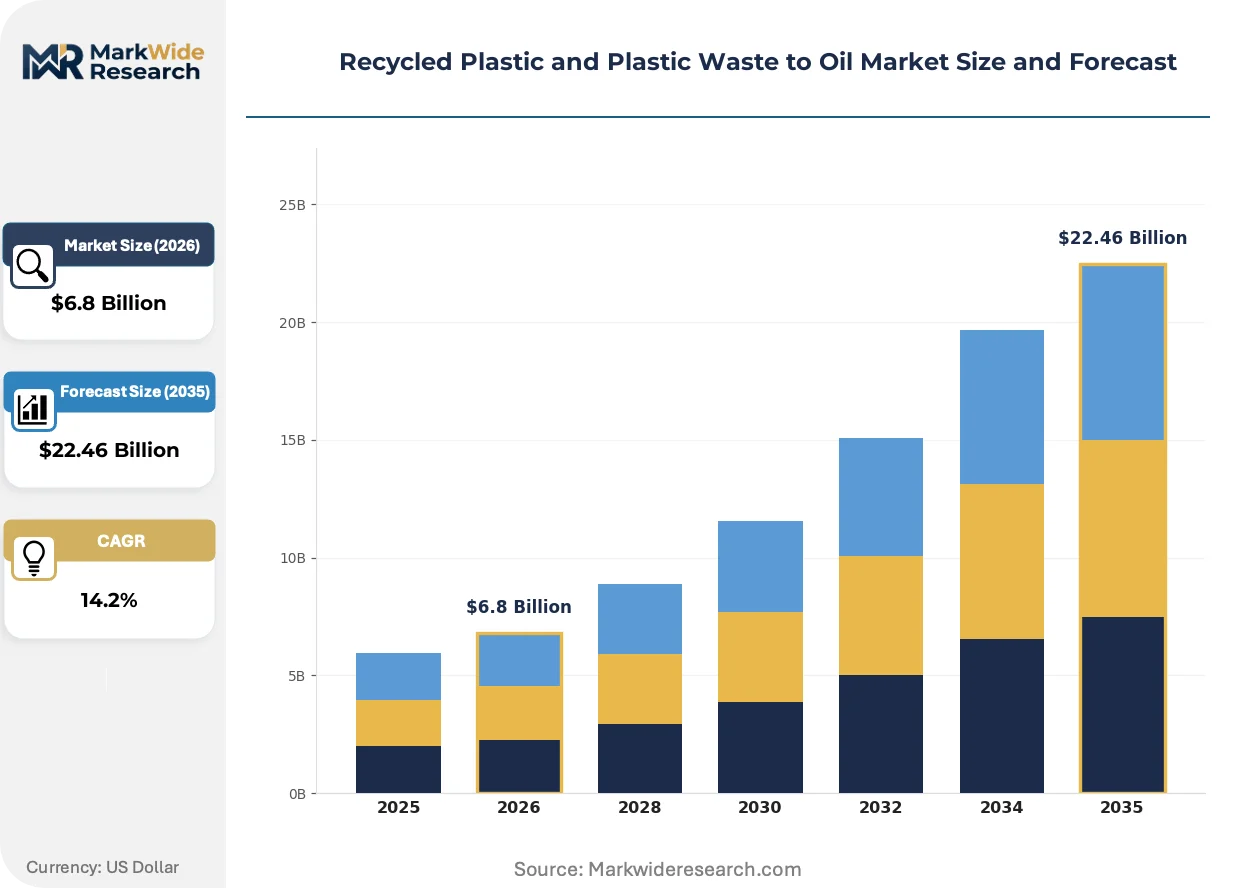
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Pyrolysis, Gasification, Depolymerization, Catalytic Conversion Feedstock Type: Post-Consumer Waste, Post-Industrial Waste, Agricultural Plastics, Others End User: Energy Producers, Chemical Manufacturers, Fuel Retailers, Recyclers Output Type: Diesel, Gasoline, Jet Fuel, Wax |
| Companies Covered | Agilyx Inc., Cynar Plc, Vadxx Energy LLC, Nexus Fuels LLC, Clean Blue Technologies Inc., Plastic2Oil Inc., RES Polyflow, Plastic Energy, Brightmark LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled Plastic and Plastic Waste to Oil Market Strategic Shifts
Technology convergence between thermal decomposition and catalytic upgrading is collapsing the historical trade-off between feedstock flexibility and product selectivity, while regulatory carbon-accounting rules reshape procurement criteria.
Catalytic pyrolysis with zeolite upgrading is supplanting standalone thermal systems in projects targeting gasoline-range aromatic outputs. Petrochemical majors in Germany and the Netherlands are deploying these integrated configurations for naphtha replacement, enabling direct substitution in steam crackers without hydrotreating steps. The structural compression of upgrading stages is reducing both capital intensity and product quality variability.
REACH registration requirements for pyrolysis oil constituents are tightening substance characterization obligations for EU market access. ECHA's evolving guidance on complex substance identification forces operators to invest in analytical capabilities and supply-chain documentation. Chemical manufacturers in Belgium and France are responding by pre-qualifying only those suppliers with complete dossier submissions, consolidating procurement pools.
Long-term supply contracts with indexed pricing are displacing spot-market transactions for pyrolysis-derived feedstocks. Petrochemical procurement teams in Germany's Rhine corridor are locking in decade-long agreements to secure volume certainty for circular-content targets. This contractual shift concentrates buyer power among integrated industrial clusters while marginalizing smaller developers lacking balance-sheet capacity for counterparty risk.
Recycled Plastic and Plastic Waste to Oil Market Segmentation
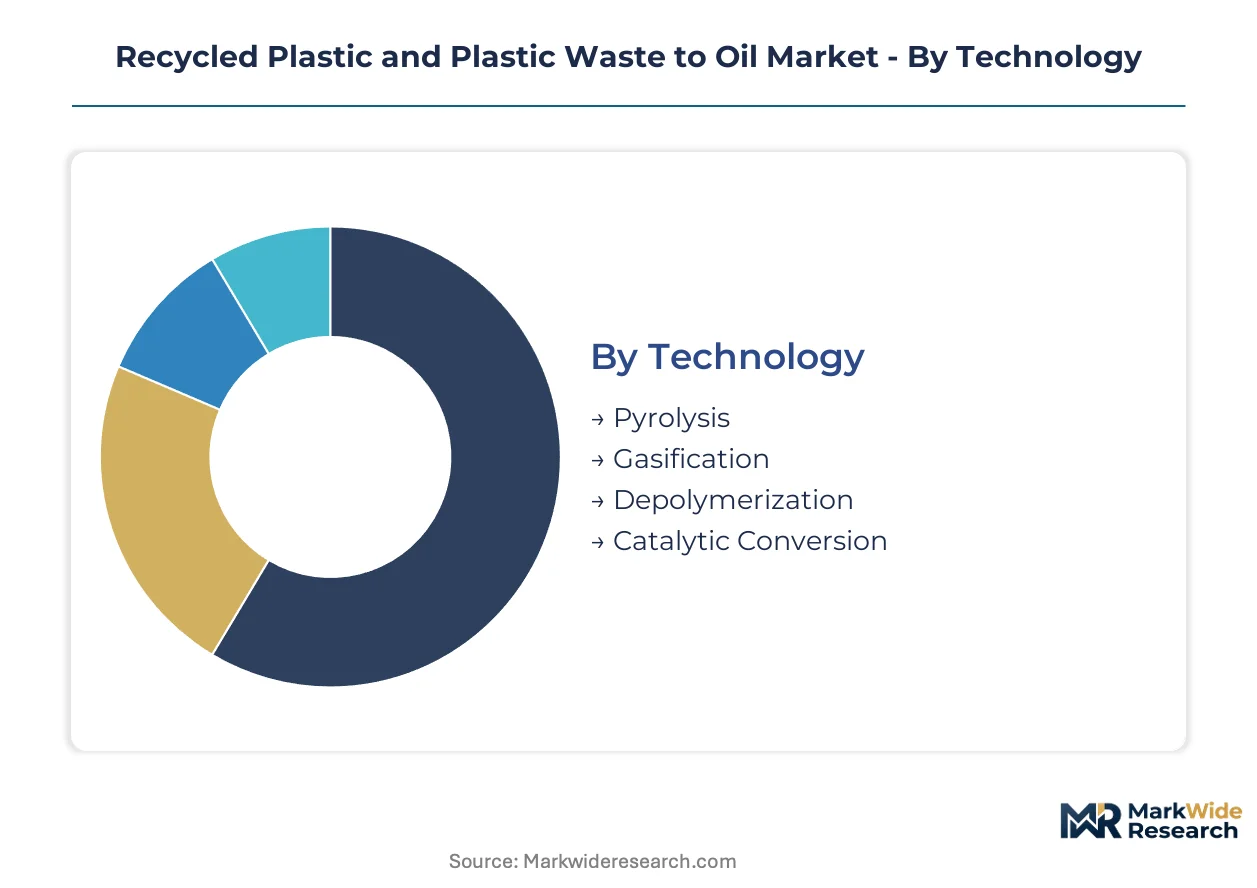
Technology choice determines capital requirements, feedstock flexibility, and product slate for waste-to-oil operators. Regulatory pathways for fuel qualification and chemical manufacturing integration vary sharply across processing configurations, making segmentation a strategic necessity rather than a descriptive exercise.
Technology:
EPA hazardous waste combustion rules and EU Green Deal emission thresholds create divergent compliance burdens across thermal and catalytic systems, reshaping project economics by geography.
- Pyrolysis:Oxygen-starved thermal decomposition at 300–800°C processes contaminated mixed-plastic streams that mechanical recyclers reject. Demand concentrates in Germany's Rhine corridor industrial clusters, where integrated offtake agreements with petrochemical majors secure volume certainty for circular-content targets.
- Catalytic Conversion:Zeolite-mediated upgrading achieves higher selectivity toward gasoline-range aromatic hydrocarbons, enabling direct naphtha substitution in steam crackers without hydrotreating. Belgium and Netherlands-based chemical manufacturers pre-qualify only suppliers with complete REACH dossier submissions, consolidating procurement pools around integrated thermal-catalytic configurations.
- Gasification:Partial oxidation at higher temperatures produces syngas for Fischer-Tropsch synthesis, requiring oxygen supply infrastructure that limits deployment to large-scale centralized facilities.
- Depolymerization:Selective polymer chain cleavage targets monomer recovery rather than fuel-range hydrocarbons, serving specialty chemical applications with tighter purity specifications.
Pyrolysis handles the majority of throughput; catalytic conversion is the fastest mover on share.
Feedstock Type:
Gate fee volatility and contamination levels stratify addressable supply pools by cost tier and collection infrastructure maturity.
- Post-Consumer Waste:Municipal solid waste streams dominate volume availability as collection infrastructure expands across member states. Fluctuating landfill capacity and regional collection gaps compress unit economics for operators dependent on these streams.
- Agricultural Plastics:Silage film and greenhouse sheeting replacement schedules in Spain and Italy generate concentrated polyethylene feedstock with lower contamination than municipal waste. EU Green Deal circular economy mandates accelerate permitting for facilities targeting these retirement cycles.
- Post-Industrial Waste:Manufacturing scrap from automotive and packaging sectors offers predictable composition and supply contracts, though volume concentrates among established waste management incumbents.
- Others:Construction debris and medical plastics require specialized preprocessing due to hazardous additive content, limiting viable processing to licensed hazardous waste facilities.
Post-consumer waste commands the largest volume position; agricultural plastics are expanding most quickly on share.
End User:
Procurement specification timelines and counterparty risk tolerance separate long-term contract markets from spot-oriented offtake channels.
- Chemical Manufacturers:Procurement departments rewrite naphtha specifications to accept pyrolysis-derived feedstocks, compressing qualification timelines from years to months and forcing technology licensors to standardize output quality for direct steam cracker integration.
- Fuel Retailers:Diesel and jet fuel outputs qualify for renewable fuel standards, opening aviation and road transport blending pools beyond petrochemical value chains. Germany's transport sector absorbs significant volumes through mandated sustainable aviation fuel quotas.
- Energy Producers:Power generation offtake remains limited by pyrolysis oil's oxygen and heteroatom content, requiring combustion system retrofits that most utilities defer.
- Recyclers:Mechanical recycling operators explore hybrid thermal-mechanical configurations to handle residues rejected by conventional sorting lines.
Chemical manufacturers anchor contract volume; fuel retailers are climbing the fastest on procurement share.
Output Type:
Product slate determines downstream market access, with fuel specifications governed by EPA and national transport agency rules while chemical feedstocks face REACH substance identification requirements.
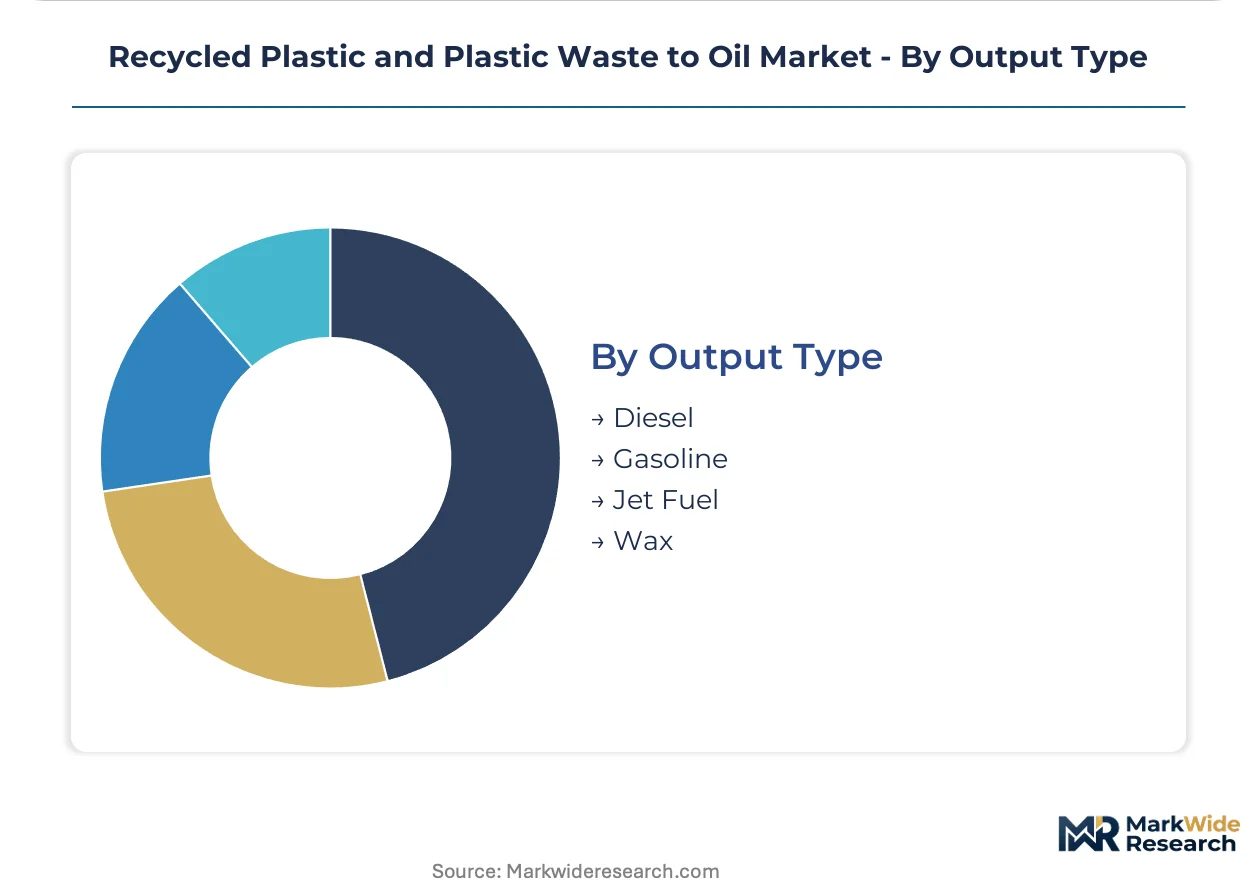
- Diesel:Middle distillate cuts meet renewable diesel specifications for road transport blending pools, with EU member state mandates driving offtake certainty.
- Gasoline:Light naphtha-range outputs require catalytic upgrading to achieve aromatic specifications for direct refinery substitution.
- Jet Fuel:Kerosene-range hydrocarbons qualify for sustainable aviation fuel certification under ICAO carbon accounting frameworks, with Germany and Netherlands leading European offtake.
- Wax:Heavy residual fractions serve specialty lubricant and coating applications with lower volume but premium pricing relative to fuel commodities.
Diesel captures the dominant output share; jet fuel is gaining share fastest on regulatory mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's Rhine corridor industrial clusters while feedstock cost volatility compresses margins for operators dependent on municipal waste streams in Southern Europe.
Germany
Integrated offtake agreements with petrochemical majors anchor demand in North Rhine-Westphalia and Hesse. The EU Green Deal's binding plastic-waste reduction targets accelerate permitting timelines for waste-to-oil facilities. BASF and Dow Chemical procurement teams in Ludwigshafen secure decade-long supply contracts with indexed pricing to meet circular-content commitments.
United States
Midwest agricultural plastics retirement cycles and concentrated petrochemical demand drive facility investments in Indiana and Ohio. EPA hazardous waste combustion rules shape emission thresholds and product qualification for fuel markets. Brightmark's concentrated facility portfolio in the US Midwest exemplifies the scale-driven deployment model.
Netherlands
Rotterdam's port infrastructure and chemical manufacturing density attract integrated thermal-catalytic configurations targeting naphtha replacement. ECHA REACH registration requirements for pyrolysis oil constituents tighten substance characterization obligations. Shell and SABIC procurement operations in the Port of Rotterdam pre-qualify suppliers with complete dossier submissions.
Spain
Silage film and greenhouse sheeting replacement schedules in Andalusia and Valencia generate concentrated polyethylene feedstock streams. EU circular economy action plan mandates accelerate permitting for facilities targeting agricultural waste. Almería's greenhouse cluster offers lower-contamination feedstock pools than municipal solid waste alternatives.
Italy
Po Valley agricultural plastics retirement and mechanical recycling residue volumes create hybrid feedstock opportunities. National sustainable aviation fuel quotas under EU transport decarbonization frameworks drive diesel and jet fuel offtake. ENI's refineries in Sannazzaro de' Burgondi pilot pyrolysis oil co-processing for renewable fuel certification.
Recycled Plastic and Plastic Waste to Oil Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with proprietary conversion platform developers commanding premium positioning while modular unit fabricators compete on deployment speed and capital efficiency. The vendor base stratifies across three tiers: integrated technology licensors with long-term supply contracts, regional project developers securing localized feedstock agreements, and equipment fabricators supplying containerized systems. Scale-driven consolidation pressures smaller developers lacking balance-sheet capacity for counterparty risk in decade-long procurement deals. Dominant competitive moves include strategic partnerships with petrochemical majors for offtake certainty and geographic expansion toward agricultural waste clusters with lower contamination profiles.
Among North American technology developers, Agilyx Inc. and Brightmark LLC occupy distinct positions within the integrated project developer archetype, while Plastic Energy anchors European development through its UK-based operations and long-term supply contract model. Nexus Fuels LLC and Cynar Plc represent the mid-scale regional developer segment focused on specific feedstock categories and localized offtake relationships.
| Leading Market Players |
|---|
| Agilyx Inc. |
| Cynar Plc |
| Vadxx Energy LLC |
| Nexus Fuels LLC |
| Clean Blue Technologies Inc. |
| Plastic2Oil Inc. |
| RES Polyflow |
| Plastic Energy |
| Brightmark LLC |
| Others |
Value Chain & Pricing Dynamics
Ninety-day feedstock inventory buffers at Rhine corridor facilities concentrate pricing power among integrated operators with captive waste supply agreements, while spot-dependent buyers absorb gate fee volatility from municipal collection gaps. Contract tenors stretching to ten years anchor cost predictability for BASF and Dow procurement teams, compressing margins for developers lacking balance-sheet depth for counterparty risk.
Pricing Analysis
The customization-premium spread separates standard pyrolysis naphtha from catalytically upgraded gasoline-range outputs qualified for direct steam cracker integration. Long-term offtake contracts with indexed pricing dominate procurement patterns, with chemical manufacturers in Germany and the Netherlands locking volume certainty for circular-content targets. Price differentiation rests on REACH dossier completeness and output consistency rather than commodity spot dynamics. Smaller modular operators face acute price sensitivity as petrochemical majors consolidate supplier pools around integrated thermal-catalytic configurations with decade-long track records.
Supply Chain Analysis
Germany and the Netherlands anchor pyrolysis oil characterization expertise and REACH-compliant chemical manufacturing integration, while Spain and Italy feed concentrated agricultural polyethylene streams from greenhouse and silage film retirement cycles. Feedstock supply draws from municipal collection infrastructure, post-industrial manufacturing scrap, and seasonal agricultural plastic replacement schedules. Single-source vulnerability concentrates in laboratory capacity for complex hydrocarbon analysis, with capable facilities clustered in North Rhine-Westphalia and Rotterdam. Distribution runs through Rhine corridor industrial clusters with integrated offtake agreements, bypassing spot-market intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is recovering from feedstock cost volatility cycles as EU Green Deal mandates institutionalize waste-derived hydrocarbon procurement, with agricultural plastic retirement schedules providing counter-cyclical volume stability.
For Market Incumbents: Compound technology leadership in catalytic upgrading configurations that achieve direct naphtha substitution without hydrotreating, while securing backward integration into agricultural waste collection networks in Spain and Italy to escape municipal gate fee compression. Defend procurement relationships by completing REACH dossier submissions ahead of ECHA guidance tightening, as Belgian and French chemical manufacturers pre-qualify only suppliers with full substance characterization. For New Entrants and Emerging Players: Modular containerized pyrolysis service gaps at remote industrial facilities offer white-space entry where logistics costs exclude large-scale competitors, particularly in Midwest agricultural processing clusters and Mediterranean greenhouse regions. Target post-industrial manufacturing scrap from automotive and packaging sectors with predictable composition and lower contamination than municipal streams. Pursue joint development agreements with waste management incumbents holding captive feedstock access rather than greenfield collection infrastructure buildout. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded pyrolysis technology assets lacking capital for REACH compliance investment and long-term contract underwriting. Five-to-ten year viability hinges on carbon border adjustment mechanism expansion beyond pilot phases, with waste-derived hydrocarbon cost competitiveness improving as fossil import penalties mature. Monitor ECHA guidance publication timelines as inflection signals for supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Collection | Captive supply of agricultural plastics from Spain's Almería greenhouse cluster insulates against municipal gate fee volatility. |
| Catalytic Upgrading Capacity Expansion | Zeolite-mediated configurations in Rotterdam's Port enable direct naphtha substitution for Shell and SABIC steam crackers. |
| REACH Dossier Completion Program | Full substance characterization unlocks BASF and Dow procurement pre-qualification in Germany's Rhine corridor. |
| Long-term Supply Agreement Structuring | Decade-long indexed contracts with petrochemical majors secure volume certainty for circular-content commitments. |
| Modular Unit Geographic Deployment | Containerized systems at Indiana and Ohio agricultural processing sites reduce feedstock logistics costs for Brightmark. |
Study Parameters
The analysis maps pyrolysis technology licensors, catalytic upgrading system developers, and modular unit fabricators, each validated through procurement directors at petrochemical majors, waste management facility operators, and ECHA regulatory affairs specialists. Primary interviews with plant managers at Rhine corridor installations, downstream chemical manufacturing R&D leads, and agricultural plastics collection coordinators combined with secondary validation from EU Green Deal implementation reports, ECHA substance registration databases, and customs trade data tracking pyrolysis oil cross-border flows. Bottom-up facility capacity builds and top-down chemical feedstock demand estimates underwent triangulation against petrochemical industry circular-content target disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with modeled segmentation spanning technology configuration, feedstock contamination tier, end-user qualification requirements, and regional regulatory framework clusters. CAGRs derived from facility deployment pipelines, offtake contract tenors, and feedstock availability projections. Industry-specific forecast inputs incorporated REACH registration timeline assumptions and carbon border adjustment mechanism phase-in schedules.
Forecasts assume regulatory continuity in EU Green Deal implementation and ECHA substance identification frameworks; material policy shifts would require re-modeling. Specific risks that could revise projections include pyrolysis oil reclassification under hazardous waste rules, feedstock competition from mechanical recycling capacity expansion, and petrochemical demand destruction from alternative circular feedstock commercialization. Recalibration cycles align with material shifts in ECHA guidance, CBAM expansion decisions, and major offtake contract renegotiation windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
South Korea Recycled Plastics Market
Recycled Plastics
Non-Ferrous Scrap Recycling Market
Recycled Plastics
North America BPA Free Plastic Market
Recycled Plastics
Post-Consumer Recycled Plastics in Consumer Electronics Market
Recycled Plastics
India Plastic Market
Recycled Plastics
Modified Polypropylene Market
Recycled Plastics
Malaysia Plastics Market
Recycled Plastics
Vietnam Recycling Market
Recycled Plastics
Aluminum Recycling Market
Recycled Plastics
Germany Plastics Market
Recycled Plastics
Indonesia Plastics Market
Recycled Plastics
Global Construction Plastics Market
Recycled Plastics
Saudi Arabia Plastic Components Market
Recycled Plastics
Recyclability-Optimized Impact Modifiers for Polyolefins Market
Recycled Plastics
US Plastics Market
Recycled Plastics
Global Post-Consumer Recycled Plastics Market