
 China Plastics Market | 2026-2036
China Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
China Plastics Market Intelligence
Custom compounding services for application-specific polymer grades is expanding the definition of value beyond simple resin sales. State-owned enterprises like Sinopec and PetroChina leverage immense production scale to control commodity polymer segments. In contrast, specialized firms such as Kingfa compete on modified and high-performance plastics for demanding applications like automotive and electronics. Formosa Plastics Group sustains its market position through a diversified portfolio spanning multiple polymer types.
Plastics are a category of synthetic materials derived from polymers, often combined with additives to enhance specific properties like strength or flexibility. These materials are processed using methods such as injection molding or extrusion to create solid objects for countless applications. Polyethylene and Polypropylene dominate volume due to their extensive use in packaging. However, engineering plastics like Polycarbonate and Acrylonitrile Butadiene Styrene represent higher-margin opportunities in automotive components and electronics.
The State Administration for Market Regulation (SAMR) enforces national GB standards for plastic products, impacting material specifications for food contact and safety. Concurrently, China's 'dual carbon' goals are creating mandates for increased recycled content and bio-polymer development. Navigating the evolving regulatory landscape for sustainability and material circularity is now a central strategic challenge for all producers operating within the country.
Market Dynamics
The central dynamic shaping China's plastics market is the state-driven mandate for industrial decarbonization. China's 'dual carbon' goals are forcing a systemic re-evaluation of material lifecycles, from feedstock sourcing to end-of-life management, impacting all polymer producers.
Growth Catalysts
- Automotive Lightweighting:Sustained demand from China's vast automotive industry for lightweight plastics to improve fuel efficiency and extend the range of electric vehicles acts as a primary growth engine.
- National Sustainability Policies:China's 'dual carbon' strategy and related GB standards are creating a regulated market for recycled polymers and bio-based plastics, particularly in packaging and consumer goods.
- Manufacturing Cluster Concentration:The high density of advanced manufacturing in zones like the Pearl River Delta and Yangtze River Delta creates concentrated pockets of demand for specialized and high-performance polymers.
Market Restraints
- Feedstock Price Volatility:The industry's heavy reliance on petrochemical feedstocks like naphtha exposes producers to significant margin pressure from fluctuations in global crude oil prices.
- Commodity Market Dominance:The immense scale of state-owned enterprises creates intense price competition in commodity segments like polyethylene and polypropylene, limiting profitability for smaller, non-specialized firms.
- Technical Gaps in High-Performance Grades:Despite a large production base, China still relies on imports for certain ultra-high-performance polymers, indicating a domestic technology and production gap for the most demanding applications.
Strategic Opportunities
- Medical-Grade Polymers:Expansion of the domestic healthcare industry creates an opportunity for developing and supplying high-purity, medical-grade plastics compliant with stringent NMPA regulations for devices and disposables.
- Biodegradable Agricultural Films:Government focus on soil health and agricultural pollution provides a significant opening for biodegradable mulch films and other polymer-based agricultural products.
- Advanced Compounding:There is a growing opportunity for custom compounding services that develop application-specific polymer formulations for high-value sectors like 5G infrastructure and advanced electronics.
Industry Challenges
- Recyclate Quality and Consistency:A key operational challenge is securing a stable supply of high-quality post-consumer recyclate (PCR) needed to meet recycled-content mandates without compromising final product performance.
- Complex Regulatory Compliance:Producers face the challenge of continuously adapting to evolving GB standards enforced by the SAMR, which requires significant investment in testing and certification processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Plastics Market |
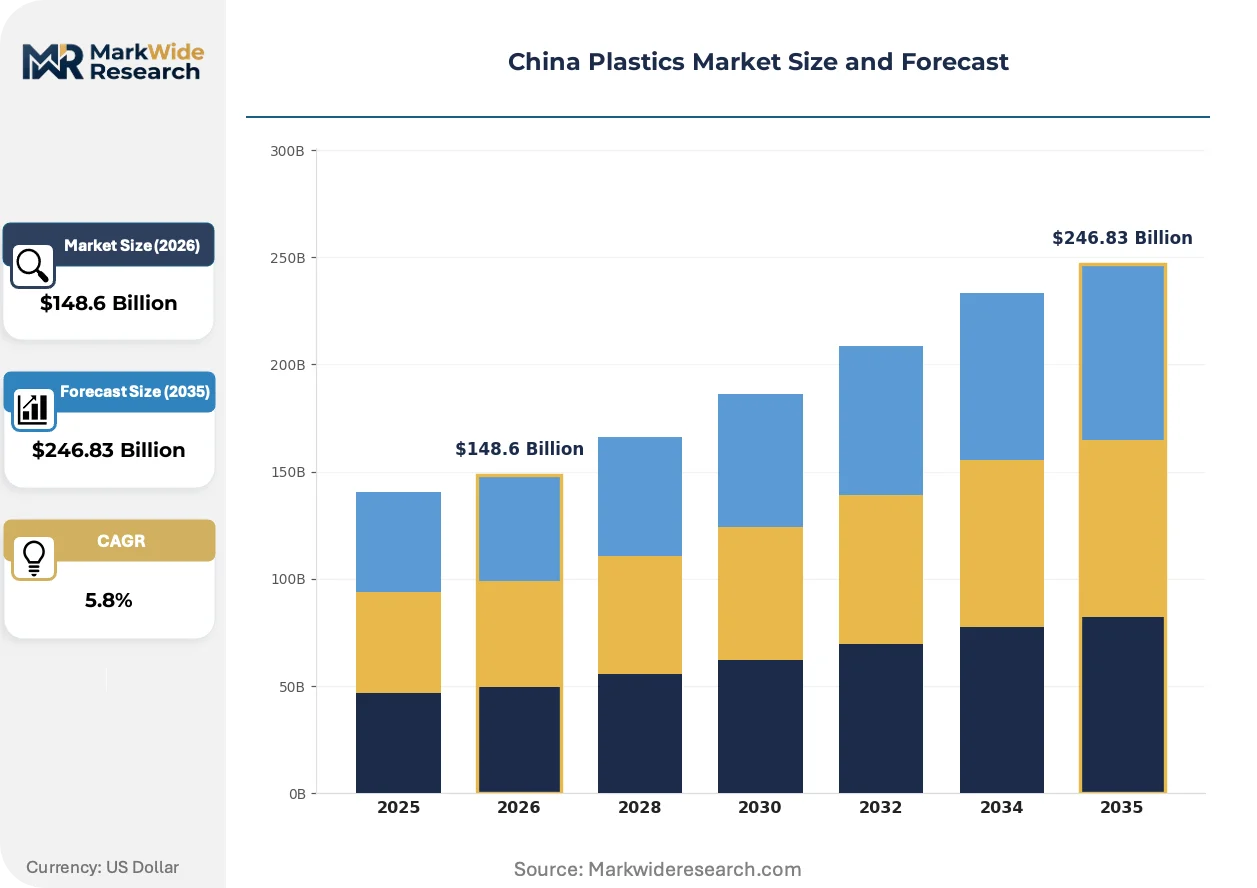
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $246.83 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene, Polycarbonate, Acrylonitrile Butadiene Styrene Application: Packaging, Construction Materials, Automotive Components, Electrical & Electronics, Consumer Goods, Agriculture Films Processing Technology: Injection Molding, Blow Molding, Extrusion, Thermoforming, Rotational Molding, Compression Molding End User Industry: Building & Construction, Vehicle Manufacturing, Electronics Assembly, Consumer Appliances, Agricultural Sector, Textile Production |
| Companies Covered | Chi Mei, ShengMei Precision Industrial (KunShan) Co., Ltd., Sinopec, Tangyin Xinxing Plastics Engineering Co., Ltd., Chi Cheng Enterprise Co., Ltd., PetroChina, Formosa Plastics Group, Polyreflex Hi-Tech Co., Ltd., Kingfa, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Plastics Market Strategic Shifts & Innovations
The market is undergoing a fundamental shift from a volume-centric model to one emphasizing material circularity and value-added specialization. This transition is driven by a combination of stringent national environmental policies and the sophisticated demands of China's advanced manufacturing base.
Bio-based polymers, derived from renewable feedstocks like starch and cellulose, offer a sustainable alternative to conventional fossil-fuel-based plastics. The domestic food packaging and consumer electronics sectors are accelerating their adoption to meet both regulatory pressure and consumer preferences for greener products. This sustainable material science is converging with digital fabrication, enabling the production of customized, biodegradable components through processes like 3D printing.
China's national 'dual carbon' policy framework creates binding targets for reducing industrial emissions and enhancing resource efficiency. This top-down directive, overseen by bodies like the MEE, forces a strategic pivot toward circular economy principles across the polymer value chain. The construction and automotive industries are most affected, responding by redesigning components for recyclability and investing in closed-loop collection systems to meet future GB standards.
A significant behavioral change is evident as industrial buyers prioritize lifecycle performance and sustainability metrics over upfront material cost. This trend is disrupting traditional procurement, which was often based on simple price comparisons for commodity resins, and replacing it with collaborative, application-specific development partnerships. This shift is most visible within the export-oriented electronics and appliance manufacturing clusters in the Guangdong province.
China Plastics Market Segmentation
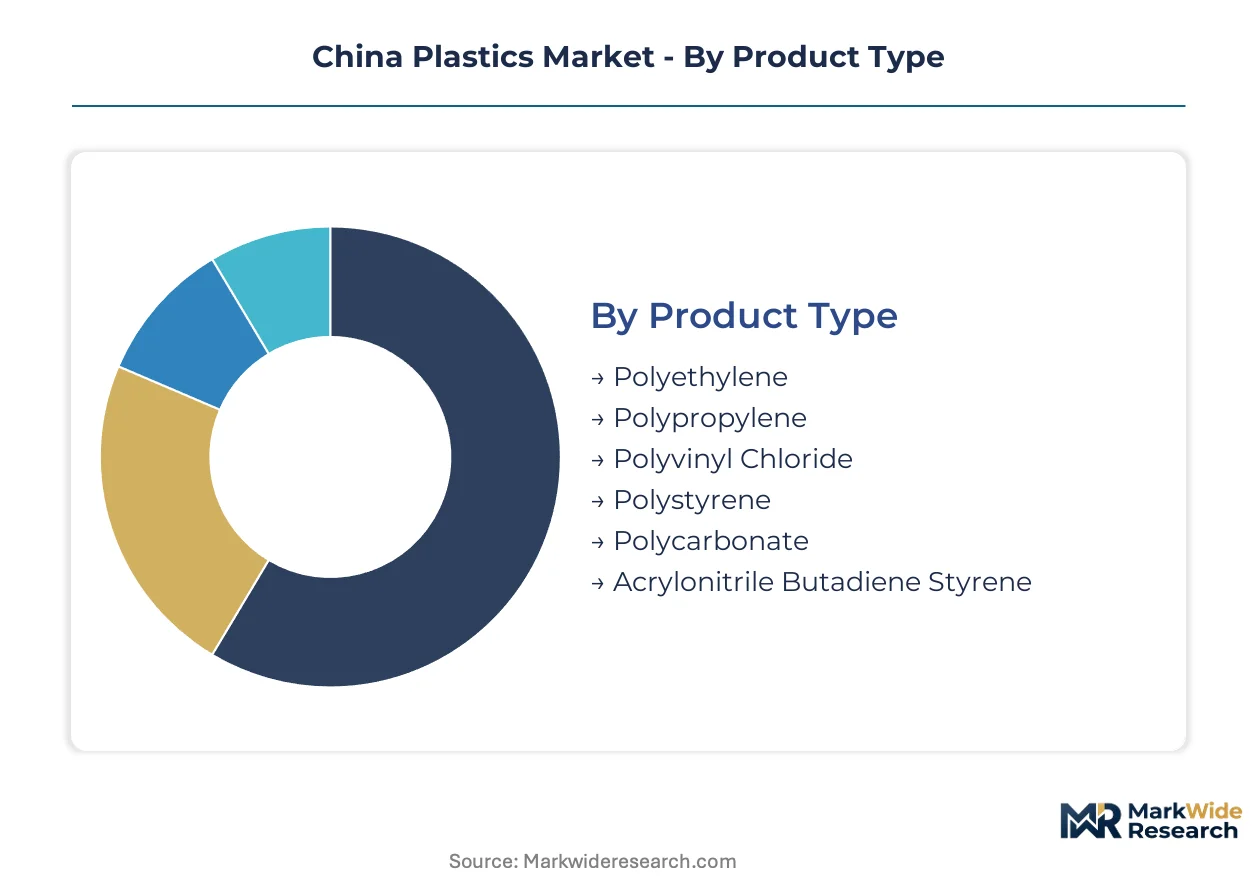
The China Plastics Market is highly diversified, with segmentation providing critical insights into material selection, application-specific demands, and the underlying processing technologies that shape product outcomes. Understanding these distinct segments helps producers align their offerings with specific industrial requirements and evolving regulatory mandates within the country.
Product Type:
The market for plastics in China is defined by the technical specifications and performance characteristics of various polymer grades, each serving distinct functional purposes across industries.
- Polyethylene:A thermoplastic polymer known for its high ductility and low cost, widely used in films, containers, and pipes. Demand concentrates in food and beverage packaging, driven by its moisture barrier properties and ease of processing in China.
- Polypropylene:A versatile thermoplastic polymer offering good chemical resistance and high stiffness, utilized in automotive parts and consumer goods. Its demand from the automotive sector is sustained by the push for lightweighting initiatives in vehicle manufacturing across China.
- Polyvinyl Chloride:A rigid or flexible polymer with excellent chemical resistance, primarily used in construction pipes and window profiles within China.
- Polystyrene:A rigid, transparent thermoplastic, finding applications in disposable packaging and insulation due to its low cost and ease of processing.
- Polycarbonate:A transparent, high-impact resistant engineering thermoplastic, critical for electronics housings and optical media components.
- Acrylonitrile Butadiene Styrene:An opaque thermoplastic polymer known for its strength and impact resistance, used in appliance casings and automotive interiors.
Polyethylene leads on scale; Polypropylene leads on momentum.
Application:
End-use applications dictate specific material requirements, influencing polymer selection and processing methods across diverse industries within China's economy.
- Packaging:Utilizes plastics for protective films, rigid containers, and flexible pouches, crucial for product preservation and transport. Demand in China's Pearl River Delta manufacturing clusters is driven by the vast export-oriented consumer goods sector.
- Automotive Components:Integrates plastics for interior parts, exterior body panels, and under-the-hood components to reduce vehicle weight. The nation's expansive vehicle manufacturing sector, particularly for electric vehicles, drives this segment's material consumption.
- Construction Materials:Employs plastics in pipes, window frames, and insulation, benefiting from durability and corrosion resistance in Chinese infrastructure projects.
- Electrical & Electronics:Uses plastics for insulating components, device housings, and wire coatings, supporting China's advanced electronics production capabilities.
- Consumer Goods:Incorporates plastics into household items, toys, and sports equipment due to versatility and cost-effectiveness for the domestic market.
- Agriculture Films:Applies plastics for greenhouse covers, mulch films, and irrigation tubing, enhancing crop yields and water management in China's agricultural sector.
Packaging represents the largest volume segment; Automotive Components expands most quickly.
Processing Technology:
The choice of manufacturing process is critical for shaping plastic resins into functional products, impacting efficiency and final part properties for Chinese manufacturers.
- Injection Molding:A high-volume manufacturing process for producing complex plastic parts by injecting molten material into a mold. This technology is indispensable for consumer electronics and automotive components in China's advanced manufacturing hubs.
- Extrusion:A continuous process pushing molten plastic through a die to create objects of a fixed cross-sectional profile, such as pipes, films, and sheets. Demand from construction and packaging sectors in China relies heavily on this cost-efficient method.
- Blow Molding:Utilized for creating hollow plastic objects like bottles and containers, particularly for packaging applications in China.
- Thermoforming:Involves heating a plastic sheet and forming it over a mold, commonly used for trays and packaging inserts within Chinese manufacturing.
- Rotational Molding:A process for producing large, hollow, seamless plastic products like tanks and industrial containers for various sectors.
- Compression Molding:Forms plastic parts by compressing a preheated material within a mold, suitable for high-strength components in specialized applications.
Injection Molding maintains the largest installed base; Extrusion continues gaining share fastest across industrial applications.
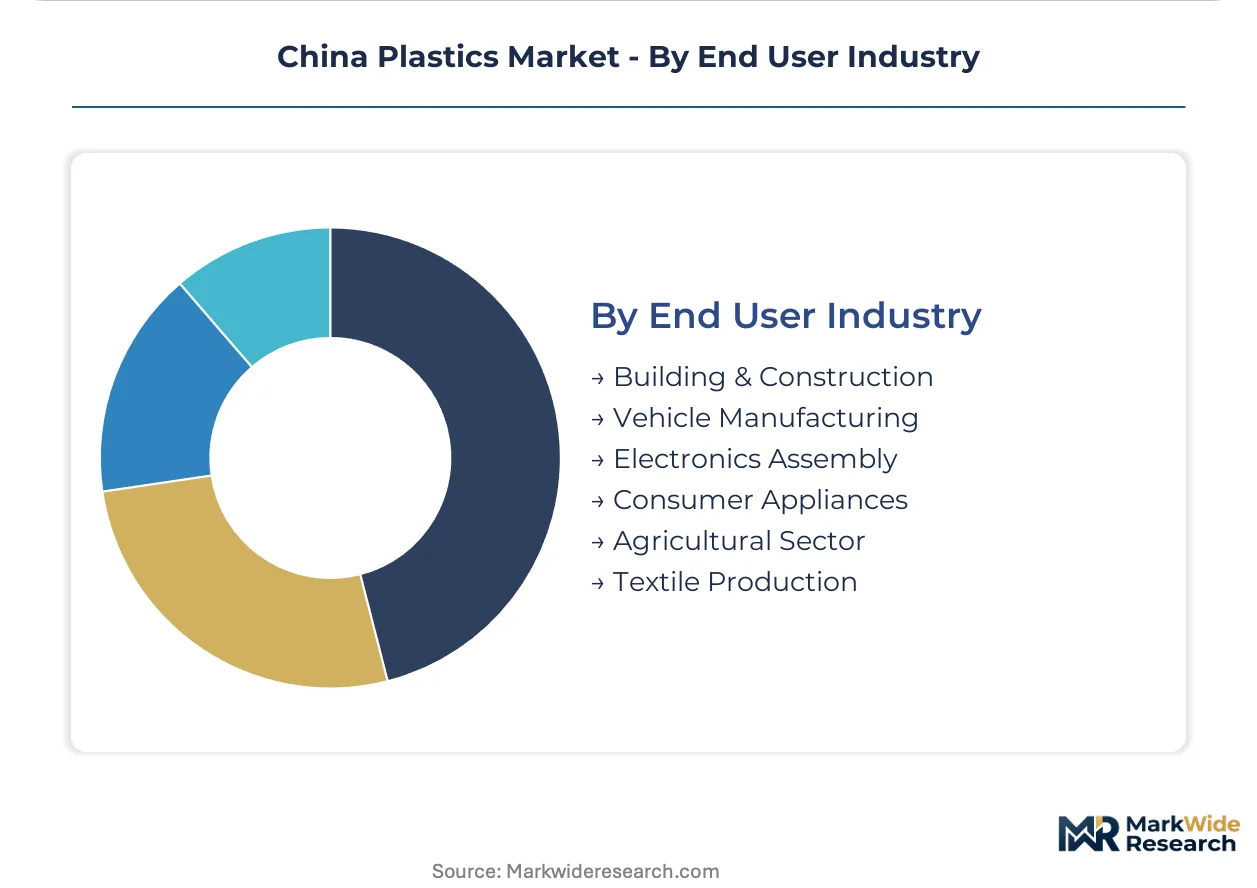
End User Industry:
Specific industry requirements drive demand for tailored plastic solutions, reflecting varying performance needs and regulatory landscapes across China's diverse economy.
- Vehicle Manufacturing:This industry consumes a wide array of plastics for lightweighting, safety, and interior aesthetics in both traditional and electric vehicles. China's sustained growth in automotive production directly fuels demand for specialized polymers.
- Building & Construction:Utilizes plastics for durability, insulation, and corrosion resistance in infrastructure, residential, and commercial projects. National GB standards for material performance and sustainability mandates influence product selection in this sector.
- Electronics Assembly:Requires high-performance plastics for insulation, heat dissipation, and protective enclosures in consumer and industrial electronics production.
- Consumer Appliances:Incorporates plastics for housings, internal components, and aesthetic finishes in white goods and small appliances for the domestic market.
- Agricultural Sector:Employs plastics for irrigation systems, protective films, and storage solutions to improve farming efficiency and output.
- Textile Production:Uses synthetic fibers like polyester and nylon, derived from plastics, for apparel and industrial textiles manufactured in China.
Vehicle Manufacturing represents the fastest-growing trajectory in plastic consumption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While the Pearl River Delta drives plastics demand through export-oriented manufacturing, the Yangtze River Delta sees significant growth from its automotive and electronics sectors. China's national 'dual carbon' goals influence material choices across all regions. These distinct regional economic profiles shape localized polymer consumption patterns.
Pearl River Delta
The Pearl River Delta region drives plastics consumption through its vast export-oriented consumer goods and electronics manufacturing. GB standards for product safety and material specifications directly influence polymer selection here. Guangdong province's manufacturing clusters, particularly around Shenzhen and Dongguan, require high volumes of specialized plastics for packaging and device housings.
Yangtze River Delta
Shanghai and its surrounding areas within the Yangtze River Delta exhibit strong demand for engineering plastics in automotive and advanced electronics production. China's 'dual carbon' goals mandate increased recycled content, particularly for packaging and automotive applications in this region. Advanced manufacturing hubs across Jiangsu and Zhejiang provinces are investing in high-performance polymer solutions.
Beijing-Tianjin-Hebei
Northern China's Beijing-Tianjin-Hebei cluster generates demand from large-scale infrastructure projects and construction materials. MEE directives on industrial emissions and resource efficiency influence the adoption of sustainable plastics in this metropolitan area. State-led initiatives in Tianjin and Hebei cities prioritize durable and environmentally compliant polymer solutions for urban development.
Sichuan-Chongqing
Western China's Sichuan-Chongqing economic zone experiences rising plastics demand from its expanding automotive production and consumer goods sectors. Local environmental protection policies encourage the use of lighter and more recyclable materials across its industrial base. Chengdu and Chongqing cities are becoming significant manufacturing centers for automotive interiors and electronic device components.
China Plastics Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the China plastics market. The landscape features a tiered structure, from immense state-owned enterprises dominating commodity polymers to specialized firms focused on high-performance grades. Strategic archetypes include large-scale commodity producers, niche high-performance compounders, and diversified polymer suppliers. Capacity expansion and portfolio diversification are common competitive moves among these players.
At the scale-driven end, state-owned enterprises like Sinopec and PetroChina represent the commodity polymer segment, leveraging immense production capabilities in basic resins. Specialized firms such as Kingfa exemplify the focus on modified and high-performance plastics, targeting demanding applications within the automotive and electronics industries. Formosa Plastics Group, with its diversified portfolio, occupies a position across multiple polymer types, sustaining its market standing through broad product offerings and integrated operations. These players collectively shape the market's competitive dynamics.
| Leading Market Players |
|---|
| Chi Mei |
| ShengMei Precision Industrial (KunShan) Co., Ltd. |
| Sinopec |
| Tangyin Xinxing Plastics Engineering Co., Ltd. |
| Chi Cheng Enterprise Co., Ltd. |
| PetroChina |
| Formosa Plastics Group |
| Polyreflex Hi-Tech Co., Ltd. |
| Kingfa |
Cost & Logistics Intelligence
China's 'dual carbon' goals are forcing a systemic re-evaluation of material lifecycles, impacting all polymer producers. This regulatory pressure shifts procurement priorities towards sustainable plastics, influencing pricing models across the value chain.
Pricing Analysis
Capacity additions in China are reshaping price floors within commodity polymer segments. Pricing largely follows a commodity spot model for basic resins, while specialized engineering plastics often utilize contract-based long-term offtake agreements. Price differentiation stems from GB standard compliance and the level of custom compounding required for demanding applications. Pricing pressure stems from the immense production scale of state-owned enterprises, making packaging and consumer goods producers highly price-sensitive compared to less sensitive automotive and electronics manufacturers.
Supply Chain Analysis
Regional distribution centers, particularly within the Pearl River Delta and Yangtze River Delta, form the core of China's plastics supply chain. Supply concentration is anchored within China for most polymer types, though specialized grades source from international suppliers. The industry relies heavily on petrochemical feedstocks like naphtha and ethylene, exposing producers to significant margin pressure from global crude oil price fluctuations. Downstream distribution primarily occurs through direct sales to large industrial buyers and a network of regional distributors serving smaller manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China Plastics Market offers significant margin expansion opportunities through a strategic pivot towards high-performance and specialty polymer grades. This shift is driven by advanced manufacturing demands and national sustainability mandates, moving value beyond basic resin sales.
For Market Incumbents: Anticipate sustained pressure from commodity market dominance by state-owned enterprises like Sinopec. Incumbents should invest significantly in R&D for bio-based and recycled polymers to meet 'dual carbon' goals and evolving GB standards. Expanding custom compounding services for high-value applications like automotive and electronics provides a crucial lever for differentiation. Deepening vertical integration into specialized end-use applications can also mitigate margin erosion from basic resin sales.
For New Entrants and Emerging Players: Advanced material science for custom compounding creates a technology-first wedge for new entrants in China's plastics market. Target white-space opportunities in medical-grade polymers compliant with NMPA regulations and biodegradable agricultural films. The most penetrable segment lies in specialized, high-performance applications for electronics and automotive components. A collaborative development approach with advanced manufacturing clusters in the Yangtze River Delta offers a strong go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized firms focused on high-performance and sustainable polymer solutions within China. Long-term viability in this market is driven by national decarbonization mandates and the sophisticated demands of advanced manufacturing. Acquisition targets should prioritize agile custom compounders with strong R&D in bio-based or recycled content. The signal to watch is the increasing investment in closed-loop material collection systems and advanced recyclate processing technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases domestic supply of high-performance polymers for advanced manufacturing in China. |
| Green Manufacturing Transition | Aligns production processes with China's 'dual carbon' goals and MEE environmental directives. |
| Long-term Supply Agreement | Secures stable feedstock supply, mitigating price volatility for polymer producers. |
| Acquisition of Specialist Firm | Integrates advanced compounding capabilities for niche applications like medical devices. |
| Product Launch | Introduces new bio-based packaging solutions to meet consumer and regulatory demand. |
Research Approach
Direct dialogue with polymer R&D directors, automotive procurement managers, and packaging industry executives provided crucial primary insights. These conversations were validated through secondary research, including GB standards documents, MEE reports, and industry association data. A bottom-up approach to market sizing, combined with top-down validation, ensured comprehensive data triangulation. This methodology integrates perspectives from across China's polymer value chain.
A bottom-up analytical framework projected market growth across the analysis window. Segmentation dimensions modeled included product type, application, processing technology, end-user industry, and regional consumption patterns. Compound Annual Growth Rates were derived from historical trends and projected demand shifts influenced by national policies. Key industry-specific forecast inputs included China's vehicle production forecasts and infrastructure development spending.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical shifts and raw material price volatility. These forecasts reflect a specific set of assumptions regarding China's economic trajectory and regulatory enforcement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
US Recycled Plastics Market
Recycled Plastics
Recycled PET Flakes Market
Recycled Plastics
Japan Recycled Plastics Market
Recycled Plastics
Vietnam Plastics Market
Recycled Plastics
Recycled Plastic and Plastic Waste to Oil Market
Recycled Plastics
USA Plastic-To-Fuel Market
Recycled Plastics
Modified Polypropylene Market
Recycled Plastics
BPA Free Plastic Market
Recycled Plastics
Polyvinyl Chloride (PVC) Market
Recycled Plastics
Plastic Recycling Market
Recycled Plastics
Plastic Drums Market
Recycled Plastics
Plastics-To-Fuel (PTF) Market
Recycled Plastics
Global Recycled Asphalt Market
Recycled Plastics
Americas Plastic Sheets Market
Recycled Plastics
Global Recycled PET (R-PET) Bottles Market
Recycled Plastics
Plastic Ignition Holders Market