
 Polyvinyl Alcohol Resins Market | 2026-2036
Polyvinyl Alcohol Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Polyvinyl Alcohol Resins Market Analytics
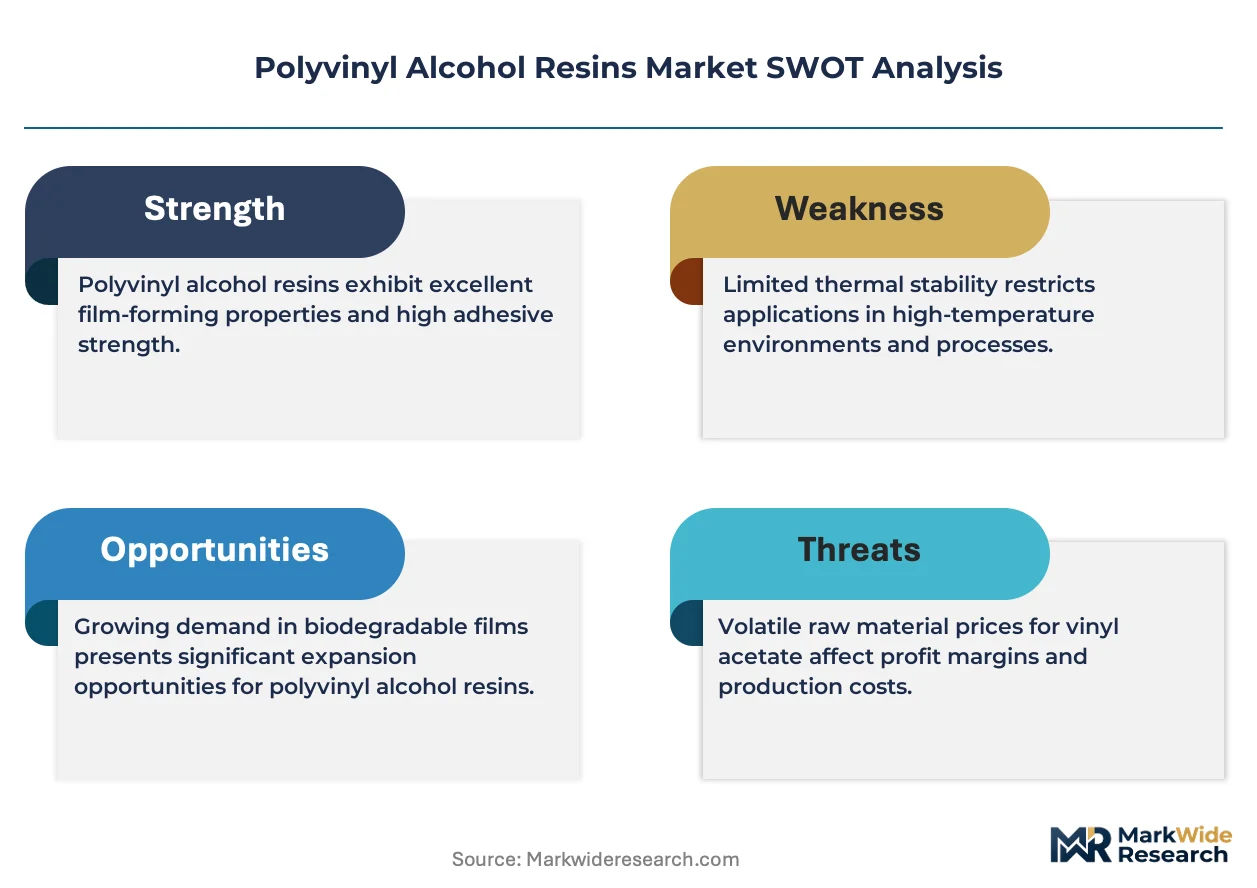
REACH registration requirements for polymer imports into Europe is broadening the cost-of-entry calculus for Asian exporters. Kuraray Co., Ltd. leverages captive vinyl acetate supply chains to sustain margin stability across hydrolysis grades. Anhui Wanwei Group Co., Ltd. anchors its position through backward integration into carbide-based acetylene chemistry. Chang Chun Group differentiates via specialty copolymer lines serving optical and electronic film niches.
Polyvinyl alcohol resins are synthetic water-soluble polymers manufactured through alkaline alcoholysis of polyvinyl acetate, with hydrolysis degrees ranging from approximately 80% to over 99% determining solubility profiles and crystallinity. These resins function primarily as film-forming agents, binders, and emulsion stabilizers across packaging, textile, and adhesive systems where dispersibility and tensile strength govern performance. Fully hydrolyzed PVOH commands premium positioning in barrier coating applications for food packaging where oxygen transmission rates must remain minimal. Partially hydrolyzed grades occupy volume-driven segments in paper sizing and textile warp sizing where cost efficiency outweighs ultimate barrier performance. PVOH copolymers represent the fastest-expanding structural category as ethylene-modified variants unlock thermoplastic processing compatibility previously unattainable with conventional grades.
EPA industrial chemical reporting under TSCA Section 8 and China's MEE pollutant discharge standards for vinylon manufacturing constrain capacity expansion timelines and capital deployment. Japan's METI enforces JIS K 6726 quality benchmarks that govern film tensile strength and dissolution kinetics for pharmaceutical and agricultural applications. Stakeholders must monitor evolving biodegradability certification protocols across multiple jurisdictions to anticipate which hydrolysis grades will qualify for preferred procurement status in packaging and single-use film segments.
Market Dynamics
Water-soluble film specifications for pharmaceutical unit-dose packaging are compressing hydrolysis grade tolerances, forcing resin producers to tighten process control across alkaline alcoholysis lines.
Growth Catalysts
- GB standards on biodegradable materials:China's national standards mandate compostable packaging in municipal waste streams, qualifying fully hydrolyzed PVOH for preferred procurement in single-use film applications.
- Textile warp sizing:Water-jet weaving expansion in East Asian manufacturing corridors is pulling partially hydrolyzed grades for yarn binding where synthetic sizing agents face substitution pressure.
- Ethylene-modified copolymers:Thermoplastic processing compatibility unlocks blown film extrusion for barrier layers previously limited to cast film methods.
Market Restraints
- Vinyl acetate monomer volatility:Acetylene-based and ethylene-based feedstock routes both face input cost swings that compress margin stability for non-integrated producers.
- East Asian supply concentration:Carbide-based acetylene chemistry clusters around specific industrial corridors create geographic vulnerability to energy pricing shocks and environmental enforcement waves.
- Barrier performance ceiling:PVOH oxygen transmission rates plateau against ethylene vinyl alcohol copolymers in high-humidity conditions, limiting penetration into retort pouch applications.
Strategic Opportunities
- Agricultural film mulching:Soil-biodegradable formulations for controlled-release nutrient delivery remain underdeveloped outside Japanese and Chinese pilot zones.
- 3D printing support materials:Water-soluble PVOH filaments for complex geometry printing in medical device prototyping represent nascent demand with limited qualified resin supply.
- METI circular economy mandates:Japan's material flow accounting requirements create procurement preference for certified biodegradable resins in packaging supply chains serving domestic retail.
Industry Challenges
- Alcoholysis process control talent:Hydrolysis degree precision to 99%+ specifications requires operators trained in viscosity-molecular weight correlation monitoring, a skill set concentrated at legacy vinylon producers.
- Biodegradability certification timelines:Multi-jurisdiction qualification for home compostable versus industrial compostable status extends product development cycles by 18-24 months.
- Legacy textile sizing equipment compatibility:Water-soluble PVOH film conversion requires warp sizing line modifications that mill operators delay during capital rationing periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyvinyl Alcohol Resins Market |
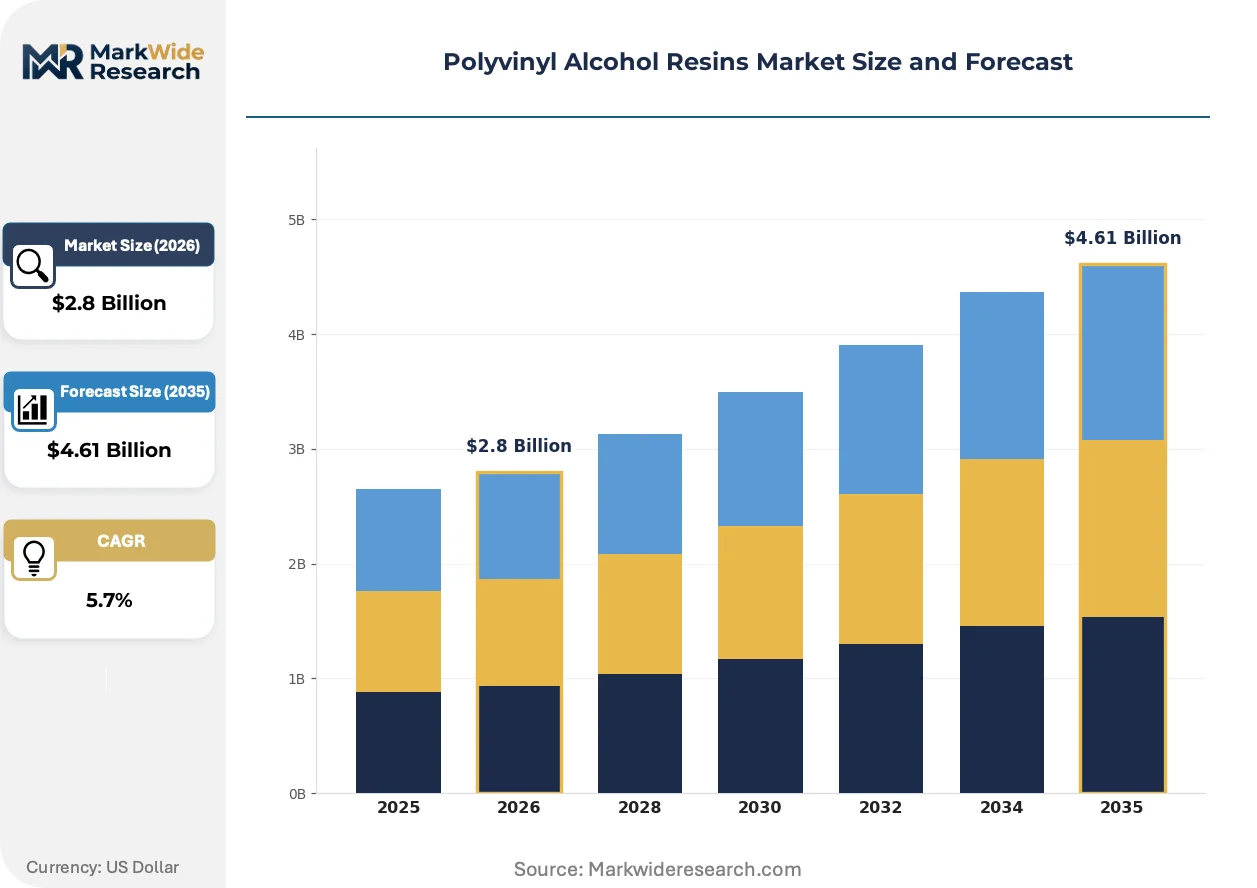
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed PVOH, Partially Hydrolyzed PVOH, Fully Hydrolyzed PVOH, PVOH Copolymer End Use Industry: Textiles, Paper, Adhesives, Coatings Application: Packaging, Construction, Agriculture, Pharmaceuticals Formulation Type: Solution-Based, Powdered, Gel-Based, Film-Forming |
| Companies Covered | Kuraray Co., Ltd., Anhui Wanwei Group Co., Ltd., Chang Chun Group, Sinopec Sichuan Vinylon Works, SEKISUI CHEMICAL CO., LTD., Mitsubishi Chemical Corporation, Ningxia Dadi Circular Development Corp., Ltd., Denka Company Limited, China Petrochemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyvinyl Alcohol Resins Market Evolving Landscape
Ethylene-modified copolymer development is rewriting process boundaries between conventional cast film and thermoplastic extrusion methods, while regulatory biodegradability frameworks are hardening procurement specifications across packaging value chains.
Reactive extrusion of ethylene-vinyl alcohol copolymers is absorbing processing constraints that previously segregated PVOH from standard polyolefin equipment. Blown film converters in food packaging are adopting these grades at accelerating rates. The technology is absorbing capital that would otherwise flow to multilayer coextrusion lines with discrete barrier layers.
REACH registration requirements for polymer imports into Europe are broadening documentation burdens for Asian exporters. ECHA substance evaluation protocols now extend to hydrolysis grade variations previously treated as single polymer entries. Food contact notification pathways for fully hydrolyzed grades face extended dossier preparation timelines, compressing European market entry speed for non-registered suppliers.
Pharmaceutical contract manufacturers are consolidating resin qualification around pre-certified biodegradability tiers. Unit-dose packaging buyers now specify dissolution kinetics thresholds that exclude uncertified hydrolysis grades. This preference compression is most visible in Japanese and German packaging supply chains where METI and BfR guidance documents have hardened into de facto procurement mandates.
Polyvinyl Alcohol Resins Market Segmentation
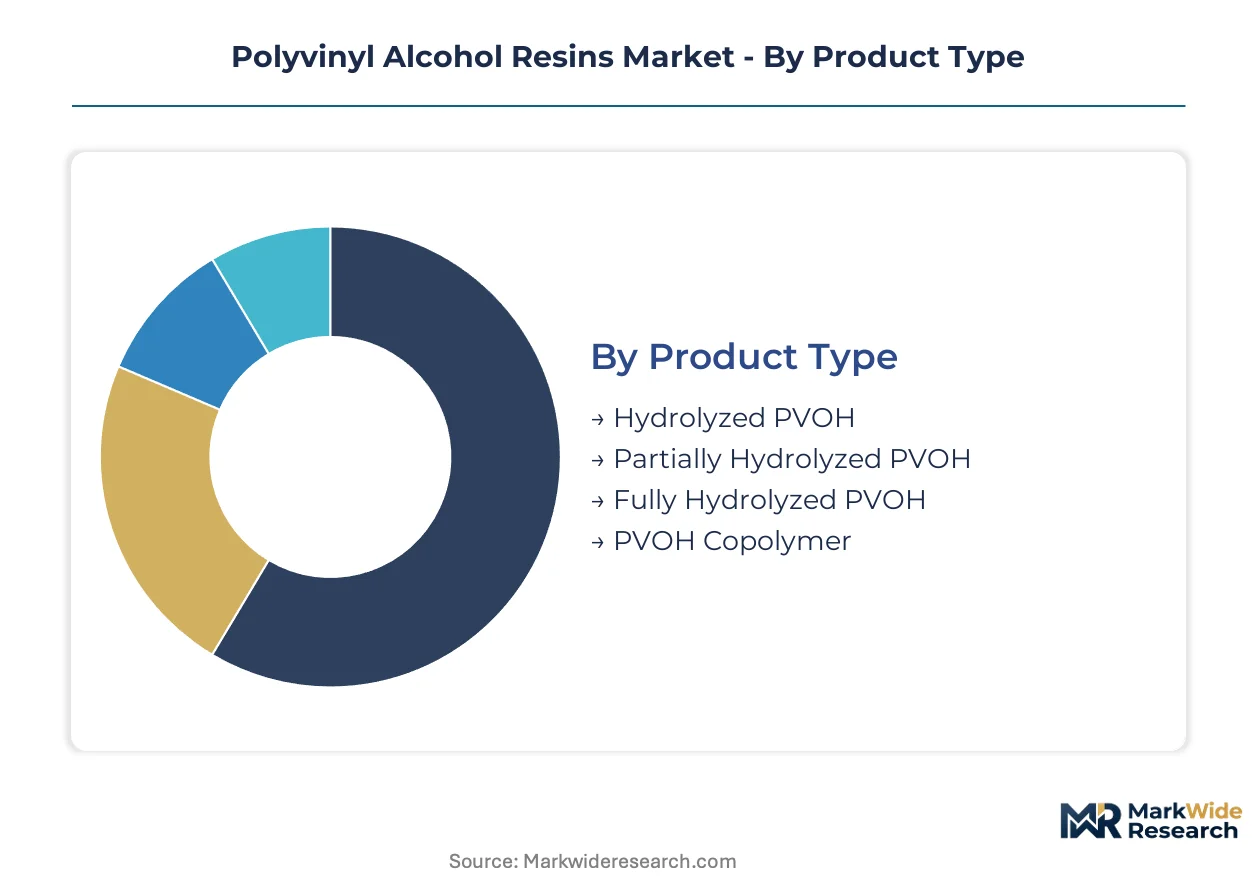
Polyvinyl alcohol resins segment along hydrolysis chemistry, end-use integration depth, and formulation state. These dimensions determine whether resins function as standalone films, embedded binders, or reactive coating systems across industrial applications.
Product Type:
Integration depth varies sharply: fully hydrolyzed grades operate as standalone barrier films, while copolymers embed into thermoplastic matrices requiring compatibilization.
- Fully Hydrolyzed PVOH:These resins achieve hydrolysis degrees exceeding 99%, delivering crystalline structures with minimal oxygen transmission. Demand concentrates in Japanese pharmaceutical packaging corridors where METI biodegradability mandates favor certified film grades for unit-dose applications.
- PVOH Copolymer:Ethylene-modified variants achieve thermoplastic processability on standard blown film lines. Chinese packaging converters around Shanghai industrial clusters are adopting these grades fastest to bypass cast film equipment limitations.
- Partially Hydrolyzed PVOH:Hydrolysis ranges of 80-90% balance water solubility with cost efficiency for textile warp sizing.
- Hydrolyzed PVOH:Intermediate grades serve paper sizing applications where moderate barrier performance suffices.
Volume placements concentrate in Partially Hydrolyzed PVOH; the faster expansion belongs to PVOH Copolymer.
End Use Industry:
Cost tier stratification separates premium film-grade demand in pharmaceuticals from commodity sizing volumes in textiles and paper.
- Textiles:Warp sizing for water-jet weaving consumes the largest resin volumes globally. East Asian manufacturing corridors around Osaka and Shanghai pull partially hydrolyzed grades where synthetic sizing agent substitution accelerates.
- Pharmaceuticals:Unit-dose packaging and tablet coating require fully hydrolyzed grades with certified dissolution kinetics. German contract manufacturers now specify pre-qualified biodegradability tiers that exclude uncertified hydrolysis variants.
- Paper:Surface sizing and pigment binding employ cost-optimized partially hydrolyzed grades.
- Adhesives:Water-based formulations leverage PVOH emulsion stabilization for construction and consumer applications.
Margin concentration sits with Pharmaceuticals; steepest volume climb occurs in Textiles.
Application:
Application maturity separates established packaging films from emerging agricultural and construction integration modes.
- Packaging:Food barrier coatings and water-soluble detergent pods dominate commercial deployment. China's GB standards on biodegradable materials are redirecting procurement toward certified fully hydrolyzed grades for single-use film mandates.
- Agriculture:Soil-biodegradable mulch films and controlled-release nutrient delivery systems remain underdeveloped outside Japanese pilot zones. Ethylene-modified copolymers are gaining trial placement for blown film mulch applications.
- Construction:Cement admixtures and tile adhesives utilize PVOH as redispersible powder binders.
- Pharmaceuticals:Tablet coating and capsule sealing demand pharmaceutical-grade hydrolysis precision.
Revenue gravity centers on Packaging; agricultural film represents the most open competitive terrain.
Formulation Type:
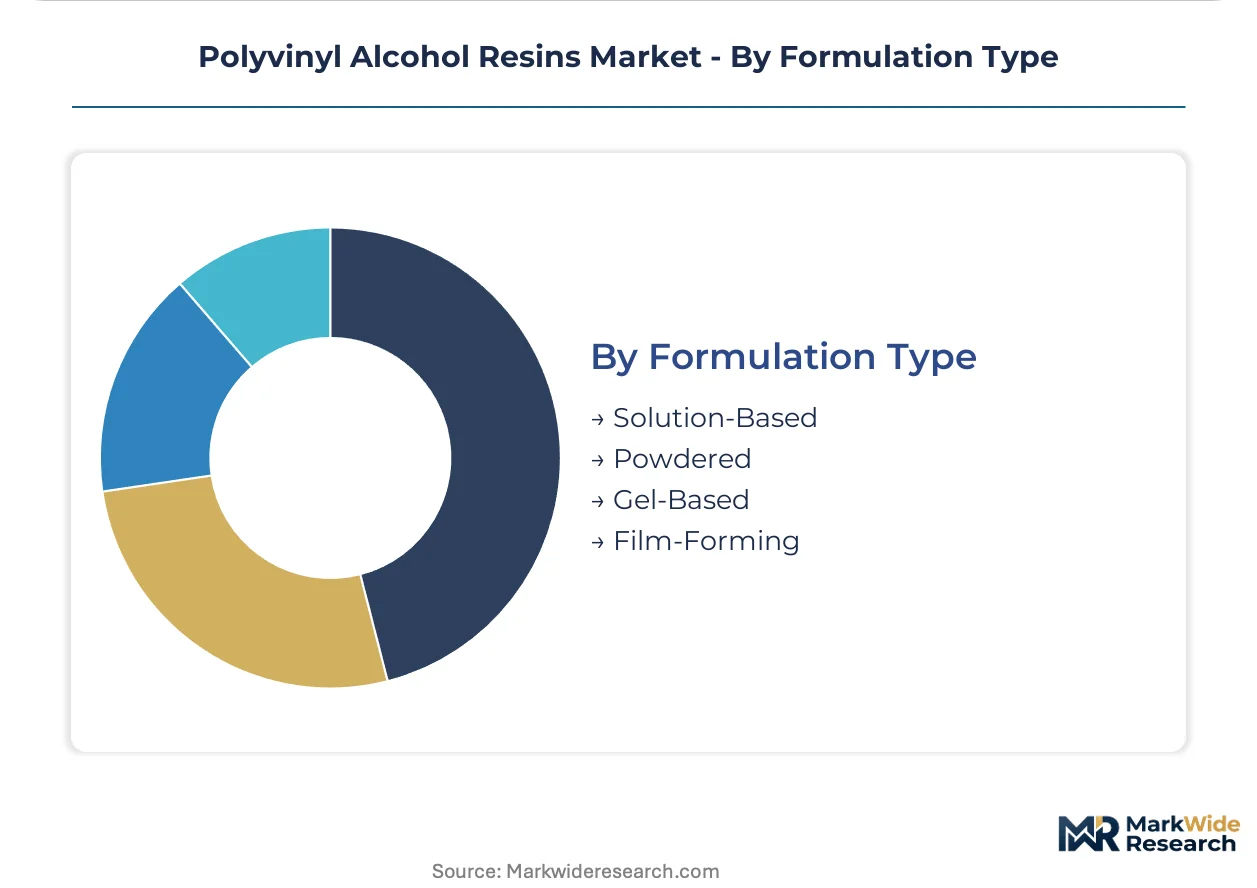
Supply concentration clusters around solution and powder formats, with film-forming grades commanding premium positioning through processing complexity.
- Film-Forming:Cast and extruded films for packaging and transfer printing require viscosity-controlled solutions with tight molecular weight distribution. Japanese vinylon producers anchor supply through legacy alcoholysis process expertise.
- Powdered:Redispersible powders for construction adhesives and textile sizing support global volume distribution. Chinese carbide-based acetylene chemistry clusters dominate cost-optimized powder production.
- Solution-Based:Ready-to-use liquid formulations serve paper coating and adhesive compounding.
- Gel-Based:Thickened preparations target specialized cosmetic and personal care applications.
Capacity concentrates in Powdered; Film-Forming claims the highest value-added expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese and Japanese manufacturers absorb the majority of resin volumes for textile sizing and pharmaceutical packaging. East Asian industrial corridors around Shanghai and Osaka concentrate both production capacity and downstream conversion expertise. European and North American demand relies heavily on certified imports for specialized film applications.
China
Textile warp sizing for water-jet weaving and detergent pod packaging consume the largest resin volumes. GB standards on biodegradable materials mandate compostable packaging in municipal waste streams, qualifying fully hydrolyzed grades for preferred procurement. The Yangtze River Delta around Shanghai anchors carbide-based acetylene chemistry clusters that supply cost-optimized partially hydrolyzed powder grades.
Japan
Pharmaceutical unit-dose packaging and agricultural mulch films drive premium-grade consumption. METI circular economy mandates enforce JIS K 6726 quality benchmarks that govern film tensile strength and dissolution kinetics. The Kansai industrial corridor around Osaka concentrates vinylon production expertise and legacy alcoholysis process control talent.
Germany
Food barrier coatings and pharmaceutical contract manufacturing pull certified fully hydrolyzed imports. ECHA substance evaluation protocols under REACH now extend to hydrolysis grade variations, extending dossier preparation timelines for Asian suppliers. The Rhine-Ruhr manufacturing belt hosts blown film converters trialing ethylene-modified copolymer grades for thermoplastic compatibility.
United States
Construction adhesives and redispersible powder applications sustain steady demand for partially hydrolyzed formulations. EPA industrial chemical reporting under TSCA Section 8 constrains import documentation burdens for non-registered suppliers. The Gulf Coast petrochemical corridor processes ethylene-based feedstock routes for domestic PVOH derivative production.
South Korea
Electronics-grade films and optical coating applications absorb specialty copolymer volumes. The country's national chemical regulator enforces pollutant discharge standards for vinylon manufacturing that align with broader East Asian environmental enforcement waves. The Seoul Capital Area concentrates downstream film conversion capacity serving display and semiconductor packaging end-uses.
Polyvinyl Alcohol Resins Market Competitive Landscape
Japanese producers anchor the premium film-grade tier; Chinese state-affiliated and private specialists hold volume-driven positions in partially hydrolyzed powders. The market structures around three strategic archetypes: acetylene-chemistry integrators with backward integration into carbide feedstocks, ethylene-based petrochemical players with co-located vinyl acetate supply, and specialty copolymer developers targeting thermoplastic processability. Competitive moves concentrate on capacity expansion in East Asian industrial corridors and technology licensing for ethylene-modified grades.
Among Japanese specialists, Kuraray Co., Ltd. and SEKISUI CHEMICAL CO., LTD. occupy positions exemplifying premium-tier film-grade expertise. Chinese state-affiliated entities including Sinopec Sichuan Vinylon Works and China Petrochemical Corporation represent scale-driven acetylene-chemistry integration. Mitsubishi Chemical Corporation sits within the specialty copolymer development archetype, while Anhui Wanwei Group Co., Ltd. anchors private-sector participation in carbide-based production corridors.
| Leading Market Players |
|---|
| Kuraray Co., Ltd. |
| Anhui Wanwei Group Co., Ltd. |
| Chang Chun Group |
| Sinopec Sichuan Vinylon Works |
| SEKISUI CHEMICAL CO., LTD. |
| Mitsubishi Chemical Corporation |
| Ningxia Dadi Circular Development Corp., Ltd. |
| Denka Company Limited |
| China Petrochemical Corporation |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between pharmaceutical-grade fully hydrolyzed resins and commodity partially hydrolyzed powders manifests in both pricing power and supply chain configuration. METI biodegradability mandates and ECHA REACH registration burdens concentrate premium pricing with Japanese vinylon producers while Chinese carbide-chemistry clusters anchor economy-tier supply.
Pricing Analysis
Volume placements in partially hydrolyzed textile sizing grades compress margins against acetylene feedstock volatility, while pharmaceutical film-grade premiums widen on JIS K 6726 certification scarcity. Three-tier pricing structure across premium, standard, and economy levels separates certified unit-dose packaging resins from water-jet weaving powders and construction adhesive grades. Cost compression in standard-tier powders intensifies because vinyl acetate monomer swings transmit directly to non-integrated producers. Textile mill procurement teams exhibit highest price sensitivity; Japanese pharmaceutical contract manufacturers show lowest.
Supply Chain Analysis
Single-source vulnerability sits with carbide-based acetylene chemistry clusters in China's Yangtze River Delta, where environmental enforcement waves disrupt powder-grade supply without short-term alternatives. Production draws from vinyl acetate monomer, carbide feedstock, and ethylene-based petrochemical routes. Tariff exposure on polymer imports into Europe under REACH documentation burdens creates asymmetric compliance costs for Asian exporters. Distribution runs through regional chemical distributors serving textile converters and direct mill supply agreements for pharmaceutical film grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ethylene-modified copolymer thermoplastic compatibility is displacing conventional cast film methods, forcing capital reallocation across processing equipment and resin qualification protocols.
For Market Incumbents: To counter ethylene-modified copolymer displacement of cast film barrier layers, Kuraray and SEKISUI CHEMICAL should deepen captive vinyl acetate integration and accelerate JIS K 6726 certification pipeline expansion for pharmaceutical unit-dose packaging. Backward integration into carbide-based acetylene chemistry protects margin stability against VAM volatility. For New Entrants and Emerging Players: Capture agricultural mulch film white space in European and North American pilot zones where soil-biodegradable formulations remain underdeveloped outside Japanese corridors. Target blown film converters seeking thermoplastic processability without cast equipment investment. Qualify through home compostable certification pathways ahead of procurement mandate hardening. For Investors and Strategic Acquirers: Re-rating potential sits with specialty copolymer developers given ethylene-modified grade adoption acceleration in Chinese packaging converters. Five-to-ten-year viability favors producers with dual-route feedstock flexibility and METI pre-certification. Watch ECHA substance evaluation protocol expansion to hydrolysis grade variations as inflection signal for import documentation burden intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetylene Feedstock | Anhui Wanwei and Sinopec Sichuan anchor cost positions through captive carbide-based chemistry supply. |
| Ethylene-Modified Copolymer Capacity Expansion | Chang Chun Group and Mitsubishi Chemical unlock blown film converter adoption with thermoplastic processability. |
| JIS K 6726 Certification Investment | Japanese vinylon producers defend pharmaceutical film premiums through METI-mandated dissolution kinetics compliance. |
| Long-Term Supply Agreement with Textile Mills | Osaka and Shanghai corridor producers lock water-jet weaving demand against synthetic sizing agent substitution. |
| REACH Registration Dossier Preparation | Asian exporters to Europe extend ECHA compliance timelines to maintain market access under evolving substance evaluation protocols. |
Research Methodology
Multi-period observation of hydrolysis grade adoption rates, certification timeline compression, and ethylene-modified copolymer trial placements anchored the trend analysis, supplemented by interviews with vinylon plant managers, textile procurement leads at water-jet weaving OEMs, pharmaceutical packaging technical directors, and chemical distribution channel partners. Secondary validation drew from ECHA substance evaluation protocols, METI circular economy guidance documents, SEC 10-K filings of listed resin producers, and customs trade data for polyvinyl alcohol resin imports. Bottom-up capacity and demand modeling triangulated against top-down end-use consumption estimates.
Segment-weighting across hydrolysis chemistry tiers, end-use industry verticals, and formulation state categories structured the analytical framework throughout the projection horizon. CAGRs derived from fitted growth curves applied to baseline consumption estimates, with ethylene-modified copolymer penetration rates and GB standards compliance timelines as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to environmental enforcement intensity in Chinese industrial corridors and biodegradability certification protocol harmonization across jurisdictions. Forecasts reflect documented assumptions on feedstock route economics and regulatory implementation pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Styrene-Butadiene-Styrene Block Copolymer Market
Polymers & Resins
Asia-Pacific Geopolymer Market
Polymers & Resins
South America Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Global Polyolefin Powders Market
Polymers & Resins
Polycarbonate Resin Market
Polymers & Resins
Green Polyols Market
Polymers & Resins
Terpene Resins Market
Polymers & Resins
Middle East Engineering Plastics Market
Polymers & Resins
High-Purity Epoxy Resin Market
Polymers & Resins
Flexible Epoxy Resin Market
Polymers & Resins
North America Plastic Compounding Market
Polymers & Resins
GCC Polyethylene Terephthalate (PET) Market
Polymers & Resins
Global Cyanate Ester Resins Market
Polymers & Resins
Neoprene Market
Polymers & Resins
Canada Bioresorbable Polymers Market
Polymers & Resins
Paste PVC Resin Market