
 India Plastic Market | 2026-2036
India Plastic Market Size, Share, and Industry Trends Forecast 2026-2036
India Plastic Market Insights
Skilled polymer technologist availability is collapsing across Gujarat and Maharashtra, forcing processors to automate compounding lines or absorb wage inflation. Chemplast Sanmar Ltd anchors its position through captive chlor-alkali and PVC resin integration at Mettur and Karaikal. Plastiblends India Ltd specializes in masterbatch formulation for automotive OEM color matching, sustaining technical partnerships with tier-1 suppliers. Shaily Engineering Plastics dominates precision injection molding for medical device housings, leveraging FDA-equivalent process validation at its Vadodara facility.
Plastic comprises synthetic or semi-synthetic organic polymers—typically carbon backbone chains with molecular weights exceeding 10,000 g/mol—processed via extrusion, injection molding, or blow molding into rigid or flexible articles serving containment, protection, insulation, or structural functions. Polyethylene retains volume leadership in flexible packaging films and blow-molded containers, though margin pools are thinning from import parity pressures on ethylene feedstock. Polypropylene captures faster expansion in automotive underhood components and microwaveable food trays, where heat deflection temperature above 100°C justifies premium pricing over polyethylene substitutes.
BIS certification for food-contact plastics and the Plastic Waste Management Rules enforce recyclate incorporation thresholds and extended producer responsibility registration, raising compliance costs for unorganized compounders while consolidating volume with integrated resin-to-article manufacturers. The Central Pollution Control Board's state-level enforcement varies, creating arbitrage between Tamil Nadu's stricter audit schedules and Uttar Pradesh's slower implementation timelines. Stakeholders must monitor feedstock cost pass-through mechanics and BIS labeling mandates before committing greenfield capacity in any Indian state.

Market Dynamics
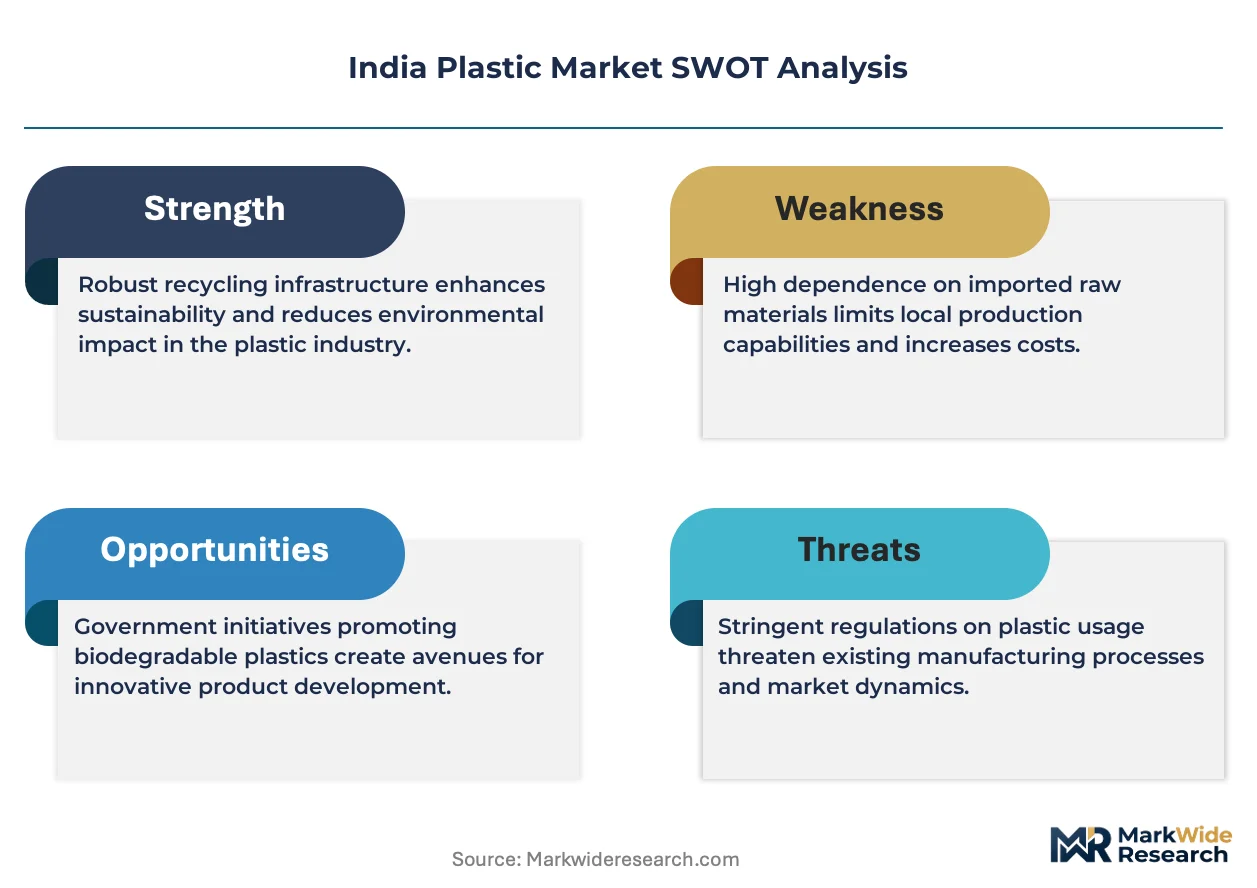
Extended producer responsibility mandates under India's Plastic Waste Management Rules are compressing margins for unorganized compounders while consolidating volume with integrated resin-to-article manufacturers possessing captive recycling infrastructure.
Growth Catalysts
- E-commerce packaging surge:FMCG and quick-commerce channels are driving blow-molded container and flexible film consumption across Maharashtra and Gujarat processing clusters.
- Automotive underhood expansion:Heat-deflection-grade polypropylene is capturing engine bay component contracts from metal substitutes as OEMs pursue lightweighting targets.
- BIS certification harmonization:Food-contact safety standards are professionalizing the masterbatch and compounding sector, disqualifying informal suppliers from institutional procurement.
Market Restraints
- Ethylene feedstock import parity:Naphtha-linked polyethylene resin costs fluctuate with Middle East supply disruptions, squeezing film processor margins.
- Skilled polymer technologist scarcity:Gujarat and Maharashtra face collapsing availability of compound formulation specialists, forcing automation capex or wage inflation absorption.
- Mechanical recycling quality ceiling:Contaminated post-consumer waste streams limit rPET and rPE incorporation rates in food-contact applications below regulatory thresholds.
Strategic Opportunities
- Tamil Nadu petrochemical cluster expansion:Karaikal and Mettur infrastructure supports chlor-alkali and PVC integration plays for construction piping and medical device housings.
- Medical device precision molding:FDA-equivalent process validation capabilities open export contracts for surgical instrument and diagnostic housing manufacturers.
- PLI scheme downstream extension:Production-linked incentives for advanced chemistry manufacturing could subsidize specialty polymer and masterbatch capacity buildout.
Industry Challenges
- Compounder certification timelines:BIS laboratory testing queues for food-contact safety approvals extend 8-14 months, delaying new product commercialization.
- Legacy extrusion line retrofit costs:Recyclate incorporation mandates require twin-screw compounding upgrades incompatible with single-screw equipment prevalent in Uttar Pradesh.
- State-level enforcement variance:Central Pollution Control Board audit intensity gaps between Tamil Nadu and Uttar Pradesh create compliance arbitrage complexity for multi-state operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Plastic Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene Application: Packaging, Automotive Components, Consumer Goods, Medical Devices End User: Manufacturing, Retail, Construction, Healthcare Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | S.M. Extrusions, APPL Industries Limited, M3 Extrusion, Shaily Engineering Plastics, Chemplast Sanmar Ltd, Sanjay Polymers, Maruti Flexoplast Industries, Plastiblends India Ltd, Xtrude International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Plastic Market Trends and Innovations
Chemical recycling and bio-based feedstock pathways are fragmenting the traditional fossil-resin value chain, while regulatory compliance automation and buyer consolidation reshape competitive requirements across India's plastic processing landscape.
Pyrolysis-based chemical recycling is fragmenting the mechanical recycling monopoly on post-consumer waste recovery. FMCG majors in Maharashtra are piloting offtake agreements for pyrolysis oil-derived polyethylene at 15-20% price premiums to virgin resin. This technology is fragmenting the waste management value chain by enabling contaminated film and multi-layer packaging recovery previously routed to cement kiln co-processing.
India's Plastic Waste Management Rules are mandating phased recyclate incorporation thresholds for rigid packaging. BIS is developing testing protocols for recycled content verification, forcing compounders to invest in spectroscopic traceability systems. Food-contact plastics manufacturers in Gujarat face the steepest compliance curves as brand owners demand audit-ready supply chain documentation.
Quick-commerce fulfillment networks are compressing primary packaging specifications toward mono-material formats compatible with 30-minute delivery logistics. E-commerce grocery platforms in Bangalore and Mumbai are rejecting multi-layer laminates in favor of PE or PP mono-film pouches. This specification tightening is most visible in snack and personal care segments where shelf-appeal graphics must now conform to sortation-compatible substrate choices.
India Plastic Market Segmentation
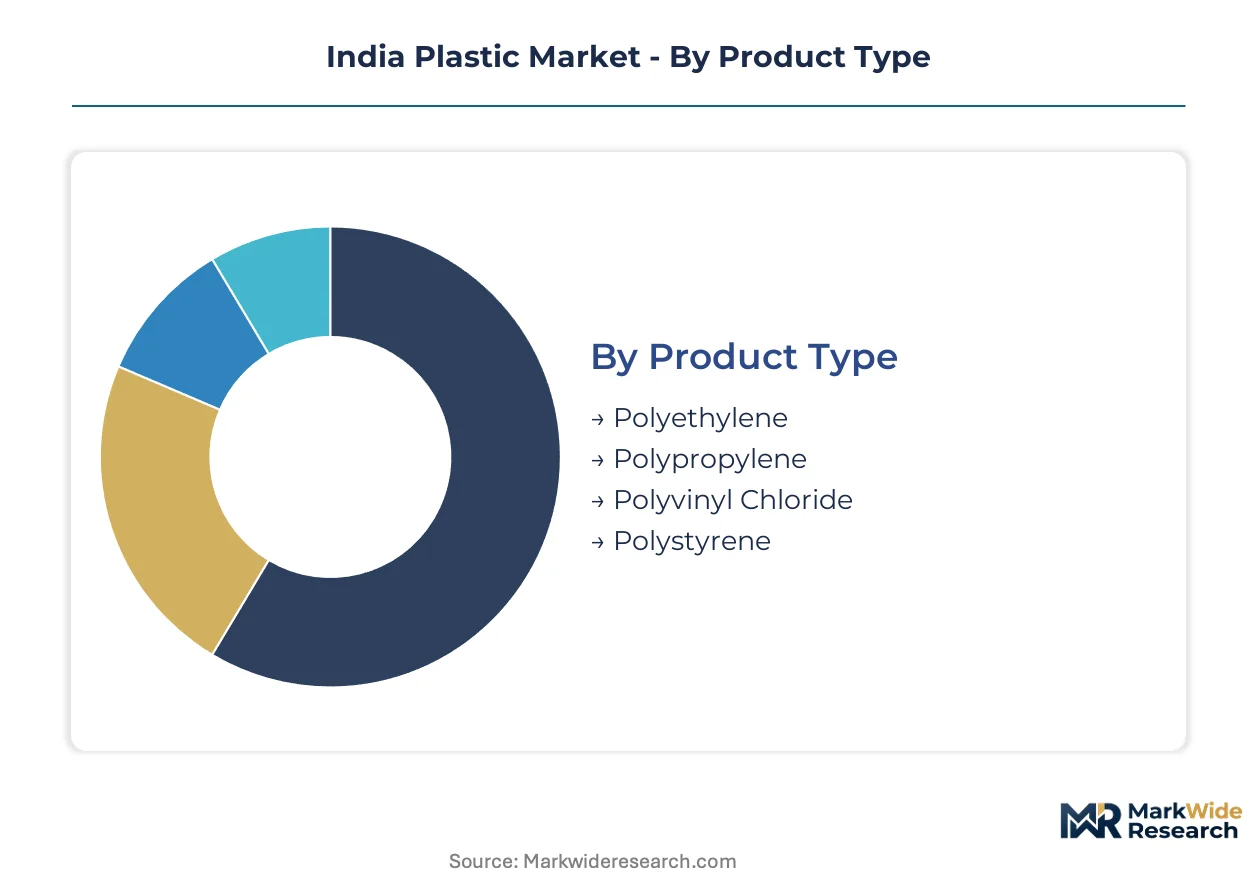
Segmentation in the India plastic market reveals distinct procurement patterns across domestic manufacturing clusters and export-oriented processing zones. Resin selection and application specifications diverge sharply between Maharashtra's FMCG supply chains and Tamil Nadu's medical device export corridors.
Product Type:
Polyethylene and polypropylene dominate domestic flexible packaging consumption, while PVC and polystyrene serve specialized construction and consumer goods segments with stronger export linkages.
- Polyethylene:Linear low-density and high-density grades constitute the backbone of flexible films and blow-molded containers. Demand concentrates in Gujarat and Maharashtra processing clusters serving FMCG and quick-commerce fulfillment networks, where mono-material specifications are displacing multi-layer laminates.
- Polypropylene:Homopolymer and copolymer variants deliver heat deflection temperatures exceeding 100°C for automotive underhood components and microwaveable food trays. Tamil Nadu and Haryana automotive tier-1 suppliers are expanding polypropylene intake as metal substitution accelerates under OEM lightweighting mandates.
- Polyvinyl Chloride:Suspension and emulsion grades anchor construction piping, cable insulation, and medical device housings through chlor-alkali integrated production at Karaikal and Mettur.
- Polystyrene:General-purpose and high-impact formulations serve consumer electronics packaging and disposable food service ware, with demand fragmentation across Uttar Pradesh's unorganized molding sector.
Polyethylene commands the established base. The steepest expansion runs through polypropylene.
Application:
Application mix reflects India's consumption pyramid, with packaging absorbing commodity resin volumes while automotive and medical segments command specialty formulation premiums.
- Packaging:Flexible films, rigid containers, and protective foams process 60% of domestic polyethylene and polypropylene offtake. E-commerce grocery platforms in Bangalore and Mumbai are enforcing mono-material specifications that disqualify legacy multi-layer structures from vendor qualification.
- Automotive Components:Underhood ducts, battery housings, and interior trim leverage glass-filled polypropylene and engineering polymer blends. Haryana and Tamil Nadu automotive clusters are expanding precision molding capacity to serve export-facing OEM contracts.
- Consumer Goods:Appliances, furniture, and housewares utilize ABS, polystyrene, and polypropylene in injection-molded and thermoformed articles. Gujarat's processing belt dominates this mid-margin segment with distributed small-batch production.
- Medical Devices:Diagnostic housings, surgical instruments, and drug delivery systems require FDA-equivalent process validation and BIS-certified materials. Vadodara and Chennai facilities are capturing export contracts through ISO 13485 compliance and cleanroom molding infrastructure.
Packaging absorbs the volume foundation. Medical devices deliver the margin expansion.
End User:
End-user concentration tracks India's industrial geography, with manufacturing and retail absorbing standard grades while healthcare and construction demand certified and durable formulations.
- Manufacturing:Original equipment manufacturers and contract molders across the Delhi-Mumbai Industrial Corridor consume bulk resin through annual frame contracts. BIS certification requirements are disqualifying unorganized compounders from institutional procurement.
- Retail:Quick-commerce and traditional trade channels drive primary packaging specifications toward 30-minute delivery-compatible formats. Mono-material pouches are replacing multi-layer laminates in snack and personal care segments.
- Construction:PVC piping, waterproofing membranes, and insulation materials serve residential and infrastructure projects. Tamil Nadu's chlor-alkali integration supports cost-competitive piping for southern markets.
- Healthcare:Hospitals, diagnostic chains, and pharmaceutical packaging operations demand audit-ready supply chain documentation and spectroscopic traceability for recycled content verification.
Manufacturing and retail anchor volume throughput. Healthcare is climbing fastest on compliance premiums.
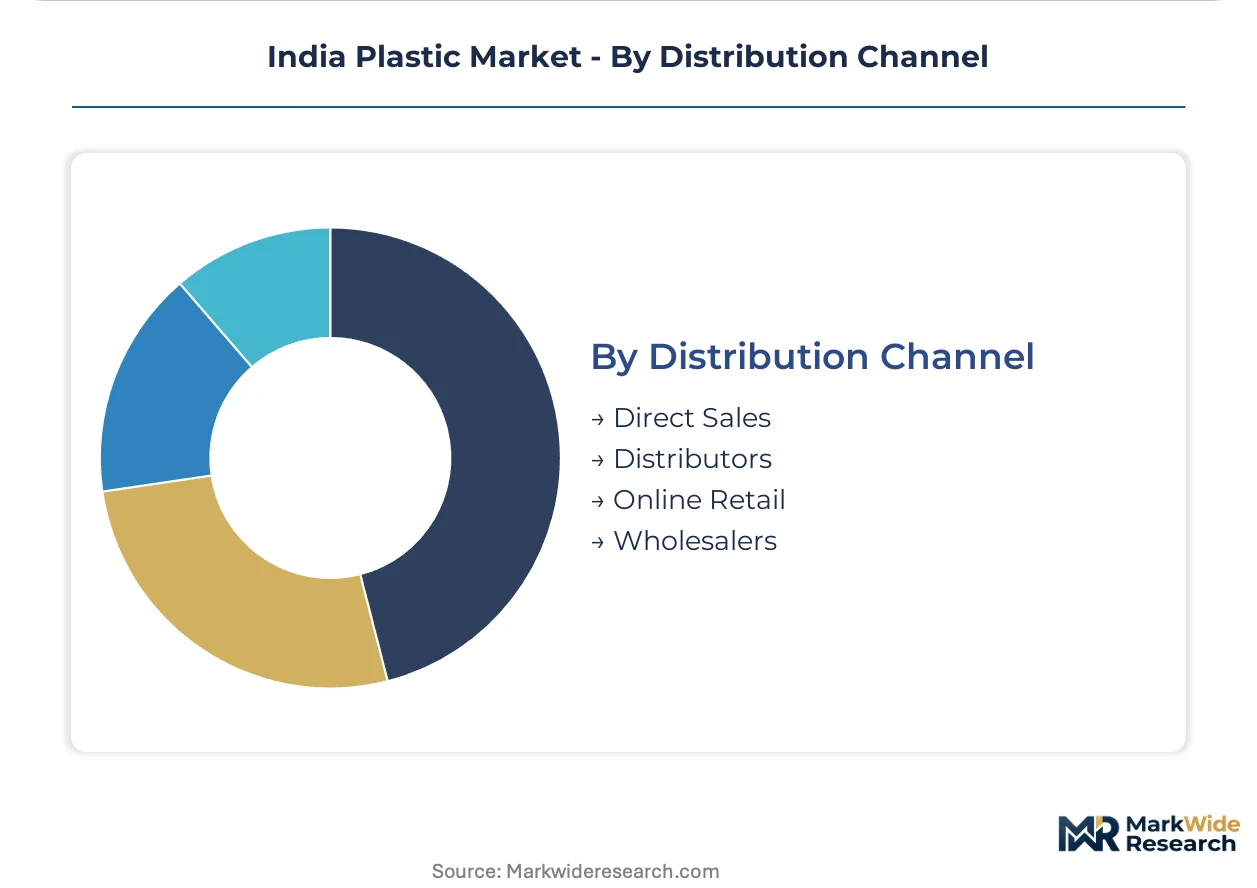
Distribution Channel:
Channel structure bifurcates between resin producers' direct mill relationships with large processors and distributor networks serving fragmented small-batch molders.
- Direct Sales:Reliance Industries, Indian Oil, and Gail command 70% of domestic polyethylene and polypropylene supply through long-term offtake agreements with Gujarat and Maharashtra film processors.
- Distributors:Regional stockists in Uttar Pradesh and Madhya Pradesh bridge supply gaps for unorganized injection molders lacking credit facilities for mill-direct procurement.
- Online Retail:B2B platforms are emerging for specialty masterbatch and engineering polymer spot purchases, though volume remains below 5% of resin trade.
- Wholesalers:Commodity PVC and polystyrene flow through construction material mandis and industrial chemical markets with price discovery tied to import parity fluctuations.
Direct sales lock in the volume base. Distributor networks are expanding most quickly into tier-2 processing clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra and Gujarat consume polyethylene and polypropylene for flexible packaging at rates exceeding southern states, while Tamil Nadu specializes in medical-grade precision molding for export markets.
Maharashtra
Quick-commerce fulfillment networks in Mumbai and Pune are driving blow-molded container specifications toward mono-material formats compatible with 30-minute delivery logistics. BIS certification mandates for food-contact plastics are disqualifying unorganized compounders from institutional procurement. The Mumbai-Thane processing belt dominates flexible film production for FMCG supply chains.
Gujarat
Petrochemical clusters in Vadodara and Ahmedabad anchor domestic polyethylene and polypropylene supply through integrated resin-to-article manufacturing. The state's Plastic Waste Management Rules enforcement is stricter than northern counterparts, raising compliance costs for mechanical recyclers. Vadodara facilities are capturing medical device export contracts through FDA-equivalent process validation.
Tamil Nadu
Automotive underhood component demand from Chennai and Sriperumbudur OEM suppliers is accelerating heat-deflection-grade polypropylene intake. The state's chlor-alkali integration at Karaikal and Mettur supports cost-competitive PVC piping for southern construction markets. Chennai medical device molders are expanding ISO 13485-compliant cleanroom infrastructure for diagnostic housing exports.
Haryana
Automotive tier-1 suppliers in Manesar and Gurgaon are expanding glass-filled polypropylene capacity to serve export-facing OEM lightweighting contracts. Central Pollution Control Board audit intensity gaps create compliance arbitrage complexity for multi-state operators with Uttar Pradesh facilities. The Delhi-Mumbai Industrial Corridor segment here processes bulk resin through annual frame contracts.
West Bengal
Eastern packaging demand concentrates in Kolkata for consumer goods distribution into Bangladesh and Northeast India markets. BIS laboratory testing queues for food-contact safety approvals extend 8-14 months, delaying new product commercialization for local compounders. The Haldia petrochemical corridor provides feedstock proximity for rigid container manufacturers serving the eastern consumption belt.
India Plastic Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with resin producers commanding direct mill relationships while regional compounders serve fragmented small-batch molders. The market structure bifurcates between scale-driven integrated players with captive recycling infrastructure and formulation specialists competing on technical partnerships. Three archetypes dominate: petrochemical-integrated resin suppliers, precision molding specialists with medical validation capabilities, and masterbatch formulators serving automotive color-matching requirements. Competitive moves center on automation capex to offset skilled technologist scarcity and strategic partnerships for pyrolysis oil offtake agreements.
Within the integrated manufacturing tier, Chemplast Sanmar Ltd and Shaily Engineering Plastics exemplify divergent specialization paths—one anchored in chlor-alkali and PVC resin integration, the other in precision injection molding with medical device validation. Plastiblends India Ltd occupies a position within the masterbatch formulation specialist tier, serving technical partnerships with automotive suppliers. These three represent the competitive spectrum from upstream chemical integration through downstream precision manufacturing to specialty additive formulation.
| Leading Market Players |
|---|
| S.M. Extrusions |
| APPL Industries Limited |
| M3 Extrusion |
| Shaily Engineering Plastics |
| Chemplast Sanmar Ltd |
| Sanjay Polymers |
| Maruti Flexoplast Industries |
| Plastiblends India Ltd |
| Xtrude International |
| Others |
Pricing and Supply Chain Analysis
Ninety-day resin inventory buffers at Gujarat processing clusters concentrate pricing power with Reliance Industries and Indian Oil, who command 70% of domestic polyethylene and polypropylene supply through long-term offtake agreements. This concentration amplifies feedstock cost pass-through mechanics while compressing margins for film processors lacking backward integration into naphtha-linked ethylene production.
Pricing Analysis
Long-term offtake agreements dominate resin procurement for large Maharashtra and Gujarat processors, while spot purchases through regional distributors serve Uttar Pradesh's fragmented molding sector. Price differentiation rests on BIS certification grade and volume scale, with food-contact safety approvals commanding 15-20% premiums over industrial grades. Pricing pressure stems from Middle East ethylene supply disruptions transmitting through naphtha-linked import parity. Small-batch molders in unorganized segments exhibit highest price sensitivity, while medical device manufacturers with FDA-equivalent validation absorb premiums for audit-ready supply chain documentation.
Supply Chain Analysis
Strategic stockpiling of polyethylene and polypropylene resin prevails among integrated processors in Gujarat and Maharashtra, while just-in-tight inventory models dominate quick-commerce packaging converters facing 30-minute delivery logistics. Geographic supply concentrates in India, with feedstock dependencies on Middle East naphtha and domestic chlor-alkali integration at Tamil Nadu's Karaikal and Mettur facilities. Single-source vulnerability runs through ethylene import channels exposed to Red Sea logistics chokepoints. Distribution runs through direct mill relationships for large processors and regional distributor networks for tier-2 molding clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The collapse of skilled polymer technologist availability across western India has transformed formulation capability into a scarce asset, forcing processors to choose between automation capital expenditure and wage inflation absorption while consolidating volume with integrated resin-to-article manufacturers.
For Market Incumbents: Fortify market position by deepening captive recycling infrastructure to meet Plastic Waste Management Rules thresholds and securing pyrolysis oil offtake partnerships with FMCG majors piloting chemical recycling. Automation capex in compounding lines offsets skilled technologist scarcity threatening operational continuity. For New Entrants and Emerging Players: Anchor in Tamil Nadu's medical device precision molding corridor, where ISO 13485 compliance requirements and FDA-equivalent process validation capabilities create defensible positioning against commodity resin competitors. Target diagnostic housing and surgical instrument contracts through cleanroom infrastructure investment and BIS-certified material sourcing. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because extended producer responsibility mandates are compressing margins for unorganized compounders while concentrating volume with integrated manufacturers possessing captive recycling infrastructure. Acquisition focus should center on masterbatch formulators with automotive OEM technical partnerships and spectroscopic traceability systems for recycled content verification. The signal to watch is BIS laboratory testing queue lengths for food-contact safety approvals, which currently extend 8-14 months and indicate regulatory capacity constraints that favor pre-certified assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali | Chemplast Sanmar's captive PVC resin production at Mettur and Karaikal eliminates feedstock cost volatility exposure. |
| Pyrolysis Oil Offtake Partnership | FMCG majors in Maharashtra are piloting agreements at 15-20% premiums to virgin resin for contaminated film recovery. |
| Automation Capex in Compounding | Twin-screw equipment upgrades enable recyclate incorporation mandates incompatible with legacy single-screw extrusion lines. |
| ISO 13485 Cleanroom Expansion | Vadodara and Chennai facilities capture export contracts through FDA-equivalent process validation infrastructure. |
| Spectroscopic Traceability Investment | BIS recycled content verification protocols force compounders to deploy analytical systems for audit-ready supply chain documentation. |
Research Methodology
A spread of perspectives from polymer plant managers, procurement leads at automotive Tier 1 suppliers, distribution channel partners in Uttar Pradesh and Madhya Pradesh, and technical R&D directors at masterbatch formulators converged on the working assumptions shaping this analysis. Secondary validation drew from customs and trade data, Central Pollution Control Board enforcement schedules, BIS certification registries, and SEC filings of listed petrochemical producers. Bottom-up resin consumption estimates across Maharashtra, Gujarat, and Tamil Nadu processing clusters were triangulated against top-down petrochemical production data from Reliance Industries and Indian Oil disclosures.
Segmentation dimensions modeled encompass resin grade tier, end-use application, regulatory compliance cluster, and regional production hub concentration across the analysis window. CAGRs were derived through regression analysis of historical resin offtake patterns and projection of e-commerce packaging demand trajectories, automotive lightweighting penetration rates, and medical device export growth. Industry-specific forecast inputs include BIS certification timeline assumptions and state-level Plastic Waste Management Rules enforcement intensity differentials.
Decision-makers should treat outputs as directional under assumptions of sustained naphtha-linked ethylene cost pass-through and stable BIS laboratory testing capacity; material deviation would warrant model refresh. Revision becomes warranted when Central Pollution Control Board audit intensity gaps between Tamil Nadu and northern states narrow, altering compliance arbitrage calculations for multi-state operators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Polyvinyl Chloride (PVC) Market
Recycled Plastics
North America Plastic Waste Management Market
Recycled Plastics
Global Recycled Plastics Market
Recycled Plastics
South Korea Recycled Plastics Market
Recycled Plastics
Recycled Polypropylene Market
Recycled Plastics
Green Polyvinyl Chloride Market
Recycled Plastics
Plastics-To-Fuel (PTF) Market
Recycled Plastics
Recycled Carbon Fiber Market
Recycled Plastics
Saudi Arabia Plastic Components Market
Recycled Plastics
USA Plastic-To-Fuel Market
Recycled Plastics
Foam Plastics Market
Recycled Plastics
Plastic Drums Market
Recycled Plastics
Plastic Ignition Holders Market
Recycled Plastics
Plastic Color Sorter Market
Recycled Plastics
Recycled PET Flakes Market
Recycled Plastics
Global Recycled Asphalt Market