
 Iron Recycling Market | 2026-2036
Iron Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Iron Recycling Market Outlook
The gap between prime heavy melting steel and shredded light scrap is rebalancing as EAF operators tighten chemistry specifications and pay wider spreads for predictable melt chemistry. Nucor Corporation leverages its coast-to-coast mill network to source scrap directly from industrial generators, locking in volume and quality consistency. ArcelorMittal anchors its recycling position through integrated flat-rolled operations in North America and Europe, blending scrap with direct reduced iron to manage residuals. Schnitzer Steel Industries, Inc. competes by dominating West Coast export flows and processing infrastructure, giving it pricing power in Pacific Rim ferrous trade.
Iron recycling recovers ferrous metals from end-of-life products and industrial byproducts for reintroduction into steelmaking furnaces, with shredded scrap typically containing 0.2-0.5% copper contamination that must be diluted or managed in melt chemistry. Its primary purpose is to substitute virgin iron ore and pig iron, cutting energy use by roughly 60-75% per ton of crude steel output. Collection through scrap yards and industrial channels captures the highest-margin material streams, as these sources yield cleaner grades with lower residual element content that command premium pricing over curbside flows. Processing via shredding and magnetic separation now dominates volume throughput, though specialized baling of heavy melting steel retains importance for traditional integrated mills seeking dense, predictable furnace charges.
The EPA oversees industrial emissions from shredding and melting operations in the United States, while the EU Green Deal and REACH framework constrain allowable contaminant levels in scrap imported into European steelworks. China's MIIT enforces national scrap utilization ratio targets that directly shape import demand and domestic collection infrastructure investment. Stakeholders must monitor how carbon border adjustments and scrap quality standards in multiple jurisdictions reshape arbitrage flows and processing technology choices.
Market Dynamics
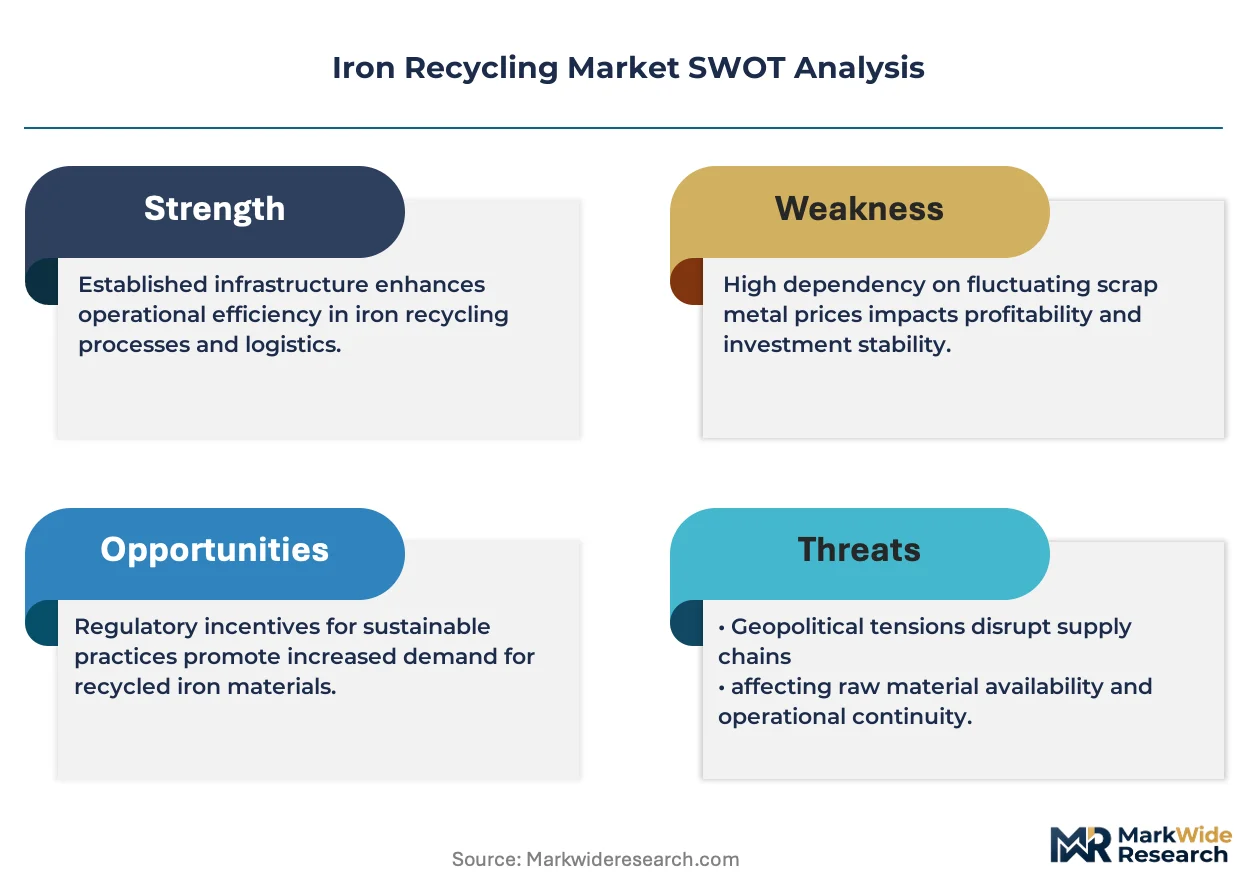
Electric arc furnace capacity expansion is compressing demand for virgin iron ore while tightening scrap quality specifications, forcing collection infrastructure to upgrade sorting precision and residual management capabilities.
Growth Catalysts
- EU Green Deal decarbonization mandates:Steelmakers face binding emissions reduction targets that elevate post-consumer scrap premiums above pig iron alternatives. Automotive OEMs now specify minimum recycled content in supplier contracts.
- China MIIT scrap utilization ratio targets:National policy directs steelmakers to raise scrap input rates, triggering domestic shredding capacity construction and import quota adjustments.
- Shredding technology diffusion:Advanced sensor-based sorting systems now extract non-ferrous contaminants at throughput rates that justify brownfield yard upgrades.
Market Restraints
- Copper contamination concentration:Shredded automotive scrap carries residual copper levels that exceed EAF chemistry tolerances, requiring costly dilution with prime heavy melting steel or direct reduced iron.
- Geographic supply fragmentation:Collection infrastructure concentrates in industrial corridors, leaving rural and post-industrial regions underserved with logistics costs that erode processor margins.
- REACH compliance friction:EU import screening for hazardous substance content creates documentation burdens and detention risks that compress arbitrage windows for exporters.
Strategic Opportunities
- India PLI scheme alignment:Domestic steel capacity expansion under production-linked incentives creates demand for organized scrap collection networks currently dominated by informal channels.
- Automotive end-of-life vehicle mandates:Extended producer responsibility regulations in multiple jurisdictions guarantee feedstock volumes to processors with certified dismantling capabilities.
- Digital platform integration:Blockchain-tracked provenance systems connect industrial generators directly to EAF operators, disintermediating traditional scrap yard intermediaries.
Industry Challenges
- Metallurgical assay skill scarcity:Rapid chemistry verification at collection points requires technicians trained in handheld spectroscopy, a competency pipeline that lags equipment deployment.
- Legacy baling equipment stranded costs:Traditional integrated mills reducing blast furnace operations leave processors with underutilized heavy melting steel infrastructure.
- ISO 14001 certification timeline compression:Carbon disclosure requirements from downstream steel customers demand environmental management system documentation that smaller yards struggle to assemble.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iron Recycling Market |
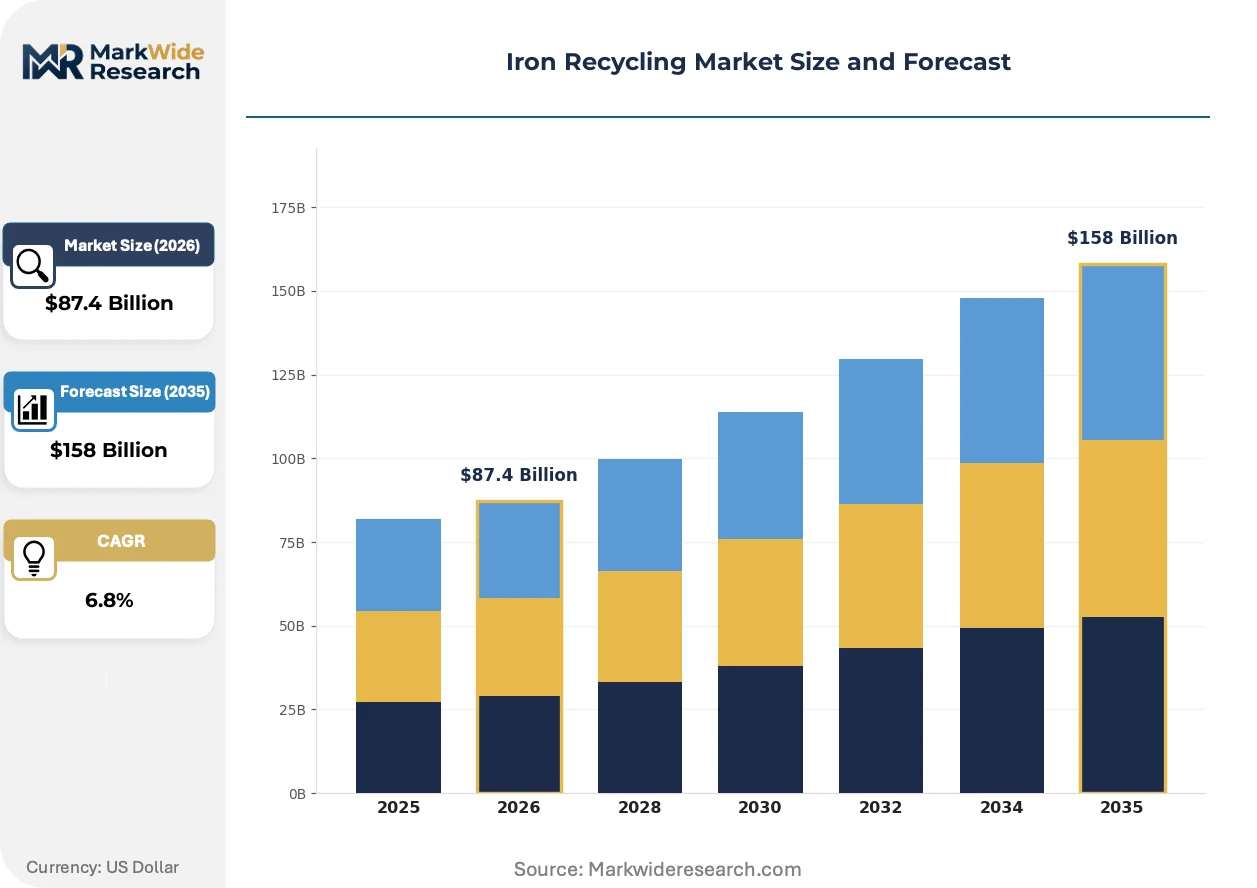
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Collection Method: Drop-off Centers, Curbside Collection, Scrap Yards, Industrial Collection End Use Industry: Construction, Automotive, Manufacturing, Packaging Processing Technique: Shredding, Melting, Magnetic Separation, Baling Material Grade: Heavy Melting Steel, Light Melting Steel, Scrap Iron, Others |
| Companies Covered | ArcelorMittal, Nucor Corporation, SIMS Metal Management Limited, Commercial Metals Company, European Metal Recycling Limited, Schnitzer Steel Industries, Inc., OmniSource Corporation, SA Recycling LLC, Tata Steel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iron Recycling Market Strategic Shifts
Sensor-based sorting and digital traceability systems are absorbing capital and talent, compressing the competitive advantage of traditional volume-based processors while elevating chemistry-predictable material premiums.
Artificial intelligence-driven optical sorting is absorbing contamination detection tasks previously requiring manual sampling and laboratory analysis. EAF operators in Germany and Japan deploy these systems to guarantee melt chemistry compliance with minimal human intervention. The technology is absorbing margin from processors who rely on post-shipment adjustments and penalty negotiations.
REACH substance of very high concern screening is tightening import documentation requirements for scrap entering EU steelworks. Processors must now maintain chain-of-custody records linking each shipment to specific end-of-life product categories. Turkish and Indian exporters face elevated inspection rates that compress working capital cycles and favor larger operators with dedicated compliance staff.
Automotive OEMs are consolidating scrap procurement through direct mill relationships rather than merchant intermediaries. BMW and Volvo now contract directly with Nucor and ArcelorMittal for closed-loop aluminum and steel recovery from manufacturing scrap. This bypasses traditional scrap yards in North America and Europe, concentrating volume with processors capable of dedicated logistics and quality certification.
Iron Recycling Market Segmentation
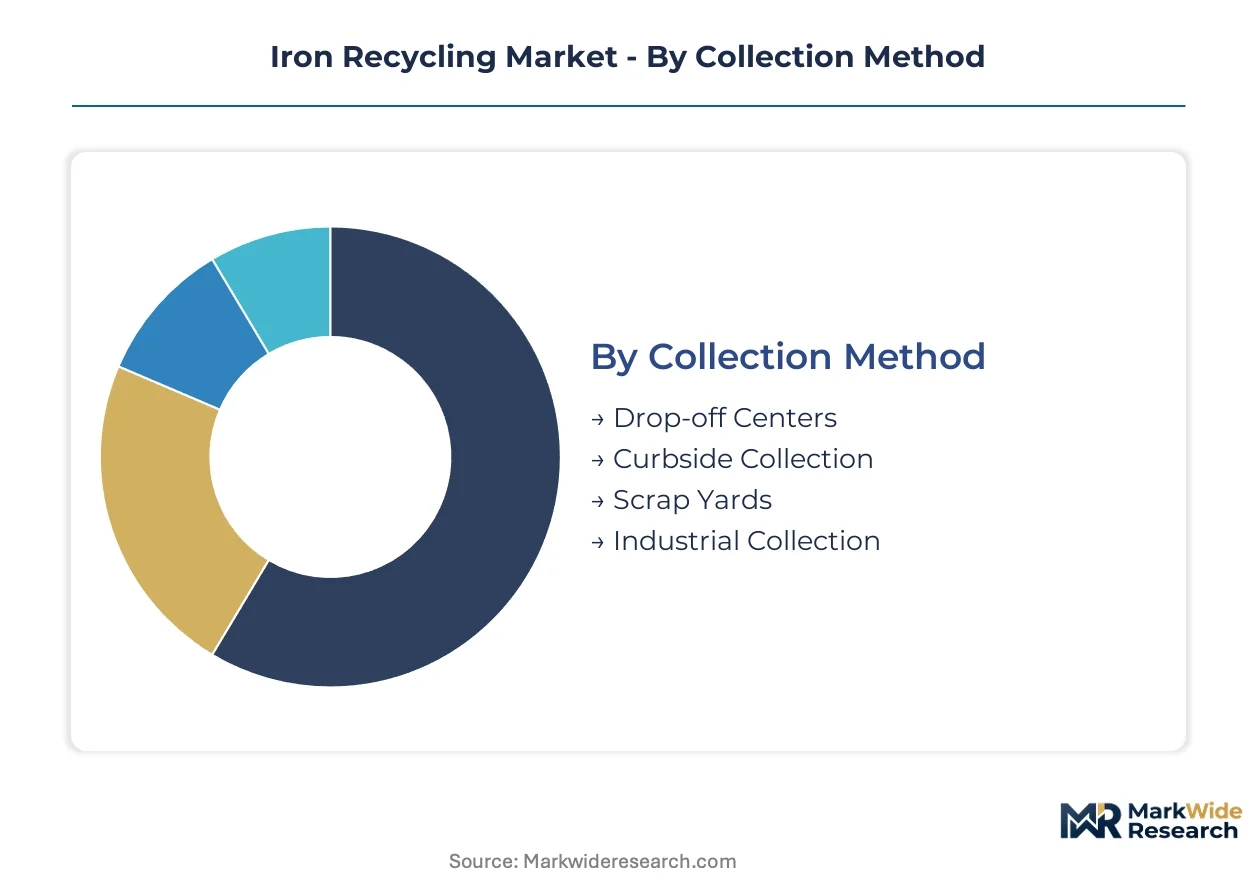
Segmentation in iron recycling separates material flows by collection economics, processing requirements, and end-use chemistry constraints. Each dimension shapes capital allocation decisions for processors and procurement strategies for steelmakers seeking predictable melt outcomes.
Collection Method:
Collection infrastructure varies dramatically in integration depth, from standalone consumer-facing drop points to embedded industrial supply agreements that bypass merchant intermediaries entirely.
- Drop-off Centers:Consumer-facing facilities accept small-volume ferrous loads from households and small businesses. Germany's dual recycling system mandates these centers for end-of-life appliances, creating guaranteed feedstock volumes under extended producer responsibility frameworks.
- Curbside Collection:Municipal programs capture residential metal waste through scheduled pickup routes. These flows suffer from high contamination rates and unpredictable chemistry, limiting their value to processors without advanced sorting capabilities.
- Scrap Yards:Merchant processors consolidate material from multiple sources, performing initial grading and preparation. These facilities dominate volume throughput in North America, though their intermediary position faces disintermediation pressure from digital platform integration.
- Industrial Collection:Direct sourcing agreements between steel mills and manufacturing generators lock in quality and volume. Nucor's coast-to-coast network exemplifies this embedded approach, capturing prime industrial scrap before it reaches open markets.
Industrial collection leads volumes today; curbside collection is gaining share fastest as municipal recycling mandates expand.
End Use Industry:
Downstream steel consumption patterns dictate scrap quality premiums, with chemistry-tolerant applications absorbing contaminated shredded material while precision applications demand prime grades.
- Construction:Rebar and structural steel production consumes substantial ferrous scrap volumes. EAF operators in Turkey and Italy supply this segment, tolerating moderate residual levels that would disqualify material from flat-rolled applications.
- Automotive:Advanced high-strength steel specifications require tight chemistry control. OEMs now specify minimum recycled content in supplier contracts, creating closed-loop recovery systems that bypass traditional scrap channels.
- Manufacturing:Machinery and equipment production draws on diverse scrap grades depending on component specifications. This segment's fragmented demand spreads across multiple processor tiers without concentration in any single supply channel.
- Packaging:Tinplate and can stock recycling operates through established collection infrastructure with predictable material flows. European deposit-return schemes guarantee volume stability for processors serving this segment.
Construction absorbs the highest tonnage; automotive commands the steepest quality premiums.
Processing Technique:
Technology selection determines residual management capability and throughput economics, with capital-intensive methods reserved for high-volume operations serving quality-sensitive end uses.
- Shredding:Hammer-mill systems reduce end-of-life vehicles and appliances to fist-sized fragments for magnetic separation. Sensor-based sorting upgrades now extract non-ferrous contaminants at rates justifying brownfield yard investments.
- Melting:Direct remelting of sorted scrap in induction or cupola furnaces produces foundry-grade iron with minimal residual dilution. This technique serves specialized casting applications with chemistry specifications tighter than commodity steel.
- Magnetic Separation:Drum and belt systems extract ferrous material from shredded flows based on susceptibility differentiation. These units operate downstream of shredding as standard configuration, though their efficiency limits determine final product grade.
- Baling:Compression of heavy melting steel into dense furnace-ready charges retains importance for traditional integrated mills. Legacy baling infrastructure faces stranded costs as blast furnace operations decline in Europe and North America.
Shredding dominates throughput; sensor-augmented magnetic separation is climbing the fastest as EAF chemistry tolerances tighten.
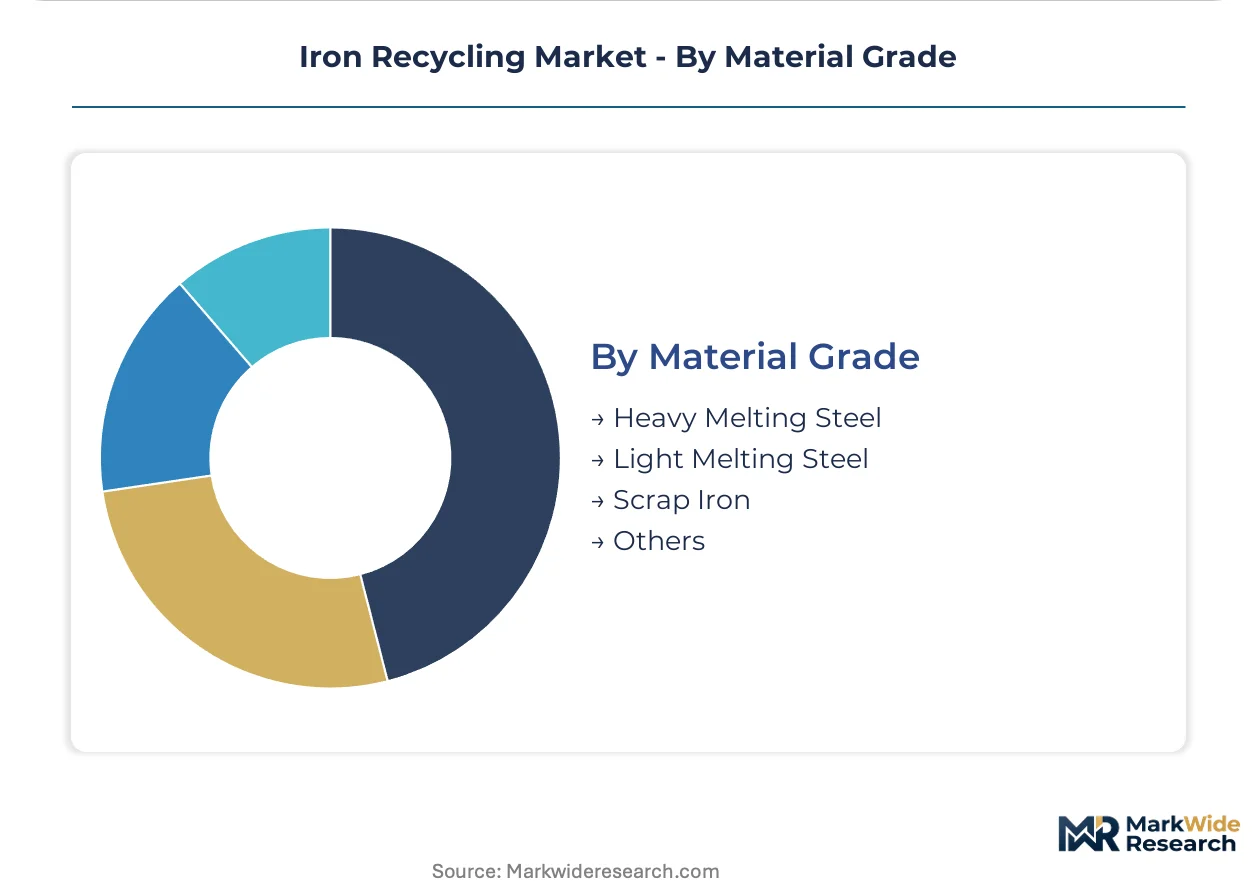
Material Grade:
Grade differentiation reflects density, residual content, and furnace charge compatibility, with pricing spreads widening as EAF operators demand predictable melt chemistry.
- Heavy Melting Steel:Dense, cut-grade material from structural demolition and industrial sources carries minimal copper contamination. This grade commands consistent premiums over shredded alternatives in markets where EAF operators face strict residual limits.
- Light Melting Steel:Thinner-gauge material from sheet metal and appliance sources requires densification before furnace charging. China's MIIT scrap utilization targets are expanding domestic demand for this grade as EAF capacity construction accelerates.
- Scrap Iron:Cast and foundry-grade material with higher carbon and silicon content serves specialized melting applications distinct from steelmaking. Foundry demand concentrates in industrial corridors with machinery manufacturing presence.
- Others:Railroad scrap, turnings, and borings occupy niche positions with limited fungibility across applications. These grades trade at discounts reflecting handling complexity and restricted end-use suitability.
Heavy melting steel leads pricing power; light melting steel is expanding most quickly as shredding capacity diffuses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's electric arc furnace expansion contrasts with Germany's chemistry-tightening scrap standards, revealing divergent pathways for iron recycling infrastructure development across major steel-producing economies.
China
MIIT scrap utilization ratio targets are accelerating domestic shredding capacity construction in Hebei and Jiangsu provinces. The policy mandates higher scrap input rates at steelworks, triggering import quota adjustments that reshape Pacific Rim trade flows. Tangshan steel clusters now source light melting steel from expanded provincial collection networks to feed new EAF installations.
United States
EPA emissions oversight of shredding operations combines with automotive OEM closed-loop mandates to elevate industrial scrap premiums. Nucor's coast-to-coast mill network captures prime manufacturing scrap through direct generator agreements before material reaches open markets. Detroit-area automotive stamping plants now contract exclusively with EAF operators for manufacturing scrap recovery.
Germany
EU Green Deal decarbonization targets and REACH substance screening create dual compliance pressure on scrap processors. The Ruhr industrial corridor hosts advanced sensor-based sorting installations serving flat-rolled steel producers with chemistry-guaranteed material. ThyssenKrupp's Duisburg operations blend scrap with direct reduced iron to manage residual element tolerances.
Turkey
Construction-grade rebar demand from Middle East export markets absorbs moderate-residual shredded scrap that European flat-rolled mills reject. EAF operators in Iskenderun and Izmir face elevated EU import inspection rates that compress working capital cycles. Marmara region processors are consolidating to afford dedicated REACH compliance staff.
India
PLI scheme steel capacity expansion is creating organized scrap collection demand currently served by informal channels. BIS quality standards for construction steel are tightening residual tolerances that informal collectors struggle to meet. Gujarat's Hazira industrial zone is attracting shredding investments to supply new EAF capacity at nearby steelworks.
Iron Recycling Market Competitive Environment
Top-tier vendors anchor integrated mill networks, while specialized processors compete on geographic positioning and sorting technology access. The vendor base spans steelmakers with captive recycling operations, independent merchant processors with regional density, and technology-enabled sorting specialists. Three archetypes dominate: integrated steelmakers blending scrap with virgin inputs, coastally positioned export-oriented processors, and sensor-technology early adopters extracting non-ferrous contaminants. Competitive moves concentrate on brownfield yard upgrades with optical sorting and direct mill partnerships that bypass traditional merchant channels.
Within the integrated steelmaker archetype, ArcelorMittal and Nucor Corporation exemplify contrasting geographic strategies. ArcelorMittal anchors European and North American flat-rolled operations through blended scrap and direct reduced iron inputs. Nucor Corporation occupies a position defined by coast-to-coast US mill density enabling direct industrial scrap capture. Schnitzer Steel Industries, Inc. represents the export-oriented processor model with West Coast infrastructure positioning for Pacific Rim ferrous trade.
| Leading Market Players |
|---|
| ArcelorMittal |
| Nucor Corporation |
| SIMS Metal Management Limited |
| Commercial Metals Company |
| European Metal Recycling Limited |
| Schnitzer Steel Industries, Inc. |
| OmniSource Corporation |
| SA Recycling LLC |
| Tata Steel |
| Others |
Value Chain & Pricing Dynamics
Copper contamination levels in shredded automotive scrap cascade through pricing tiers as EAF operators in Germany and Japan tighten chemistry specifications and widen premiums for predictable melt grades. This input-cost pressure concentrates pricing power with processors deploying sensor-based sorting, while legacy yards without upgrade capital absorb margin compression.
Pricing Analysis
Capacity additions in China's Hebei and Jiangsu provinces are reshaping price floors for light melting steel as domestic EAF construction accelerates under MIIT utilization targets. Pricing stratifies across premium heavy melting steel, standard shredded grades, and economy curbside flows based on residual content and certification documentation. Price erosion runs through economy tiers as informal collectors in India and rural US regions struggle with logistics costs and BIS or EPA compliance burdens. Construction-grade rebar producers in Turkey exhibit highest price sensitivity due to thin margins on Middle East export contracts, while automotive OEMs in Detroit and Stuttgart show lowest sensitivity as closed-loop agreements guarantee volume premiums.
Supply Chain Analysis
Workforce availability for handheld spectroscopy technicians lags equipment deployment in Germany's Ruhr corridor and Japan's Chiba prefecture, constraining rapid chemistry verification at collection points. Supply concentrates in the United States, China, and Turkey as these countries host the densest shredding infrastructure and EAF capacity. Raw material flows draw from end-of-life vehicle dismantlers, industrial manufacturing generators, and municipal curbside programs. Single-source vulnerability emerges from China's import quota adjustments that reshape Pacific Rim arbitrage flows without warning. Distribution runs through direct mill agreements for prime industrial scrap, merchant yards for consolidated grades, and export channels for Pacific Rim ferrous trade.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The iron recycling market functions as a stable compounder, with EU Green Deal decarbonization mandates and China's MIIT scrap utilization targets embedding structural demand growth across multiple regulatory jurisdictions.
For Market Incumbents: Lock in industrial generator relationships through embedded collection agreements before digital platforms disintermediate merchant yards. Secure brownfield yard positions in Hebei and Gujarat where EAF capacity construction concentrates feedstock demand. Sensor-based sorting investment defends margin position against processors relying on post-shipment penalty negotiations. For New Entrants and Emerging Players: Scrap yard operators in underserved rural US corridors and India's informal collection zones represent the most penetrable channel partner type for organized network buildout. Target automotive dismantling certification in jurisdictions with extended producer responsibility mandates. Deploy blockchain-tracked provenance systems as go-to-market wedge to bypass traditional merchant intermediaries and connect directly to EAF operators. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance costs and ISO 14001 certification timelines strand smaller yards without dedicated staff. The five-to-ten year viability window favors processors with coastal export positioning or embedded mill relationships over volume-commodity players. Acquisition target archetype: sensor-technology early adopters with brownfield upgrade capacity in Tangshan or Hazira industrial zones. Monitor EU carbon border adjustment implementation as inflection signal for scrap premium widening against pig iron alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Based Sorting Deployment | ThyssenKrupp and Nucor deploy AI-driven optical systems to guarantee melt chemistry compliance with minimal human intervention. |
| Direct Mill Partnership Agreements | BMW and Volvo contract exclusively with ArcelorMittal for closed-loop steel recovery, bypassing traditional scrap yard channels entirely. |
| REACH Compliance Infrastructure | Turkish exporters in Iskenderun consolidate operations to afford dedicated compliance staff as EU inspection rates intensify. |
| Blockchain Provenance Integration | Digital platforms connect industrial generators directly to EAF operators, disintermediating merchant intermediaries in North America. |
| Coastal Export Capacity Expansion | Schnitzer Steel leverages West Coast infrastructure to capture Pacific Rim ferrous trade flows reshaped by China's import quotas. |
Study Parameters
Direct dialogue with scrap yard operators, EAF procurement managers, automotive dismantling facility directors, and EPA compliance officers grounded qualitative findings in operational reality. Secondary validation drew from SEC filings of integrated steelmakers, MIIT policy circulars, EU Green Deal implementation texts, and customs data on ferrous scrap trade flows. Bottom-up volume estimates from shredding capacity utilization triangulated against top-down steel production scrap intensity ratios.
Segment-level projections across collection method, processing technique, material grade, and end-use industry fed into consolidated market sizing across the analysis window. CAGRs derived from regression analysis of historical scrap-to-steel ratios against EAF capacity expansion pipelines and regulatory utilization mandates. Key forecast inputs included China's provincial EAF construction timelines and automotive OEM recycled content contract specifications.
Revisions become necessary when MIIT utilization targets shift, EU carbon border adjustment mechanisms activate, or sensor-based sorting technology costs drop below brownfield upgrade thresholds. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Saudi Arabia Plastic Components Market
Recycled Plastics
Germany Plastics Market
Recycled Plastics
Recycled Leather Market
Recycled Plastics
Green Polyvinyl Chloride Market
Recycled Plastics
Plastic Compounds Market
Recycled Plastics
China Plastics Market
Recycled Plastics
Plastic Recycling Market
Recycled Plastics
Global Recycled Asphalt Market
Recycled Plastics
Vietnam Plastics Market
Recycled Plastics
Fiber-Reinforced Plastic (FRP) Recycling Market
Recycled Plastics
Non-Ferrous Scrap Recycling Market
Recycled Plastics
Vietnam Recycled Plastics Market
Recycled Plastics
Plastic Pellets Market
Recycled Plastics
South Korea Recycled Plastics Market
Recycled Plastics
Japan Recycled Plastics Market
Recycled Plastics
India Plastic Market