
 Epoxy Type Stabilizers Market | 2026-2036
Epoxy Type Stabilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Epoxy Type Stabilizers Market Foresight
Specialty chemical distribution is fragmenting across multiple tiers as regional distributors and direct-to-midmarket channels compete for epoxy stabilizer volumes. ADEKA Corporation leverages its integrated manufacturing base in Asia to sustain cost-competitive aromatic stabilizer supply. BASF SE anchors European demand through REACH-certified product lines, while Evonik Industries AG differentiates via high-purity polymeric grades for electric insulation applications.
Epoxy type stabilizers are heat-resistant additives formulated from organometallic compounds or nitrogen-based chemistries, typically dosed at 0.5-5.0 wt% to inhibit thermal degradation and discoloration in cured epoxy systems. Their primary commercial purpose is extending service life in coatings, adhesives, and composites exposed to elevated operating temperatures or UV stress. Aromatic stabilizers occupy the largest volume share due to mature supply chains and broad compatibility with standard bisphenol-A epoxy resins. Coating stabilizers represent the fastest-expanding application segment as architectural and industrial protective coatings adopt higher solids formulations requiring enhanced thermal protection.
REACH registration requirements in Europe, RoHS substance restrictions on hazardous additives, and China's GB standards for chemical purity collectively elevate formulation costs while screening out uncertified suppliers. EMA and ECHA frameworks in Europe enforce migration limits that push manufacturers toward polymeric and aliphatic alternatives with lower extractable content. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation cycles and qualify alternative chemistries before compliance deadlines tighten.
Market Dynamics
REACH registration deadlines and RoHS substance restrictions are compressing formulation cycles across the epoxy stabilizer value chain, forcing rapid qualification of polymeric alternatives before extractable-content limits tighten in Europe and China.
Growth Catalysts
- Electric vehicle battery encapsulation:Thermal management requirements in EV power electronics are pulling high-purity aromatic stabilizers into potting compounds and conformal coatings. Chinese GB standards for battery safety are accelerating this specification shift.
- REACH-certified supply chains:European coating manufacturers are locking in ECHA-registered stabilizer sources ahead of 2025 registration renewal windows, creating pull-through demand for compliant aliphatic grades.
- Organometallic innovation:Advanced tin-free catalyst systems are opening formulation space in food-contact adhesives and medical device coatings previously blocked by migration concerns.
Market Restraints
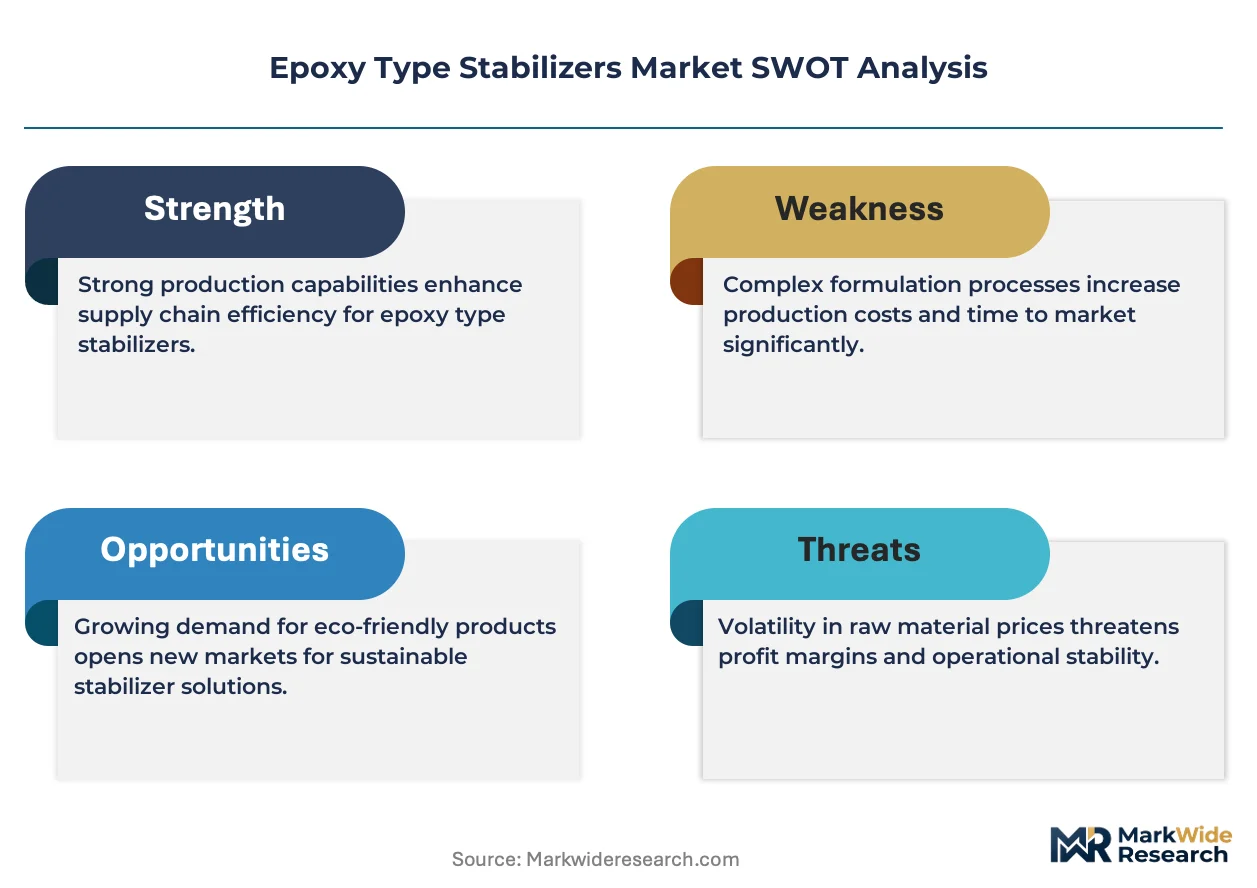
- Raw material concentration:Organotin and organophosphite precursors concentrate among Chinese and South Korean intermediate suppliers, exposing formulators to shipping volatility and tariff exposure.
- Substitution pressure from polyurethane:Flexible foam and sealant applications are migrating toward polyurethane systems with lower stabilizer loading requirements, compressing addressable volume in certain coating segments.
- REACH registration cost burden:ECHA data requirements for tonnage-band upgrades are screening out sub-scale European distributors, consolidating supply among integrated manufacturers with captive toxicology resources.
Strategic Opportunities
- India industrial coatings expansion:BIS certification requirements and domestic epoxy resin capacity additions are creating first-mover advantage for stabilizer suppliers establishing local technical service presence.
- UV-curable hybrid systems:Convergence of cationic photoinitiators with thermal stabilizer packages is opening dual-cure applications in automotive refinish and electronics assembly.
- Direct-to-compounder channels:Mid-market adhesive formulators in Southeast Asia are bypassing traditional distribution tiers, creating margin capture opportunity for stabilizer producers with regional technical sales infrastructure.
Industry Challenges
- Formulation chemist scarcity:Expertise in organometallic stabilization mechanisms and regulatory toxicology is concentrating among senior technical staff at major resin producers, constraining independent distributor technical support capabilities.
- Multi-jurisdiction certification timelines:Parallel REACH, RoHS, and GB standard compliance pathways are extending product launch cycles and requiring dedicated regulatory affairs investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epoxy Type Stabilizers Market |
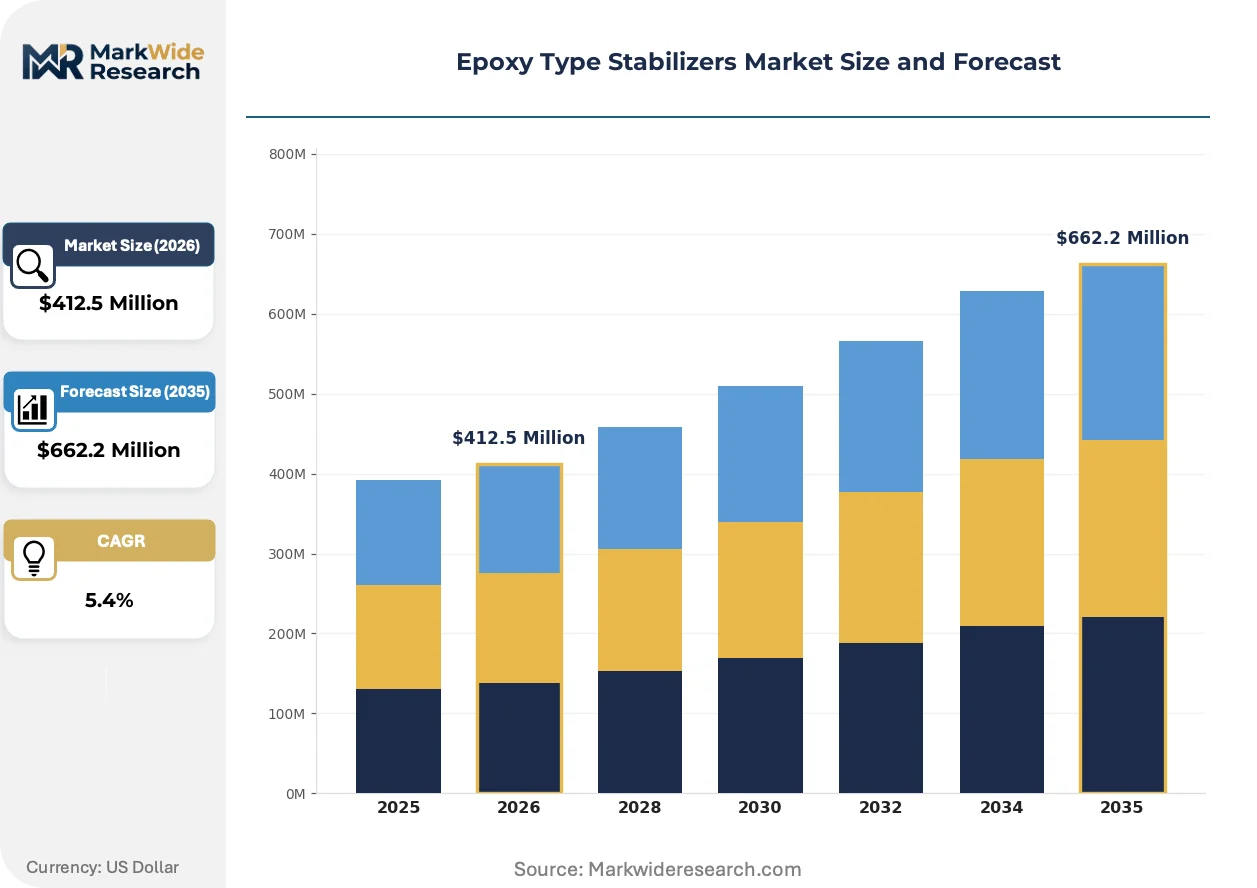
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aromatic, Aliphatic, Polymeric, Coating Stabilizers Application: Adhesives, Coatings, Electric Insulation, Composites End User: Aerospace, Automotive, Electronics, Construction Form: Liquid, Powder, Granular, Emulsion |
| Companies Covered | ADEKA Corporation, Clariant AG, BASF SE, Akzo Nobel N.V., Huntsman Corporation, Albemarle Corporation, Solvay S.A., Evonik Industries AG, Songwon Industrial Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epoxy Type Stabilizers Market Shifts & Advancements
Reactive stabilizer architectures and digital formulation tools are compressing development timelines while regulatory pressure on extractable content is forcing chemistry redesigns across the value chain.
Polymeric hindered amine light stabilizers with reactive epoxy functionality are rendering obsolete conventional low-molecular-weight HALS additives in high-solids industrial coatings. Automotive OEM specification teams are accelerating qualification of these graftable grades for clearcoat applications. The technology is compressing additive migration testing cycles and enabling thinner-film corrosion protection systems.
ECHA's restriction roadmap for microplastics and emerging PFAS limits are forcing reformulation of fluorinated surfactant packages in epoxy coatings. Industrial maintenance coating producers are pivoting toward silicone-modified aliphatic stabilizers with lower environmental persistence profiles. The segment most affected is marine and offshore protective coatings, where anti-corrosion performance requirements previously blocked alternative chemistries.
Compounders in China and Southeast Asia are consolidating purchase volumes through regional buying cooperatives, disintermediating traditional national distributors. Direct manufacturer relationships are replacing multi-tier distribution for standard aromatic stabilizer grades in the adhesives sector. This pattern is most visible in Guangdong and Zhejiang province clusters, where epoxy resin consumption concentrates among mid-scale flooring and electronics assembly formulators.
Epoxy Type Stabilizers Market Segmentation
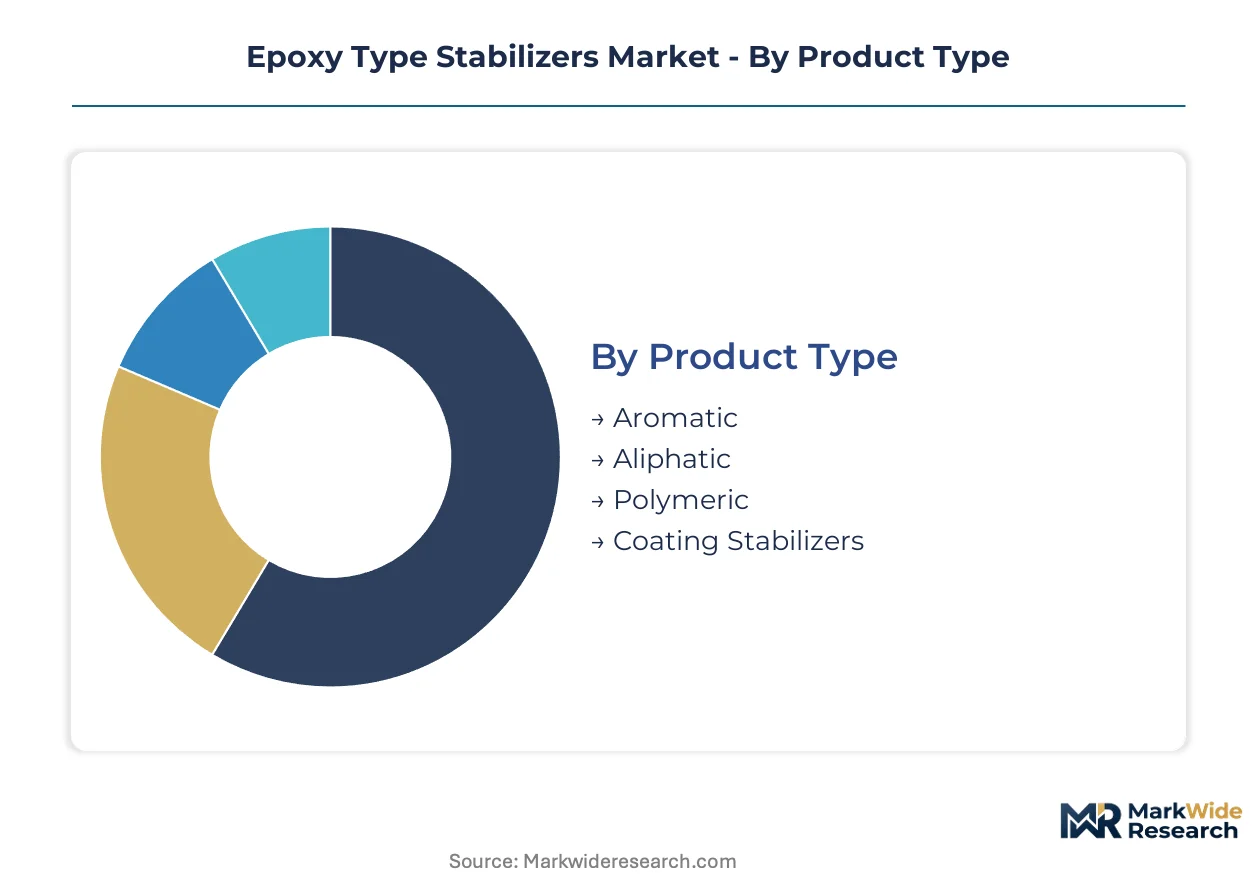
Epoxy stabilizer procurement patterns diverge sharply across product chemistries and end-use specifications, with formulation requirements in high-reliability electronics pulling specialty grades away from commodity aromatic supply. Segmentation discipline enables suppliers to align technical service resources against margin-differentiated application clusters rather than undifferentiated volume plays.
Product Type:
Formulators select stabilizer architectures based on thermal load profiles, migration limits, and compatibility with base resin systems across protective coatings, structural adhesives, and electrical encapsulation.
- Aromatic:Organometallic compounds derived from hindered phenol or benzotriazole chemistries deliver broad-spectrum UV and thermal protection at moderate cost. Demand concentrates in China and South Korea where standard bisphenol-A epoxy production underpins high-volume consumption in industrial maintenance coatings.
- Coating Stabilizers:Specialty formulations optimized for high-solids and waterborne coating systems inhibit discoloration under elevated cure temperatures. Architectural and automotive refinish specifications in Germany and Japan are accelerating qualification of these grades for thin-film corrosion protection.
- Aliphatic:Saturated hydrocarbon backbones with lower extractable content meet REACH migration limits for food-contact and medical device applications.
- Polymeric:High molecular weight architectures with reactive epoxy functionality graft permanently into cured networks, eliminating additive bloom in electric insulation laminates.
Established volume favors aromatic grades; emerging adoption favors coating stabilizers.
Application:
End-use performance requirements dictate stabilizer loading rates, with thermal management specifications in power electronics driving premium-grade absorption.
- Coatings:Industrial protective and architectural finishes require stabilizer packages that prevent chalking and gloss loss under UV exposure and thermal cycling. Marine and offshore maintenance programs in Norway and Singapore specify these additives for extended recoat intervals in harsh environments.
- Electric Insulation:Potting compounds, conformal coatings, and laminate prepregs demand high-purity stabilizers with minimal ionic contamination to preserve dielectric strength. EV battery encapsulation specifications from Chinese GB standards and German automotive OEMs are pulling tin-free organometallic grades into this segment.
- Adhesives:Structural bonding applications in aerospace assembly rely on stabilizers that maintain clarity and shear strength during thermal aging.
- Composites:Fiber-reinforced epoxy systems in wind turbine blades and pressure vessels incorporate stabilizers to resist thermo-oxidative degradation during cure and service.
Coatings command the largest absolute volume; electric insulation expands most quickly.
End User:
Industry-specific certification requirements and liability exposure create divergent procurement behaviors across stabilizer-consuming sectors.
- Electronics:Semiconductor packaging, printed circuit boards, and power module encapsulation require stabilizers qualified to IPC and JEDEC reliability standards. Taiwanese and South Korean contract manufacturers are consolidating specification authority for high-purity grades.
- Automotive:Underhood adhesives, structural composites, and battery thermal management materials must survive 150°C continuous operation. OEM qualification protocols in Stuttgart and Toyota City are extending stabilizer validation cycles.
- Construction:Flooring, structural adhesives, and protective coatings for infrastructure employ aromatic stabilizers in high-tonnage applications with less stringent purity requirements.
- Aerospace:Primary and secondary structural composites specify stabilizers with full traceability and batch certification for airworthiness documentation.
Electronics procurement concentrates specification power; automotive volumes scale fastest.
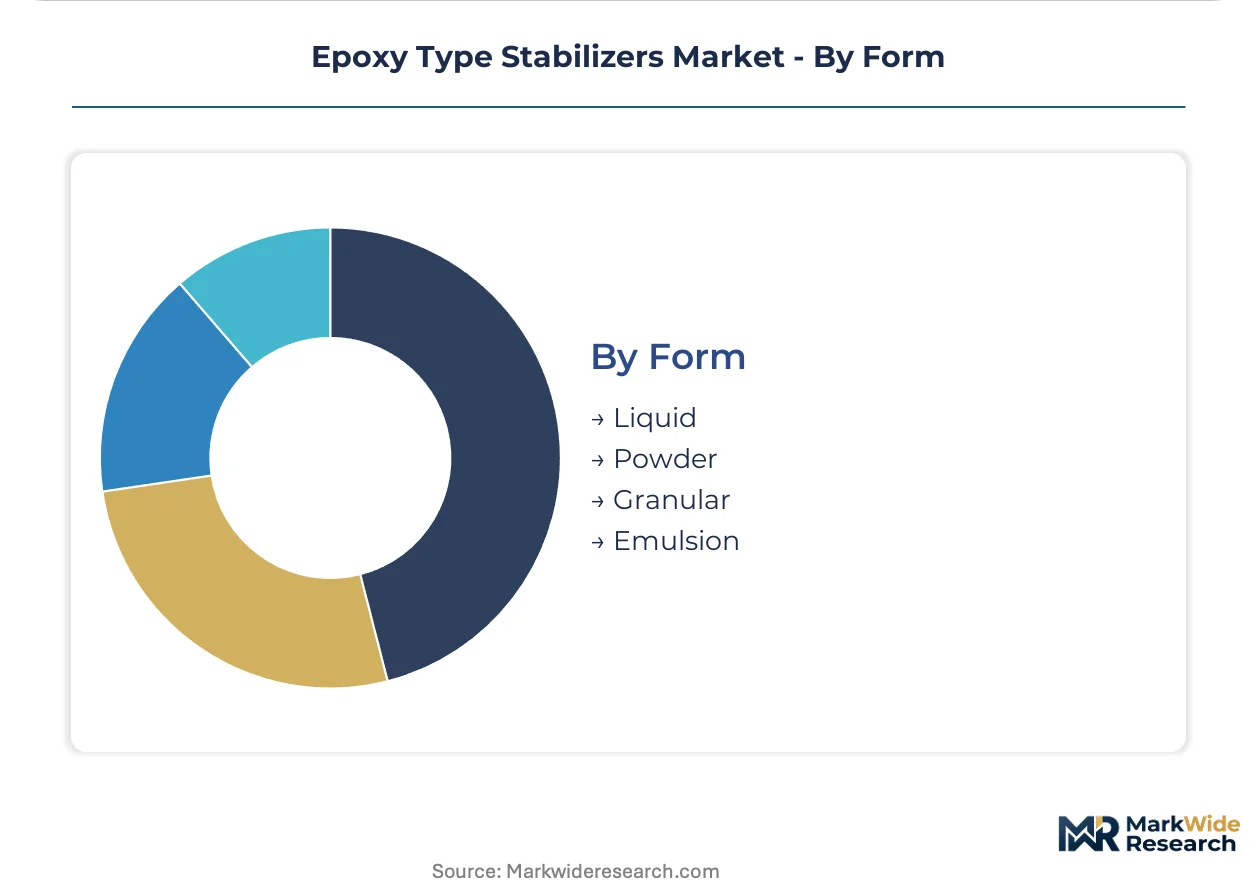
Form:
Physical delivery format determines handling equipment, incorporation efficiency, and dust exposure controls in compounding operations.
- Liquid:100% active or solvent-cut solutions enable metered addition in continuous coating lines and automated adhesive batching. High-solids coating producers in Italy and the Netherlands prefer liquid delivery for reduced dust generation.
- Powder:Free-flowing pulverized grades suit dry-blend operations in powder coating and solid epoxy resin compounding. Chinese flooring adhesive manufacturers in Guangdong province consume substantial powder volumes.
- Granular:Low-dust agglomerated forms balance flowability with reduced respirable exposure in manual weighing operations.
- Emulsion:Water-dispersed stabilizers serve waterborne coating and adhesive formulations where solvent incorporation is restricted by VOC regulations.
Liquid forms dominate coating integration; powder maintains cost position in construction adhesives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in epoxy type stabilizers tilts toward German and Japanese producers commanding REACH-certified and high-purity grades, while Chinese manufacturers compete on volume through integrated aromatic supply chains anchored to domestic resin capacity.
China
Guangdong and Zhejiang province clusters concentrate epoxy resin production that underpins stabilizer consumption in flooring adhesives and electronics assembly. GB standards for battery safety and chemical purity are tightening formulation requirements for EV encapsulation grades. The Pearl River Delta hosts mid-scale compounders consolidating purchases through regional buying cooperatives that disintermediate traditional distribution tiers.
Germany
Automotive OEM qualification protocols in Stuttgart and Wolfsburg are extending validation cycles for underhood adhesives and battery thermal management materials. REACH registration renewal windows through ECHA are locking in ECHA-registered stabilizer sources ahead of 2025 deadlines. The Ruhr industrial corridor maintains specialty chemical manufacturing infrastructure serving coating producers migrating toward high-solids formulations.
United States
EPA oversight of chemical safety and state-level VOC regulations in California and New York are pushing waterborne coating adoption requiring emulsion-form stabilizers. The Gulf Coast petrochemical corridor supplies organophosphite precursors to domestic formulators. Texas-based adhesive compounders serving aerospace assembly in Wichita and Seattle specify stabilizers with full batch traceability for airworthiness documentation.
Japan
METI industrial standards and JIS certification requirements govern electric insulation applications in semiconductor packaging and printed circuit boards. The Kansai region around Osaka hosts resin producers qualifying high-purity polymeric grades for conformal coatings. Toyota City automotive engineering centers are stress-testing stabilizer packages for 150°C continuous operation in power electronics.
South Korea
MFDS chemical safety frameworks and K-Battery standards are accelerating specification shifts for tin-free organometallic grades in EV battery encapsulation. The Gumi electronics cluster concentrates contract manufacturer demand for IPC-qualified stabilizers in semiconductor packaging. Busan-Ulsan industrial corridors integrate stabilizer supply into shipbuilding composites and offshore protective coating programs.
Epoxy Type Stabilizers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain, with formulation expertise and regulatory certification serving as the primary moats. The vendor base arranges into three tiers: integrated multinational chemical conglomerates with captive toxicology resources, regional distributors consolidating through cooperative purchasing, and specialty additive houses focused on reactive architectures. Competitive dynamics center on REACH registration completion ahead of tonnage-band deadlines and direct technical service relationships with mid-market compounders in Southeast Asia.
Among Asia-Pacific integrated producers, ADEKA Corporation and Songwon Industrial Co., Ltd. exemplify the scale-driven archetype leveraging domestic manufacturing bases to sustain cost-competitive aromatic supply. BASF SE and Evonik Industries AG occupy positions within the European premium tier, with the latter representing specialization in high-purity polymeric grades. These named entities anchor their respective regional supply chains without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| ADEKA Corporation |
| Clariant AG |
| BASF SE |
| Akzo Nobel N.V. |
| Huntsman Corporation |
| Albemarle Corporation |
| Solvay S.A. |
| Evonik Industries AG |
| Songwon Industrial Co., Ltd. |
| Others |
Supply & Pricing Matrix
Tariff exposure on organotin and organophosphite precursors from Chinese and South Korean intermediate suppliers compresses margins at both ends of the value chain, forcing aromatic stabilizer producers into longer-term contract structures while specialty grade manufacturers capture premium spreads through REACH-certified supply guarantees.
Pricing Analysis
The customization-premium spread separates configured-to-order polymeric grades from standard aromatic supply. Three-tier pricing structure across premium, standard, and economy levels tracks certification tier and volume commitment, with REACH-registered aliphatic stabilizers commanding substantial markups over uncertified alternatives. Cost compression in commodity aromatic supply is intensifying because Chinese resin producers are consolidating purchase volumes through regional buying cooperatives. Mid-market adhesive formulators in Southeast Asia exhibit highest price sensitivity, while German automotive OEMs demonstrate lowest sensitivity given qualification-driven procurement protocols.
Supply Chain Analysis
Upstream feedstock concentration in hindered phenol and benzotriazole derivatives draws from petrochemical corridors in China, South Korea, and the US Gulf Coast. Organometallic precursor supply rests on integrated manufacturing bases in Asia, with tin-free catalyst innovation tethered to Japanese and German specialty chemical infrastructure. Single-source vulnerability runs through Chinese intermediate suppliers for standard aromatic grades. Distribution runs through direct manufacturer relationships replacing multi-tier channels for mid-market compounders, while premium grades retain specialized distributor technical service layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemist scarcity in organometallic stabilization mechanisms and regulatory toxicology concentrates expertise among senior technical staff at major resin producers, constraining independent distributor capabilities and creating acquisition leverage for integrated manufacturers with captive R&D resources.
For Market Incumbents: Entrench specification authority by completing REACH tonnage-band upgrades ahead of ECHA deadlines and establishing direct technical service presence in India's industrial coatings corridor. Backward integration into organophosphite precursor supply hedges tariff exposure from Chinese intermediate sources. Channel control through regional buying cooperative partnerships in Guangdong and Zhejiang provinces defends volume position against distributor disintermediation. For New Entrants and Emerging Players: India's BIS certification requirements and domestic epoxy resin capacity additions represent the most penetrable white-space target, with first-mover advantage accruing to suppliers establishing local technical service infrastructure. UV-curable hybrid stabilizer systems for automotive refinish applications offer second entry vector with lower incumbent lock-in. Go-to-market through direct-to-compounder channels in Southeast Asia bypasses traditional distribution tiers and captures margin otherwise lost to national distributors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated manufacturers with captive toxicology resources over sub-scale European distributors facing REACH registration cost burdens. Long-term viability across the analysis window hinges on regulatory certification completion and regional technical service density. Acquisition target archetype: mid-cap specialty additive houses with reactive stabilizer architectures and established ECHA registration status. Signal to watch: qualification timelines for tin-free organometallic grades in Chinese GB battery safety standards as inflection indicator for specification shift velocity.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Completion | ECHA-registered status screens out uncertified competitors ahead of tonnage-band deadlines. |
| Backward Integration into Precursors | Captive organophosphite supply hedges tariff exposure from Chinese intermediate concentration. |
| Direct Technical Service Expansion | Regional sales infrastructure in India and Southeast Asia captures disintermediated compounder volumes. |
| Reactive Stabilizer R&D Investment | Polymeric hindered amine architectures with epoxy functionality eliminate additive bloom in high-reliability applications. |
| Long-term Supply Agreements | Locked-in offtake with Chinese resin producers stabilizes aromatic grade volume against spot volatility. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, ECHA registration databases, SEC filings from listed chemical producers, and ACC industry reports. Interviews with plant managers at epoxy resin manufacturers, procurement leads at downstream coating OEMs, distribution channel partners, and technical R&D directors at stabilizer houses informed demand-side validation. Bottom-up volume estimates from end-use consumption patterns triangulate against top-down supply-side capacity assessments across the analysis window.
Forecast inputs include grade tier differentiation, end-use industry thermal load requirements, packaging format preferences, and regional production hub dynamics. Modeled segmentation spans aromatic, aliphatic, polymeric, and coating stabilizer chemistries against coatings, electric insulation, adhesives, and composite applications. CAGRs derive from regression analysis of historical consumption patterns adjusted for regulatory-driven specification shifts and EV battery encapsulation demand acceleration. Capacity expansion timelines at Chinese resin producers and REACH registration completion schedules constitute industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Asian integrated manufacturers or accelerated ECHA restriction timelines would shift outcomes. Cross-checking against ECHA registration database updates and Chinese customs trade statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market
Additives
Global Scale Inhibitors Market
Additives
Potting Mix Additives Market
Additives
North America Pectin Market
Additives
Amino Acids Premixes Market
Additives
Biofuel Additives Market
Additives
Ammonium Acetate Market
Additives
Polyols and Sorbitols Products Market
Additives
Oilfield Drilling Fluid Additive Market
Additives
Thallium Acetate Market
Additives
Butyrate Additives Market
Additives
Encapsulated Citric Acid Market
Additives
Global Butyric Acid Derivatives Market
Additives
Ruminant Feed Additive Market
Additives
Citric Acid Market
Additives
Global Peptone Market